
 Software Publishers Market | 2026-2036
Software Publishers Market Size, Share, and Industry Trends Forecast 2026-2036
Software Publishers Market Analytics
The shift from single-source enterprise licensing to multi-source SaaS procurement is hardening across the industry. Microsoft leverages its hybrid cloud stack to anchor long-term enterprise relationships. Oracle competes through aggressive database-to-cloud migration programs. Salesforce specializes in CRM workflow automation that extends customer lifetime value for subscription revenue.
Software publishers develop, license, and distribute executable code, application programming interfaces, and cloud-native platforms designed to automate business processes, manage data flows, or enable digital commerce. Enterprise software and SaaS products command the dominant revenue share, while cloud solutions represent the fastest-expanding margin pool as public cloud deployment models displace on-premises infrastructure. Mobile applications occupy a mature, high-volume segment with compressed pricing, whereas hybrid cloud deployments capture premium pricing from financial services and government end users seeking workload flexibility.
US HIPAA and SEC disclosure rules shape healthcare and financial software compliance requirements, while EU GDPR and the EU AI Act impose data governance and algorithmic accountability standards that vendors must embed by design. India's BIS certification framework and data localization directives under the Digital Personal Data Protection Act are creating market access conditions for foreign publishers. Stakeholders must monitor how fragmented sovereignty requirements across Washington, Brussels, and New Delhi reshape product architecture and go-to-market costs.
Market Dynamics
Cloud-native architectures are hardening procurement requirements across enterprise buyers, forcing publishers to restructure delivery models around containerized workloads and API-first integration rather than monolithic licensing.
Growth Catalysts
- HIPAA cloud migration mandates:US healthcare providers accelerate procurement of compliant SaaS platforms for electronic health records and telemedicine infrastructure.
- EU AI Act algorithmic accountability:Publishers embedding governance-by-design features capture premium positioning in financial services and public sector procurement.
- India's data localization directives:Foreign publishers establish domestic cloud regions to satisfy Digital Personal Data Protection Act requirements and access government contracts.
Market Restraints
- Specialized cloud engineering talent scarcity:DevOps and platform engineering skills command 40-60% compensation premiums, compressing margins for mid-tier publishers.
- Concentrated hyperscaler dependency:AWS, Azure, and GCP control 65%+ of underlying infrastructure, creating pricing power asymmetry for software vendors.
- GDPR territorial scope friction:Cross-border data transfer mechanisms require legal engineering that extends sales cycles 3-6 months for European buyers.
Strategic Opportunities
- Germany's sovereign cloud initiative:Gaia-X compliance certification opens public sector procurement previously dominated by domestic systems integrators.
- Edge-to-cloud workload orchestration:Convergence of Kubernetes container management with 5G network slicing creates new platform categories for industrial IoT.
- BIS cybersecurity certification:Indian standardization creates first-mover advantage for publishers achieving EMVCo and ISO 27001 alignment ahead of 2025 enforcement.
Industry Challenges
- Legacy ERP integration complexity:SAP and Oracle on-premises installations resist API connectivity, forcing publishers to maintain expensive middleware layers.
- Open-source license contamination risk:GPL and AGPL code scanning requirements extend legal review timelines and create IP indemnification exposure in enterprise sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Publishers Market |
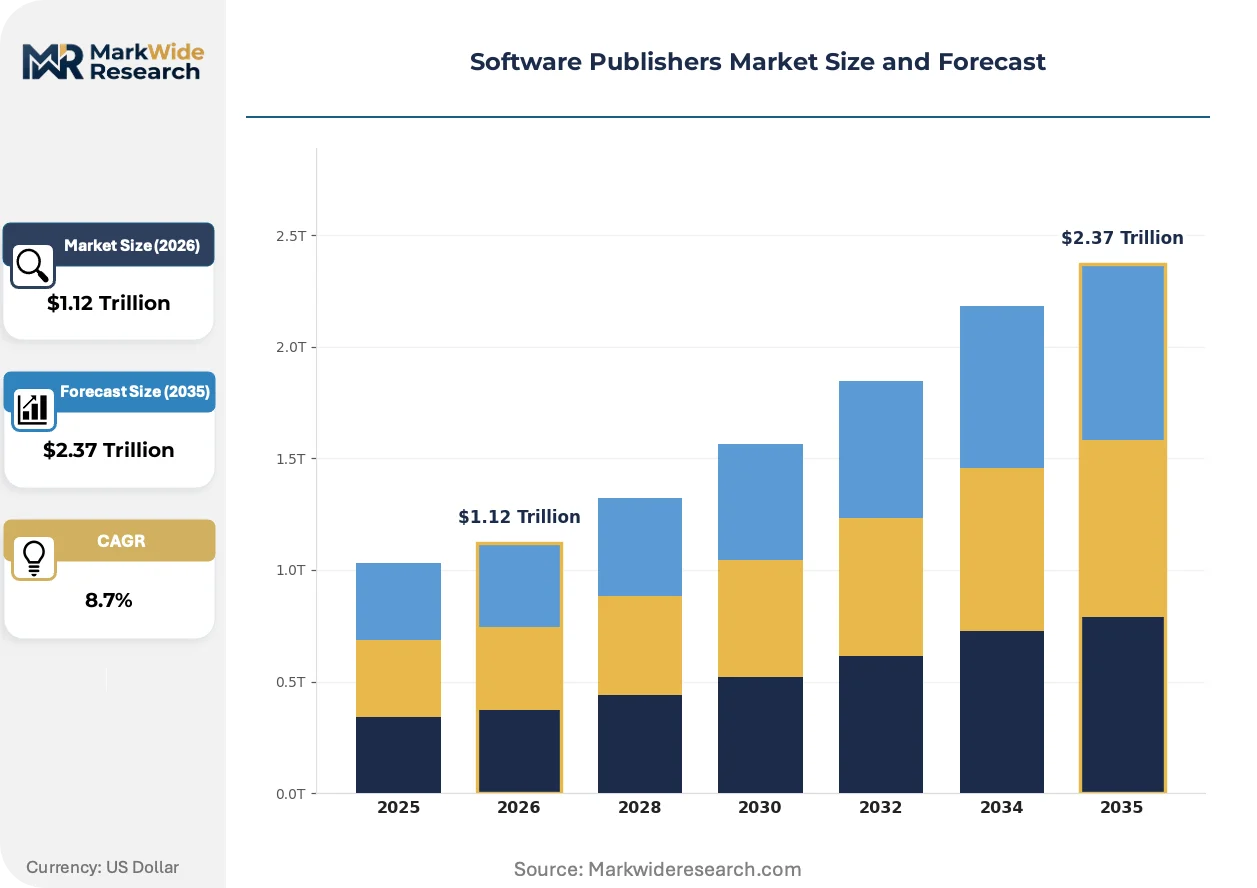
| Market Size in 2026 | $1.12 Trillion |
| Market Size in 2035 | $2.37 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enterprise Software, Mobile Applications, Cloud Solutions, SaaS Products Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud End User: Small Businesses, Large Enterprises, Government Agencies, Educational Institutions Pricing Model: Subscription-Based, One-Time Purchase, Freemium, Tiered Pricing |
| Companies Covered | Microsoft, Alphabet, Oracle, SAP, Salesforce, IBM, ServiceNow, Intuit, Adobe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Publishers Market Evolving Landscape
Generative AI capabilities are embedding into core software workflows, transforming how publishers structure product roadmaps and monetize incremental functionality through consumption-based pricing rather than seat licenses.
Low-code application platforms are consolidating enterprise software development by abstracting infrastructure complexity into visual workflow designers. Manufacturing and logistics buyers deploy citizen-developed applications for inventory and quality management without IT department bottlenecks. This consolidation is compressing traditional professional services revenue pools while expanding recurring platform subscription margins.
EU AI Act risk classification tiers are forcing publishers to reengineer product architectures around prohibited, high-risk, and limited-risk use case categories. Financial services software vendors face mandatory conformity assessments for credit scoring and fraud detection algorithms. German and French regulators are establishing national supervisory sandboxes where publishers test compliance tooling before full enforcement.
Subscription fatigue among mid-market buyers is fragmenting procurement authority away from centralized IT departments toward line-of-business executives with departmental budgets. Finance and HR leaders in United States and United Kingdom enterprises now directly evaluate and purchase point solutions for forecasting and talent analytics. This disintermediation favors publishers with self-service onboarding and transparent per-user pricing over traditional enterprise sales motions.
Software Publishers Market Segmentation

Software publishers structure product portfolios around distinct buyer capabilities, compliance requirements, and infrastructure maturity. Segmentation reveals where pricing power concentrates and which delivery models capture recurring revenue.
Product Type:
Enterprise buyers differentiate by integration complexity and total cost of ownership across their technology stacks.
- Enterprise Software:Monolithic suites for ERP, supply chain, and financial management dominate IT budgets at Fortune 500 companies. Demand concentrates in United States and Germany where SAP and Oracle legacy installations drive maintenance and migration spending.
- SaaS Products:Cloud-native applications delivered via browser or API eliminate infrastructure overhead for buyers. Salesforce and Workday anchor this segment through vertical-specific workflow automation that extends customer lifetime value.
- Cloud Solutions:Infrastructure platforms and managed services for workload orchestration.
- Mobile Applications:Consumer and enterprise apps distributed through Apple App Store and Google Play with compressed pricing.
Enterprise Software leads volumes today; SaaS Products are gaining share fastest.
Deployment Model:
Procurement authority shifts based on data sovereignty mandates and existing capital investments in on-premises infrastructure.
- Public Cloud:AWS, Azure, and GCP host scalable workloads without capital expenditure. Financial services firms in United States and United Kingdom deploy trading and risk applications here, though EU GDPR cross-border transfer rules extend sales cycles.
- Hybrid Cloud:Workload portability between private data centers and public cloud captures premium pricing from government and healthcare buyers seeking flexibility. India's data localization directives under the Digital Personal Data Protection Act accelerate domestic hybrid deployments.
- On-Premises:Legacy installations in regulated industries with extended depreciation schedules.
- Private Cloud:Single-tenant infrastructure for defense and intelligence community requirements.
Hybrid Cloud commands the steepest expansion trajectory as sovereignty requirements harden across Washington, Brussels, and New Delhi.
End User:
Budget authority and procurement velocity vary sharply by organizational scale and funding source.
- Large Enterprises:Centralized IT procurement with multi-year enterprise agreements and dedicated vendor management offices. German automotive and industrial conglomerates drive demand for Gaia-X compliant sovereign cloud solutions.
- Government Agencies:Federally mandated compliance certifications and lengthy RFP cycles. India's BIS cybersecurity standards and EMVCo alignment create first-mover advantages for publishers targeting 2025 enforcement windows.
- Small Businesses:Departmental purchasing through self-service onboarding with per-seat pricing transparency.
- Educational Institutions:Volume licensing through consortium arrangements with extended payment terms.
Large Enterprises anchor current revenue; Government Agencies are expanding procurement fastest as digital sovereignty investments accelerate.
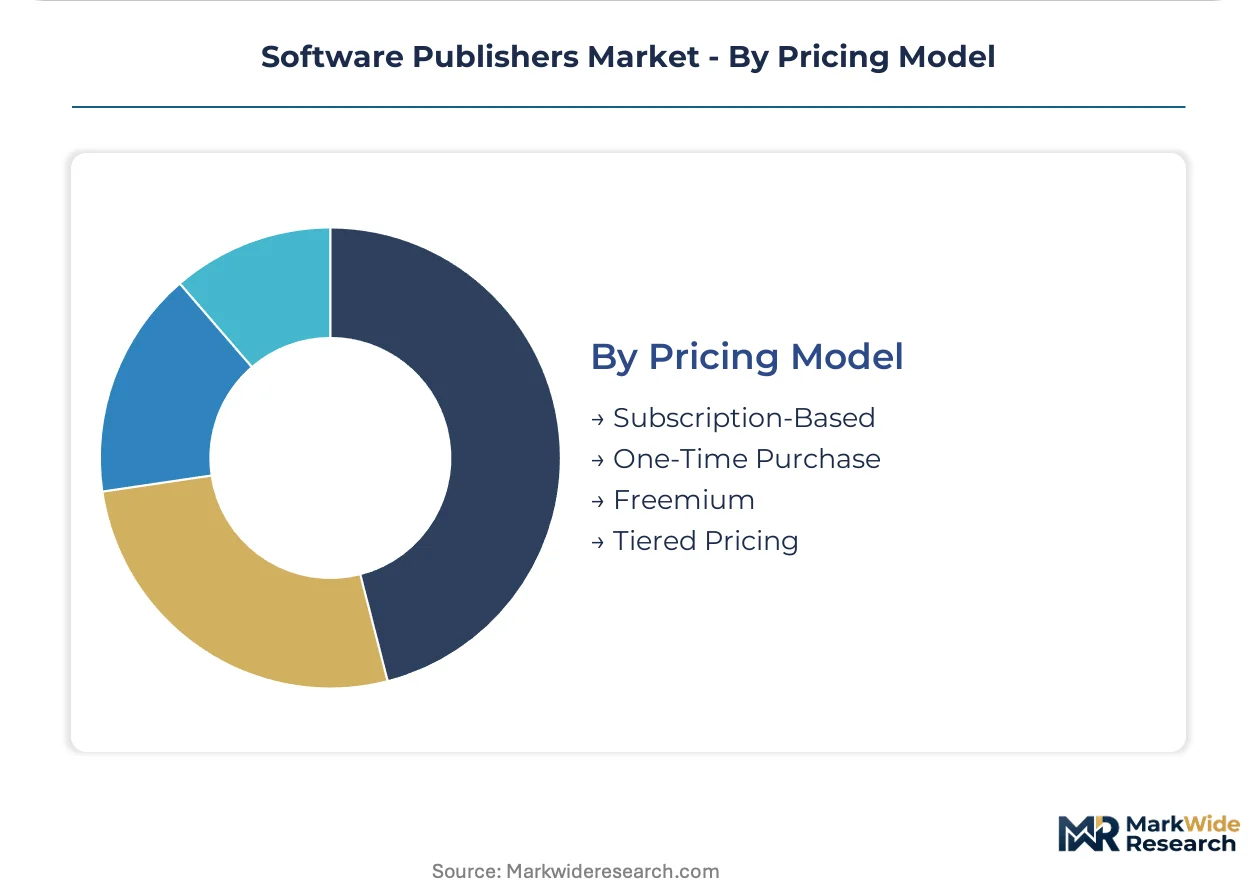
Pricing Model:
Monetization structure determines cash flow predictability and customer acquisition economics.
- Subscription-Based:Monthly or annual recurring revenue with automatic renewal clauses. United States mid-market buyers exhibit fatigue with seat-based models, prompting publishers to introduce consumption-based alternatives tied to API calls or data processed.
- Freemium:Tiered feature gates convert free users to paid tiers through workflow lock-in. Mobile application publishers deploy this model for user acquisition before monetizing through in-app purchases or enterprise upgrades.
- One-Time Purchase:Perpetual licenses with maintenance contracts for legacy on-premises software.
- Tiered Pricing:Three-level differentiation across premium, standard, and economy feature sets.
Subscription-Based pricing dominates current bookings; Freemium models are climbing the fastest as product-led growth displaces traditional enterprise sales motions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where software publishers establish delivery infrastructure, with compliance cost differentials between Washington, Brussels, and New Delhi driving regional cloud region investments and data center localization strategies.
United States
HIPAA cloud migration mandates accelerate procurement of compliant SaaS platforms for electronic health records and telemedicine infrastructure. SEC disclosure rules impose algorithmic accountability requirements on financial software vendors. Seattle and San Francisco Bay Area clusters anchor hyperscaler headquarters and enterprise software R&D concentration.
Germany
Gaia-X compliance certification opens public sector procurement previously dominated by domestic systems integrators. EU GDPR cross-border transfer rules extend sales cycles for financial services software buyers. Munich and Frankfurt financial centers drive demand for sovereign cloud solutions with workload portability guarantees.
India
Data localization directives under the Digital Personal Data Protection Act accelerate domestic hybrid cloud deployments for government contracts. BIS cybersecurity certification creates first-mover advantage for publishers achieving EMVCo and ISO 27001 alignment. Bangalore and Hyderabad technology corridors concentrate software development talent and captive delivery centers.
United Kingdom
Subscription fatigue among mid-market buyers fragments procurement authority toward line-of-business executives with departmental budgets. Financial Conduct Authority algorithmic governance guidance shapes procurement requirements for credit scoring and fraud detection software. London fintech cluster drives demand for API-first integration platforms.
Japan
METI digital transformation subsidies accelerate legacy ERP migration to cloud-native architectures. Personal Information Protection Commission data governance standards impose localization requirements on foreign publishers. Tokyo and Osaka metropolitan areas concentrate enterprise software procurement for automotive and electronics manufacturing supply chains.
Software Publishers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue vertical-specific workflow automation and edge-to-cloud orchestration capabilities. The vendor base stratifies across three tiers: hyperscalers with infrastructure control, enterprise suite providers with installed base leverage, and point-solution specialists with API-first architectures. Dominant competitive moves include strategic partnerships for sovereign cloud compliance and portfolio diversification into generative AI consumption-based pricing models.
Within the enterprise suite tier, Microsoft and Oracle exemplify archetypes leveraging hybrid cloud stacks and database-to-cloud migration programs respectively. Salesforce occupies a position representing CRM workflow automation specialists extending customer lifetime value through subscription revenue structures. These three anchors illustrate how publishers restructure delivery models around containerized workloads rather than monolithic licensing.
| Leading Market Players |
|---|
| Microsoft |
| Alphabet |
| Oracle |
| SAP |
| Salesforce |
| IBM |
| ServiceNow |
| Intuit |
| Adobe |
| Others |
Value Network & Pricing Analysis
DevOps and platform engineering talent scarcity in Bangalore and Hyderabad commands 40-60% compensation premiums, widening the spread between premium-tier enterprise SaaS and economy-tier mobile applications as labor cost differentials transmit directly into pricing architecture.
Pricing Analysis
Direct-to-enterprise subscription contracts bypass distributor markups entirely, compressing channel-margin layers to near-zero for cloud-native publishers. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration complexity and compliance certification depth, with HIPAA and GDPR attestation driving 20-30% premiums. Pricing pressure stems from hyperscaler infrastructure cost pass-throughs as AWS, Azure, and GCP control underlying compute. Mid-market buyers exhibit acute price sensitivity, while government agencies tolerate premium positioning for sovereign cloud guarantees.
Supply Chain Analysis
ISO 27001 and BIS cybersecurity certification gating restricts component sourcing to audited infrastructure providers, filtering out uncertified cloud region operators. Supply concentrates in the United States, Ireland, and Singapore for hyperscaler data center capacity, with India emerging for captive development centers. Raw material dependencies center on specialized silicon for AI inference, subsea fiber capacity for inter-region latency, and scarce Kubernetes platform engineering talent. Single-source vulnerability runs through the three-hyperscaler oligopoly controlling 65% of underlying infrastructure. Distribution runs through API-first direct procurement and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU AI Act enforcement deadlines and India's Digital Personal Data Protection Act localization mandates are accelerating replacement cycles and expanding addressable spend.
For Market Incumbents: Anchor hybrid cloud relationships through multi-year enterprise agreements that embed containerized workload portability as a switching cost. Defend against point-solution disintermediation by acquiring low-code platform specialists before line-of-business executives fragment procurement authority. Prioritize Gaia-X and BIS certification investment to lock out unqualified competitors from German public sector and Indian government contracts.
For New Entrants and Emerging Players: Channel partners specializing in vertical-specific system integration offer the fastest path to credibility without enterprise sales infrastructure. Target mid-market finance and HR departments in the United Kingdom and United States where subscription fatigue has already disintermediated centralized IT procurement. Lead with transparent per-user pricing and self-service onboarding to bypass traditional RFP cycles.
For Investors and Strategic Acquirers: Valuations sit cheapest among DevOps tooling and edge-to-cloud orchestration specialists lacking HIPAA or GDPR certification. Long-term viability favors publishers with demonstrated compliance-by-design architecture rather than retrofitting approaches. Watch hyperscaler capex guidance as the inflection signal for infrastructure capacity constraints that would shift pricing power toward software vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Containerized workload portability locks in enterprise relationships across AWS, Azure, and GCP simultaneously. |
| Strategic Partnership | Gaia-X compliance alliances with German systems integrators open sovereign cloud procurement previously closed to foreign publishers. |
| Acquisition of Specialist Firm | Low-code platform absorption compresses professional services revenue while expanding recurring subscription margins. |
| Geographic Expansion | Domestic cloud region establishment in India satisfies Digital Personal Data Protection Act localization for government contracts. |
| Product Launch | Generative AI consumption-based pricing modules capture incremental revenue beyond traditional seat licenses. |
Research Methodology
Coverage spans the United States, Germany, India, the United Kingdom, and Japan, with primary inputs from each market gathered through structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners. Secondary validation draws from SEC filings, hyperscaler capex disclosures, App Annie mobile application metrics, and EU regulatory enforcement notices. Bottom-up sizing of individual publisher revenue streams triangulates against top-down market aggregate estimates from trade association data.
Granularity-level modeling disaggregates the analysis window by deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derive from segment-specific growth rate assumptions applied to base-year revenue estimates, with cross-segment reconciliation ensuring internal consistency. Industry-specific forecast inputs include hyperscaler infrastructure expansion timelines, regulatory enforcement calendar milestones, and enterprise ERP replacement cycle data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sovereign data localization enforcement intensity and generative AI capability commoditization. Forecasts reflect assumptions about compliance cost trajectories and talent scarcity persistence that material deviation would invalidate. A model refresh is warranted upon material change in EU AI Act implementation timelines or hyperscaler pricing power erosion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Collaborative Office Software Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Driver and Staff Management Software Market
Software & Services
Expense Management Software Market
Software & Services
Global Distribution Software Market
Software & Services
Live Software Market
Software & Services
Construction Project Management Software Market
Software & Services
Remote Desktop Software Market
Software & Services
Global Gym Software Market
Software & Services
Global Webinar Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Illustration Software Market
Software & Services
Asia-Pacific ERP Software Market
Software & Services
Meditation Software Market
Software & Services
Global Digital Rights Management Software Market
Software & Services
Global Salesforce Appexchange Tools Market