
 Risk-Based Authentication (RBA) Market | 2026-2036
Risk-Based Authentication (RBA) Market Size, Share, and Industry Trends Forecast 2026-2036
Risk-Based Authentication (RBA) Market Analytics
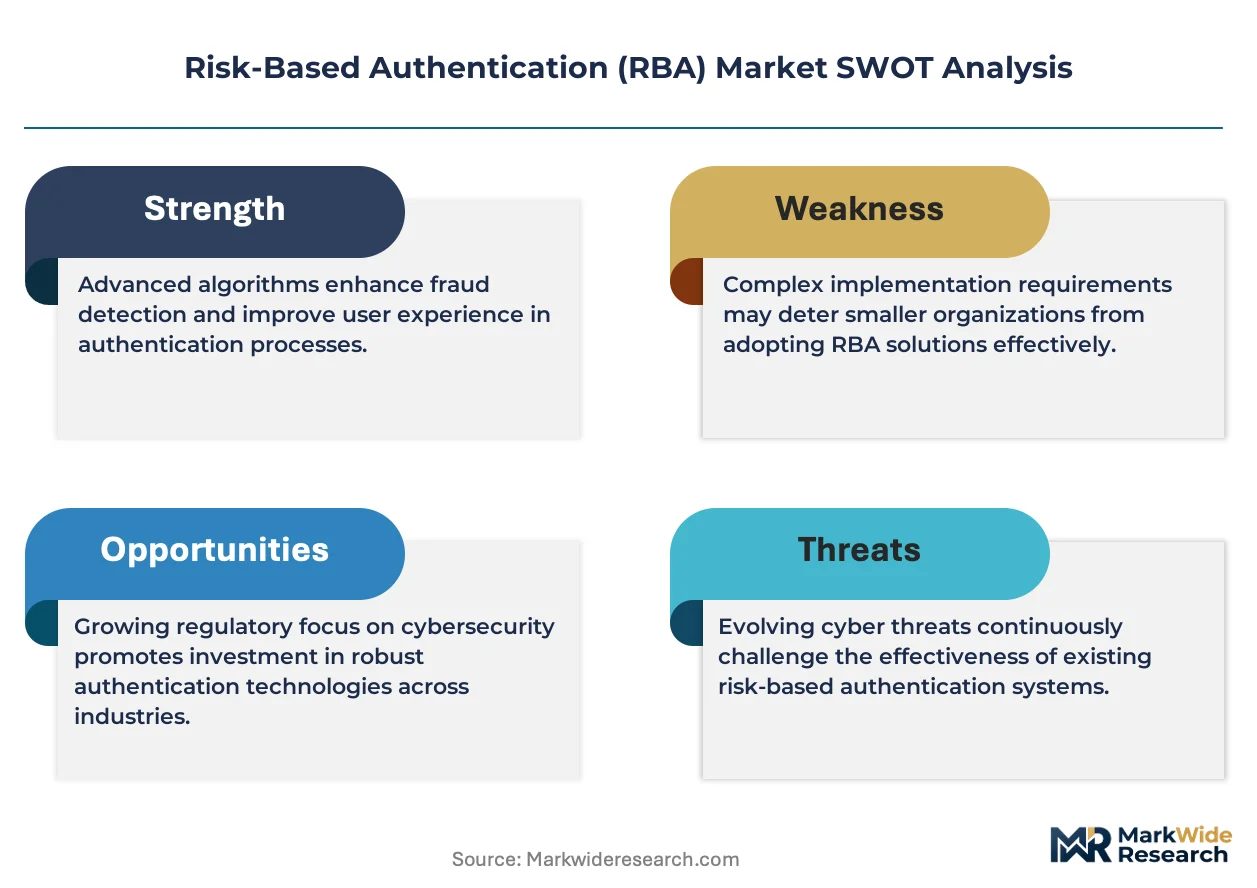
Shortage of machine learning engineers with fraud-detection expertise is rotating enterprise procurement toward managed service models that bundle algorithmic tuning with platform licensing. IBM Corporation leverages its hybrid cloud infrastructure to anchor large financial services deployments. Okta Inc. competes through native identity orchestration that simplifies API-based RBA integration. Thales Group specializes in hardware-rooted trust architectures that differentiate its offering for government-grade security requirements.
Risk-based authentication is an adaptive identity verification methodology that evaluates contextual signals—device fingerprint, geolocation, behavioral biometrics, and transaction velocity—to dynamically adjust authentication stringency in real time. The system employs machine learning models that continuously recalibrate risk scores against evolving threat patterns, primarily serving to reduce friction for legitimate users while escalating scrutiny for anomalous access attempts. Cloud-based deployment architectures now capture the fastest expansion as enterprises abandon capital-intensive on-premises identity stacks, though hybrid configurations retain strong positioning among regulated financial services entities with data residency constraints. Behavioral analytics and biometric verification segments are gaining share as password fatigue drives demand for invisible authentication layers that operate without explicit user action.
The EU AI Act imposes algorithmic transparency requirements on automated decision systems used for access control, compelling vendors to document risk-scoring logic and enable human override mechanisms. In the United States, NIST zero-trust architecture guidelines and HIPAA security rule updates are mandating continuous verification protocols for healthcare and federal contractor environments. Stakeholders must monitor how divergent regulatory timelines for AI governance across Washington, Brussels, and Beijing reshape interoperability standards and complicate single-platform global rollouts.
Market Dynamics
Machine learning inference latency requirements are compressing deployment architectures toward edge-native authentication nodes, forcing vendors to restructure software stacks for localized risk scoring without cloud round-trips.
Growth Catalysts
- Federal zero-trust mandates:United States government contractors must implement continuous verification protocols under NIST SP 800-207 guidelines, accelerating procurement of contextual access platforms across defense and civilian agencies.
- Behavioral biometrics maturation:Keystroke dynamics and mouse-movement analysis now achieve false-accept rates below 0.1%, enabling passwordless deployment in financial services customer-facing applications.
- India:Reserve Bank of India directives mandating multi-factor authentication for digital payments above specified thresholds are driving bank investments in adaptive risk engines.
Market Restraints
- Specialized ML engineering scarcity:Talent shortages in fraud-detection model development inflate implementation costs and extend deployment timelines for enterprise self-managed deployments.
- EU AI Act algorithmic documentation:Automated decision systems for access control require explainable risk-scoring logic and human override capabilities, increasing compliance engineering overhead.
- On-premises hardware legacy:Regulated financial institutions with data residency constraints maintain capital-intensive identity stacks, slowing cloud migration velocity relative to less regulated sectors.
Strategic Opportunities
- Brazil:ANVISA digital health certification requirements for telemedicine platforms create demand for patient identity verification with adaptive risk adjustment.
- Convergence of RBA and secure access service edge:Unified policy enforcement across identity and network layers enables vendors to displace point-product procurement in distributed enterprise environments.
- Managed detection and response bundling:Security service providers are packaging algorithmic tuning, threat intelligence feeds, and platform licensing into subscription offerings that reduce customer technical staffing requirements.
Industry Challenges
- API integration complexity:Heterogeneous legacy identity directories and custom application authentication flows demand extensive professional services engagement for seamless RBA deployment.
- Cross-border data flow restrictions:Divergent data localization requirements between Washington, Brussels, and Beijing complicate single-platform global rollouts for multinational enterprises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Risk-Based Authentication (RBA) Market |
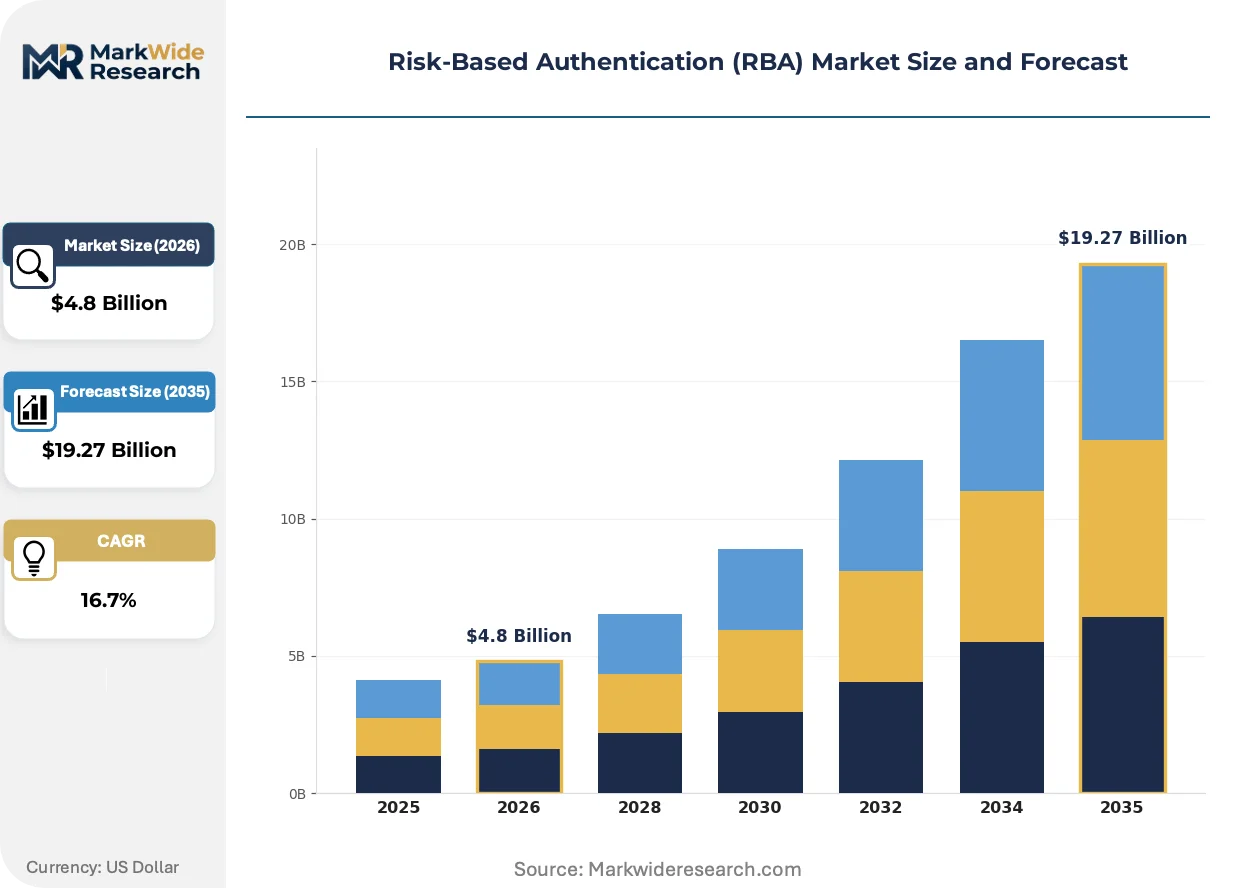
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Behavioral Analytics, Biometric Verification, Multi-Factor Authentication Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Financial Services, Healthcare, Retail, Government Application: Mobile Security, Online Banking, E-Commerce, Enterprise Security |
| Companies Covered | Micro Focus International plc, SecureAuth Corporation, RSA Security LLC, Oracle Corporation, Thales Group, IBM Corporation, Okta Inc., HID Global Corporation, Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Risk-Based Authentication (RBA) Market Evolving Landscape
Authentication infrastructure is fragmenting into composable microservices that enable selective capability deployment, reducing vendor lock-in while complicating interoperability certification.
Continuous authentication is decomposing static session boundaries into perpetual risk evaluation streams. Financial institutions in North America and Western Europe are deploying keystroke and touch-pattern analysis across mobile banking applications within eighteen-month refresh cycles. This technology is decomposing the binary login-or-denial paradigm into graduated friction adjustment that preserves transaction completion rates.
The EU AI Act imposes algorithmic transparency requirements on automated access control decisions, compelling vendors to document risk-scoring logic and enable human override mechanisms. Financial services and healthcare sectors face the steepest compliance engineering obligations. German and French regulators are interpreting these provisions most stringently, creating a two-speed compliance landscape across the European market.
Enterprise buyers are unbundling authentication platform procurement from professional services, demanding API-first architectures that support in-house integration teams. Managed service providers and systems integrators are capturing implementation and tuning revenue that vendors previously monopolized. This pattern is most pronounced in United States healthcare systems undergoing HIPAA security rule modernization.
Risk-Based Authentication (RBA) Market Segmentation
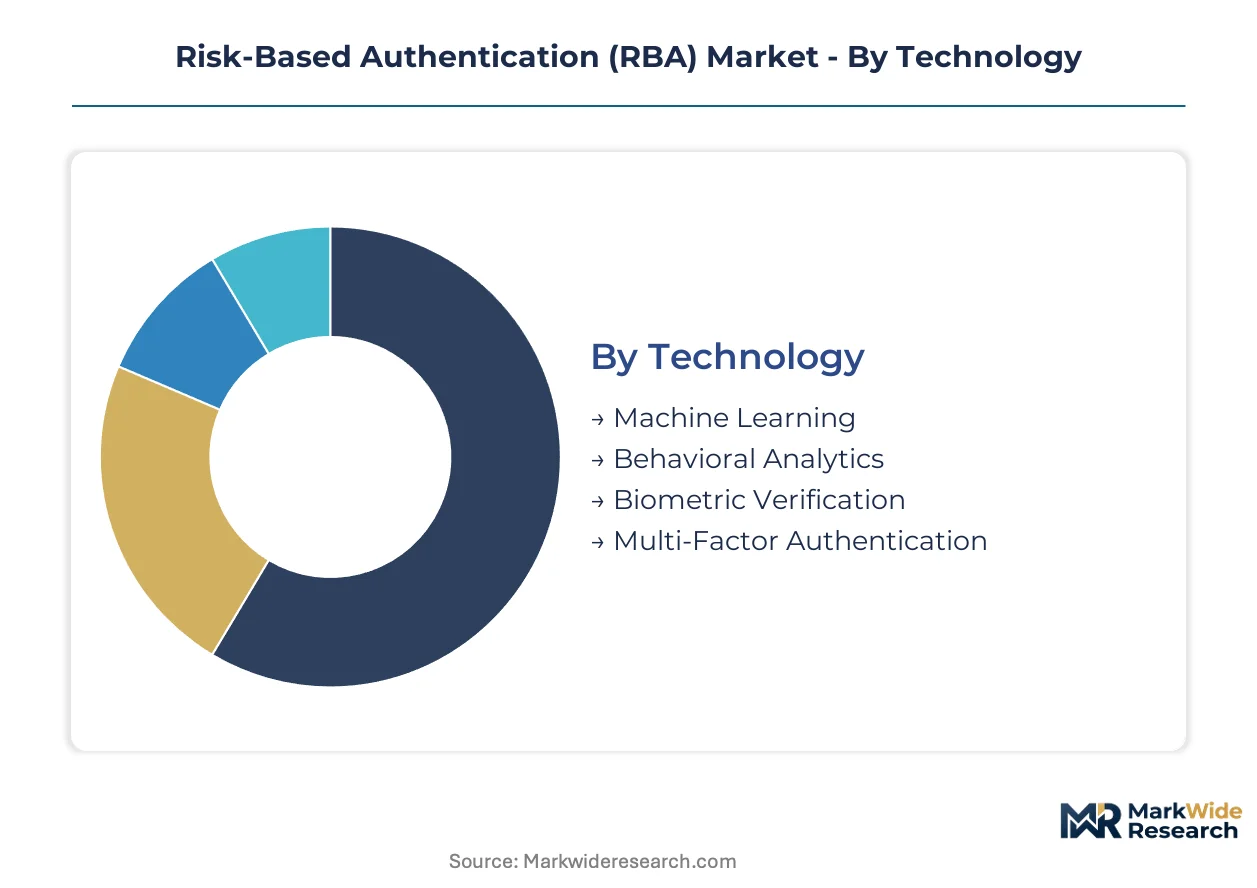
Risk-based authentication platforms fragment across multiple technical and operational dimensions. Vendors configure product roadmaps around deployment architecture, technology stack, and vertical compliance requirements rather than pursuing horizontal scale.
Technology:
Behavioral analytics and biometric verification face accelerating substitution pressure from passwordless authentication standards, while machine learning cores remain defensible through proprietary fraud-detection training data.
- Machine Learning:Adaptive risk-scoring engines process device fingerprints, geolocation vectors, and transaction velocity patterns in real time. Financial services institutions in the United States concentrate procurement here, driven by NIST zero-trust mandates requiring continuous verification protocols.
- Behavioral Analytics:Keystroke dynamics and mouse-movement analysis achieve sub-0.1% false-accept rates, enabling invisible authentication layers. Demand clusters in North American mobile banking applications where password fatigue erodes customer retention metrics.
- Biometric Verification:Fingerprint, facial recognition, and voiceprint modalities anchor high-assurance workflows.
- Multi-Factor Authentication:SMS, TOTP, and hardware token combinations persist as compliance baselines.
Machine learning retains volume leadership; behavioral analytics holds the steepest expansion curve.
Deployment:
Cost tier stratification separates capital-intensive on-premises stacks from operational-expense cloud models, with hybrid configurations commanding premium pricing for data residency compliance.
- Cloud-Based:Serverless architectures eliminate infrastructure ownership while enabling elastic scaling during authentication spikes. Enterprises without legacy identity investments favor this model for eighteen-month refresh cycles.
- Hybrid:Split-processing designs keep sensitive biometric templates on-premises while routing risk analytics to cloud inference endpoints. German and French financial institutions under GDPR and EU AI Act mandates drive regional concentration.
- On-Premises:Air-gapped deployments satisfy classified government network requirements.
- Managed Services:Bundled algorithmic tuning and threat intelligence subscriptions address ML engineering scarcity.
Cloud-based deployments are expanding most quickly; hybrid architectures capture the highest margin premiums.
End User:
Application maturity diverges sharply—financial services operate eighteen-month refresh cycles while healthcare lags twelve to twenty-four months behind on HIPAA security rule compliance timelines.
- Financial Services:Adaptive identity verification defends against authorized push payment fraud and account takeover attacks. RBI directives in India mandate multi-factor authentication for digital payments above specified thresholds.
- Healthcare:Patient portal access and telemedicine platforms require stepped-up authentication for prescription workflows. ANVISA digital health certification requirements in Brazil create procurement windows for patient identity verification with adaptive risk adjustment.
- Retail:Cart abandonment reduction drives invisible authentication investments.
- Government:Federal zero-trust architectures under NIST SP 800-207 guidelines mandate continuous verification.
Financial services commands revenue concentration; healthcare is gaining share fastest as HIPAA modernization accelerates.
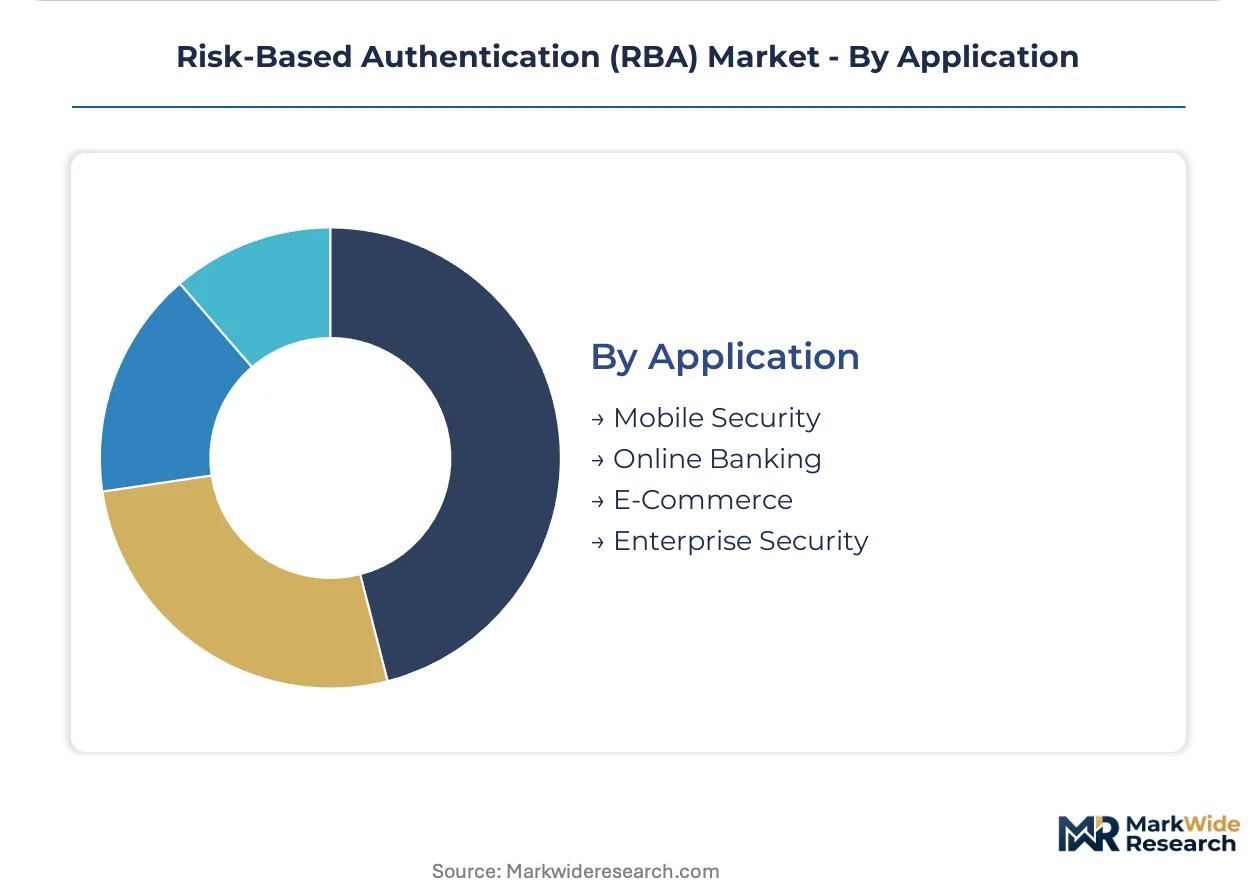
Application:
Customer-facing use cases prioritize friction reduction while internal enterprise security tolerates higher authentication burden for privileged access protection.
- Mobile Security:Touch-pattern analysis and behavioral biometrics operate without explicit user action across iOS and Android banking applications. Continuous authentication decomposes static session boundaries into perpetual risk evaluation streams.
- Online Banking:Real-time transaction risk scoring escalates scrutiny for anomalous wire transfers and new payee additions. Keystroke dynamics deployment preserves completion rates for legitimate customers.
- E-Commerce:Guest checkout flows demand low-friction identity verification at scale.
- Enterprise Security:Privileged access management integrates contextual risk signals for administrator sessions.
Mobile security leads transaction volume; online banking demonstrates the steepest technology refresh velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial institutions in the United States deploy adaptive risk engines for real-time transaction scoring, while German and French banks prioritize hybrid architectures that keep biometric templates under local custody. Indian payment processors emphasize SMS-based multi-factor authentication at scale, reflecting divergent infrastructure maturity and regulatory timelines across markets.
United States
Federal contractors under NIST SP 800-207 guidelines drive procurement of continuous verification platforms across defense and civilian agencies. The HIPAA Security Rule updates mandate stepped-up authentication for healthcare patient portals and telemedicine workflows. New York and San Francisco financial services clusters anchor enterprise deployments of behavioral biometrics in mobile banking applications.
Germany
GDPR data residency constraints and EU AI Act algorithmic transparency requirements push financial institutions toward split-processing hybrid architectures. The KBA and BaFin interpret automated decision system provisions stringently, elevating compliance engineering overhead. Frankfurt's banking concentration hosts extensive on-premises identity stack investments with localized risk-scoring nodes.
France
CNIL enforcement of algorithmic accountability provisions compels vendors to document risk-scoring logic and enable human override mechanisms. ANSM digital health certification requirements for telemedicine platforms create procurement windows for patient identity verification with adaptive risk adjustment. Paris fintech clusters accelerate passwordless authentication pilots using behavioral analytics.
India
RBI directives mandating multi-factor authentication for digital payments above specified thresholds drive bank investments in adaptive risk engines. The central bank's phased implementation timeline compresses procurement cycles for domestic payment processors. Mumbai and Bengaluru technology corridors concentrate cloud-based authentication deployments for retail banking and UPI integration.
Brazil
ANVISA digital health certification requirements for telemedicine platforms generate demand for patient identity verification with adaptive risk adjustment. The central bank's instant payment system modernization accelerates procurement of real-time transaction risk scoring. São Paulo's financial services hub anchors enterprise deployments targeting cart abandonment reduction through invisible authentication layers.
Risk-Based Authentication (RBA) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across technology vectors and deployment models. Cloud-native identity orchestration providers compete against hardware-rooted trust architecture specialists, with hybrid infrastructure vendors capturing premium pricing from regulated financial services. Strategic moves concentrate on API-first platform unbundling and managed service bundling that reduces customer technical staffing requirements.
Within the integrated infrastructure tier, IBM Corporation and Oracle Corporation anchor large financial services deployments through hybrid cloud and database-integrated identity stacks. Thales Group occupies a position among hardware-rooted trust specialists, differentiating offerings for government-grade security requirements with data residency constraints. Okta Inc. exemplifies the cloud-native orchestration archetype, competing through simplified API-based integration that displaces point-product procurement in distributed enterprise environments.
| Leading Market Players |
|---|
| Micro Focus International plc |
| SecureAuth Corporation |
| RSA Security LLC |
| Oracle Corporation |
| Thales Group |
| IBM Corporation |
| Okta Inc. |
| HID Global Corporation |
| Broadcom Inc. |
| Others |
Value Network & Pricing Analysis
Thirty-to-ninety-day implementation timelines for enterprise RBA deployments compress procurement cycles and anchor pricing power with vendors possessing pre-certified integration libraries. Cloud-native providers extract premiums through elastic scaling guarantees while hybrid infrastructure specialists capture margin advantages from GDPR and EU AI Act compliance engineering.
Pricing Analysis
Subscription-tiered SaaS contracts dominate enterprise procurement, with annual recurring revenue models displacing perpetual licensing across North American financial services. Price differentiation centers on API call volume thresholds and SOC 2 Type II certification tiers, with healthcare buyers exhibiting acute sensitivity to per-seat costs. Cost compression in mid-market cloud tiers is intensifying because managed service providers bundle algorithmic tuning at scale, while federal contractors demonstrate the least price sensitivity due to zero-trust mandate urgency.
Supply Chain Analysis
Inbound logistics costs for hardware security modules and biometric sensors face volatility along Asia-Pacific trade lanes serving European assembly facilities. Component sourcing concentrates in Taiwan for semiconductor inference accelerators, Germany for precision biometric hardware, and Ireland for GDPR-compliant data center infrastructure. Raw material dependencies include specialized ASICs, cryptographic processors, and behavioral analytics training datasets. Single-source vulnerability in ML training data aggregation presents structural risk. Distribution runs through hyperscaler marketplaces and systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates multiple viable entry points as enterprises unbundle authentication procurement from professional services, spawning niche opportunities for API-first specialists and managed detection providers.
For Market Incumbents: Fortify hybrid cloud positioning through captive biometric template hosting capabilities that address German and French data residency constraints. Deepen vertical integration into behavioral analytics training data pipelines to defend against substitute pressure from passwordless standards. Prioritize SOC 2 Type II certification maintenance as table stakes for healthcare procurement. For New Entrants and Emerging Players: ANVISA fast-track certification for Brazilian telemedicine platforms opens immediate revenue windows with lower competitive density than saturated North American financial services. Target Indian payment processors adapting to RBI multi-factor authentication thresholds, where cloud-native deployment models bypass legacy on-premises incumbents. Lead with API-first architectures that enable in-house integration teams to displace professional services dependencies. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified cybersecurity conglomerates seeking to monetize non-core identity assets amid portfolio rationalization. Position acquisitions for sustained relevance through continuous authentication technology maturation rather than static multi-factor replacement cycles. Monitor NIST zero-trust implementation velocity across federal contractor ecosystems as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures displace point-product procurement in distributed enterprise environments. |
| Acquisition of Specialist Firm | Behavioral analytics training data providers anchor proprietary fraud-detection model differentiation. |
| Geographic Expansion | EU AI Act compliance engineering creates premium pricing power in German and French markets. |
| Strategic Partnership | Hyperscaler marketplace distribution accelerates procurement velocity for cloud-native entrants. |
| Product Launch | Edge-native authentication nodes address latency requirements for real-time transaction scoring. |
Research Methodology
The analysis maps machine learning cores, behavioral analytics modules, biometric verification layers, and multi-factor authentication baselines, each validated through CTOs at financial institutions, IT procurement officers in healthcare systems, platform engineers at cloud providers, and integration specialists at systems integrators. Primary interview findings triangulate against SEC filings, NIST guideline documentation, EU regulatory filings, and hyperscaler capex disclosures. Bottom-up deployment volume estimates reconcile with top-down market sizing across technology and vertical segments.
Consistency checks validated volume and value outputs against external benchmarks including regulatory mandate implementation timelines and enterprise refresh cycle patterns. The analytical framework models deployment architecture, technology stack, vertical compliance requirements, and integration complexity across the projection horizon. CAGRs derive from segment-level adoption curves weighted by regulatory enforcement schedules. Forecast inputs include NIST SP 800-207 compliance deadlines and RBI phased implementation timelines for payment authentication thresholds.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement momentum and stable hyperscaler infrastructure pricing; material deviation in AI governance timelines or cloud cost structures would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Video Intercom Devices and Equipment Market
Security Software
Anti-Fraud Management System Market
Security Software
Mobile Antivirus Software Market
Security Software
Geofencing Market
Security Software
Global Consumer Identity and Access Management Market
Security Software
Cloud Encryption Software Market
Security Software
Europe IP Video Intercom Device and Equipment Market
Security Software
Public Key Infrastructure (PKI) Market
Security Software
Global Consumer IAM Market
Security Software
Global Mobile Identification Market
Security Software
GDPR Software and Tools Market
Security Software
Data Leakage Prevention Product Market
Security Software
Security Testing Market
Security Software
Security Software Market
Security Software
Passport Reader Market
Security Software
Home Webcam Market