
 Global Consumer Identity and Access Management Market | 2026-2036
Global Consumer Identity and Access Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Consumer Identity and Access Management Market Analysis
Enterprise reseller and managed service provider channels are rewriting how consumer identity platforms reach end buyers. Microsoft Corporation leverages its Azure Active Directory ecosystem to anchor cloud-native identity workloads across retail and financial verticals. Okta Inc. competes through deep SaaS integration partnerships that sustain recurring enterprise commitments. Ping Identity specializes in hybrid deployments that occupy the transitional space between legacy on-premises directories and cloud migration timelines.
Consumer Identity and Access Management encompasses software systems that authenticate, authorize, and administer digital identities for individual end users across web, mobile, and connected device interfaces, typically incorporating biometric verification, behavioral analytics, and tokenized session management to prevent unauthorized account access. These systems serve commercial purposes by reducing fraud exposure, streamlining registration flows, and enabling personalized service delivery under explicit user consent. Cloud-based deployments lead technology adoption due to elastic scaling and reduced infrastructure overhead, while multi-factor authentication represents the fastest-growing deployment category as phishing-resistant protocols displace password-only security. Identity governance solutions command premium margins among financial institutions facing stringent audit requirements for privileged access traceability.
The US Federal Trade Commission enforces data breach notification standards that shape product roadmaps for incident response automation, while the European Union's GDPR and AI Act impose algorithmic transparency mandates on automated identity verification decisions. India's Digital Personal Data Protection Act introduces consent-layer requirements that vendors must architect into consumer-facing workflows. Stakeholders should monitor diverging national digital identity standards to determine where interoperability investments yield sustainable competitive differentiation.
Market Dynamics
Financial institutions are consolidating authentication stacks into single-vendor platforms to satisfy EU AI Act algorithmic transparency mandates while reducing operational fragmentation across hybrid cloud environments.
Growth Catalysts
- GDPR Article 22 compliance:Automated decision-auditing requirements in Europe are forcing banks to replace legacy rule-based identity verification with explainable AI systems that document consent trails.
- Biometric liveness detection:Deepfake-resistant facial recognition protocols are displacing document-centric KYC workflows in Indian neobanks facing RBI digital lending guidelines.
- US digital identity frameworks:State-level mobile driver's license deployments in California, New York, and Arizona are creating interoperable authentication backends for consumer-facing applications.
Market Restraints
- Silicon supply concentration:Hardware security module manufacturing depends on TSMC's advanced node capacity in Taiwan, creating single-source vulnerability for FIDO2 key attestation.
- Cross-border data localization:India's Digital Personal Data Protection Act mandates domestic storage of biometric templates, fragmenting vendor architectures and inflating compliance engineering costs.
- Password manager substitution:Consumer-grade credential vaults from browser vendors are capturing low-risk authentication volumes, compressing entry-tier IAM pricing power.
Strategic Opportunities
- German eID integration:The federal government's AusweisApp ecosystem offers API access for private-sector identity verification, opening regulated onboarding workflows for fintechs and insurers.
- Behavioral biometrics convergence:Keystroke dynamics fused with device fingerprinting enables continuous authentication without friction for US e-commerce checkout flows.
- Managed security service channels:Channel partners are bundling identity governance with SOC offerings, capturing mid-market buyers lacking in-house IAM engineering depth.
Industry Challenges
- Zero-trust architecture skills gap:Enterprise deployment of continuous verification models requires scarce identity architects familiar with SPIFFE/SPIRE frameworks and cloud-native policy engines.
- Legacy directory migration friction:Active Directory forests with decades of nested group policies resist automated refactoring, prolonging hybrid coexistence periods and support cost inflation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Consumer Identity and Access Management Market |
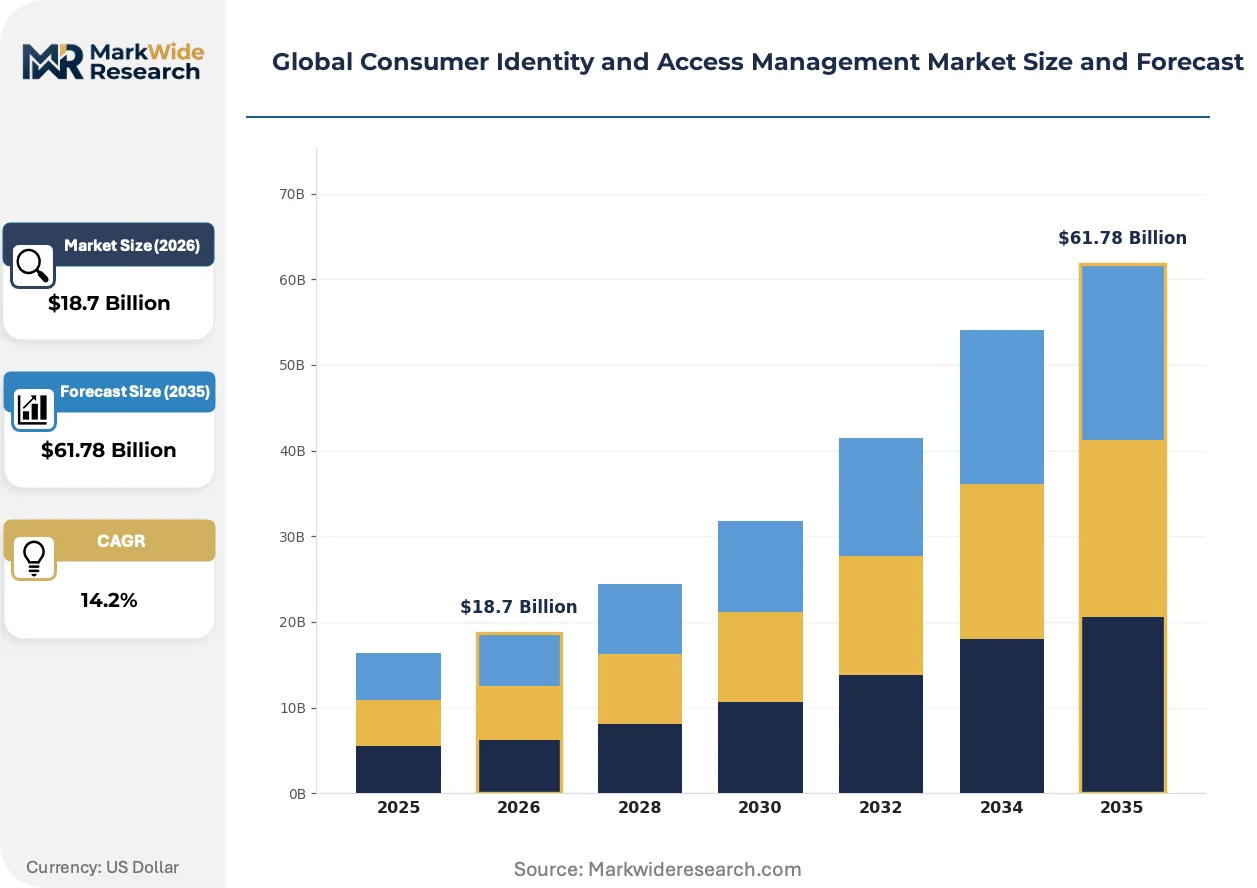
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud-Based, On-Premises, Hybrid, SaaS Deployment: Single Sign-On, Multi-Factor Authentication, Identity Governance, Directory Services Customer Type: Retailers, Financial Institutions, Healthcare Providers, Government Agencies Service Type: Consulting, Integration, Managed Services, Support |
| Companies Covered | Microsoft Corporation, IBM Corporation, Okta Inc., Ping Identity, Salesforce Inc., SAP, Broadcom, Akamai Technologies, ForgeRock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Consumer Identity and Access Management Market Emerging Trajectories
Decentralized identity standards are redistributing control from centralized identity providers to user-held credentials, compressing vendor lock-in dynamics while elevating interoperability engineering as a competitive differentiator.
Passkey authentication built on FIDO2 standards is rendering obsolete SMS-based one-time passwords and knowledge-based verification across US financial services. Chase, Bank of America, and Wells Fargo have committed to passwordless roadmaps by 2025. This shift is compressing fraud investigation teams and redirecting security budgets toward device trust infrastructure.
The EU AI Act's risk classification system for biometric identification systems is forcing vendors to maintain dual product lines: high-risk applications requiring conformity assessments and low-risk flows with lighter documentation. German and French regulators are conducting pre-market reviews of facial recognition algorithms, slowing deployment timelines but creating compliance moats for prepared vendors.
Enterprise buyers are unbundling identity governance from core authentication platforms, selecting specialized tools for access certification and separation-of-duties enforcement. This procurement pattern favors best-of-breed vendors with deep SAP and Oracle ERP integrations over horizontal cloud suites, particularly in European manufacturing and pharmaceutical verticals where audit granularity requirements exceed generic platform capabilities.
Global Consumer Identity and Access Management Market Segmentation
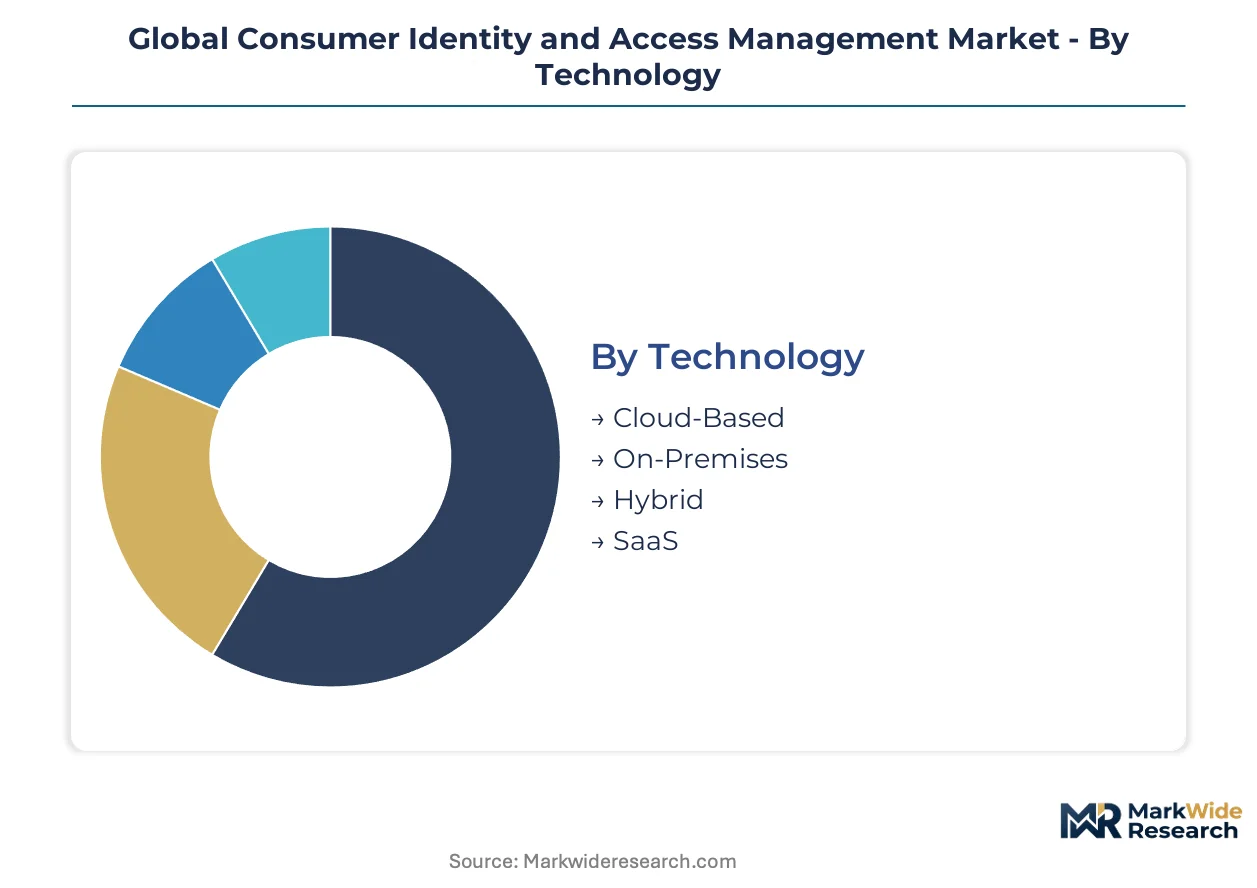
Technology choices in consumer IAM determine infrastructure ownership models and compliance posture across regulated industries. Deployment configurations shape authentication friction and fraud exposure for end users. Customer type and service model selections reflect organizational maturity and in-house security engineering depth.
Technology:
Cost tier separates vendor selection in this category, with capital intensity and operational overhead driving procurement patterns.
- Cloud-Based:Elastic compute resources enable dynamic scaling during authentication traffic spikes without fixed infrastructure commitments. Financial institutions in the United States favor this model for digital onboarding workloads subject to FTC data breach notification timelines.
- Hybrid:Split architectures maintain sensitive credential hashing on-premises while federating session management to cloud endpoints. German insurers deploying AusweisApp integrations require this configuration to satisfy domestic data residency requirements alongside EU AI Act algorithmic transparency mandates.
- On-Premises:Dedicated hardware deployments serve air-gapped environments in defense and critical infrastructure sectors.
- SaaS:Subscription delivery models compress time-to-value for mid-market retailers lacking identity engineering teams.
Cloud-Based holds installed capacity. Hybrid is rotating up the share rankings.
Deployment:
Application context determines which authentication layer addresses the specific threat model facing each organization.
- Multi-Factor Authentication:Phishing-resistant protocols using FIDO2 hardware keys or biometric liveness detection displace password-only security. Indian neobanks facing RBI digital lending guidelines deploy deepfake-resistant facial recognition to satisfy KYC automation requirements.
- Identity Governance:Access certification workflows and separation-of-duties enforcement command premium pricing from European pharmaceutical manufacturers with SAP ERP audit granularity needs exceeding generic platform capabilities.
- Single Sign-On:Session federation reduces credential fatigue across SaaS application portfolios.
- Directory Services:Legacy Active Directory forests and cloud-native LDAP alternatives anchor user attribute storage.
Multi-Factor Authentication is climbing the fastest. Identity Governance holds installed capacity.
Customer Type:
Volume concentration varies sharply by sector, with transaction value and regulatory scrutiny shaping authentication investment intensity.
- Financial Institutions:Consolidating authentication stacks into single-vendor platforms to satisfy EU AI Act mandates while reducing operational fragmentation. Chase, Bank of America, and Wells Fargo have committed to passwordless roadmaps, redirecting security budgets toward device trust infrastructure.
- Government Agencies:State-level mobile driver's license deployments in California, New York, and Arizona create interoperable authentication backends for consumer-facing applications.
- Retailers:Behavioral biometrics integration enables continuous authentication without checkout friction for US e-commerce flows.
- Healthcare Providers:HIPAA compliance drives privileged access traceability for clinical systems handling protected health information.
Financial Institutions holds installed capacity. Government Agencies is rotating up the share rankings.
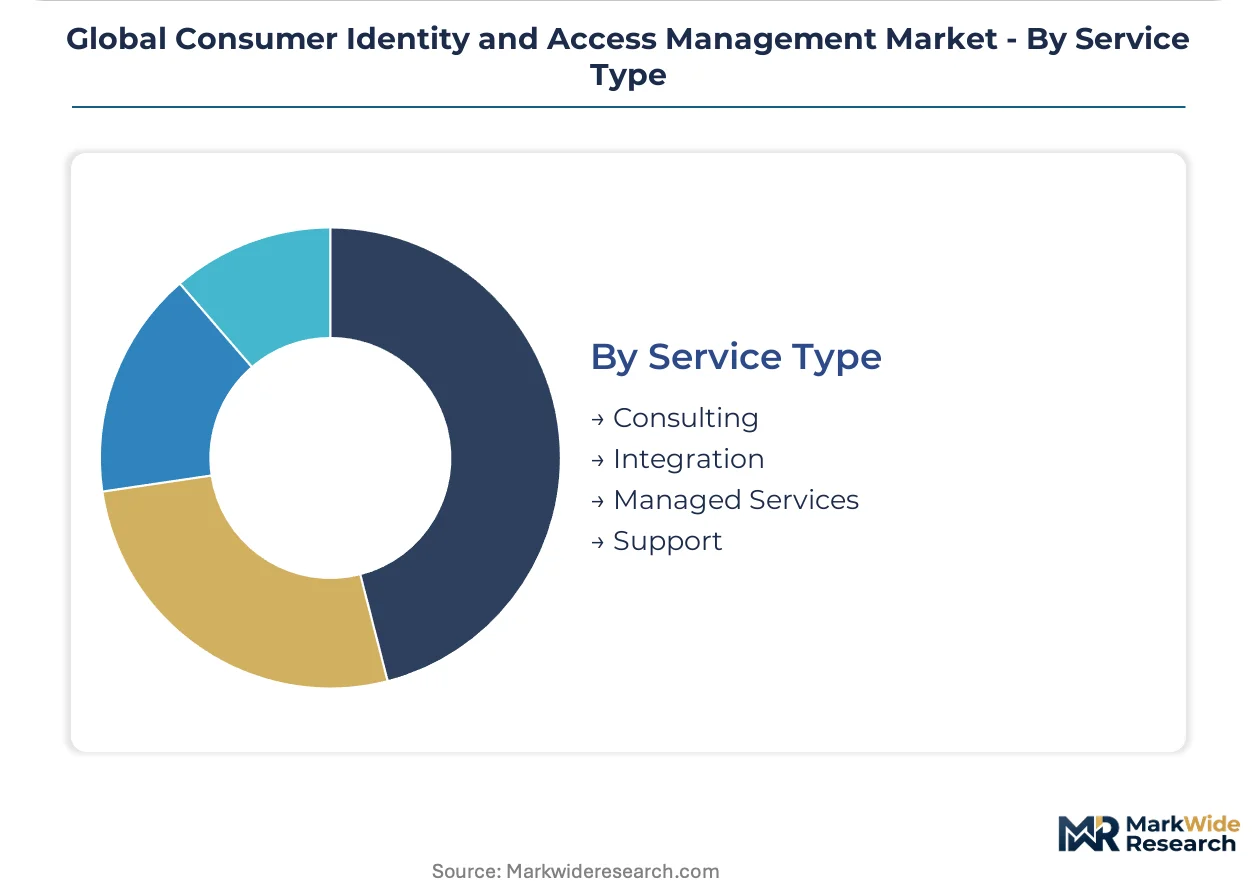
Service Type:
Customer maturity and in-house capability gaps determine whether buyers consume IAM as engineering labor, operational transfer, or ongoing managed outcome.
- Managed Services:Channel partners bundle identity governance with SOC offerings, capturing mid-market buyers lacking in-house IAM engineering depth. This model accelerates zero-trust architecture deployment where SPIFFE/SPIRE framework expertise remains scarce.
- Integration:Professional services refactor legacy Active Directory forests with decades of nested group policies, prolonging hybrid coexistence periods.
- Consulting:Advisory engagements map regulatory requirements to technical controls for EU AI Act and GDPR Article 22 compliance.
- Support:Tiered response contracts maintain operational continuity for production authentication infrastructure.
Managed Services is expanding most quickly. Integration holds installed capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government digital identity frameworks and financial sector compliance mandates are reshaping procurement patterns across major economies. National regulators are embedding authentication requirements into banking licenses and data protection statutes. Vendors must architect multi-jurisdictional deployments to serve multinational clients.
United States
State-level mobile driver's license programs in California, New York, and Arizona are creating interoperable authentication backends for consumer applications. The FTC enforces data breach notification standards that shape product roadmaps for incident response automation. Chase, Bank of America, and Wells Fargo have committed to passwordless roadmaps by 2025, redirecting security budgets toward device trust infrastructure in the New York and Charlotte financial centers.
Germany
The federal government's AusweisApp ecosystem offers API access for private-sector identity verification, opening regulated onboarding workflows for fintechs and insurers. GDPR Article 22 and the EU AI Act impose algorithmic transparency mandates on automated identity verification decisions. Frankfurt's financial district and Munich's insurance cluster are deploying hybrid architectures to satisfy domestic data residency alongside EU compliance requirements.
India
Neobanks facing RBI digital lending guidelines are deploying deepfake-resistant facial recognition to satisfy KYC automation requirements. The Digital Personal Data Protection Act mandates domestic storage of biometric templates, fragmenting vendor architectures. Bangalore's technology corridor and Mumbai's financial district are driving demand for cloud-native identity platforms with localized data centers.
United Kingdom
Financial conduct authority guidelines are pushing banks toward explainable AI systems for credit and identity decisions. Post-Brexit divergence from EU frameworks creates dual compliance obligations for cross-border institutions. London's fintech cluster and Edinburgh's banking sector are consolidating authentication stacks into single-vendor platforms to reduce operational fragmentation.
Japan
METI initiatives for digital identity infrastructure are accelerating enterprise adoption of FIDO2 and biometric authentication standards. Aging demographics are driving demand for frictionless authentication in retail and healthcare applications. Tokyo's financial district and Osaka's manufacturing belt are investing in behavioral biometrics for continuous authentication without user burden.
Global Consumer Identity and Access Management Market Vendor Landscape
On the supply side, the industry is consolidating around integrated cloud platforms with hybrid deployment capabilities. Large technology conglomerates and specialized identity vendors compete for enterprise authentication workloads. Three archetypes dominate: hyperscale cloud providers with directory ecosystems, pure-play SaaS identity specialists, and legacy infrastructure vendors managing hybrid transitions. Competitive moves center on strategic partnerships with financial institutions and geographic expansion through managed service channels.
Within the hyperscale tier, Microsoft Corporation anchors cloud-native identity workloads through its Azure Active Directory ecosystem across retail and financial verticals. Okta Inc. and Ping Identity occupy specialized positions, with Okta exemplifying deep SaaS integration partnerships and Ping Identity representing hybrid deployment expertise for transitional on-premises-to-cloud migrations. These three companies illustrate the strategic segmentation between full-stack platform provision and targeted authentication specialization.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Okta Inc. |
| Ping Identity |
| Salesforce Inc. |
| SAP |
| Broadcom |
| Akamai Technologies |
| ForgeRock |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Taiwan's advanced semiconductor foundries is compressing margins for hardware security module manufacturers while simultaneously enabling aggressive pricing from cloud-native identity platforms that consume this silicon. This utilization dynamic creates divergent cost structures between on-premises hardware-dependent deployments and elastic SaaS consumption models.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement, with three-tier pricing separating premium identity governance suites from standard multi-factor authentication bundles and economy-tier directory services. Price differentiation hinges on certification grade (ISO 27001, SOC 2 Type II) and integration complexity with legacy ERP systems. Pricing pressure stems from browser-native password managers capturing low-risk authentication volumes, compressing entry-tier margins. Mid-market retailers exhibit highest price sensitivity, while financial institutions facing EU AI Act compliance obligations demonstrate lowest sensitivity due to regulatory risk premiums.
Supply Chain Analysis
Upstream feedstock for FIDO2 hardware keys and secure enclave components draws from Taiwan, South Korea, and China's semiconductor packaging corridors. Critical dependencies include advanced node silicon wafers, cryptographic co-processors, and biometric sensor modules. Single-source vulnerability concentrates in TSMC's 5nm and 7nm capacity for trusted platform modules. Distribution runs through hyperscale cloud marketplaces, managed security service providers, and direct enterprise sales channels serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, with passwordless authentication roadmaps at major US financial institutions creating durable demand tailwinds for device trust infrastructure and behavioral biometrics platforms.
For Market Incumbents: Harden hybrid deployment capabilities against pure-play SaaS challengers by maintaining on-premises credential vaulting expertise for German and Indian data residency requirements. Invest in EU AI Act conformity assessment pre-certification to build compliance moats before regulatory enforcement intensifies. Prioritize channel control through managed security service provider partnerships that bundle identity governance with SOC offerings.
For New Entrants and Emerging Players: Mid-market healthcare providers in the United States represent the most penetrable entry point, given HIPAA compliance gaps and limited in-house IAM engineering depth. Indian neobanks facing RBI digital lending guidelines offer a secondary white-space target for deepfake-resistant biometric verification. A device-agnostic, API-first go-to-market angle bypasses incumbent lock-in through embedded integration partnerships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among SaaS-native identity platforms with embedded workflow automation and vertical-specific compliance modules. Long-term viability over a multi-year horizon favors vendors with demonstrated EU AI Act and GDPR Article 22 audit trail capabilities. The signal to monitor is state-level mobile driver's license deployment velocity in California, New York, and Arizona, which will determine interoperable authentication backend demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding identity verification into SAP and Oracle ERP workflows captures European manufacturing audit granularity requirements. |
| Strategic Partnership | Managed security service provider alliances accelerate zero-trust architecture deployment where SPIFFE/SPIRE expertise remains scarce. |
| Acquisition of Specialist Firm | Behavioral biometrics capabilities address US e-commerce demand for continuous authentication without checkout friction. |
| Geographic Expansion | Localized data centers in Bangalore and Mumbai satisfy India's Digital Personal Data Protection Act biometric storage mandates. |
| Product Launch | Passkey authentication roadmaps at Chase, Bank of America, and Wells Fargo redirect security budgets toward device trust infrastructure. |
Methodological Framework
A standing panel of chief information security officers, identity architects, cloud procurement officers, and managed security service provider executives provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against SEC filings, hyperscaler capex disclosures, App Annie mobile authentication adoption data, and regulatory filing databases. Bottom-up and top-down triangulation anchored volume estimates to actual deployment footprints.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning deployment model, organization size, vertical regulatory intensity, integration complexity, and regional adoption pattern. CAGRs derived from elasticity modeling against authentication transaction volumes and compliance-driven replacement cycles. Industry-specific forecast inputs included EU AI Act implementation timelines and state-level mobile driver's license rollout schedules.
Macroeconomic conditions sit as an overlay; deviation in enterprise IT spending cycles and semiconductor capacity utilization would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and interoperability standard adoption. Cross-checking against hyperscaler identity service revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Endpoint Detection and Response [EDR] Market
Security Software
Asia-Pacific Fraud Detection & Prevention Market
Security Software
Internet Filter Software Market
Security Software
Global Hardware Security Modules (HSM) Market
Security Software
Cybersecurity Software Market
Security Software
Biometric POS Terminals Market
Security Software
Identity-As-A-Service (Idaas) Market
Security Software
Global Mobile Security Software Market
Security Software
Global Data Classification Market
Security Software
Spam Blocking Software Market
Security Software
Global Data Breach Notification Software Market
Security Software
Consumer Endpoint Security Market
Security Software
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market
Security Software
Secure Flash Drive Market
Security Software
US Hardware OTP Token Authentication Market
Security Software
Global Log Management Market