
 Network Camera Market | 2026-2036
Network Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Network Camera Market Analysis
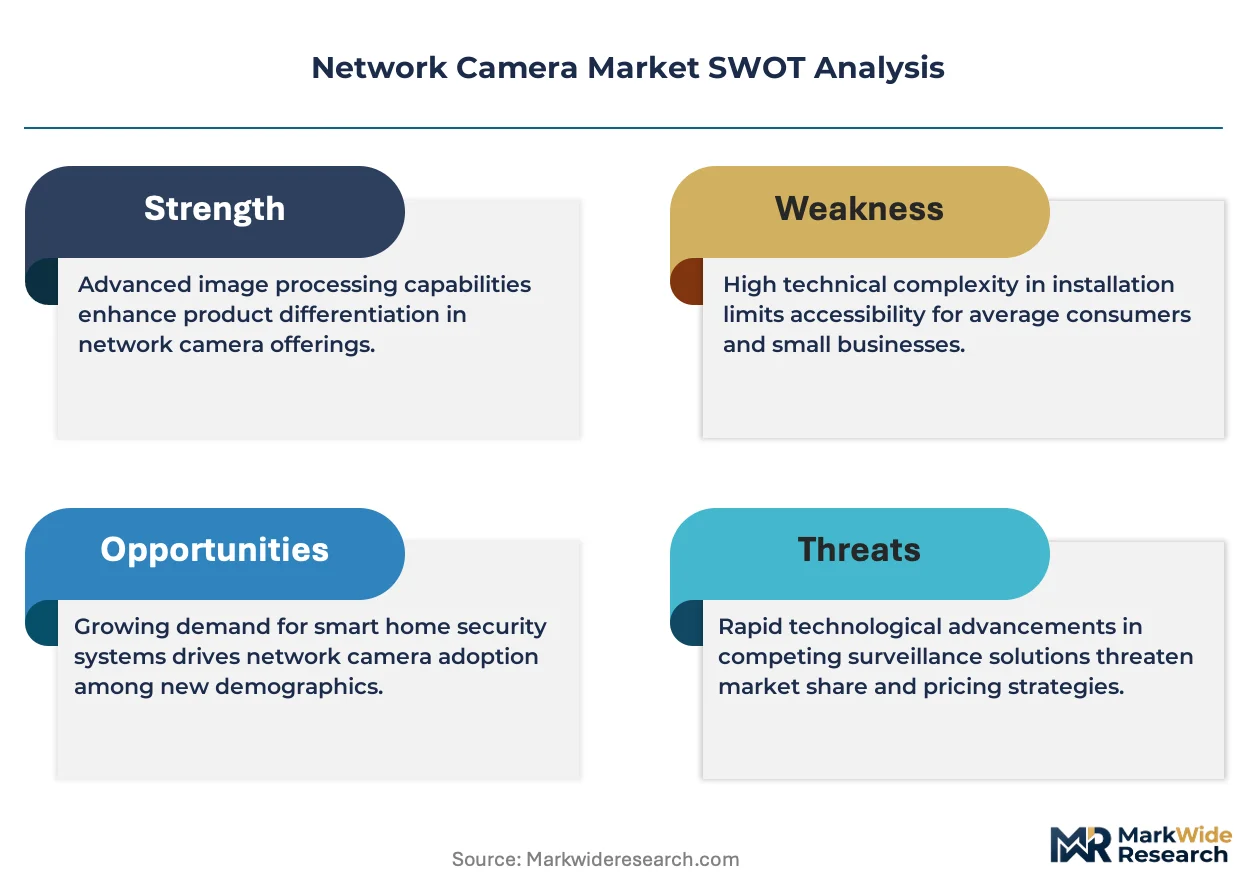
ONVIF Profile S and T certification is bifurcating the competitive landscape into interoperable ecosystem vendors and proprietary platform operators. Axis Communications leverages its open-architecture philosophy to sustain channel partnerships across enterprise verticals. Dahua Technology anchors its position through backward integration into image sensor and SoC design. Bosch Security Systems differentiates via German-engineered reliability standards that command premium positioning in critical infrastructure bids.
A network camera is an internet protocol-connected imaging device that digitizes, compresses, and streams video across Ethernet or wireless networks, typically employing H.265/H.266 codecs and edge-based analytics processors to enable real-time object detection without centralized server dependency. Dome and bullet housings dominate volume shipments, while PTZ configurations capture disproportionate margin pools in perimeter defense and critical infrastructure monitoring. Wireless technology segments are expanding fastest in retrofit residential and small commercial deployments where structured cabling proves cost-prohibitive.
FCC Part 15 emissions compliance gates US market access for radio-enabled models, while GDPR and the EU AI Act constrain facial recognition feature rollouts across European government and retail installations. China's GB/T 28181 standard mandates encrypted transmission protocols for all public security network cameras, creating a regulatory moat for domestic manufacturers. Stakeholders must monitor divergence between regional data sovereignty requirements and the interoperability demands of multinational enterprise accounts.
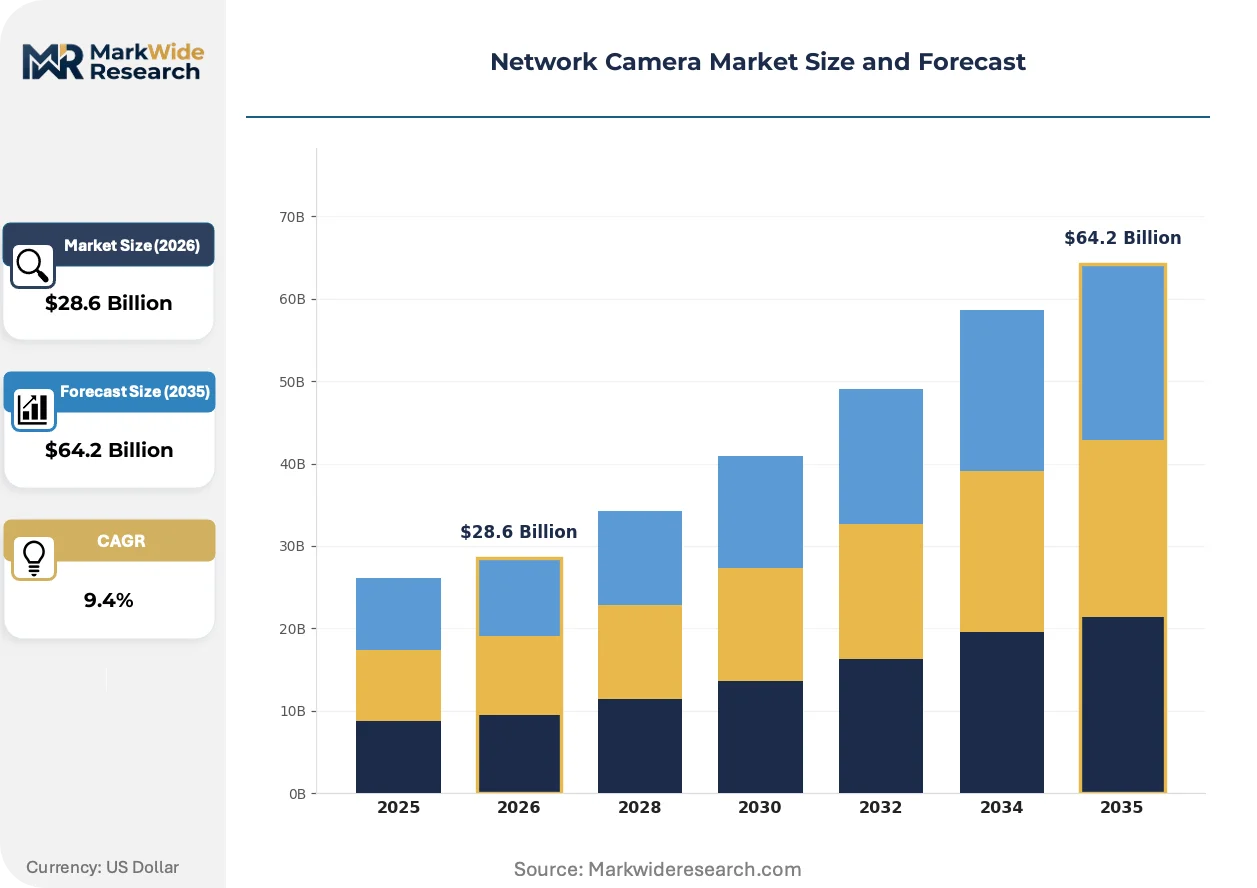
Market Dynamics
The network camera market is bifurcating around edge AI compute architectures that enable real-time analytics without server dependency, compressing traditional centralized VMS value chains while elevating SoC and firmware capabilities to primary competitive differentiators.
Growth Catalysts
- Smart city infrastructure mandates:Singapore's Safe City program and comparable initiatives in Dubai and Barcelona are accelerating procurement of AI-enabled surveillance systems with integrated traffic and crowd management capabilities.
- EU AI Act compliance deadlines:Facial recognition deployment restrictions are creating replacement cycles for GDPR-certified equipment across European government and retail installations.
- Wireless retrofit demand:Wi-Fi 6 and 6E penetration in residential and small commercial buildings is displacing structured cabling requirements in renovation projects.
Market Restraints
- Image sensor supply concentration:Sony and OmniVision control premium CMOS supply, exposing OEMs to allocation volatility during semiconductor demand spikes.
- GB/T 28181 encryption mandates:China's national standard for public security network cameras creates technical barriers for non-domestic manufacturers seeking government contracts.
- Cloud storage substitution:Hybrid cloud-NVR architectures are compressing on-premise NVR hardware attach rates in mid-market enterprise deployments.
Strategic Opportunities
- India smart city expansion:The country's 100 Smart Cities Mission remains underpenetrated for AI-enabled surveillance, with municipal budgets scaling through central government PLI scheme support.
- Healthcare patient monitoring:Fall detection and behavioral analytics applications are emerging in aged care facilities and hospital wards, requiring HIPAA-aligned edge processing.
- ONVIF Profile M convergence:Audio and metadata standardization is enabling multi-sensor integration opportunities for analytics vendors previously locked to proprietary protocols.
Industry Challenges
- Edge AI firmware talent scarcity:Embedded computer vision engineering skills concentrate in Shenzhen and Taipei, forcing Western OEMs into costly relocation or acquisition strategies.
- Multi-certification timeline compression:Simultaneous FCC Part 15, CE marking, and BIS compliance requirements extend product launch cycles by 8-14 months for multi-region launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Camera Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome, Bullet, PTZ, Fish-eye Technology: IP-Based, Wireless, Thermal, Analog End User: Retail, Transportation, Government, Residential Installation: Indoor, Outdoor, Wall-Mounted, Ceiling-Mounted |
| Companies Covered | Hangzhou Hikvision Digital Technology, Axis Communications, Dahua Technology, Bosch Security Systems, Honeywell International, Sony Corporation, Panasonic Corporation, Samsung Electronics, Hanwha Vision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Camera Market Emerging Trajectories
Computational imaging and sovereign data architectures are restructuring how video intelligence is generated, transmitted, and governed across enterprise and public sector deployments.
H.266/VVC codec adoption is displacing H.265/HEVC in bandwidth-constrained installations such as remote perimeter defense and cellular-connected mobile units. Critical infrastructure operators in Scandinavia and Australia's mining corridors are deploying VVC-enabled cameras to halve backhaul costs over satellite links. This compression efficiency is displacing low-resolution legacy equipment that previously dominated cost-sensitive remote monitoring.
The EU AI Act's risk-based classification system is forcing facial recognition vendors to segregate product lines between "unacceptable risk" biometric applications and "limited risk" opt-in retail analytics. German automotive manufacturers are now requiring supply chain partners to document AI conformity assessments for factory floor monitoring equipment. This regulatory friction is compressing deployment timelines for emotion recognition and predictive behavior analytics across European retail banking.
Outcome-based service contracts are replacing capital expenditure models in North American multi-site retail and logistics chains. Amazon's fulfillment network and comparable operators are unbundling hardware ownership from video-analytics-as-a-service subscriptions, transferring cybersecurity and firmware maintenance liability to integrators. This shift is most visible in the US Southeast's warehouse construction corridor, where specifiers now prioritize API flexibility over upfront equipment cost.
Network Camera Market Segmentation
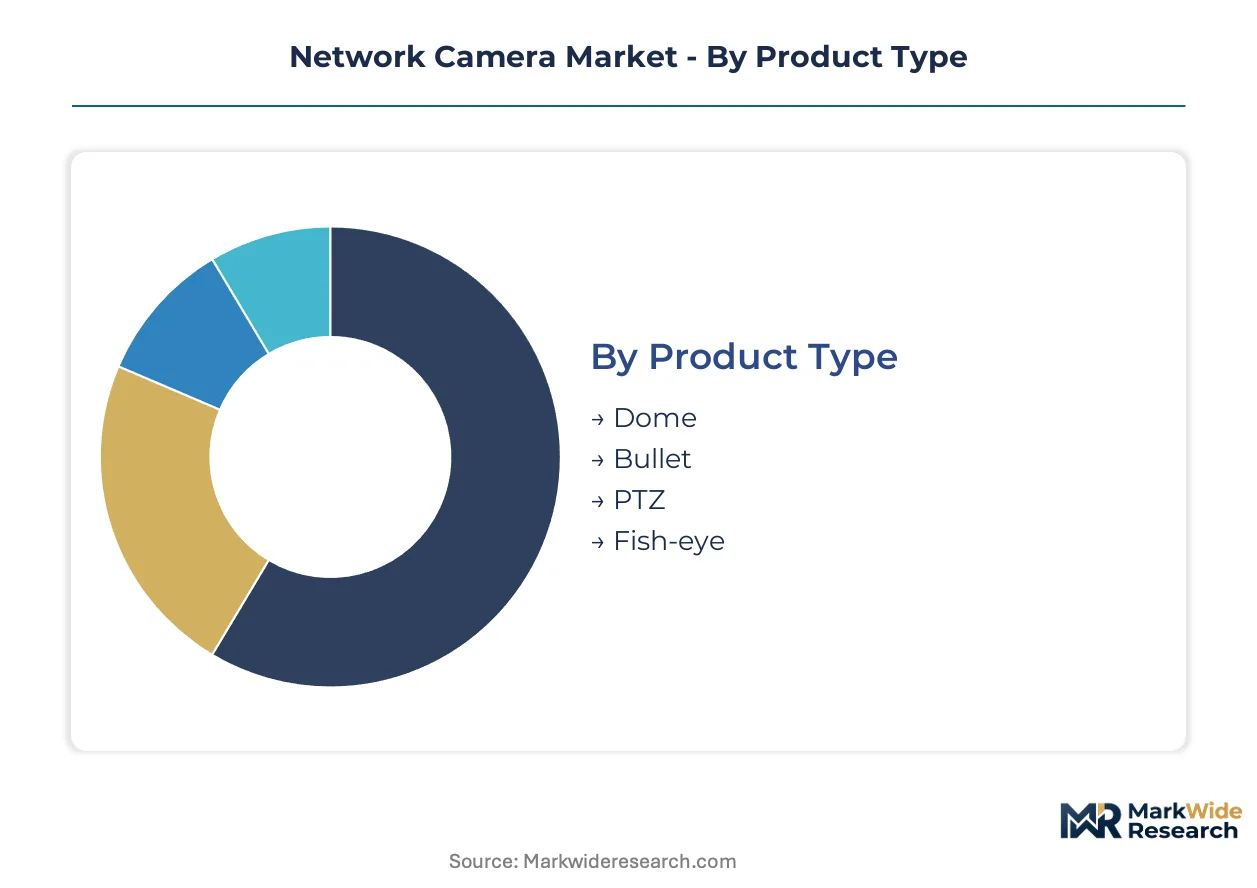
Network camera procurement decisions hinge on environmental constraints, connectivity infrastructure, and regulatory compliance scope. Segment boundaries increasingly blur as edge AI capabilities and hybrid cloud architectures reshape traditional hardware categories.
Product Type:
Regulatory differentiation across housing standards shapes procurement specifications, with explosion-proof and vandal-resistant certifications gating access to critical infrastructure and transit authority contracts.
- Dome:Hemispherical housings with tamper-resistant polycarbonate domes suit discrete indoor surveillance and aesthetic-sensitive retail environments. Singapore's Safe City program and Dubai metro systems specify IK10-rated dome variants for high-vandalism public spaces, driven by smart city infrastructure mandates requiring unobtrusive form factors.
- Bullet:Cylindrical housings with integrated sunshades and weather sealing dominate perimeter defense and long-range corridor monitoring. China's eastern coastal manufacturing corridors favor bullet cameras for factory floor coverage, where dust-resistant IP67 ratings and integrated IR illumination reduce maintenance overhead in high-particulate environments.
- PTZ:Motorized pan-tilt-zoom mechanisms with optical zoom ranges exceeding 30x serve perimeter defense and critical infrastructure monitoring. German automotive manufacturers require PTZ units with AI conformity assessments under EU AI Act supply chain documentation rules.
- Fish-eye:Ultra-wide-angle lenses delivering 360-degree coverage through single-sensor dewarping algorithms suit compact retail spaces and elevator lobbies. Scandinavian critical infrastructure operators deploy VVC-enabled fish-eye units to halve satellite backhaul costs in remote monitoring.
Established volume favors dome and bullet configurations; emerging adoption favors fish-eye deployments in space-constrained retrofit installations.
Technology:
Cost tier differentiation separates enterprise-grade edge AI deployments from budget-constrained residential retrofit projects, with connectivity infrastructure determining viable technology pathways.
- IP-Based:Ethernet-connected devices employing H.265/H.266 codecs and ONVIF protocol compliance dominate enterprise and government verticals. FCC Part 15 emissions compliance gates US market access for radio-enabled variants, while China's GB/T 28181 encryption mandates create procurement barriers for non-domestic manufacturers in public security tenders.
- Wireless:Wi-Fi 6 and 6E-enabled cameras eliminate structured cabling requirements in renovation projects. North American multi-site retail chains and residential retrofits drive fastest expansion, though bandwidth constraints limit streaming resolution compared to wired alternatives.
- Thermal:Uncooled microbolometer sensors detecting infrared radiation enable detection through smoke, fog, and complete darkness. Australia's mining corridors and Scandinavian remote perimeter defense deploy thermal units for intrusion detection without visible illumination.
- Analog:Coaxial-connected legacy devices persist in budget-constrained small commercial installations and incremental upgrade scenarios. Replacement cycles accelerate as hybrid DVR-NVR architectures compress attach rates for dedicated analog recording hardware.
IP-based architectures capture premium enterprise positioning; wireless configurations are climbing the fastest in renovation-intensive residential and small commercial segments.
End User:
Application-specific analytics requirements reshape feature prioritization, with facial recognition compliance deadlines and patient privacy mandates creating divergent procurement specifications.
- Retail:Footfall analytics, queue management, and loss prevention applications prioritize edge-based object detection with GDPR-certified data handling. EU AI Act risk classifications force segregation between biometric and opt-in analytics deployments across European installations.
- Transportation:License plate recognition, traffic flow optimization, and crowd density monitoring require PTZ and thermal configurations with integrated edge processors. Singapore's Safe City program specifications influence procurement templates across comparable smart city initiatives.
- Government:Public safety and critical infrastructure monitoring demand sovereign data architectures with encrypted transmission protocols. China's GB/T 28181 standard and India's PLI scheme support create divergent compliance pathways for domestic versus multinational suppliers.
- Residential:Cloud-integrated consumer devices with mobile app control and DIY installation dominate volume shipments. Wi-Fi 6 penetration and subscription-based storage models displace on-premise NVR requirements in North American and European markets.
Government and transportation verticals anchor premium pricing; residential adoption expands most quickly through subscription-model unbundling of hardware ownership.
Installation:
Customer type differentiation separates spec-driven enterprise projects from consumer self-installation, with mounting constraints determining form factor and connectivity choices.
- Indoor:Climate-controlled environments permit compact dome and fish-eye configurations without extreme temperature ratings. HIPAA-aligned edge processing requirements emerge in US aged care facilities and hospital wards deploying fall detection analytics.
- Outdoor:Weather-resistant housings with IP66+ ratings and integrated heaters sustain operation across temperature extremes. Mining corridors in Australia and Scandinavia specify VVC-enabled outdoor units for bandwidth-constrained remote monitoring.
- Wall-Mounted:Vertical surface attachment suits perimeter defense and corridor monitoring with unobstructed fields of view. Bullet and PTZ configurations dominate this mounting category for long-range optical performance.
- Ceiling-Mounted:Overhead placement optimizes coverage density in retail floors, transit concourses, and open-plan offices. Dome and fish-eye form factors exploit ceiling mounting for 360-degree surveillance with minimal aesthetic intrusion.
Ceiling-mounted dome configurations dominate indoor commercial volume; outdoor wall-mounted bullet and PTZ units command premium positioning in perimeter defense applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise security buyers cluster around sovereign data requirements and smart city procurement pipelines. Government verticals in Asia-Pacific and Europe drive premium specification demand. Industrial retrofit activity concentrates in North American logistics corridors.
United States
Amazon's fulfillment network and comparable logistics operators are unbundling hardware ownership from video-analytics-as-a-service subscriptions. FCC Part 15 emissions compliance gates market access for radio-enabled models. The US Southeast's warehouse construction corridor now prioritizes API flexibility over upfront equipment cost in procurement specifications.
Germany
Automotive manufacturers require supply chain partners to document AI conformity assessments for factory floor monitoring equipment under EU AI Act rules. German-engineered reliability standards command premium positioning in critical infrastructure bids. Industrial clusters in Bavaria and Baden-Württemberg are replacing legacy surveillance with GDPR-certified systems ahead of compliance deadlines.
China
Eastern coastal manufacturing corridors favor bullet cameras for factory floor coverage where dust-resistant IP67 ratings reduce maintenance overhead. GB/T 28181 encryption mandates create a regulatory moat for domestic manufacturers in public security tenders. Shenzhen and Taipei concentrate embedded computer vision engineering talent for edge AI firmware development.
Singapore
The Safe City program accelerates procurement of AI-enabled surveillance systems with integrated traffic and crowd management capabilities. IK10-rated dome variants are specified for high-vandalism public spaces. Smart city infrastructure mandates from Singapore influence procurement templates across comparable initiatives in Dubai and Barcelona.
India
The 100 Smart Cities Mission remains underpenetrated for AI-enabled surveillance with municipal budgets scaling through central government PLI scheme support. BIS compliance requirements extend product launch timelines for multinational entrants. Procurement activity concentrates in Maharashtra and Gujarat where state-level urban infrastructure programs are deploying integrated security ecosystems.
Network Camera Market Vendor Landscape
Player mix skews toward diversified electronics conglomerates with captive semiconductor supply chains and specialized security pure-plays with verticalized software stacks. Market structure exhibits tiered consolidation around three strategic archetypes: open-architecture ecosystem vendors, proprietary platform operators with backward integration into image sensors, and German-engineered reliability specialists. Dominant competitive moves include M&A to acquire edge AI firmware capabilities and strategic partnerships to secure ONVIF certification compliance.
Within the open-architecture tier, Axis Communications represents interoperability-focused positioning through channel partnership sustainment across enterprise verticals. Dahua Technology exemplifies backward integration strategy with in-house production of image sensors and SoC design. Bosch Security Systems anchors premium-tier positioning through reliability engineering that commands critical infrastructure bid preference. These three players illustrate divergent responses to ONVIF Profile S and T certification bifurcation.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology |
| Axis Communications |
| Dahua Technology |
| Bosch Security Systems |
| Honeywell International |
| Sony Corporation |
| Panasonic Corporation |
| Samsung Electronics |
| Hanwha Vision |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day image sensor lead times from Sony and OmniVision concentrate pricing power among domestic OEMs with captive semiconductor supply, while forcing Western vendors into premium positioning or margin compression. This inventory dynamic amplifies cost advantages for Shenzhen-based manufacturers bidding on GB/T 28181-compliant public security tenders in China.
Pricing Analysis
Cost-plus contracts indexed to CMOS sensor spot prices dominate enterprise procurement, with three-tier pricing structure across premium, standard, and economy levels separating German-engineered critical infrastructure units from Chinese OEM volume plays. Price differentiation hinges on ONVIF certification grade and edge AI compute capability. Cost compression in mid-market IP cameras is intensifying because hybrid cloud-NVR architectures displace on-premise recording hardware attach rates. Government verticals exhibit lowest price sensitivity; residential retrofit buyers drive hardest bargain negotiations.
Supply Chain Analysis
Taiwan Strait shipping lanes underpin semiconductor logistics for network camera SoCs, with production gravity centering on Shenzhen, Taipei, and Seoul for image sensors, edge processors, and wireless modules. Raw material dependencies span CMOS wafers, polycarbonate dome housings, and rare-earth magnet components for PTZ motors. Single-source vulnerability concentrates in Sony's premium sensor allocation during demand spikes. Distribution runs through integrator channel partners serving enterprise verticals and direct-to-installer platforms for residential retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Video-analytics-as-a-service subscriptions are expanding faster than hardware shipments across North American logistics chains, transforming capital expenditure models into recurring revenue architectures with superior lifetime value capture.
For Market Incumbents: Secure edge AI firmware engineering talent in Shenzhen and Taipei through acquisition or relocation subsidies before capability scarcity widens competitive gaps. Defend channel partnerships by accelerating ONVIF Profile M certification for audio-metadata integration, countering proprietary platform lock-in from backward-integrated Chinese OEMs. Prioritize German-engineered reliability positioning in EU AI Act compliance cycles to sustain premium pricing. For New Entrants and Emerging Players: BIS fast-track certification for India's 100 Smart Cities Mission offers lowest barrier-to-entry among major government verticals, with municipal budgets scaling through central PLI scheme support. Target healthcare patient monitoring in US aged care facilities requiring HIPAA-aligned edge processing, where incumbent presence remains thin. Pursue outcome-based service contracts unbundling hardware ownership to bypass capital expenditure procurement friction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across wireless retrofit segments where Wi-Fi 6 penetration eliminates structured cabling infrastructure requirements. Long-term viability favors specialized analytics pure-plays with verticalized software stacks over diversified electronics conglomerates facing margin compression. Watch VVC codec adoption rates in bandwidth-constrained installations as signal for compression-technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Firmware Acquisition | Embedded computer vision engineering in Shenzhen closes capability gaps against domestic OEMs. |
| ONVIF Profile M Certification | Audio-metadata standardization unlocks multi-sensor integration for analytics vendors. |
| Outcome-Based Service Contracts | Amazon fulfillment network models transfer cybersecurity liability to integrator partners. |
| VVC Codec Product Transition | Scandinavian mining corridor deployments halve satellite backhaul costs for remote units. |
| GB/T 28181 Compliance Investment | Encryption mandates create regulatory moat for domestic manufacturers in China tenders. |
Methodological Framework
Initial hypotheses were tested against primary input from security systems integrators, municipal procurement officers, edge AI firmware engineers, and enterprise IT directors, then refined against customs trade data, FCC equipment authorization filings, SEC 10-K disclosures from listed OEMs, and smart city tender databases. Bottom-up unit economics from component bill-of-materials analysis were triangulated with top-down market sizing from regional infrastructure spending commitments.
Variance-decomposition framing separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product housing type, connectivity technology, end-use vertical, regional regulatory cluster, and edge compute capability tier. CAGRs were derived from installed base replacement cycles and greenfield smart city procurement pipelines, with specific inputs from image sensor allocation forecasts and Wi-Fi 6 penetration curves in renovation-intensive buildings.
Underlying assumptions cover sustained semiconductor supply normalization, stable China-India trade corridors for component sourcing, and EU AI Act enforcement timelines, with deviation risk concentrated in export control expansions affecting SoC foundry access. Practitioners should keep alternative scenarios live as sovereign data architecture requirements and regional encryption mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Mobile Identity Management Market
Security Software
Employee Surveillance and Monitoring Software Market
Security Software
Smartphone Security Market
Security Software
Remote Access Management Market
Security Software
ATM Security Market
Security Software
Mass Notification System Market
Security Software
Europe Smart Doorbell Market
Security Software
Anomaly Detection Tools Market
Security Software
Privileged Access Management (PAM) Market
Security Software
Banking Encryption Software Market
Security Software
Global Anti-Spam Software Market
Security Software
Digital Risk Protection Software Market
Security Software
Global Data Loss Prevention Software Market
Security Software
Global Mobile Security Software Market
Security Software
Global IMSI Catcher Market
Security Software
Global Background Screening Market