
 Singapore Data Center Networking Market | 2026-2036
Singapore Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Data Center Networking Market Insights
Software-defined networking is reshaping how data center fabrics are architected across Singapore's facilities, decoupling control planes from hardware to enable programmable traffic management. Cisco Systems Inc. leverages its merchant silicon partnerships to sustain pricing flexibility in high-density switching. Arista Networks Inc. dominates the cloud-scale segment with operating systems purpose-built for leaf-spine architectures. Juniper Networks Inc. anchors its position through Apstra-based intent networking that automates multi-vendor deployments.
Singapore data center networking encompasses the switching, routing, security, and traffic management infrastructure that interconnects compute and storage resources within and between facilities, typically operating at speeds from 25 Gbps at the server access layer to 400 Gbps and beyond in core aggregation tiers. The primary purpose is to deliver deterministic, low-latency packet forwarding that meets service-level agreements for financial trading, cloud services, and enterprise applications. Ethernet switching captures the largest installed base among product types, though SDN-enabled fabrics represent the fastest-growing technology dimension as operators seek centralized policy orchestration across hybrid deployments. Load balancers command premium margins where application delivery controllers handle encrypted traffic at scale, while traditional firewall appliances face displacement from software-defined perimeter approaches in multi-tenant colocation environments.
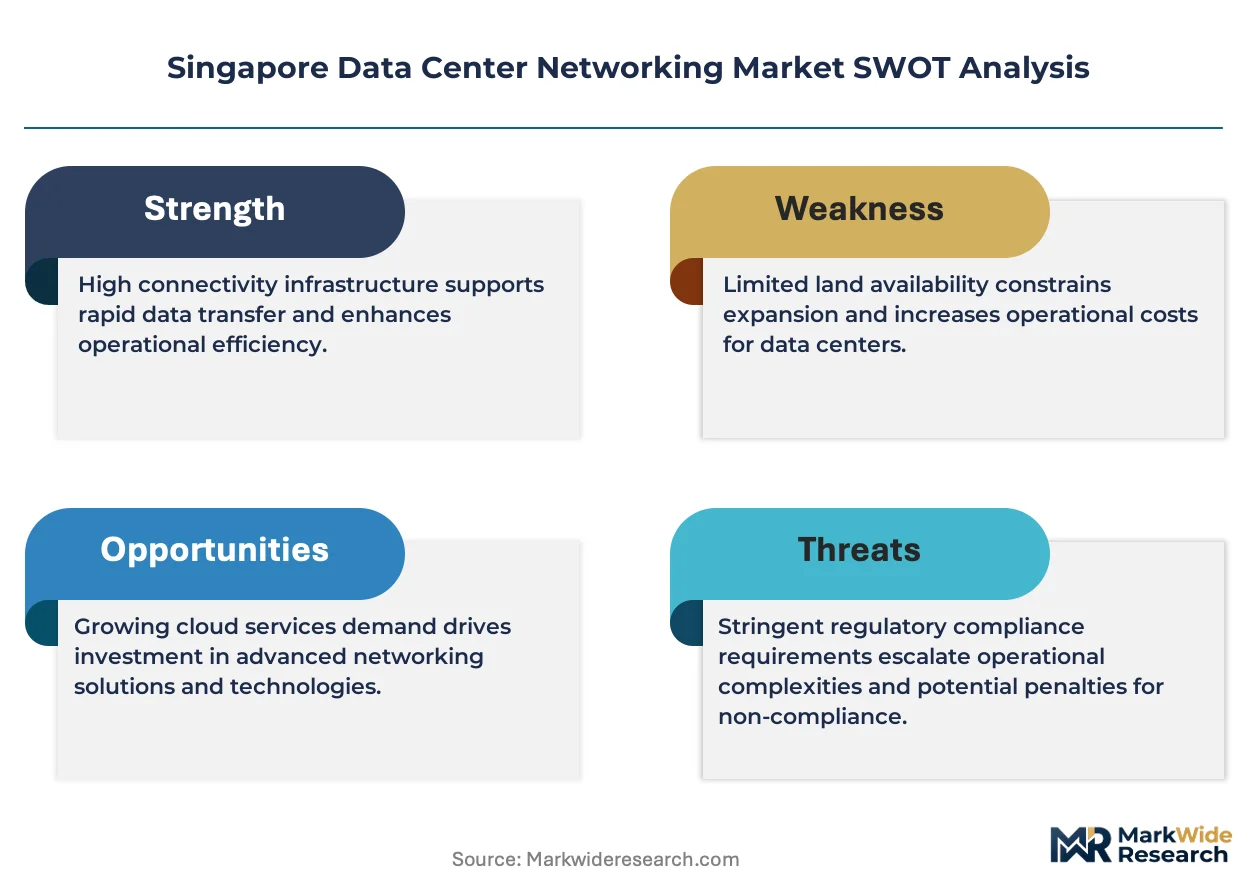
IMDA's data center energy efficiency standards and BCA Green Mark certification constrain facility expansion, indirectly filtering networking procurement toward equipment that supports power-usage effectiveness targets through intelligent workload placement. The Monetary Authority of Singapore's technology risk management guidelines impose resilience requirements on financial services connectivity, mandating redundant path diversity that shapes router and switch redundancy architectures. Stakeholders must monitor how submarine cable landing station expansions at Changi and Tuas alter inter-fiber latency economics and corresponding switching topology decisions.
Market Dynamics
Software-defined networking architectures are decoupling control planes from merchant silicon across Singapore's facilities, enabling programmable traffic management that compresses provisioning cycles from weeks to hours. This structural shift is forcing incumbent hardware vendors to reposition around intent-based automation while cloud operators consolidate procurement around disaggregated switching stacks.
Growth Catalysts
- IMDA Sustainability Standards:The Infocomm Media Development Authority's data center energy efficiency framework mandates intelligent workload placement, accelerating demand for power-aware switching fabrics that optimize thermal loads.
- Submarine Cable Expansion:New landing stations at Changi and Tuas are creating low-latency fiber corridors, pulling investment into edge aggregation switches that interconnect terrestrial and submarine networks.
- Financial Services Resilience Mandates:The Monetary Authority of Singapore's technology risk management guidelines require redundant path diversity, driving dual-homed router architectures across trading and banking facilities.
Market Restraints
- Land and Power Scarcity:Singapore's constrained physical geography and capped data center power allocations limit facility expansion, filtering networking procurement toward only the most energy-efficient equipment classes.
- Merchant Silicon Concentration:Switching ASIC supply concentrates among three foundry sources, creating vulnerability in lead times for 400G and 800G port densities during demand surges.
- Legacy Protocol Inertia:Financial trading floors maintain deep investments in InfiniBand and proprietary low-latency fabrics, slowing Ethernet adoption in the highest-performance segments.
Strategic Opportunities
- Jurong and Tanjong Klang Cluster Density:Government-designated data center zones at submarine cable intersections offer co-location synergies for multi-tenant switching fabrics serving Southeast Asian cloud egress.
- AI Training Workload Inflection:GPU cluster networking requirements are converging with Ethernet-based RDMA over converged Ethernet, opening white space for RoCEv2-optimized spine switches in new builds.
- Green Mark Certification Premium:BCA Green Mark tiered incentives reward facilities that demonstrate intelligent cooling-network integration, creating pull for environmental sensor-embedded switching infrastructure.
Industry Challenges
- Intent-Based Networking Skill Scarcity:Apstra and similar automation platforms require cross-functional expertise spanning Python, BGP policy engineering, and thermal modeling, creating recruitment bottlenecks for facility operators.
- Multi-Vendor Integration Complexity:Disaggregated procurement strategies combining white-box switches with third-party network operating systems introduce interoperability testing burdens that compress deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Data Center Networking Market |
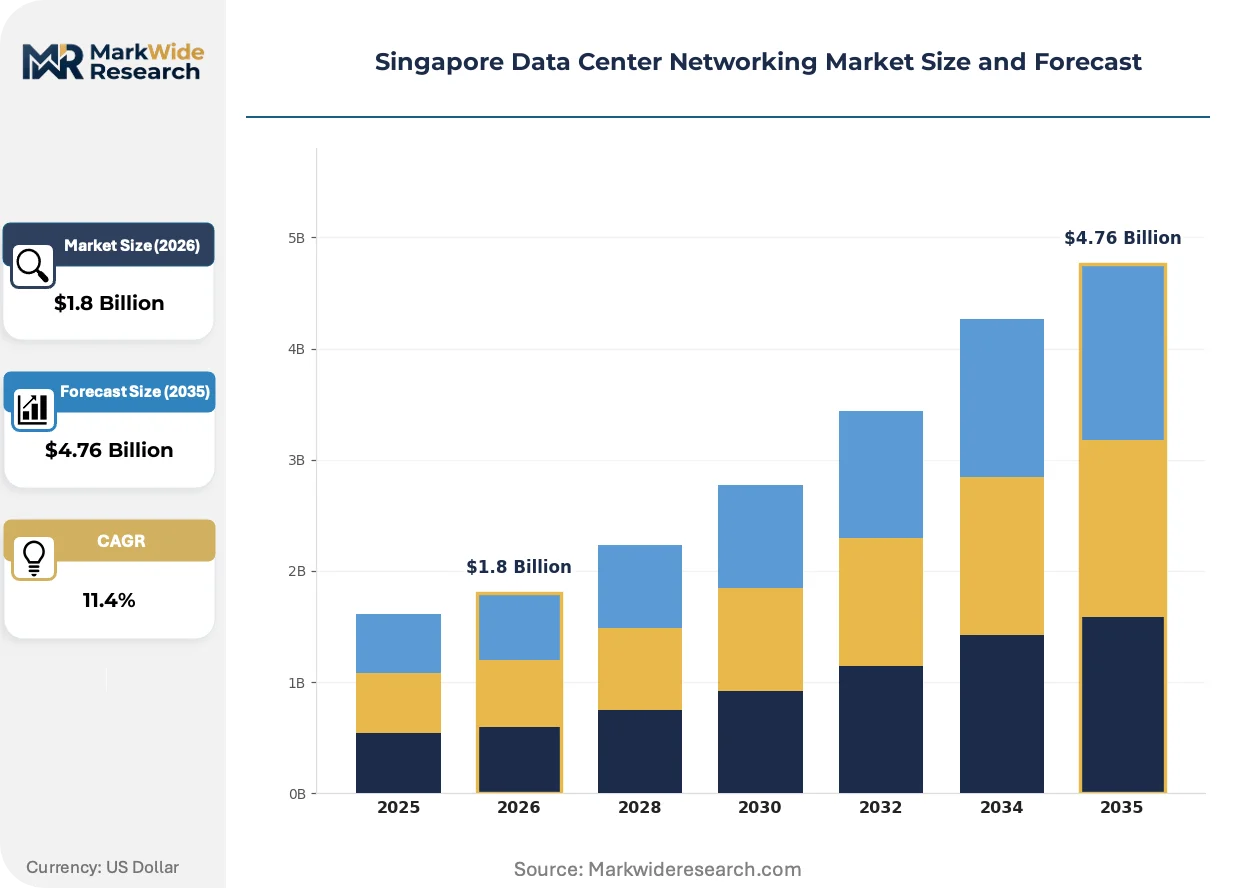
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Load Balancers Technology: Ethernet, IP/MPLS, Fiber Channel, SDN End User: IT Services, Telecommunications, Cloud Providers, Enterprises Deployment Model: On-Premises, Hybrid, Multi-Cloud, Colocation |
| Companies Covered | Cisco Systems Inc., Juniper Networks Inc., Arista Networks Inc., H3C Holding Limited, VMware Inc., Huawei Technologies Co. Ltd., Extreme Networks Inc., Broadcom Corp, NVIDIA Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Data Center Networking Market Trends and Innovations
Networking automation is compressing operational headcount requirements while elevating software engineering competencies within Singapore data center operations. The convergence of merchant silicon maturity and cloud-native orchestration is redefining how facilities architect their switching hierarchies.
SmartNICs and DPUs are digitizing server-level network functions that previously consumed host CPU cycles, enabling bare-metal cloud providers to offer virtualized networking without hypervisor overhead. Financial services operators are deploying these accelerators most aggressively, compressing latency budgets for algorithmic trading workloads. The structural consequence is digitizing the boundary between server and network infrastructure, forcing traditional switch vendors to develop DPU-integrated fabric management tools.
IMDA's data center energy efficiency standards are mandating granular power metering and thermal optimization that cascades into networking procurement specifications. Facilities must demonstrate intelligent workload placement that correlates traffic patterns with cooling load, pushing operators toward switches with embedded telemetry and programmable power states. The colocation segment is responding fastest, using these capabilities to differentiate multi-tenant offerings against self-built enterprise facilities.
Hyperscale cloud operators are consolidating procurement around disaggregated hardware-software bundles that separate merchant silicon from network operating system licensing. This buying-pattern shift is displacing traditional chassis-based switching in new Singapore builds, compressing margins for integrated vendors while opening distribution opportunities for Taiwanese ODMs and software-centric alternatives. The behavioral change is most visible among Chinese cloud providers expanding their Singapore footprint, who favor this procurement model for supply chain flexibility.
Singapore Data Center Networking Market Segmentation
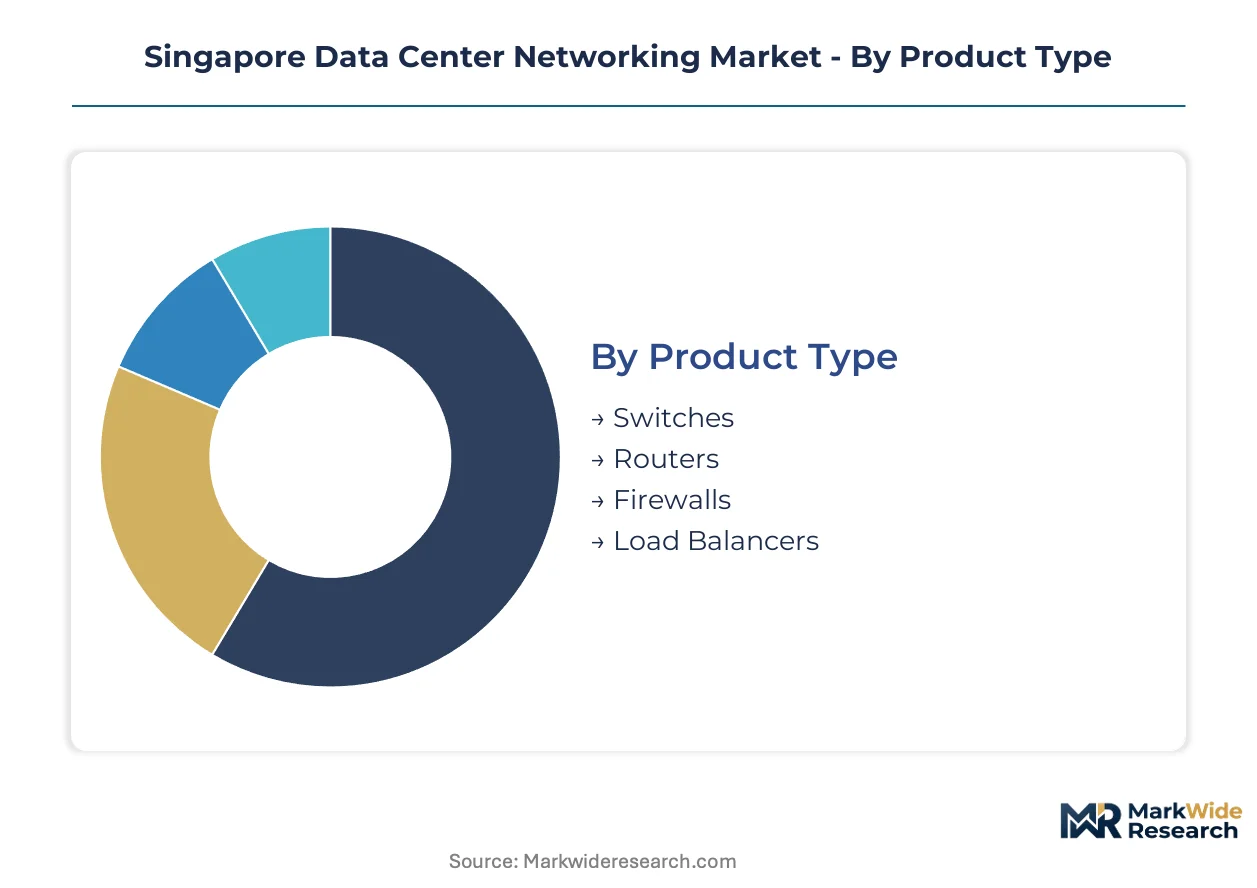
Singapore data center networking procurement patterns diverge sharply by segment, with switching hardware cycling every 3-4 years while firewall refreshes stretch to 5-7 years. Understanding these replacement rhythms shapes inventory planning and vendor negotiation timing for facility operators across Jurong and Tanjong Klang clusters.
Product Type:
Ethernet switches turn over fastest at 36-48 month cycles, driven by port density upgrades, while load balancers refresh slowest due to software licensing decoupled from hardware lifecycles.
- Switches:Leaf-spine architectures dominate new builds, with 400G aggregation ports becoming standard in hyperscale deployments. Demand concentrates in cloud provider facilities at Tanjong Klang where merchant silicon switching enables rapid scaling without chassis lock-in.
- Routers:Core and edge routing platforms handle inter-facility traffic across Singapore's submarine cable landing zones. Financial services operators in Marina Bay prioritize redundant BGP path diversity mandated by the Monetary Authority of Singapore's resilience guidelines.
- Firewalls:Next-generation appliances with TLS inspection capabilities address encrypted traffic visibility requirements in multi-tenant colocation environments.
- Load Balancers:Application delivery controllers manage traffic distribution across distributed compute clusters, with virtualized form factors gaining traction in hybrid deployments.
Switches dominate installed base. Load balancers are where expansion concentrates.
Technology:
Cost tiers separate legacy protocol investments from software-defined premiums, with SDN commanding 40-60% price premiums over traditional architectures due to orchestration licensing.
- Ethernet:25G server access and 400G spine interconnects form the physical foundation of Singapore facilities. Cloud providers in Jurong drive merchant silicon adoption, displacing proprietary ASIC switches through disaggregated procurement models.
- SDN:Centralized control planes enable programmable traffic engineering across hybrid cloud footprints. Colocation operators deploy SDN fabrics fastest to differentiate multi-tenant service orchestration against self-built enterprise alternatives.
- IP/MPLS:Carrier-grade routing protocols underpin financial services connectivity with deterministic latency guarantees for algorithmic trading.
- Fiber Channel:Storage area networking persists in legacy enterprise data centers, though converged Ethernet alternatives displace dedicated SAN switching in new builds.
Ethernet anchors physical infrastructure. SDN is climbing the fastest as automation requirements harden.
End User:
Customer type determines procurement sophistication, with cloud providers driving disaggregated hardware-software bundles while enterprises favor integrated chassis-based solutions.
- Cloud Providers:Hyperscale operators specify merchant silicon switches with third-party network operating systems, compressing margins for integrated vendors. Chinese cloud expansions into Singapore favor this procurement model for supply chain flexibility.
- IT Services:Systems integrators and managed service providers aggregate demand across mid-market enterprises, standardizing on vendor-neutral automation platforms to reduce multi-tenant operational complexity.
- Telecommunications:Carrier-neutral facilities interconnect submarine cable systems with terrestrial fiber, requiring edge aggregation switches that bridge optical transport and packet switching domains.
- Enterprises:Self-built financial and manufacturing facilities prioritize chassis-based redundancy and established vendor support relationships over disaggregation economics.
Cloud providers drive architectural innovation. IT services aggregate volume across fragmented demand.
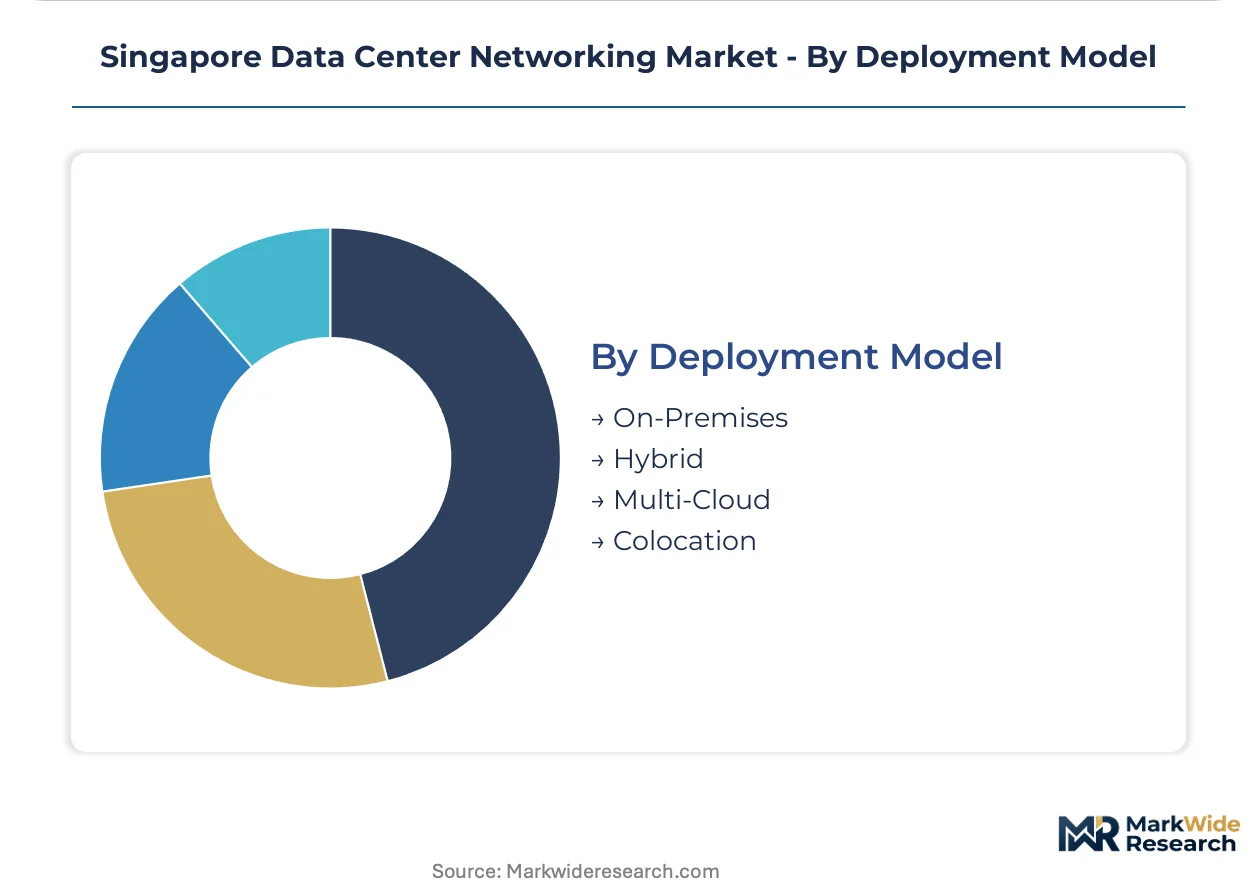
Deployment Model:
Geography within Singapore shapes topology decisions, with colocation facilities at cable landing stations optimizing for cross-connect density while on-premises deployments prioritize latency isolation.
- Colocation:Multi-tenant facilities at Changi and Tuas submarine cable landings interconnect terrestrial and submarine networks through edge aggregation switches. IMDA sustainability standards filter equipment selection toward power-aware fabrics.
- Hybrid:Enterprises bridge on-premises workloads with cloud bursting through SD-WAN overlays, demanding consistent policy orchestration across physical and virtual switching domains.
- On-Premises:Financial trading floors in Raffles Place maintain dedicated low-latency fabrics, with InfiniBand persistence slowing Ethernet adoption in the highest-performance segments.
- Multi-Cloud:Distributed application architectures require consistent networking abstractions across AWS, Azure, and Google Cloud regions, pulling investment in cloud-native load balancing and service mesh technologies.
Colocation captures the largest facility footprint. Hybrid deployments are gaining share fastest as enterprises diversify cloud risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's data center networking infrastructure functions as a critical export hub for Southeast Asian digital services, with cross-border bandwidth demand outpacing domestic consumption. The city-state's submarine cable landings generate substantial re-export value in network services to Indonesia, Malaysia, Thailand, and Vietnam.
Jurong
Cloud provider demand concentrates in this western industrial zone where merchant silicon switching enables rapid scaling without chassis lock-in. IMDA's data center energy efficiency framework mandates intelligent workload placement, filtering procurement toward power-aware fabrics. Hyperscale facilities here interconnect with submarine cables landing at Tuas, creating low-latency corridors to India and Europe.
Tanjong Klang
Submarine cable intersections at this southwestern cluster pull investment into edge aggregation switches bridging terrestrial and submarine networks. The Monetary Authority of Singapore's technology risk management guidelines require redundant path diversity, driving dual-homed router architectures across financial services facilities. Chinese cloud providers expanding here favor disaggregated hardware-software bundles for supply chain flexibility.
Changi
New cable landing station expansions are creating low-latency fiber corridors to East Asia and Australia, altering inter-fiber latency economics. BCA Green Mark tiered incentives reward facilities demonstrating intelligent cooling-network integration, creating pull for environmental sensor-embedded switching. Colocation operators deploy SDN fabrics fastest here to differentiate multi-tenant service orchestration.
Marina Bay
Financial services operators in this central business district prioritize chassis-based redundancy and established vendor support relationships over disaggregation economics. The Monetary Authority of Singapore's resilience guidelines mandate redundant BGP path diversity across trading and banking facilities. Algorithmic trading floors here maintain investments in low-latency fabrics, slowing Ethernet adoption in highest-performance segments.
Tuas
Government-designated data center zone development coincides with submarine cable landing expansion, offering co-location synergies for multi-tenant switching fabrics. IMDA sustainability standards constrain facility expansion, filtering networking procurement toward only the most energy-efficient equipment classes. GPU cluster networking requirements for AI training workloads are converging with RoCEv2-optimized spine switches in new builds here.
Singapore Data Center Networking Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated chassis vendors, merchant silicon specialists, and software-centric automation platforms. Incumbent hardware vendors reposition around intent-based automation while cloud operators consolidate procurement around disaggregated switching stacks. Dominant competitive moves include portfolio diversification into SmartNIC and DPU integration, plus strategic partnerships with Taiwanese ODMs for supply chain flexibility.
Within the integrated systems tier, Cisco Systems Inc. and Juniper Networks Inc. anchor established positions through chassis-based reliability and Apstra-based automation respectively. Arista Networks Inc. occupies the cloud-scale specialist position with operating systems purpose-built for leaf-spine architectures. Among Asia-Pacific headquartered vendors, H3C Holding Limited and Huawei Technologies Co. Ltd. exemplify the merchant silicon-plus-software bundling approach favored by regional cloud expansions.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Juniper Networks Inc. |
| Arista Networks Inc. |
| H3C Holding Limited |
| VMware Inc. |
| Huawei Technologies Co. Ltd. |
| Extreme Networks Inc. |
| Broadcom Corp |
| NVIDIA Corporation |
| Others |
Pricing and Supply Chain Analysis
Changi-Tuas submarine cable corridors anchor freight cost dynamics across Singapore's data center networking supply chain, concentrating procurement leverage among hyperscale cloud operators while compressing margins for chassis-integrated vendors serving financial services facilities in Marina Bay.
Pricing Analysis
Cloud provider buyers anchor a three-tier pricing structure across premium, standard, and economy levels in Singapore's data center networking market. Price differentiation rests on merchant silicon flexibility versus proprietary ASIC performance, with BCA Green Mark certification tiers commanding measurable premiums for power-aware switching fabrics. Cost compression in the mid-market chassis segment is intensifying because Chinese cloud expansions favor disaggregated hardware-software bundles. Colocation operators at Jurong and Tanjong Klang exhibit highest price sensitivity, while Marina Bay financial services facilities prioritize vendor support relationships over unit economics.
Supply Chain Analysis
US semiconductor export controls on advanced switching ASICs constrain supply flows into Singapore's 400G and 800G port density procurement. Merchant silicon supply concentrates in Taiwan, South Korea, and the United States, with switching hardware assembly feeding from Malaysian and Vietnamese manufacturing nodes. Raw material dependencies span silicon wafers, high-speed optical transceivers, and specialized thermal interface materials. Single-source vulnerability around three foundry sources for switching ASICs creates lead time fragility during demand surges. Distribution runs through direct hyperscale procurement contracts and systems integrator channels serving mid-market enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
White-box switching and merchant silicon bundling threaten incumbent proprietary vendors, forcing defensive repositioning around automation software and DPU-integrated fabric management.
For Market Incumbents: Insulate chassis-based revenue streams by deepening Apstra and similar intent-based automation licensing, while accelerating SmartNIC integration to capture server-network boundary value. IMDA sustainability standards filter procurement toward power-aware equipment, creating certification-based differentiation against white-box alternatives. Vertical integration into DPU software stacks represents the critical defensive lever. For New Entrants and Emerging Players: Mid-market colocation facilities in Changi and Tuas represent the most penetrable entry point, where SDN fabric orchestration demands outpace incumbent response capabilities. GPU cluster networking for AI training workloads at Tuas offers second white-space concentration, with RoCEv2-optimized spine switches gaining traction against InfiniBand persistence. A managed network services wrapper around merchant silicon hardware enables rapid customer acquisition without chassis R&D overhead. For Investors and Strategic Acquirers: IMDA's phased data center energy efficiency standard implementation reshapes the acquisition landscape, elevating targets with embedded telemetry and programmable power state capabilities. Vendors demonstrating BCA Green Mark certification traction and hyperscale cloud procurement relationships offer strongest long-term viability within a five-to-ten year window. The signal to watch is Chinese cloud provider procurement committee decisions favoring disaggregated versus integrated switching architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Silicon Partnership Expansion | Taiwanese ODM relationships enable supply chain flexibility for hyperscale procurement committees. |
| Intent-Based Automation Platform Development | Apstra-based orchestration reduces multi-vendor integration burdens across Jurong facilities. |
| DPU-Integrated Fabric Management Tools | SmartNIC digitization captures server-level network functions previously consuming host CPU cycles. |
| BCA Green Mark Certification Investment | Tiered incentives reward facilities demonstrating intelligent cooling-network integration capabilities. |
| RoCEv2-Optimized Spine Switch Product Line | GPU cluster networking requirements converge with Ethernet-based RDMA in Tuas AI training builds. |
Research Methodology
Operator-level perspectives from data center facility managers, network architects at cloud providers, colocation procurement leads, and submarine cable landing station engineers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through IMDA regulatory filings, BCA Green Mark certification databases, Monetary Authority of Singapore technology risk guidelines, and hyperscaler capital expenditure disclosures. Bottom-up equipment shipment analysis and top-down facility construction tracking were triangulated to establish market sizing boundaries.
Scenario-bracketing around IMDA sustainability compliance timelines and submarine cable landing expansion schedules framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, technology protocol, end-user vertical, and deployment model complexity, with additional granularity on power efficiency tier and merchant silicon sourcing strategy. CAGRs were derived from facility build-out pipelines and equipment refresh cycle analysis, incorporating GPU cluster networking inflection points and financial services resilience mandate compliance trajectories.
Stress conditions across foundry capacity allocation, export control enforcement intensity, and IMDA power allocation caps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hyperscale cloud expansion commitments and submarine cable landing station completion schedules. Material shifts in US semiconductor export control scope or IMDA data center moratorium extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Global Data Warehouse As a Service (Dwaas) Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Denmark Data Center Networking Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
Europe Subscriber Data Management Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Edge Server Market
Data Center and Networking
Brazil Optical Transceiver Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Datacenter Network Consulting and Integration Service Market
Data Center and Networking
United Kingdom Data Center Networking Market
Data Center and Networking
Philippines Data Center Networking Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
Software Defined Video Networking Market
Data Center and Networking
Global Data Management Platform Market