
 Global Data Lakes Market | 2026-2036
Global Data Lakes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Lakes Market Foresight
Healthcare enterprises is redrawing demand patterns in the data lakes landscape, displacing earlier dominance by retail and media buyers. Amazon Web Services leverages its hyperscale infrastructure to anchor cloud-native lake deployments across regulated industries. Microsoft Corporation competes through deep integration with enterprise productivity stacks and Azure governance tooling. Databricks specializes in lakehouse architectures that blur traditional boundaries between data lakes and warehouses.
A data lake constitutes a centralized storage repository that ingests structured, semi-structured, and unstructured data in native formats, typically employing distributed file systems such as Apache Hadoop HDFS or cloud object storage with schema-on-read query engines. Its primary commercial purpose is to enable organizations to perform advanced analytics, machine learning training, and business intelligence without premature data transformation costs. Cloud-based deployment leads in new capacity additions as enterprises exit capital-intensive on-premises infrastructure, while hybrid configurations capture margin pools in regulated sectors requiring data residency. Analytics and visualization solutions within the solution type segment represent the fastest-expanding revenue layer as organizations prioritize actionable insight extraction over raw storage accumulation.
The EU AI Act, GDPR, and HIPAA compliance frameworks in the United States are reshaping product requirements toward automated data lineage, access auditing, and residency controls that directly influence procurement specifications. ISO 27001 and SOC 2 certifications have become baseline market access credentials rather than differentiators for platform vendors. Stakeholders must evaluate whether their data lake investments incorporate native governance capabilities or risk costly retrofitting as regulatory scopes expand.
Market Dynamics
Healthcare data gravity is concentrating patient records into unified repositories, forcing vendors to architect lakehouse platforms that satisfy HIPAA audit trails and EU AI Act algorithmic transparency mandates simultaneously.
Growth Catalysts
- EU AI Act compliance deadlines:European healthcare providers are accelerating governed data lake procurement to meet algorithmic risk classification requirements. Automated lineage tooling has become a procurement prerequisite.
- Cloud hyperscaler infrastructure expansion:AWS, Microsoft Azure, and Google Cloud are deploying region-specific sovereign cloud instances that satisfy data residency constraints for regulated workloads.
- Federal data modernization mandates:United States agencies including VA and CMS are consolidating siloed systems into cloud-native lake architectures under OMB guidance.
Market Restraints
- Specialized talent scarcity:Data engineers with Spark optimization and Delta Lake expertise command premium compensation, constraining mid-market deployment velocity.
- Cloud egress cost volatility:Unpredictable data transfer fees between hyperscalers and on-premises systems complicate multi-year TCO forecasting for hybrid architectures.
- Schema-on-read performance degradation:Query latency spikes on unoptimized Parquet partitions limit real-time analytics viability for trading floors and ICU monitoring.
Strategic Opportunities
- India's digital health stack expansion:The country's National Health Stack and ABHA identifier system are generating petabyte-scale data streams requiring lake infrastructure.
- Lakehouse-SQL convergence:Databricks Delta Lake and Apache Iceberg are collapsing the historical warehouse-lake boundary, opening unified analytics procurement budgets.
- Japan's METI data free flow with trust initiative:Cross-border data trust frameworks are enabling Japanese automotive and pharmaceutical firms to deploy multi-region lake architectures.
Industry Challenges
- Legacy mainframe integration complexity:COBOL-era systems in banking and insurance resist API-based ingestion, forcing expensive change-data-capture middleware.
- ISO 27001 certification timelines:Six-to-twelve-month audit cycles delay vendor qualification for procurement pipelines in defense and healthcare sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Lakes Market |
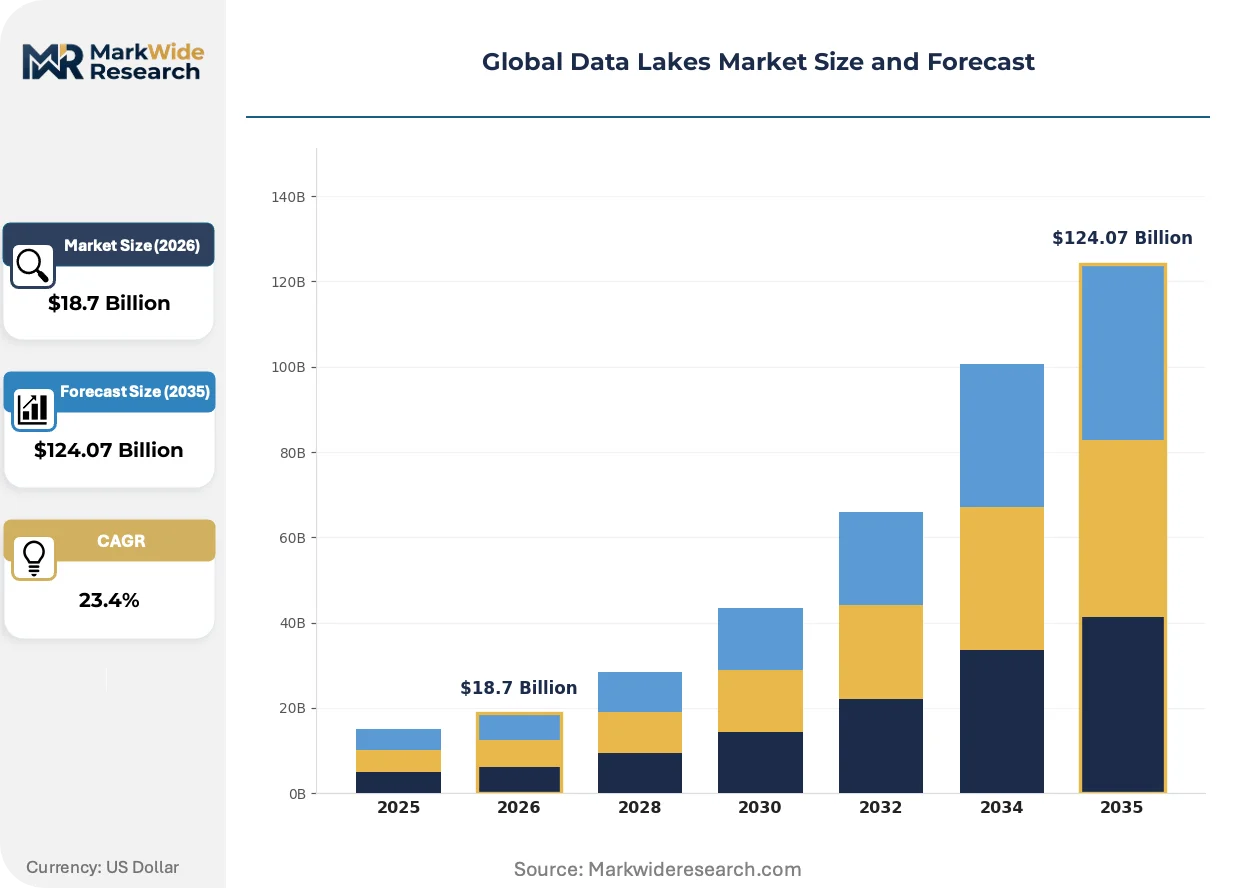
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $124.07 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Multi-Cloud Solution Type: Data Integration, Data Governance, Data Security, Analytics & Visualization, Metadata Management Use Case: Customer Analytics, Fraud Detection, Predictive Maintenance, Supply Chain Optimization, Risk Management End User: BFSI, Telecommunications, Manufacturing, Media & Entertainment, Government |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google LLC, IBM, Oracle Corporation, Cloudera, Snowflake Inc., Databricks, Teradata Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Lakes Market Shifts & Advancements
Open table formats and automated governance engines are compressing the traditional build-versus-buy decision cycle for enterprise data infrastructure. Architectural patterns are fragmenting across industry-specific compliance requirements.
Apache Iceberg and Delta Lake open table formats are bifurcating storage engine roadmaps. Financial services firms in Singapore and Switzerland are adopting Iceberg for its partition evolution capabilities, while healthcare systems standardize on Delta Lake for ACID transaction guarantees. The format competition is fragmenting vendor interoperability commitments and forcing buyers into premature architectural lock-in.
GDPR Article 30 record-keeping obligations and EU AI Act high-risk system documentation requirements are mandating automated data catalog integration. German automotive manufacturers and French healthcare networks must now maintain immutable audit trails from ingestion through model training. Vendors are embedding Apache Atlas and DataHub lineage engines as default components rather than optional modules.
Healthcare procurement committees are consolidating vendor relationships from point solutions to integrated lakehouse platforms. United States hospital systems and German Krankenkassen are prioritizing native governance tooling over best-of-breed storage. This concentration is compressing evaluation cycles and elevating Microsoft Fabric and Databricks Unity Catalog in competitive bake-offs against pure-play storage vendors.
Global Data Lakes Market Segmentation
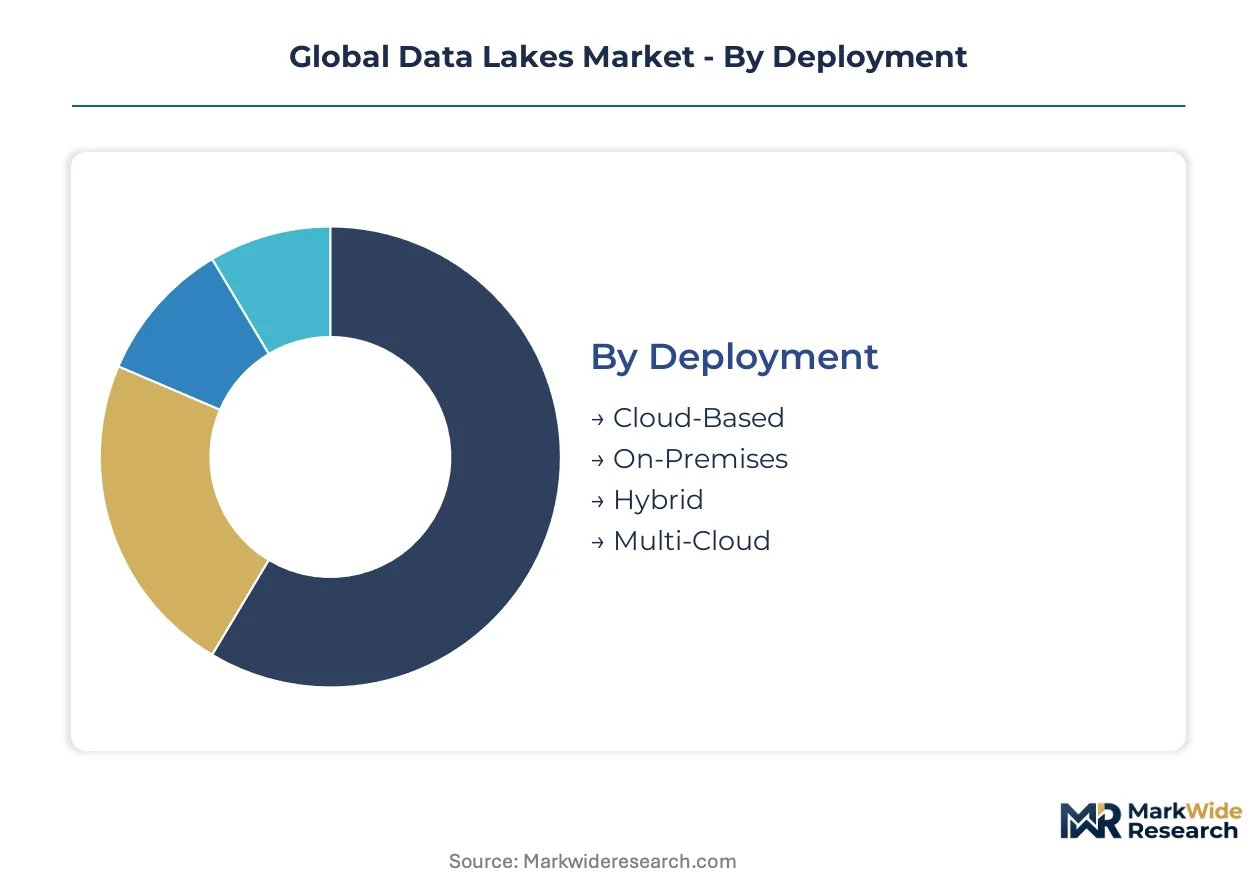
Deployment architectures and solution stacks in the data lakes market fragment across regulatory constraints, latency requirements, and TCO optimization pressures. Understanding substitution dynamics between cloud-native and hybrid configurations enables procurement committees to align infrastructure investments with evolving compliance mandates.
Deployment:
Cloud-based configurations face substitution pressure from sovereign cloud instances and hybrid architectures as data residency regulations tighten across European and Asian jurisdictions.
- Cloud-Based:Hyperscaler-managed object storage with serverless query engines eliminates capital expenditure cycles. United States federal agencies under OMB cloud-first mandates are consolidating petabyte-scale workloads into AWS GovCloud and Azure Government regions.
- On-Premises:Hadoop distributions and software-defined storage retain foothold in defense and intelligence sectors where air-gapped environments are non-negotiable. German automotive manufacturers maintain on-premises lakes for proprietary powertrain telemetry to satisfy trade secret protections under national industrial policy.
- Hybrid:Tiered hot-warm-cold architectures partition sensitive patient records on-premises while pushing anonymized training data to cloud ML pipelines. HIPAA-covered entities in the United States deploy this model to balance audit control with compute elasticity.
- Multi-Cloud:Vendor-agnostic abstraction layers using Apache Iceberg or Delta Lake prevent hyperscaler lock-in. Japanese pharmaceutical firms leverage multi-cloud strategies to satisfy METI data free flow with trust frameworks across Tokyo, Singapore, and Frankfurt regions.
Cloud-based deployments anchor the volume base while hybrid configurations gain share at the steepest rate as regulated industries navigate sovereignty requirements.
Solution Type:
Cost tier differentiation separates commodity storage layers from premium governance and analytics modules that command recurring subscription premiums.
- Data Integration:Batch and streaming ingestion pipelines using Apache Kafka, Flink, and Airflow normalize schema drift across source systems. United States healthcare networks prioritize CDC-enabled integration to synchronize Epic and Cerner EHR instances into unified lakes.
- Data Governance:Automated lineage, policy enforcement, and access auditing address EU AI Act and GDPR Article 30 mandates. French CNIL enforcement actions against algorithmic opacity are accelerating procurement of embedded governance engines.
- Data Security:Encryption-at-rest, tokenization, and key management services protect high-risk system classifications. Swiss banking regulators require field-level encryption for cross-border data lake replication between Zurich and Singapore.
- Analytics & Visualization:SQL query engines, BI connectors, and embedded ML model serving transform raw storage into decision workflows. Expansion here outpaces raw storage growth as enterprises prioritize insight extraction over data accumulation.
- Metadata Management:Data catalogs, business glossaries, and automated tagging reduce discovery friction. Indian IT services firms embed metadata automation to support National Health Stack interoperability requirements.
Analytics and visualization solutions capture the steepest expansion trajectory while data integration tools constitute the largest installed base by transaction volume.
Use Case:
Application maturity varies sharply, with predictive maintenance and fraud detection commanding proven ROI while supply chain optimization struggles with data quality standardization.
- Customer Analytics:Unified profile construction across CRM, web, and transaction streams enables personalization at scale. Telecommunications operators in South Korea deploy lakehouse architectures to reduce churn through real-time behavioral scoring.
- Fraud Detection:Anomaly detection on streaming payment feeds requires sub-second query latency. United States card networks combine graph analytics on lake-resident transaction histories with real-time inference at the edge.
- Predictive Maintenance:Sensor fusion from industrial IoT predicts equipment failure before operational impact. German manufacturers integrate SAP PM data with vibration telemetry lakes to optimize maintenance windows.
- Supply Chain Optimization:Multi-tier visibility across supplier networks demands harmonized master data. Retailers in the Netherlands struggle with EDI format heterogeneity that limits lake query accuracy.
- Risk Management:Regulatory capital calculations and stress testing aggregate position data across trading books. Swiss and Singaporean banks maintain separate lake instances for trading risk and credit risk to satisfy ring-fencing requirements.
Customer analytics anchors enterprise deployment scale while predictive maintenance climbs fastest as industrial IoT sensor density increases.
End User:
Customer type concentration reflects data gravity patterns, with BFSI and telecommunications leading early adoption while government segments accelerate under modernization mandates.
- BFSI:Trading analytics, AML surveillance, and regulatory reporting drive petabyte-scale investments. United States banks under CCAR and CECL requirements maintain decade-long data retention in governed lake architectures.
- Telecommunications:Network optimization, subscriber analytics, and 5G service assurance generate continuous ingest volumes. South Korean operators deploy edge-lake hierarchies to support ultra-low latency RAN intelligence.
- Manufacturing:Digital thread initiatives connect PLM, MES, and quality systems into unified product lifecycle lakes. Japanese automotive firms leverage METI-supported data trusts to share anonymized defect patterns across competitive boundaries.
- Media & Entertainment:Content recommendation engines and advertising yield optimization process streaming interaction data. Subscription video platforms in India scale lake storage to support regional language content personalization.
- Government:Census analytics, tax compliance, and public health surveillance consolidate agency silos. United States VA and CMS modernization programs under OMB guidance represent the fastest-expanding public sector demand pool.
BFSI retains the deepest installed base while government verticals expand most quickly as sovereign data infrastructure investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based hyperscalers export data lake infrastructure to European healthcare networks and Asian manufacturing conglomerates, establishing cross-border demand corridors that reshape regional procurement patterns. Cloud service providers in Seattle and San Francisco anchor transatlantic deployments through sovereign cloud instances in Frankfurt and Paris. Japanese automotive firms source governed lake architectures from these same US vendors to satisfy METI data trust frameworks.
United States
Federal agencies under OMB cloud-first mandates consolidate siloed systems into petabyte-scale lake architectures. HIPAA audit requirements and VA modernization programs drive procurement of hybrid configurations with on-premises residency controls. Hospital systems in Boston and the Research Triangle prioritize native governance tooling over pure storage expansion.
Germany
Automotive manufacturers and Krankenkassen health insurers demand ACID-guaranteed lakehouse platforms for proprietary telemetry and patient records. GDPR Article 30 obligations and EU AI Act algorithmic transparency mandates accelerate automated lineage procurement. Industrial clusters in Bavaria and Baden-Württemberg maintain on-premises lakes for powertrain data under national trade secret protections.
Japan
Pharmaceutical and automotive firms deploy multi-region architectures under METI data free flow with trust initiatives. PMDA regulatory submissions require immutable audit trails from ingestion through model training. Tokyo-Osaka corporate networks leverage cross-border data trusts to share anonymized defect patterns across competitive boundaries.
India
National Health Stack and ABHA identifier systems generate petabyte-scale streams requiring lake infrastructure for interoperability. CDSCO regulatory frameworks and RBI data localization norms push hybrid deployment models. IT services clusters in Bengaluru and Hyderabad embed metadata automation to support government digital health expansion.
Switzerland
Private banking and pharmaceutical sectors mandate field-level encryption for cross-border lake replication between Zurich and Singapore nodes. Swissmedic documentation requirements and FINMA audit standards elevate governance engine procurement. Geneva and Basel financial centers maintain separate lake instances for trading risk and credit risk ring-fencing.
Global Data Lakes Market Competitive Landscape
Listed hyperscalers compete with private specialists across infrastructure scale and vertical integration depth. The vendor base separates into three tiers: cloud-native platforms with serverless query engines, legacy database vendors extending into lakehouse architectures, and pure-play governance specialists embedding automated lineage. Consolidation pressure intensifies as healthcare procurement committees favor integrated platforms over point solutions. Dominant competitive moves include strategic partnerships between storage vendors and analytics specialists, plus geographic expansion through sovereign cloud instances in Frankfurt, Singapore, and Tokyo.
Within the cloud-native tier, Amazon Web Services and Microsoft Corporation anchor hyperscale deployments across regulated industries, representing the infrastructure-heavy archetype that eliminates capital expenditure cycles for enterprise buyers. Databricks occupies a specialist position exemplifying lakehouse-SQL convergence, collapsing historical warehouse-lake boundaries through open table format standardization. These three entities collectively illustrate the competitive tension between horizontal platform breadth and vertical governance depth that shapes procurement evaluation cycles.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Google LLC |
| IBM |
| Oracle Corporation |
| Cloudera |
| Snowflake Inc. |
| Databricks |
| Teradata Corporation |
| Others |
Supply & Pricing Matrix
Apache Iceberg replacing Delta Lake as the dominant open table format in European financial services is simultaneously shifting procurement geography toward Singapore and Switzerland while compressing price premiums for ACID-guaranteed storage engines. This substitution dynamic redirects supply chain investment from US West Coast hyperscaler regions toward sovereign cloud instances in Frankfurt and Zurich that command residency premiums.
Pricing Analysis
Next-generation lakehouse platforms with embedded governance engines command 40-60% premiums over prior-generation object storage with bolt-on analytics, while legacy Hadoop distributions face accelerated price erosion. Subscription-based SaaS tiers dominate, with price differentiation anchored in ISO 27001 certification status and data residency controls. Cost compression in mid-market storage tiers intensifies as AWS, Azure, and Google Cloud engage in capacity-based discounting for petabyte-scale commitments. Healthcare providers exhibit highest price sensitivity due to constrained IT budgets, while BFSI segments accept premium pricing for sub-second query latency guarantees.
Supply Chain Analysis
The United States anchors hyperscaler infrastructure production for cloud-native lake deployments, while India and Ireland concentrate software development and customer engineering talent for metadata automation tooling. Supply chains draw from Taiwanese semiconductor fabrication for storage controllers, South Korean memory components for query acceleration, and German industrial automation for on-premises hardware. Single-source vulnerability concentrates in Apache Spark optimization specialists commanding premium compensation. Distribution runs through direct enterprise sales teams for regulated healthcare and BFSI accounts, with self-serve channels capturing mid-market analytics workloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against lakehouse-SQL convergence collapsing traditional warehouse-lake procurement boundaries, as Databricks and Snowflake encroach on pure-play storage margins with unified analytics platforms.
For Market Incumbents: Secure native governance capabilities through acquisition of automated lineage specialists before EU AI Act enforcement hardens procurement requirements. Defend position by embedding Apache Atlas or DataHub engines as standard components rather than optional modules, countering vertical integration moves by Microsoft Fabric and Databricks Unity Catalog.
For New Entrants and Emerging Players: Automated metadata tagging for India's National Health Stack interoperability requirements represents the most penetrable white-space target, as incumbent hyperscalers under-serve regional language content personalization needs. Target hybrid deployment configurations for HIPAA-covered entities seeking on-premises audit control with cloud ML elasticity, leveraging channel partnerships with Epic and Cerner integration specialists.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors governance-integrated platforms over point-solution storage vendors. Long-term viability hinges on automated compliance tooling for EU AI Act and GDPR Article 30 mandates, with acquisition targets spanning Delta Lake optimization specialists and sovereign cloud infrastructure providers. Watch for CDSCO and RBI enforcement actions on data localization as inflection indicators for hybrid architecture demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Lineage Engine Acquisition | EU AI Act compliance deadlines in French healthcare networks mandate immutable audit trail capabilities. |
| Sovereign Cloud Instance Expansion | Swiss banking regulators require field-level encryption for Zurich-Singapore cross-border replication. |
| Lakehouse-SQL Platform Integration | German automotive manufacturers seek ACID guarantees for proprietary powertrain telemetry under trade secret law. |
| Metadata Automation Partnership | Indian IT services clusters embed tagging engines to support ABHA identifier system interoperability. |
| Hybrid Configuration Certification | United States VA modernization programs under OMB guidance demand HIPAA-compliant on-premises residency controls. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, hospital procurement databases, and CMS Medicare data. Data lake architects at United States hospital systems, compliance officers at German Krankenkassen, and platform engineers at Bengaluru IT services firms provided qualitative inputs on governance tooling priorities. Secondary validation drew from SEC 10-K filings of listed cloud providers, GPO contracts for healthcare infrastructure, and EMA submissions referencing data management protocols. Bottom-up deployment estimates triangulate against top-down market sizing across cloud-native, hybrid, and on-premises configurations.
Segmentation dimensions modeled include deployment architecture, solution type tier, end-use vertical, and regional regulatory cluster across the analysis window. CAGRs derive from elasticity-adjusted adoption curves incorporating EU AI Act compliance deadlines, federal data modernization mandates, and industrial IoT sensor density trajectories. Forecast inputs integrate OMB cloud-first policy velocity, METI data trust framework adoption rates, and Spark optimization talent supply constraints.
Forecasts assume regulatory continuity in EU AI Act implementation, HIPAA enforcement patterns, and RBI data localization norms; material policy shifts would require re-modeling. Specific risks include cloud egress cost volatility disrupting hybrid TCO forecasts, ISO 27001 audit cycle delays compressing vendor qualification timelines, and schema-on-read performance limitations constraining real-time analytics viability. Recalibration cycles align with material shifts in sovereign data infrastructure investments and open table format standardization outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
APAC Data Center Networking Market
Data Center and Networking
Switzerland Data Center Networking Market
Data Center and Networking
South Korea Data Center Networking Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Managed Network Services Market
Data Center and Networking
Germany Data Center Server Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Infrastructure As a Service Market
Data Center and Networking
North America Data Center Networking Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
Data Center Servers Market