
 Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market | 2026-2036
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market Size, Share, and Industry Trends Forecast 2026-2036
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market Foresight
Single-source CDN reliance is decoupling from operator strategies as multi-vendor architectures reduce outage risk. fuboTV leverages specialized sports streaming infrastructure to sustain subscriber retention during peak live events. DirecTV Stream anchors its competitive position through proprietary edge server placement across metropolitan zones. YouTube TV differentiates via global caching partnerships that minimize last-mile delivery costs.
An IPTV Content Delivery Network distributes television content over Internet Protocol using managed server networks that cache video segments closer to end users, typically operating at latency thresholds below two seconds for live streams. The primary purpose centers on ensuring consistent quality of service across variable broadband conditions while reducing origin server load. Cloud-based deployment leads segment adoption as operators abandon capex-heavy on-premise installations, though edge computing represents the fastest-growing architecture for ultra-low-latency live broadcasting. Video streaming services generate the largest revenue pool within service types, while subscriber management tools capture expanding margin as churn reduction becomes critical.
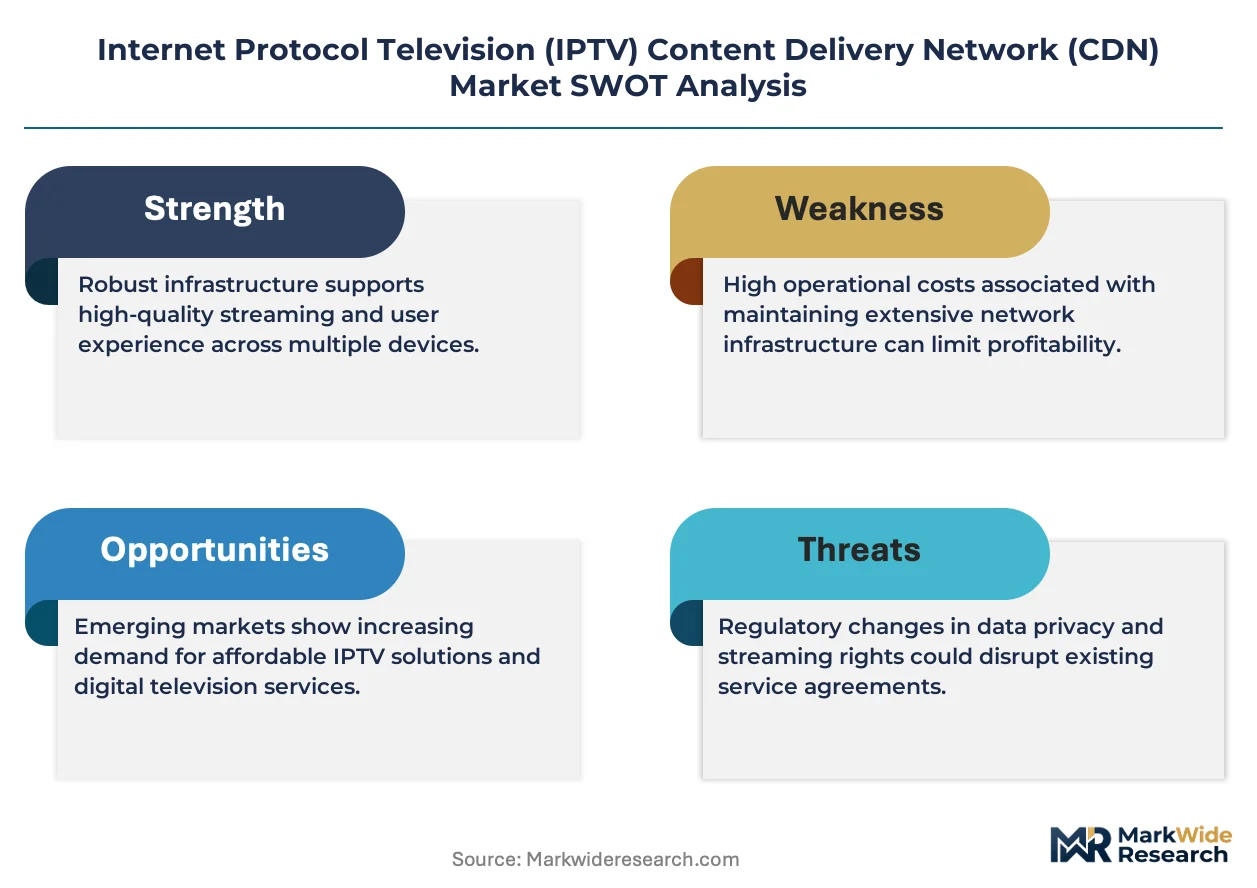
FCC net neutrality frameworks and GDPR data localization requirements shape how CDN providers architect traffic routing and user data storage across jurisdictions. EMA content classification standards and CE marking for network equipment further constrain product design and market access pathways. Stakeholders must monitor regulatory divergence between data sovereignty mandates and open internet principles when selecting CDN partnership structures.
Market Dynamics
The shift from single-source CDN architectures toward multi-vendor redundancy frameworks is restructuring operator procurement priorities and vendor competitive positioning across the IPTV infrastructure landscape.
Growth Catalysts
- Fiber-to-the-home expansion:Broadband infrastructure upgrades in the United States are creating physical pathways for 4K and live sports streaming at scale.
- Adaptive bitrate streaming protocols:HLS and DASH standards are reducing buffering latency across variable network conditions without requiring wholesale network replacement.
- GDPR data localization:European data sovereignty requirements are mandating edge server placement within national borders, accelerating distributed infrastructure investment.
Market Restraints
- Origin server load concentration:Centralized content ingestion points create single points of failure during peak live events such as championship broadcasts.
- CE marking compliance costs:European network equipment certification timelines extend product launch windows by six to twelve months.
- Cloud migration capex cliffs:Operators face stranded asset risk from abandoned on-premise hardware investments during platform transitions.
Strategic Opportunities
- Edge computing convergence:Ultra-low-latency live broadcasting requirements are driving compute placement at cellular tower aggregation points.
- Subscriber management tool expansion:Churn reduction analytics represent margin expansion potential as streaming competition intensifies.
- OTT bundling strategies:Multi-service packaging in North American markets is creating CDN capacity commitment guarantees.
Industry Challenges
- Multi-vendor integration complexity:API standardization gaps between CDN providers extend deployment timelines and increase testing overhead.
- Live event traffic spike management:Unpredictable concurrent viewer surges strain auto-scaling infrastructure and trigger quality degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market |
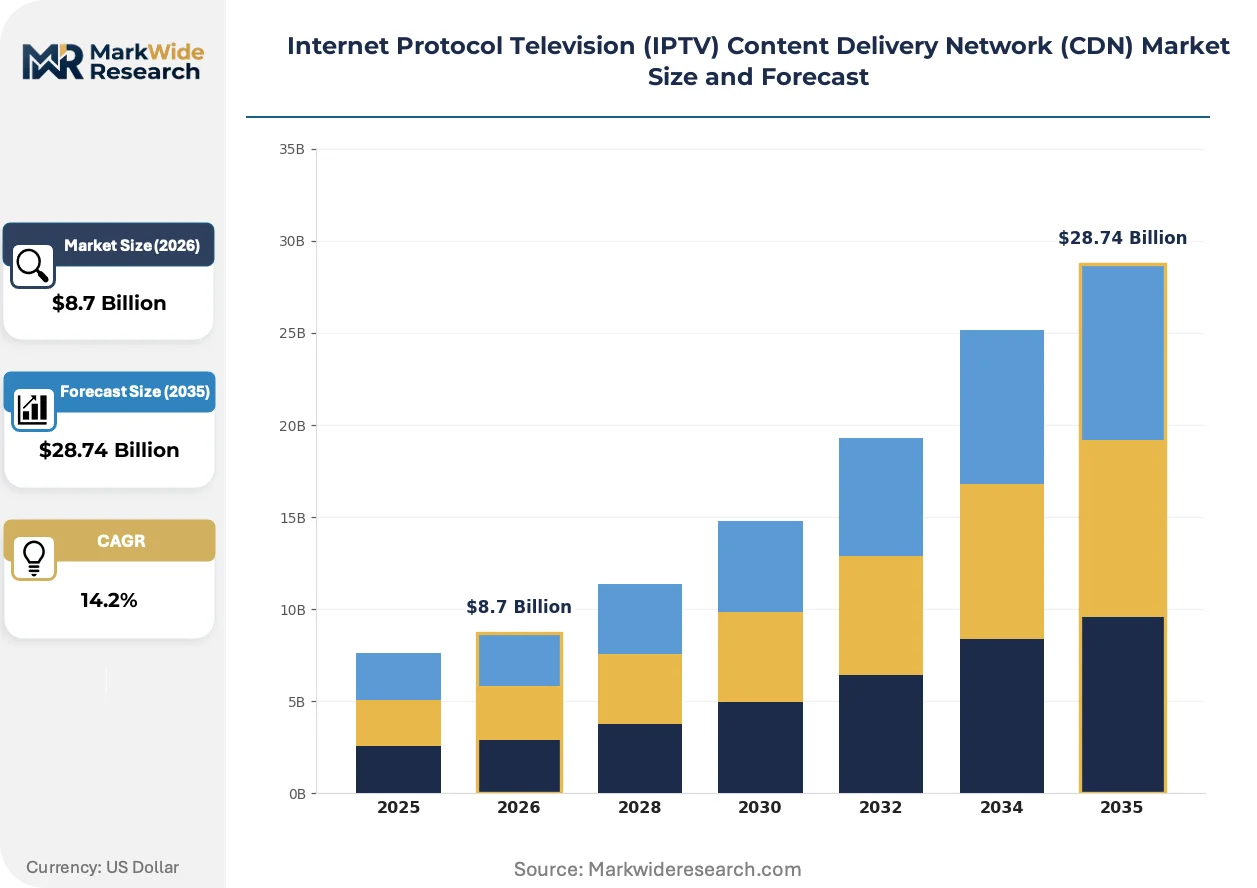
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: On-Premise, Cloud-Based, Hybrid, Edge Computing Service Type: Video Streaming, Live Broadcasting, Video on Demand, Subscriber Management Technology: Adaptive Bitrate Streaming, Multicast, Unicast, CDN Optimization End User: Telecommunications, Media Companies, Enterprises, Educational Institutions |
| Companies Covered | Xtreme HD IPTV, IPTVGear, ZYMINEX, DirecTV Stream, fuboTV, IPVARIO, StrimoIPTV, YouTube TV, TELEVIXY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market Shifts & Advancements
Compression of delivery latency thresholds below two seconds is forcing infrastructure architecture decisions that favor distributed compute over centralized cloud models.
Edge server mesh networks are consolidating video caching functions at metropolitan aggregation points. Telecommunications providers in Germany and Japan are deploying these nodes within 50 kilometers of subscriber clusters. This topology is consolidating vendor relationships around suppliers with proven last-mile integration capabilities.
FCC net neutrality frameworks are constraining traffic prioritization arrangements between content platforms and last-mile providers. The regulatory friction is elevating peering agreement negotiation complexity. Sports streaming services are responding by building proprietary edge footprints to bypass transit cost uncertainty.
Viewer tolerance for startup delay has compressed from fifteen seconds to under three seconds across premium live events. Broadcasters are unbundling quality-of-service guarantees from standard subscription tiers. This behavioral shift is most visible in United States markets where fiber subscribers now expect broadcast-equivalent reliability.
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market Segmentation
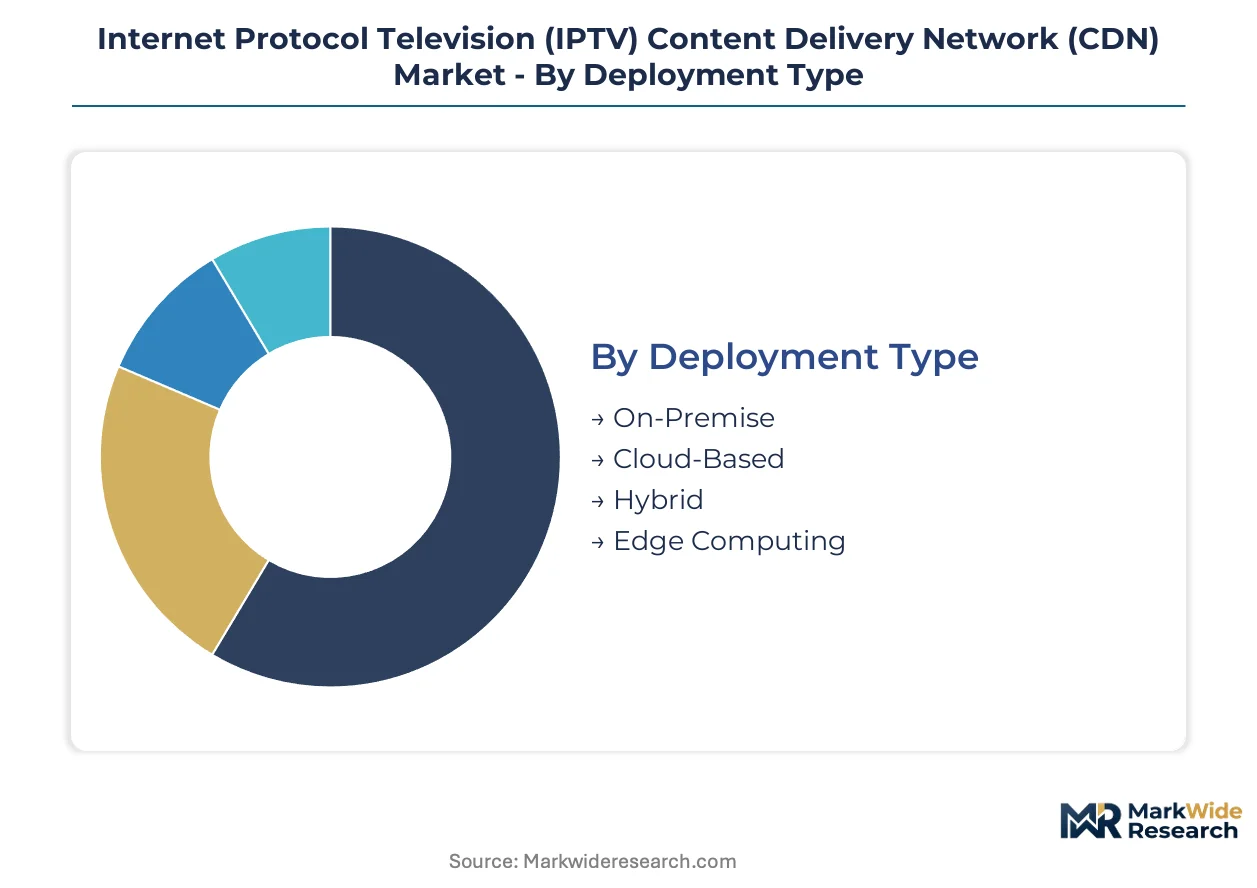
IPTV CDN infrastructure investment decisions hinge on deployment architecture choices that determine capital intensity, operational flexibility, and latency performance. Service providers segment procurement across technology layers to balance origin server load distribution with edge placement economics.
Deployment Type:
Cloud-based deployment absorbs the heaviest upfront infrastructure commitment as operators abandon owned data center footprints for consumption-based models.
- Cloud-Based:Third-party hyperscaler infrastructure eliminates physical server procurement and facility maintenance. Demand concentrates among mid-tier telecommunications providers in Germany and Japan seeking rapid 4K streaming scale without stranded asset risk from hardware obsolescence.
- Edge Computing:Distributed compute nodes placed within 50 kilometers of subscriber clusters enable sub-two-second latency for live sports broadcasting. Cellular tower aggregation points in metropolitan United States zones drive steepest capacity additions as broadcasters bypass transit cost uncertainty through proprietary footprints.
- On-Premise:Operator-owned origin servers and caching layers retain relevance for national broadcasters with strict content sovereignty mandates.
- Hybrid:Blended architectures partition latency-sensitive live traffic to edge nodes while archiving video-on-demand libraries in centralized cloud repositories.
Most installed capacity flows through Cloud-Based deployment. Expansion is steepest in Edge Computing.
Service Type:
Revenue concentration skews toward high-bandwidth video delivery, though subscriber retention tools capture expanding margin as churn reduction becomes critical.
- Video Streaming:On-demand content delivery generates the largest revenue pool through adaptive bitrate protocols that adjust quality to variable broadband conditions. United States fiber-to-the-home deployments accelerate CDN capacity investments for 4K and live sports consumption.
- Subscriber Management:Analytics platforms for churn prediction and personalization capture expanding margin as OTT bundling intensifies competition. North American operators prioritize these tools to defend subscriber lifetime value against platform fragmentation.
- Live Broadcasting:Real-time event streaming imposes strict latency thresholds below two seconds for sports and news applications.
- Video on Demand:Library content caching reduces origin server load through pre-positioned storage at metropolitan aggregation points.
Video Streaming commands the largest share of committed capacity. Subscriber Management is climbing the fastest as operators prioritize retention economics.
Technology:
Protocol standardization determines interoperability costs and vendor selection flexibility across multi-CDN architectures.
- Adaptive Bitrate Streaming:HLS and DASH protocols dynamically adjust video quality to network conditions without requiring wholesale infrastructure replacement. FCC net neutrality frameworks constrain traffic prioritization, elevating peering complexity and driving investment in protocol-layer optimization.
- CDN Optimization:Traffic routing algorithms and cache efficiency tools reduce bandwidth costs for high-volume distributors. GDPR data localization mandates in Europe accelerate deployment of optimization layers that enforce geographic content boundaries.
- Multicast:Simultaneous stream replication to multiple subscribers conserves backbone bandwidth for linear broadcast simulcasts.
- Unicast:Individualized stream delivery supports personalized advertising insertion and interactive features.
Adaptive Bitrate Streaming anchors current infrastructure deployment. CDN Optimization is gaining share fastest as regulatory fragmentation complicates traffic management.
End User:
Procurement authority and technical requirements diverge sharply between connectivity providers and content publishers.
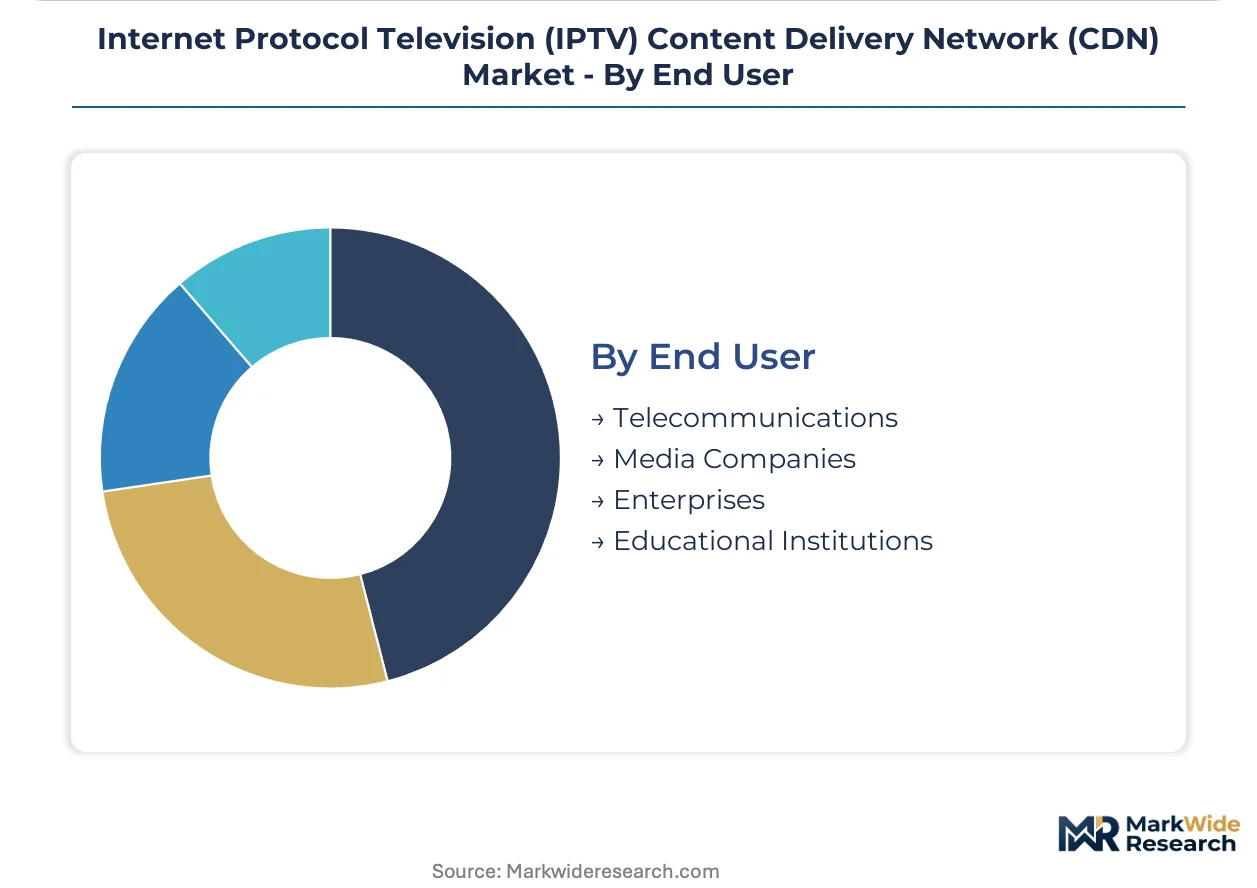
- Telecommunications:Broadband operators integrate CDN functions into last-mile service bundles, requiring seamless handoff between core networks and subscriber premises equipment. Fiber expansion in United States metropolitan zones drives capacity commitment guarantees through multi-year vendor contracts.
- Media Companies:Sports streaming specialists and broadcast networks prioritize edge server placement to sustain subscriber retention during peak live events. Proprietary infrastructure investments bypass transit cost uncertainty from peering disputes.
- Enterprises:Corporate video distribution and internal streaming platforms demand security-hardened caching layers.
- Educational Institutions:Campus networks and distance learning platforms require cost-optimized delivery for asynchronous video libraries.
Telecommunications providers account for the majority of committed infrastructure spend. Media Companies are expanding most quickly as direct-to-consumer streaming displaces traditional distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States metropolitan fiber corridors anchor infrastructure investment intensity for low-latency video delivery. Regulatory frameworks and broadband deployment programs across Germany, Japan, United Kingdom, and India are accelerating distributed edge placement.
United States
FCC net neutrality constraints and fiber-to-the-home expansion in Texas and California drive multi-vendor CDN procurement. Municipal broadband initiatives in Chattanooga and Austin bypass incumbent transit negotiations. Edge server clusters in Dallas-Fort Worth and Los Angeles metro zones sustain sub-two-second latency for live sports.
Germany
GDPR data localization mandates and 4K streaming adoption among Deutsche Telekom subscribers force national border server placement. CE marking compliance extends hardware certification timelines for network equipment vendors. Berlin and Munich host the densest metropolitan caching node concentrations for OTT bundling platforms.
Japan
METI digital infrastructure targets and 8K broadcast trials by NHK push ultra-low-latency architecture investment. JIS standards govern equipment interoperability for multi-vendor deployments. Tokyo-Osaka corridor operators deploy cellular tower aggregation points within 50 kilometers of subscriber clusters.
United Kingdom
Ofcom wholesale access rules and BT Openreach fiber upgrades enable competitive CDN capacity scaling. Post-Brexit data sovereignty divergence from EU frameworks complicates cross-border traffic routing. London and Manchester data centers anchor peering agreement negotiations for sports streaming specialists.
India
TRAI OTT regulatory consultations and Reliance Jio fiber expansion create mass-market 4K streaming pathways. BIS certification requirements for imported network equipment delay vendor onboarding. Bangalore and Hyderabad tech corridors concentrate edge computing pilots for regional language content delivery.
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized sports streaming infrastructure and proprietary edge footprints. The vendor base stratifies across hyperscaler-dependent platforms, telecommunications-integrated operators, and independent streaming specialists. Three archetypes dominate: fiber-bundle anchors, sports-centric direct-to-consumer services, and global caching partnership platforms. Capacity commitment guarantees through multi-year vendor contracts and metropolitan edge server placement constitute the primary competitive vectors.
Among United States-based streaming platforms, YouTube TV, fuboTV, and DirecTV Stream exemplify divergent infrastructure strategies. YouTube TV occupies a position anchored in global hyperscaler partnerships that minimize last-mile transit costs. fuboTV exemplifies the sports-specialist archetype through proprietary edge investments that sustain subscriber retention during peak concurrent viewership. DirecTV Stream represents the telecommunications-integrated tier with fiber-bundle distribution and owned metropolitan server placement.
| Leading Market Players |
|---|
| Xtreme HD IPTV |
| IPTVGear |
| ZYMINEX |
| DirecTV Stream |
| fuboTV |
| IPVARIO |
| StrimoIPTV |
| YouTube TV |
| TELEVIXY |
| Others |
Supply & Pricing Matrix
Multi-vendor CDN procurement mandates from telecommunications operators in the United States and Germany are forcing infrastructure vendors to absorb integration testing costs and compress margin structures across hardware and software tiers.
Pricing Analysis
Input-cost pass-through from semiconductor components and optical networking equipment anchors CDN infrastructure pricing. Three-tier pricing structure across premium edge-computing nodes, standard cloud-based deployments, and economy-grade on-premise hardware captures performance differentiation. Cost compression in the economy tier is intensifying because hyperscaler competition is commoditizing basic caching functions. Mid-tier telecommunications providers in Germany exhibit highest price sensitivity, while sports streaming specialists in the United States prioritize latency guarantees over unit cost.
Supply Chain Analysis
Edge server manufacturing rests on Taiwanese semiconductor foundries, South Korean memory producers, and Chinese optical component assemblers. Bare metal servers, solid-state storage arrays, and 100G/400G networking switches constitute critical input categories. Single-source vulnerability concentrates in advanced node chip fabrication. Distribution runs through direct OEM relationships with telecommunications equipment vendors and hyperscaler procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IPTV CDN infrastructure functions as a stable compounder anchored by irreversible fiber-to-the-home deployment cycles and persistent bandwidth demand from live sports streaming.
For Market Incumbents: To counter hyperscaler encroachment into edge computing, incumbent CDN vendors should deepen backward integration into custom silicon design for video processing acceleration. Capacity additions in Japan's Tokyo-Osaka corridor and Germany's Berlin-Munich axis will defend installed base relationships against multi-vendor procurement mandates. For New Entrants and Emerging Players: GDPR data localization in Germany opens a window for sovereign edge infrastructure specialists to capture national broadcaster contracts bypassing global hyperscaler footprints. India's TRAI OTT regulatory consultations present a second entry point for regional language content delivery optimization. A direct sales model targeting state-owned telecommunications operators offers the cleanest go-to-market path. For Investors and Strategic Acquirers: Asymmetric upside sits with edge-computing hardware vendors possessing proven last-mile integration capabilities and existing cellular tower relationships. The five-to-ten-year viability window favors suppliers with software-defined networking stacks that abstract multi-vendor complexity. Watch for inflection signals in peering agreement renegotiations between sports streaming platforms and last-mile providers.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Server Mesh Deployment | Cellular tower aggregation points in Dallas-Fort Worth enable sub-two-second latency for live sports. |
| Multi-Vendor API Standardization | HLS and DASH protocol harmonization reduces integration overhead for German telecommunications operators. |
| GDPR-Compliant Data Localization | National border server placement satisfies European data sovereignty mandates for OTT bundling platforms. |
| Subscriber Management Platform Integration | Churn prediction analytics capture expanding margin as North American streaming competition intensifies. |
| Hyperscaler Partnership Structuring | Global caching agreements minimize last-mile transit costs for fiber-bundle anchors like YouTube TV. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with CDN engineering directors, telecommunications procurement officers, sports streaming platform CTOs, and regulatory affairs specialists at European network operators informed demand-side assumptions. Secondary validation drew from FCC net neutrality filings, EMA content classification standards, TRAI consultation papers, and hyperscaler capex disclosures. Bottom-up capacity deployment tracking and top-down market sizing triangulated volume estimates.
Comparable-period anchoring linked forward projections to historical infrastructure investment cycles across fiber-to-the-home deployment waves. The analytical framework modeled deployment type, service category, technology protocol, and end-user vertical dimensions across the projection horizon. CAGRs derived from installed base growth rates and subscriber management tool penetration curves. Forecast inputs incorporated adaptive bitrate streaming adoption trajectories and edge computing node placement density assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory fragmentation scenarios and peering agreement disputes. Projections reflect documented assumptions about fiber deployment timelines and hyperscaler pricing discipline. A small set of named triggers—FCC rulemaking on traffic prioritization, GDPR enforcement actions, and live event concurrency records—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Network Function Virtualization (NFV) Market
Data Center and Networking
Broadband Network Gateway Market
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
Data Center Networks Market
Data Center and Networking
Software Defined Video Networking Market
Data Center and Networking
North America Data Center Networking Market
Data Center and Networking
Germany Data Center Server Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Network Optimization Services Market
Data Center and Networking
Switzerland Data Center Networking Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
Denmark Data Center Networking Market
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
New Zealand Data Center Networking Market