
 Ultraviolet (UV) Coatings Market | 2026-2036
Ultraviolet (UV) Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Ultraviolet (UV) Coatings Market Analytics
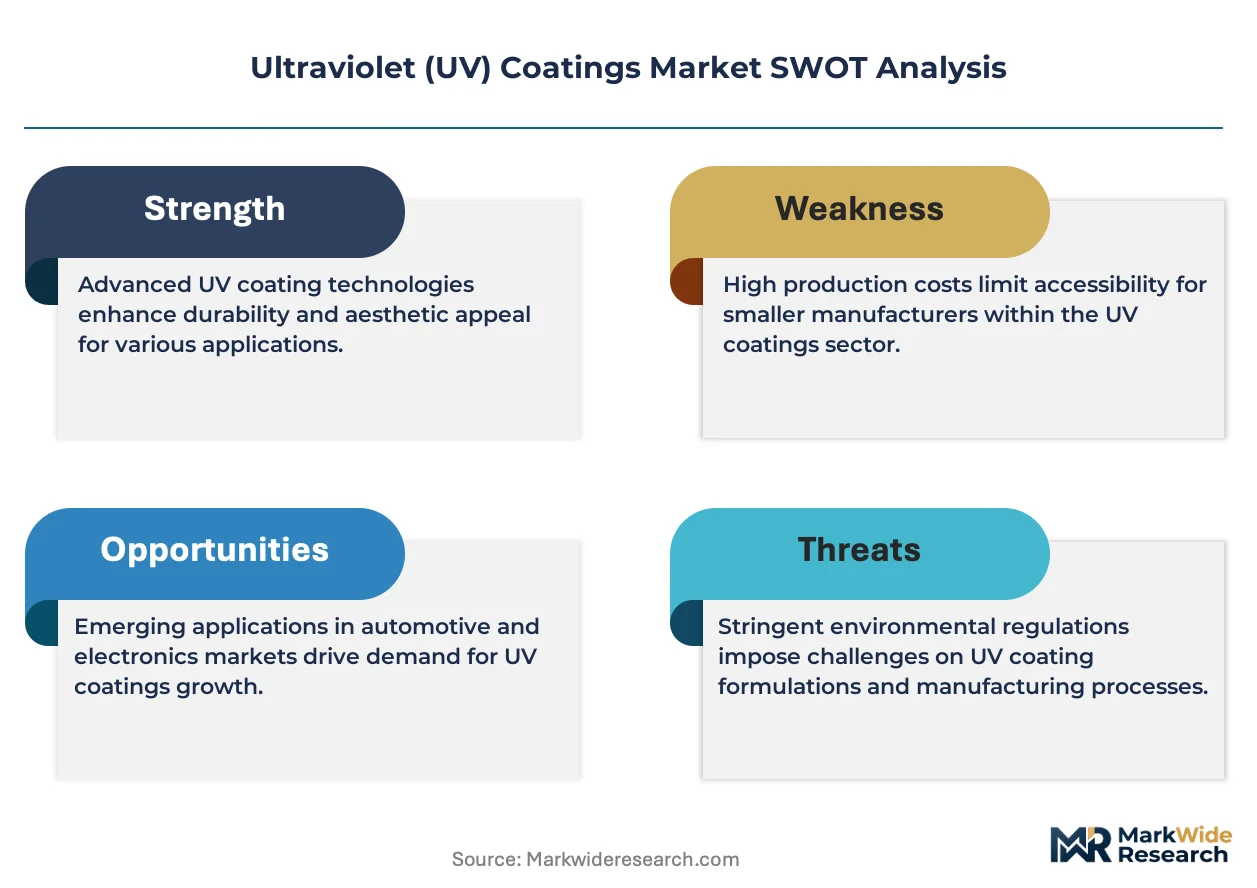
High-performance scratch-resistant grade specifications are redrawing competitive boundaries in the UV coatings sector. AkzoNobel NV leverages its marine and protective coatings heritage to anchor premium industrial UV formulations. PPG Industries sustains technology leadership through deep R&D investment in automotive clearcoat applications. BASF SE differentiates via backward integration into photoinitiator chemistry and resin synthesis.
Ultraviolet coatings are liquid or powder formulations that cure almost instantly upon exposure to UV light in the 200-400 nanometer wavelength range, typically containing oligomers, monomers, photoinitiators, and functional additives that polymerize through free-radical or cationic mechanisms. Their primary commercial purpose is to deliver durable, chemically resistant surface protection with near-zero volatile organic compound emissions and energy consumption far below thermal curing systems. Industrial UV coatings occupy the largest volume position due to mature factory-floor deployment across metal finishing and plastic substrate lines, while LED UV technology represents the fastest-expanding technology segment as mercury vapor phase-outs accelerate under environmental mandates. Electronics protection applications command margin concentration because of exacting purity requirements and qualification barriers in semiconductor and display manufacturing.
The EPA regulates VOC content under architectural and industrial maintenance coating rules, while REACH governs chemical registration and restricted substance thresholds across European supply chains. FDA compliance requirements for food-contact packaging coatings create additional specification layers that filter supplier eligibility in North American markets. LED UV technology maturation and evolving photoinitiator safety classifications will demand sustained formulation investment and regulatory tracking from stakeholders across the value chain.
Market Dynamics
Mercury vapor lamp phase-outs under the Minamata Convention are compressing equipment replacement cycles and forcing rapid LED UV retrofit investments across coating lines.
Growth Catalysts
- REACH VOC Thresholds:Tightening emission ceilings across European industrial coating operations are accelerating solvent-to-UV conversion mandates in Germany and France.
- Automotive Interior Specifications:Scratch-resistant dashboard and trim finishes now specify UV-cured clearcoats as standard equipment across premium vehicle programs.
- LED UV Wavelength Maturation:395 nanometer diode arrays now deliver cure depths matching legacy mercury systems at half the energy input.
Market Restraints
- Photoinitiator Supply Concentration:Specialty photoinitiator manufacturing clusters in China and India create input vulnerability for Western formulators.
- Substrate Compatibility Limits:Heat-sensitive thermoplastics and certain engineered woods resist UV cure penetration, excluding segments from conversion.
- Capital Equipment Intensity:Full LED UV line retrofits demand seven-figure investments that mid-tier coaters cannot finance without equipment-leasing structures.
Strategic Opportunities
- Food-Contact Packaging:FDA-compliant UV varnish formulations for folding cartons remain underdeveloped relative to solvent and water-based alternatives.
- Wind Turbine Blade Coatings:Offshore wind installation growth creates demand for UV-cured leading-edge protection with rapid factory throughput.
- Dual-Carbon Policy Alignment:China's MEE energy-intensity targets reward UV conversion with preferential factory licensing in coastal provinces.
Industry Challenges
- Formulation Chemistry Expertise Gap:Free-radical and cationic cure mechanism optimization requires polymer science specialization scarce outside major chemical clusters.
- Photoinitiator Migration Testing:Extended FDA and EFSA food-contact certification timelines delay new product commercialization by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultraviolet (UV) Coatings Market |
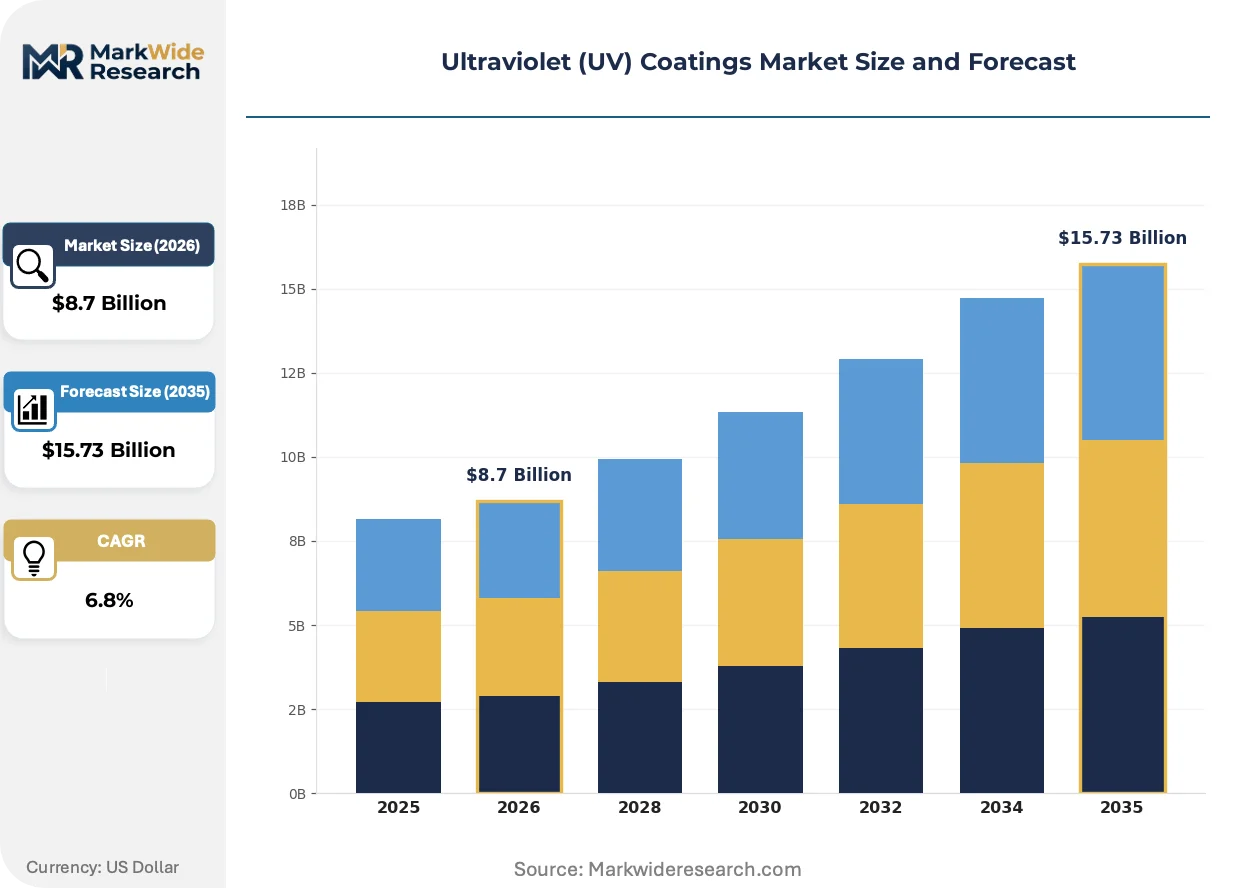
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial UV Coatings, Medical UV Coatings, Graphic Arts UV Coatings, Electronic UV Coatings Application: Automotive Finishing, Electronics Protection, Wood Coatings, Packaging Solutions Technology: Mercury Vapor Lamps, LED UV Technology, Electron Beam Curing, UV Flexography End User: Automotive OEMs, Electronics Manufacturers, Furniture Producers, Customized Packaging |
| Companies Covered | AkzoNobel NV, PPG Industries, The Sherwin-Williams Company, BASF SE, Axalta Coating Systems, Dymax Corp., Royal DSM NV, DIC Corporation, Nippon Paints, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultraviolet (UV) Coatings Market Evolving Landscape
Formulation chemistry, curing hardware, and regulatory compliance frameworks are simultaneously evolving, compressing product development cycles and rewarding integrated R&D capabilities.
LED UV curing systems operating at 385-405 nanometers are supplanting medium-pressure mercury arc lamps across industrial coating lines. Automotive OEMs in Stuttgart and Wolfsburg now specify LED-compatible formulations for all new interior trim programs. This hardware transition is compressing cure station footprints by sixty percent while eliminating mercury handling compliance costs.
REACH Annex XVII restrictions on specific photoinitiator chemistries are forcing reformulation investments across European supply chains. ECHA hazard classifications for certain Type I photoinitiators are triggering substitution mandates in consumer-facing applications. Packaging coaters serving German food brands are accelerating migration to Type II oligomeric photoinitiator systems despite higher raw material costs.
Automotive OEMs now require coating suppliers to assume full environmental compliance liability through contractual indemnification clauses. Tier-1 interior component manufacturers in Germany and Michigan are transferring regulatory risk to their formulation partners. This liability shift is concentrating procurement among vertically integrated suppliers with captive toxicology and regulatory affairs capabilities.
Ultraviolet (UV) Coatings Market Segmentation
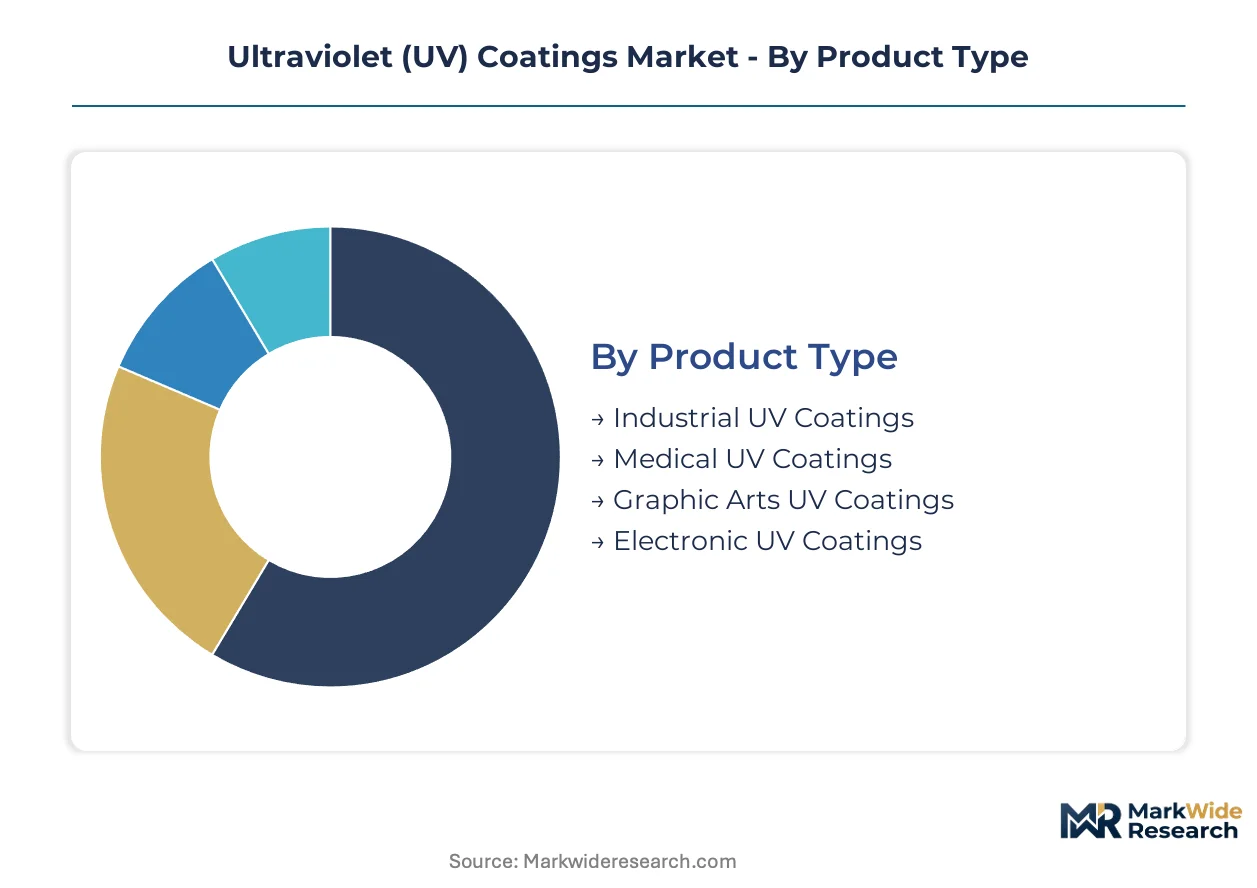
UV coatings segmentation reveals divergent technical requirements across industrial, medical, and electronics applications. Each product category demands specialized photoinitiator packages and cure kinetics that reshape supplier qualification criteria and geographic sourcing patterns.
Product Type:
Industrial UV coatings dominate domestic consumption in manufacturing belts, while medical and electronics grades concentrate in export-led specialty chemical clusters.
- Industrial UV Coatings:High-volume formulations built on acrylate oligomers and multifunctional monomers deliver scratch resistance and chemical protection for metal and plastic substrates. Demand concentrates in Germany's automotive belt around Stuttgart and Wolfsburg, where REACH VOC thresholds are accelerating solvent-to-UV conversion mandates.
- Electronic UV Coatings:Ultra-pure formulations with sub-ppm ionic contamination limits protect semiconductor wafers and display panels. This segment concentrates in coastal Chinese provinces, where MEE dual-carbon policy targets reward UV conversion with preferential factory licensing.
- Medical UV Coatings:Biocompatible formulations meeting ISO 10993 standards for device surface protection.
- Graphic Arts UV Coatings:High-gloss overprint varnishes for commercial printing with rapid press turnaround requirements.
Industrial UV coatings hold the largest share; momentum sits with electronic UV coatings.
Application:
Automotive finishing commands premium pricing tiers, while packaging solutions operate on volume-driven cost structures with thinner margin profiles.
- Automotive Finishing:Scratch-resistant dashboard and interior trim clearcoats now specify UV-cured systems as standard equipment across premium vehicle programs. Specifications from Stuttgart and Wolfsburg OEMs are cascading through Tier-1 supplier networks in Michigan and Ontario.
- Electronics Protection:Conformal coatings and encapsulants shield PCBs from moisture, thermal cycling, and ionic migration. Exact purity requirements and qualification barriers in semiconductor manufacturing create margin concentration unmatched by other applications.
- Wood Coatings:UV-cured finishes for flooring and furniture deliver hardness without solvent emissions.
- Packaging Solutions:FDA-compliant UV varnishes for folding cartons remain underdeveloped relative to solvent alternatives.
Automotive finishing generates the highest revenue per liter; electronics protection is climbing the fastest on semiconductor capacity expansion.
Technology:
Customer procurement patterns split between legacy mercury infrastructure and LED retrofit investments, with electron beam curing occupying niche high-performance segments.
- LED UV Technology:385-405 nanometer diode arrays now deliver cure depths matching legacy mercury systems at half the energy input. Automotive OEMs in Germany now specify LED-compatible formulations for all new interior trim programs, compressing cure station footprints by sixty percent.
- Mercury Vapor Lamps:Medium-pressure arc lamps face phase-out pressure under the Minamata Convention, compressing equipment replacement cycles across coating lines.
- Electron Beam Curing:Radiation-cured systems for thick-film applications where UV penetration limits arise.
- UV Flexography:Central impression cylinder presses for flexible packaging with high-speed web handling.
Mercury vapor lamps retain installed-base dominance; LED UV technology shows the steepest expansion trajectory on energy efficiency mandates.
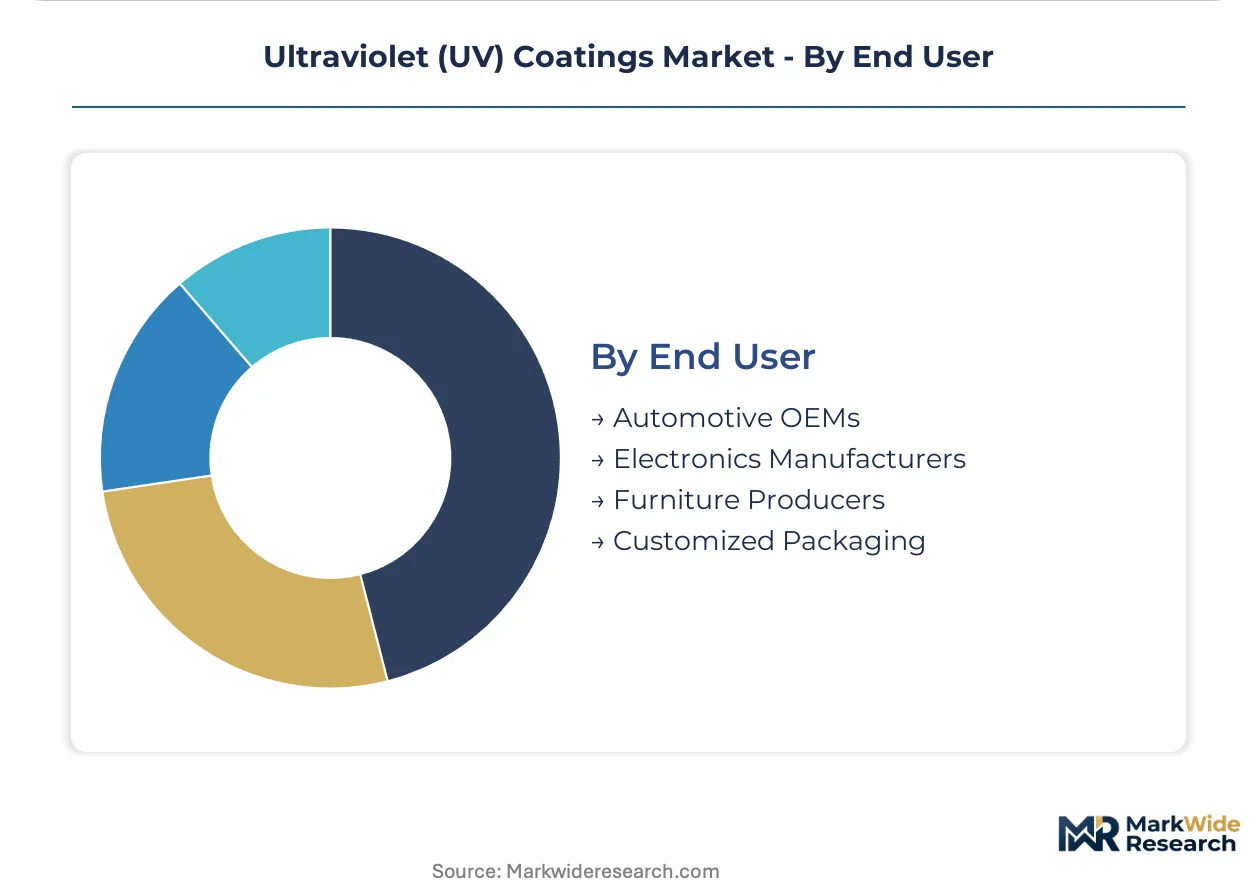
End User:
Automotive OEMs and electronics manufacturers drive specification authority, while furniture producers and packaging converters follow formulation recommendations from upstream suppliers.
- Automotive OEMs:Volkswagen, BMW, and Mercedes-Benz programs now require coating suppliers to assume full environmental compliance liability through contractual indemnification clauses. This liability shift is concentrating procurement among vertically integrated suppliers with captive toxicology capabilities.
- Electronics Manufacturers:Semiconductor fabs and display panel producers in Taiwan and South Korea demand photoinitiator migration testing protocols that extend qualification timelines.
- Furniture Producers:North American and European flooring manufacturers adopting UV-cured finishes for factory throughput advantages.
- Customized Packaging:Folding carton and label converters serving food brands with FDA-compliant formulation requirements.
Automotive OEMs command the largest formulation volumes; electronics manufacturers are gaining share fastest on fab capacity builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty photoinitiator manufacturing clusters in China and India feed formulation plants in Germany and the United States, creating interdependent supply corridors that reshape regional competitive dynamics.
Germany
Automotive OEMs in Stuttgart and Wolfsburg now mandate UV-cured interior clearcoats across premium vehicle programs. REACH Annex XVII restrictions on specific photoinitiator chemistries force reformulation investments across Baden-Württemberg coating plants. Tier-1 suppliers in Lower Saxony transfer regulatory compliance liability to formulation partners through contractual indemnification clauses.
China
MEE dual-carbon policy targets reward UV conversion with preferential factory licensing in coastal provinces. Semiconductor fabs and display panel producers in the Yangtze River Delta demand photoinitiator migration testing protocols that extend qualification timelines. LED UV equipment retrofits accelerate in Guangdong manufacturing belts as mercury vapor phase-outs compress replacement cycles.
United States
FDA compliance requirements for food-contact packaging coatings filter supplier eligibility in North American markets. EPA VOC content rules under architectural and industrial maintenance coating rules push solvent-based alternatives toward UV-cured systems. Michigan-based Tier-1 automotive suppliers adopt German OEM specifications for scratch-resistant dashboard finishes.
Japan
Electronics protection applications command margin concentration because of exacting purity requirements in semiconductor manufacturing. METI energy-efficiency mandates accelerate LED UV adoption in Kanto region coating lines. DIC Corporation and Nippon Paints anchor domestic supply chains for display panel and PCB conformal coatings.
South Korea
Display panel producers in the Seoul Capital Area specify ultra-pure UV formulations with sub-ppm ionic contamination limits. MFDS food-contact regulations create parallel certification requirements for packaging coaters serving export markets. Samsung and LG supplier networks drive LED UV curing specifications across Gyeonggi-do component plants.
Ultraviolet (UV) Coatings Market Competitive Landscape
Concentration sits with diversified chemical conglomerates possessing captive photoinitiator synthesis and regulatory affairs capabilities. The vendor base splits between vertically integrated multinationals and regional specialists serving single end-use segments. Three archetypes dominate: conglomerates with backward integration into resin chemistry, automotive-focused coating formulators with OEM qualification depth, and electronics-grade specialists with cleanroom manufacturing protocols. Competitive moves center on LED UV formulation licensing partnerships and assumption of environmental compliance liability through contractual structures.
Among diversified chemical conglomerates, AkzoNobel NV and BASF SE exemplify the integrated archetype through upstream control over photoinitiator chemistry and resin synthesis. PPG Industries occupies a position within the automotive-qualified tier, leveraging deep OEM relationships in interior trim specifications. These three anchors represent distinct competitive vectors: European chemical heritage, North American automotive coating dominance, and German industrial integration respectively.
| Leading Market Players |
|---|
| AkzoNobel NV |
| PPG Industries |
| The Sherwin-Williams Company |
| BASF SE |
| Axalta Coating Systems |
| Dymax Corp. |
| Royal DSM NV |
| DIC Corporation |
| Nippon Paints |
| Others |
Value Network & Pricing Analysis
REACH Annex XVII restrictions on specific photoinitiator chemistries gate both supplier qualification and price differentiation simultaneously, creating tiered entry barriers that separate vertically integrated multinationals from regional formulators.
Pricing Analysis
REACH VOC thresholds dictate the pricing tier structure across European supply chains, separating premium LED-compatible formulations from legacy mercury-cured grades. Price differentiation hinges on photoinitiator migration certification under EFSA protocols and volume-scale procurement leverage. Cost compression in standard industrial grades is intensifying because of photoinitiator supply concentration in Asian manufacturing clusters. Customized packaging coaters serving German food brands exhibit highest price sensitivity, while semiconductor fabs demand premium purity grades with minimal cost elasticity.
Supply Chain Analysis
China and India anchor specialty photoinitiator manufacturing, feeding formulation plants in Germany and the United States through interdependent supply corridors. Western formulators draw from acrylate oligomer production in the Netherlands and monomer synthesis in Belgium, creating multi-node dependencies. Single-source vulnerability concentrates around Type I photoinitiator precursors subject to ECHA hazard reclassification. Distribution runs through regional chemical distributors with technical service capabilities, bypassing commodity trading houses for specification-grade materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LED UV wavelength maturation fragments procurement authority, creating specialist niches for formulation houses that bridge equipment OEMs and end-user qualification protocols.
For Market Incumbents: Secure captive photoinitiator synthesis capacity before REACH Annex XVII expansion triggers raw material obsolescence. Deepen regulatory affairs capabilities to assume environmental compliance liability that Tier-1 automotive suppliers now refuse. LED equipment OEMs represent the emerging threat vector as they backward integrate into formulation licensing. For New Entrants and Emerging Players: Food-contact packaging FDA compliance services present a service-layer gap where incumbents under-serve mid-tier folding carton converters. Target this segment through formulation partnerships with established photoinitiator suppliers rather than greenfield synthesis investment. Qualification acceleration services—compressing 18-month migration testing timelines—offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across LED UV equipment-formulation integrated offerings, favoring asset-light licensing models over manufacturing ownership. Acquisition target archetype: regional specialists with OEM qualification depth in automotive interior trim or electronics conformal coatings. Watch LED UV diode cost curves as the inflection signal—crossover points with mercury system total cost of ownership will reshape competitive boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Synthesis | Captures margin concentration and insulates against REACH substitution mandates. |
| LED UV Formulation Licensing Partnerships | Equipment OEMs in Germany specify compatible chemistry for new interior trim programs. |
| Food-Contact Migration Testing Infrastructure | FDA and EFSA certification timelines create 18-24 month barriers for unprepared competitors. |
| Automotive Liability Assumption Contracts | Volkswagen and BMW procurement now requires full environmental compliance indemnification. |
| Dual-Carbon Policy Alignment in China | MEE preferential licensing rewards UV conversion in Yangtze River Delta manufacturing belts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with coating formulators, automotive Tier-1 procurement leads, photoinitiator plant managers, and LED UV equipment OEM technical directors. Secondary validation drew from ECHA regulatory filings, EPA VOC rulemaking dockets, customs trade data for acrylate resin flows, and SEC disclosures from diversified chemical conglomerates. Bottom-up volume modeling triangulated against top-down value estimates across the projection horizon.
Across the analysis window, forecasts incorporate segmentation by product type, application technology, and end-user procurement authority, with additional granularity on REACH compliance tier and LED wavelength compatibility. CAGRs were derived from installed-base replacement cycles, solvent-to-UV conversion elasticity under tightening VOC thresholds, and semiconductor fab capacity expansion trajectories. Photoinitiator supply concentration indices and automotive OEM specification velocity served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in REACH Annex XVII and EPA architectural coating rules; material policy shifts would require re-modeling. Specific risks include accelerated mercury vapor lamp phase-outs under Minamata Convention amendments, EFSA photoinitiator migration threshold revisions, and MEE dual-carbon enforcement intensity variations. Recalibration cycles align with material shifts in regulatory hazard classifications and LED UV diode cost-performance curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market
Coatings
Global Antiviral Coatings Market
Coatings
Automotive Conformal Coatings Market
Coatings
Mexico Protective Coatings Market
Coatings
Italy Protective Coatings Market
Coatings
Europe Super Hydrophobic Coatings Market
Coatings
Functional Coil Coating Market
Coatings
Coating Binders Market
Coatings
Canada Protective Coatings Market
Coatings
Europe Thermal Spray Market
Coatings
Silicate Coatings Market
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
Global Nanocoatings Market
Coatings
Coating Equipment Market
Coatings
Global Industrial Floor Coatings Market
Coatings
Asia-Pacific Floor Coatings Market