
 Mold Release Coatings Market | 2026-2036
Mold Release Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Mold Release Coatings Market Foresight
ISO 14001 environmental management certification is reorganizing competitive access in mold release coatings, filtering out smaller compounders lacking documented sustainability systems. Henkel AG & Co. KGaA leverages its adhesives heritage to cross-sell integrated release-and-bonding solutions across automotive stamping operations. Shin-Etsu Chemical Co., Ltd anchors fluorosilicone technology leadership through captive organosilicon feedstock and precision polymerization control.
Mold release coatings are thin-film surface treatments applied to tooling substrates to prevent adhesion between molded parts and die surfaces, typically formulated with polydimethylsiloxane, fluoropolymers, or proprietary wax blends and engineered to withstand temperatures exceeding 300°C in thermoset compression molding. Their primary purpose is to preserve part dimensional accuracy, reduce cycle times, and extend tool life in high-volume manufacturing. Aqueous formulations now lead product type demand as shop-floor VOC limits harden, while silicone-based materials capture the deepest margin pools due to thermal stability premiums in aerospace turbine blade molding. Electronics application growth outpaces automotive as miniaturized polymer enclosures for 5G infrastructure multiply cavity complexity.
EPA NESHAP standards for hazardous air pollutants and REACH Annex XVII restrictions on perfluorinated compounds are forcing reformulation timelines across North American and European supply chains, with compliance costs favoring larger registrants. China's MEE enforcement of GB standards for industrial emissions is tightening local production permits for solvent-based release agents. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border tooling supply chains.
Market Dynamics
Automotive OEMs are consolidating supplier bases around solvent-free release systems to meet tightening volatile organic compound limits, compressing procurement timelines and favoring compounders with documented environmental management certification.
Growth Catalysts
- REACH Annex XVII restrictions:European perfluorinated compound limits are accelerating aqueous formulation adoption across aerospace turbine blade molding operations.
- China mold-making capacity:Domestic tooling expansion for electronics export production is concentrating demand for high-temperature silicone release agents in Guangdong and Jiangsu provinces.
- Hot melt technology maturation:Elimination of solvent handling infrastructure is reducing shop-floor compliance costs for automotive stamping plants in the United States.
Market Restraints
- Organosilicon feedstock concentration:Captive production of polydimethylsiloxane precursors limits supply flexibility and creates dependency on Asian petrochemical complexes.
- Fluoropolymer technical ceiling:Perfluorinated chemistries face hard thermal stability boundaries above 350°C in thermoset compression applications.
- EPA NESHAP compliance friction:Hazardous air pollutant permitting timelines extend reformulation cycles for North American solvent-based release agent manufacturers.
Strategic Opportunities
- 5G infrastructure enclosures:Miniaturized polymer cavity complexity in telecommunications hardware is opening specialized release coating specifications.
- China MEE enforcement tailwind:GB standard industrial emission tightening is creating first-mover advantage for aqueous technology providers in domestic electronics molding.
- Digital formulation platforms:AI-driven rheology prediction is converging with additive manufacturing to enable on-demand release agent customization for prototyping shops.
Industry Challenges
- ISO 14001 certification timelines:Documented sustainability system requirements are filtering smaller compounders from automotive OEM approved vendor lists.
- Cross-border inventory stranding:Regulatory divergence between EPA, REACH, and MEE jurisdictions creates compliance mismatches in multinational tooling supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mold Release Coatings Market |
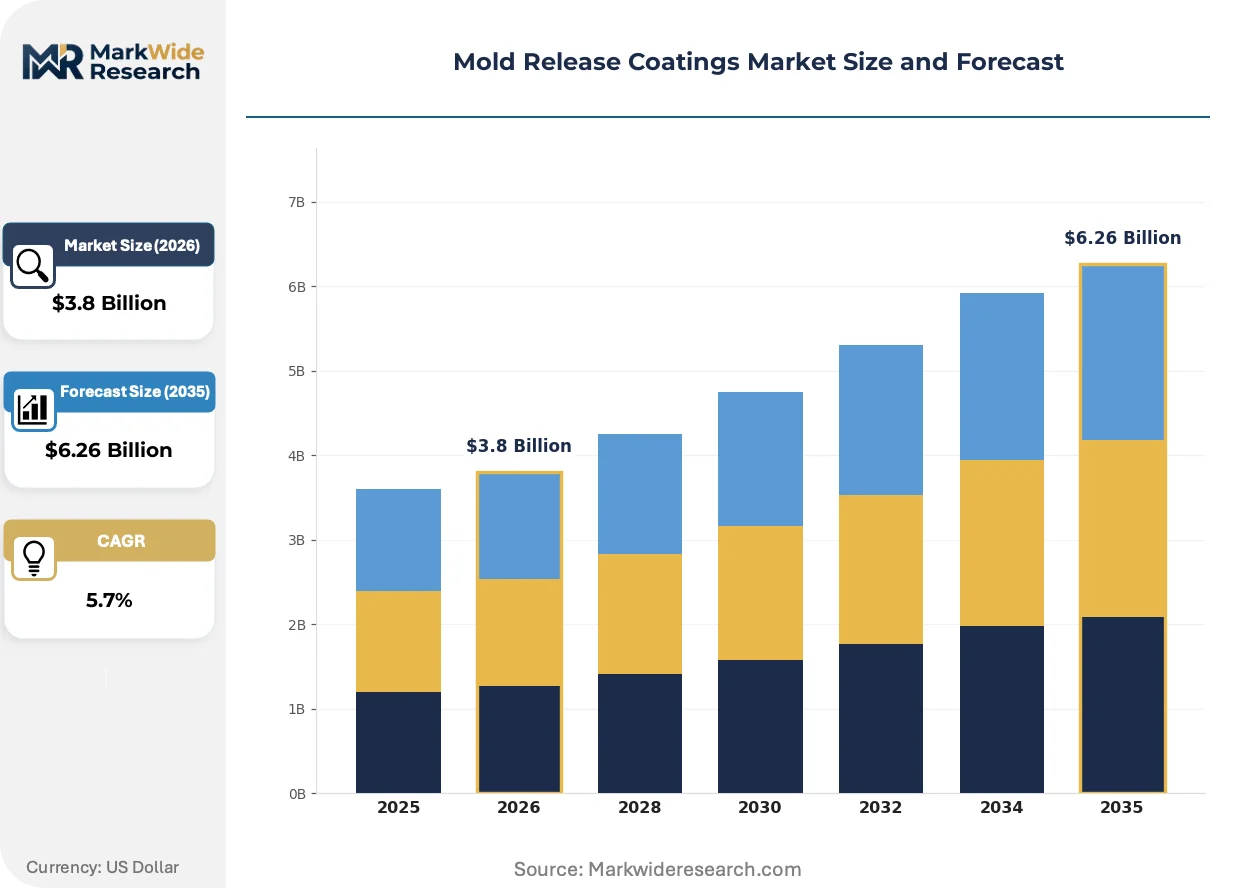
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous, Solvent-Based, Hot Melt, Spray Application: Automotive, Aerospace, Consumer Goods, Electronics Material: Polyurethane, Silicone, Teflon, Wax End User: Manufacturers, Designers, Contractors, Suppliers |
| Companies Covered | Daikin Industries Ltd, Chem-Trend L.P., Henkel AG & Co. KGaA, McGee Industries, Inc., Michelman Inc., Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd, Chukyo Yushi Co., Ltd, Croda International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mold Release Coatings Market Shifts & Advancements
Formulation science is pivoting toward thermal stability premiums and environmental compliance, with aqueous chemistries capturing share from solvent-based systems across high-temperature molding applications.
Fluorosilicone hybrid release coatings are displacing conventional polydimethylsiloxane formulations in aerospace turbine blade molding where thermal cycling exceeds 300°C. Tier-one aerospace suppliers are specifying these materials in new platform qualifications. The shift is compressing margin pools for standard silicone compounders lacking fluoropolymer synthesis capability.
REACH Annex XVII perfluorinated restrictions are forcing European supply chain reformulation with 18-month compliance windows. Automotive stamping operations face tooling recertification costs that favor larger registrants with dedicated regulatory affairs functions. Aqueous and hot melt alternatives are capturing specification share in Germany and France ahead of enforcement deadlines.
Buyer consolidation around integrated release-and-bonding solutions is reshaping automotive procurement patterns. Tier suppliers are unbundling standalone release agent contracts in favor of adhesive system integrators with cross-selling capabilities. This pattern is most visible in German and Japanese automotive clusters where OEMs specify system-level performance guarantees rather than component-level purchasing.
Mold Release Coatings Market Segmentation
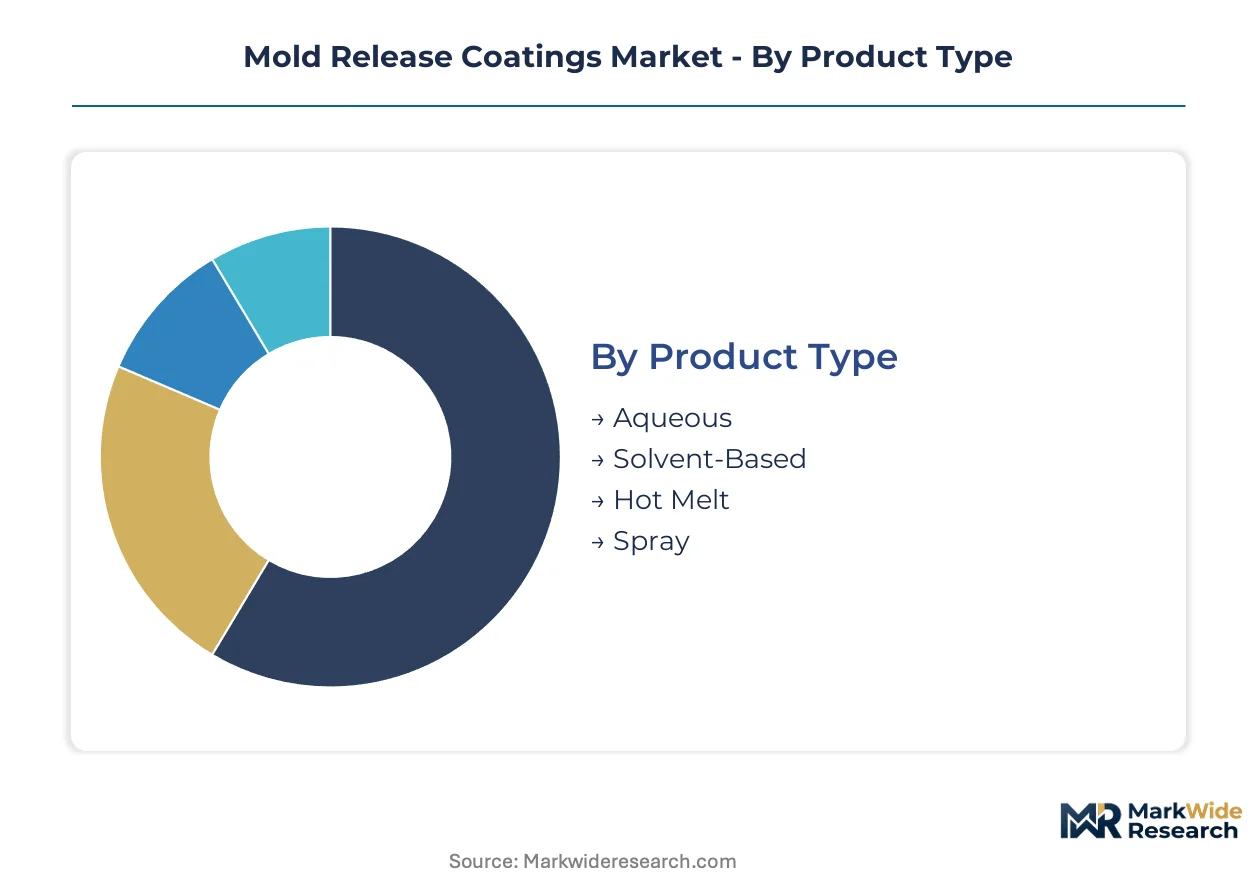
Mold release coatings segment across four critical dimensions that determine formulation specifications, thermal performance thresholds, and procurement channel access. Product chemistry and application environment dictate margin structures, while material selection locks in temperature ceilings and regulatory compliance pathways.
Product Type:
Aqueous formulations command the deepest margin pools due to VOC compliance premiums and solvent-handling infrastructure elimination.
- Aqueous:Water-based emulsions of polydimethylsiloxane or fluoropolymer dispersions formulated for spray or dip application. Demand concentrates in German automotive stamping plants facing REACH Annex XVII enforcement deadlines, where shop-floor VOC limits harden quarterly.
- Solvent-Based:Hydrocarbon or alcohol-borne solutions carrying high-solids silicone or wax actives for rapid film formation. Aerospace turbine blade molders in France and Italy retain specifications here where thermal shock resistance exceeds aqueous chemistry limits.
- Hot Melt:Thermoplastic wax or polymer systems applied molten and solidifying on tool surfaces. Packaging molders in Japan specify these for elimination of solvent recovery equipment.
- Spray:Aerosol or pump-spray delivery formats for maintenance touch-up and prototyping shops. Electronics contract manufacturers in Guangdong province rotate toward compressed-air spray systems for miniaturized cavity access.
Aqueous holds installed capacity. Hot Melt is rotating up the share rankings.
Application:
Electronics applications are climbing the fastest as 5G infrastructure enclosure complexity multiplies cavity geometries and release agent specification tiers.
- Automotive:Stamping die treatments and injection molding of interior polymer components. OEM consolidation around solvent-free systems in the United States compresses approved vendor lists to compounders with EPA NESHAP documentation.
- Aerospace:Turbine blade compression molding and composite layup tooling. Tier-one suppliers in Germany and Japan specify fluorosilicone hybrids for thermal cycling above 300°C.
- Consumer Goods:Packaging, housewares, and appliance molding operations. Brazilian processors favor wax-based releases for cost-sensitive high-volume production.
- Electronics:Miniaturized polymer enclosures for telecommunications infrastructure and handheld devices. Shenzhen and Dongguan molders drive specification complexity for 5G component cavities.
Automotive retains volume leadership. Electronics is gaining share fastest.
Material:
Silicone anchors margin concentration through thermal stability premiums and captive organosilicon feedstock control.
- Polyurethane:Reaction-injection molding releases for automotive fascia and seating components. Tier suppliers in Michigan and Ontario specify these for compatibility with paint-adhesion requirements.
- Silicone:Polydimethylsiloxane and fluorosilicone formulations spanning -50°C to 350°C service windows. Aerospace molders in Toulouse and Hamburg pay premiums for Shin-Etsu and Dow Corning qualified materials.
- Teflon:PTFE dispersions for extreme chemical inertness in semiconductor wafer handling fixtures. Taiwanese electronics foundries specify these for fluorocarbon purity standards.
- Wax:Carnauba, paraffin, and synthetic wax blends for low-temperature thermoplastics. Indian packaging processors in Maharashtra and Gujarat dominate consumption here.
Silicone holds specification authority. Polyurethane is rotating up the share rankings.
End User:
Manufacturer procurement is concentrating around integrated adhesive-release system suppliers, compressing standalone coating vendor access.
- Manufacturers:Tier-one and Tier-two molders operating captive tooling fleets. German automotive stampers consolidate spend with Henkel and 3M for bonded release-and-adhesive packages.
- Designers:Product development firms specifying release agents for prototype and bridge tooling. California and Massachusetts prototyping shops drive on-demand formulation customization.
- Contractors:Maintenance and repair organizations applying touch-up coatings in field conditions. Mexican maquiladora service providers expand with nearshoring tooling support contracts.
- Suppliers:Distributors and compounders serving fragmented processor bases. Korean trading houses in Seoul and Busan consolidate regional supply for electronics molders.
Manufacturers hold procurement volume. Designers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA NESHAP enforcement timelines and REACH Annex XVII compliance windows are redrawing procurement geography for mold release coatings, concentrating supply relationships in jurisdictions with aligned regulatory calendars.
United States
Automotive stamping plants in Michigan and Ohio face compressed vendor recertification cycles under EPA NESHAP hazardous air pollutant standards. Tier-one suppliers consolidate approved lists around compounders with documented environmental management systems. Detroit-area tool shops drive specification shifts toward aqueous formulations as shop-floor VOC limits tighten quarterly.
Germany
Aerospace turbine blade molders in Hamburg and Munich specify fluorosilicone hybrid release coatings for thermal cycling above 300°C. REACH Annex XVII perfluorinated compound restrictions accelerate 18-month reformulation timelines across Bavarian and North Rhine-Westphalian manufacturing clusters. Stuttgart automotive stampers unbundle standalone release contracts in favor of adhesive system integrators.
China
Electronics contract manufacturers in Shenzhen and Dongguan multiply cavity complexity specifications for 5G infrastructure enclosures. MEE enforcement of GB industrial emission standards tightens production permits for solvent-based release agents in Guangdong and Jiangsu provinces. Domestic mold-making capacity expansion concentrates demand for high-temperature silicone formulations.
Japan
Packaging molders in Osaka and Nagoya specify hot melt release systems to eliminate solvent recovery equipment. METI industrial emissions guidelines align with corporate sustainability reporting requirements for Tier suppliers. Chubu region automotive clusters consolidate procurement around integrated release-and-bonding solution providers.
France
Aerospace composite layup tooling operations in Toulouse retain solvent-based specifications where thermal shock resistance exceeds aqueous chemistry limits. ANSM chemical substance notifications intersect with REACH compliance timelines for European market access. Occitanie region suppliers face tooling recertification costs that favor larger registrants with dedicated regulatory affairs functions.
Mold Release Coatings Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology and regulatory certification capabilities, producing a tiered structure where scale-driven compounders hold automotive OEM relationships and boutique operators serve prototyping shops. Three archetypes dominate: multinational chemical conglomerates with captive feedstock control, regional specialists with ISO 14001 documentation, and application-specific formulators serving electronics miniaturization requirements. Competitive moves concentrate on backward integration into organosilicon precursors and strategic partnerships with adhesive system integrators.
Within the multinational tier, Daikin Industries Ltd exemplifies fluoropolymer synthesis capability, while Wacker Chemie AG anchors European silicone chemistry leadership. Shin-Etsu Chemical Co., Ltd represents the archetype of captive organosilicon feedstock control through precision polymerization operations.
| Leading Market Players |
|---|
| Daikin Industries Ltd |
| Chem-Trend L.P. |
| Henkel AG & Co. KGaA |
| McGee Industries, Inc. |
| Michelman Inc. |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd |
| Chukyo Yushi Co., Ltd |
| Croda International Plc |
| Others |
Supply & Pricing Matrix
ISO 14001 certification gates supplier qualification and price differentiation simultaneously, forcing automotive OEMs to pay premiums for documented environmental management while excluding smaller compounders from approved vendor lists entirely. Aqueous formulation investments and REACH compliance documentation compress margin pools for uncertified competitors.
Pricing Analysis
Certification level (ISO 14001/REACH-compliant) creates the primary spread between premium silicone compounders and commodity wax blenders. Contract-based long-term offtake dominates automotive procurement, with volume scale and thermal stability grade as secondary differentiation drivers. Cost compression in solvent-based tiers is intensifying because EPA NESHAP compliance extends reformulation cycles. Contract manufacturers in Guangdong province exhibit highest price sensitivity; aerospace turbine blade molders in Hamburg and Toulouse show lowest.
Supply Chain Analysis
China and Japan anchor organosilicon precursor production, with Germany retaining fluoropolymer synthesis capability. Polydimethylsiloxane feedstock, fluorosilicone intermediates, and specialized wax blends draw from petrochemical complexes concentrated in Asian manufacturing hubs. Single-source vulnerability runs through Shin-Etsu and Dow Corning captive production of high-purity silicone precursors. Distribution runs through adhesive system integrators in German and Japanese automotive clusters, bypassing standalone release agent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorosilicone hybrid synthesis capability represents the critical scarcity asset, separating qualified aerospace suppliers from standard silicone compounders locked out of turbine blade specifications. Mastery of precision polymerization at temperatures exceeding 300°C gates access to margin-rich thermoset compression molding contracts.
For Market Incumbents: Secure backward integration into organosilicon feedstock to defend against Asian petrochemical complex supply disruptions. Deepen fluoropolymer synthesis investments to maintain aerospace qualification advantages as REACH Annex XVII restrictions accelerate. Lock in long-term offtake contracts with German and Japanese automotive OEMs consolidating around integrated release-and-bonding solutions. For New Entrants and Emerging Players: Anchor in aqueous formulation technology for Chinese electronics molders facing MEE enforcement of GB industrial emission standards. Target Shenzhen and Dongguan contract manufacturers multiplying cavity complexity for 5G infrastructure enclosures. Lead with on-demand customization capabilities for California and Massachusetts prototyping shops seeking rapid formulation turnaround. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fluorosilicone hybrid production lines as precision polymerization equipment requirements escalate. Long-term viability favors compounders with captive feedstock control and documented regulatory affairs functions over distribution-dependent traders. Watch for consolidation signals when tooling recertification costs force smaller REACH registrants toward distressed sale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organosilicon Feedstock | Captive polydimethylsiloxane supply insulates against Asian petrochemical price volatility and supply disruption. |
| Fluorosilicone Hybrid Capacity Expansion | Qualified materials for aerospace turbine blade molding above 300°C capture thermal stability premiums. |
| REACH Annex XVII Compliance Documentation | Documented reformulation timelines secure automotive OEM approved vendor status in European manufacturing clusters. |
| Integrated Release-and-Bonding System Partnerships | Henkel-style cross-selling capabilities align procurement consolidation trends in German automotive stamping. |
| Digital Formulation Platform Development | AI-driven rheology prediction serves California prototyping shops demanding on-demand customization. |
Research Methodology
Cross-validation between regulatory filing analysis and supply chain documentation anchors the qualitative findings across this study. Primary interviews with plant managers at automotive stamping operations, procurement leads at Tier 1 aerospace suppliers, distribution channel partners in Asian electronics manufacturing hubs, and technical R&D directors at silicone compounders combined with secondary validation from EPA NESHAP enforcement records, ECHA REACH registration databases, customs and trade flow data, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up demand modeling and top-down supply capacity assessment triangulate volume estimates.
Sensitivity analysis across thermal stability grade tiers, end-use industry concentration, and regional regulatory enforcement intensity frames the projection horizon. Segmentation dimensions modeled include product chemistry, application environment, material thermal ceiling, and end-user procurement channel access. CAGRs derive from installed capacity expansion rates correlated with OEM tooling recertification cycles. Forecast inputs incorporate MEE enforcement trajectory for Chinese electronics molders and REACH Annex XVII compliance window timing.
Decision-makers should treat outputs as directional under sustained EPA, REACH, and MEE enforcement calendars; material deviation in regulatory timelines or feedstock supply disruption would warrant model refresh. Recalibration cycles align with material shifts in aerospace platform qualification schedules and automotive OEM vendor consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Polyester Coatings Market
Coatings
Fillers and Coating Market
Coatings
Ethylene Tetrafluoroethylene (ETFE) Coatings Market
Coatings
France Protective Coatings Market
Coatings
Polysiloxane Coatings Market
Coatings
Flexible Waterproof Coating Market
Coatings
2K Protective Coatings Market
Coatings
North America Concrete Floor Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
Global Heat Resistant Coatings Market
Coatings
Biopolymer Coatings Market
Coatings
Germany Protective Coatings Market
Coatings
2K Coatings Market
Coatings
Thermal Barrier Coatings Market
Coatings
Nigeria Protective Coatings Market
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market