
 North America Intraocular Lens Market | 2026-2036
North America Intraocular Lens Market Size, Share, and Industry Trends Forecast 2026-2036
North America Intraocular Lens Market Analytics
Ambulatory surgical center procurement is rewriting how premium intraocular lenses reach patients across North America. Alcon leverages its direct-to-facility logistics network to sustain high fill rates for toric and multifocal platforms. Johnson & Johnson competes through specialized training ecosystems that anchor surgeon loyalty in premium channel segments.
An intraocular lens is a biocompatible optical implant, typically measuring six millimeters in diameter with an optic zone between five and six millimeters, designed to replace the eye's natural crystalline lens after cataract extraction or refractive lens exchange. Monofocal lenses dominate procedure volume due to established reimbursement pathways, while toric and multifocal platforms capture disproportionate margin pools from out-of-pocket patient payments. Hydrophobic acrylic materials lead material preference for posterior chamber fixation given their controlled unfolding kinetics and low posterior capsular opacification rates.
FDA premarket notification and PMA pathways govern commercial entry, while CMS national coverage determinations and HCPCS coding directly shape physician adoption economics for advanced technology IOL categories. Health Canada and ISO 11979 biocompatibility standards impose additional design validation requirements for cross-border manufacturers. Stakeholders must monitor CMS physician fee schedule negotiations and state-level certificate-of-need regulations for ambulatory surgery centers as these mechanisms determine site-of-service expansion and premium lens penetration trajectories.
Market Dynamics
CMS reimbursement coding revisions for advanced technology intraocular lenses are compressing commercialization timelines and forcing manufacturers to front-load clinical evidence generation before market entry.
Growth Catalysts
- HCPCS Coding Expansion:CMS quarterly coding updates for presbyopia-correcting and toric platforms expand patient out-of-pocket thresholds, unlocking premium lens penetration in ambulatory surgical centers across the United States.
- Hydrophobic Acrylic Material Science:Controlled unfolding kinetics and sub-10% posterior capsular opacification rates drive surgeon preference toward posterior chamber fixation platforms with enhanced long-term visual stability.
- Southeastern United States Demographics:High-density retirement corridors in Florida and Arizona concentrate cataract procedure volume, creating predictable demand pull for multifocal and extended depth-of-focus inventory.
Market Restraints
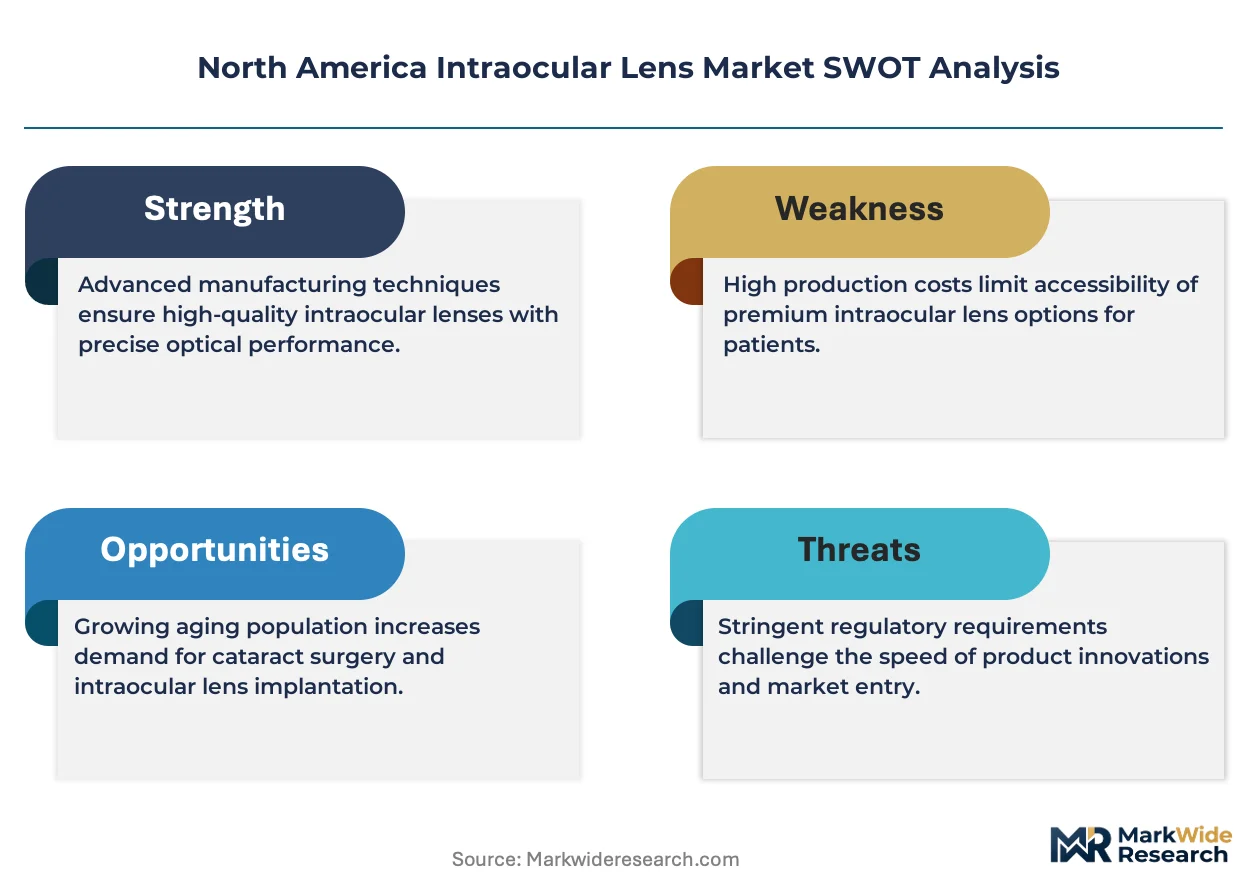
- FDA PMA Timeline Compression:Premarket approval pathways for novel optical designs extend validation cycles to 24-36 months, straining R&D amortization against finite patent windows.
- Acrylic Monomer Supply Concentration:Hydrophobic acrylic precursor manufacturing clusters in Germany and Japan expose North American lens fabricators to transoceanic logistics volatility and currency hedge complexity.
- Monofocal Reimbursement Anchoring:Established Medicare fee schedules for standard single-vision implants create price ceilings that suppress premium platform penetration in safety-net patient populations.
Strategic Opportunities
- Canadian Provincial Expansion:Ontario and British Columbia are revising ophthalmic device procurement frameworks to include presbyopia-correcting categories previously excluded from public formulary coverage.
- Light-Adjustable Lens Convergence:Post-implant UV photo-adjustment technology intersects with wavefront-guided customization, enabling refractive fine-tuning without explantation risk.
- Direct-to-Facility Distribution:Ambulatory surgical center consignment inventory models eliminate distributor markups and accelerate case-by-case lens matching to surgeon preference cards.
Industry Challenges
- Corneal Topography Skill Deficit:Accurate toric IOL axis alignment demands anterior segment imaging proficiency that cataract surgeons in smaller metropolitan markets struggle to maintain without dedicated technicians.
- ISO 11979 Biocompatibility Recertification:Material formulation changes trigger full cytotoxicity and implantation study repetition, delaying design iterations by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Intraocular Lens Market |
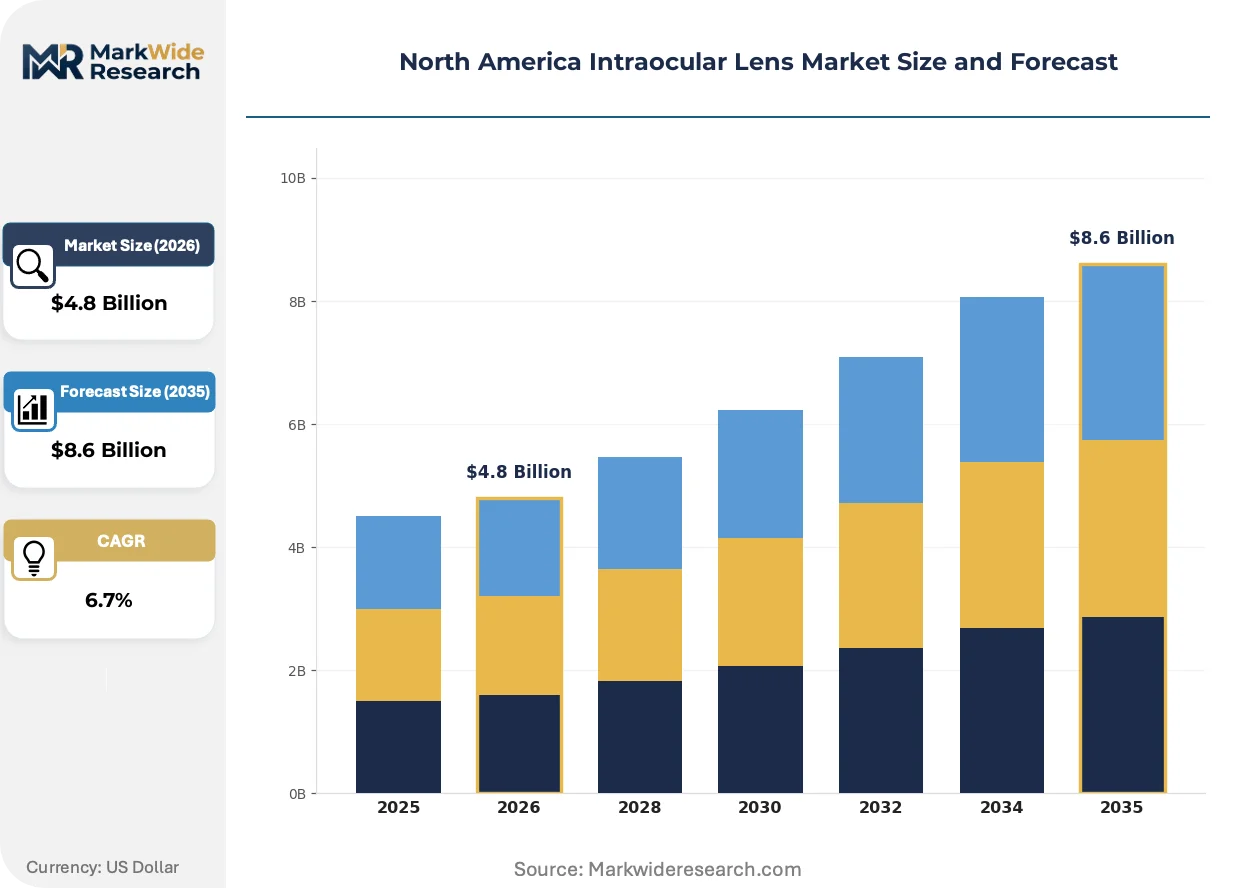
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monofocal, Multifocal, Toric, Accommodative End User: Hospitals, Clinics, Ambulatory Surgical Centers, Ophthalmology Practices Material: Polymethyl Methacrylate, Silicone, Hydrophilic Acrylic, Hydrophobic Acrylic Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Pharmacies |
| Companies Covered | Alcon, Carl Zeiss Meditec AG, Bausch Health Companies Inc., Johnson & Johnson, HOYA Corporation, STAAR Surgical, EyeKon Medical, Rayner, Lenstec, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Intraocular Lens Market Evolving Landscape
Optical customization technologies are collapsing the boundary between refractive surgery and cataract replacement, forcing lens manufacturers to compete on visual performance metrics previously dominated by LASIK platforms.
Extended depth-of-focus optical profiles are collapsing the historical trade-off between near and distance acuity. Ambulatory surgical centers in Texas and California are adopting these platforms at twice the rate of hospital-based ophthalmology departments. The technology is collapsing residual spectacle dependence rates to under 15% for bilateral implantations, compressing patient-reported dissatisfaction metrics that previously plagued multifocal predecessors.
FDA 510(k) clearance pathway modifications for presbyopia-correcting indications are accelerating comparative effectiveness requirements. Manufacturers must now submit head-to-head defocus curve data against predicate devices, elevating clinical trial costs. Toric extended depth-of-focus hybrids face the steepest evidentiary burden, with FDA demanding astigmatic stability data across 12-month postoperative windows.
Patient out-of-pocket contribution tolerance is reshaping site-of-service selection. High-deductible health plan enrollees in the United States are migrating toward independent ambulatory surgical centers that transparently bundle facility and professional fees. This concentration is most pronounced in Georgia and North Carolina, where certificate-of-need restrictions on hospital outpatient department expansion have channeled volume toward freestanding facilities with leaner cost structures.
North America Intraocular Lens Market Segmentation
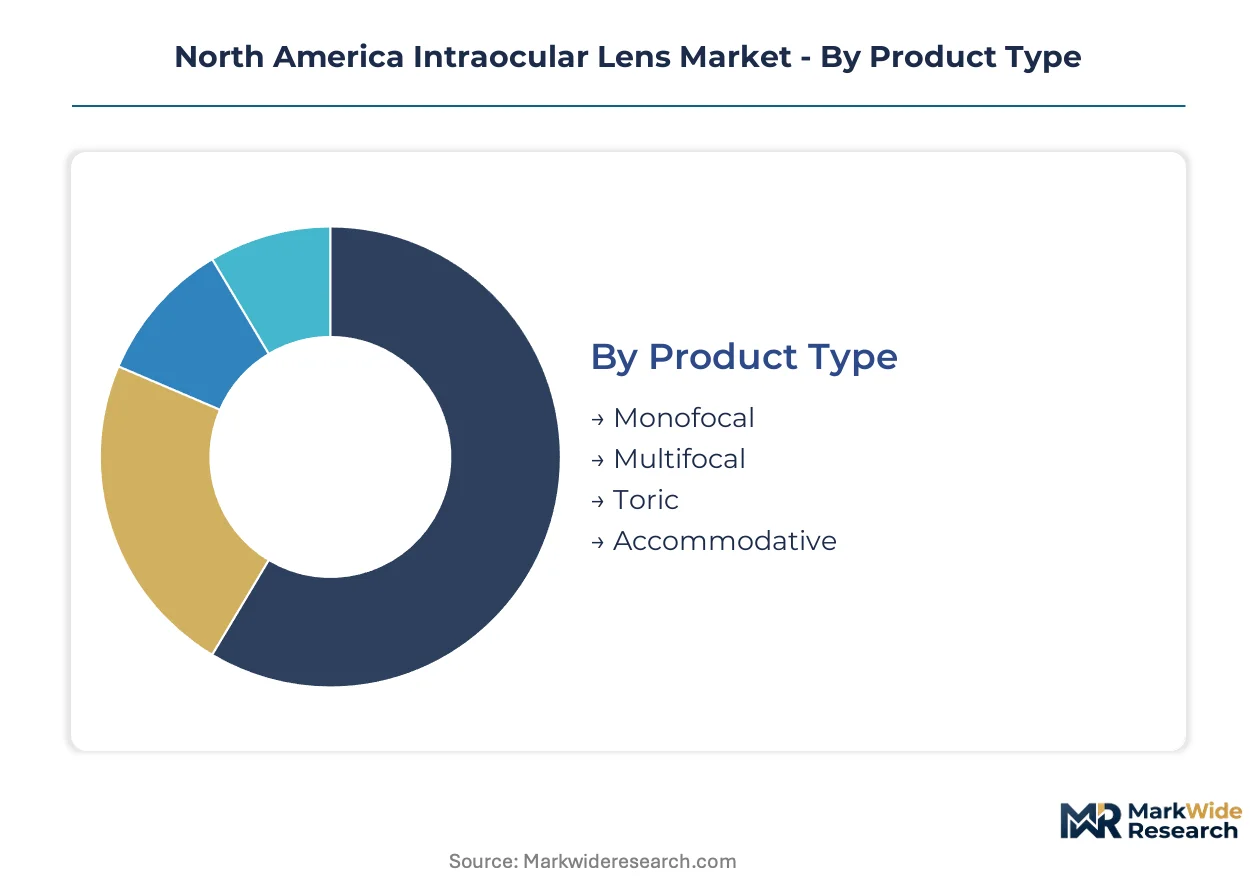
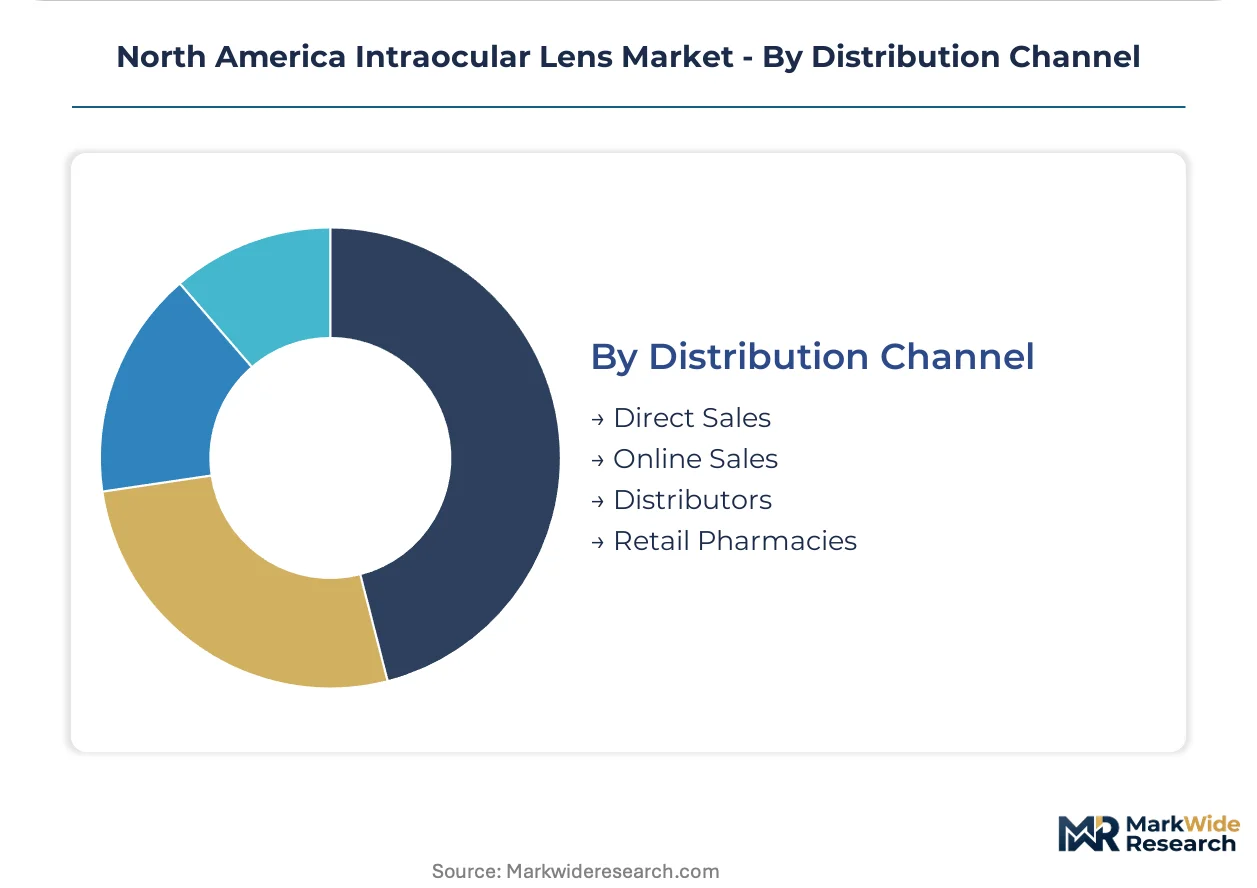
Intraocular lens procurement patterns diverge sharply across clinical settings and payment models, forcing manufacturers to maintain parallel supply configurations. Understanding these segment boundaries clarifies where premium platform investments yield returns versus where commodity logistics dominate.
Product Type:
Use-case spectrum spans vision correction goals from basic distance acuity restoration to full spectacle independence across all focal distances.
- Monofocal:Single-focus optical design delivering distance vision correction with minimal optical aberration. Medicare reimbursement fully covers standard monofocal implants, concentrating volume in safety-net populations across Texas, Florida, and Arizona retirement corridors where out-of-pocket tolerance remains constrained.
- Multifocal:Diffractive optic technology splitting light across multiple focal planes to address presbyopia. Demand concentrates in ambulatory surgical centers serving high-deductible health plan enrollees in Georgia and North Carolina, where bundled pricing transparency drives patient self-selection toward premium platforms despite co-payment requirements.
- Toric:Cylindrical power correction for pre-existing corneal astigmatism integrated into monofocal or multifocal platforms.
- Accommodative:Hinge-based designs attempting to mimic natural lens focusing through ciliary muscle engagement.
Established volume favors monofocal; emerging adoption favors multifocal.
End User:
Site-of-service economics create distinct procurement rhythms based on facility scale and case-mix complexity.
- Hospitals:Integrated health systems with ophthalmology departments managing complex comorbidities and combined procedures. Volume concentrates in academic medical centers across the northeastern United States and California, where resident training programs and Medicaid safety-net obligations sustain monofocal-dominant case mixes despite lower per-procedure margins.
- Ambulatory Surgical Centers:Freestanding facilities optimized for high-throughput cataract workflows with transparent bundled pricing. Southeastern United States corridors in Florida and Arizona drive disproportionate premium lens penetration where retiree demographics and elective procedure self-selection align.
- Clinics:Office-based settings handling preoperative evaluation and postoperative follow-up rather than implantation.
- Ophthalmology Practices:Physician-owned entities combining clinical services with surgical scheduling coordination.
Institutional procurement favors hospitals; margin capture favors ambulatory surgical centers.
Material:
Biocompatibility profiles and mechanical handling characteristics govern surgeon preference and long-term complication rates.
- Hydrophobic Acrylic:Controlled unfolding kinetics and sub-10% posterior capsular opacification rates anchor surgeon preference for posterior chamber fixation. Demand concentrates in United States ambulatory surgical centers where long-term visual stability metrics support premium pricing justification and patient satisfaction guarantees.
- Silicone:Lower refractive index and reduced surface adhesion properties suited for specific anterior segment anatomies. Niche adoption persists in complex cases requiring sulcus fixation or combined vitreoretinal procedures, particularly within California and New York academic hospital networks managing trauma and uveitis cohorts.
- Polymethyl Methacrylate:Rigid legacy material with historical usage in developing-world cataract campaigns.
- Hydrophilic Acrylic:Higher water content enabling injection through smaller incisions but elevated posterior capsular opacification risk.
Performance metrics favor hydrophobic acrylic; cost minimization favors hydrophilic alternatives.
Distribution Channel:
Supply chain configuration determines working capital intensity and lens-matching responsiveness.
- Direct Sales:Manufacturer-to-facility relationships eliminating intermediary markups and enabling consignment inventory models. Alcon and Johnson & Johnson leverage dedicated logistics networks to sustain high fill rates for toric and multifocal platforms across high-volume ambulatory surgical center chains in Texas and Florida.
- Distributors:Regional intermediaries aggregating multiple manufacturer portfolios for smaller facilities. Concentration persists in rural ophthalmology practices across the Mountain West and Great Plains where case volumes fail to justify direct manufacturer relationships.
- Online Sales:Digital procurement platforms with limited penetration given implant traceability requirements.
- Retail Pharmacies:Minimal participation given prescription-only device classification and surgical implantation requirement.
Scale economics favor direct sales; fragmentation favors distributor intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium intraocular lens pricing in the United States commands a 40-60% premium over Canadian provincial procurement rates, creating divergent commercialization strategies across the border. This asymmetry shapes manufacturer resource allocation and site-of-service investment priorities throughout the analysis window.
United States
Medicare Advantage penetration in Florida and Arizona retirement corridors concentrates demand for multifocal and extended depth-of-focus platforms. FDA premarket approval pathways govern commercial entry timelines, while CMS quarterly HCPCS coding updates directly shape physician reimbursement economics. The southeastern United States, particularly Georgia and North Carolina, channels high-deductible health plan enrollees toward independent ambulatory surgical centers with transparent bundled pricing.
Canada
Ontario and British Columbia are revising ophthalmic device procurement frameworks to include presbyopia-correcting categories previously excluded from public formulary coverage. Health Canada and ISO 11979 biocompatibility standards impose additional design validation requirements for cross-border manufacturers. Quebec maintains distinct provincial reimbursement schedules that lag Ontario's premium lens adoption curve by 18-24 months.
Mexico
Private hospital networks in Mexico City and Monterrey drive demand for hydrophobic acrylic platforms among medical tourism cohorts seeking refractive outcomes comparable to United States standards. COFEPRIS regulatory pathways for imported ophthalmic devices require local clinical validation studies that extend commercialization timelines. The Bajío Region's manufacturing clusters supply hydrophilic acrylic precursors to North American lens fabricators.
North America Intraocular Lens Market Competitive Landscape
Diversified ophthalmic conglomerates and specialized intraocular lens manufacturers split the market across distinct capability vectors. Consolidation pressure intensifies as premium platform development costs escalate and patent windows compress. Three archetypes dominate: integrated surgical ecosystem providers, pure-play optical implant specialists, and regional fabrication houses with material science advantages. Competitive moves center on direct-to-facility distribution network expansion and surgeon training ecosystem anchoring.
Within the integrated surgical ecosystem tier, Alcon and Johnson & Johnson occupy positions defined by logistics scale and training infrastructure depth. Alcon leverages direct-to-facility consignment models across high-volume ambulatory surgical center chains. Johnson & Johnson competes through specialized training ecosystems that anchor surgeon loyalty. Carl Zeiss Meditec AG represents the precision-optical heritage archetype, with German engineering credibility supporting premium positioning in academic medical centers.
| Leading Market Players |
|---|
| Alcon |
| Carl Zeiss Meditec AG |
| Bausch Health Companies Inc. |
| Johnson & Johnson |
| HOYA Corporation |
| STAAR Surgical |
| EyeKon Medical |
| Rayner |
| Lenstec |
| Others |
Value Network & Pricing Analysis
Undercapacity in hydrophobic acrylic precursor manufacturing across Germany and Japan concentrates supplier leverage, forcing North American lens fabricators to absorb currency hedge volatility while defending premium platform margins through consignment inventory commitments.
Pricing Analysis
The customization-premium spread separates configured-to-order toric and multifocal platforms from standard monofocal implants. Three-tier pricing structure across premium, standard, and economy levels reflects FDA PMA certification status and surgeon training ecosystem depth as primary differentiation drivers. Pricing pressure stems from Medicare fee schedule anchoring for monofocal categories, compressing margin pools in safety-net populations. Ambulatory surgical centers serving high-deductible health plan enrollees exhibit lowest price sensitivity, while hospital outpatient departments managing Medicaid case mixes face acute cost compression.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk calculus for hydrophobic acrylic monomer flows. Manufacturing clusters in Germany, Japan, and the Bajío Region of Mexico anchor raw material dependencies, with acrylic monomer, UV-curable coatings, and precision-molding equipment constituting critical input categories. Single-source vulnerability in German precursor production threatens inventory continuity for premium platform fabricators. Distribution runs through direct-to-facility consignment models for high-volume ambulatory surgical center chains, with regional distributors serving fragmented rural practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where FDA PMA regulatory entrenchment and surgeon training ecosystem switching costs protect incumbent positions against rapid displacement.
For Market Incumbents: Insulate premium platform margins by deepening backward integration into hydrophobic acrylic precursor production and securing exclusive ambulatory surgical center consignment contracts. Emerging optical customization technologies from refractive surgery competitors threaten toric and multifocal category differentiation, demanding accelerated R&D investment in light-adjustable lens platforms. For New Entrants and Emerging Players: Canadian provincial underpenetration in presbyopia-correcting categories offers the most accessible white-space target, with Ontario and British Columbia procurement framework revisions enabling formulary inclusion previously blocked. Light-adjustable lens technology convergence with wavefront-guided customization represents the most penetrable application segment, with direct-to-facility distribution partnerships offering the clearest go-to-market angle against established logistics networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across extended depth-of-focus platform development, elevating barriers for sub-scale competitors. Acquisition targets should emphasize mid-tier manufacturers with Health Canada ISO 11979 certification infrastructure and established surgeon training relationships. The signal to monitor is CMS quarterly HCPCS coding updates for presbyopia-correcting categories, which would accelerate premium penetration trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | PMA validation cycles anchor competitive timelines and patent amortization economics. |
| CMS Reimbursement Strategy | HCPCS coding updates directly shape physician adoption economics for advanced technology categories. |
| Hospital System Partnership | Academic medical center alliances sustain resident training pipelines and complex case volume. |
| Backward Integration | Captive hydrophobic acrylic precursor production mitigates transoceanic logistics volatility. |
| Software Companion Development | Corneal topography integration platforms address toric alignment skill deficits in smaller markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA PMA submission databases, CMS HCPCS quarterly update records, and Health Canada device licensing registries. Primary interviews engaged cataract surgeons, ambulatory surgical center procurement directors, ophthalmic device regulatory affairs specialists, and GPO contracts managers. Secondary validation drew from hospital procurement databases, Medicare claims data, and ISO 11979 biocompatibility certification records. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Forecast inputs incorporate product type segmentation across monofocal, multifocal, toric, and accommodative platforms; end-user site-of-service economics spanning hospitals, ambulatory surgical centers, and ophthalmology practices; and material science differentiation between hydrophobic acrylic, silicone, and hydrophilic alternatives. CAGRs derived from regression analysis against demographic cataract incidence projections and premium lens penetration elasticity. Industry-specific inputs include Medicare Advantage enrollment trajectories and provincial formulary revision timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated refractive surgery platform competitors would shift outcomes. Material shifts in FDA 510(k) clearance pathway requirements for presbyopia-correcting indications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Uterine Fibroid Embolization Devices Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
North America Medical Device Regulatory Affairs Market
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Dissolving Microneedle Eye Patch Market
Medical Devices
Band Ligators Market
Medical Devices
Bone Power Tools Market
Medical Devices
Global Transcranial Magnetic Stimulators Market
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
US Medical Bionic Implants & Artificial Organs Market