
 Elbow Fixation Systems Market | 2026-2036
Elbow Fixation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Elbow Fixation Systems Market Foresight
Switzerland is reconfiguring its orthopedic device manufacturing footprint through precision machining clusters near Basel and Zurich. Arthrex leverages its arthroscopy-derived instrumentation expertise to anchor premium elbow plating portfolios in sports medicine channels. DePuy Synthes sustains broad hospital contracting power through integrated trauma sets that span distal humerus to proximal forearm constructs. Stryker Corporation competes on robotics-compatible fixation platforms that interface with its upper-extremity navigation systems.
Elbow fixation systems comprise implants and instruments designed to stabilize fractures, nonunions, and osteotomies of the distal humerus, proximal radius, and proximal ulna through mechanical rigidity and anatomical restoration, typically utilizing titanium alloy or stainless steel constructs with cortical and cancellous screw options manufactured via CNC milling and electron beam melting. These systems serve primarily to maintain reduction alignment, permit early mobilization, and prevent post-traumatic arthrosis in complex intra-articular and extra-articular elbow injuries. Internal fixators and bone plates command the dominant revenue share due to their biomechanical superiority in multi-fragmentary distal humerus fractures, while biodegradable polymers represent the fastest-expanding material segment as surgeons seek to eliminate hardware removal procedures in younger athletic populations. Surgical centers and orthopedic clinics are diverging in procurement patterns, with hospitals prioritizing comprehensive trauma sets and outpatient facilities selecting modular, procedure-specific configurations.
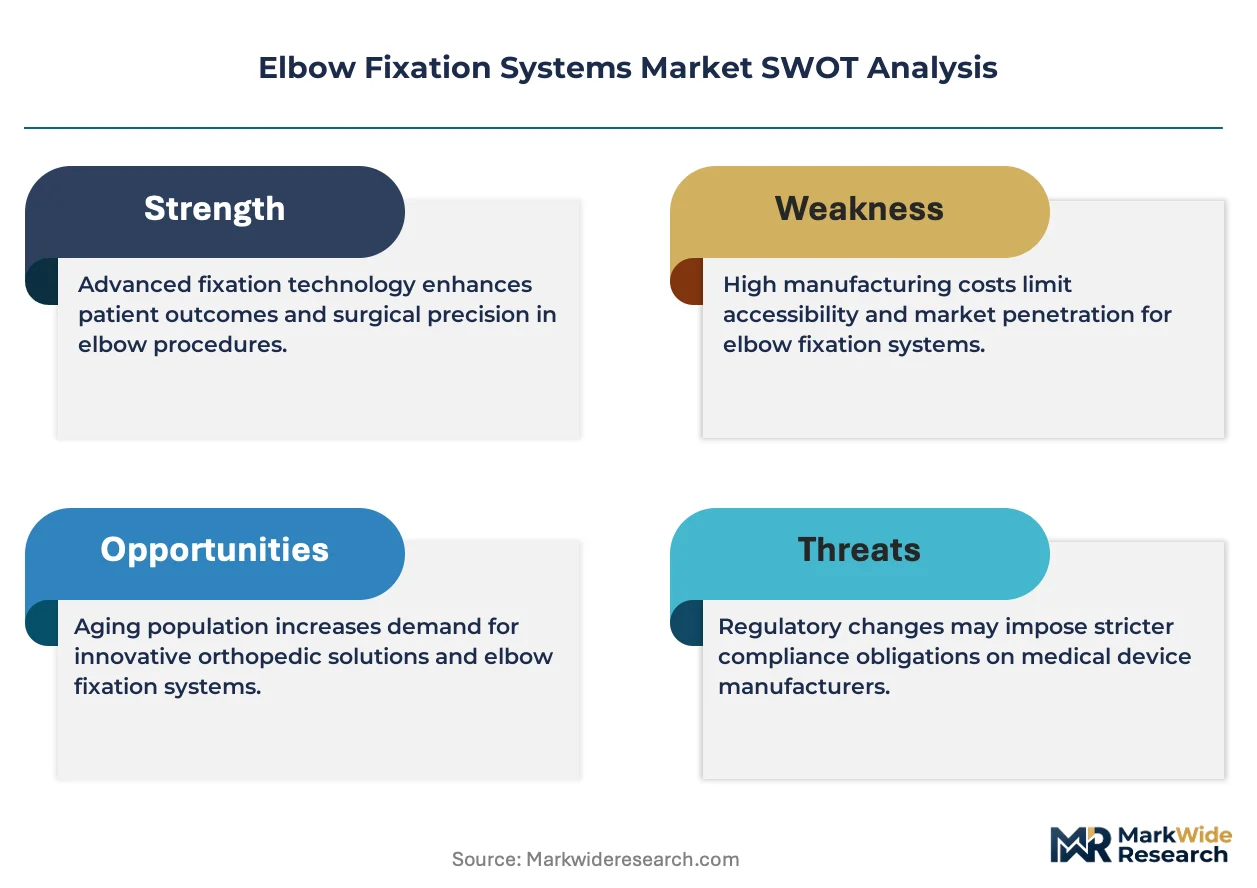
FDA 510(k) premarket notification requirements and ISO 13485 quality management standards govern device approval and manufacturing compliance for elbow fixation systems in the United States, while the EU Medical Device Regulation mandates clinical evaluation and post-market surveillance for CE-marked implants sold in European member states. These frameworks elevate barrier costs for new entrants but reinforce incumbent positions among manufacturers with established regulatory infrastructure and notified body relationships. Stakeholders must monitor evolving biomechanical evidence on locking plate fatigue performance and patient-reported outcome thresholds that increasingly influence hospital value-analysis committee purchasing decisions.
Market Dynamics
Trauma surgery units in tertiary hospitals are consolidating purchasing authority around anatomically contoured plating systems, compressing vendor selection cycles and elevating biomechanical performance thresholds as the primary procurement criterion.
Growth Catalysts
- Biodegradable polymer fixation:Younger athletic populations in Germany and Switzerland are driving surgeon preference for magnesium-based and polylactic acid constructs that eliminate secondary hardware removal procedures.
- FDA 510(k) pathway streamlining:Class II orthopedic device clearances are accelerating commercial entry for novel construct designs, reducing time-to-revenue for innovative plating geometries.
- Ambulatory surgical center expansion:United States outpatient facilities are building dedicated upper-extremity procedure capacity, creating new demand nodes for modular fixation configurations.
Market Restraints
- Titanium alloy price volatility:Raw material input costs for Ti-6Al-4V ELI remain exposed to aerospace sector demand fluctuations and Russian supply chain disruptions.
- Precision machining concentration:Swiss and German CNC milling clusters control critical manufacturing capacity for anatomically contoured plates, creating single-source vulnerability.
- CE marking timeline extension:EU Medical Device Regulation clinical evaluation requirements are extending approval cycles by 12-18 months for novel implant geometries.
Strategic Opportunities
- India trauma infrastructure buildout:Government hospital networks under the Ayushman Bharat scheme are establishing dedicated orthopedic trauma units in tier-2 cities with unmet fixation device access.
- Robotics-compatible platform convergence:Navigation-enabled plating systems that interface with surgical planning software are opening premium positioning in academic medical centers.
- Modular instrument leasing models:Outpatient surgical centers are adopting procedure-specific tray rentals to reduce capital deployment and sterilization infrastructure requirements.
Industry Challenges
- Locking screw torque specification standardization:Variability across manufacturer drive systems creates operative workflow friction and inventory complexity for hospital sterile processing departments.
- Post-market surveillance data collection:MDR-mandated implant registries require costly longitudinal patient tracking infrastructure that mid-tier manufacturers struggle to operationalize.
- Biomechanical fatigue testing capacity:Validating locking plate performance under cyclic loading demands specialized equipment that contract research organizations in Basel and Zurich command at premium rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elbow Fixation Systems Market |
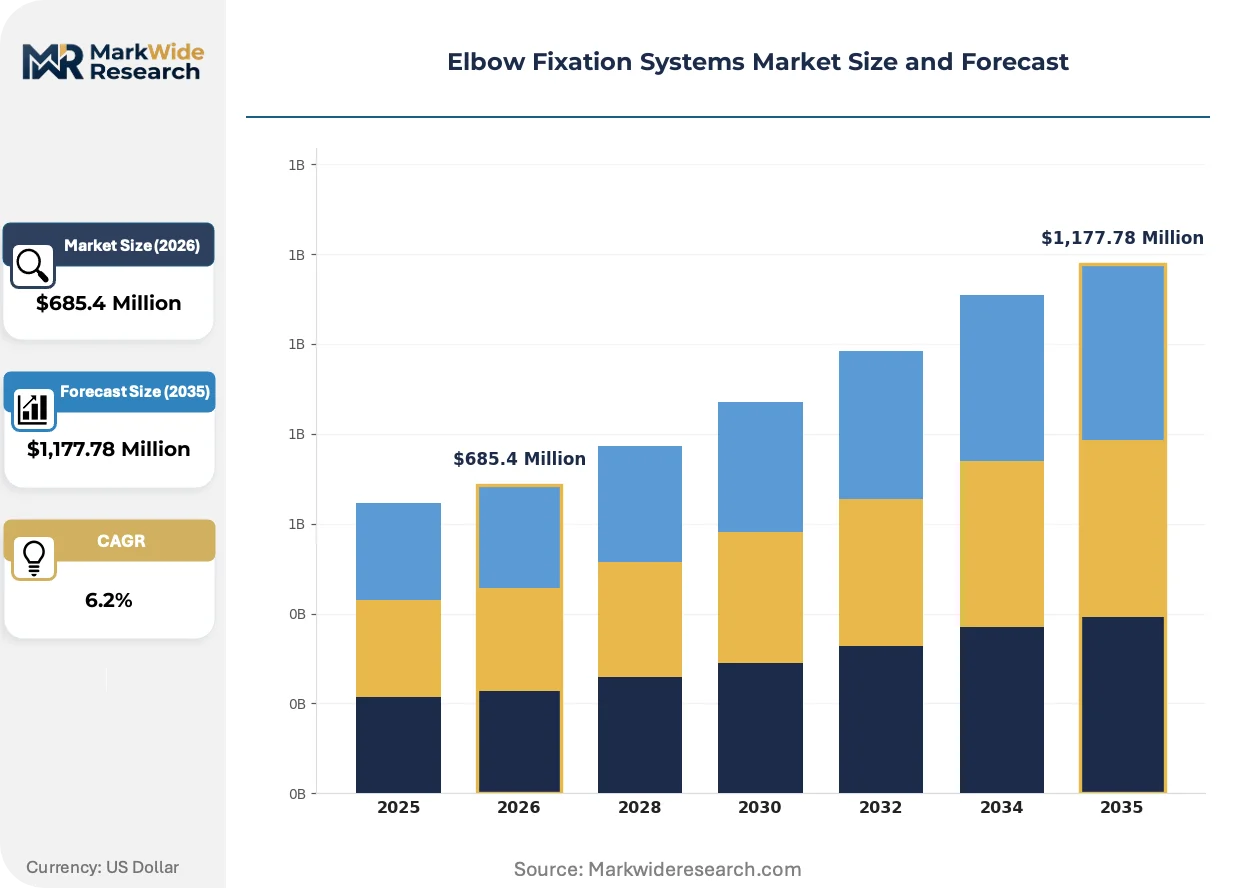
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Fixators, Internal Fixators, Bone Plates, Screws Customer Type: Surgical Centers, Hospitals, Rehabilitation Clinics, Orthopedic Clinics End User: Orthopedic Surgeons, Trauma Surgeons, Sports Medicine Specialists, General Practitioners Material: Stainless Steel, Titanium Alloys, Biodegradable Polymers, Carbon Fiber |
| Companies Covered | Arthrex, Acumed, DePuy Synthes, Orthofix Medical Inc., Wright Medical Group, Zimmer Biomet, Smith & Nephew, Response Ortho, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elbow Fixation Systems Market Shifts & Advancements
Digital surgical planning tools and patient-specific instrumentation are compressing operative time requirements and reshaping how trauma surgeons approach complex intra-articular fracture patterns.
Patient-specific 3D-printed titanium guides are virtualizing preoperative planning workflows by translating CT datasets into sterilizable drilling templates that eliminate intraoperative fluoroscopy dependence. Academic trauma centers in the United States and Switzerland are adopting these platforms for complex distal humerus reconstructions. The technology is virtualizing traditional freehand reduction techniques and compressing learning curves for fellowship-trained surgeons.
EU Medical Device Regulation post-market clinical follow-up requirements are mandating systematic implant performance tracking across CE-marked elbow fixation portfolios. Manufacturers must now maintain active surveillance systems that capture revision rates and patient-reported outcomes. Small-to-mid-tier device firms without established clinical affairs infrastructure face disproportionate compliance cost burdens relative to incumbent trauma set suppliers.
Ambulatory surgical centers are unbundling comprehensive trauma sets in favor of procedure-specific instrument configurations delivered through consignment inventory models. United States outpatient facilities now represent the fastest-growing channel for distal radius and olecranon fracture fixation hardware. This channel compression is forcing traditional hospital-contracting manufacturers to develop modular pricing architectures that align with case-volume variability in non-admitting settings.
Elbow Fixation Systems Market Segmentation
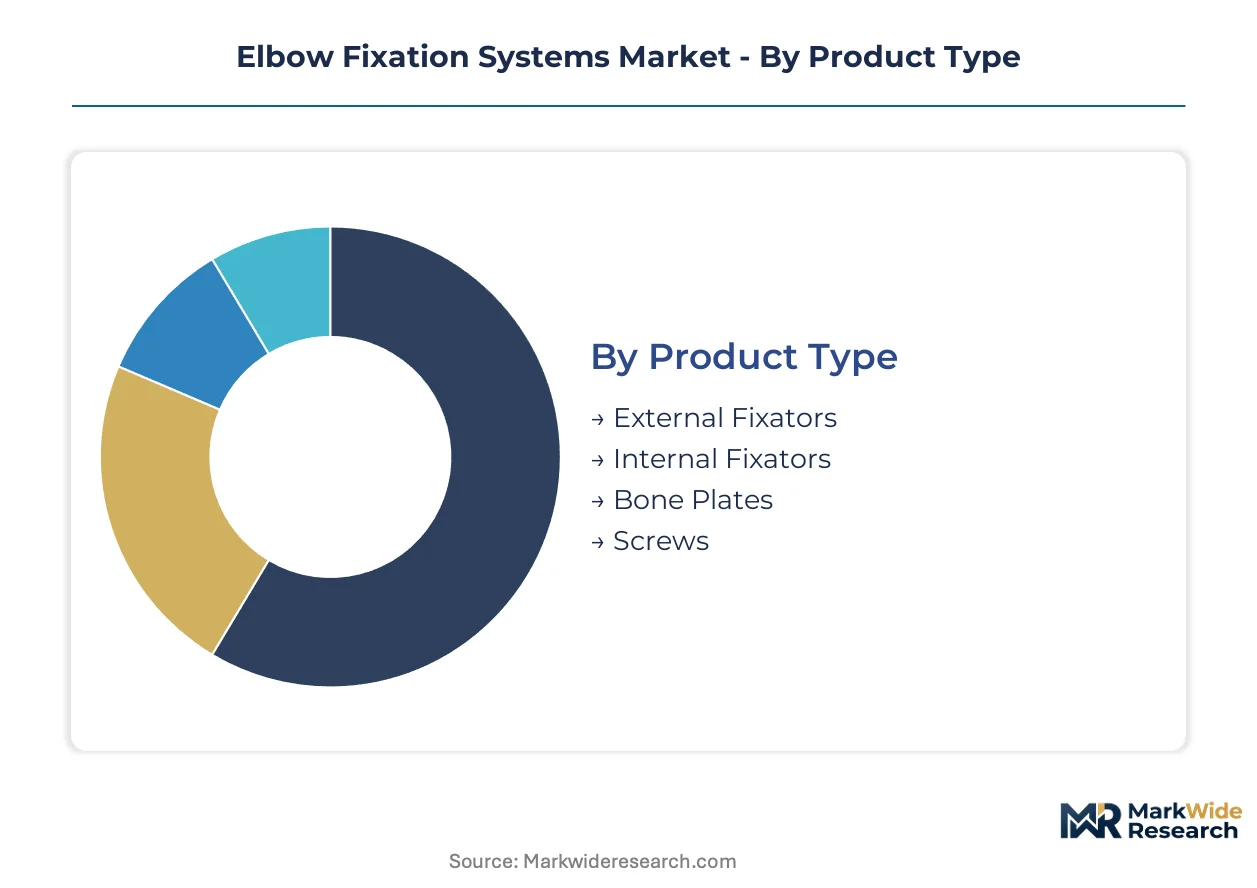
Elbow fixation systems segment across multiple dimensions that directly shape procurement velocity, pricing power, and inventory turnover. Product type and material composition drive the longest replacement cycles, while customer type and end-user specialization determine how quickly novel constructs penetrate clinical practice.
Product Type:
Cycle times vary dramatically—external fixators turn over in days for acute trauma, while internal plates remain implanted for years, creating divergent revenue recognition patterns across manufacturer portfolios.
- Internal Fixators:Titanium and stainless steel constructs provide rigid stabilization for complex distal humerus fractures through intramedullary nails and compression screws. Tertiary hospital trauma units in the United States concentrate procurement around these systems for multi-fragmentary injuries, though titanium alloy price volatility from aerospace sector competition constrains margin expansion.
- Bone Plates:Anatomically contoured locking plates deliver biomechanical superiority in olecranon and coronoid process fractures via pre-contoured geometries matched to patient anatomy. Swiss precision machining clusters near Basel and Zurich control critical manufacturing capacity for these devices, creating single-source vulnerability that extends lead times during supply disruptions.
- External Fixators:Modular pin-bar configurations enable temporary stabilization for open fractures and severe soft-tissue compromise.
- Screws:Cortical and cancellous screw options complete construct assemblies with variable pitch and self-tapping designs.
Internal fixators anchor the volume base while biodegradable polymer-compatible screw systems gain share at the steepest rate.
Customer Type:
Procurement authority fragments across facility types with diverging capital deployment models—hospitals prioritize comprehensive trauma sets, while outpatient channels favor modular, procedure-specific configurations.
- Hospitals:Tertiary trauma centers consolidate purchasing around integrated plating systems spanning distal humerus to proximal forearm constructs. United States hospital value-analysis committees now elevate biomechanical fatigue performance and patient-reported outcome thresholds as primary selection criteria, compressing vendor selection cycles.
- Surgical Centers:Ambulatory facilities in the United States are building dedicated upper-extremity procedure capacity and unbundling comprehensive sets in favor of consignment inventory models. Modular instrument leasing arrangements reduce capital deployment and sterilization infrastructure requirements, though locking screw torque specification variability across manufacturers creates operative workflow friction.
- Orthopedic Clinics:Specialist practices select procedure-specific configurations for outpatient fracture management.
- Rehabilitation Clinics:Post-operative monitoring sites influence hardware removal timing and secondary procedure scheduling.
Hospitals dominate absolute revenue contribution while surgical centers expand most quickly as site-of-care migration accelerates.
End User:
Specialist training depth determines adoption velocity for patient-specific instrumentation and navigation-enabled platforms, with fellowship-trained surgeons driving premium construct uptake.
- Orthopedic Surgeons:Fellowship-trained specialists in academic medical centers drive adoption of patient-specific 3D-printed titanium guides and robotics-compatible fixation platforms. Digital surgical planning tools compress operative time for complex intra-articular reconstructions, virtualizing traditional freehand reduction techniques.
- Trauma Surgeons:Emergency department specialists prioritize rapid construct assembly and standardized instrument configurations for polytrauma scenarios.
- Sports Medicine Specialists:Athletic injury focus creates preference for biodegradable polymer constructs in younger patient populations.
- General Practitioners:Primary care referral patterns influence initial fracture stabilization decisions and specialist handoff timing.
Orthopedic surgeons command the highest per-case construct value while trauma surgeons generate the greatest procedure volume.
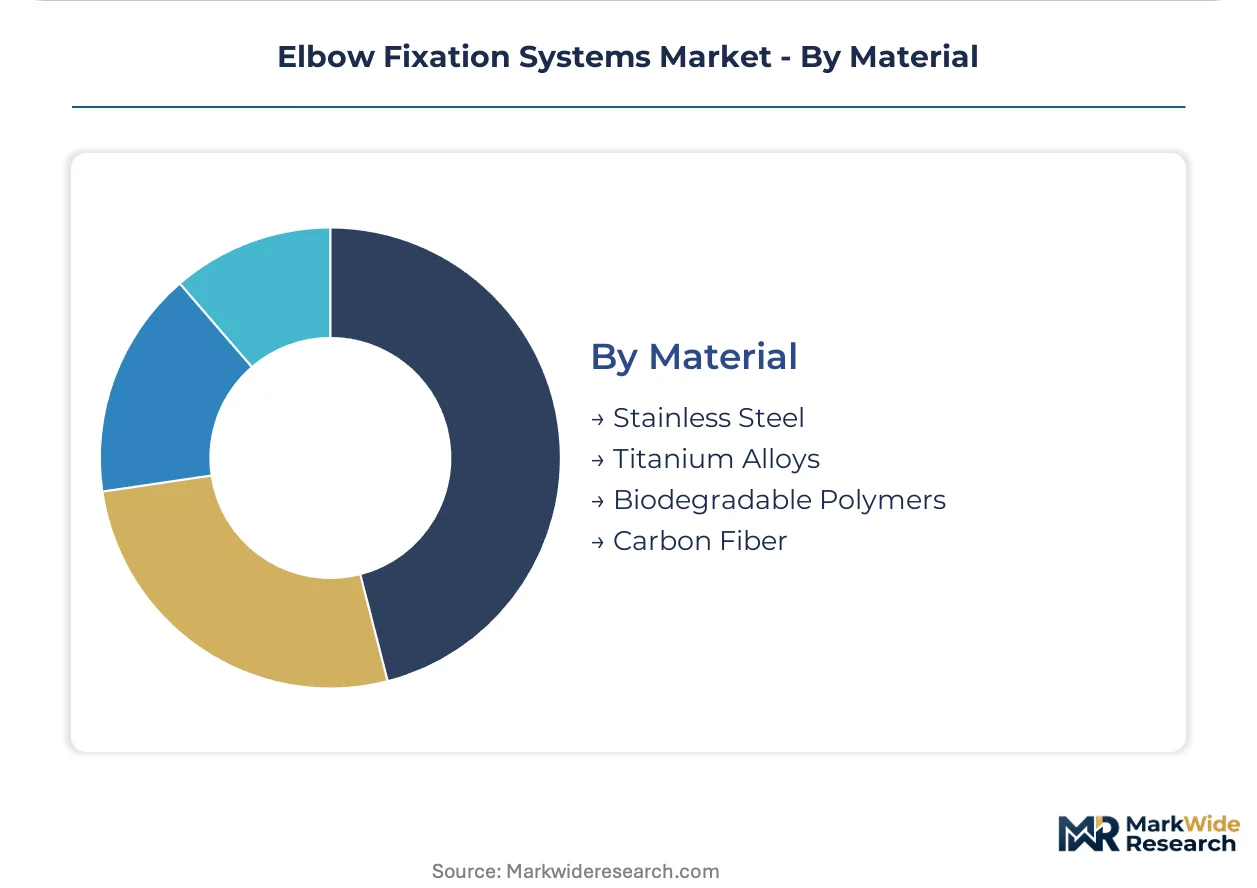
Material:
Material selection balances mechanical performance against biological interaction, with metallic systems dominating load-bearing applications and absorbable alternatives eliminating secondary removal procedures.
- Titanium Alloys:Ti-6Al-4V ELI delivers strength-to-weight superiority and magnetic resonance imaging compatibility for long-term implantation. Raw material input costs remain exposed to Russian supply chain disruptions and aerospace sector demand fluctuations, constraining pricing flexibility for manufacturers dependent on spot market procurement.
- Biodegradable Polymers:Magnesium-based and polylactic acid constructs eliminate hardware removal procedures in younger athletic populations. Germany and Switzerland demonstrate the strongest surgeon preference for these materials, though fatigue performance under cyclic loading requires specialized validation equipment that contract research organizations command at premium rates.
- Stainless Steel:Cost-effective alternative for temporary fixation and resource-constrained settings.
- Carbon Fiber:Radiolucent properties enable improved intraoperative imaging visualization.
Titanium alloys anchor the volume base while biodegradable polymers climb the fastest as elimination of secondary procedures drives surgeon preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss and German precision machining clusters control critical manufacturing capacity for anatomically contoured elbow plates, while demand concentrates in the United States where ambulatory surgical centers expand upper-extremity procedure capacity.
United States
FDA 510(k) clearance pathways accelerate commercial entry for novel construct designs, reducing time-to-revenue for innovative plating geometries. The IRA's hospital price transparency mandates pressure value-analysis committees to elevate biomechanical performance thresholds as primary procurement criteria. Tertiary trauma centers in Texas and Florida are consolidating purchasing authority around integrated trauma sets.
Germany
Younger athletic populations drive surgeon preference for magnesium-based and polylactic acid constructs that eliminate secondary hardware removal procedures. The BfArM maintains stringent post-market surveillance requirements under EU MDR implementation timelines. CNC milling clusters in Baden-Württemberg and Bavaria command premium rates for fatigue testing validation equipment.
Switzerland
Precision machining expertise near Basel and Zurich anchors European manufacturing capacity for anatomically contoured locking plates. Swissmedic mandates rigorous clinical evaluation documentation for CE-marked implants, extending approval cycles for novel geometries. The Basel-region industrial corridor specializes in electron beam melting production for patient-specific titanium constructs.
India
Government hospital networks under the Ayushman Bharat scheme establish dedicated orthopedic trauma units in tier-2 cities with unmet fixation device access. CDSCO regulatory pathways for Class II orthopedic devices streamline import substitution for domestic manufacturers. Maharashtra and Gujarat host emerging machining capacity serving regional demand.
China
NMPA innovation pathways for domestically manufactured trauma implants accelerate local production scale-up. Provincial hospital procurement reforms under volume-based purchasing compress vendor margins while expanding access to distal humerus plating systems. The Yangtze River Delta concentrates precision manufacturing infrastructure for titanium alloy processing.
Elbow Fixation Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in precision machining and materials supply. The vendor base organizes around three strategic archetypes: diversified trauma set suppliers with broad hospital contracting power, arthroscopy-derived instrumentation specialists leveraging sports medicine channels, and robotics-compatible platform developers integrating navigation software. Dominant competitive moves include modular instrument leasing arrangements for outpatient surgical centers and patient-specific 3D-printed guide development for academic medical centers.
Among diversified platform suppliers, DePuy Synthes and Stryker Corporation exemplify integrated trauma set strategies spanning distal humerus to proximal forearm constructs. Arthrex occupies a position within the arthroscopy-derived instrumentation tier, leveraging sports medicine channel expertise. These three companies represent distinct competitive positioning vectors: comprehensive hospital contracting, robotics-compatible navigation integration, and premium sports medicine anchoring respectively.
| Leading Market Players |
|---|
| Arthrex |
| Acumed |
| DePuy Synthes |
| Orthofix Medical Inc. |
| Wright Medical Group |
| Zimmer Biomet |
| Smith & Nephew |
| Response Ortho |
| Stryker Corporation |
| Others |
Supply & Pricing Matrix
Ti-6Al-4V ELI titanium alloy price volatility from aerospace sector demand competition and Russian supply chain disruptions determines both the premium-to-economy tier spread in plating systems and the geographic clustering of precision machining capacity around Swiss and German industrial corridors.
Pricing Analysis
FDA 510(k) clearance pathways dictate the pricing tier structure across elbow fixation portfolios, separating robotics-compatible navigation-integrated platforms from standard locking plate configurations. Three-tier pricing stratifies across premium patient-specific 3D-printed constructs, standard anatomically contoured plates, and economy stainless steel alternatives. Cost compression in the standard tier intensifies as hospital value-analysis committees elevate biomechanical fatigue thresholds as primary procurement criteria. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize performance metrics over unit cost.
Supply Chain Analysis
Upstream feedstock flows from Russian titanium sponge producers, Chinese rare earth processors, and German specialty steel mills into CNC milling operations. Component manufacturing draws from Swiss precision machining clusters near Basel, German Baden-Württemberg facilities, and emerging Yangtze River Delta capacity. Single-source vulnerability concentrates in electron beam melting equipment for patient-specific titanium constructs. Distribution runs through hospital GPO contracts, surgical center consignment arrangements, and orthopedic clinic direct purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from modular instrument leasing, sterilization logistics, and surgeon training programs expands faster than implant hardware sales, creating recurring revenue architectures that manufacturers must build to defend margin structure.
For Market Incumbents: Pre-empt biodegradable polymer fixation disruption by acquiring magnesium-alloy processing capabilities or exclusive distribution rights with Swiss precision machining clusters. Lock in multi-year GPO contracts with tertiary trauma centers before EU MDR clinical evaluation timelines extend competitive entry windows. Anchor hospital contracting power through integrated trauma sets spanning distal humerus to proximal forearm constructs. For New Entrants and Emerging Players: Establish a beachhead in Indian tier-2 city trauma units under Ayushman Bharat infrastructure buildout, where unmet fixation device access creates first-mover positioning. Target ambulatory surgical center modular instrument leasing as the most penetrable channel, bypassing incumbent hospital-contracting lock-in. Lead with procedure-specific configurations and consignment inventory models that reduce customer capital deployment. For Investors and Strategic Acquirers: EU MDR post-market surveillance mandates reshape the acquisition landscape by elevating clinical affairs infrastructure as a scarce capability that mid-tier manufacturers struggle to operationalize. Five-to-ten year viability hinges on regulatory compliance scalability rather than product innovation velocity alone. Target acquisition archetypes include Swiss precision machining specialists with electron beam melting capacity and established notified body relationships. Watch FDA 510(k) clearance velocity for novel construct geometries as the signal indicating which platform developers can compress time-to-revenue.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evaluation documentation extends approval cycles for novel implant geometries. |
| Hospital System Partnership | Integrated trauma set contracts with tertiary centers compress vendor selection cycles. |
| Software Companion Development | Digital surgical planning tools interface with robotics-compatible fixation platforms. |
| Reimbursement Strategy | Coverage determinations for outpatient upper-extremity procedures shape site-of-care migration. |
| Backward Integration into Titanium Processing | Captive supply of Ti-6Al-4V ELI insulates margins from aerospace sector price volatility. |
Research Methodology
Initial hypotheses were tested against primary input from orthopedic trauma surgeons, hospital purchasing committee members, biomedical engineers at precision machining clusters, and GPO contracts managers, then refined against secondary validation from FDA 510(k) filings, ISO 13485 audit records, EU MDR clinical evaluation reports, and hospital procurement databases. Bottom-up construct demand modeling and top-down trauma incidence epidemiology were triangulated to anchor volume estimates.
Demand-supply balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning product type, material composition, customer facility type, and end-user specialist training depth. CAGRs were derived from procedure volume growth trajectories and implant price evolution patterns, incorporating inputs from ambulatory surgical center expansion rates and biodegradable polymer fatigue validation timelines.
Sensitivities concentrate around titanium alloy spot market volatility, EU MDR approval timeline extensions, and site-of-care migration velocity toward outpatient settings. Cross-checking against CMS Medicare procedure volume data and GPO contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
EEG Electrodes Market
Medical Devices
United Kingdom General Surgical Devices Market
Medical Devices
Global Keratometers Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Global Ureteroscopes Market
Medical Devices
Bariatric Beds Market
Medical Devices
Balloon Valvuloplasty Device Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Sterile Filtration Module Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
South Africa Anesthesia Devices Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Buccal Drug Delivery System Market
Medical Devices
Polymer-Based Prefilled Syringe Market