
 Central and Eastern Europe (CEE) Facility Management Market | 2026-2036
Central and Eastern Europe (CEE) Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Central and Eastern Europe (CEE) Facility Management Market Insights
Buyer concentration among large commercial landlords and multinational tenants in the CEE region is hardening, pushing facility management contracts toward fewer, larger providers with cross-border capabilities. CBRE Group leverages its pan-European property management platform to bundle FM with leasing services across Warsaw and Prague. ISS A/S anchors its regional position through long-term integrated contracts with manufacturing clients in Hungary and Slovakia. Strabag SE competes by extending construction-phase relationships into operational FM mandates, particularly for industrial and logistics assets.
Facility management in Central and Eastern Europe encompasses the professional coordination of building operations, maintenance, cleaning, security, and energy systems to ensure functional, safe, and cost-efficient environments for occupants. Technical scope includes HVAC calibration, fire safety compliance testing, and integrated building automation protocols that monitor real-time energy consumption across multi-site portfolios. The service type dimension remains dominated by cleaning and maintenance, where scale efficiencies protect margins, while IoT solutions within the technology segment represent the fastest-expanding category as owners deploy smart sensors to meet tightening EU energy disclosure rules. Energy management systems command premium pricing due to specialized engineering requirements and regulatory compliance value.
The EU Green Deal and its Energy Performance of Buildings Directive reshape procurement standards across the region, compelling FM providers to certify energy reduction outcomes. ECHA's REACH protocols further govern chemical cleaning products used in commercial maintenance, while national transpositions of the EU AI Act begin touching automated building systems. Facility managers must monitor how Poland's building energy codes and the Czech Republic's renovation wave funding criteria evolve, as these will determine which technology investments qualify for contract eligibility. Stakeholders should track whether integrated providers or specialized energy-tech firms capture the margin pool from decarbonization-linked FM contracts.
Market Dynamics
The EU Green Deal's Energy Performance of Buildings Directive is compressing procurement cycles across the CEE region as landlords race to retrofit aging commercial stock before mandatory disclosure deadlines trigger penalty exposure.
Growth Catalysts
- EU Green Deal enforcement:Mandatory energy performance certificates for existing buildings are accelerating FM contract renewals with decarbonization clauses across Poland and Czechia.
- Smart sensor deployment:IoT-enabled building automation systems are automating real-time HVAC calibration and fire safety compliance testing in Warsaw's multinational-occupied office towers.
- Warsaw-Kraków corridor concentration:Multinational tenant demand for specification-grade FM services is pulling integrated providers into Poland's primary commercial axis.
Market Restraints
- Skilled technician scarcity:Certified energy systems engineers command premium wages that compress margins on fixed-price integrated contracts.
- REACH chemical compliance:ECHA's restricted substance lists are forcing reformulation of industrial cleaning solvents used across Hungarian manufacturing facilities.
- Construction-to-FM transition friction:Strabag SE's project-based relationships struggle to convert into recurring operational mandates without dedicated service infrastructure.
Strategic Opportunities
- Slovak industrial hinterland:Underpenetrated logistics parks near Bratislava present whitespace for energy-management-specialized FM entrants.
- EU AI Act building systems mandate:Automated compliance documentation for smart building algorithms creates premium service tiers for certified providers.
- Czech renovation wave funding:National subsidy criteria favoring integrated FM-energy retrofit bundles are opening public-sector contract pools.
Industry Challenges
- BMS integration complexity:Legacy Siemens and Honeywell building management systems in Prague's 1990s-era commercial stock resist seamless sensor overlay without costly gateway hardware.
- Cross-border certification recognition:Polish energy auditor credentials face acceptance delays in Czech tender processes, fragmenting provider mobility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central and Eastern Europe (CEE) Facility Management Market |
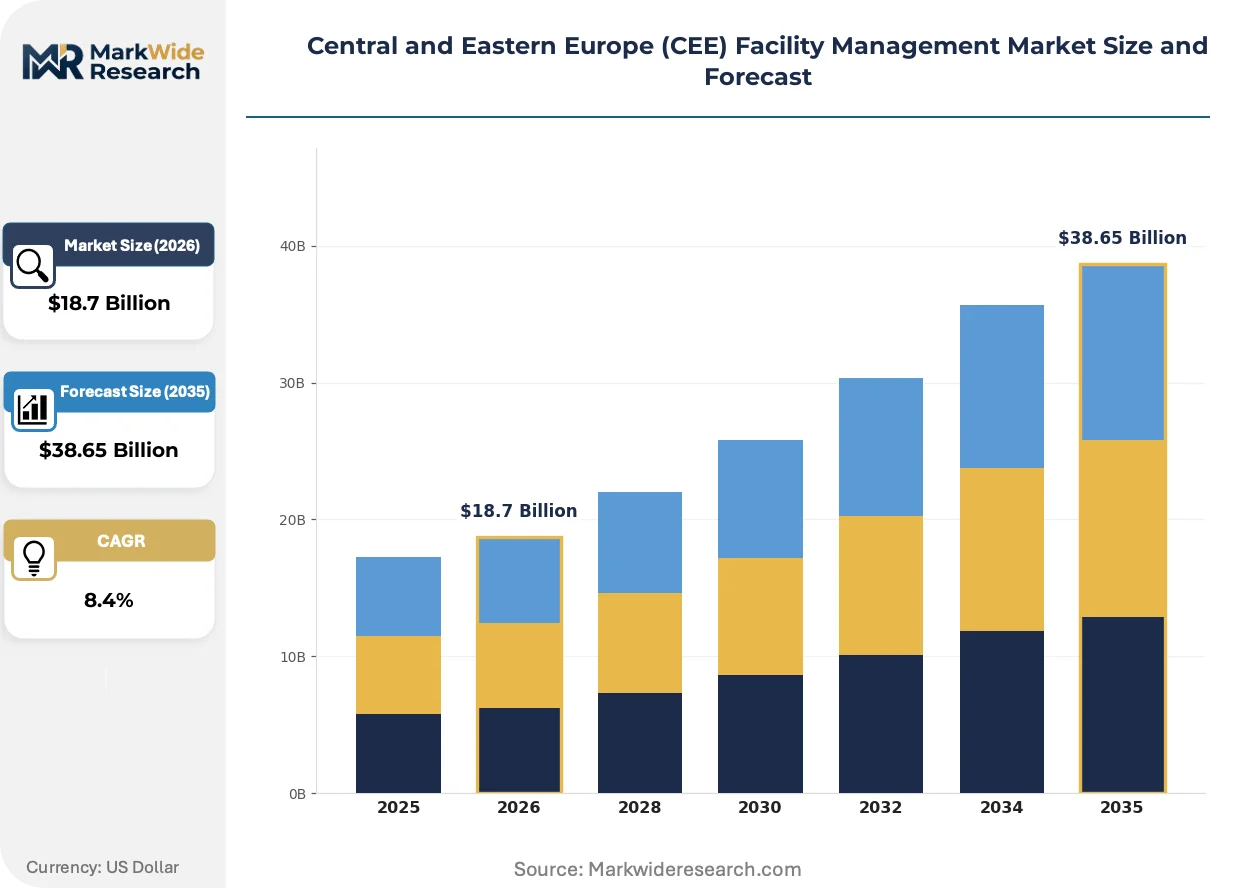
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Landscaping End User: Commercial Buildings, Educational Institutions, Residential Complexes, Healthcare Facilities Technology: Building Automation, IoT Solutions, Energy Management Systems, Smart Sensors Size: Small Enterprises, Medium Enterprises, Large Corporations, Multinational Companies |
| Companies Covered | Strabag SE, Bilfinger SE, Dussmann Group, CBRE Group, OKIN Facility, SIMACEK GmbH, ISS A/S, SPIE SA, Apleona GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central and Eastern Europe (CEE) Facility Management Market Trends and Innovations
Digital building infrastructure and regulatory disclosure mandates are converging to reshape how FM services are specified, priced, and validated across the CEE region.
IoT sensor networks are automating continuous energy consumption monitoring and predictive maintenance scheduling across multi-site commercial portfolios. Large landlords in Warsaw and Prague are deploying these systems at scale to pre-empt EU Green Deal audit requirements. The technology is automating manual meter-reading and compliance reporting functions that previously consumed 15-20% of facility management labor hours.
REACH chemical governance is tightening permissible formulations in commercial cleaning products used across Hungarian and Slovak manufacturing facilities. ECHA's 2024 substance restriction updates are forcing FM providers to requalify supplier bases and retrain cleaning protocols. Industrial segments with heavy solvent dependence are absorbing the highest compliance transition costs and accelerating contractor consolidation to access reformulated chemical supply chains.
Integrated service bundling is displacing single-service FM procurement as multinational tenants demand single-accountability contracts spanning leasing, maintenance, and energy performance. CBRE Group's pan-European platform is capturing this shift by wrapping FM into property management mandates. The pattern is most pronounced in Warsaw's central business district, where German and US-headquartered tenants specify outcome-based contracts with energy reduction guarantees.
Central and Eastern Europe (CEE) Facility Management Market Segmentation
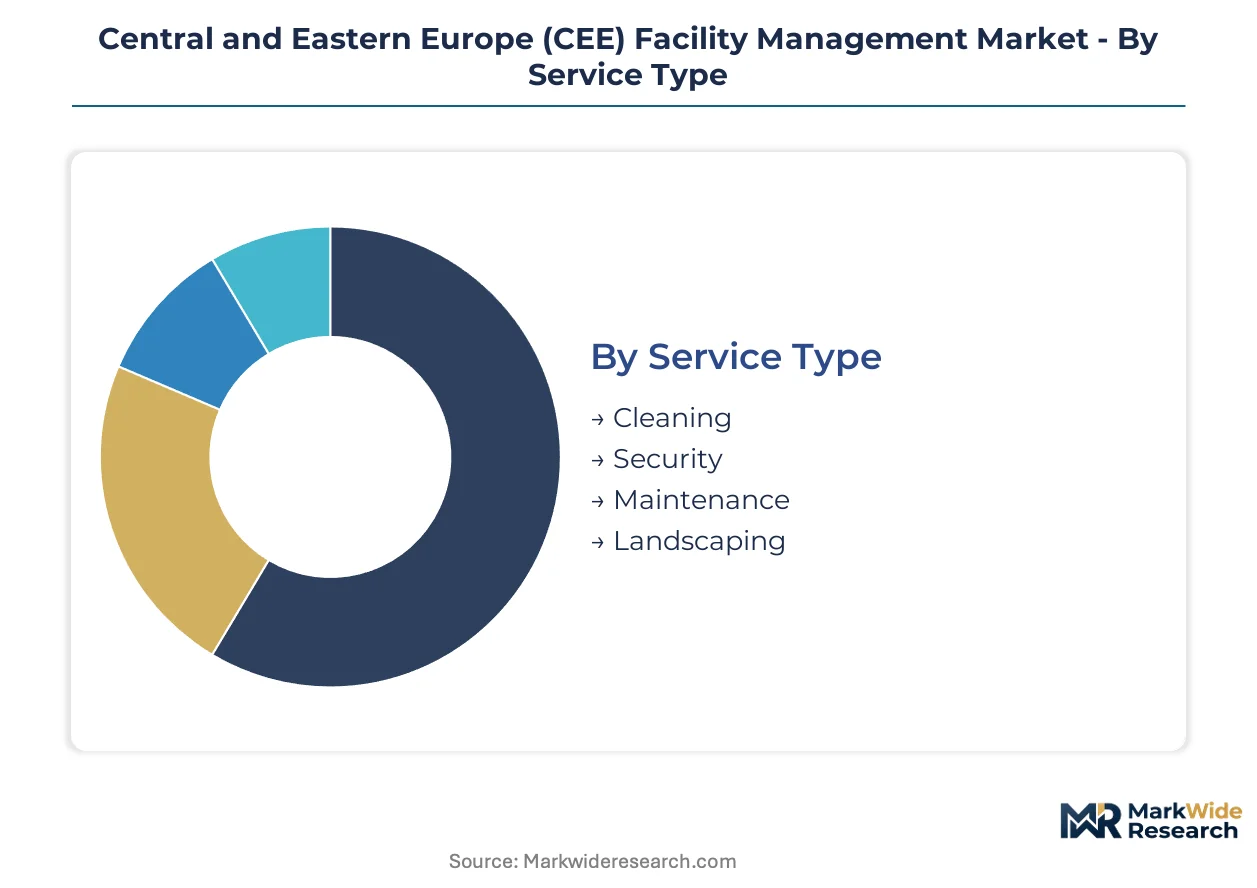
Facility management procurement patterns across Central and Eastern Europe diverge sharply by integration depth. Standalone service contracts dominate legacy portfolios, while embedded technology-enabled bundles capture premium pricing from multinational tenants seeking single-accountability structures.
Service Type:
Standalone services anchor legacy procurement in Poland's public sector and Czech industrial zones, while integrated multi-service contracts penetrate Warsaw's multinational-occupied commercial towers where single-provider accountability reduces vendor management overhead.
- Cleaning:Labor-intensive janitorial and specialized sanitation services constitute the volume base across CEE commercial portfolios. Polish shopping centers and Czech office parks outsource these functions most heavily as unionized in-house labor costs rise. REACH chemical compliance is forcing reformulation of industrial solvents used in Hungarian manufacturing facilities, consolidating contractor selection toward providers with qualified chemical supply chains.
- Security:Manned guarding and electronic access control systems protect commercial assets across the Warsaw-Kraków corridor. Demand concentrates in Prague's financial district where GDPR-compliant visitor management systems are becoming tender prerequisites. The segment absorbs technology overlay fastest as biometric and AI-enabled surveillance systems displace legacy guard-post models.
- Maintenance:Corrective and preventive technical services span HVAC, electrical, and structural systems. Slovak logistics parks and Romanian industrial zones drive specification upgrades as EU Green Deal energy performance deadlines approach.
- Landscaping:Grounds maintenance and seasonal exterior services support commercial curb appeal and regulatory green space requirements. Polish retail developments and Czech business parks specify these as bundled amenities rather than standalone procurements.
Cleaning leads volumes today; integrated multi-service bundles are gaining share fastest.
End User:
Cost tier segmentation separates specification-grade procurement by multinational tenants from price-sensitive public sector tendering across the region.
- Commercial Buildings:Office towers, retail centers, and mixed-use developments in Warsaw and Prague command premium FM specifications. German and US-headquartered tenants mandate outcome-based contracts with energy reduction guarantees, pulling integrated providers toward the Warsaw-Kraków corridor. EU Green Deal disclosure deadlines accelerate contract renewals with decarbonization clauses.
- Educational Institutions:Universities and public schools across Poland and Czechia operate under constrained budgets that favor basic cleaning and maintenance over technology-enabled services. National procurement frameworks limit provider flexibility despite rising energy efficiency mandates.
- Residential Complexes:Multi-unit housing developments in Budapest and Bratislava outsource concierge, cleaning, and technical maintenance to specialized residential FM operators. Homeowners association governance structures fragment contract scale and complicate integrated service adoption.
- Healthcare Facilities:Hospitals and clinics require infection control protocols, medical waste management, and 24/7 critical systems redundancy. Hungarian and Slovak healthcare infrastructure modernization programs are opening specialized contract pools for certified providers.
Commercial buildings absorb the highest contract values; healthcare facilities are expanding procurement most quickly.
Technology:
Application depth varies from standalone monitoring tools to fully embedded building automation architectures that reshape provider capability requirements.
- Building Automation:Centralized control systems orchestrate HVAC, lighting, and security across multi-site portfolios. Prague's 1990s-era commercial stock with legacy Siemens and Honeywell installations resists seamless sensor overlay without costly gateway hardware upgrades.
- IoT Solutions:Networked sensors enable predictive maintenance and real-time energy consumption tracking. Warsaw's multinational-occupied office towers deploy these systems at scale to pre-empt EU Green Deal audit requirements and automate manual meter-reading functions.
- Energy Management Systems:Specialized engineering platforms optimize building performance against tightening regulatory standards. These command premium pricing due to certified auditor requirements and compliance documentation value.
- Smart Sensors:Discrete monitoring devices for occupancy, air quality, and equipment health feed data into centralized analytics platforms. Czech renovation wave funding criteria increasingly favor buildings with sensor-enabled performance verification.
Building automation holds the installed base; IoT solutions are climbing the fastest.
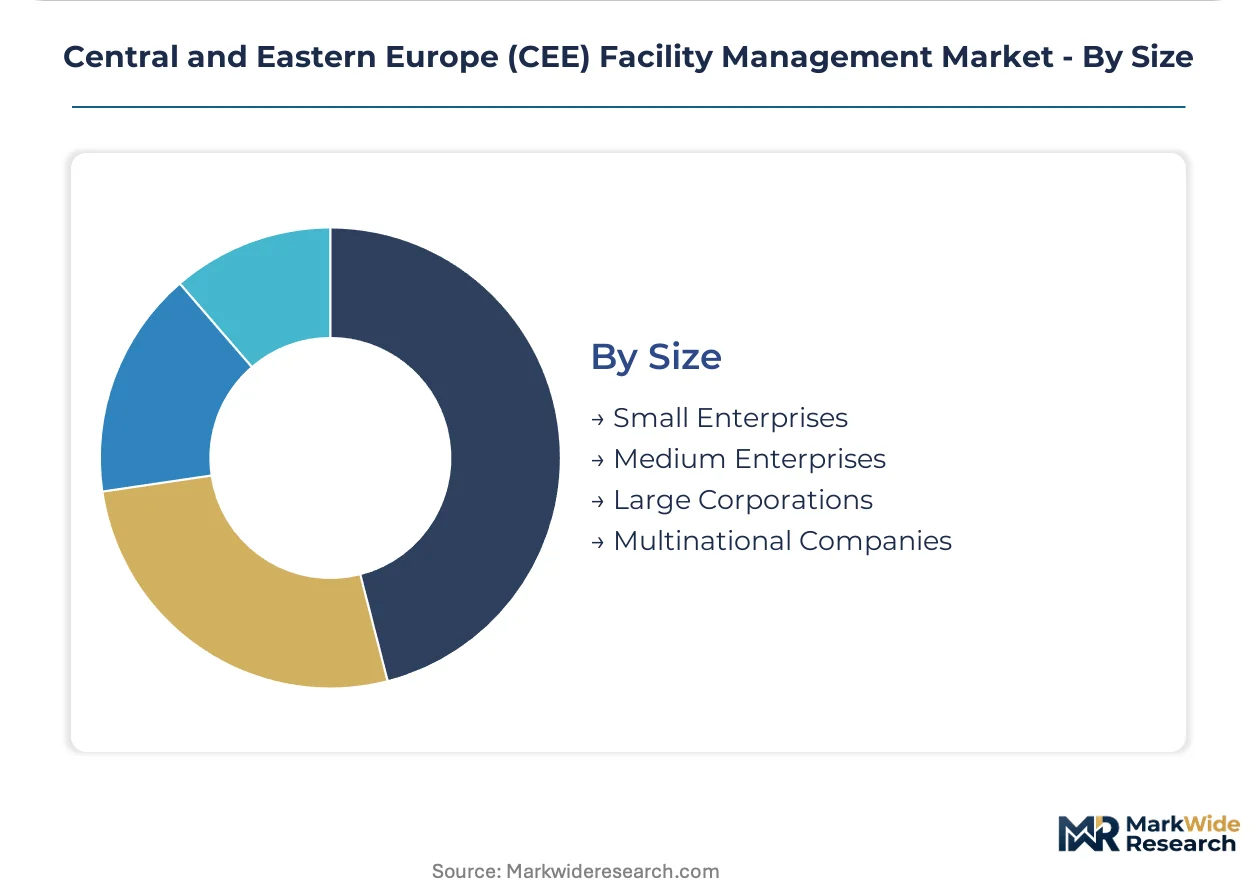
Size:
Customer maturity and procurement sophistication separate enterprise segments, with volume concentration and margin structure diverging by organizational scale.
- Small Enterprises:Local cleaning contractors and single-site maintenance providers serve fragmented demand across secondary Polish and Romanian cities. Limited technology adoption and price competition compress margins.
- Medium Enterprises:Regional FM operators with multi-city coverage compete for public sector and mid-market commercial contracts in Hungary and Slovakia. EU funding access requirements are accelerating certification investments.
- Large Corporations:Domestic property owners and industrial operators with concentrated portfolios negotiate multi-year integrated contracts. Czech and Polish energy-intensive manufacturers specify energy performance guarantees.
- Multinational Companies:Global tenants and cross-border landlords mandate pan-European service standards and centralized reporting. CBRE Group and ISS A/S capture this segment through cross-border capability and ESG disclosure alignment.
Large corporations dominate contract value; multinational companies are driving specification upgrades most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland commands the largest contract value pool across the region, while Czechia's renovation wave funding accelerates specification upgrades faster than neighboring markets.
Poland
Warsaw's central business district and the Kraków corridor concentrate multinational tenant demand for integrated FM services with energy performance guarantees. The country's building energy codes mandate disclosure deadlines that compress procurement cycles for commercial landlords. Katowice's emerging office market is pulling specialized providers into Silesia as German manufacturers expand regional headquarters.
Czechia
Prague's 1990s-era commercial stock requires extensive BMS retrofitting to meet EU Green Deal standards, creating demand for gateway hardware and sensor integration specialists. National renovation wave funding criteria favor bundled FM-energy retrofit contracts for public buildings. Brno's technology park cluster is specifying smart building automation for new logistics and R&D facilities.
Hungary
Budapest's industrial zones and residential complex developments drive outsourcing of technical maintenance and concierge services to specialized operators. ECHA's REACH protocols govern chemical cleaning products used across manufacturing facilities in the country's eastern regions. Debrecen's automotive supplier parks are mandating integrated security and energy management contracts.
Slovakia
Bratislava's underpenetrated logistics parks present whitespace for energy-management-specialized FM entrants seeking industrial mandates. The country's transposition of EU AI Act requirements touches automated building systems compliance documentation. Košice's manufacturing belt is absorbing specification upgrades as EU-funded infrastructure modernization programs expand.
Romania
Bucharest's commercial development wave and secondary city industrial zones fragment demand between price-sensitive local contractors and specification-grade providers. National procurement frameworks for educational institutions limit technology-enabled service adoption despite rising efficiency mandates. Cluj-Napoca's IT sector growth is pulling premium FM specifications into Transylvania's emerging office market.
Central and Eastern Europe (CEE) Facility Management Market Competitive Landscape
Western European integrated providers anchor the premium contract tier; regional specialists from Germany and Austria hold mid-market industrial positions. Market structure concentrates around cross-border capability, with pan-European platforms capturing multinational tenant mandates while construction-origin firms struggle to convert project relationships into recurring operational revenue. Three archetypes dominate: property management bundlers, long-term integrated contract holders, and construction-phase relationship extenders. Competitive moves center on M&A for chemical supply chain qualification and strategic partnerships for smart sensor deployment.
Among Austria-based construction-origin firms, Strabag SE exemplifies the challenge of converting project-based relationships into recurring FM mandates without dedicated service infrastructure. Danish integrated service providers occupy positions emphasizing long-term industrial contracts with energy performance accountability. Within the property management bundler tier, CBRE Group represents cross-border capability alignment with multinational tenant ESG disclosure requirements.
| Leading Market Players |
|---|
| Strabag SE |
| Bilfinger SE |
| Dussmann Group |
| CBRE Group |
| OKIN Facility |
| SIMACEK GmbH |
| ISS A/S |
| SPIE SA |
| Apleona GmbH |
| Others |
Pricing and Supply Chain Analysis
IoT sensor deployment across Warsaw's commercial towers is compressing labor-intensive service margins while concentrating procurement power among providers with certified energy engineering capabilities. This technology transition simultaneously elevates upfront hardware costs and fragments supplier bases as legacy building management systems require gateway retrofits.
Pricing Analysis
Capacity additions in Poland's FM labor pool are reshaping price floors for cleaning and maintenance services as cross-border technician mobility improves. Three-tier pricing structure across premium, standard, and economy levels separates energy-performance-guaranteed contracts from basic janitorial procurement. Price differentiation hinges on ISO 50001 energy certification status and bundled technology enablement. Cost compression in the standard tier is intensifying because REACH-compliant chemical reformulation raises input costs. Public sector educational institutions exhibit highest price sensitivity; multinational-occupied Warsaw CBD towers show least.
Supply Chain Analysis
Refurbishment flows for legacy Siemens and Honeywell building management systems create secondary equipment markets that extend functional life of Prague's 1990s commercial stock. Component sourcing concentrates in Germany, Austria, and Czechia for HVAC control hardware. Raw material dependencies span copper wiring, sensor microcontrollers, and specialty cleaning solvents governed by ECHA restrictions. Single-source vulnerability runs through German-engineered BMS gateway manufacturers. Distribution runs through regional FM integrators who bundle hardware with service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Energy Performance of Buildings Directive functions as a regulatory compounder, accelerating contract renewal cycles as disclosure deadlines trigger penalty exposure for non-compliant landlords.
For Market Incumbents: Lock in long-term integrated contracts with energy performance guarantees before specialized energy-tech firms capture decarbonization margin pools. Defensive consolidation through M&A targets chemical supply chain qualification capabilities to absorb REACH compliance transition costs. Threat of construction-origin firms converting project relationships demands preemptive service infrastructure investment. For New Entrants and Emerging Players: AI-enabled building automation compliance documentation offers a technology-first wedge into the premium service tier created by EU AI Act transposition requirements. White-space targets include Bratislava's underpenetrated logistics parks and Czech public-sector renovation wave funding pools. Go-to-market angle: certified energy auditor credentials with cross-border Polish-Czech recognition. For Investors and Strategic Acquirers: Valuations sit cheapest among regional mid-cap FM operators lacking technology enablement capabilities but holding established industrial client relationships. Long-term viability frames toward providers who capture recurring revenue from sensor-enabled performance verification. Acquisition target archetype: Slovak or Hungarian specialists with EU funding access qualifications. Signal to watch: national transpositions of EU AI Act building systems mandates as contract eligibility inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Deployment Partnership | Warsaw's multinational tenants mandate IoT-enabled energy monitoring to pre-empt EU Green Deal audit requirements. |
| REACH-Compliant Chemical Supply Chain Acquisition | ECHA's 2024 substance restrictions force reformulation of industrial cleaning solvents across Hungarian manufacturing. |
| Cross-Border Energy Auditor Certification | Polish credentials face acceptance delays in Czech tender processes, fragmenting provider mobility. |
| Integrated FM-Energy Retrofit Bundling | Czech renovation wave funding criteria favor combined service contracts for public buildings. |
| Legacy BMS Gateway Hardware Integration | Prague's 1990s commercial stock requires costly retrofitting to enable seamless sensor overlay. |
Research Methodology
Bottom-up commercial building modeling reconciled against top-down integrated service provider tracking forms the analytical core of this study. Primary interviews with facility management executives, energy systems engineers, property portfolio managers, and ESG compliance officers combined with secondary validation from EU ECHA regulatory filings, national building energy code transpositions, and EPC contract databases. Triangulation across stakeholder perspectives and documentary sources anchors segmentation estimates.
Input-output matrices map service type demand against technology adoption curves and end-user procurement sophistication across the projection horizon. Segmentation dimensions modeled include service integration depth, technology application tier, end-user vertical, and customer organizational scale. CAGRs derive from fitted growth curves calibrated to disclosed contract values and regulatory deadline impacts. Industry-specific forecast inputs incorporate EU Green Deal implementation pacing and national renovation wave funding allocation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act transposition timing and REACH chemical restriction enforcement intensity. Practitioners should monitor Polish building energy code amendments and Czech public procurement framework updates for early signals of contract eligibility shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Australia Facility Management Market
Facility Management
Asia-Pacific Hard Facility Management Market
Facility Management
Italy Facility Management Services Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
Moldova Facility Management Market
Facility Management
Latin America Soft Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Belgium Facility Management Market
Facility Management
India Facility Management Market
Facility Management
China Facility Management Market
Facility Management
Lithuania Facility Management Market
Facility Management
Croatia Facility Management Market
Facility Management
Bahrain Facility Management Market
Facility Management
Thailand Facility Management Market
Facility Management
New Zealand Facility Management Market
Facility Management
Africa Facility Management Market