
 Saudi Arabia Facility Management Market | 2026-2036
Saudi Arabia Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Facility Management Market Analysis
Saudi contractor capacity is restructuring around integrated service delivery as mega-project pipelines strain traditional single-service models. Musanadah Facilities Management Co. LTD anchors large-scale maintenance operations across industrial zones. Almajal G4S dominates security-centric bundled offerings for critical infrastructure. Initial Saudi Group extends its footprint through soft services specialization in hospitality and commercial segments.
Facility management encompasses the coordinated oversight of built environment operations including cleaning, maintenance, security, and landscaping services, typically governed by SLA-driven contracts with defined response times and performance metrics. Its primary purpose ensures asset longevity, occupant safety, and operational continuity for physical infrastructure. Hard services and integrated facilities management command premium contract values due to technical skill requirements and capital equipment needs. Soft services segments face margin compression from labor cost inflation yet attract new entrants through lower barriers. IoT solutions and building management systems represent the fastest-expanding technology dimension as Saudi operators digitize asset monitoring.
SASO mandates energy efficiency benchmarks for commercial buildings, compelling facility managers to adopt smart HVAC and energy management systems. The Saudi Building Code, enforced by municipal authorities, structures maintenance protocols and safety inspection frequencies across asset classes. SFDA guidelines impose specialized cleaning and environmental controls on healthcare facility contracts. Stakeholders must assess whether technology investments align with evolving regulatory thresholds before committing to long-term service agreements.
Market Dynamics
Vision 2030 hospital privatization mandates are restructuring how healthcare assets contract maintenance services, forcing facility managers to reconfigure service delivery models around clinical compliance requirements rather than traditional building operations.
Growth Catalysts
- Healthcare privatization mandates:Vision 2030 directives transfer government hospital operations to private operators, generating specialized facility management contracts requiring clinical-grade environmental controls and infection prevention protocols.
- SASO energy efficiency standards:Mandatory efficiency benchmarks for commercial buildings compel retrofitting of HVAC and lighting systems, creating sustained demand for technical maintenance services and energy management system integration.
- Mega-project construction pipelines:Sustained development in Riyadh and Jeddah generates recurring facilities management needs across commercial, residential, and mixed-use assets as buildings transition from construction to operational phases.
Market Restraints
- Labor cost inflation in soft services:Wage pressures for cleaning and security personnel compress margins in labor-intensive service segments, limiting profitability for providers without scale economies.
- Technical skill scarcity:Shortage of certified technicians for smart building systems and energy management equipment constrains service expansion in high-value hard services segments.
- Regulatory compliance fragmentation:Overlapping requirements from SASO, the Saudi Building Code, and sector-specific regulators like SFDA create administrative burden and certification complexity for multi-site operators.
Strategic Opportunities
- Neom and Red Sea Project greenfield developments:New city-scale developments require integrated facilities management from inception, enabling providers to embed digital-native service models without legacy system constraints.
- IoT-enabled predictive maintenance:Sensor networks and building management system convergence allow remote monitoring contracts that shift revenue from reactive labor to technology-enabled subscription models.
- Industrial zone specialization:Concentrated manufacturing clusters in Jubail and Yanbu create demand for hazardous environment maintenance expertise with higher contract values and longer tenures.
Industry Challenges
- Certified technician recruitment:Competition for professionals holding SASO-recognized credentials in electrical, mechanical, and fire safety systems limits operational scaling.
- Legacy asset integration:Older commercial buildings in established Riyadh and Jeddah districts lack infrastructure for smart building retrofits, complicating service standardization across portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Facility Management Market |
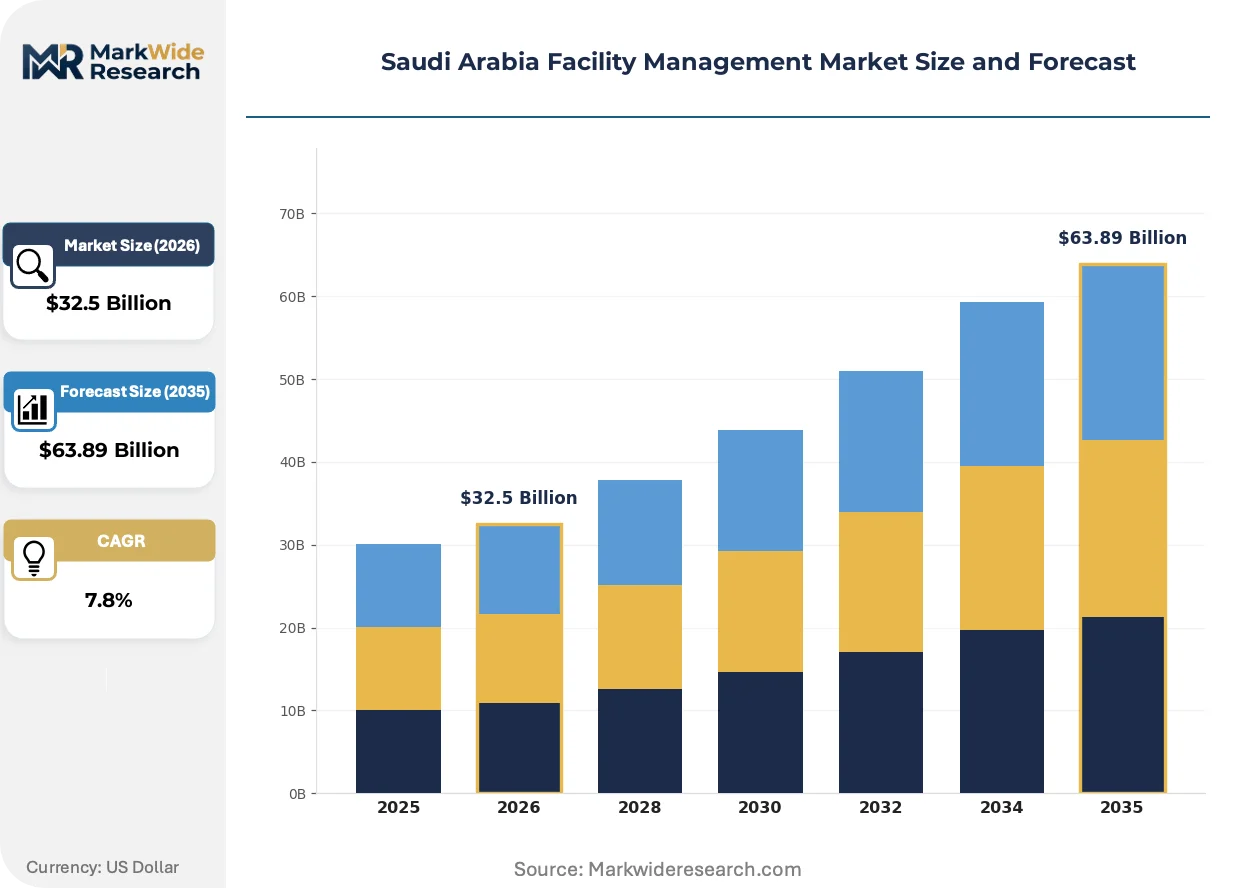
| Market Size in 2026 | $32.5 Billion |
| Market Size in 2035 | $63.89 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Maintenance, Security, Landscaping End User: Educational Institutions, Healthcare Facilities, Commercial Buildings, Residential Complexes Technology: IoT Solutions, Building Management Systems, Energy Management Systems, Smart HVAC Contract Type: Hard Services, Soft Services, Integrated Facilities Management, Outsourced Services |
| Companies Covered | Initial Saudi Group, Almajal G4S, Emcor Saudi Company Limited, SETE Energy Saudia for Industrial Projects Ltd, ZOMCO, Musanadah Facilities Management Co. LTD, MEEM Facility Management Co., Muheel Services for Maintenance & Operations LLC, Khidmah, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Facility Management Market Emerging Trajectories
Digital infrastructure is displacing labor-intensive inspection routines across Saudi facility operations. Three developments are compressing traditional service models while opening premium technology-enabled contract structures.
Building management systems integrating IoT sensors are automating condition monitoring for HVAC, electrical, and fire safety equipment. Large commercial landlords in Riyadh are deploying these platforms to replace scheduled preventive maintenance with condition-based interventions. This compression of routine labor hours is reallocating contract value toward data analytics and remote diagnostics capabilities.
The Saudi Building Code enforcement by municipal authorities is mandating documented maintenance protocols and inspection frequencies across asset classes. Commercial property owners must now maintain digital audit trails for safety system testing and corrective actions. Healthcare facilities face the strictest documentation requirements under parallel SFDA environmental control guidelines.
Buyers are consolidating vendor relationships to reduce contract administration overhead. Single-service cleaning or security contracts are giving way to integrated facilities management agreements spanning hard and soft services. This consolidation is most visible in Jeddah's commercial office sector, where property managers seek unified accountability for operational performance metrics.
Saudi Arabia Facility Management Market Segmentation
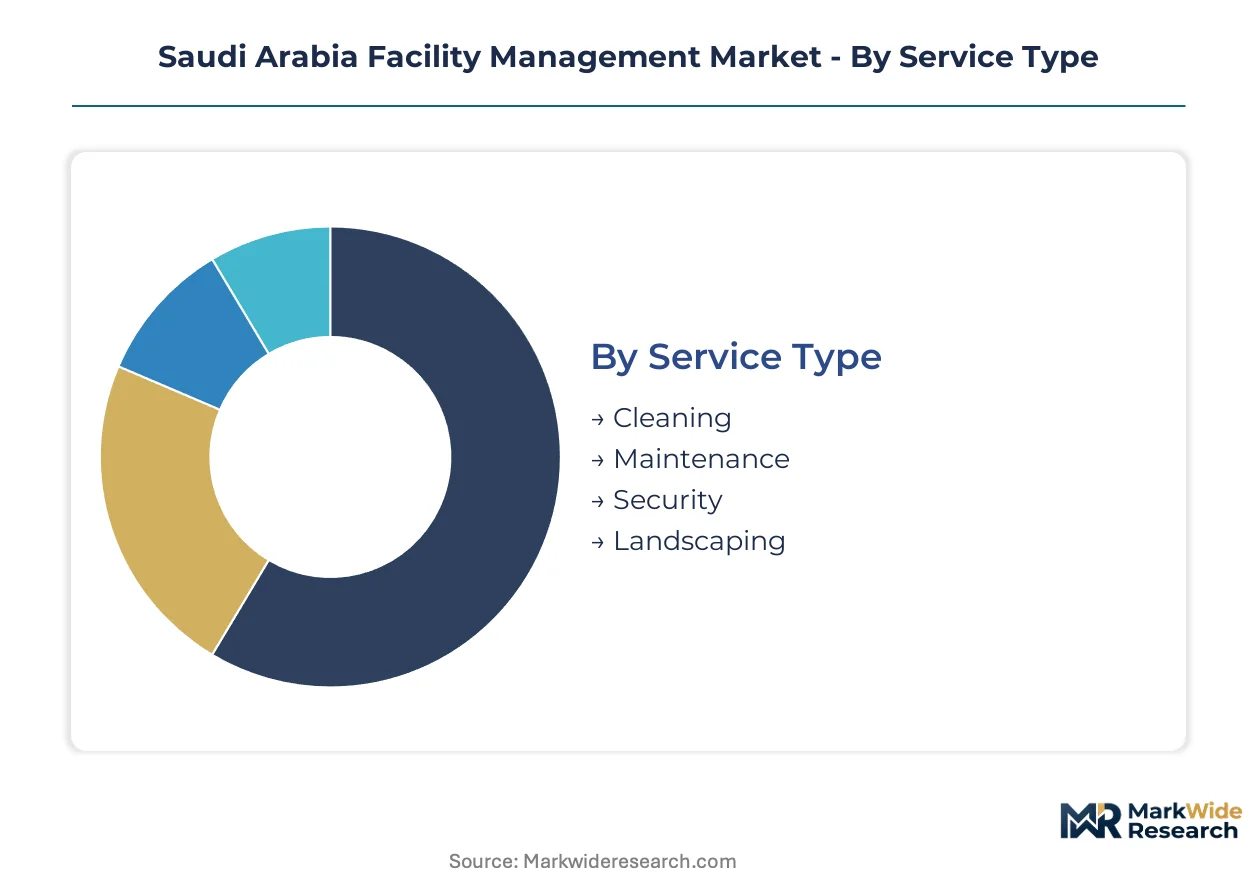
Facility management providers in Saudi Arabia configure service portfolios around asset-specific risk profiles and compliance intensity. Segmentation reveals where capital deployment, technical certification, and contract duration vary most sharply across buyer categories.
Service Type:
Capital intensity diverges sharply between equipment-heavy technical services and labor-dependent operational functions.
- Maintenance:Encompasses mechanical, electrical, and fire safety systems requiring certified technicians and specialized diagnostic equipment. Demand concentrates in Riyadh's commercial office stock and Jeddah's healthcare facilities under SASO energy efficiency mandates, where predictive maintenance contracts are displacing scheduled interventions.
- Security:Combines manned guarding with electronic access control and surveillance systems. Critical infrastructure operators in Jubail's industrial zones and Yanbu's manufacturing clusters drive premium contract values due to hazardous environment protocols and 24/7 operational requirements.
- Cleaning:Labor-intensive service spanning routine janitorial to specialized healthcare environmental controls. SFDA guidelines for hospital-grade disinfection create compliance tiering that separates clinical from commercial applications.
- Landscaping:Irrigation, grounds maintenance, and hardscape upkeep for commercial and residential assets. Water scarcity regulations in the Kingdom constrain expansion despite sustained construction activity in Riyadh's northern districts.
Maintenance absorbs the bulk of installed capacity; Security is expanding most quickly.
End User:
Contract value scales with regulatory scrutiny and operational criticality rather than asset square footage alone.
- Healthcare Facilities:Hospitals, clinics, and medical centers requiring clinical-grade environmental controls, infection prevention protocols, and SFDA-mandated documentation systems. Vision 2030 privatization transfers government hospital operations to private operators, generating specialized facility management contracts with stringent performance metrics.
- Commercial Buildings:Office towers, retail centers, and mixed-use developments in Riyadh and Jeddah. SASO energy efficiency benchmarks compel retrofitting of HVAC and lighting systems, creating sustained demand for technical maintenance services.
- Educational Institutions:Universities, schools, and training centers with seasonal occupancy patterns. Contract structures emphasize flexible staffing models to accommodate academic calendar fluctuations.
- Residential Complexes:Gated communities and high-rise apartment buildings. Service standardization proves difficult across fragmented ownership structures and varying amenity tiers.
Commercial Buildings dominate current contract volume; Healthcare Facilities are climbing the fastest.
Technology:
Technology adoption separates premium service providers from commodity operators through remote monitoring capabilities and predictive analytics.
- Building Management Systems:Centralized platforms integrating HVAC, lighting, and security controls. Large commercial landlords in Riyadh deploy these systems to automate condition monitoring and compress routine labor hours.
- IoT Solutions:Sensor networks enabling predictive maintenance and real-time asset tracking. Neom and Red Sea Project greenfield developments embed digital-native service models without legacy system constraints.
- Smart HVAC:Automated climate control systems optimizing energy consumption against SASO efficiency benchmarks. Retrofit demand concentrates in older Riyadh and Jeddah commercial districts.
- Energy Management Systems:Software platforms monitoring consumption patterns and identifying optimization opportunities. Municipal enforcement of the Saudi Building Code drives adoption across asset classes.
Building Management Systems command the largest installed base; IoT Solutions are gaining share fastest.
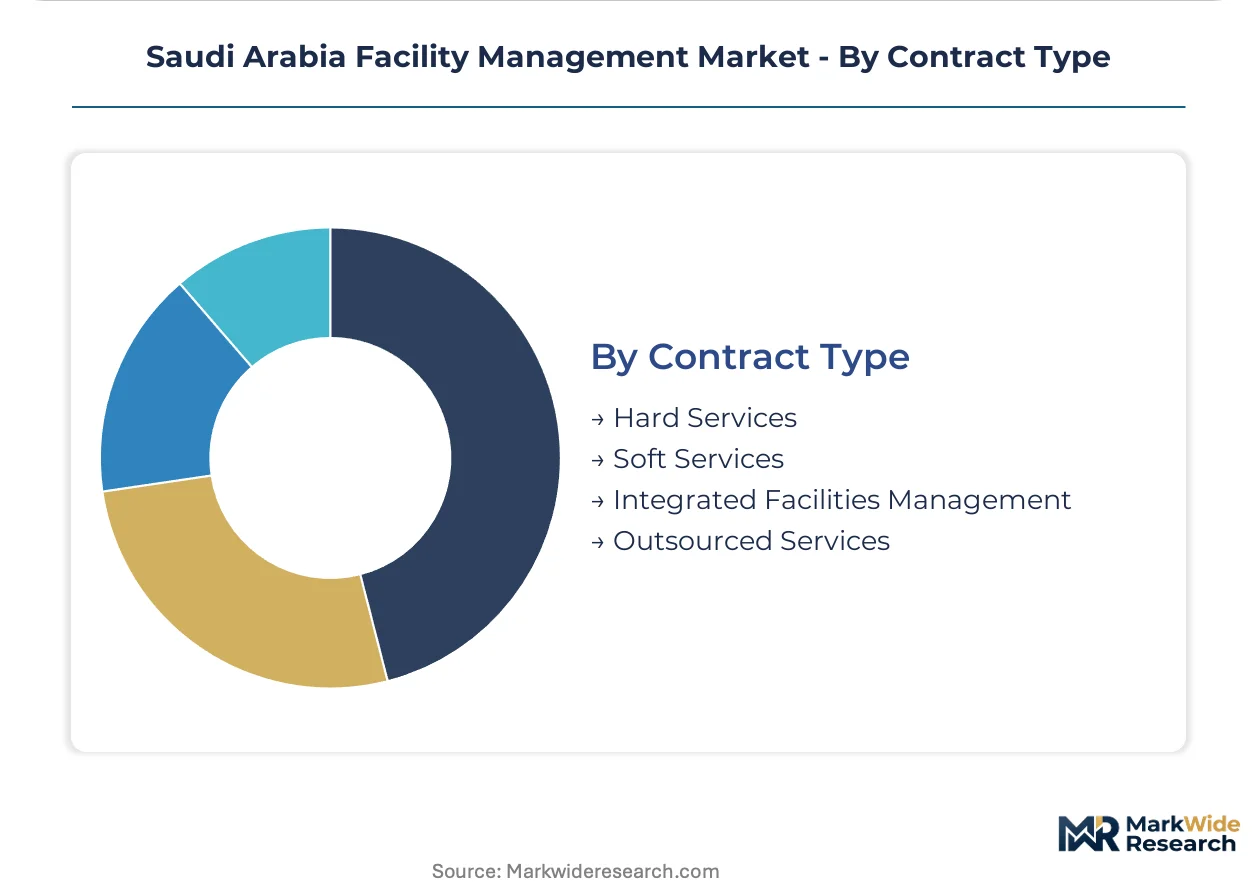
Contract Type:
Buyer consolidation favors integrated agreements that unify accountability across service categories.
- Integrated Facilities Management:Bundled contracts spanning hard and soft services under single-provider accountability. Jeddah's commercial office sector shows strongest consolidation momentum as property managers seek unified performance metrics.
- Hard Services:Technical maintenance of mechanical, electrical, and structural systems. Certified technician scarcity constrains expansion despite premium pricing.
- Soft Services:Cleaning, security, and landscaping functions. Labor cost inflation compresses margins, driving provider consolidation around scale economies.
- Outsourced Services:Third-party provision of functions previously managed in-house. Vision 2030 hospital privatization accelerates outsourcing of clinical support services.
Soft Services retain the widest contract count; Integrated Facilities Management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the Eastern Province anchors facility management demand across Saudi Arabia's industrial corridor. Urbanization concentrates service requirements in four distinct economic zones.
Riyadh
Commercial office stock and mega-project construction generate sustained demand for integrated facilities management contracts. SASO energy efficiency mandates drive HVAC retrofitting across aging commercial districts. King Abdullah Financial District property managers consolidate vendor relationships under unified performance metrics.
Eastern Province
Jubail and Yanbu industrial clusters require hazardous environment maintenance expertise with specialized safety protocols. SFDA guidelines extend to pharmaceutical manufacturing facilities in the region. Petrochemical operators contract long-tenure technical maintenance for critical process equipment.
Western Region
Jeddah's hospitality and commercial sectors expand outsourced soft services under Vision 2030 tourism development. The Saudi Building Code enforcement mandates documented maintenance protocols for coastal commercial assets. Red Sea Project greenfield developments embed digital-native service models from inception.
NEOM Northwest
The linear city development creates demand for technology-integrated facilities management without legacy infrastructure constraints. IoT-enabled predictive maintenance contracts replace scheduled interventions in new-build assets. Municipal authorities enforce stringent sustainability benchmarks for operational-phase service providers.
Saudi Arabia Facility Management Market Vendor Landscape
Global majors compete with regional champions across contract scale and specialization depth. The vendor base organizes around three tiers: integrated service providers spanning hard and soft services, technical specialists concentrating on certified maintenance operations, and labor-scale operators competing on cleaning and security volume. Strategic moves center on portfolio diversification into adjacent service categories and technology partnerships for building management system integration.
Within the integrated service tier, Musanadah Facilities Management Co. LTD and Initial Saudi Group exemplify contrasting geographic and sectoral positioning. Almajal G4S occupies a distinct position bundling security-centric offerings for critical infrastructure operators. These three anchors represent archetypes visible across contract structures: industrial zone technical specialists, hospitality-focused soft service providers, and security-integrated hard service bundlers.
| Leading Market Players |
|---|
| Initial Saudi Group |
| Almajal G4S |
| Emcor Saudi Company Limited |
| SETE Energy Saudia for Industrial Projects Ltd |
| ZOMCO |
| Musanadah Facilities Management Co. LTD |
| MEEM Facility Management Co. |
| Muheel Services for Maintenance & Operations LLC |
| Khidmah |
| Others |
Supply Flow & Price Mechanics
Certified technician concentration in Riyadh and the Eastern Province anchors labor-cost differentials that widen pricing-tier spreads between integrated facilities management providers and commodity soft-service operators. Wage premiums for SASO-recognized credentials in electrical and mechanical systems translate directly into contract value stratification across hard and soft service bundles.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium integrated contracts from unbundled reactive service agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and technology enablement, with IoT-enabled predictive maintenance commanding top-tier positioning. Price differentiation rests on SASO compliance tier and geographic delivery cost to remote industrial zones. Cost compression in soft services is intensifying because wage inflation for cleaning and security personnel outpaces contract escalation clauses. Healthcare facilities under SFDA guidelines show least price sensitivity due to clinical compliance mandates, while residential complexes exhibit highest sensitivity to per-unit service charges.
Supply Chain Analysis
Workforce availability constraints in Saudi Arabia's certified technician pipeline shape supply chain configuration for technical service delivery. Equipment and technology sourcing draws from Germany, the United Arab Emirates, and South Korea for building management systems and smart HVAC components. Raw material dependencies include specialized fire safety equipment, energy management sensors, and diagnostic instrumentation for predictive maintenance platforms. Single-source vulnerability concentrates in proprietary building automation software licensed from European vendors. Distribution runs through direct service deployment by integrated providers rather than third-party channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
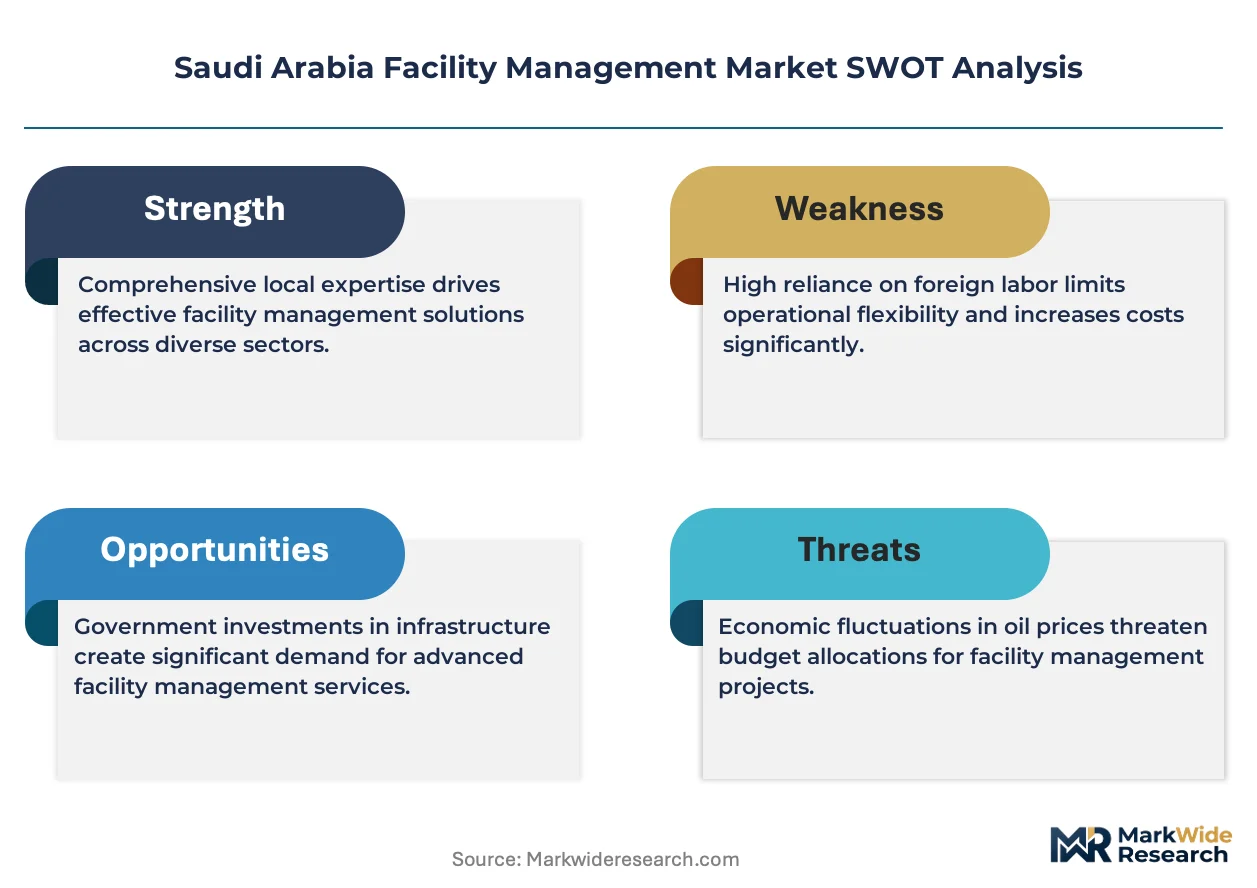
This market reads as a cost-of-compliance story where SASO energy efficiency mandates and SFDA healthcare protocols erect barrier-to-entry moats favoring certified incumbent operators over unqualified entrants.
For Market Incumbents: Extend predictive maintenance capabilities through IoT platform investments to displace labor-intensive scheduled interventions. Deepen certification pipelines for electrical and mechanical technicians to defend against emerging technology-enabled competitors. Prioritize backward integration into energy management system deployment to capture retrofit demand from SASO-mandated commercial building upgrades. For New Entrants and Emerging Players: Sensor-first predictive maintenance platforms offer wedge positioning against legacy scheduled-service incumbents in Riyadh's commercial office stock. Target Neom and Red Sea Project greenfield developments where digital-native service models face no legacy infrastructure constraints. Pursue hazardous environment specialization in Jubail and Yanbu industrial zones where technical certification scarcity limits incumbent capacity expansion. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with established SASO credential pipelines and healthcare facility relationships. Long-term viability hinges on technology-enabled service models that shift revenue from reactive labor to subscription-based remote monitoring. Watch IoT adoption rates in King Abdullah Financial District commercial assets as inflection indicator for market-wide predictive maintenance transition.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Enables condition-based maintenance contracts that compress routine labor hours across Riyadh commercial portfolios. |
| SASO Certification Investment | Creates enforceable differentiation for hard services bidding under Saudi Building Code mandates. |
| Healthcare Specialization | Captures privatization-driven contract flow from Vision 2030 hospital transfers to private operators. |
| Industrial Zone Expansion | Secures long-tenure technical maintenance agreements in Jubail and Yanbu petrochemical clusters. |
| Energy Management System Deployment | Addresses retrofit demand from municipal enforcement of commercial building efficiency benchmarks. |
Methodological Framework
Regulatory filings, municipal contract award databases, and energy efficiency compliance records formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with facilities management executives, hospital procurement directors, commercial property managers, and SASO certification officers triangulated against secondary data to validate service penetration rates and contract value estimates. Bottom-up aggregation of provider capacity and top-down demand modeling from construction pipeline data converged on segment-level forecasts.
Historical trendline analysis of contract award values and service mix evolution established baseline growth patterns across the projection horizon. Segmentation modeling incorporated service type, end-user vertical, technology adoption tier, and contract structure dimensions. CAGRs were derived from regression analysis of disclosed contract values and announced capacity expansions. Forecast inputs included Vision 2030 healthcare privatization timelines, mega-project construction completion schedules, and SASO enforcement intensity trajectories.
Several conditions sit outside the modeled scope, including abrupt regulatory enforcement changes, geopolitical disruption to equipment import channels, and accelerated automation adoption beyond current technology penetration curves. Forecasts reflect documented assumptions regarding labor cost inflation trajectories and certification pipeline expansion rates. Material deviation in Vision 2030 implementation pace or SASO penalty enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Brazil Facility Management Market
Facility Management
Moldova Facility Management Market
Facility Management
Sweden Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Italy Facility Management Services Market
Facility Management
North America Facilities Management Market
Facility Management
Austria Facility Management Market
Facility Management
China Facility Management Market
Facility Management
Malaysia Facility Management Market
Facility Management
Norway Facility Management Market
Facility Management
United States Facility Management Market
Facility Management
Albania Facility Management Market
Facility Management
Czech Republic Facility Management Market
Facility Management
Panama Facility Management Market
Facility Management
Netherlands Facility Management Market
Facility Management
Germany Facility Management Market