
 Asia Pacific Facility Management Market | 2026-2036
Asia Pacific Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Facility Management Market Outlook
The capability gap between asset-light platform operators and full-service integrators is reorganizing competitive tiers across the Asia Pacific Facility Management Market. CBRE Group, Inc. leverages its proprietary technology stack to anchor premium contracts in tier-one commercial towers. Sodexo S.A. differentiates through integrated workplace experience services that sustain long-term institutional relationships. Aeon Delight Co., Ltd. dominates Japan's precision maintenance segment through decades of specialized technical accreditation.
Facility management encompasses the coordinated delivery of hard services (mechanical, electrical, plumbing systems) and soft services (cleaning, security, groundskeeping) to ensure optimal building performance across operational lifecycles. The discipline requires compliance with fire safety protocols, HVAC efficiency benchmarks, and occupational health standards that govern occupant productivity and asset preservation. Cleaning and maintenance services command the largest revenue pools due to their non-discretionary nature and recurring contract structures, while building automation and energy management technology segments are expanding fastest as owners pursue operational expenditure reduction. The commercial end-user category absorbs the majority of outsourced FM spend, though healthcare facilities represent a higher-margin growth corridor where specialized infection control and equipment calibration expertise commands premium pricing.
Japan's METI enforces building energy efficiency standards that mandate smart metering integration, while Australia's NCC and India's ECO Niwas Samhita impose thermal performance requirements that reshape retrofit demand. China's MIIT dual carbon goals and GB standards for intelligent buildings further accelerate technology substitution across the region. Facility operators must monitor how fragmented national certification regimes affect cross-border service scalability and technology procurement decisions.
Market Dynamics
The convergence of Japan's METI-mandated smart metering requirements with Australia's NCC thermal performance codes is compressing retrofit timelines across commercial portfolios. Facility operators now face simultaneous pressure to digitize legacy building systems while meeting fragmented national certification regimes that complicate cross-border service scalability.
Growth Catalysts
- India's ECO Niwas Samhita:The building energy code mandates thermal efficiency benchmarks for new commercial construction, creating mandatory upgrade pathways for mechanical and electrical systems across metropolitan corridors.
- Healthcare outsourcing:Southeast Asian hospital networks are expanding bundled FM contracts that integrate infection control protocols with equipment calibration services, generating premium-margin revenue pools.
- Building automation convergence:Integration of IoT sensors with predictive maintenance algorithms is compressing response times for HVAC and electrical failures in tier-one commercial towers.
Market Restraints
- Skilled technician scarcity:Certification requirements for precision maintenance in Japan's JIS-accredited facilities outpace vocational training pipeline output, inflating labor costs.
- Copper and semiconductor input volatility:Smart building component manufacturing faces raw material price swings that destabilize equipment procurement budgets for FM technology upgrades.
- Fragmented national standards:China's GB intelligent building codes diverge from Australia's NCC protocols, forcing operators to maintain parallel compliance architectures that dilute economies of scale.
Strategic Opportunities
- Vietnam's emerging commercial corridor:Da Nang and Ho Chi Minh City office stock lacks mature FM service infrastructure, creating first-mover positioning for integrated workplace experience providers.
- China's dual carbon mandate:MIIT enforcement of carbon intensity targets accelerates demand for energy management technology substitution in provincial manufacturing facilities.
- Digital twin convergence:Overlay of BIM data with real-time sensor feeds enables predictive asset lifecycle modeling that commands premium pricing from institutional investors.
Industry Challenges
- Cross-certification complexity:Technicians holding Japan's specialized electrical maintenance licenses require supplemental accreditation to service equivalent systems in Australia, constraining workforce mobility.
- Legacy system integration:1990s-era building management systems in India's aging commercial stock resist API connectivity with modern IoT platforms, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Facility Management Market |
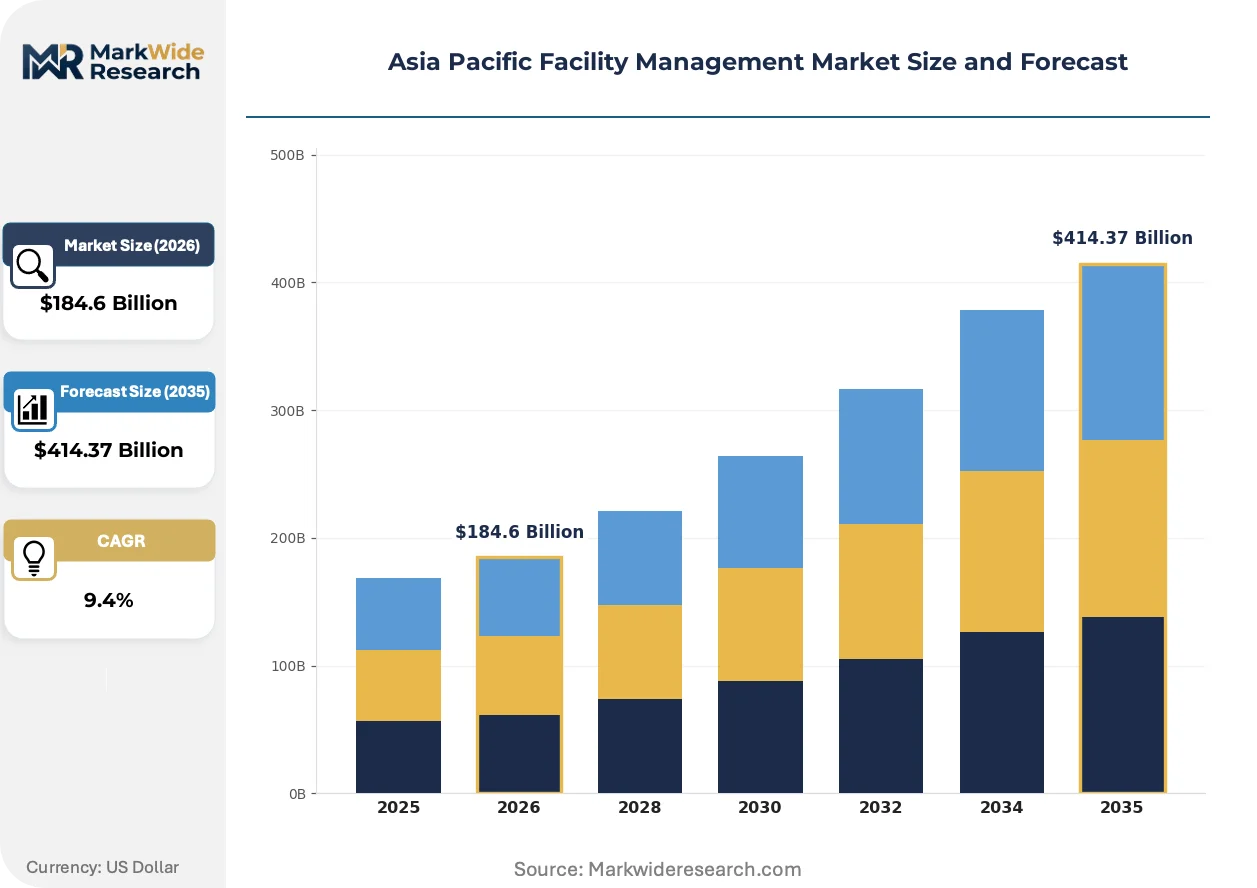
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $414.37 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Maintenance, Security, Landscaping End User: Commercial, Residential, Institutional, Industrial Technology: Building Automation, Energy Management, IoT, Software Solutions Application: Office Buildings, Retail Spaces, Healthcare Facilities, Educational Institutions |
| Companies Covered | CBRE Group, Inc., Jones Lang LaSalle Incorporated, Sodexo S.A., ISS Facility Services AG, Johnson Controls, Aeon Delight Co., Ltd., Aden Group, Group Atalian, C&W Facility Services Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Facility Management Market Strategic Shifts
Digital infrastructure is compressing the traditional separation between hard services maintenance and soft services delivery. Technology convergence is enabling unified service models that collapse operational silos and reshape contract structures.
Cloud-native building management platforms are supplanting on-premise SCADA installations in premium commercial assets. Singaporean and Australian REITs are accelerating adoption cycles from five-year replacement windows to eighteen-month upgrade sprints. This compression is enabling real-time energy optimization that reduces operational expenditure by consolidating previously discrete mechanical and electrical monitoring functions.
China's GB standards for intelligent buildings now mandate interoperability protocols that force proprietary system vendors to open API access. The regulation creates compliance-driven procurement criteria that favor modular technology architectures over locked ecosystems. Australian facility operators navigating NCC Section J energy efficiency requirements report accelerated substitution of legacy pneumatic controls with direct digital control systems to meet verification thresholds.
Asset owners are unbundling long-term bundled contracts into discrete service modules with separate performance metrics. Indian institutional investors in Mumbai and Bangalore commercial towers now procure cleaning, security, and mechanical maintenance through distinct RFP processes rather than single-source arrangements. This fragmentation concentrates pricing pressure on standardized service categories while preserving premiums for specialized technical accreditation.
Asia Pacific Facility Management Market Segmentation
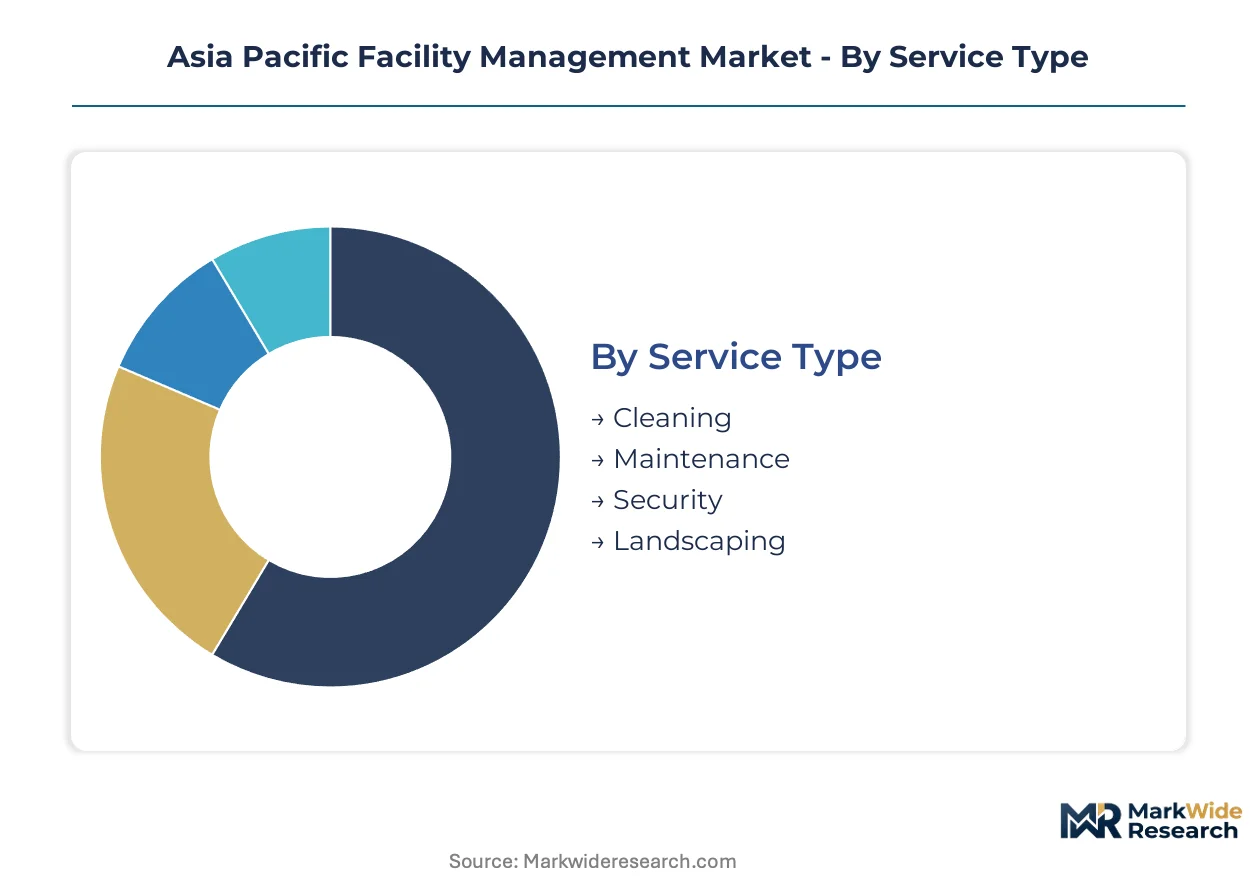
Segmentation in the Asia Pacific Facility Management Market reveals how contract structures diverge across service intensity and regulatory exposure. Service providers must align capability portfolios with distinct procurement channels that separate recurring maintenance from technology-integrated solutions.
Service Type:
Channel mix varies sharply between labor-intensive recurring services and technology-augmented offerings that flow through specialized integrators.
- Cleaning:Labor-intensive surface sanitation and waste management protocols dominate recurring contract volumes. Demand concentrates in India's metropolitan commercial corridors where institutional investors modernize aging office stock under ECO Niwas Samhita thermal efficiency mandates.
- Maintenance:Mechanical, electrical, and plumbing system upkeep requires JIS-accredited technician certification in Japan. Southeast Asian hospital networks are expanding bundled contracts that integrate equipment calibration with infection control protocols, generating premium-margin revenue pools.
- Security:Personnel-based access control and surveillance systems flow through facility management bundling.
- Landscaping:Grounds maintenance and exterior aesthetic services attach to premium commercial tower contracts.
Cleaning dominates installed base. Maintenance is where expansion concentrates.
End User:
Cost tier stratification separates standardized service procurement from specialized technical accreditation requirements.
- Commercial:Office towers and retail complexes absorb standardized cleaning and security through competitive bidding. Australia's NCC Section J energy efficiency requirements accelerate substitution of legacy pneumatic controls with direct digital systems.
- Healthcare:Infection control protocols and medical equipment calibration demand specialized certification. China's MIIT dual carbon goals and GB standards for intelligent buildings accelerate technology substitution in provincial hospital networks.
- Residential:Property management companies procure bundled soft services for multi-unit developments.
- Industrial:Manufacturing facilities require integrated hard services with predictive maintenance capabilities.
Commercial anchors contract volumes. Healthcare commands steepest expansion trajectory.
Technology:
Application maturity determines whether solutions deploy through retrofit channels or new construction specifications.
- Building Automation:Integrated HVAC, lighting, and access control systems mandate API interoperability under China's GB standards. Japan's METI enforces smart metering integration that compresses retrofit timelines across commercial portfolios.
- Energy Management:Real-time consumption monitoring and carbon accounting platforms align with Australia's NCC thermal performance codes. Singaporean and Australian REITs accelerate adoption cycles from five-year replacement windows to eighteen-month upgrade sprints.
- IoT:Sensor networks for predictive maintenance deploy through technology integrator channels.
- Software Solutions:Cloud-native platforms supplant on-premise SCADA installations in premium assets.
Building Automation dominates technology spend. Energy Management is where vendor positioning intensifies.
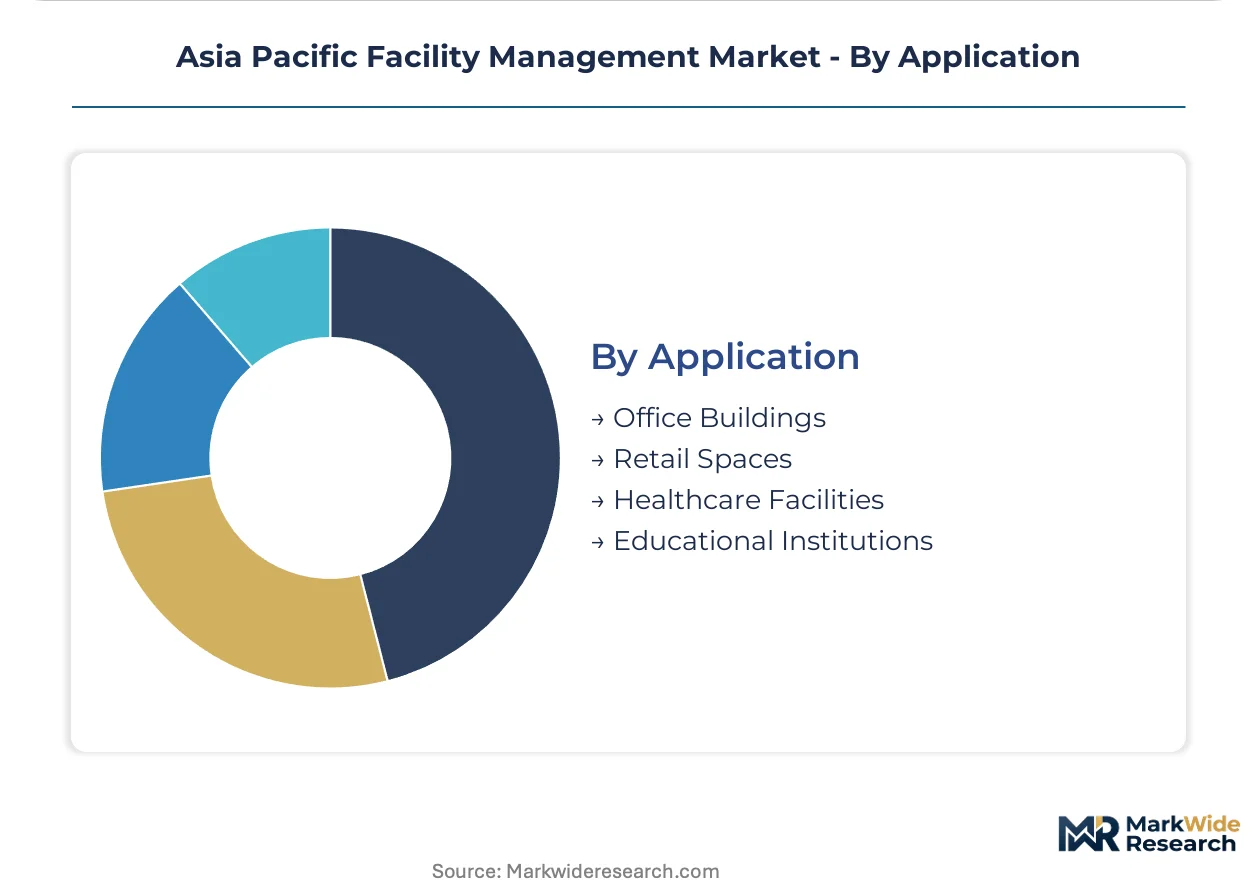
Application:
Geography within the Asia Pacific region shapes regulatory compliance requirements and service bundling complexity.
- Office Buildings:Tier-one commercial towers in Mumbai and Bangalore unbundle long-term contracts into discrete service modules. India's ECO Niwas Samhita mandates thermal efficiency benchmarks that create mandatory upgrade pathways for mechanical systems.
- Healthcare Facilities:Southeast Asian hospital networks lack mature FM infrastructure, creating first-mover positioning for integrated workplace experience providers. Specialized infection control expertise commands premium pricing.
- Retail Spaces:High-foot-traffic environments prioritize cleaning frequency and security visibility.
- Educational Institutions:Public sector procurement favors standardized service specifications with cost minimization emphasis.
Office Buildings anchor outsourced spend. Healthcare Facilities represent the highest-margin growth corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan's precision maintenance segment while Indian metropolitan corridors absorb standardized services through competitive bidding. This asymmetry reflects divergent regulatory maturity and certification requirements across the region.
Japan
Demand for JIS-accredited technical certification outpaces vocational training pipeline output, inflating labor costs for precision maintenance contracts. METI-mandated smart metering integration compresses retrofit timelines across commercial portfolios. Tokyo and Osaka anchor premium service pricing for tier-one commercial towers.
India
Institutional investors in Mumbai and Bangalore modernize aging office stock under ECO Niwas Samhita thermal efficiency mandates. The building energy code creates mandatory upgrade pathways for mechanical and electrical systems. Metropolitan commercial corridors absorb the majority of outsourced facility management spend.
China
MIIT enforcement of dual carbon goals accelerates demand for energy management technology substitution in provincial manufacturing facilities. GB standards for intelligent buildings mandate API interoperability protocols that reshape procurement criteria. Yangtze River Delta and Pearl River Delta clusters drive technology-integrated contract growth.
Australia
NCC Section J energy efficiency requirements accelerate substitution of legacy pneumatic controls with direct digital systems. REITs compress adoption cycles from five-year replacement windows to eighteen-month upgrade sprints. Sydney and Melbourne commercial towers prioritize real-time energy optimization platforms.
Vietnam
Da Nang and Ho Chi Minh City office stock lacks mature facility management infrastructure, creating first-mover positioning for integrated workplace experience providers. Rapid commercial construction outpaces specialized service provider entry. Emerging commercial corridors attract bundled contract expansion from regional operators.
Asia Pacific Facility Management Market Competitive Environment
Concentration sits with full-service integrators holding proprietary technology stacks and specialized accreditation portfolios. The market structure divides between asset-light platform operators and technical specialists with decades of certification depth. Three archetypes dominate: premium commercial tower integrators, healthcare-focused infection control specialists, and precision maintenance accreditation holders. Competitive moves center on technology licensing partnerships and geographic expansion into underserved emerging corridors.
Within the premium integrator tier, CBRE Group, Inc. and Jones Lang LaSalle Incorporated occupy positions anchored by proprietary building management platforms. Sodexo S.A. exemplifies the workplace experience specialization archetype through integrated service bundling. Aeon Delight Co., Ltd. represents Japan's precision maintenance segment with technical accreditation depth.
| Leading Market Players |
|---|
| CBRE Group, Inc. |
| Jones Lang LaSalle Incorporated |
| Sodexo S.A. |
| ISS Facility Services AG |
| Johnson Controls |
| Aeon Delight Co., Ltd. |
| Aden Group |
| Group Atalian |
| C&W Facility Services Inc. |
| Others |
Value Chain & Pricing Dynamics
Direct digital control systems replacing legacy pneumatic controls across Australia's NCC-mandated retrofits simultaneously concentrate procurement demand on East Asian component manufacturers and compress margin structures for standardized installation services. This substitution dynamic reshapes where value accumulates in the supply chain and how facility operators negotiate long-term service contracts.
Pricing Analysis
The customization-premium spread between JIS-accredited precision maintenance and standardized cleaning contracts exceeds threefold across Japan's tier-one commercial towers. Three-tier pricing structure across premium, standard, and economy levels dominates contract structures, with certification grade and geographic delivery cost as primary differentiation drivers. Cost compression in India's metropolitan corridors intensifies because institutional investors unbundle services into discrete RFP processes. Healthcare facilities demonstrate least price sensitivity due to infection control liability exposure.
Supply Chain Analysis
Port congestion on the Shanghai-Singapore trade lane elevates inbound logistics costs for smart building components arriving from Chinese manufacturing clusters. Supply concentrates in China, South Korea, and Japan for IoT sensors, direct digital control modules, and energy management software. Raw material dependencies include copper wiring, semiconductor chips, and rare earth elements for sensor manufacturing. Single-source vulnerability around Taiwan-based chip fabrication creates procurement risk. Distribution runs through technology integrator channels that bundle hardware with ongoing service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against in-house facility management teams building captive technical capabilities. Incumbents must demonstrate irreplaceable value through proprietary technology and certification depth.
For Market Incumbents: Compound technical accreditation portfolios through JIS and GB standards compliance to deepen moats against platform competitors. Acquire specialized infection control capabilities in Southeast Asian healthcare corridors before hospital networks develop internal expertise. Prioritize vertical integration into predictive maintenance software to capture recurring revenue streams. For New Entrants and Emerging Players: Vietnam's emerging commercial corridor in Da Nang and Ho Chi Minh City offers white-space positioning where integrated workplace experience providers remain scarce. Target unbundled security and landscaping contracts in India's fragmented metropolitan markets where incumbents lack service density. Pursue technology licensing partnerships with established building automation vendors rather than proprietary platform development. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional operators holding concentrated healthcare contracts but lacking technology integration capabilities. Five-to-ten year viability hinges on successful digital transformation of legacy service portfolios. Monitor GB standards enforcement velocity in China as inflection indicator for technology substitution demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | Accelerates API interoperability compliance under China's GB intelligent building mandates. |
| JIS Accreditation Investment | Captures premium pricing in Japan's precision maintenance segment where technician scarcity inflates margins. |
| Healthcare Contract Acquisition | Secures infection control expertise that commands pricing power in Southeast Asian hospital networks. |
| Energy Management Platform Launch | Aligns with Australia's NCC Section J requirements and Singaporean REIT upgrade cycles. |
| Vietnam Geographic Expansion | Establishes first-mover positioning in Da Nang and Ho Chi Minh City commercial corridors. |
Study Parameters
A standing panel of facility management directors, REIT asset managers, healthcare procurement officers, and building automation engineers provided ongoing calibration against secondary data sources including METI enforcement notices, NCC compliance databases, ECO Niwas Samhita implementation records, and MIIT carbon intensity disclosures. Primary interviews with technology integrators and vocational training institutions combined with customs data on smart building component imports enabled bottom-up and top-down triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type intensity, end-user regulatory exposure, technology deployment maturity, and application geography. CAGRs derived from historical contract value trajectories and policy-mandated upgrade timelines incorporate India's ECO Niwas Samhita thermal efficiency thresholds and China's dual carbon enforcement mechanisms.
Forecasts assume regulatory continuity in Japan's METI smart metering mandates, Australia's NCC thermal codes, and China's GB interoperability standards; material policy shifts would require re-modeling. Semiconductor supply volatility and copper price swings constitute specific risk factors that could revise technology adoption timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Japan Facility Management Market
Facility Management
United States Facility Management Market
Facility Management
Saudi Arabia Facility Management Market
Facility Management
Facility Management Services Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
North America Hard Facility Management Market
Facility Management
Latvia Facility Management Market
Facility Management
Africa Facility Management Market
Facility Management
Australia Facility Management Market
Facility Management
Europe Hard Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
Moldova Facility Management Market
Facility Management
Global Facility Management Software Market
Facility Management
Slovenia Facility Management Market
Facility Management
Taiwan Facility Management Services Market