
 Italy Facility Management Services Market | 2026-2036
Italy Facility Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Facility Management Services Market Insights
Healthcare end users is collapsing reliance on in-house facility teams across Italy's northern hospital networks. Sodexo Facilities Management Services leverages integrated service bundles to capture these outsourcing transitions. Rekeep SpA anchors public-sector contracts through its dominance in Rome's municipal infrastructure. ISS Facility Services competes on technology-led maintenance protocols for premium corporate clients in Milan.
Facility management services encompass the coordinated delivery of hard services (mechanical, electrical, plumbing maintenance) and soft services (cleaning, security, catering) to ensure operational continuity of built environments, typically governed by SLA frameworks specifying response times, uptime thresholds, and energy performance benchmarks. Cleaning services lead contract value among service-type segments due to labor intensity and frequency requirements, while IoT Solutions within technology segments represents the fastest-expanding margin pool as predictive maintenance replaces scheduled interventions. Integrated contracts across contract-type segments concentrate profitability among vendors capable of bundling hard and soft service lines under unified accountability.
Italy's National Agency for the Evaluation of Universities and Research Institutes enforces public building efficiency standards that shape procurement specifications for state-funded facilities. The European Union's Energy Performance of Buildings Directive, transposed through Italian legislative decree, mandates systematic energy audits that expand demand for technology-enabled maintenance services. Stakeholders must monitor how Italy's evolving green public procurement criteria will reweight vendor selection toward carbon-accounting capabilities and circular service models.
Market Dynamics
Italy's Superbonus 110% energy retrofit incentive is compressing procurement timelines for integrated facility contracts as building owners race against subsidy expiration deadlines. This fiscal mechanism is forcing rapid vendor consolidation around full-service providers capable of bundling hard infrastructure upgrades with ongoing soft services.
Growth Catalysts
- Superbonus 110% retrofit mandates:Property owners across Lombardy and Lazio are outsourcing entire building modernization programs to capture expiring tax credits, accelerating contract bundling.
- Healthcare outsourcing waves:Northern Italy's hospital clusters are dismantling in-house maintenance departments in favor of multi-service SLAs covering clinical and non-clinical infrastructure.
- IoT-enabled predictive maintenance:Sensor networks are displacing scheduled interventions, creating premium pricing power for technology-integrated service providers in Milan's commercial corridor.
Market Restraints
- Skilled technician scarcity:Italy's aging HVAC and electrical specialist workforce is constraining service expansion without costly apprenticeship programs or immigration waivers.
- Energy input volatility:Natural gas price fluctuations are compressing margins on thermal system maintenance contracts with fixed pricing terms.
- Regional procurement fragmentation:Municipal tendering rules vary between Rome, Milan, and Turin, forcing vendors to maintain parallel compliance infrastructures.
Strategic Opportunities
- Southern Italy facility modernization:Naples and Bari public infrastructure zones remain undersupplied with integrated FM services relative to northern saturation levels.
- Circular service model mandates:Italy's evolving green public procurement criteria are reweighting vendor selection toward waste-reduction and material-recovery capabilities.
- Digital twin convergence:Building information modeling fused with real-time sensor feeds is opening premium contract tiers for predictive space optimization.
Industry Challenges
- Multi-vendor SLA orchestration:Clients demand unified accountability across fragmented subcontractor networks, requiring costly integration platforms.
- Certification timeline compression:Energy auditor qualifications under EU Energy Performance of Buildings Directive transposition are creating bottlenecks for service expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Facility Management Services Market |
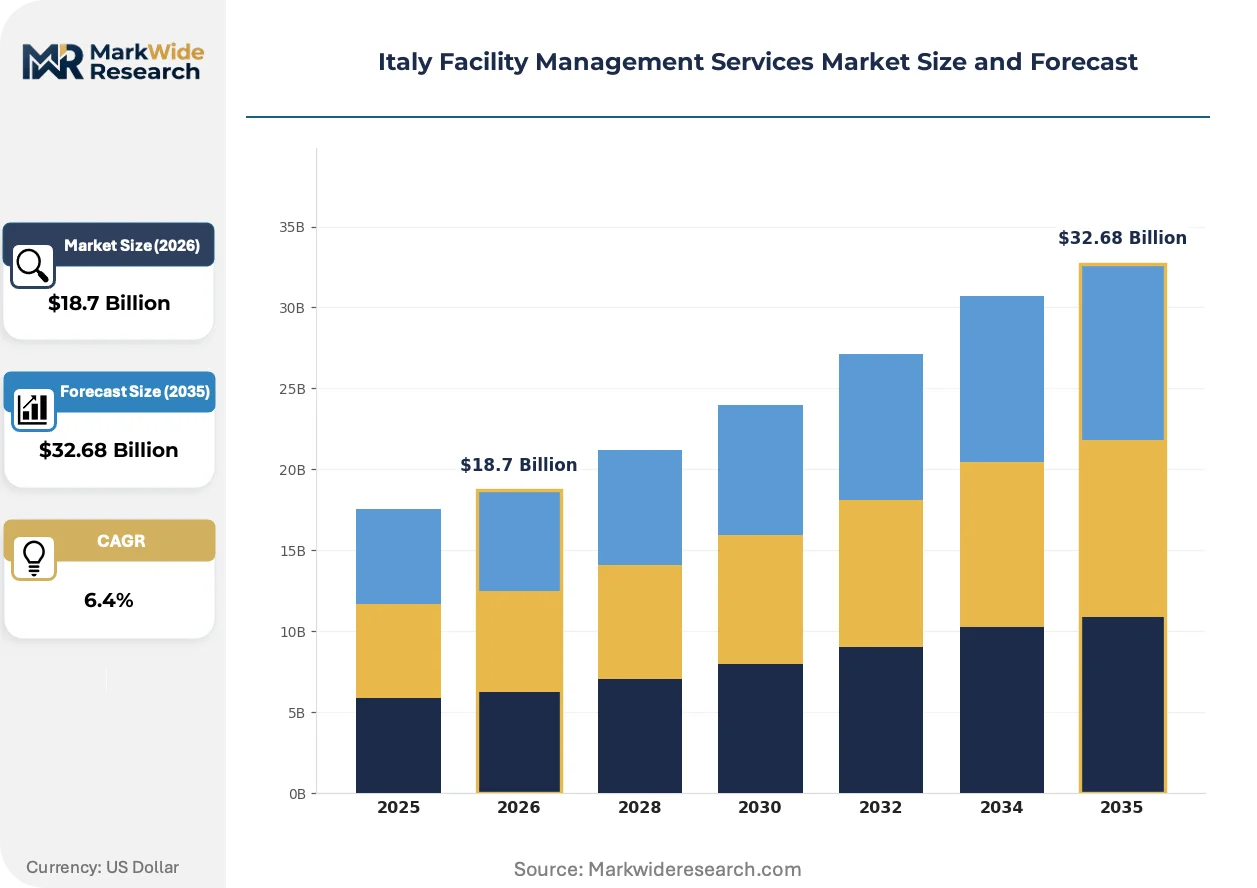
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Landscaping End User: Corporate, Education, Healthcare, Retail Technology: Cloud-Based, IoT Solutions, Software, Mobile Apps Contract Type: Single-Service, Integrated, Outsourced, Managed |
| Companies Covered | Rekeep SpA, Sodexo Facilities Management Services, ATLAS I.F.M. S.R.L., ISS Facility Services, CBRE Group, Compass Group PLC, Euro & Promos Facility Management S.P.A., NAZCA Facility Management, Olly Services SRL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Facility Management Services Market Trends and Innovations
Facility management in Italy is pivoting from cost-center containment to energy-performance accountability as regulatory frameworks harden operational benchmarks. Technology infusion and procurement model evolution are separating premium integrated providers from commodity maintenance vendors.
Building management systems is bifurcating the competitive landscape between sensor-native platforms and legacy scheduled-maintenance operations. Premium corporate clients in Milan's financial district are adopting real-time environmental monitoring with sub-hour response guarantees. This technology compression is eliminating mid-tier vendors lacking capital for IoT infrastructure deployment.
Italy's transposition of the EU Energy Performance of Buildings Directive is mandating systematic energy audits with public disclosure requirements. Commercial property owners now face penalty structures for non-compliance, expanding demand for certified audit-and-remediation service bundles. Rome's municipal infrastructure zone is experiencing the steepest compliance-driven contract growth.
Integrated service contracting is displacing single-service procurement across Italy's public healthcare networks. Hospital clusters in Emilia-Romagna and Veneto are consolidating cleaning, security, and engineering maintenance under unified vendor accountability with outcome-based penalty clauses. This procurement evolution is most advanced in Lombardy's regional health authority tenders.
Italy Facility Management Services Market Segmentation
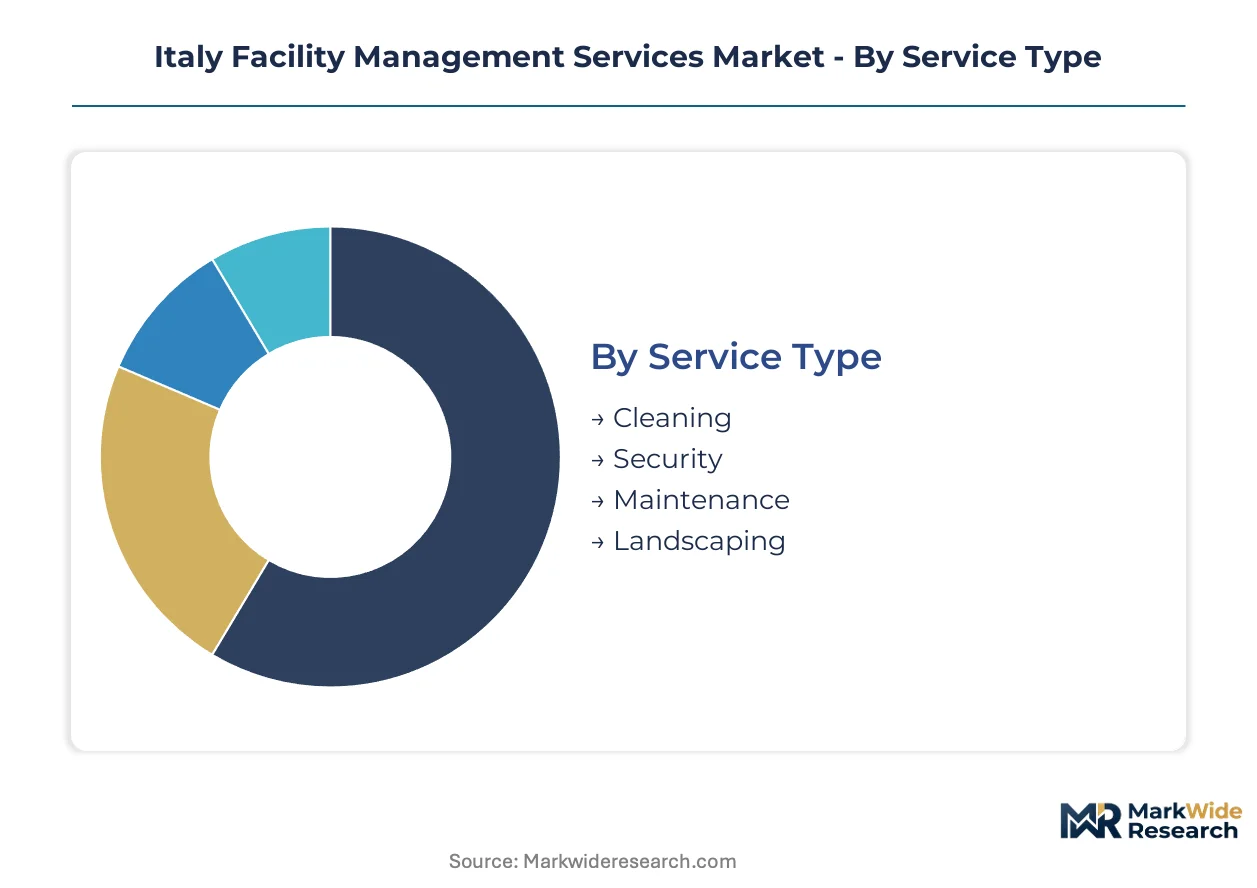
Service bundling patterns and technology adoption curves diverge sharply across Italy's facility management landscape. Procurement specifications from ANVIN (National Agency for Public Contracts) and regional health authorities reshape how vendors position across segment boundaries.
Service Type:
Italy's EU Energy Performance of Buildings Directive transposition creates tiered compliance burdens that segment service procurement by technical intensity and labor certification requirements.
- Cleaning:Labor-intensive operations with specialized protocols for healthcare environments dominate contract value. Northern Italy's hospital clusters in Lombardy and Veneto outsource clinical-grade sanitation under strict infection-control SLAs mandated by regional health authorities.
- Maintenance:Hard services spanning HVAC, electrical, and plumbing systems carry the highest technician certification barriers. Superbonus 110% retrofit deadlines concentrate demand in Lombardy and Lazio as property owners bundle energy upgrades with ongoing technical maintenance.
- Security:Personnel-based guarding and access control systems serve commercial and public infrastructure zones with varying regulatory oversight.
- Landscaping:Grounds maintenance and green space management rounds out soft service portfolios, typically appended to integrated municipal contracts.
Established volume favors Cleaning; emerging adoption favors Maintenance.
End User:
Procurement centralization varies dramatically by sector, with public healthcare tendering consolidation diverging from fragmented corporate decision-making.
- Healthcare:Hospital clusters dismantle in-house facility teams across Emilia-Romagna and Veneto. Regional health authorities consolidate multi-service contracts covering clinical infrastructure and non-clinical support under unified vendor accountability.
- Corporate:Premium office assets in Milan's financial district demand technology-integrated service bundles with real-time environmental monitoring. ISS Facility Services and Sodexo compete on IoT-enabled response guarantees for this segment.
- Education:Universities and research institutes operate under ANVUR efficiency standards that shape maintenance specifications for state-funded facilities.
- Retail:Distributed store networks favor standardized service levels across multiple locations, with less procurement sophistication than healthcare or corporate segments.
Contract consolidation concentrates in Healthcare; margin expansion concentrates in Corporate.
Technology:
Capital deployment requirements separate sensor-native platforms from legacy operations, with Milan's commercial corridor driving premium technology adoption.
- IoT Solutions:Sensor networks enable predictive maintenance protocols that displace scheduled interventions. Real-time equipment monitoring commands premium pricing in Milan's premium commercial properties where uptime guarantees carry financial penalties.
- Cloud-Based:Centralized data platforms aggregate facility performance metrics across distributed asset portfolios. Vendors leverage these systems to offer outcome-based contracts with transparent KPI dashboards.
- Software:Computerized maintenance management systems track work orders, asset lifecycles, and compliance documentation for mid-tier operations.
- Mobile Apps:Field technician enablement tools streamline dispatch and service verification without requiring heavy infrastructure investment.
Margin concentration sits with IoT Solutions; accessibility concentration sits with Mobile Apps.
Contract Type:
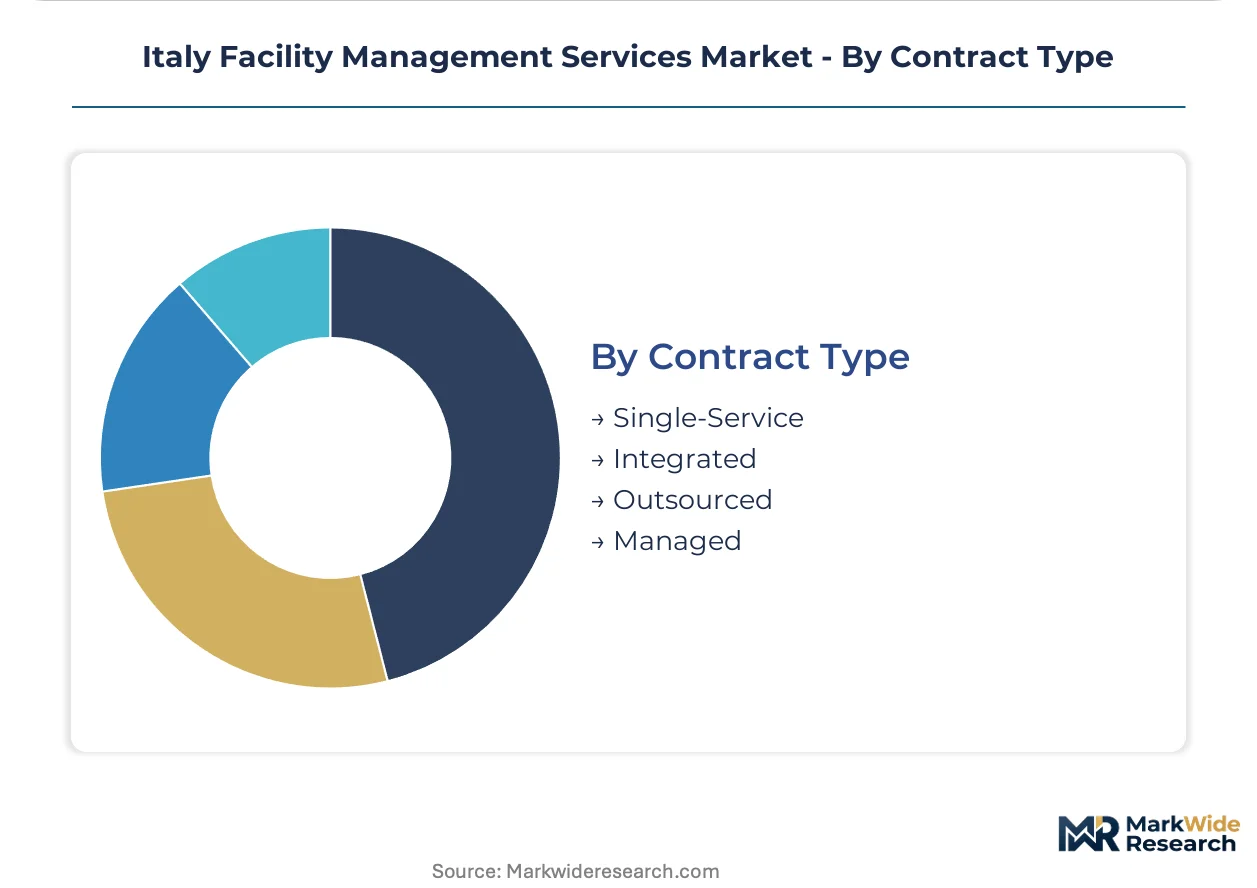
Accountability structures reshape vendor selection as clients migrate from fragmented procurement toward unified service responsibility.
- Integrated:Bundled hard and soft services under single-vendor accountability concentrate profitability among full-service providers. Superbonus 110% retrofit mandates accelerate this shift as building owners seek one-stop modernization partners.
- Managed:Outcome-based arrangements with penalty clauses for non-performance align vendor incentives with operational targets. Rome's municipal infrastructure zone experiments with these structures for public building portfolios.
- Single-Service:Discrete procurement of individual service lines persists in fragmented municipal tendering and small commercial properties.
- Outsourced:Traditional third-party contracting without outcome guarantees retains share in cost-sensitive segments.
Profit migration favors Integrated; transition velocity favors Managed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor capability clusters around northern industrial corridors where Superbonus retrofit deadlines and healthcare consolidation drive contract velocity. Southern regions present expansion frontiers with undersupplied municipal infrastructure and lagging technology adoption.
Lombardy
Milan's financial district anchors premium corporate demand for IoT-integrated service bundles with real-time monitoring guarantees. The EU Energy Performance of Buildings Directive transposition through Italian legislative decree mandates systematic energy audits for commercial properties over 500 square meters. Hospital clusters in Bergamo and Brescia dismantle in-house maintenance teams in favor of multi-service SLAs covering clinical infrastructure.
Lazio
Rome's municipal infrastructure zone experiences steepest compliance-driven contract growth under public building efficiency standards. Italy's National Agency for the Evaluation of Universities and Research Institutes enforces maintenance specifications that shape procurement for state-funded research facilities. The Superbonus 110% incentive compresses procurement timelines as property owners race against subsidy expiration deadlines.
Veneto
Regional health authority tenders in Verona and Padua consolidate cleaning, security, and engineering maintenance under unified vendor accountability. The EU Energy Performance of Buildings Directive mandates systematic energy audits with public disclosure requirements. Hospital clusters dismantle in-house facility teams across the region in favor of outcome-based contracts with penalty clauses.
Emilia-Romagna
Bologna's university and research institute concentration operates under ANVUR efficiency standards that shape maintenance specifications. Healthcare outsourcing waves dismantle in-house maintenance departments across regional hospital networks. Modena and Parma manufacturing corridors generate industrial facility management demand distinct from commercial and healthcare segments.
Campania
Naples public infrastructure zones remain undersupplied with integrated FM services relative to northern saturation levels. Municipal tendering rules vary from northern counterparts, forcing vendors to maintain parallel compliance infrastructures. The gap between technology adoption curves in southern versus northern regions creates expansion opportunities for full-service providers.
Italy Facility Management Services Market Competitive Landscape
Concentration sits with integrated service providers capable of bundling hard infrastructure upgrades with ongoing soft services. The vendor base stratifies between multinational platforms with capital for IoT deployment and regional specialists anchored in public-sector relationships. Two archetypes dominate: technology-led premium service providers and relationship-driven public infrastructure incumbents. Competitive moves center on vendor consolidation around Superbonus-driven retrofit bundling and rapid certification acquisition for EU Energy Performance of Buildings Directive compliance.
Among Italy-based operators, Rekeep SpA and ATLAS I.F.M. S.R.L. occupy positions within the public infrastructure archetype, while Sodexo Facilities Management Services represents the multinational integrated service platform. ISS Facility Services exemplifies the technology-led premium segment competing on IoT-enabled maintenance protocols. These named entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Rekeep SpA |
| Sodexo Facilities Management Services |
| ATLAS I.F.M. S.R.L. |
| ISS Facility Services |
| CBRE Group |
| Compass Group PLC |
| Euro & Promos Facility Management S.P.A. |
| NAZCA Facility Management |
| Olly Services SRL |
| Others |
Pricing and Supply Chain Analysis
Italy's EU Energy Performance of Buildings Directive transposition gates both vendor qualification and price differentiation simultaneously, as energy auditor certification requirements segment providers into compliance-capable tiers with corresponding rate structures. Property owners in Lombardy and Lazio face compressed procurement timelines under Superbonus 110% deadlines, forcing rapid trade-offs between certified premium providers and uncertified economy operators.
Pricing Analysis
The EU Energy Performance of Buildings Directive dictates the pricing tier structure across Italy's facility management landscape, separating certified energy audit-and-remediation bundles from commodity maintenance contracts. Pricing stratifies across premium IoT-integrated providers, standard multi-service vendors, and economy single-service operators based on technician certification levels and technology deployment depth. Cost compression in economy tiers is intensifying because natural gas price volatility erodes fixed-price thermal maintenance margins. Corporate clients in Milan's financial district exhibit the lowest price sensitivity due to uptime guarantee penalties, while municipal tendering in southern regions remains most cost-driven.
Supply Chain Analysis
Technician certification bottlenecks under Italy's National Agency for Public Contracts standards create supply chokepoints that constrain service expansion across all regions. The vendor base draws from Germany, France, and domestic Italian training pipelines for HVAC and electrical specialist labor. Critical dependencies include sensor hardware from East Asian manufacturers, energy audit software platforms, and subcontractor networks for peak demand surging. Single-source vulnerability concentrates in certified energy auditor pools where EU directive transposition timelines outpace qualification throughput. Distribution runs through regional hub-and-spoke models anchored in Milan, Rome, and Naples, with last-mile service delivery executed via localized technician depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's facility management market rewards vendors possessing both hard infrastructure upgrade capabilities and soft service delivery networks, yet the intersection of these skill sets remains scarce relative to contract demand acceleration. The widening gap between Superbonus-driven modernization mandates and qualified provider supply creates asymmetric opportunity windows.
For Market Incumbents: Compound technology infrastructure investments to capture predictive maintenance premium tiers before mid-tier vendors achieve IoT deployment parity. Acquire certified energy audit capabilities under EU Energy Performance of Buildings Directive timelines to defend against compliance-native entrants. Vertical integration into technician apprenticeship programs mitigates skilled labor scarcity threatening expansion capacity. For New Entrants and Emerging Players: Southern Italy's municipal infrastructure zones present service-layer gaps where integrated FM penetration lags northern saturation by substantial margins. Naples and Bari public building portfolios offer the most penetrable geography given undersupplied vendor presence and evolving green procurement criteria. A go-to-market angle anchored in circular service models—waste reduction and material recovery capabilities—aligns with Rome's procurement evolution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across IoT-enabled service tiers as sensor network deployment becomes table stakes for premium contract eligibility. Long-term viability favors platforms combining hard infrastructure upgrade execution with ongoing soft service accountability under unified SLAs. Acquisition target archetypes include regional specialists with Rome municipal relationships and uncertified technology assets. The signal to watch is Superbonus program extension or contraction decisions affecting retrofit contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Energy Auditor Certification Acquisition | EU Energy Performance of Buildings Directive mandates create bottlenecked qualification premiums for compliant vendors. |
| IoT Sensor Network Deployment | Predictive maintenance protocols displace scheduled interventions in Milan's premium commercial property corridor. |
| Technician Apprenticeship Program Buildout | Italy's aging HVAC specialist workforce constrains expansion without immigration waiver navigation or training investment. |
| Southern Italy Geographic Expansion | Naples and Bari municipal zones remain undersupplied relative to northern saturation levels. |
| Circular Service Model Development | Green public procurement criteria reweight vendor selection toward waste-reduction and material-recovery capabilities. |
Research Methodology
A standing panel of facility management contract directors, regional health authority procurement leads, energy auditor certification bodies, and municipal tendering officers provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation from ANVUR efficiency standards documentation, EU Energy Performance of Buildings Directive transposition decrees, and regional health authority tender databases. Bottom-up contract value aggregation across service types, end users, and geographies triangulated against top-down market sizing from macroeconomic indicators and construction activity indices.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including service type intensity, end-user procurement centralization, technology deployment tier, and contract accountability structure. CAGRs derived from fitted growth curves incorporating Superbonus incentive phase-out assumptions, healthcare outsourcing velocity, and IoT adoption S-curves. Industry-specific forecast inputs captured energy retrofit subsidy elasticity and skilled technician supply constraints.
Underlying assumptions cover subsidy program continuity, certification timeline adherence, and natural gas price stabilization, with deviation risk concentrated in regulatory extension decisions and immigration policy shifts affecting technician supply. Practitioners should keep alternative scenarios live as Italy's green public procurement criteria and EU directive enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
France Facility Management Market
Facility Management
Africa Facility Management Market
Facility Management
Slovak Republic Facility Management Market
Facility Management
Global Facility Management Software Market
Facility Management
Panama Facility Management Market
Facility Management
Malaysia Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
Malta Facility Management Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Luxembourg Facility Management Market
Facility Management
Global Unified Facility Management Market
Facility Management
Canada Facility Management Market
Facility Management
Asia Pacific Facility Management Market
Facility Management
Moldova Facility Management Market
Facility Management
Europe Hard Facility Management Market