
 Austria Facility Management Market | 2026-2036
Austria Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Facility Management Market Outlook
Asset-light leasing and project finance models is narrowing the capital barrier for mid-tier FM providers seeking public-sector contracts. ISS Facility Services GmbH leverages its pan-European scale to dominate bundled service packages across Vienna's commercial core. Apleona GmbH anchors its position through deep vertical specialization in healthcare and pharmaceutical facility operations. STRABAG Property and Facility Services GmbH extends its construction heritage into integrated lifecycle FM, competing on single-source accountability for infrastructure assets.
Austria Facility Management encompasses the coordinated delivery of hard services (mechanical, electrical, HVAC maintenance) and soft services (cleaning, security, groundskeeping) to ensure operational continuity, regulatory compliance, and asset longevity across built environments. The discipline integrates preventive maintenance scheduling, energy monitoring protocols, and workspace compliance auditing to sustain building performance at target service levels. Cleaning Services and Maintenance Services together occupy the largest revenue share, reflecting Austria's aging building stock and stringent hygiene mandates in Healthcare Facilities. IoT Solutions and Building Automation represent the fastest-expanding technology cluster, where margin pools concentrate around predictive maintenance platforms and real-time energy optimization dashboards.
Austrian FM operators navigate oversight from the national building code enforcement apparatus, EU Energy Performance of Buildings Directive transpositions, and Vienna's municipal procurement standards that mandate social and environmental criteria. These frameworks shape demand by requiring certified energy auditors, documented carbon reporting, and minimum wage compliance in public contracts. Stakeholders must monitor how forthcoming EU CSRD disclosure rules will cascade into FM contract specifications and supplier qualification thresholds.
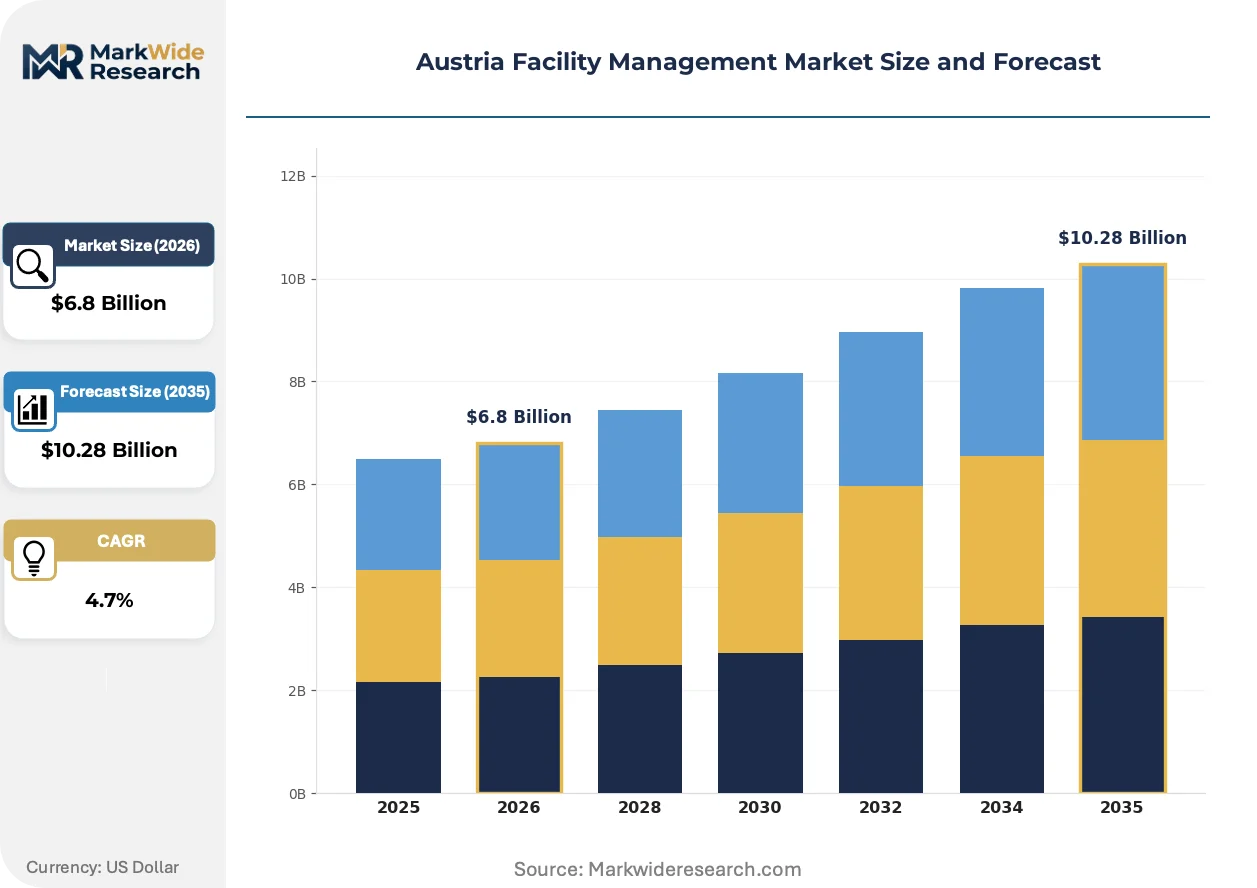
Market Dynamics
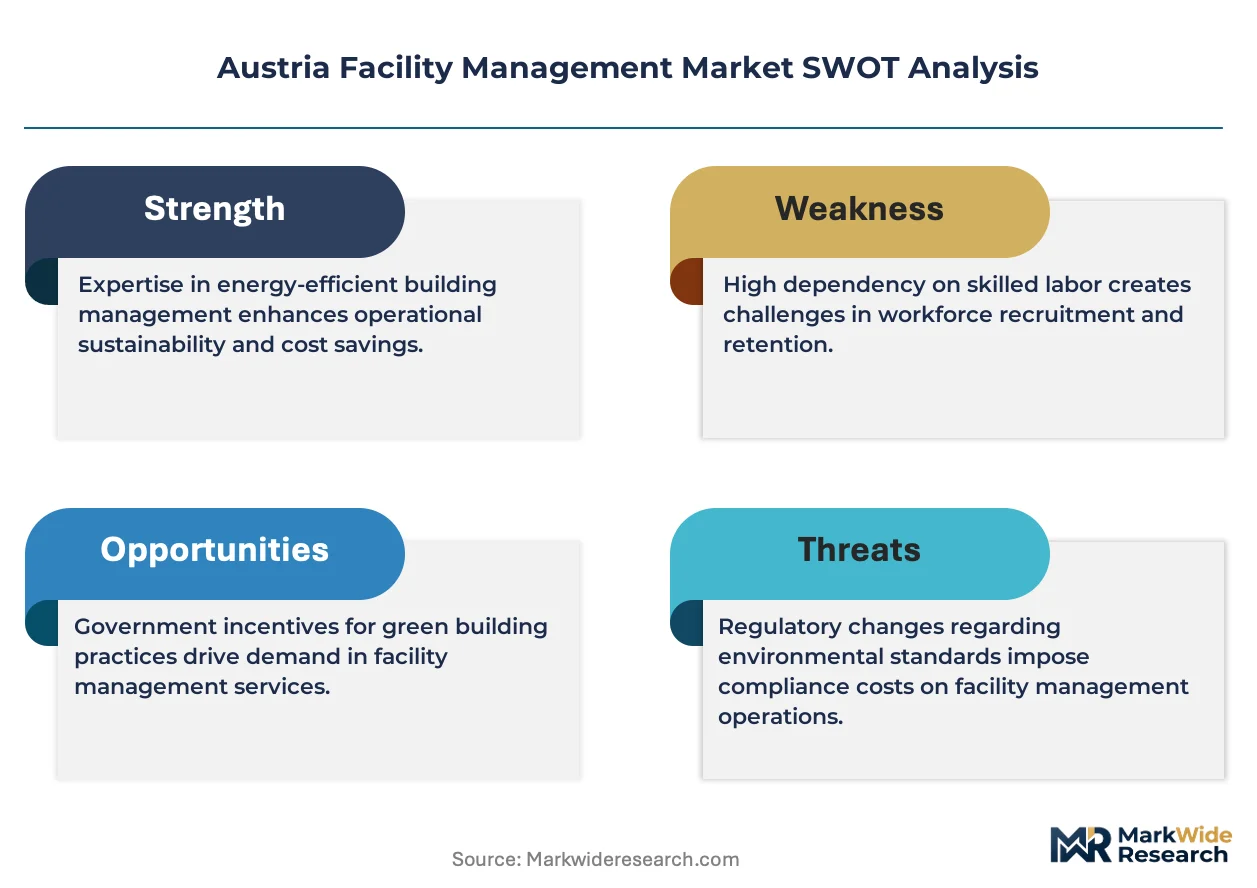
The EU Green Deal's building efficiency mandates are compressing operational margins while forcing capital redeployment toward energy retrofitting and carbon monitoring infrastructure across Austrian facility portfolios.
Growth Catalysts
- Healthcare outsourcing acceleration:Austrian hospitals and pharmaceutical manufacturing campuses are unbundling non-core operations into multi-year integrated FM contracts. Vienna's medical district expansion creates concentrated demand for certified hygiene protocols and GMP-compliant maintenance.
- EU Energy Performance of Buildings Directive transposition:Austria's national implementation mandates building energy certificates and renovation roadmaps for commercial stock over 1000 square meters. This forces asset owners toward professionalized FM operators with documented carbon accounting capabilities.
- Building automation convergence:IoT sensor networks and predictive analytics platforms are penetrating mid-tier commercial properties in Graz and Linz. Federal state energy efficiency subsidies lower adoption barriers for automated HVAC and lighting control systems.
Market Restraints
- Skilled technician scarcity:Austria's dual vocational training pipeline produces insufficient certified HVAC and electrical maintenance specialists. FM providers compete with construction and manufacturing sectors for the same Mechatroniker and Elektrotechniker labor pool.
- Input cost volatility:Natural gas and electricity price fluctuations directly impact heating and cooling service margins. Energy-intensive hard services face margin compression when fixed-price contracts encounter spot market spikes.
- Public procurement fragmentation:Each of Austria's nine federal states maintains distinct tendering platforms and social criteria weightings. Standardized service packaging across Burgenland, Tyrol, and Vorarlberg requires redundant compliance investments.
Strategic Opportunities
- Life sciences vertical expansion:Biotech manufacturing clusters around Vienna and Lower Austria require specialized cleanroom maintenance and validated equipment calibration. FM operators with GMP and FDA inspection experience capture premium pricing in this compliance-intensive segment.
- CSRD-driven disclosure services:The EU Corporate Sustainability Reporting Directive mandates granular building-level emissions data from 2024 onward. FM providers can bundle real-time energy monitoring with automated regulatory report generation for real estate investment trusts.
- Photovoltaic integration:Rooftop solar deployment across Austrian industrial parks creates demand for combined FM and asset management services. Providers offering predictive inverter maintenance and performance guarantees differentiate from pure-play O&M contractors.
Industry Challenges
- Legacy BMS integration complexity:Decades-old building management systems in Vienna's historic commercial core resist seamless IoT retrofitting. FM technicians must maintain parallel analog and digital control infrastructures.
- Certification timeline compression:ISO 41001 facility management certification and energy auditor credentials require substantial training investment. Smaller regional providers struggle to staff certified personnel before contract qualification deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Facility Management Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Security Services, Maintenance Services, Landscaping Services End User: Commercial Buildings, Healthcare Facilities, Educational Institutions, Residential Complexes Technology: IoT Solutions, CMMS, Energy Management Systems, Building Automation Distribution Channel: Direct Sales, Online Platforms, Third-Party Distributors, Partnerships |
| Companies Covered | ISS Facility Services GmbH, Apleona GmbH, STRABAG Property and Facility Services GmbH, Sodexo Österreich, SIMACEK Facility Management Group GmbH, Dussmann Service Osterreich GmbH, VINCI Energies Austria, Equans Austria, Leadec Austria, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Facility Management Market Strategic Shifts
Digital infrastructure is penetrating asset-intensive service delivery, compressing response times while elevating data transparency requirements in Austrian procurement specifications.
Digital twin technology is hybridizing physical building operations with real-time simulation capabilities. Vienna's largest commercial landlords deploy sensor-fed virtual replicas to stress-test HVAC configurations before seasonal peaks. This convergence is compressing commissioning timelines for new properties while enabling remote diagnostic triage that reduces emergency technician dispatches.
The EU CSRD disclosure framework mandates granular Scope 1 and 2 emissions reporting from Austrian real estate portfolios exceeding 500 employees. Asset managers now require FM contractors to deliver automated carbon data feeds compatible with assurance-grade audit trails. Healthcare and financial services tenants in Vienna's Innere Stadt and Leopoldstadt districts face the earliest compliance deadlines.
Integrated service bundling is displacing single-service procurement across Austrian public-sector tenders. Municipalities in Styria and Upper Austria now specify combined hard and soft service contracts with unified KPI dashboards. This consolidation favors operators with cross-functional workforce flexibility over specialized cleaning or security contractors.
Austria Facility Management Market Segmentation
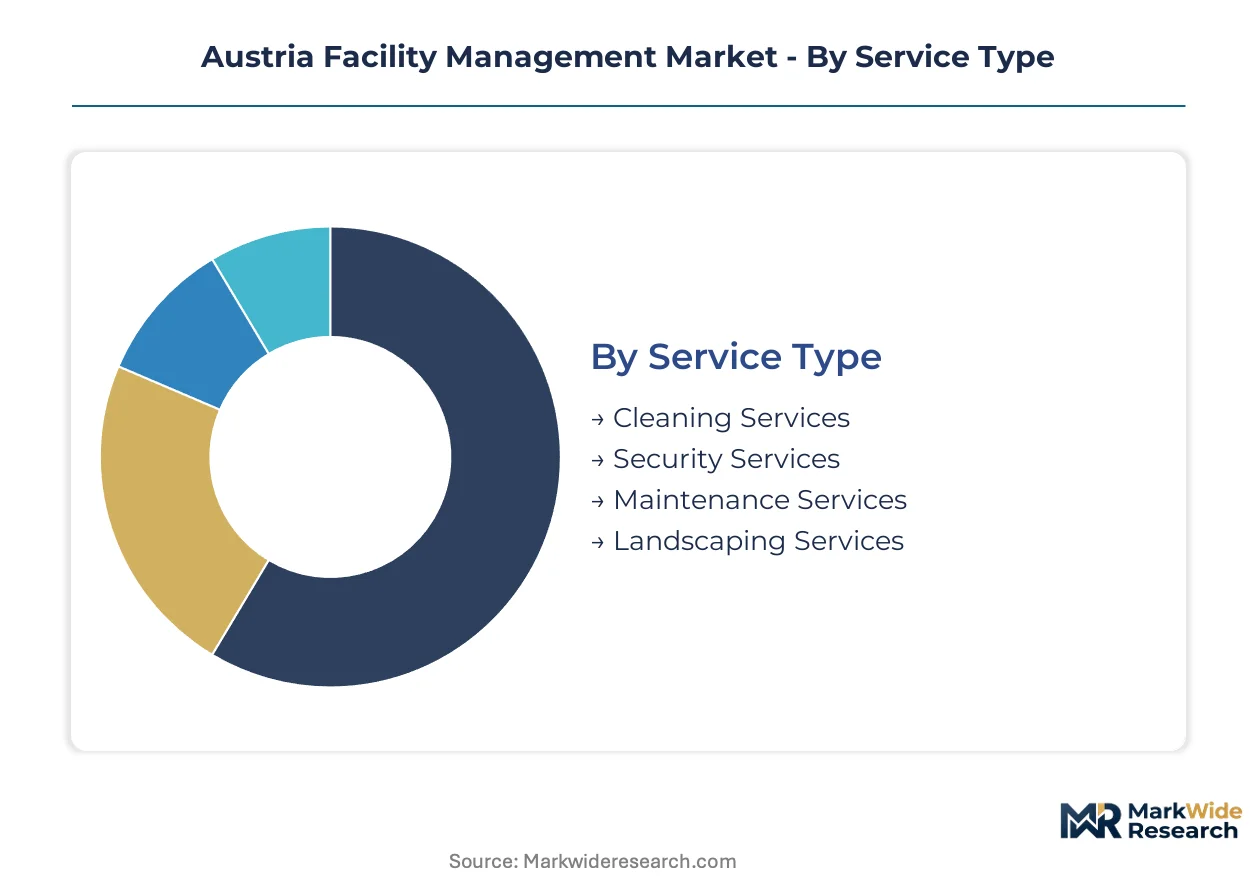
Facility management in Austria fragments across service delivery modes, end-use verticals, and technology integration levels. Each segmentation axis reveals distinct margin structures and procurement behaviors that shape competitive positioning across Vienna's commercial core and federal state markets.
Service Type:
Mature operational categories dominate contract value, while emerging specializations capture premium pricing in compliance-intensive environments.
- Cleaning Services:Encompasses daily janitorial operations, disinfection protocols, and waste management across commercial and healthcare properties. Vienna's medical district expansion and stringent hygiene mandates in pharmaceutical manufacturing drive demand for ISO-certified operators with documented infection control procedures.
- Maintenance Services:Covers preventive and corrective maintenance for mechanical, electrical, HVAC, and building envelope systems. Aging building stock in Graz and Linz concentrates demand for certified HVAC technicians capable of EU Energy Performance of Buildings Directive compliance reporting.
- Security Services:Includes manned guarding, access control, and surveillance system monitoring for commercial and residential assets.
- Landscaping Services:Delivers grounds maintenance, seasonal planting, and snow removal for corporate campuses and municipal properties.
Maintenance Services handles the majority of throughput; Cleaning Services is the fastest mover on share.
End User:
Application intensity varies sharply across property types, with regulatory pressure and asset complexity determining outsourcing depth.
- Healthcare Facilities:Hospitals, clinics, and pharmaceutical manufacturing campuses requiring GMP-compliant maintenance and validated equipment calibration. Vienna's biotech corridor and Lower Austria's life sciences clusters generate concentrated demand for specialized FM operators with FDA and EMA inspection experience.
- Commercial Buildings:Office towers, retail centers, and logistics facilities across Vienna, Graz, and Linz. EU Green Deal efficiency mandates and CSRD disclosure requirements push asset owners toward integrated FM contracts with bundled energy monitoring and carbon reporting.
- Educational Institutions:Universities, technical colleges, and primary-secondary schools under federal state procurement frameworks.
- Residential Complexes:Multi-unit housing developments and mixed-use properties requiring standardized soft services delivery.
Commercial Buildings absorbs the largest contract volume; Healthcare Facilities is expanding most quickly on outsourcing penetration.
Technology:
Technology adoption clusters around compliance automation and operational efficiency, with federal subsidies accelerating mid-market penetration.
- IoT Solutions:Sensor networks for occupancy detection, air quality monitoring, and predictive equipment diagnostics. Federal state energy efficiency programs in Styria and Upper Austria reduce adoption barriers for automated HVAC and lighting control retrofits in mid-tier commercial properties.
- Building Automation:Integrated control systems for HVAC, lighting, and security with centralized dashboard management. Vienna's largest commercial landlords deploy sensor-fed digital twins to stress-test configurations before seasonal demand peaks.
- CMMS:Computerized maintenance management systems for work order tracking and asset lifecycle documentation.
- Energy Management Systems:Platforms for real-time consumption monitoring and automated carbon reporting aligned with CSRD requirements.
IoT Solutions commands the dominant deployment share; Building Automation is climbing the fastest on new construction integration.
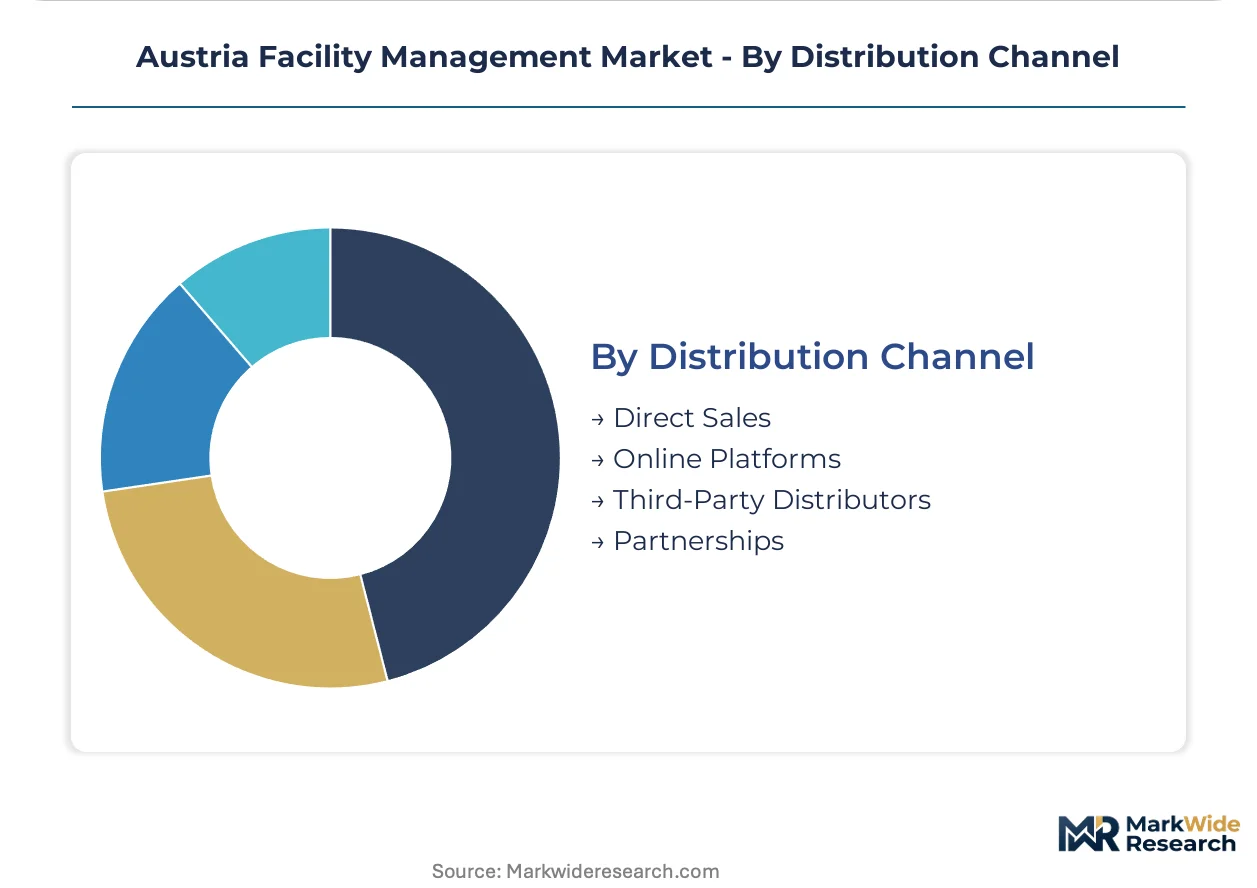
Distribution Channel:
Channel structure reflects procurement complexity, with public-sector fragmentation favoring relationship-heavy engagement models.
- Direct Sales:Provider-led contract negotiation with asset owners and facility managers. Large integrated operators leverage existing relationships with Vienna's municipal procurement offices and federal state tendering platforms.
- Partnerships:Strategic alliances with construction firms, property developers, and real estate investment trusts. STRABAG Property and Facility Services GmbH extends its construction heritage into integrated lifecycle FM through captive project pipelines.
- Online Platforms:Digital tendering portals and service matching platforms for standardized service procurement.
- Third-Party Distributors:Intermediary networks connecting regional FM providers with property management companies.
Direct Sales captures the bulk of contract value; Partnerships is gaining share fastest on integrated project delivery models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large commercial landlords and municipal procurement offices dominate FM contract origination across Austria's federal states. Vienna's medical district expansion and Graz's industrial automation clusters concentrate specialized service demand. Federal energy efficiency subsidies reshape adoption patterns in mid-tier commercial markets.
Vienna
Vienna anchors Austria's FM demand through its medical district biotech corridor and historic commercial core. The city's municipal procurement standards mandate social and environmental criteria in public contracts. Vienna's Innere Stadt and Leopoldstadt districts face the earliest CSRD compliance deadlines for building-level emissions reporting.
Lower Austria
Lower Austria hosts concentrated pharmaceutical manufacturing campuses requiring GMP-compliant maintenance and validated equipment calibration. The federal state's life sciences clusters generate demand for specialized operators with FDA and EMA inspection experience. Tulln and Krems anchor biotech facility expansion driving integrated FM outsourcing.
Styria
Styria's federal energy efficiency programs reduce adoption barriers for automated HVAC and lighting control retrofits in mid-tier commercial properties. Graz concentrates industrial automation demand where IoT sensor networks penetrate manufacturing facilities. The state's municipalities specify combined hard and soft service contracts with unified KPI dashboards.
Upper Austria
Upper Austria maintains distinct tendering platforms with social criteria weightings that favor integrated service bundling. Linz anchors demand for certified HVAC technicians capable of EU Energy Performance of Buildings Directive compliance reporting. The state's procurement fragmentation requires redundant compliance investments from standardized service providers.
Tyrol and Vorarlberg
Tyrol and Vorarlberg present procurement fragmentation challenges with separate tendering platforms from eastern federal states. Alpine tourism infrastructure creates seasonal demand variation for facilities maintenance. Innsbruck and Bregenz concentrate commercial property management requiring flexible workforce deployment across hard and soft service categories.
Austria Facility Management Market Competitive Environment
Channel-controlling players compete with product-specialist players across Austria's fragmented federal procurement landscape. The vendor base clusters around three tiers: pan-European scale operators capturing bundled contracts, construction-heritage firms extending into lifecycle FM, and regional specialists dominating single-service niches. Dominant competitive moves include strategic partnerships with real estate investment trusts and portfolio diversification into energy monitoring and carbon reporting services.
Within the integrated service tier, ISS Facility Services GmbH exemplifies pan-European scale deployment across Vienna's commercial core. Apleona GmbH occupies a position anchored through healthcare and pharmaceutical vertical specialization. STRABAG Property and Facility Services GmbH represents construction-heritage extension into single-source lifecycle accountability for infrastructure assets.
| Leading Market Players |
|---|
| ISS Facility Services GmbH |
| Apleona GmbH |
| STRABAG Property and Facility Services GmbH |
| Sodexo Österreich |
| SIMACEK Facility Management Group GmbH |
| Dussmann Service Osterreich GmbH |
| VINCI Energies Austria |
| Equans Austria |
| Leadec Austria |
| Others |
Value Chain & Pricing Dynamics
German HVAC component manufacturing concentrates upstream supply for Austrian FM operators, concentrating margin capture with certified system integrators capable of ISO 41001-compliant service bundling. This feedstock geography shapes pricing power across Vienna's commercial core, where energy monitoring capabilities command premium positioning against commodity maintenance providers.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers in Austrian FM contracting. Three-tier pricing structure across ISO 41001-certified premium, standard commercial, and economy maintenance levels reflects differentiation by energy auditor credentials and GMP compliance depth. Cost compression in economy-tier cleaning and security services is intensifying because federal state procurement platforms favor lowest-bidder selection. Healthcare facilities and pharmaceutical campuses show least price sensitivity due to FDA and EMA inspection requirements, while municipal contracts in Styria and Upper Austria exhibit highest bid-pressure elasticity.
Supply Chain Analysis
HVAC compressors and control modules feed from German, Italian, and Czech manufacturing hubs into Austrian FM inventory networks. Predictive maintenance platforms draw from cloud infrastructure anchored in Frankfurt and Amsterdam data centers, while IoT sensor hardware sources from Chinese and Taiwanese component suppliers. Single-source vulnerability concentrates around specialized cleanroom filtration systems for pharmaceutical applications. Distribution runs through direct sales teams for large integrated contracts and regional distributor networks for standardized service procurement across federal state tendering platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Austria's FM market sits at a platform-economics inflection where building automation interoperability standards are consolidating vendor ecosystems around centralized energy data exchange protocols.
For Market Incumbents: Pre-empt margin erosion from pure-play IoT entrants by acquiring certified energy auditor capabilities before EU CSRD disclosure mandates harden qualification thresholds. Captive control over predictive maintenance algorithm development defends against software-defined disintermediation from cross-border platform operators. For New Entrants and Emerging Players: Tyrol and Vorarlberg's fragmented procurement landscape offers white-space entry for operators capable of unified tendering compliance across Alpine tourism infrastructure. Specialized cleanroom maintenance for Lower Austria's biotech corridor presents the most penetrable premium segment, accessible through GMP certification investment and FDA inspection experience positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier FM operators holding federal state contract backlogs but lacking carbon reporting automation capabilities. Long-term viability hinges on CSRD-compliant service bundling penetration; watch for accelerated municipal tender specifications mandating real-time energy data feeds as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 41001 Certification Investment | Federal state procurement offices in Upper Austria now mandate certified facility management credentials for contract qualification. |
| Energy Monitoring Platform Integration | EU CSRD disclosure requirements force real-time carbon data feeds into REIT and pharmaceutical asset manager dashboards. |
| Healthcare Vertical Specialization | Vienna's biotech corridor expansion creates demand for GMP-compliant maintenance operators with FDA inspection experience. |
| Photovoltaic Asset Management Bundling | Rooftop solar deployment across industrial parks requires combined FM and predictive inverter maintenance capabilities. |
| Digital Twin Technology Deployment | Sensor-fed virtual replicas enable Vienna commercial landlords to stress-test HVAC configurations before seasonal demand peaks. |
Study Parameters
A spread of perspectives from facility management executives, municipal procurement officers, energy auditor certification bodies, and pharmaceutical plant engineering heads converged on the working assumptions shaping this analysis. Primary field engagement combined structured interviews with secondary validation against EU Energy Performance of Buildings Directive transposition documents, federal state tendering platform records, and building automation system vendor technical specifications. Bottom-up contract value aggregation across service type segments was triangulated against top-down macroeconomic indicators for the Austrian built environment sector.
Demand-supply balance dynamics across the projection horizon were modeled through analytical framework approaches integrating service type segmentation, end-use vertical intensity, and technology adoption curve assumptions. Segmentation dimensions span hard versus soft service delivery, healthcare versus commercial versus public sector application, and IoT-enabled versus conventional operational models. CAGRs were derived from fitted trend extrapolation validated against historical outsourcing penetration rates and regulatory compliance timeline compression.
Practitioners should monitor EU CSRD implementation granularity and federal state energy subsidy program renewals for early signals of forecast revision. Cross-checking against Austrian Federal Economic Chamber construction sector employment data and HVAC technician vocational training pipeline outputs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Germany Facility Management Market
Facility Management
Latvia Facility Management Market
Facility Management
Serbia Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
China Facility Management Market
Facility Management
Asia Pacific Facility Management Market
Facility Management
Refrigerated Warehousing Market
Facility Management
Slovenia Facility Management Market
Facility Management
Egypt Facility Management Market
Facility Management
Finland Facility Management Market
Facility Management
Warehouse Management Service Market
Facility Management
Slovak Republic Facility Management Market
Facility Management
Global Unified Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Brazil Facility Management Market
Facility Management
Soft Facility Management Market