
 Thailand Facility Management Market | 2026-2036
Thailand Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Facility Management Market Insights
Capital-intensity divergence between integrated platform operators and single-service vendors is redrawing competitive boundaries in Thailand's facility management sector. CBRE (Thailand) Co., Ltd leverages its proprietary technology stack to anchor premium commercial contracts in Bangkok's central business district. Sodexo Services (Thailand) Co., Ltd sustains deep operational expertise across healthcare and education campuses, while IFS Facility Services Co., Ltd specializes in industrial maintenance for Eastern Economic Corridor manufacturing facilities.
Facility management encompasses the integrated coordination of building operations, maintenance, security, and environmental services to ensure optimal functionality, safety, and efficiency of physical assets across commercial, industrial, and institutional properties. The discipline applies technical parameters including energy performance benchmarking, preventive maintenance scheduling cycles, and indoor air quality compliance thresholds to sustain asset lifecycle value. Cleaning and maintenance services command the largest revenue share within service type segmentation, reflecting Thailand's aging building stock and tightening hygiene protocols in hospitality and healthcare settings. IoT Solutions and CAFM Software represent the fastest-expanding technology category, as real-time asset monitoring and predictive analytics displace reactive maintenance models and unlock measurable labor efficiencies for portfolio operators.
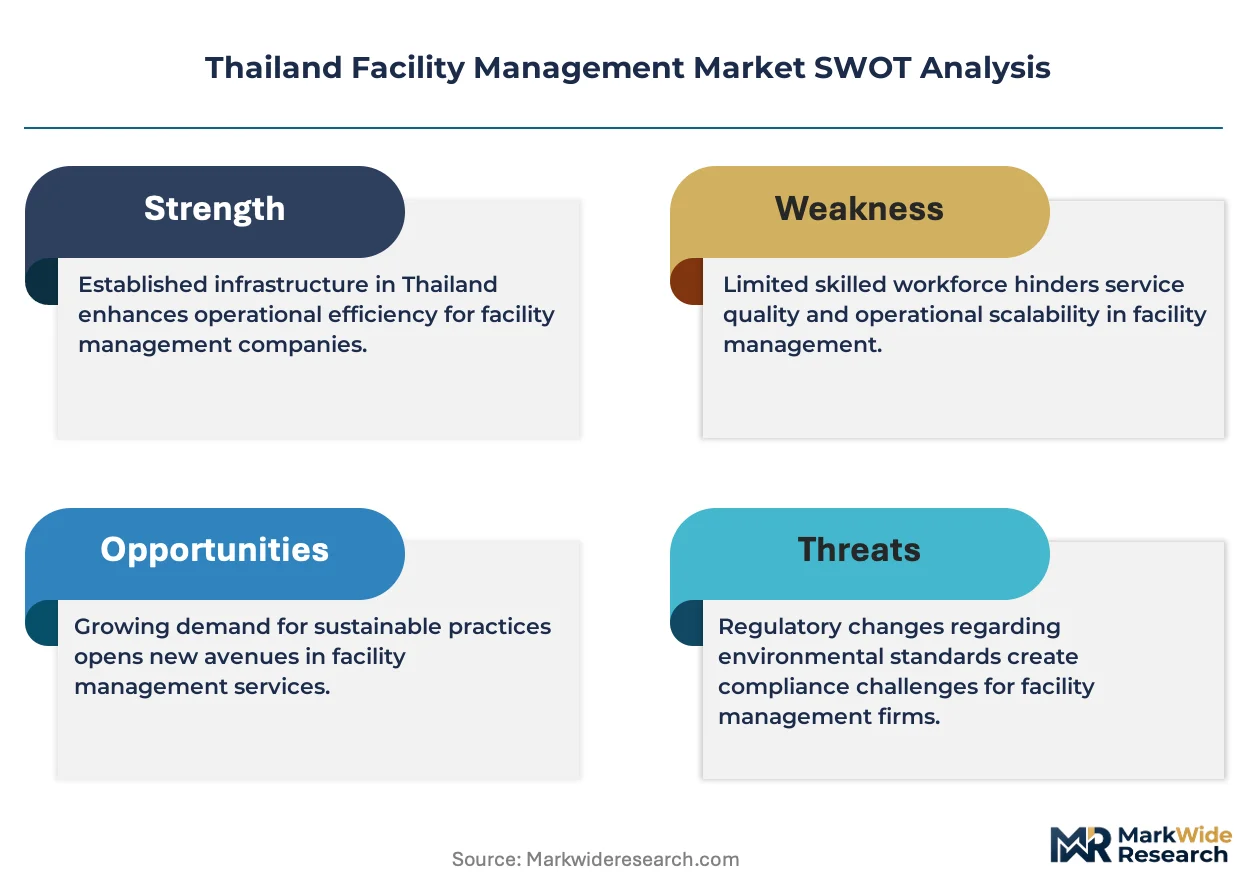
Thailand's Department of Public Works and Town & Country Planning enforces building safety standards that mandate periodic structural audits, directly expanding technical maintenance demand across commercial portfolios. The country's Ministry of Energy, through Building Energy Code revisions, compels large facilities to deploy automated energy management systems, creating technology upgrade pathways for FM providers. Stakeholders must monitor how Thailand's evolving green building certification requirements and provincial environmental regulations reshape contract specifications and vendor qualification criteria.
Market Dynamics
Thailand's Building Energy Code amendments are compressing service delivery timelines and forcing portfolio operators to retrofit aging assets with automated energy management systems, fundamentally altering contract specifications and vendor qualification thresholds.
Growth Catalysts
- Building Energy Code Compliance:Thailand's Ministry of Energy mandates automated energy management systems for large facilities, creating technology upgrade pathways for FM providers serving commercial portfolios in Bangkok.
- Healthcare Campus Expansion:Bangkok and Chiang Mai hospitals are outsourcing infection control compliance to specialized FM operators, expanding technical maintenance demand across medical infrastructure.
- Eastern Economic Corridor Industrialization:Manufacturing estates in Rayong, Chonburi, and Chachoengsao are consolidating fragmented vendor arrangements into integrated FM contracts.
Market Restraints
- Skilled Technician Scarcity:Thailand's technical vocational pipeline produces insufficient certified HVAC and building automation specialists, constraining service expansion capacity.
- Imported Equipment Dependency:Smart building sensors and IoT hardware concentrate in supply chains originating from China and Germany, exposing operators to currency fluctuation and logistics disruption.
- Legacy System Interoperability:Proprietary protocols in existing building management systems block seamless integration with new CAFM platforms, forcing costly middleware development.
Strategic Opportunities
- Chiang Mai Secondary Hub:Northern Thailand's healthcare and education campus clusters remain underpenetrated by integrated FM platforms, offering first-mover expansion potential.
- Green Building Certification Tailwind:Thailand's evolving TREES (Thailand's Rating of Energy and Environmental Sustainability) standards reshape contract specifications, favoring vendors with carbon accounting capabilities.
- IoT-CAFM Convergence:Real-time asset monitoring platforms merging with predictive analytics software unlock measurable labor efficiencies for portfolio operators managing distributed industrial estates.
Industry Challenges
- BAS Technician Certification Bottlenecks:Thailand's limited accredited training centers for building automation system specialists delay workforce scaling for smart retrofit projects.
- Multi-Vendor Integration Complexity:Facilities managing heterogeneous equipment fleets from Schneider, Siemens, and Honeywell face protocol fragmentation when deploying unified monitoring dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Facility Management Market |
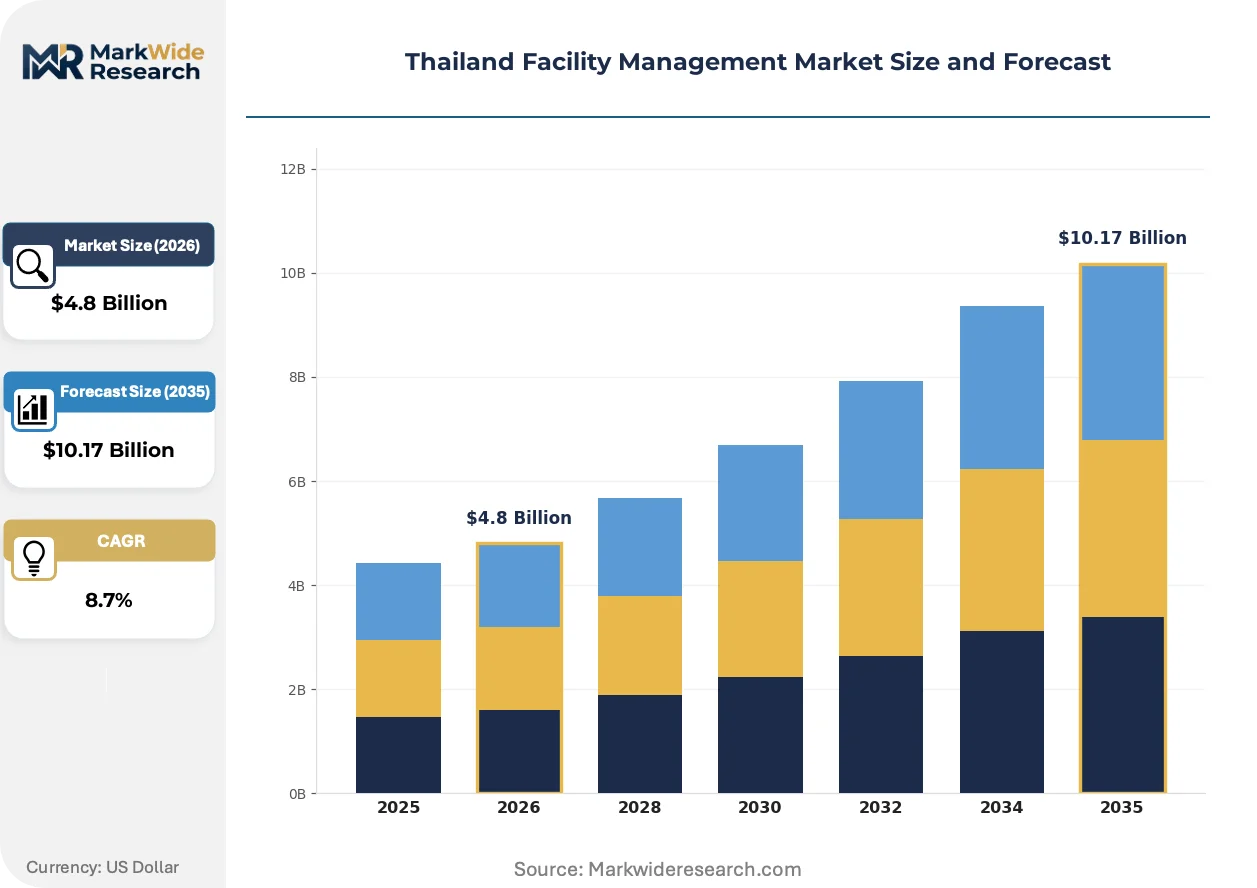
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Maintenance, Security, Landscaping End User: Commercial, Healthcare, Education, Hospitality Technology: IoT Solutions, CAFM Software, Automated Systems, Green Building Technologies Contract Type: Outsourced, In-House, Integrated, Hybrid |
| Companies Covered | CBRE (Thailand) Co., Ltd, IFS Facility Services Co., Ltd, PCS Security and Facility Services Limited, G4S Security Services (Thailand) Limited, Sodexo Services (Thailand) Co., Ltd, Jones Lang LaSalle (Thailand) Ltd, Cushman & Wakefield Services (Thailand) Co., Ltd, Savills (Thailand) Limited, KJTN Engineering Co., Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Facility Management Market Trends and Innovations
Sensor hardware and software analytics are compressing maintenance response cycles and enabling predictive intervention models that displace scheduled preventive regimes across Thailand's commercial and industrial portfolios.
Edge computing nodes deployed across building systems are miniaturizing data processing footprints, enabling real-time anomaly detection without cloud latency. Industrial estates in the Eastern Economic Corridor are adopting these devices fastest, driven by 24/7 manufacturing uptime requirements. This technology is miniaturizing the hardware-to-software cost ratio in FM contracts, shifting value capture toward analytics providers.
Thailand's Department of Public Works and Town & Country Planning now mandates periodic structural audits for commercial buildings above specified floor areas, expanding technical maintenance demand. The regulation compels portfolio owners to retain certified engineering inspectors, creating recurring revenue streams for qualified FM operators. Bangkok's central business district faces the steepest compliance deadlines, accelerating contract awards to audit-capable vendors.
Asset owners are unbundling long-term bundled service agreements into discrete performance-based modules with separate KPIs and penalty structures. Industrial manufacturing tenants in Rayong and Chonburi now procure energy management, cleaning, and security through distinct contracts rather than single integrated awards. This pattern concentrates most visibly in the Eastern Economic Corridor, where multinational anchor tenants impose procurement templates from regional headquarters in Singapore and Japan.
Thailand Facility Management Market Segmentation
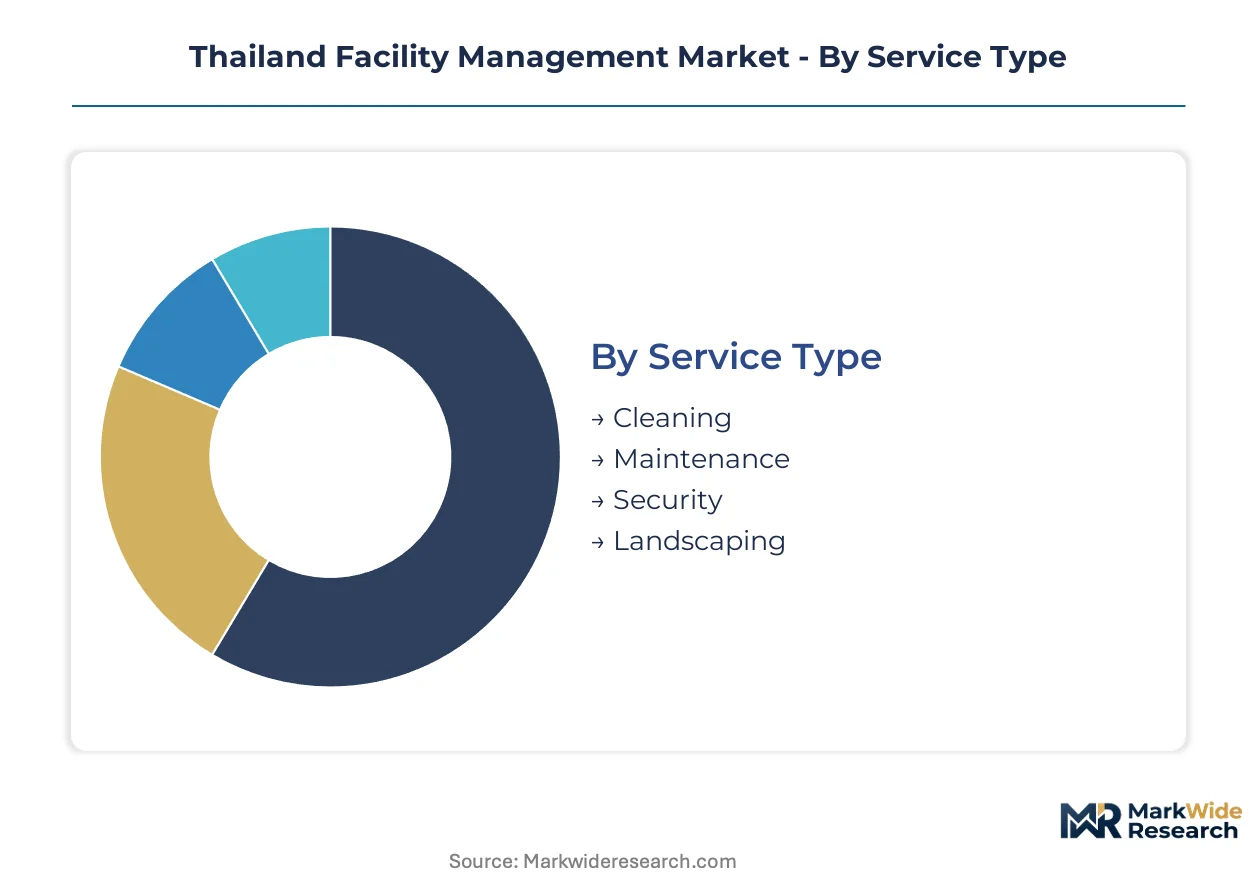
Thailand's facility management market fragments along service delivery models, technology adoption maturity, and sector-specific compliance requirements. Understanding these divisions reveals where integrated platforms displace single-service vendors and which contract structures dominate specific asset classes.
Service Type:
Channel mix varies sharply across service categories, with bundled offerings flowing through integrated FM platforms while discrete services route through specialized subcontractors.
- Cleaning:Encompasses infection control protocols, hazardous waste handling, and commercial hygiene maintenance. Demand concentrates in Bangkok's healthcare campuses and hospitality assets, where Thailand's Ministry of Public Health enforces tightening sanitation standards post-pandemic.
- Maintenance:Covers HVAC systems, electrical infrastructure, plumbing networks, and structural integrity inspections. Eastern Economic Corridor manufacturing estates drive volume, as 24/7 production uptime mandates compress response timeframes and elevate preventive scheduling frequency.
- Security:Includes access control, surveillance systems, and personnel deployment across commercial and industrial perimeters. Industrial estates in Rayong and Chonburi anchor procurement volume.
- Landscaping:Encompasses grounds maintenance, irrigation management, and exterior aesthetic services for corporate campuses and hospitality properties.
Cleaning commands the largest installed base across Thailand's aging commercial stock. Maintenance is where expansion concentrates fastest as Building Energy Code compliance forces technical upgrades.
End User:
Cost tier segmentation separates premium integrated contracts in central Bangkok from price-sensitive arrangements in provincial markets, with compliance intensity determining margin structure.
- Commercial:Office towers, retail complexes, and mixed-use developments requiring full-service FM coordination. Bangkok's central business district concentrates contract value, with landlords prioritizing energy benchmarking to meet TREES certification pathways.
- Healthcare:Hospitals, clinics, and medical research facilities demanding specialized infection control and air quality management. Chiang Mai's expanding hospital networks represent an underpenetrated expansion corridor for technical FM operators.
- Education:University campuses and K-12 facilities combining high-traffic maintenance with seasonal occupancy patterns. Procurement flows through centralized government tendering.
- Hospitality:Hotels, resorts, and convention centers requiring 24/7 service continuity and brand-standard consistency across guest-facing operations.
Commercial dominates current contract volume. Healthcare is climbing the fastest as Bangkok and Chiang Mai hospital expansions outsource compliance-heavy technical functions.
Technology:
Application maturity separates pilot-stage deployments from scaled implementations, with industrial assets leading adoption curves due to measurable downtime cost.
- IoT Solutions:Sensor networks enabling real-time equipment monitoring and predictive failure detection. Eastern Economic Corridor manufacturing facilities deploy these fastest, driven by continuous production requirements and edge computing cost reduction.
- CAFM Software:Computer-aided facility management platforms integrating work order tracking, asset lifecycle management, and vendor coordination. Bangkok's premium commercial portfolios anchor demand as portfolio operators consolidate multi-site oversight.
- Automated Systems:Building automation controls for HVAC, lighting, and security infrastructure, typically retrofitted into aging assets to meet energy code compliance deadlines.
- Green Building Technologies:Renewable energy integration, water recycling systems, and carbon accounting tools aligned with Thailand's evolving TREES standards and international ESG reporting requirements.
CAFM Software dominates current technology spending in commercial portfolios. IoT Solutions is gaining share fastest as hardware costs decline and predictive maintenance ROI becomes demonstrable.
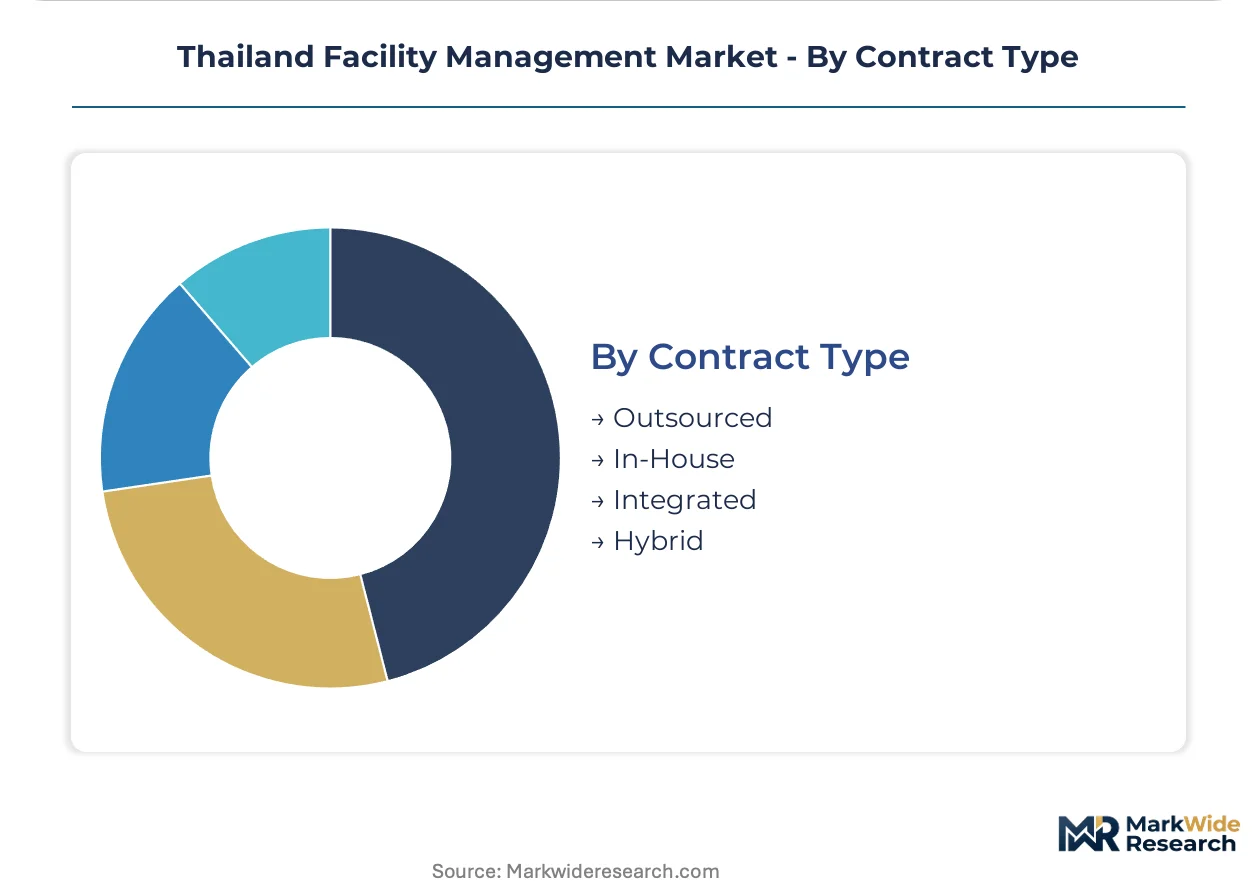
Contract Type:
Customer type and asset scale determine procurement structure, with multinational tenants imposing standardized templates while domestic owners retain fragmented vendor relationships.
- Outsourced:Third-party FM providers assuming full operational responsibility under multi-year agreements with performance-linked remuneration. Industrial estates in the Eastern Economic Corridor are consolidating toward this model.
- In-House:Direct employment of maintenance and operations staff, persisting in government-owned assets and legacy family-controlled commercial properties where labor retention outweighs efficiency gains.
- Integrated:Single-vendor responsibility spanning hard FM (engineering systems) and soft FM (cleaning, security, landscaping), capturing efficiency through unified command structures and cross-trained workforce deployment.
- Hybrid:Strategic combination retaining critical engineering functions in-house while outsourcing non-core services, common among hospital operators managing infection control internally while contracting environmental services.
Integrated contracts dominate new awards in industrial and premium commercial segments. Hybrid structures persist where regulatory complexity or labor union considerations favor selective retention of technical capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility management consumption patterns diverge sharply across Thailand's economic geography. Bangkok's premium commercial towers demand technology-integrated energy optimization, while Eastern Economic Corridor manufacturing estates prioritize uptime-critical industrial maintenance and provincial healthcare clusters seek infection-control specialization.
Bangkok Metropolitan Region
Central business district landlords deploy automated energy management systems to meet Thailand's Building Energy Code deadlines. The Ministry of Energy mandates these retrofits for large facilities above specified floor thresholds. Sathorn and Silom corridors concentrate contract awards to audit-capable vendors managing TREES certification pathways.
Eastern Economic Corridor
Rayong, Chonburi, and Chachoengsao manufacturing estates consolidate fragmented vendor arrangements into integrated FM contracts. Thailand's Board of Investment incentivizes smart factory infrastructure through tax privileges for automation investments. Industrial zones in Map Ta Phut and Laem Chabang anchor procurement volume for 24/7 production uptime services.
Chiang Mai and Northern Thailand
Healthcare and education campus clusters remain underpenetrated by integrated FM platforms despite expanding hospital networks. Thailand's Ministry of Public Health enforces tightening sanitation standards across medical infrastructure. Chiang Mai's expanding private hospital sector creates first-mover expansion potential for technical FM operators specializing in air quality compliance.
Phuket and Southern Tourism Belt
Hospitality assets require 24/7 service continuity and brand-standard consistency across guest-facing operations. Thailand's Ministry of Tourism and Sports promotes sustainable destination management through green building incentives. Resort concentrations in Patong and Kata Beach drive demand for bundled soft FM services combining landscaping, security, and environmental maintenance.
Thailand Facility Management Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Thailand's facility management sector. Premium commercial contracts in Bangkok's central business district concentrate among full-service platforms with proprietary technology stacks, while industrial estates and provincial markets sustain mid-tier operators with sector-specific expertise. Two strategic archetypes dominate: technology-anchored integrated platforms and compliance-focused industrial specialists. Competitive dynamics center on M&A consolidation of fragmented regional vendors and strategic partnerships with building automation hardware suppliers.
Within the integrated platform tier, CBRE (Thailand) Co., Ltd and Jones Lang LaSalle (Thailand) Ltd exemplify global real estate services firms that have localized technology deployment capabilities. Sodexo Services (Thailand) Co., Ltd occupies a distinct position among soft FM specialists with deep operational expertise across healthcare and education campuses. IFS Facility Services Co., Ltd represents the industrial maintenance archetype, anchoring technical service delivery for Eastern Economic Corridor manufacturing facilities. These three company structures illustrate how service scope differentiation—commercial portfolio technology integration versus healthcare compliance specialization versus industrial uptime engineering—defines competitive positioning in Thailand's fragmented vendor landscape.
| Leading Market Players |
|---|
| CBRE (Thailand) Co., Ltd |
| IFS Facility Services Co., Ltd |
| PCS Security and Facility Services Limited |
| G4S Security Services (Thailand) Limited |
| Sodexo Services (Thailand) Co., Ltd |
| Jones Lang LaSalle (Thailand) Ltd |
| Cushman & Wakefield Services (Thailand) Co., Ltd |
| Savills (Thailand) Limited |
| KJTN Engineering Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for imported building automation hardware compress margin buffers for FM operators bidding on integrated contracts, concentrating pricing power with distributors holding bonded warehouse stock in Laem Chabang while forcing project-based vendors toward longer lead-time penalties.
Pricing Analysis
Long-term offtake agreements dominate integrated FM contracts in Bangkok's central business district, with three-year bundled service awards carrying performance-linked remuneration structures. Price differentiation separates TREES-certified operators from uncertified competitors and scales with portfolio square footage thresholds. Cost compression in the industrial maintenance tier is intensifying because Eastern Economic Corridor manufacturing tenants unbundle services and pit specialized vendors against each other. Domestic provincial buyers exhibit highest price sensitivity, while multinational anchor tenants prioritize uptime guarantees over per-unit cost minimization.
Supply Chain Analysis
China and Germany anchor sensor hardware production for Thailand's smart building retrofits, with edge computing modules and IoT gateways flowing through Singaporean distribution hubs before customs clearance. Building automation controllers draw from German engineering supply chains, while cloud infrastructure rests on hyperscaler data centers in Singapore. Single-source vulnerability concentrates in proprietary protocol licensing from Schneider, Siemens, and Honeywell, forcing middleware development costs onto FM integrators. Distribution runs through authorized system integrators holding exclusive territorial rights, limiting direct procurement options for end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from technology-anchored platforms displacing labor-intensive service models, requiring defensive repositioning around proprietary analytics capabilities.
For Market Incumbents: Compound technical differentiation by acquiring CAFM software specialists and embedding predictive maintenance algorithms into standard contract offerings. Certification investment in Thailand's Building Energy Code compliance expertise creates switching costs against pure-play cleaning or security vendors. Vertical integration into edge computing deployment capabilities defends margin position against hardware distributors expanding downstream.
For New Entrants and Emerging Players: Anchor in Chiang Mai's underpenetrated healthcare campus cluster, where hospital expansion outpaces integrated FM platform coverage. Target TREES certification consulting as a wedge service that opens doors to broader technical maintenance contracts. Partner with German building automation OEMs as authorized system integrators to bypass distributor margin extraction.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fragmented regional vendors lack capital depth for technology platform investments. Acquisition targets combine industrial maintenance expertise with existing Eastern Economic Corridor relationships and unexploited healthcare sector exposure. Monitor Thailand's Ministry of Energy enforcement patterns for Building Energy Code compliance deadlines as the inflection signal for contract acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CAFM Platform Acquisition | Integrates predictive analytics capabilities into legacy service portfolios for Bangkok commercial towers. |
| TREES Certification Program | Aligns vendor qualifications with Thailand's evolving green building standards and carbon accounting requirements. |
| Edge Computing Partnership | Deploys real-time anomaly detection for Eastern Economic Corridor manufacturing uptime guarantees. |
| Chiang Mai Geographic Expansion | Captures first-mover position in northern Thailand's healthcare campus technical maintenance outsourcing. |
| BAS Technician Training Center | Addresses certified workforce scarcity constraining smart retrofit project scaling across industrial estates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with facility management executives, hospital procurement officers, industrial estate operators, and building automation system integrators; and secondary validation against Thailand's Ministry of Energy regulatory filings, Board of Investment incentive disclosures, and customs import records for smart building hardware. Bottom-up contract value aggregation across service type segments triangulated against top-down market sizing from national building stock databases and energy code compliance deadlines.
Across the analysis window, projections incorporate service type segmentation by delivery model, technology adoption maturity tiers, and end-user compliance intensity. CAGRs derive from weighted averaging of segment growth trajectories, with inputs including Eastern Economic Corridor manufacturing capacity expansion schedules and Bangkok commercial retrofit timelines tied to Building Energy Code enforcement phases. Model sensitivity tests variation in skilled technician pipeline output and imported equipment cost trajectories.
Material uncertainties — regulatory enforcement delays, currency fluctuation impacts on hardware imports, and legacy system interoperability breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions about sustained industrial estate consolidation and healthcare outsourcing momentum. Recalibration cycles align with material shifts in Thailand's green building certification requirements and provincial environmental regulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Philippines Facility Management Market
Facility Management
Finland Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
North America Hard Facility Management Market
Facility Management
Austria Facility Management Market
Facility Management
Greece Facility Management Market
Facility Management
Egypt Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Australia Facility Management Market
Facility Management
France Facility Management Market
Facility Management
Europe Soft Facility Management Market
Facility Management
Asia-Pacific Hard Facility Management Market
Facility Management
Netherlands Facility Management Market
Facility Management
Lithuania Facility Management Market
Facility Management
Facility Management Services Market
Facility Management
Japan Facility Management Market