
 Egypt Facility Management Market | 2026-2036
Egypt Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Facility Management Market Foresight
A shortage of certified building systems technicians is redrawing competitive dynamics across Egypt's facility management sector. EFS Facilities Services Group leverages its training academies to sustain talent pipelines across Cairo and Giza. Hassan Allam Holding anchors large-scale industrial contracts through captive engineering capabilities. CBRE Egypt competes on technology integration, differentiating via building automation platforms for premium commercial clients.
Facility management encompasses the integrated coordination of building maintenance, operations, security, and energy systems to ensure functional performance of physical assets. Services span HVAC calibration, fire safety compliance testing, and integrated workplace management systems with real-time sensor networks. Maintenance services dominate current revenue pools given aging public infrastructure and hospital retrofit cycles. Energy Management Systems represent the fastest-expanding technology segment as electricity tariff reforms push commercial offices toward consumption optimization platforms. Bundled service contracts capture widening margin pools as clients consolidate vendor relationships under outcome-based agreements.
Egypt's Ministry of Housing enforces building safety inspections through periodic compliance audits that elevate demand for certified maintenance providers. The Egyptian Organization for Standardization and Quality mandates workplace safety protocols that shape service-level specifications across industrial facilities. The central bank's green finance guidelines channel lending toward energy-efficient building retrofits, expanding the addressable base for integrated facility solutions. Stakeholders must monitor how Egypt's sovereign urban development programs redirect contract flows toward state-linked construction consortia.
Market Dynamics
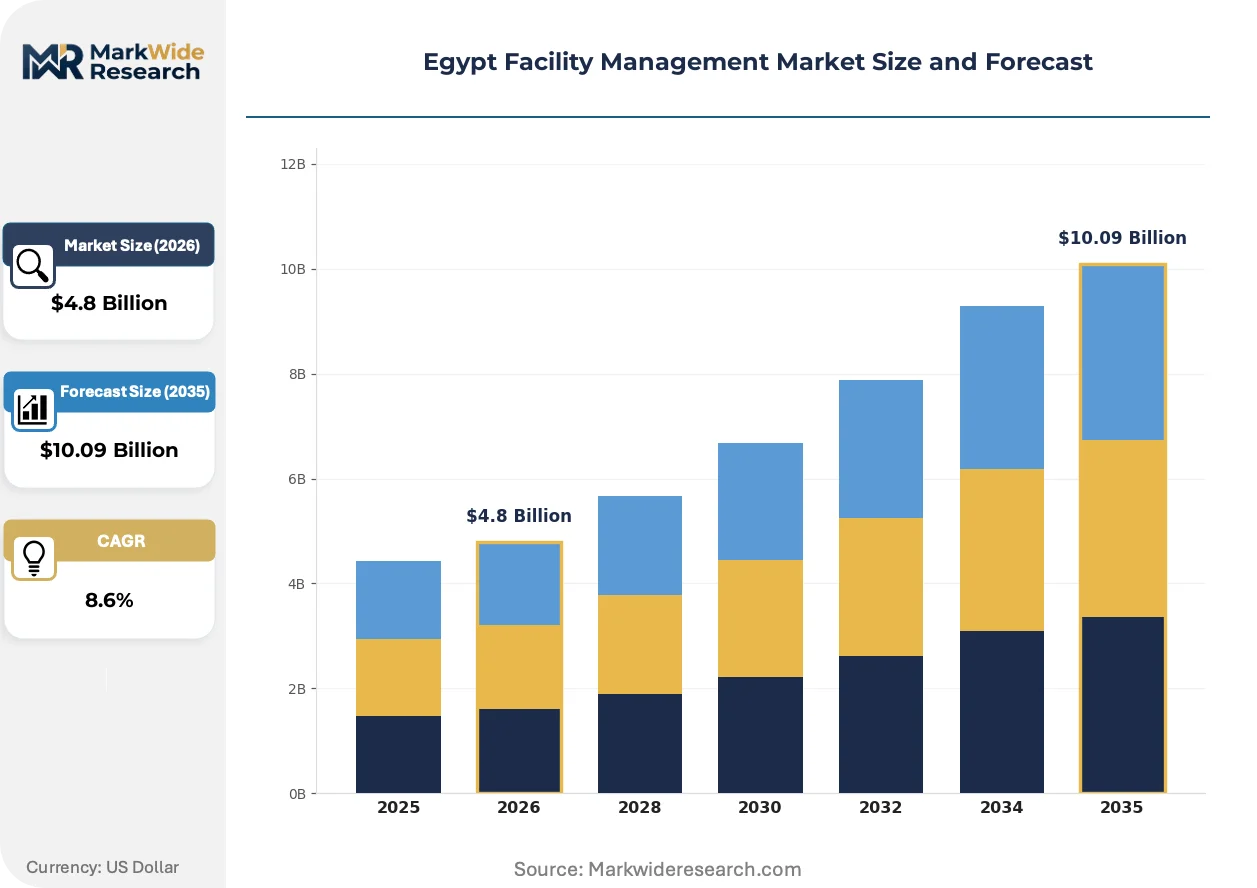
Egypt's electricity tariff restructuring is compressing facility management contract economics and forcing service providers toward energy performance guarantees. The Ministry of Electricity's phased subsidy removal creates direct pressure on commercial building operators to reduce consumption intensity.
Growth Catalysts
- Building Energy Efficiency Codes:Egypt's new mandatory efficiency standards for commercial structures mandate regular HVAC audits and system upgrades, creating recurring revenue streams for certified maintenance providers.
- Smart Sensor Networks:IoT-enabled predictive maintenance platforms are penetrating premium office towers in Cairo's New Administrative Capital, enabling real-time fault detection that reduces downtime costs.
- Healthcare Retrofit Cycles:Aging public hospital infrastructure across Nile Delta governorates requires comprehensive facility overhauls, concentrating demand for integrated mechanical and electrical maintenance bundles.
Market Restraints
- Certified Technician Scarcity:Shortage of locally trained building automation specialists limits service scalability and inflates labor costs for complex system integrations.
- Import Dependency for Components:HVAC control modules and fire suppression hardware rely heavily on European and East Asian supply chains, exposing operators to currency fluctuation risks.
- Fragmented Procurement Standards:Inconsistent tender specifications across government agencies and state-linked developers force vendors to maintain multiple compliance protocols.
Strategic Opportunities
- Upper Egypt Greenfield Developments:Industrial zones in Sohag and Qena present untapped demand for bundled facility services as manufacturing investment shifts southward from saturated Cairo-Alexandria corridor.
- Central Bank Green Finance Guidelines:Preferential lending rates for energy-efficient building retrofits expand the addressable market for integrated energy management contracts.
- Digital Twin Convergence:Integration of BIM models with live sensor data enables predictive space optimization, opening premium service tiers for multinational corporate tenants.
Industry Challenges
- Multi-Skill Technician Pipeline:Cross-training requirements spanning electrical, mechanical, and IT systems extend workforce development timelines beyond typical contract ramp periods.
- Legacy System Integration:Decades-old building management infrastructure in Cairo's commercial core resists seamless connectivity with modern cloud-based monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Facility Management Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance Services, Cleaning Services, Security Services, Landscaping Services End User: Residential Buildings, Commercial Offices, Retail Outlets, Educational Institutions Technology: Building Automation Systems, Energy Management Systems, Security Monitoring, Communication Platforms Contract Type: Bundled Services, Outsourced Services, In-House Services, Ad-Hoc Services |
| Companies Covered | Contrack FM, EFS Facilities Services Group, Enova Facilities Management Services, Apleona Egypt, G4S Egypt, JLL Egypt, CBRE Egypt, Hassan Allam Holding, Savills Egypt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Facility Management Market Shifts & Advancements
Digital infrastructure is reconfiguring how facility services are delivered and monetized across Egypt's commercial property sector. Technology providers and incumbent operators are racing to embed intelligence into physical asset management.
Building automation platforms are decomposing traditional reactive maintenance models by enabling condition-based intervention schedules. Premium office landlords in Cairo's Fifth Settlement district are deploying these systems to compress mean-time-to-repair metrics. The technology is decomposing vendor margins on emergency call-out services while expanding recurring software subscription revenues.
Egypt's Ministry of Housing enforcement of periodic safety audits through the Egyptian Organization for Standardization and Quality is elevating compliance documentation requirements. Industrial facility operators must now maintain digital inspection trails for fire suppression and electrical systems. Heavy manufacturing campuses in Alexandria's Borg El Arab industrial zone are investing in integrated compliance management platforms to satisfy audit frequency mandates.
Corporate real estate directors are consolidating vendor relationships under performance-based agreements that tie fees to measurable outcomes. Multinational tenants in Cairo's central business district are replacing fragmented single-service contracts with integrated providers accountable for total facility uptime. This concentration is most visible among pharmaceutical and financial services occupiers with critical environmental control requirements.
Egypt Facility Management Market Segmentation
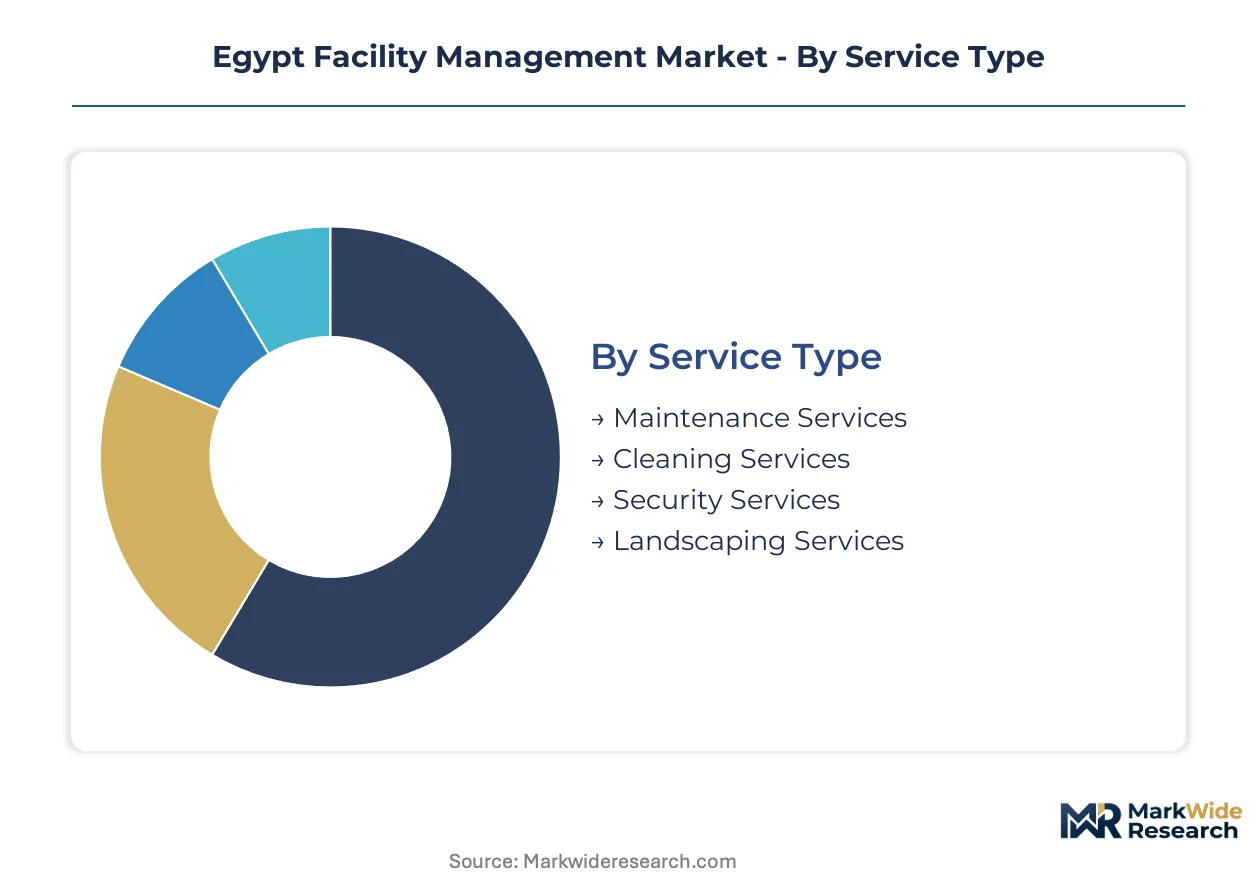
Segmentation reveals how Egypt's facility management providers align capabilities with divergent client risk profiles and regulatory exposure. Contract structures and technology adoption vary sharply across building vintages and ownership types.
Service Type:
Egypt's Ministry of Housing enforces differentiated compliance documentation across service categories through periodic safety audits.
- Maintenance Services:Encompass HVAC calibration, fire safety system testing, and electrical infrastructure upkeep. Demand concentrates in aging public hospitals across Nile Delta governorates where retrofit cycles mandate comprehensive mechanical and electrical overhaul bundles.
- Security Services:Deploys access control, surveillance networks, and perimeter monitoring for commercial assets. Premium office towers in Cairo's New Administrative Capital drive adoption of integrated guard-and-technology solutions as multinational tenants enforce strict duty-of-care protocols.
- Cleaning Services:Covers janitorial operations, waste management, and specialized hygiene protocols for healthcare facilities.
- Landscaping Services:Delivers grounds maintenance, irrigation management, and hardscape upkeep for corporate campuses and residential compounds.
Maintenance Services handles the majority of throughput; Security Services is the fastest mover on share.
End User:
Procurement sophistication splits sharply between state-linked and private sector clients.
- Commercial Offices:Occupiers in Cairo's central business district and Fifth Settlement district demand integrated workplace management with real-time sensor networks. Electricity tariff restructuring from the Ministry of Electricity forces these assets toward consumption optimization platforms and energy performance guarantees.
- Educational Institutions:Universities and technical colleges require seasonal maintenance scheduling and safety compliance for high-occupancy facilities. Public sector procurement through state-linked developers concentrates contract flows toward vendors with established government relationships.
- Residential Buildings:Compound-style developments in Giza and New Cairo favor bundled amenity management.
- Retail Outlets:Shopping malls and branded retail chains prioritize customer-facing cleanliness standards and HVAC reliability.
Commercial Offices dominates current contract value; Educational Institutions is expanding most quickly as public infrastructure investment accelerates.
Technology:
Technology deployment tracks building vintage and owner sophistication tiers.
- Energy Management Systems:Platforms for consumption monitoring, demand response, and tariff optimization. Commercial offices facing phased electricity subsidy removal deploy these systems most aggressively to compress operating expenditure.
- Building Automation Systems:Centralized control of HVAC, lighting, and access systems through cloud-connected controllers. Premium assets in Alexandria's Borg El Arab industrial zone and Cairo's commercial core adopt these for predictive maintenance and compliance documentation trails.
- Security Monitoring:Video analytics, intrusion detection, and emergency response coordination.
- Communication Platforms:Tenant-facing apps and service request portals for facility interaction.
Building Automation Systems anchors installed base; Energy Management Systems climbs the fastest as tariff reforms bite.
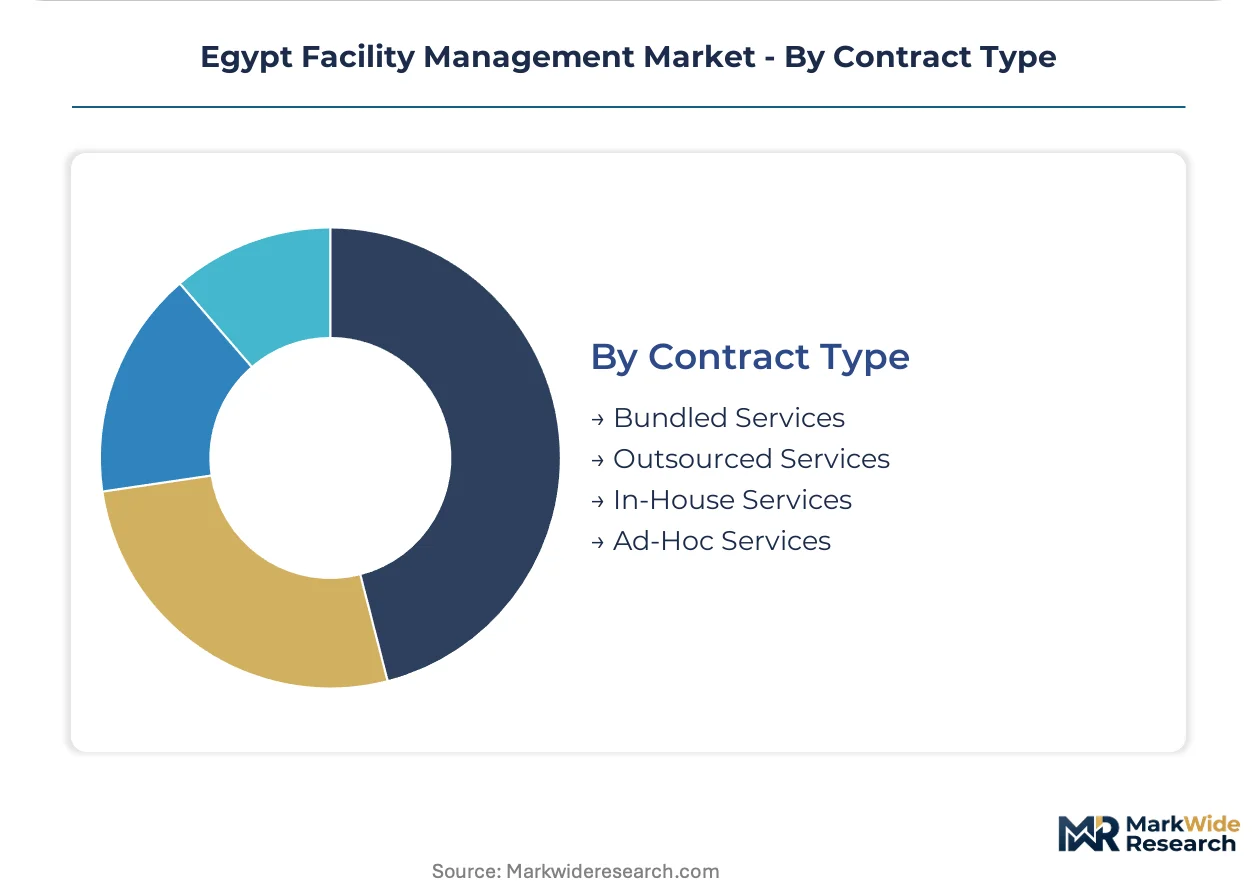
Contract Type:
Contract economics diverge based on asset criticality and owner risk appetite.
- Bundled Services:Single-provider accountability spanning maintenance, security, and energy management under outcome-based fee structures. Pharmaceutical and financial services occupiers with critical environmental control requirements consolidate vendor relationships under these agreements.
- Outsourced Services:Third-party provision of discrete functions previously managed in-house. Industrial facilities in Alexandria's Borg El Arab industrial zone favor this model to access certified technician capabilities without captive training investment.
- In-House Services:Direct employment of facility staff by asset owners, common among state-linked developers.
- Ad-Hoc Services:Reactive, transaction-based engagement for emergency repairs and seasonal peaks.
Bundled Services captures widening margin pools; Outsourced Services gains share fastest as technician scarcity pressures self-operated models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's facility management consumption patterns diverge sharply between Cairo-Alexandria corridor assets demanding technology-integrated bundles and Upper Egypt industrial zones prioritizing cost-efficient maintenance outsourcing.
Cairo Governorate
Commercial offices in the Fifth Settlement and New Administrative Capital drive demand for building automation platforms and energy performance guarantees. The Ministry of Housing enforces periodic safety audits through the Egyptian Organization for Standardization and Quality, elevating compliance documentation requirements. Smart building adoption concentrates in premium towers where multinational tenants mandate real-time sensor networks and predictive maintenance protocols.
Alexandria Governorate
Industrial facilities in Borg El Arab industrial zone require integrated mechanical and electrical maintenance bundles for heavy manufacturing campuses. The Ministry of Electricity's phased subsidy removal forces operators toward consumption optimization platforms. Certified technician scarcity limits service scalability, pushing asset owners toward outsourced service providers with captive training capabilities.
Giza Governorate
Compound-style residential developments favor bundled amenity management spanning security, landscaping, and HVAC maintenance. Central bank green finance guidelines channel preferential lending toward energy-efficient building retrofits. New Cairo's satellite city expansions concentrate contract flows toward vendors with established relationships with state-linked developers.
Sohag and Qena Governorates
Greenfield industrial zones in Upper Egypt present untapped demand for bundled facility services as manufacturing investment shifts southward. Sovereign urban development programs redirect contract flows toward state-linked construction consortia. Local workforce development lags behind technical requirements for complex system integrations, creating entry barriers for non-integrated service providers.
Egypt Facility Management Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated players capturing bundled service contracts while fragmented operators compete on discrete maintenance functions. Market structure reflects technician scarcity pressures that favor vertically integrated providers with captive training pipelines. Strategic archetypes include engineering-led conglomerates with construction heritage, international property consultancies leveraging technology platforms, and regional specialists with government relationship depth. Competitive moves concentrate on talent academy investments and outcome-based contract structuring that ties fees to measurable uptime metrics.
Among Egypt-based integrated providers, Hassan Allam Holding anchors large-scale industrial contracts through engineering capabilities, while EFS Facilities Services Group sustains talent pipelines across Cairo and Giza through training academies. CBRE Egypt occupies a position on the technology-integration vector, differentiating via building automation platforms for premium commercial clients in the central business district.
| Leading Market Players |
|---|
| Contrack FM |
| EFS Facilities Services Group |
| Enova Facilities Management Services |
| Apleona Egypt |
| G4S Egypt |
| JLL Egypt |
| CBRE Egypt |
| Hassan Allam Holding |
| Savills Egypt |
| Others |
Supply & Pricing Matrix
Egypt's Ministry of Housing enforcement of building safety inspections through periodic compliance audits gates both technician certification tiers and service pricing bands simultaneously. Certified providers command premium positioning for mandatory HVAC and fire safety documentation, while uncertified operators compete on cost for non-regulated maintenance functions.
Pricing Analysis
Long-term bundled service contracts dominate premium commercial assets in Cairo's Fifth Settlement and New Administrative Capital, locking in recurring revenue streams over three-to-five-year horizons. Pricing stratifies across premium, standard, and economy tiers based on technician certification grade from the Egyptian Organization for Standardization and Quality and after-sales service bundling depth. Cost compression in the standard tier is intensifying because electricity tariff restructuring forces building operators toward energy performance guarantees that squeeze middle-market margins. State-linked developers and public hospital procurement committees exhibit highest price sensitivity, while multinational pharmaceutical and financial services tenants prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Port congestion at Alexandria and container availability constraints on Asia-Mediterranean trade lanes inflate inbound logistics costs for HVAC control modules and fire suppression hardware. Component sourcing draws from Germany, Italy, and China for building automation controllers, sensor networks, and electrical infrastructure. Single-source vulnerability concentrates in proprietary HVAC control modules where European manufacturers hold technical lock-in. Distribution runs through authorized dealer networks and direct OEM relationships with large facility management providers, bypassing fragmented wholesale channels for critical safety systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's facility management sector functions as a service-attach opportunity where software subscription layers for building automation and energy management expand faster than hardware installation revenues. Recurring platform fees now capture widening margin pools as clients consolidate under outcome-based agreements.
For Market Incumbents: Shield installed base relationships by accelerating captive technician academy investments before certification scarcity worsens. Deepen backward integration into energy management software development to reduce dependency on European control module suppliers. Consolidate position through selective acquisition of regional specialists with established government procurement relationships.
For New Entrants and Emerging Players: Anchor in Upper Egypt's Sohag and Qena industrial zones where greenfield manufacturing investment outpaces local service capacity. Target untapped demand for bundled facility services among mid-scale industrial operators lacking captive engineering capabilities. Pursue partnership-based entry with state-linked construction consortia to secure preferred vendor status in sovereign urban development programs.
For Investors and Strategic Acquirers: Egypt's central bank green finance guidelines reshape the acquisition landscape by channeling preferential lending toward energy-efficient building retrofit specialists. Long-term viability centers on providers with integrated software-hardware-service stacks capable of capturing recurring revenue across the analysis window. Target acquisition candidates with established training pipelines and government relationships. Monitor electricity tariff reform implementation pace as the critical inflection signal for energy management contract acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Technician Academy Investment | Captive training pipelines from EFS Facilities Services Group address certified specialist scarcity constraining market expansion. |
| Building Automation Platform Integration | CBRE Egypt's technology differentiation captures premium commercial clients demanding real-time sensor networks. |
| Energy Performance Guarantee Structuring | Outcome-based contracts tie fees to measurable consumption reductions under Ministry of Electricity tariff reforms. |
| Upper Egypt Geographic Expansion | Sohag and Qena industrial zones present first-mover advantage as manufacturing investment shifts southward. |
| Government Relationship Deepening | Hassan Allam Holding's state-linked construction heritage secures large-scale industrial contract flows. |
Research Methodology
Initial hypotheses were tested against primary input from facility management executives, building automation engineers, commercial real estate directors, and procurement officers at state-linked developers and refined through secondary validation. Primary fieldwork encompassed structured discussions with maintenance service heads at industrial facilities in Alexandria's Borg El Arab zone and healthcare infrastructure managers across Nile Delta governorates. Secondary sources included Egyptian Organization for Standardization and Quality regulatory filings, Ministry of Housing audit documentation, central bank green finance guideline circulars, and trade flow data for HVAC and fire safety component imports. Bottom-up service provider capacity assessments were triangulated against top-down building stock and retrofit cycle projections.
Variance decomposition across service type, end user, technology tier, and contract structure dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation. Forecast inputs incorporated electricity tariff reform phase schedules, public hospital retrofit pipeline announcements, and smart building adoption curves in Cairo's New Administrative Capital.
Material uncertainties — sovereign urban development program redirections, currency fluctuation impacts on imported component costs, and technician training pipeline expansion rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and green finance guideline implementation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Luxembourg Facility Management Market
Facility Management
Panama Facility Management Market
Facility Management
Global Unified Facility Management Market
Facility Management
Canada Facility Management Market
Facility Management
Europe Hard Facility Management Market
Facility Management
North America Soft Facility Management Market
Facility Management
Austria Facility Management Market
Facility Management
Asia-Pacific Soft Facility Management Market
Facility Management
Bahrain Facility Management Market
Facility Management
North America Facilities Management Market
Facility Management
Middle East and Africa Hard Facility Management Market
Facility Management
Ireland Facility Management Market
Facility Management
Czech Republic Facility Management Market
Facility Management
Thailand Facility Management Market
Facility Management
Serbia Facility Management Market
Facility Management
Netherlands Facility Management Market