
 Hong Kong Facility Management Market | 2026-2036
Hong Kong Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Facility Management Market Foresight
Asset-light outsourcing and performance-based service contracts are reshaping competitive dynamics in Hong Kong's facility management sector. CBRE leverages its integrated platform to bundle property management with technical services across premium commercial portfolios. Savills Hong Kong Limited anchors its position through specialized stewardship of luxury residential and retail assets. Kai Shing Management Services Limited dominates the local mid-market through deep relationships with Hong Kong Housing Authority estates.
Facility management encompasses the professional coordination of building operations, maintenance, and occupant services through systematic lifecycle management of physical assets and infrastructure systems. In Hong Kong's high-density built environment, this discipline ensures regulatory compliance, energy optimization, and uninterrupted functionality of vertical cities where commercial towers exceed fifty floors. Cleaning and security services command the largest share of service-type revenue due to labor-intensive operational requirements and mandatory staffing ratios under local ordinances. Building Management Systems and IoT Solutions represent the fastest-expanding technology segment as landlords deploy sensor networks for predictive maintenance and real-time energy analytics. Commercial Buildings generate the dominant end-user demand, though Healthcare Facilities are emerging as a specialized growth corridor requiring stringent infection control protocols.
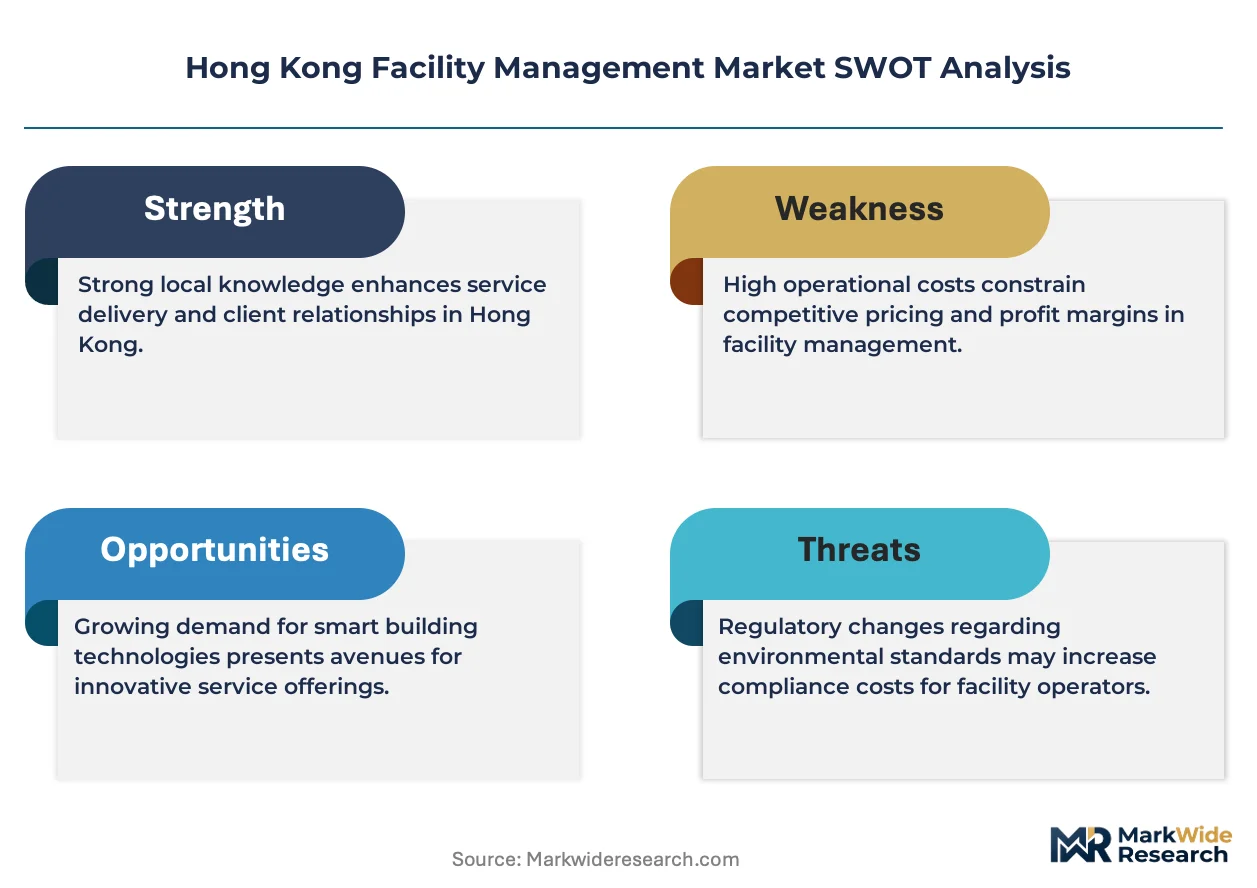
The Buildings Department and Electrical and Mechanical Services Department enforce safety and energy efficiency standards that directly shape service procurement specifications and vendor qualification criteria. BIS and ISO 41001 compliance requirements are elevating operational benchmarks for contractors serving multinational corporate tenants. Stakeholders must monitor how tightening carbon disclosure rules and smart building mandates will redefine contract scopes and technology investment priorities.
Market Dynamics
The Buildings Energy Efficiency Ordinance is compressing service procurement timelines across Hong Kong's commercial tower stock, forcing landlords to bundle energy audits with maintenance contracts and accelerating vendor consolidation around certified technical specialists.
Growth Catalysts
- Smart Building Mandates:The Electrical and Mechanical Services Department is tightening compliance windows for Building Management System upgrades, compelling owners in Central and Admiralty to accelerate IoT sensor deployment for real-time energy monitoring.
- Healthcare Facility Expansion:Hospital Authority estates in Kowloon and New Territories are issuing integrated facilities contracts that combine infection control protocols with predictive maintenance, creating specialized demand for certified contractors.
- Retrofit Acceleration:Aging commercial stock in Tsim Sha Tsui and Causeway Bay is driving elevator modernization and facade maintenance bundling as strata-title owners seek single-source accountability.
Market Restraints
- Labor Cost Escalation:Minimum wage ordinances and mandatory staffing ratios under the Security and Guarding Services Ordinance are compressing margins on security and cleaning contracts, the sector's largest service lines.
- Certification Bottlenecks:ISO 41001 and BIS compliance timelines are extending vendor qualification periods to 12-18 months, freezing new entrants from multinational corporate tenant portfolios.
- Technology Fragmentation:Proprietary Building Management System protocols from legacy Hong Kong installations are blocking seamless IoT integration, forcing costly middleware investments.
Strategic Opportunities
- Data Center Facilities:hyperscale cloud operators in Tseung Kwan O Industrial Estate are commissioning specialized cooling and power redundancy contracts outside traditional commercial FM scopes.
- Carbon Disclosure Alignment:Stock Exchange of Hong Kong ESG reporting requirements are creating advisory revenue streams around energy baseline establishment and retrofit pathway planning.
- Integrated Living-Work Concepts:mixed-use developments in Kai Tak and Wong Chuk Hang are bundling residential concierge with commercial FM under single operators, blurring traditional service boundaries.
Industry Challenges
- Technical Talent Scarcity:certified Building Energy Assessment (BEA) professionals and BMS commissioning engineers command 40% salary premiums, constraining contract scaling.
- Legacy System Integration:1980s-era pneumatic controls in older Hong Kong Island towers require phased digital retrofits that disrupt tenant operations and complicate service continuity guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Facility Management Market |
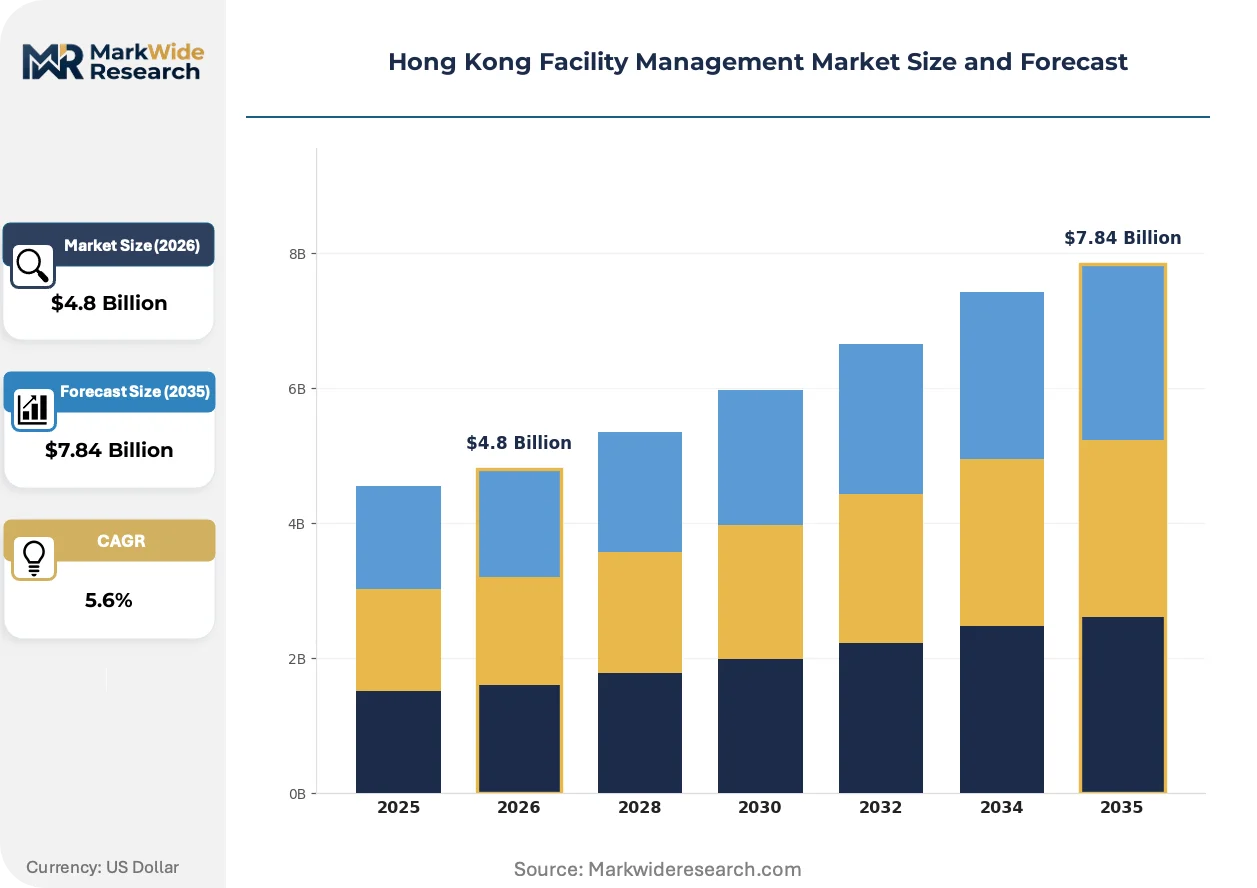
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Catering End User: Commercial Buildings, Residential Complexes, Educational Institutions, Healthcare Facilities Technology: Building Management Systems, IoT Solutions, Smart Lighting, HVAC Controls Facility Type: Office Spaces, Retail Outlets, Manufacturing Plants, Warehouses |
| Companies Covered | Urban Group, CBRE, Savills Hong Kong Limited, Hongkong Land, Kai Shing Management Services Limited, Knight Frank Hong Kong Limited EAA, ISS A/S, Jones Lang LaSalle IP, Inc., G4S Facility Services Hong Kong Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Facility Management Market Shifts & Advancements
Digital twin technology and edge computing architectures are redefining how Hong Kong's vertical cities manage mechanical, electrical, and plumbing assets through predictive rather than reactive intervention models.
Digital twin platforms are migrating from pilot deployments in flagship commercial assets to standard procurement specifications for Grade A office tenders. Swire Properties and Link REIT are mandating BIM-integrated FM handovers for new developments, compressing commissioning timelines and enabling virtual scenario testing before physical interventions. This shift is migrating from boutique technology demonstration to contractual baseline requirement.
The Buildings Energy Efficiency Ordinance is tightening audit frequency and disclosure granularity for commercial premises exceeding 500 square meters. Owners must now submit centralized energy consumption data to the Electrical and Mechanical Services Department, triggering procurement of continuous monitoring solutions rather than periodic manual assessments. Healthcare and data center verticals are responding fastest, embedding compliance infrastructure into capital planning cycles.
Integrated service contracts are displacing siloed single-service procurement across Hong Kong Island premium stock. Landlords in Admiralty and Central are consolidating cleaning, security, technical maintenance, and energy management under single accountability structures with penalty-linked KPIs. This concentration is most visible among financial services tenants demanding unified service level agreements aligned to their own operational risk frameworks.
Hong Kong Facility Management Market Segmentation
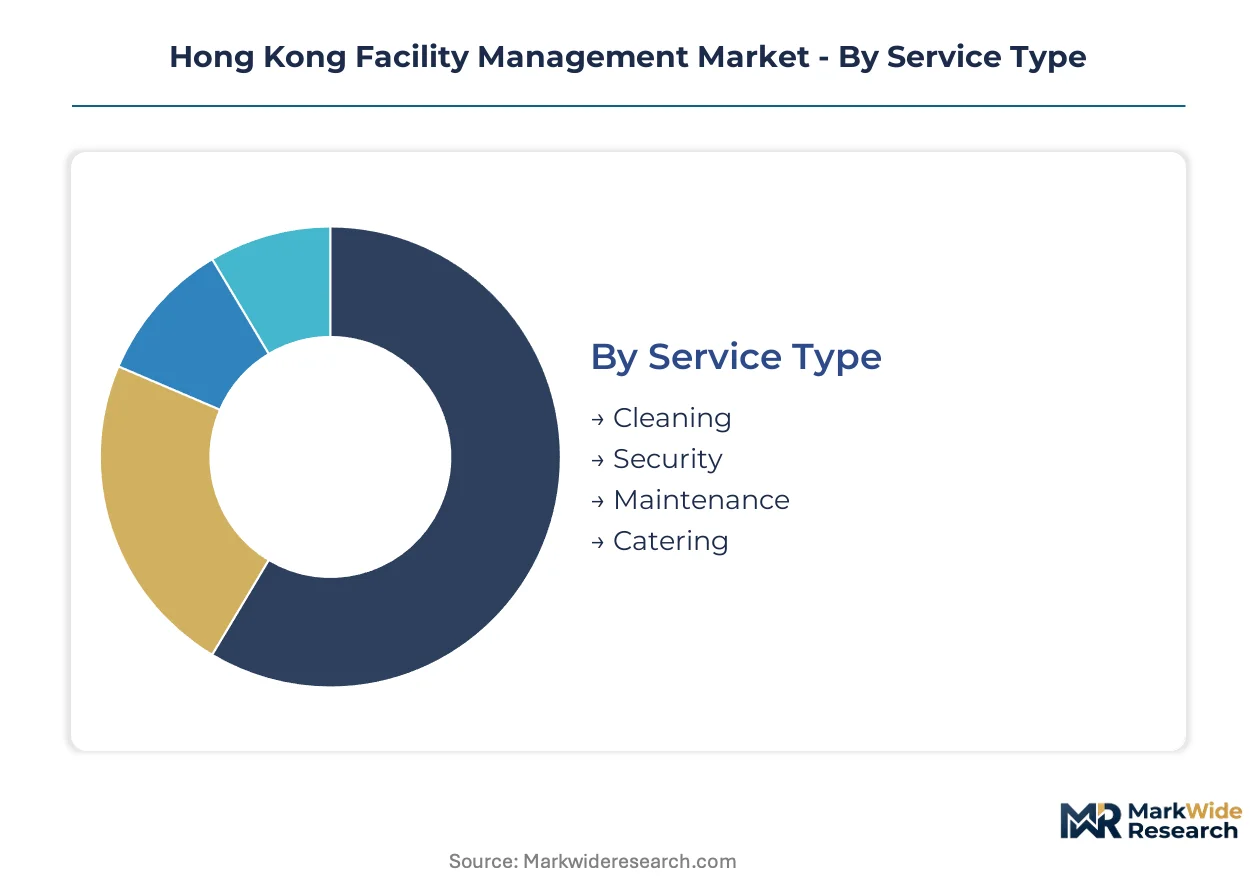
Hong Kong's facility management market fragments across service delivery models, asset categories, and technology integration levels. Each segmentation axis reveals distinct procurement patterns shaped by the territory's high-density vertical built environment and stringent regulatory frameworks.
Service Type:
Cleaning and security dominate operational expenditure across Hong Kong's commercial tower stock, while technical maintenance commands premium pricing for certified compliance work.
- Cleaning:Labor-intensive floor care, facade glass maintenance, and post-construction deep cleaning absorb the largest share of facility operating budgets. Demand concentrates in Grade A office clusters in Central and Admiralty where landlords mandate round-the-clock presentation standards under strata-title management committees.
- Security:Manned guarding, access control monitoring, and emergency response coordination operate under mandatory staffing ratios prescribed by the Security and Guarding Services Ordinance. Kowloon commercial zones and residential estates drive volume through 24/7 shift requirements that inflate labor costs.
- Maintenance:Mechanical, electrical, and plumbing asset upkeep plus elevator and fire safety system servicing.
- Catering:Food service operations for corporate canteens, staff restaurants, and residential clubhouse facilities.
Established volume favors Cleaning; emerging adoption favors Maintenance as predictive service models displace reactive contracts.
End User:
Procurement sophistication varies sharply across tenant types, with financial services and healthcare operators demanding integrated service level agreements.
- Commercial Buildings:Premium office towers and mixed-use developments requiring unified FM accountability spanning cleaning, security, technical maintenance, and energy management. Hong Kong Island's financial district anchors demand through penalty-linked KPI structures aligned to operational risk frameworks.
- Healthcare Facilities:Hospital Authority estates and private medical centers requiring stringent infection control protocols combined with predictive maintenance. Kowloon and New Territories expansions are issuing bundled facilities contracts that merge clinical hygiene standards with infrastructure lifecycle management.
- Residential Complexes:Private estates and public housing under Housing Authority stewardship.
- Educational Institutions:Universities and schools with seasonal occupancy patterns and specialized laboratory maintenance needs.
Commercial Buildings capture dominant procurement value; Healthcare Facilities are climbing the fastest as specialized compliance requirements deepen vendor relationships.
Technology:
Technology investment concentrates where regulatory deadlines compress implementation timelines and energy disclosure rules mandate continuous monitoring infrastructure.
- Building Management Systems:Centralized control platforms integrating mechanical, electrical, and plumbing assets through legacy pneumatic and modern digital architectures. Retrofit demand concentrates in 1980s-era Hong Kong Island towers where phased digital upgrades disrupt tenant operations.
- IoT Solutions:Sensor networks enabling predictive maintenance, real-time energy analytics, and automated fault detection. The Buildings Energy Efficiency Ordinance is accelerating deployment in Central and Admiralty commercial stock where owners must submit centralized consumption data to the Electrical and Mechanical Services Department.
- Smart Lighting:LED retrofits with occupancy-based controls and daylight harvesting algorithms.
- HVAC Controls:Zone-based climate management systems optimizing energy use across variable occupancy patterns.
Building Management Systems anchor current installed base; IoT Solutions are gaining share fastest as audit frequency tightens and disclosure granularity expands.
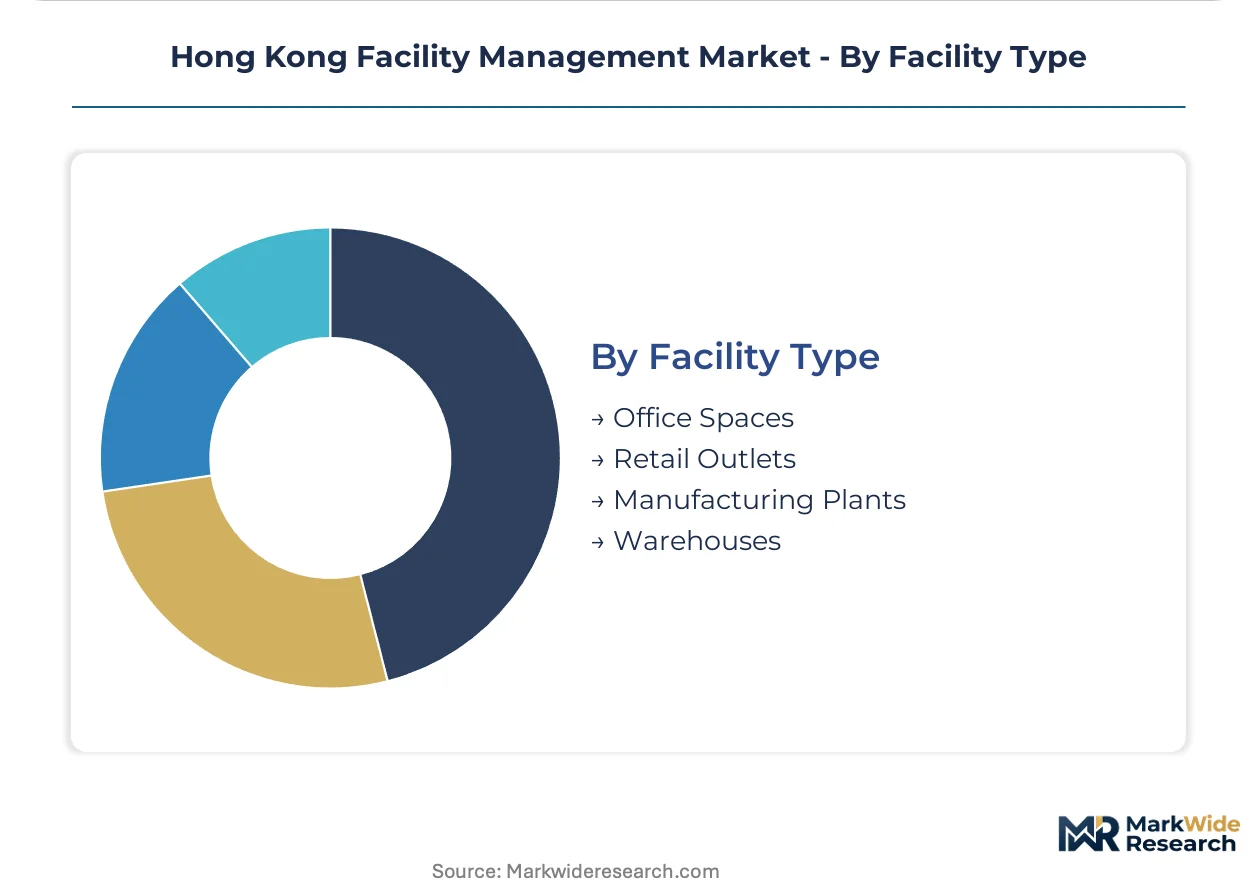
Facility Type:
Asset age and ownership structure determine service bundling preferences across Hong Kong's stratified property market.
- Office Spaces:Grade A towers and business centers requiring integrated service contracts with unified accountability. Tsim Sha Tsui and Causeway Bay aging stock is driving elevator modernization and facade maintenance bundling as owners seek single-source vendor relationships.
- Retail Outlets:Shopping malls and street-level commercial premises with high footfall maintenance demands and extended operating hours.
- Manufacturing Plants:Industrial facilities in Tseung Kwan O and outlying areas requiring specialized equipment maintenance and environmental compliance.
- Warehouses:Logistics and cold storage facilities with racking systems, loading dock equipment, and climate control infrastructure.
Office Spaces sustain premium pricing tiers; Retail Outlets are expanding most quickly as consumption recovery drives footfall-sensitive maintenance investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hong Kong Island commands premium pricing for integrated facility management contracts, while Kowloon's emerging commercial zones trade at 15-20% discounts despite faster volume growth. This asymmetry reflects divergent tenant sophistication and regulatory enforcement intensity across the territory's urban core.
Hong Kong Island
Grade A office towers in Central and Admiralty drive demand for unified service level agreements with penalty-linked KPIs. The Buildings Energy Efficiency Ordinance compresses compliance timelines for buildings exceeding 500 square meters. Swire Properties and Link REIT developments here mandate BIM-integrated FM handovers as contractual baselines.
Kowloon
Tsim Sha Tsui and Causeway Bay aging commercial stock is accelerating elevator modernization and facade maintenance bundling. The Electrical and Mechanical Services Department is tightening audit windows for Building Management System upgrades. Hospital Authority estates in this corridor are issuing integrated facilities contracts combining infection control with predictive maintenance protocols.
New Territories
Public housing estates under Hong Kong Housing Authority stewardship sustain volume demand for security and cleaning services. Mandatory staffing ratios under the Security and Guarding Services Ordinance inflate labor costs across 24/7 shift operations. Data center facilities in Tseung Kwan O Industrial Estate are commissioning specialized cooling contracts outside traditional commercial FM scopes.
Kai Tak Development Zone
Mixed-use integrated living-work concepts are bundling residential concierge with commercial FM under single operators. The Buildings Department enforces safety standards that shape procurement specifications for new developments. Strata-title management committees here are experimenting with single-source vendor accountability structures.
Wong Chuk Hang
Former industrial precincts converting to creative office and residential用途 are driving retrofit-focused FM procurement. Smart building mandates from the Electrical and Mechanical Services Department accelerate IoT sensor deployment for real-time energy monitoring. Aging pneumatic controls in 1980s-era stock require phased digital retrofits that disrupt tenant operations.
Hong Kong Facility Management Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in technical maintenance niches. Hong Kong's facility management sector exhibits tiered concentration around multinational property consultancies, local mid-market operators, and specialized security or cleaning contractors. Three archetypes dominate: integrated platform providers bundling full-service accountability, estate-focused specialists leveraging Housing Authority relationships, and compliance-certified technical contractors serving regulated verticals. Vendor consolidation accelerates through integrated service contract mandates, while certification bottlenecks around ISO 41001 and BIS compliance freeze new entrants from premium commercial portfolios.
Among platform integrators, CBRE and Jones Lang LaSalle IP, Inc. exemplify the multinational consultancy model with cross-border service bundling capabilities. Savills Hong Kong Limited and Knight Frank Hong Kong Limited EAA occupy positions within the premium residential and retail stewardship tier. Kai Shing Management Services Limited represents the localized estate specialist archetype through deep embeddedness with public housing portfolios. G4S Facility Services Hong Kong Limited sits within the security-dominant contractor segment where mandatory staffing ratios under local ordinances constrain margin flexibility. ISS A/S exemplifies the diversified European FM operator seeking scale in Asian commercial markets.
| Leading Market Players |
|---|
| Urban Group |
| CBRE |
| Savills Hong Kong Limited |
| Hongkong Land |
| Kai Shing Management Services Limited |
| Knight Frank Hong Kong Limited EAA |
| ISS A/S |
| Jones Lang LaSalle IP, Inc. |
| G4S Facility Services Hong Kong Limited |
| Others |
Supply & Pricing Matrix
Port of Hong Kong container freight corridors feed directly into facility management cost structures, with logistics premiums compressing margins on imported BMS hardware and IoT sensor networks while amplifying price differentiation between certified technical contractors and labor-intensive service providers.
Pricing Analysis
Customization-premium spreads separate ISO 41001-certified integrated service contracts from standard cleaning and security procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with penalty-linked KPI contracts commanding substantial premiums in Central and Admiralty Grade A towers. Cost compression in the standard tier intensifies because minimum wage ordinances inflate labor expenses without corresponding rate adjustment mechanisms. Public housing estates under Housing Authority stewardship exhibit the highest price sensitivity, while financial services tenants in Hong Kong Island premium stock demonstrate minimal sensitivity to service premiums.
Supply Chain Analysis
Tariff exposure between mainland China and the United States dominates supply chain risk planning for Building Management System hardware and IoT sensor components. Geographic supply concentration centers on mainland China for BMS controllers, Taiwan for semiconductor components, and Japan for precision HVAC instrumentation. Raw material dependencies draw from copper wiring systems, LED lighting arrays, and pneumatic-to-digital retrofit kits. Single-source vulnerability persists around proprietary legacy protocol middleware forcing costly integration investments. Distribution runs through electrical and mechanical services distributors serving strata-title management committees and direct procurement channels for multinational property consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hong Kong's facility management sector sits at a platform-economics inflection where BIM-integrated FM handovers and digital twin standardization are collapsing commissioning timelines and reshaping vendor interoperability requirements.
For Market Incumbents: Entrench platform dominance by deepening backward integration into predictive maintenance software stacks and securing exclusive BIS certification pathways before audit frequency mandates tighten. ISO 41001 compliance bottlenecks threaten to freeze mid-tier competitors from premium commercial portfolios, creating consolidation leverage for established operators with existing certification infrastructure.
For New Entrants and Emerging Players: Mid-market commercial buildings in Tsim Sha Tsui and Causeway Bay represent the most penetrable entry point, where aging stock demands elevator modernization and facade maintenance bundling without incumbent lock-in. Healthcare facilities in Kowloon and New Territories offer secondary white-space through infection control specialization requirements. A go-to-market angle anchored to BEA-certified energy audit services bypasses direct competition with integrated platform providers.
For Investors and Strategic Acquirers: Buildings Energy Efficiency Ordinance disclosure tightening reshapes the acquisition landscape toward technical contractors with continuous monitoring infrastructure and carbon advisory capabilities. Long-term viability favors operators capable of bridging compliance infrastructure into recurring revenue streams rather than project-dependent retrofit cycles. The signal to watch is EMSD audit window compression accelerating vendor consolidation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 41001 Certification Investment | Unlocks multinational corporate tenant portfolios where BIS compliance is mandatory. |
| Digital Twin Platform Integration | Enables Swire Properties and Link REIT to mandate BIM-integrated FM handovers as contractual baselines. |
| Healthcare Facilities Specialization | Captures Hospital Authority bundled contracts merging infection control with predictive maintenance protocols. |
| Carbon Advisory Service Launch | Aligns with Stock Exchange of Hong Kong ESG reporting requirements for energy baseline establishment. |
| Data Center Cooling Contracts | Addresses hyperscale cloud operators in Tseung Kwan O Industrial Estate outside traditional commercial scopes. |
Research Methodology
Cross-validation between Buildings Department regulatory filings and Electrical and Mechanical Services Department audit records anchors the qualitative findings. Primary interviews with facility management directors, strata-title management committee chairs, BMS commissioning engineers, and Hospital Authority procurement officers were synthesized with secondary validation from EMSD energy consumption disclosures, Buildings Energy Efficiency Ordinance compliance databases, and Hong Kong Housing Authority contract award records. Bottom-up service-type demand modeling and top-down macroeconomic triangulation were applied throughout.
Calibration against historical contract award values and disclosed vendor relationships informed the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, end-user vertical, technology integration level, and facility ownership structure. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and vendor consolidation patterns. Forecast inputs incorporated EMSD audit frequency acceleration scenarios and smart building mandate implementation timelines.
Stress conditions across labor cost inflation, certification bottleneck duration, and IoT protocol standardization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Sweden Facility Management Market
Facility Management
Romania Facility Management Market
Facility Management
North America Facilities Management Market
Facility Management
Serbia Facility Management Market
Facility Management
Oman Facility Management Market
Facility Management
Asia-Pacific Soft Facility Management Market
Facility Management
New Zealand Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Egypt Facility Management Market
Facility Management
Italy Facility Management Services Market
Facility Management
Indonesia Facility Management Market
Facility Management
Saudi Arabia Soft Facility Management Market
Facility Management
Croatia Facility Management Market
Facility Management
Vietnam Facility Management Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
Saudi Arabia Facility Management Market