
 Europe Hard Facility Management Market | 2026-2036
Europe Hard Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hard Facility Management Market Foresight
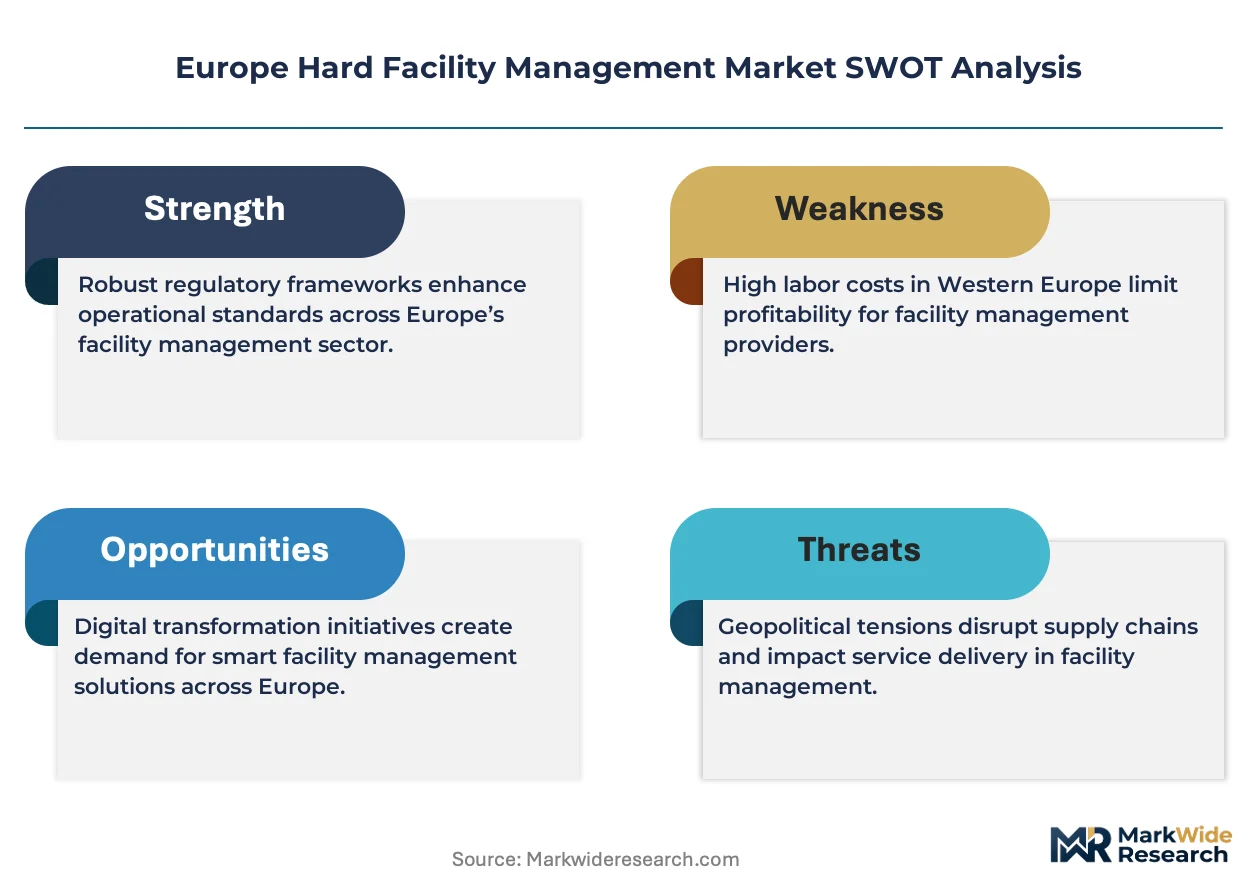
Asset-light service contracting and performance-based leasing is rewriting competitive entry barriers across Europe. Mitie Group leverages integrated technical services to anchor long-term contracts with UK public sector estates. ISS A/S sustains pan-European scale through standardized maintenance protocols across multiple facility types. Sodexo differentiates via energy performance guarantees tied to HVAC and building management outcomes.
Europe Hard Facility Management encompasses the physical maintenance, repair, and replacement of built infrastructure including mechanical, electrical, and structural systems with defined service level agreements governing uptime, thermal comfort thresholds, and regulatory compliance. The discipline ensures operational continuity of commercial, industrial, and institutional assets through scheduled preventive programs and reactive intervention protocols. Maintenance Services currently leads revenue contribution due to recurring contractual obligations and regulatory inspection mandates. IoT Solutions represents the fastest-expanding technology segment as sensor networks enable condition-based monitoring of critical plant equipment. Commercial Buildings constitute the dominant facility category, though Healthcare Facilities command premium pricing through specialized infection control and life-safety system requirements.
EU F-Gas Regulation and Ecodesign Directive jointly mandate refrigerant phase-down and minimum efficiency standards for building services equipment, directly shaping replacement cycles and technician certification requirements. ECHA REACH compliance adds material sourcing constraints on maintenance consumables and replacement components. Facility operators must monitor evolving MDR-equivalent standards for building system safety and emerging CSRD disclosure obligations affecting corporate real estate portfolios.
Market Dynamics
EU F-Gas Regulation phase-down mandates and Ecodesign Directive efficiency standards are compressing replacement cycles for HVAC and refrigeration equipment across European commercial estates. These twin regulatory pressures force asset owners into accelerated capital deployment while reshaping contractor certification requirements and service pricing structures.
Growth Catalysts
- IoT sensor networks:Condition-based monitoring systems reduce unplanned downtime in critical healthcare and data center environments. Building operators deploy wireless vibration and thermal sensors to transition from calendar-based to predictive maintenance protocols.
- Healthcare facility expansion:German hospital modernization programs under federal infrastructure investment frameworks drive specialized hard FM contracting for infection control and life-safety systems. Aging clinical estates require mechanical and electrical upgrades to meet current technical standards.
- Energy Performance of Buildings Directive:Recast EPBD mandates drive deep renovation of commercial stock across member states. Minimum energy performance standards trigger HVAC replacement and building envelope remediation at scale.
Market Restraints
- Refrigerant supply concentration:EU F-Gas quota reductions create input cost volatility for maintenance consumables. Contractors face sourcing constraints on hydrofluorocarbon alternatives during equipment servicing.
- Technician certification bottlenecks:F-Gas certification requirements and Ecodesign installer competence schemes limit qualified labor supply. Training program capacity lags behind regulatory expansion timelines.
- Electrification infrastructure gaps:Grid connection delays and capacity constraints impede heat pump deployment in commercial retrofits. Building system electrification plans stall awaiting utility-side reinforcement.
Strategic Opportunities
- Polish and Romanian commercial stock:Underpenetrated markets in Central and Eastern Europe present expansion corridors for standardized maintenance protocols. Western European service providers establish local partnerships to capture outsourcing momentum.
- CSRD-aligned disclosure services:Corporate Sustainability Reporting Directive obligations create demand for building-level energy and maintenance data analytics. FM contractors bundle asset performance tracking with compliance documentation.
- Digital twin convergence:Integration of BIM models with real-time sensor feeds enables simulation-driven maintenance scheduling. Engineering consultancies and FM operators co-develop predictive asset management platforms.
Industry Challenges
- Electromechanical skill shortages:Cross-trained technicians capable of integrated HVAC, electrical, and controls work remain scarce. Vocational pipeline output insufficient to replace retiring workforce cohorts.
- Legacy system interoperability:Proprietary building automation protocols impede unified data collection across mixed-vendor estates. Retrofit integration projects require custom middleware development.
- REACH compliance complexity:ECHA substance restrictions on maintenance chemicals and replacement components extend procurement lead times. Material substitution validation adds administrative burden to routine operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hard Facility Management Market |
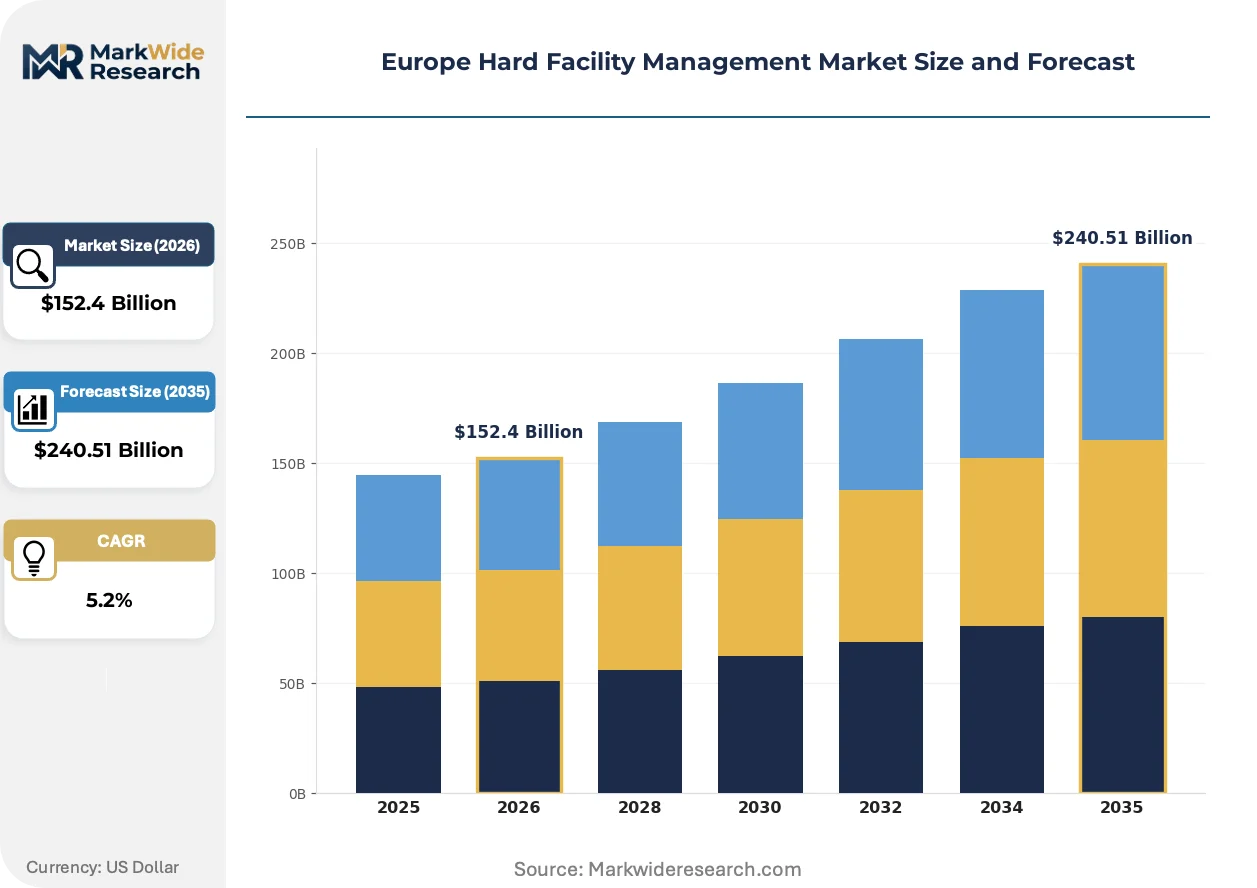
| Market Size in 2026 | $152.4 Billion |
| Market Size in 2035 | $240.51 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance Services, Repair Services, Installation Services, Security Services Technology: IoT Solutions, Building Management Systems, Energy Management Systems, HVAC Technology Facility Type: Commercial Buildings, Educational Institutions, Industrial Facilities, Healthcare Facilities Service Provider Type: In-House Facilities Management, Outsourced Service Providers, Specialized Contractors, Consultants |
| Companies Covered | Johnson Controls International, Jones Lang LaSalle, Sodexo, Atalian Services, Mitie Group, ISS A/S, VINCI Facilities, Emcor Facilities Services, CBRE Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hard Facility Management Market Shifts & Advancements
Edge computing architectures and machine learning inference at the sensor level are transforming how building systems generate actionable maintenance intelligence. This shift compresses response latency and enables autonomous equipment intervention before human dispatch.
Digital twin technology is collapsing the distinction between design-phase BIM and operational-phase asset management. Engineering firms and FM operators deploy synchronized virtual replicas to simulate thermal performance degradation and optimize replacement sequencing. Major hospital estates in France and the United Kingdom adopt these platforms to coordinate infection control with energy efficiency interventions.
F-Gas Regulation refrigerant phase-down schedules tighten procurement constraints on hydrofluorocarbon-dependent equipment. The industrial consequence accelerates natural refrigerant adoption in commercial refrigeration and heat pump applications. Scandinavian retail chains and Central European cold storage operators lead the transition to CO2 and ammonia systems, pressuring southern European laggards through supply chain audit requirements.
Consolidated procurement by real estate investment trusts and institutional asset managers concentrates contract scale with integrated service providers. Single-source technical services displace fragmented specialist subcontracting in premium commercial portfolios. This concentration most visibly reshapes competitive dynamics in London, Frankfurt, and Paris central business districts where trophy assets command performance-guaranteed contracting structures.
Europe Hard Facility Management Market Segmentation
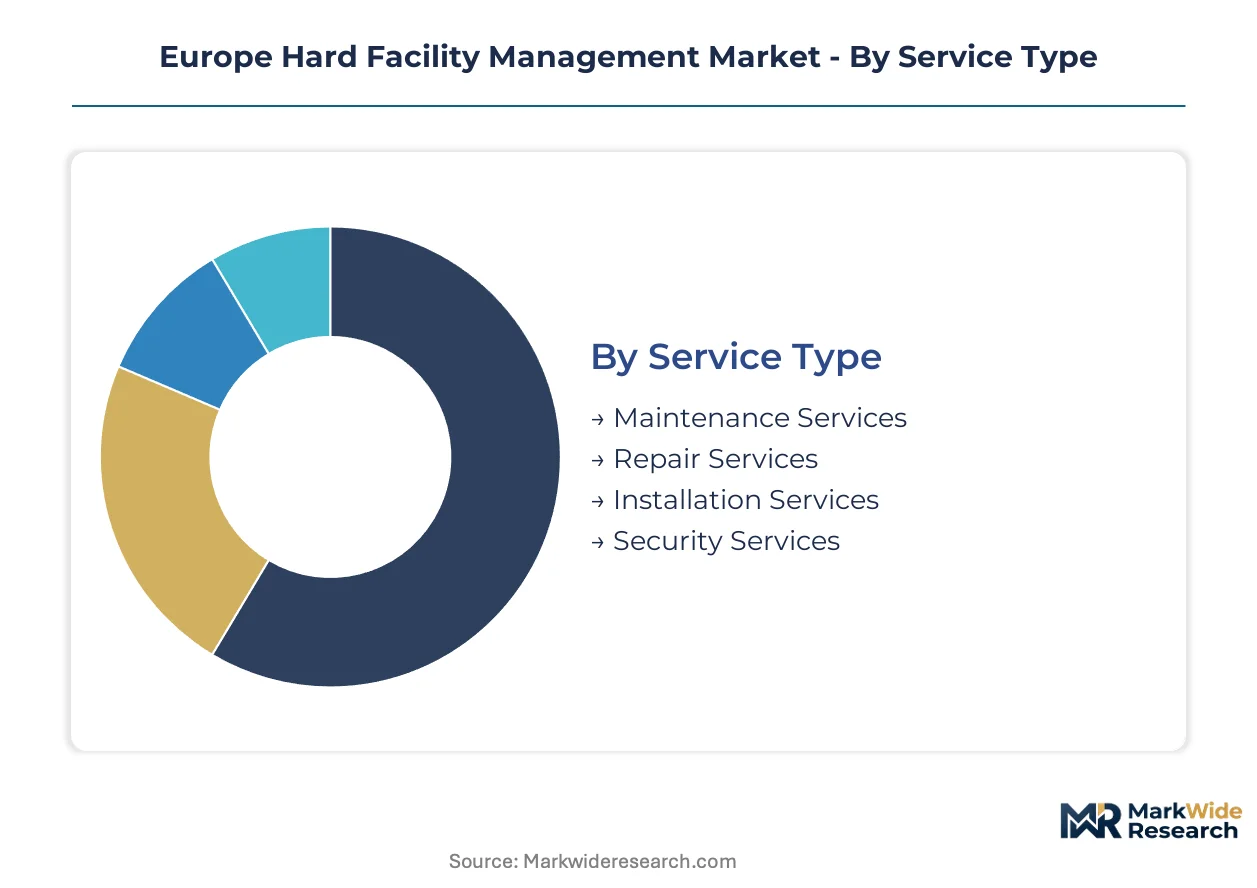
Segmentation in Europe Hard Facility Management reveals how regulatory pressure and asset complexity fragment contract structures across service tiers and technology adoption curves. Distinct procurement patterns emerge between legacy estate maintenance and digitally-enabled predictive programs.
Service Type:
Cost tier differentiation separates routine operational expenditure from capital-intensive system interventions across European commercial portfolios.
- Maintenance Services:Scheduled preventive programs covering mechanical, electrical, and structural systems under recurring contractual obligations. German hospital estates and UK public sector buildings concentrate demand here due to Ecodesign inspection mandates and F-Gas compliance requirements.
- Repair Services:Reactive intervention protocols addressing equipment failure and system degradation outside planned maintenance windows. French commercial landlords facing EPBD renovation deadlines drive demand for emergency HVAC and building envelope remediation.
- Installation Services:New equipment deployment and system replacement during retrofit or construction phases.
- Security Services:Physical access control and life-safety system maintenance including fire suppression and intrusion detection.
Maintenance Services commands the established base. The steepest expansion runs through Repair Services as aging building stock accelerates reactive intervention volumes.
Technology:
Application maturity varies sharply between legacy building automation and emerging sensor-network architectures.
- IoT Solutions:Wireless sensor networks enabling condition-based monitoring of critical plant equipment through vibration, thermal, and current signature analysis. Scandinavian data center operators and Dutch healthcare estates deploy these systems to compress response latency before human dispatch.
- Building Management Systems:Centralized control platforms integrating HVAC, lighting, and access systems across single or multi-site estates.
- Energy Management Systems:Metering and analytics platforms tracking consumption patterns against CSRD disclosure obligations and EPBD performance benchmarks.
- HVAC Technology:Equipment-specific controls and optimization tools addressing refrigerant phase-down compliance and heat pump electrification.
Building Management Systems anchors existing infrastructure. IoT Solutions gains share fastest as edge computing architectures mature.
Facility Type:
Customer type concentration shapes pricing power and contract duration across institutional versus commercial asset classes.
- Commercial Buildings:Office, retail, and hospitality estates requiring standardized maintenance protocols across large portfolios. London, Frankfurt, and Paris central business districts concentrate contract scale with integrated service providers seeking performance-guaranteed structures.
- Healthcare Facilities:Hospitals and clinical estates demanding specialized hard FM for infection control, life-safety systems, and uninterrupted critical plant operation. German federal infrastructure investment programs and UK NHS estate modernization drive premium pricing through specialized certification requirements.
- Educational Institutions:Universities and school districts with seasonal occupancy patterns and public procurement constraints.
- Industrial Facilities:Manufacturing and logistics assets requiring heavy mechanical maintenance and production-critical uptime guarantees.
Commercial Buildings holds the volume base. Healthcare Facilities climbs the fastest as clinical estate modernization accelerates across Germany, France, and the United Kingdom.
Service Provider Type:
Supply concentration dynamics determine competitive intensity and margin structure across integrated versus fragmented delivery models.
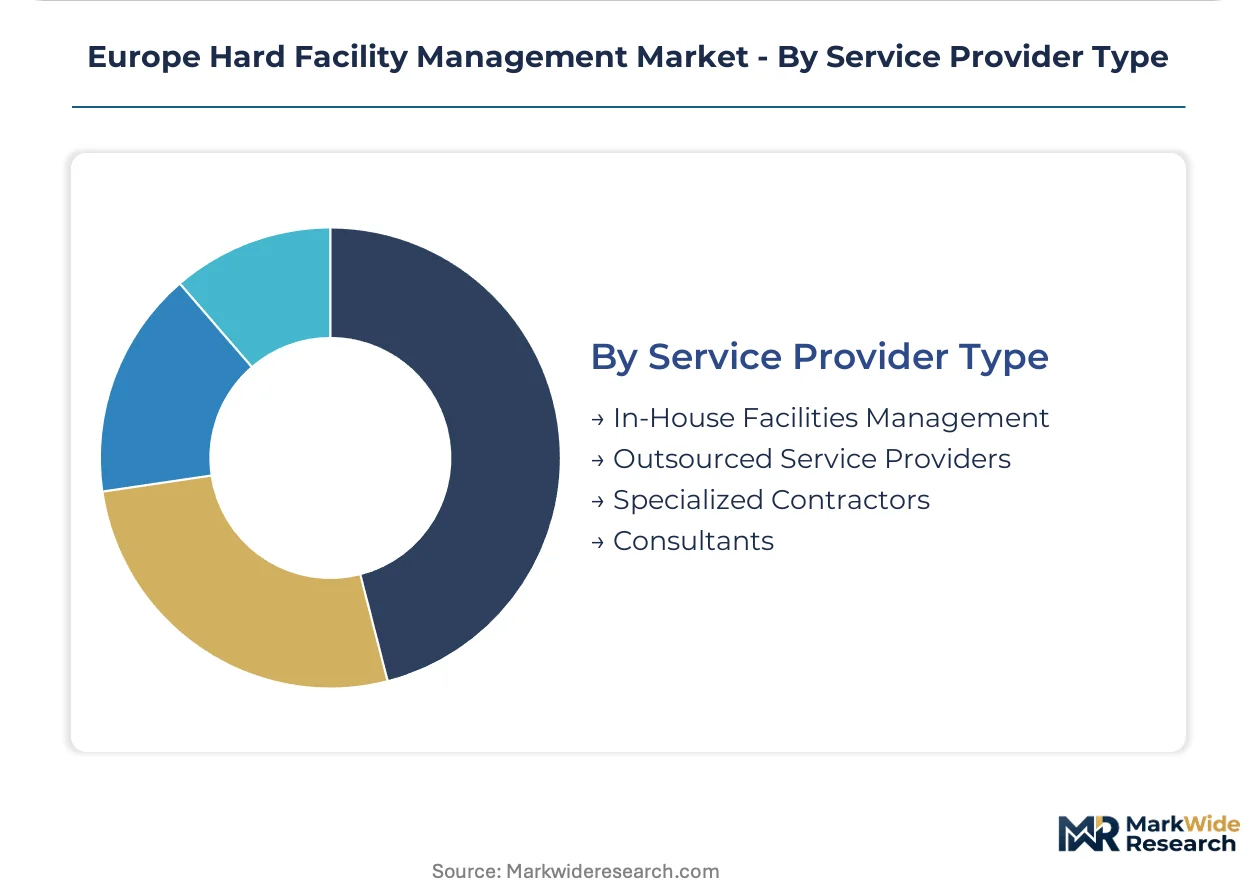
- Outsourced Service Providers:Pan-European FM operators delivering standardized technical services across multiple facility types and geographies. UK public sector estates and Dutch commercial portfolios favor these providers for long-term integrated contracts bundling maintenance, energy management, and compliance documentation.
- In-House Facilities Management:Captive teams employed directly by asset owners, predominant in specialized industrial and critical infrastructure settings.
- Specialized Contractors:Niche providers focused on single technical disciplines such as HVAC, electrical, or fire safety systems.
- Consultants:Advisory services for asset strategy, compliance navigation, and digital transformation program design.
Outsourced Service Providers dominates contract value. Specialized Contractors expands most quickly as complex regulatory compliance drives demand for certified technical expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European Hard Facility Management services flow predominantly intra-regionally, with German engineering expertise and UK operational models exporting into Central and Eastern European markets. Import dependency concentrates on specialized HVAC components and refrigerants subject to F-Gas quota constraints.
Germany
Hospital modernization programs under federal infrastructure frameworks drive specialized contracting for infection control systems. The F-Gas Regulation and Ecodesign Directive mandate accelerated HVAC replacement cycles across clinical estates. Frankfurt and Munich commercial districts concentrate integrated service provider contracts with performance-guaranteed structures.
United Kingdom
NHS estate modernization and public sector outsourcing sustain demand for technical services bundling maintenance with compliance documentation. The Building Safety Act imposes stricter accountability on life-safety system maintenance. London's central business district anchors premium contracting for trophy assets requiring uptime guarantees.
France
EPBD renovation deadlines force commercial landlords into emergency HVAC and building envelope remediation. ECHA REACH compliance adds material sourcing constraints on maintenance consumables. The Paris metropolitan area concentrates REIT procurement consolidating contract scale with integrated operators.
Netherlands
Data center expansion and healthcare estate digitization drive IoT-enabled predictive maintenance adoption. The Energy Performance of Buildings Directive recast mandates deep renovation of commercial stock. Amsterdam and Rotterdam harbor districts concentrate facility management innovation around edge computing architectures.
Poland
Underpenetrated commercial stock presents expansion corridors for standardized maintenance protocols from Western European providers. EU cohesion funds support building system upgrades in public infrastructure. Warsaw and Kraków office markets anchor outsourcing momentum as institutional investors acquire premium assets.
Europe Hard Facility Management Market Competitive Landscape
On the supply side, the industry is consolidating around integrated service providers capable of bundling technical maintenance with regulatory compliance and energy performance documentation. Pan-European operators compete against specialized national contractors through standardized protocols and long-term estate partnerships. Three archetypes dominate: diversified facility conglomerates, pure-play technical services specialists, and real estate advisory firms with captive FM divisions. Competitive moves center on portfolio diversification into adjacent energy management services and strategic partnerships to secure refrigerant supply chains.
Among diversified facility conglomerates, Sodexo and ISS A/S exemplify the pan-European scale archetype through standardized maintenance protocols across multiple facility types. Mitie Group occupies a position representing UK-centric integrated technical services with public sector estate anchoring. Johnson Controls International sits within the technology-integrated tier, bridging HVAC equipment manufacturing with service delivery.
| Leading Market Players |
|---|
| Johnson Controls International |
| Jones Lang LaSalle |
| Sodexo |
| Atalian Services |
| Mitie Group |
| ISS A/S |
| VINCI Facilities |
| Emcor Facilities Services |
| CBRE Group |
| Others |
Supply & Pricing Matrix
Undercapacity in F-Gas-certified technician training across Germany and France is compressing service pricing flexibility while elevating labor cost pass-throughs to asset owners. This utilization squeeze forces contractors into premium positioning for compliance-linked maintenance contracts.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across German and UK commercial estates. Three-tier pricing structure across premium, standard, and economy levels separates F-Gas-certified specialist providers from generalist contractors and unbundled repair services. Cost compression in standard-tier maintenance is intensifying because REACH-compliant material substitution extends procurement lead times. Public sector estates exhibit highest price sensitivity due to procurement framework constraints, while healthcare facilities demonstrate lowest sensitivity given life-safety system mandates.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates refrigerant and HVAC component sourcing strategies for continental contractors. Manufacturing concentrates in Germany, Italy, and Poland for building automation hardware, while hydrofluorocarbon alternatives draw from Chinese and Indian chemical producers. Supply chain risk centers on single-source vulnerability for IoT sensor modules used in predictive maintenance deployments. Distribution runs through pan-European FM operators with captive logistics networks serving multi-site commercial portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-house facilities management teams represent a substitution threat as asset owners internalize IoT-enabled predictive capabilities, forcing outsourced providers to demonstrate superior compliance and energy performance outcomes.
For Market Incumbents: Insulate contract renewal rates by embedding CSRD-aligned disclosure services into standard maintenance agreements. Deepen backward integration into refrigerant supply chains to offset F-Gas quota volatility. Prioritize certification investment in natural refrigerant handling competence ahead of CO2 and ammonia system adoption curves. For New Entrants and Emerging Players: Pursue underpenetrated Polish and Romanian commercial office markets through partnerships with Western European operators seeking geographic expansion. Target data center operators in the Netherlands with edge-computing maintenance platforms. Lead with energy performance guarantee structures rather than cost-plus contracting to differentiate from established incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pan-European operators with integrated technical services and long-term public sector estate anchoring. Five-to-ten-year viability favors acquisition targets with demonstrated F-Gas certification scale and IoT solution deployment capabilities. Monitor heat pump electrification infrastructure buildout as the inflection signal for contractor pricing power recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Scale-Up | F-Gas and natural refrigerant competence expansion captures regulatory-mandated replacement cycles across German clinical estates. |
| IoT Platform Integration | Edge computing sensor networks enable condition-based monitoring contracts with compressed response latency for Dutch data centers. |
| Backward Integration | Captive refrigerant supply hedges against EU quota reductions and sourcing constraints on hydrofluorocarbon alternatives. |
| CSRD Service Bundling | Building-level energy analytics and compliance documentation deepen stickiness with REIT procurement committees in Paris and London. |
| Geographic Partnership | Local alliances in Warsaw and Kraków office markets capture outsourcing momentum as Western European providers expand eastward. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with facilities directors at German hospital estates, UK NHS estate managers, commercial property asset managers in France, and technical service heads at pan-European FM operators. Secondary validation drew from ECHA REACH substance databases, EU F-Gas Regulation quota filings, EPBD transposition documents across member states, and trade data for HVAC equipment imports. Bottom-up contract value analysis triangulated against top-down sector expenditure estimates from national statistical offices.
Calibration against historical maintenance outsourcing penetration and regulatory compliance cost trajectories informed the analytical framework across the analysis window. Segmentation dimensions modeled include service type, technology adoption tier, facility category, and service provider archetype. CAGRs were derived from fitted growth curves incorporating replacement cycle acceleration under Ecodesign Directive mandates and technician supply constraints.
Macroeconomic conditions sit as an overlay; deviation in commercial real estate investment volumes and EU cohesion fund disbursement schedules would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology adoption S-curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Romania Facility Management Market
Facility Management
Lithuania Facility Management Market
Facility Management
Moldova Facility Management Market
Facility Management
New Zealand Facility Management Market
Facility Management
Canada Facility Management Market
Facility Management
Saudi Arabia Soft Facility Management Market
Facility Management
Ireland Facility Management Market
Facility Management
Brazil Facility Management Market
Facility Management
Czech Republic Facility Management Market
Facility Management
Nigeria Facility Management Services Market
Facility Management
Saudi Arabia Facility Management Market
Facility Management
Africa Facility Management Market
Facility Management
Italy Facility Management Services Market
Facility Management
India Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
GCC Facility Management Market