
 Asia-Pacific Polyvinyl Chloride (PVC) Market | 2026-2036
Asia-Pacific Polyvinyl Chloride (PVC) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Polyvinyl Chloride (PVC) Market Outlook
China's dual carbon goals is expanding the compliance burden on chlor-alkali integrated producers, forcing upstream energy and feedstock transitions across the PVC value chain. Xinjiang Zhongtai Chemical leverages captive coal-chemical integration to sustain cost leadership in rigid resin output. Shin-Etsu Chemical anchors high-purity medical-grade PVC supply through proprietary suspension polymerization technology. Formosa Plastics Corporation competes across flexible film and sheet segments with deep backward integration into VCM monomer production.
Asia-Pacific Polyvinyl Chloride denotes a thermoplastic polymer synthesized from vinyl chloride monomer through suspension, emulsion, or bulk polymerization, typically containing 56.7% chlorine by mass and exhibiting flame resistance, chemical stability, and mechanical durability across rigid and plasticized formulations. The resin serves primarily as a structural and protective material in construction piping, electrical insulation, medical devices, and automotive interior components. Rigid PVC dominates volume flows through its penetration in potable water distribution and drainage infrastructure across tropical climates. Flexible PVC commands premium positioning in healthcare tubing and automotive wire harness sheathing where phthalate-free plasticizer formulations are displacing legacy compounds. CPVC extends performance thresholds into hot-water plumbing and industrial chemical handling, capturing margin pools in retrofit and specification-grade construction.
China's MEE enforces emissions intensity benchmarks on carbide-based acetylene routes, while India's BIS mandates ISI certification for potable water contact applications, and Japan's METI oversees JIS-compliant building material standards that shape cross-border product acceptance. Regulatory divergence across these frameworks fragments certification costs and favors producers with multi-jurisdictional testing capabilities. Stakeholders must monitor feedstock cost spreads between ethylene-based and carbide-based routes while calibrating capacity additions to evolving national building codes and infrastructure procurement timelines.
Market Dynamics
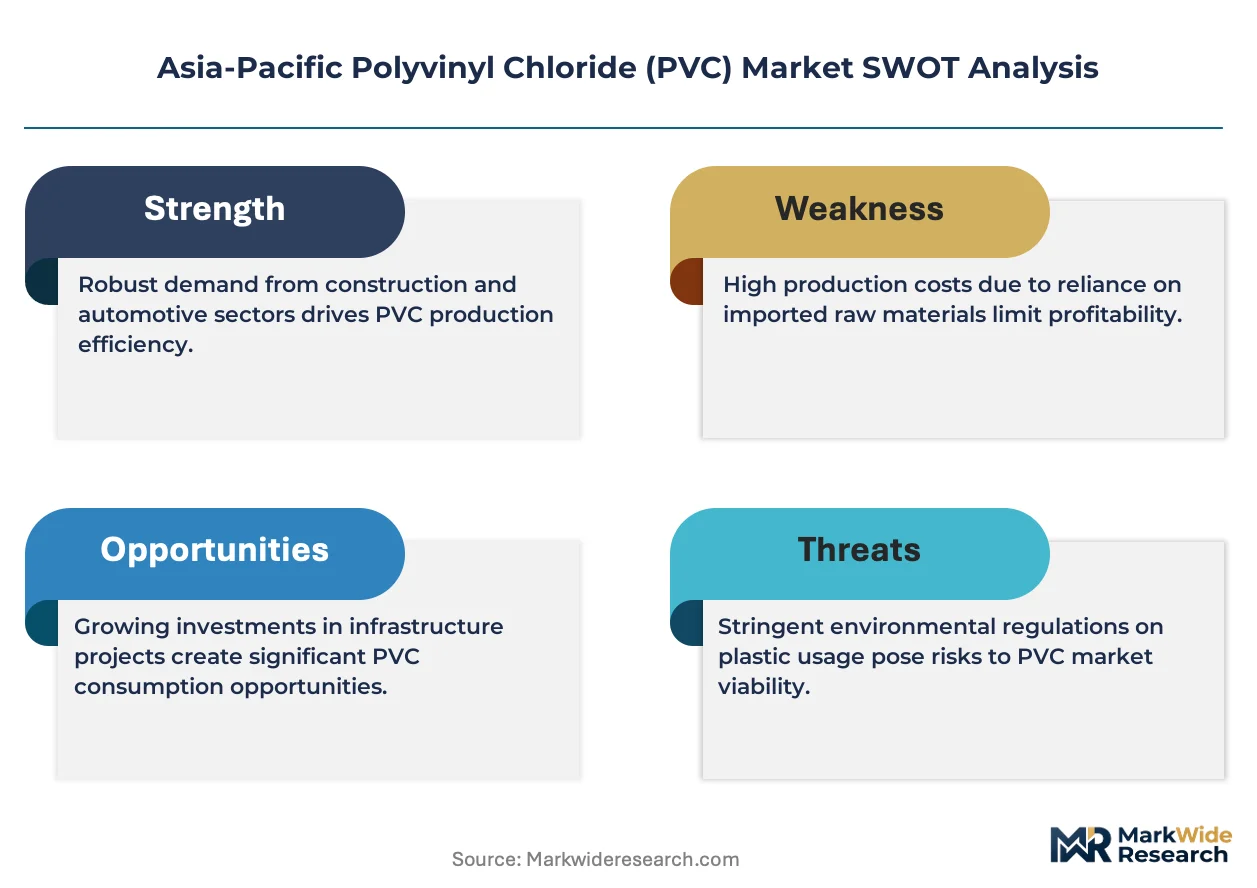
Carbide-based PVC production in China faces mounting emissions intensity benchmarks under MEE enforcement, forcing producers to absorb carbon compliance costs or pivot toward ethylene feedstock integration.
Growth Catalysts
- India's BIS ISI certification mandate:Potable water contact applications now require certified resin grades, concentrating procurement among qualified suppliers in Gujarat and Maharashtra pipe extrusion clusters.
- Phthalate-free plasticizer transition:Healthcare tubing and automotive wire harness manufacturers are reformulating flexible PVC compounds to meet Japan's METI chemical safety guidelines.
- Southeast Asian infrastructure corridors:Government procurement for drainage and irrigation systems in Vietnam, Indonesia, and Thailand is accelerating rigid PVC pipe specifications.
Market Restraints
- Coal-chemical feedstock volatility:Xinjiang-based acetylene route producers face unstable anthracite pricing and electricity cost fluctuations tied to regional energy rationing.
- Ethylene import dependency:India and Southeast Asian nations without naphtha cracking capacity remain exposed to Middle East ethylene price swings and freight cost spikes.
- Cross-linked polyethylene substitution:PEX tubing is displacing CPVC in residential hot-water plumbing across premium construction segments in Japan and South Korea.
Strategic Opportunities
- India's western industrial belt expansion:Dahej and Hazira petrochemical complexes offer greenfield VCM integration potential for resin producers targeting domestic pipe demand.
- Medical-grade suspension polymerization:High-purity formulations for blood bags and IV tubing command premium positioning as healthcare infrastructure modernizes across ASEAN markets.
- China's dual carbon technology export:Electrolytic hydrogen and biomass-ethylene pilot projects create licensing and equipment sale channels for decarbonization-enabling technologies.
Industry Challenges
- Multi-jurisdictional certification timelines:Producers must sequence BIS, JIS, and GB standard testing in parallel to avoid procurement disqualification across integrated supply contracts.
- Chlor-alkali asset retooling capex:Membrane cell conversion and mercury phase-out requirements demand capital deployment ahead of regulatory deadlines without guaranteed offtake pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Polyvinyl Chloride (PVC) Market |
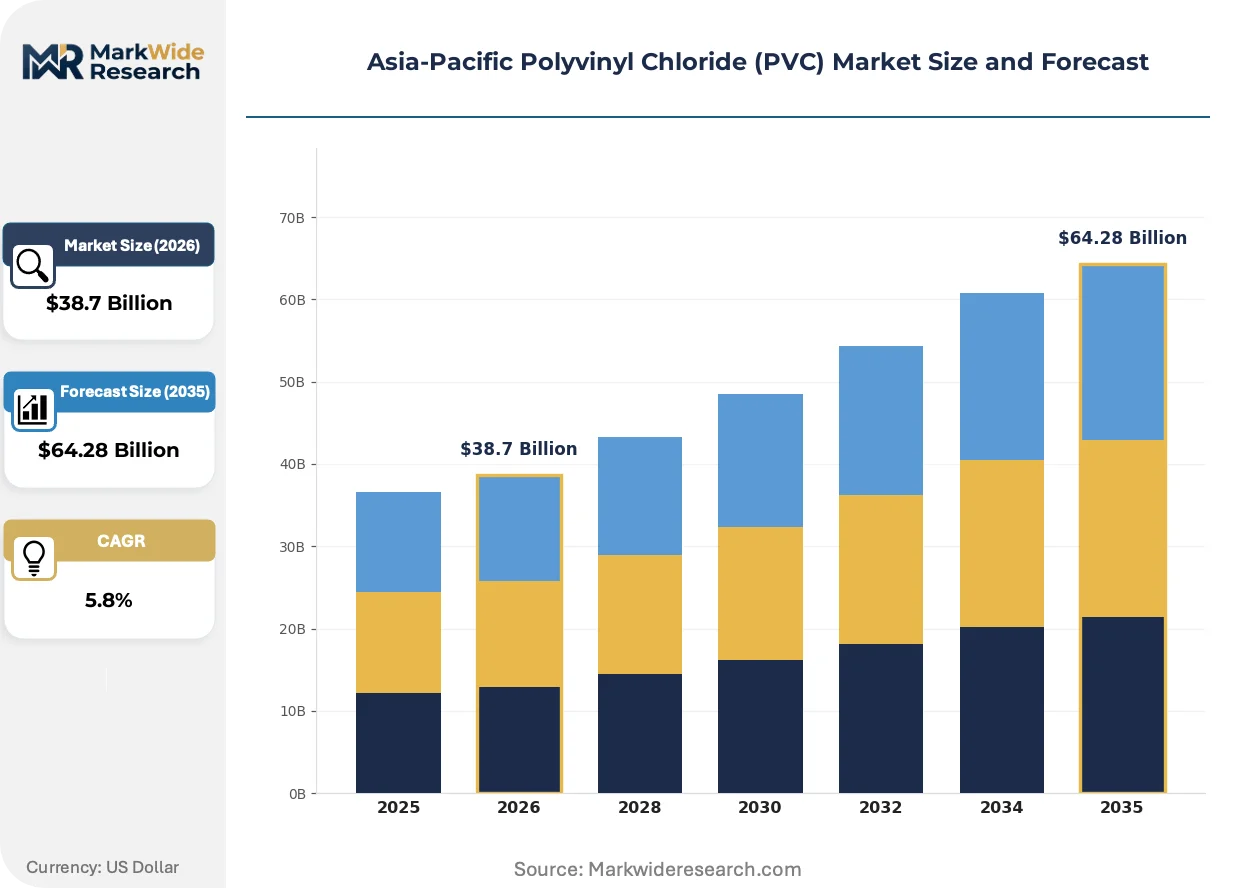
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid PVC, Flexible PVC, CPVC, PVC Foam Application: Construction, Automotive, Electrical, Healthcare End User: Manufacturers, Distributors, Retailers, Contractors Form: Pipes, Sheets, Films, Coatings |
| Companies Covered | Hanwha Solutions, Xinjiang Zhongtai Chemical, Shin-Etsu Chemical, Reliance Industries Limited, Sinochem Holdings Corporation, Formosa Plastics Corporation, ChemChina, INEOS, LG Chem, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Polyvinyl Chloride (PVC) Market Strategic Shifts
Digital twin modeling and predictive maintenance systems are penetrating chlor-alkali operations, while downstream formulation labs accelerate bio-based plasticizer screening.
Distributed control systems with embedded emissions monitoring are modularizing carbide-based plant retrofits. MEE-inspected facilities in Inner Mongolia and Ningxia are adopting these platforms to automate benchmark reporting. The technology is compressing compliance verification cycles from quarterly to real-time.
China's GB standards for building materials now incorporate recycled content traceability requirements. This is fragmenting resin sourcing as construction developers demand batch-level certification. Rigid pipe extruders in the Yangtze River Delta are responding by qualifying secondary PVC feedstock suppliers.
Specification-grade procurement now dominates infrastructure tenders across India's Smart Cities Mission. Municipal engineers are unbundling material certification from installation contracts, forcing resin producers to maintain dedicated technical liaison teams. This pattern is most visible in Maharashtra's urban water distribution retrofit programs.
Asia-Pacific Polyvinyl Chloride (PVC) Market Segmentation
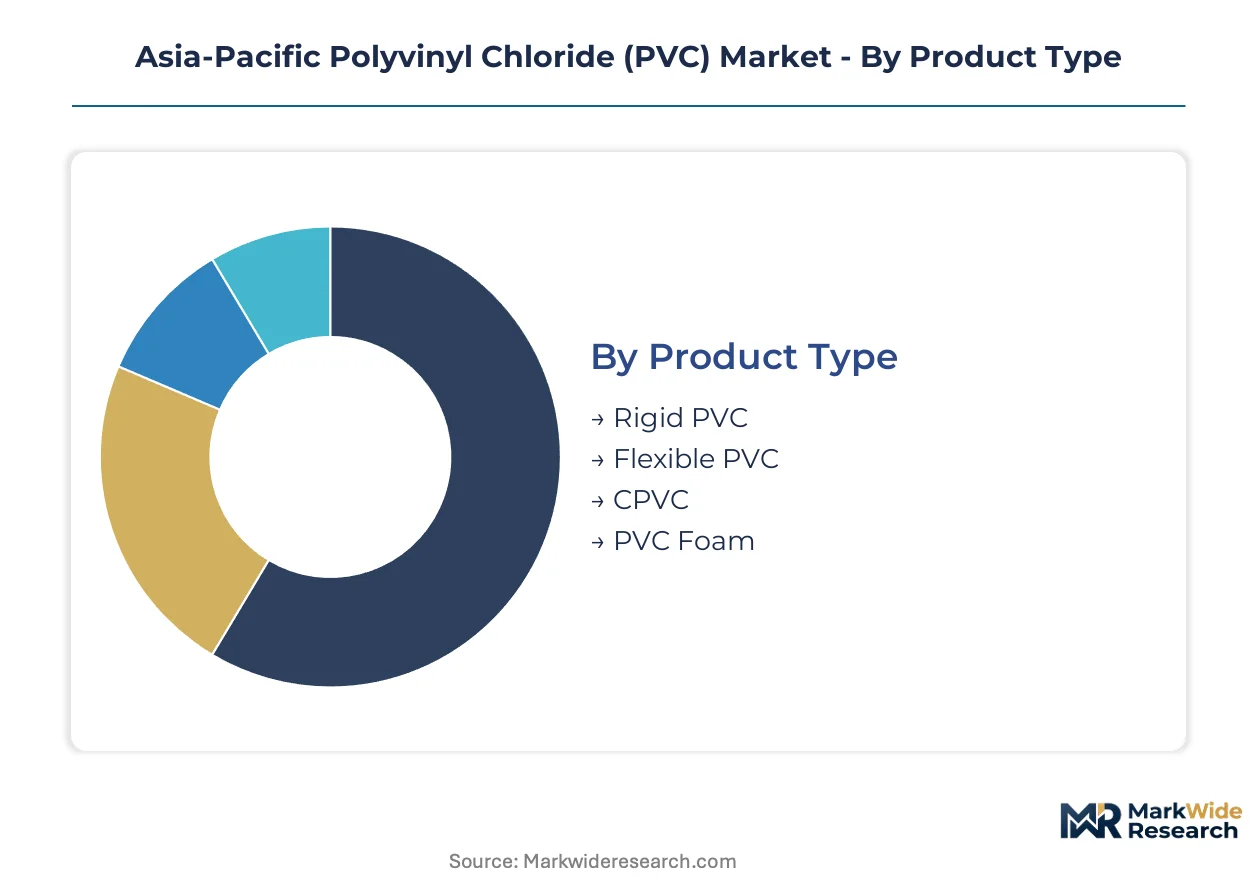
PVC resin flows through distinct product grades and form factors that command different margin structures and certification requirements across Asia-Pacific. Segmentation clarity enables producers to align capacity investments with the most defensible demand pools.
Product Type:
Integration depth varies sharply across product types, with some grades serving as standalone structural materials while others require compounding before end-use deployment.
- Rigid PVC:Unplasticized formulation containing zero external plasticizers delivers high tensile strength and dimensional stability. Demand concentrates in Maharashtra and Gujarat pipe extrusion clusters serving India's urban water distribution retrofits, driven by BIS ISI certification mandates that disqualify uncertified resin suppliers.
- Flexible PVC:Plasticized compounds with phthalate or bio-based alternatives achieve Shore A hardness ratings of 70-90. Medical tubing and automotive wire harness manufacturers in Japan's industrial corridors are reformulating to meet METI chemical safety guidelines, displacing legacy phthalate formulations.
- CPVC:Chlorinated variant tolerates continuous service temperatures to 93°C. Hot-water plumbing specifications in premium Japanese and South Korean residential construction.
- PVC Foam:Cellular structure achieved through chemical or physical blowing agents. Signage and display applications across Southeast Asian retail construction.
Rigid PVC leads volumes today; flexible PVC is gaining share fastest.
Application:
Margin capture potential tracks application complexity, with specification-grade procurement dominating infrastructure-linked segments.
- Construction:Piping, window profiles, and siding account for the dominant resin offtake. Southeast Asian infrastructure corridors in Vietnam, Indonesia, and Thailand are accelerating drainage and irrigation system procurement with rigid PVC specifications.
- Healthcare:Blood bags, IV tubing, and medical device housings demand high-purity suspension polymerization grades. ASEAN healthcare infrastructure modernization is expanding addressable demand for certified medical compounds.
- Automotive:Wire harness sheathing and interior trim panels require heat-stabilized formulations. Phthalate-free mandates from Japan's METI are forcing compound reformulation across regional auto supplier networks.
- Electrical:Cable insulation and conduit systems leverage flame-retardant properties intrinsic to chlorine content. India's western industrial belt expansion includes dedicated extrusion capacity for power distribution infrastructure.
Construction absorbs the largest resin volumes; healthcare commands the steepest premium expansion trajectory.
End User:
Channel structure determines working capital intensity and technical support requirements, with direct manufacturer relationships commanding preference in specification-grade segments.
- Manufacturers:Pipe extruders, film processors, and compounders purchase resin in bulk railcar or vessel quantities. Dahej and Hazira petrochemical complexes in India target this channel with integrated VCM-resin offerings.
- Distributors:Regional stockists buffer smaller processors from supply volatility. Multi-jurisdictional certification capabilities differentiate distributors serving cross-border construction supply chains.
- Retailers:Hardware and building material outlets serve renovation and repair demand. Urban water distribution retrofit programs in Maharashtra are unbundling material certification from installation contracts.
- Contractors:Installation-focused procurement concentrates in government infrastructure tenders. Smart Cities Mission specifications in India require dedicated technical liaison teams from resin producers.
Manufacturers dominate procurement value; distributors are expanding fastest as certification complexity fragments supply chains.
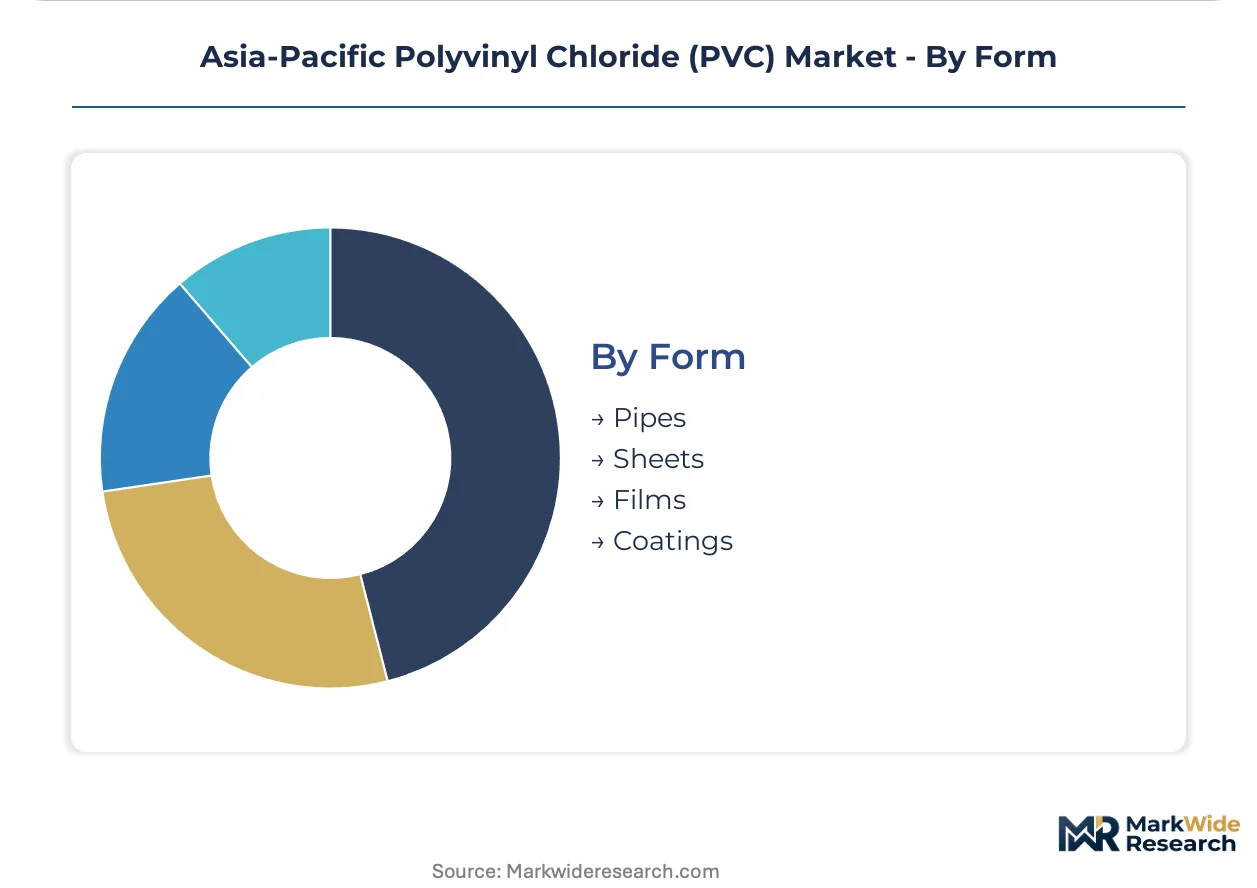
Form:
Processing technology and capital equipment requirements segment the market by form factor, with continuous extrusion dominating high-volume applications.
- Pipes:Extruded profiles for pressure and non-pressure applications represent the largest resin consumption form. Tropical climate potable water distribution across Southeast Asia drives specification-grade demand.
- Sheets:Calendered or extruded flat products serve construction and industrial applications. China's GB standards for recycled content traceability are fragmenting resin sourcing for specification-grade sheet.
- Films:Blown or cast thin-gauge products for packaging and medical applications. Flexible film segments compete with polyolefin alternatives on clarity and barrier performance.
- Coatings:Plastisol and organosol dispersions for dip-coating and spray applications. Protective coatings for metal substrates in industrial equipment.
Pipes consume the most resin by tonnage; sheets face the most acute certification-driven sourcing fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale PVC production first achieved commercial viability in Germany during the 1930s, with suspension polymerization patents establishing the technical foundation that Asia-Pacific producers later adapted for tropical climate applications and high-volume construction markets.
China
Carbide-based acetylene routes dominate domestic capacity, particularly in Inner Mongolia and Ningxia where coal-chemical integration clusters face tightening MEE emissions intensity benchmarks. The dual carbon policy framework is forcing chlor-alkali producers toward electrolytic hydrogen pilots and biomass-ethylene feedstock trials. Xinjiang-based operations sustain cost leadership through captive anthracite supply and regional electricity pricing advantages.
India
BIS ISI certification mandates for potable water contact applications are concentrating procurement among qualified suppliers in Gujarat and Maharashtra pipe extrusion clusters. Dahej and Hazira petrochemical complexes offer greenfield VCM integration potential as domestic demand outpaces local resin supply. The Smart Cities Mission is unbundling material certification from installation contracts, forcing technical liaison investments from producers.
Japan
METI chemical safety guidelines are driving phthalate-free plasticizer reformulation across automotive wire harness and medical tubing supply chains. JIS-compliant building material standards shape cross-border product acceptance for specification-grade construction exports. Kansai and Chubu industrial corridors host compounders serving premium healthcare and automotive segments.
South Korea
Cross-linked polyethylene substitution is displacing CPVC in residential hot-water plumbing across premium construction segments, pressuring chlorinated resin margins. Yeosu and Ulsan petrochemical complexes maintain ethylene-based PVC output with deep backward integration into naphtha cracking. Domestic producers are pivoting toward high-purity medical-grade formulations for ASEAN healthcare infrastructure modernization.
Vietnam
Government procurement for drainage and irrigation systems is accelerating rigid PVC pipe specifications across Mekong Delta infrastructure corridors. Import dependency on Chinese resin and VCM feedstock exposes processors to freight cost volatility and cross-border supply disruptions. Ho Chi Minh City-based extruders are qualifying regional secondary feedstock suppliers to meet recycled content traceability requirements in export-bound construction materials.
Asia-Pacific Polyvinyl Chloride (PVC) Market Competitive Environment
Capital-heavy producers compete with asset-light compounders across distinct margin pools in the Asia-Pacific PVC market. Integrated chlor-alkali operators with captive VCM supply command structural cost advantages in commodity rigid resin, while specialized compounders capture premium positioning in medical-grade and phthalate-free flexible formulations. Three archetypes dominate: coal-chemical integrated carbide-route producers, ethylene-based naphtha crackers with downstream resin assets, and formulation-focused compounders serving specification-grade end-uses. Competitive dynamics center on capacity expansion timing relative to national building code procurement cycles and strategic partnerships for multi-jurisdictional certification coverage.
Within the integrated producer tier, Xinjiang Zhongtai Chemical and Shin-Etsu Chemical exemplify divergent strategic positions. Xinjiang Zhongtai Chemical represents coal-chemical integration archetypes with captive feedstock control across western China's industrial corridor. Shin-Etsu Chemical occupies a position among technology-driven specialists leveraging proprietary polymerization platforms for high-purity medical applications. Formosa Plastics Corporation anchors the ethylene-based integration model with deep backward control over VCM monomer supply, serving flexible film and sheet segments across regional export markets.
| Leading Market Players |
|---|
| Hanwha Solutions |
| Xinjiang Zhongtai Chemical |
| Shin-Etsu Chemical |
| Reliance Industries Limited |
| Sinochem Holdings Corporation |
| Formosa Plastics Corporation |
| ChemChina |
| INEOS |
| LG Chem |
| Others |
Value Chain & Pricing Dynamics
Anthracite coal pricing volatility in Xinjiang and Inner Mongolia propagates through carbide-based acetylene routes to compress margins on economy-grade rigid resin, while ethylene import costs for Indian and Southeast Asian processors stratify pricing tiers by feedstock origin.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates medical-grade suspension polymerization from BIS-certified potable water grades and uncertified commodity resin. Price differentiation hinges on certification tier—ISI-marked resin commands premiums in Maharashtra pipe extrusion clusters—and volume scale, with railcar offtake securing discounts over bagged deliveries. Cost compression in economy-grade carbide-route output is intensifying because MEE emissions compliance burdens erode cost advantages. Municipal contractors under India's Smart Cities Mission exhibit highest price sensitivity; healthcare compounders serving ASEAN medical device markets show least.
Supply Chain Analysis
Skilled chlor-alkali technician shortages in Gujarat and Maharashtra constrain capacity ramp rates at Dahej and Hazira petrochemical complexes. Supply concentrates in China, India, and Japan, with VCM monomer and specialty plasticizer formulations drawing from regional chemical clusters. Single-source vulnerability runs through Xinjiang-based anthracite supply chains exposed to energy rationing directives. Distribution runs through manufacturer-direct railcar deliveries for bulk processors, supplemented by certified distributors buffering smaller extruders against supply volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's BIS ISI certification mandate for potable water contact applications is concentrating procurement among qualified suppliers and forcing technical liaison investments.
For Market Incumbents: Anchor cost leadership through captive VCM integration at Dahej and Hazira complexes to defend against ethylene import price volatility. Deepen certification capabilities across BIS, JIS, and GB standards to disqualify marginal competitors from integrated infrastructure contracts. Cross-linked polyethylene substitution in Japanese residential hot-water plumbing demands accelerated CPVC formulation innovation. For New Entrants and Emerging Players: Enter via medical-grade suspension polymerization for ASEAN healthcare infrastructure modernization, where high-purity resin shortages create white-space opportunity. Target India's western industrial belt pipe extrusion clusters with certified rigid resin offerings, leveraging technical liaison teams to unbundle material certification from installation contracts. Partner with established distributors possessing multi-jurisdictional testing capabilities to bypass certification timeline barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented compounders lack backward integration into VCM monomer supply and face margin compression from feedstock volatility. Long-term viability favors ethylene-based naphtha crackers with downstream resin assets over carbide-route operators exposed to coal-chemical regulatory tightening. Watch MEE enforcement intensity in Inner Mongolia and Ningxia as inflection indicator for Chinese supply rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VCM Monomer | Captive feedstock supply insulates Dahej and Hazira complexes from Middle East ethylene price swings. |
| Multi-Jurisdictional Certification Investment | Parallel BIS, JIS, and GB testing capabilities prevent procurement disqualification across integrated supply contracts. |
| Phthalate-Free Formulation Transition | METI-compliant compounds capture premium positioning in Japan's automotive wire harness and medical tubing segments. |
| Greenfield Medical-Grade Capacity | High-purity suspension polymerization addresses ASEAN healthcare infrastructure modernization demand pools. |
| Secondary Feedstock Supplier Qualification | Recycled content traceability compliance under China's GB standards fragments resin sourcing for specification-grade sheet. |
Study Parameters
Bottom-up construction sector modeling reconciled against top-down chlor-alkali capacity tracking forms the analytical core of this study. Primary interviews with pipe extrusion plant managers, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors at compounders were validated against secondary sources including customs and trade data, BIS certification registries, SEC filings from listed petrochemical groups, and MEE emissions disclosure filings. Triangulation between demand-side project pipelines and supply-side capacity announcements ensures statistical integrity.
Historical trendline analysis of resin offtake by grade tier, end-use industry, packaging format, and regional production hub established baseline growth patterns across the analysis window. Segmentation modeling incorporated rigid versus flexible formulation splits, certification tier stratification, and form factor consumption patterns. CAGRs were derived from regression analysis of capacity utilization rates, national building code procurement timelines, and feedstock cost spread dynamics.
The model holds under stable MEE enforcement intensity and continued BIS certification mandate adherence; deviation in coal-chemical regulatory tightening pace or ethylene import cost spikes would shift capacity expansion timing and margin distribution. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Europe Caustic Potash Market
Bulk Chemicals
Acetate Salt Market
Bulk Chemicals
Europe Gamma Butyrolactone Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Isatoic Acid Anhydride Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Isobutyraldehyde Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Castor Wax Market
Bulk Chemicals
Phosphates Market
Bulk Chemicals
Global Butyl Acrylate Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
Aluminum Potassium Sulfate Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Aluminum Sulfate Market