
 High Purity Aluminum Hydroxide Market | 2026-2036
High Purity Aluminum Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Aluminum Hydroxide Market Foresight
ISO 9001 and ICH Q7 qualification cycles is reorganizing supplier eligibility across pharmaceutical and electronics supply chains, favoring producers with documented quality management systems. Chalco leverages its integrated bauxite-to-refinery footprint to sustain cost-competitive high-purity output at scale. Nabaltec AG anchors European supply through specialized flame-retardant and electronic-grade production lines. Taimei Chemicals Co., Ltd. competes on sub-micron particle control for semiconductor polishing applications.
High purity aluminum hydroxide designates refined Al(OH)₃ with controlled trace-metal content below ppm thresholds, typically synthesized via seeded precipitation from sodium aluminate liquor or vapor-phase hydrolysis routes, serving primarily as a precursor for calcined alumina, pharmaceutical excipients, and electronic substrate fillers. Crystalline gibbsite variants dominate volume flows into ceramics and refractories where thermal conversion to alpha-alumina drives specification rigor, while pseudoboehmite grades capture accelerating share in catalyst support and membrane applications where surface area and pore architecture command premium pricing. Powder form remains the baseline packaging for industrial buyers, though slurry delivery is gaining traction in water treatment and continuous-process electronics manufacturing to reduce dust exposure and handling losses.
EMA pharmacopeial standards and REACH chemical safety registrations in Europe, alongside FDA cGMP expectations for pharmaceutical excipient sourcing in the United States, collectively elevate documentation and analytical burden on producers seeking multi-regional market access. China's GB standards and NMPA drug substance filings impose parallel conformity requirements that filter out smaller refiners lacking in-house metrology capabilities. Buyers must weigh certification maintenance costs against volume commitments when qualifying second-source suppliers across these jurisdictions.
Market Dynamics
Pharmacopeial compliance deadlines are compressing supplier qualification timelines, forcing pharmaceutical and electronics buyers to consolidate qualified vendor lists around refiners with certified quality management systems and documented trace-metal control.
Growth Catalysts
- EMA pharmacopeial standards:European pharmaceutical manufacturers are accelerating excipient requalification programs ahead of tightened impurity thresholds, pulling volume toward REACH-registered refiners with validated analytical protocols.
- Semiconductor substrate fillers:Advanced packaging architectures for high-bandwidth memory and chiplets require sub-ppm alkali metal content, expanding specification-grade consumption in Japan and South Korea.
- China:Domestic NMPA drug substance filings for antacid APIs are driving import substitution campaigns that favor local high-purity refiners with integrated bauxite-to-chemical processing.
Market Restraints
- Caustic soda and energy input volatility:Bayer process refiners face margin compression from fluctuating sodium hydroxide contract prices and regional electricity tariffs, particularly in European jurisdictions with carbon border adjustment exposure.
- Specialized refining concentration:Seeded precipitation capacity for electronic-grade material remains concentrated among three national producer clusters, creating single-source vulnerability for buyers requiring sub-100 ppb iron specifications.
- Amorphous alumina substitutes:Spray-dried boehmite gels are capturing catalyst support applications where surface area requirements exceed 300 m²/g, displacing traditional pseudoboehmite aluminum hydroxide in fluid catalytic cracking units.
Strategic Opportunities
- India:CDSCO's phased implementation of ICH Q7 guidelines for active pharmaceutical ingredients creates first-mover advantage for refiners establishing dedicated pharmaceutical-grade production lines ahead of domestic compliance deadlines.
- Solid-state battery electrolyte precursors:Lithium-aluminum layered double hydroxide synthesis routes are opening technical-grade consumption channels outside traditional ceramics and pharmaceuticals.
- Slurry delivery systems:Continuous-process electronics manufacturers in Taiwan and Germany are adopting bulk liquid handling infrastructure that eliminates powder handling losses and reduces cleanroom contamination risk.
Industry Challenges
- ICP-MS and GD-MS analytical talent:Trace-metal characterization at ppb levels requires specialized spectroscopists; refiners in secondary markets struggle to recruit and retain personnel capable of validating pharmacopeial compliance packages.
- ISO 9001 and ICH Q7 certification timelines:Documented quality system implementation typically spans 18-24 months, blocking market entry for new entrants regardless of technical capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Aluminum Hydroxide Market |
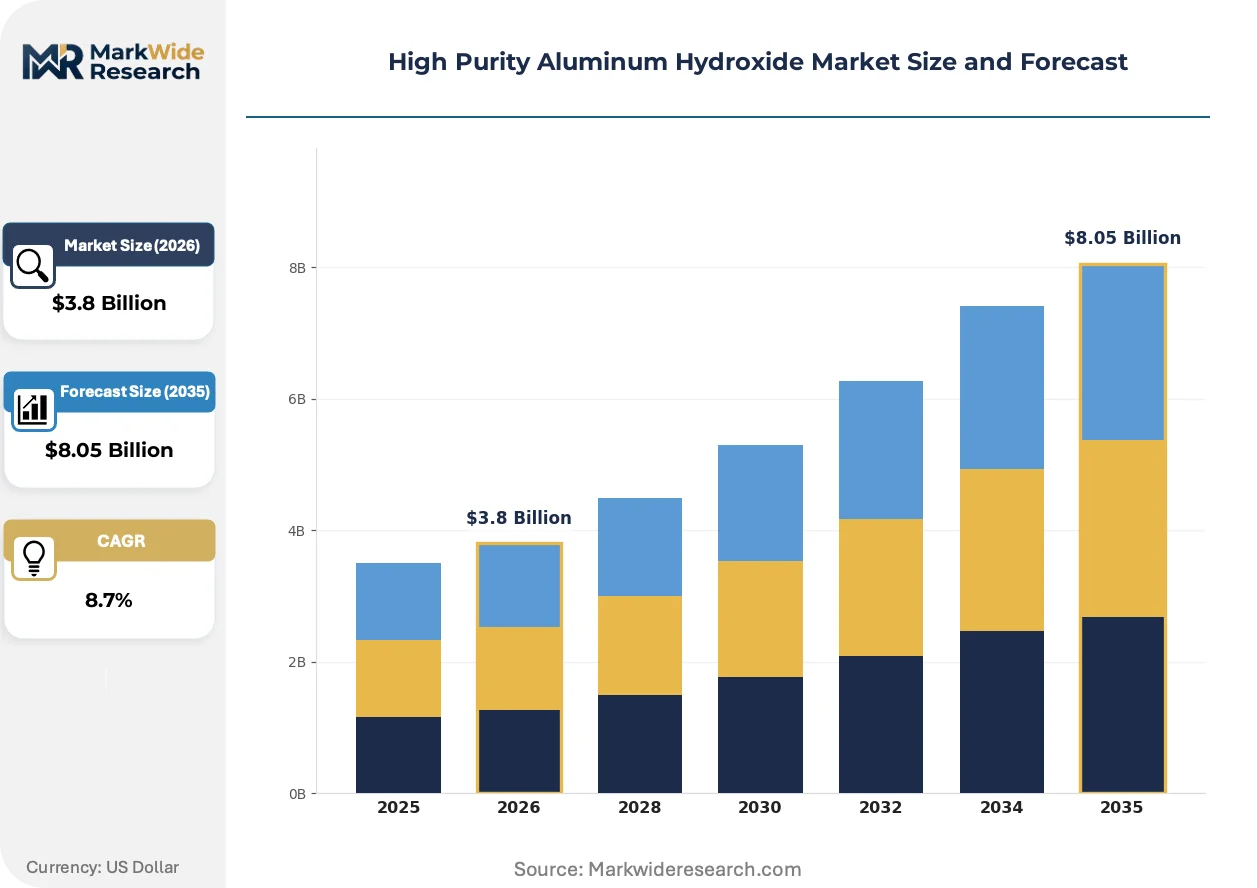
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline, Amorphous, Pseudoboehmite, Gibbsite End Use Industry: Pharmaceuticals, Food & Beverage, Electronics, Water Treatment Form: Powder, Granules, Pellets, Slurry Packaging Type: Bags, Drums, Bulk Containers, Pails |
| Companies Covered | Hefei Crystal Material Co., Ltd., Aluminum Corporation of China Limited (Chalco), Sumitomo Metal Mining Co., Ltd., Almatis, Huber Engineered Materials, Nabaltec AG, Taimei Chemicals Co., Ltd., Sumitomo Chemical Co., Ltd., Altech Chemicals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Aluminum Hydroxide Market Shifts & Advancements
Vapor-phase hydrolysis routes are gaining technical validation for electronic-grade production, while pharmaceutical buyers consolidate specifications around unified ICH quality standards that reduce regional testing redundancy.
Seeded precipitation from purified sodium aluminate liquor is supplanting traditional Bayer-derived gibbsite calcination for semiconductor polishing applications. Korean and Japanese wafer manufacturers now specify vapor-synthesized material for 3 nm node CMP slurries. This transition is compressing demand for conventional ceramic-grade calcined alumina intermediates.
REACH authorization requirements for nickel and cobalt catalyst residues are tightening analytical disclosure obligations for European pharmaceutical excipient imports. Refiners must now submit extended safety data sheets documenting trace heavy metal content below 0.1 ppm thresholds. Electronic-grade material bound for German substrate manufacturers faces parallel scrutiny under RoHS substance restrictions.
Specification consolidation is eliminating regional pharmacopeial variance as buyers push for single global raw material qualifications. Multinational pharmaceutical formulators now reject country-specific testing protocols in favor of harmonized ICH Q3D elemental impurity assessments. This behavior is most visible among US and European headquarters sourcing teams managing Asian contract manufacturing organization supply chains.
High Purity Aluminum Hydroxide Market Segmentation
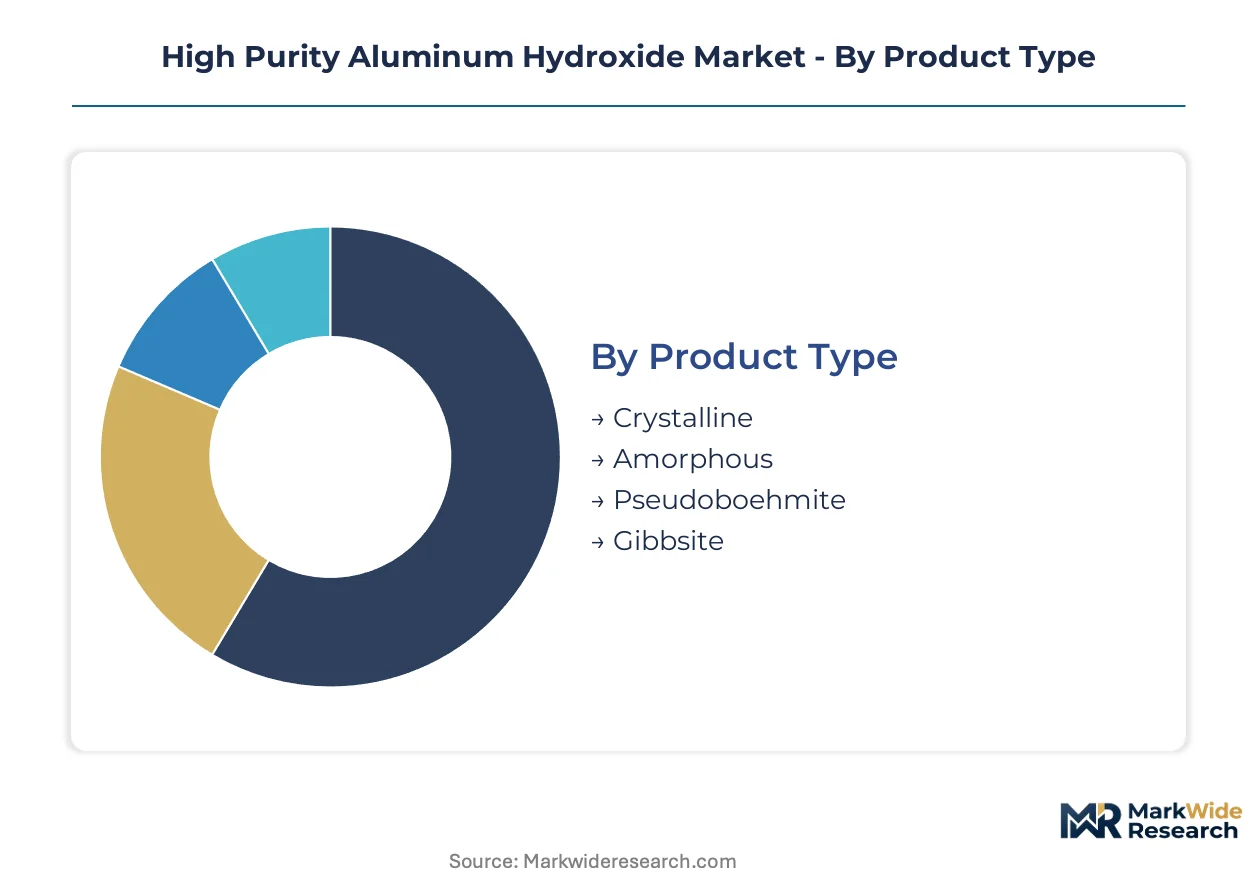
High purity aluminum hydroxide markets fragment across crystalline structure, end-use specifications, and physical delivery formats. Buyers in electronics and pharmaceuticals impose divergent purity thresholds that reshape supplier qualification requirements. Each segmentation axis carries distinct margin profiles and regulatory documentation burdens.
Product Type:
Crystalline grades dominate domestic consumption in ceramic and refractory applications, while amorphous and pseudoboehmite variants drive export flows to semiconductor and catalyst manufacturers.
- Crystalline:Gibbsite-dominant structures with controlled particle size distribution serve thermal conversion to alpha-alumina for ceramic substrates. German and Japanese refractory manufacturers specify iron content below 50 ppm for high-temperature furnace linings. REACH-registered refiners in Europe capture premium pricing through validated trace-metal protocols.
- Amorphous:Spray-dried gels with surface areas exceeding 200 m²/g anchor catalyst support applications in fluid catalytic cracking units. US Gulf Coast petrochemical complexes favor amorphous grades for zeolite impregnation where pore volume controls active site dispersion.
- Pseudoboehmite:Layered aluminum oxyhydroxide structures command membrane and adsorbent applications requiring tunable pore architecture.
- Gibbsite:Well-crystallized trihydroxide phases supply antacid API production under FDA cGMP and EMA pharmacopeial standards.
Crystalline commands the established base. The steepest expansion runs through pseudoboehmite.
End Use Industry:
Cost tier differentiation separates qualification-intensive pharmaceutical and electronics segments from volume-driven water treatment and food additive markets.
- Pharmaceuticals:Excipient and antacid API production demands ICH Q7-compliant quality systems with documented trace-metal control below 10 ppm for iron and silicon. CDSCO's phased ICH implementation in India is compressing supplier qualification timelines for domestic formulators. NMPA filings in China favor refiners with integrated bauxite-to-chemical processing.
- Electronics:Substrate fillers and CMP slurry precursors require sub-ppb alkali metal specifications for 3 nm node semiconductor manufacturing. Korean wafer fabricators specify vapor-phase hydrolysis material to minimize sodium contamination in high-bandwidth memory packaging.
- Food & Beverage:EFSA-registered grades for color fixation and pH buffering face lower analytical burden than pharmaceutical equivalents.
- Water Treatment:Municipal and industrial flocculation applications consume standard-purity powder and slurry formats with minimal certification overhead.
Water treatment anchors volume throughput. Electronics generates the highest margin per kilogram.
Form:
Supply concentration in powder processing gives way to slurry infrastructure investments among continuous-process manufacturers seeking dust elimination.
- Powder:Baseline packaging for industrial buyers with established pneumatic handling systems. Bagged powder shipments to ceramic manufacturers in Japan and Germany remain volume-dominant despite handling losses.
- Slurry:Aqueous suspensions at 30-50% solids content eliminate cleanroom contamination risks for Taiwanese electronics contract manufacturers. Bulk liquid delivery systems reduce occupational exposure and simplify automated dosing in continuous water treatment plants.
- Granules:Controlled agglomeration for fluidized bed applications in catalyst manufacturing.
- Pellets:Extruded formats for fixed-bed reactor configurations in petrochemical processing.
Powder retains the volume base. Slurry delivery is climbing the fastest among specification-grade buyers.
Packaging Type:
Customer scale and handling infrastructure determine packaging selection, with bulk containers capturing share among integrated manufacturers and drums retaining relevance for qualified pharmaceutical supply.
- Bulk Containers:Intermediate bulk containers and tanker deliveries serve high-volume electronics and water treatment consumers in Germany and South Korea with dedicated unloading infrastructure.
- Drums:Steel and fiber drums with sealed liners protect pharmaceutical-grade material from moisture ingress during qualified supplier shipments. FDA-registered repackagers in the US maintain drum inventory for just-in-time excipient delivery.
- Bags:Multi-wall paper and PE-lined sacks dominate ceramic and refractory procurement with lower unit costs.
- Pails:Small-format packaging for R&D sampling and pilot-scale pharmaceutical formulation work.
Drums and bags split the established industrial base. Bulk containers are gaining share fastest among integrated downstream processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulators and semiconductor fabricators concentrate procurement in jurisdictions with harmonized pharmacopeial standards and established refining infrastructure. Buyer qualification requirements favor countries with integrated bauxite processing and certified quality management systems.
China
Domestic NMPA filings for antacid APIs and substrate fillers drive import substitution toward local refiners with captive bauxite-to-chemical operations. GB standards and NMPA drug substance regulations filter out smaller producers lacking in-house metrology. Shandong Peninsula clusters host integrated refiners serving pharmaceutical and electronics contract manufacturers.
Germany
EMA pharmacopeial standards and REACH authorization requirements compress supplier qualification timelines for pharmaceutical excipient sourcing. RoHS substance restrictions and carbon border adjustment exposure elevate documentation burdens on electronic-grade imports. North Rhine-Westphalia anchors European flame-retardant and electronic-grade production capacity.
Japan
Sub-ppb alkali metal specifications for 3 nm node CMP slurries pull demand toward vapor-phase hydrolysis material. METI industrial standards and PMDA pharmaceutical regulations enforce trace-metal protocols across wafer fabrication and excipient supply chains. Kyushu semiconductor clusters specify refined material for high-bandwidth memory packaging applications.
United States
FDA cGMP expectations for pharmaceutical excipient sourcing elevate analytical burden on imports from non-ICH Q7-compliant refiners. EPA environmental compliance and OSHA workplace exposure standards shape slurry delivery adoption in continuous-process manufacturing. Texas Gulf Coast petrochemical complexes consume amorphous grades for catalyst support applications.
India
CDSCO's phased ICH Q7 implementation for active pharmaceutical ingredients creates first-mover advantage for refiners establishing dedicated pharmaceutical-grade lines. BIS quality standards and FSSAI food-grade registrations parallel pharmaceutical compliance requirements. Gujarat and Maharashtra pharmaceutical clusters drive excipient requalification programs ahead of domestic deadlines.
High Purity Aluminum Hydroxide Market Competitive Landscape
Player mix skews toward integrated aluminum majors and specialized chemical refiners with certified quality systems. Concentration remains moderate among electronic-grade producers, while pharmaceutical-grade supply consolidates around REACH-registered and ICH Q7-qualified operators. Two strategic archetypes dominate: integrated bauxite-to-chemical processors with captive raw material security, and specialized refiners with sub-micron particle control capabilities. Competitive moves center on backward integration into bauxite mining and quality certification expansion across multiple pharmacopeial jurisdictions.
Among Chinese integrated producers, Aluminum Corporation of China Limited represents the scale-driven archetype with bauxite-to-refinery footprint advantages. Specialized Japanese and German refiners occupy premium-tier positions: Taimei Chemicals Co., Ltd. exemplifies sub-micron particle control specialization, while Nabaltec AG anchors European supply through certified flame-retardant and electronic-grade production lines. Huber Engineered Materials and Sumitomo Chemical Co., Ltd. sit within the multinational diversified chemicals tier with cross-regional quality system documentation.
| Leading Market Players |
|---|
| Hefei Crystal Material Co., Ltd. |
| Aluminum Corporation of China Limited (Chalco) |
| Sumitomo Metal Mining Co., Ltd. |
| Almatis |
| Huber Engineered Materials |
| Nabaltec AG |
| Taimei Chemicals Co., Ltd. |
| Sumitomo Chemical Co., Ltd. |
| Altech Chemicals Ltd. |
| Others |
Supply & Pricing Matrix
Vapor-phase hydrolysis material displacing seeded precipitation for 3 nm node CMP slurries is redrawing procurement geography toward Japanese and Korean refiners while compressing legacy ceramic-grade pricing tiers. This substitution simultaneously elevates premium-tier contract values for sub-ppb specifications and erodes margins on conventional Bayer-process gibbsite.
Pricing Analysis
Long-term offtake agreements with caustic soda indexation dominate contract structures for Bayer-process refiners, insulating against sodium hydroxide volatility while locking in volume commitments. Three-tier pricing structure across ICH Q7-certified pharmaceutical, REACH-registered electronic, and standard industrial grades reflects documentation burden differentials. Cost compression in electronic-grade material is intensifying as Korean wafer fabricators consolidate qualified supplier lists around vapor-synthesis specialists. Water treatment buyers exhibit highest price sensitivity due to specification flexibility, while semiconductor substrate manufacturers accept premium positioning for trace-metal validation.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for German electronics manufacturers sourcing from Shandong Peninsula refiners. Supply concentrates in China, Germany, and Japan, with seeded precipitation capacity for sub-100 ppb iron specifications resting on three national producer clusters. Raw material dependencies encompass bauxite ore, caustic soda, and specialized precipitation reagents. Single-source vulnerability pervades electronic-grade procurement, as vapor-phase hydrolysis capacity remains limited to Japanese and Korean specialists. Distribution runs through qualified pharmaceutical repackagers and direct bulk delivery to integrated electronics fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor node advancement toward 3 nm architectures constitutes a high-growth disruption, as sub-ppb alkali metal specifications invalidate legacy refining routes and compress supplier qualification timelines.
For Market Incumbents: Secure ICH Q7 certification expansion across multiple pharmacopeial jurisdictions before CDSCO's phased implementation closes qualification windows. Defend market position by deepening backward integration into captive bauxite mining in Shanxi and Henan provinces, eliminating raw material cost volatility that amorphous alumina substitutes exploit.
For New Entrants and Emerging Players: Lead with slurry delivery infrastructure investments targeting Taiwanese electronics contract manufacturers seeking dust elimination and cleanroom contamination reduction. White-space opportunities concentrate in India's pharmaceutical-grade segment ahead of domestic ICH Q7 deadlines, and in solid-state battery electrolyte precursors outside traditional ceramics channels. Go-to-market execution should emphasize documented quality management system implementation concurrent with technical capability demonstration.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized refiners with sub-micron particle control and multi-jurisdiction certification portfolios. Long-term viability hinges on backward integration depth and analytical talent retention for ppb-level trace-metal characterization. Acquisition targets should display integrated bauxite-to-chemical processing or vapor-phase hydrolysis technical validation. The signal to watch is CDSCO compliance deadline acceleration, which will strand non-certified capacity and create distressed asset opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Mining | Captive ore supply eliminates caustic soda contract volatility for Bayer-process refiners in Shanxi province. |
| ICH Q7 Certification Expansion | Multi-jurisdiction quality documentation opens pharmaceutical excipient procurement at EMA and FDA-regulated formulators. |
| Vapor-Phase Hydrolysis Capacity Buildout | Sub-ppb alkali metal output qualifies material for Korean 3 nm node CMP slurry specifications. |
| Slurry Delivery Infrastructure Investment | Bulk liquid handling systems reduce cleanroom contamination risk for Taiwanese electronics manufacturers. |
| Specialized Analytical Talent Acquisition | ICP-MS and GD-MS spectroscopists enable pharmacopeial compliance package validation for REACH-registered refiners. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at Bayer-process refiners, procurement leads at downstream pharmaceutical formulators, technical R&D directors specializing in precipitation chemistry, and distribution channel partners handling qualified excipient shipments; and secondary validation through customs and trade data, SEC 10-K filings of integrated aluminum majors, EMA and FDA pharmacopeial submission records, and ACC regional production reports. Bottom-up capacity modeling triangulated against top-down consumption estimates across crystalline, amorphous, and pseudoboehmite product categories.
Across the analysis window, the analytical framework modeled segmentation dimensions spanning grade tier (electronic, pharmaceutical, industrial), end-use industry (semiconductor, antacid API, catalyst support), packaging format (powder, slurry, bulk liquid), and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific forecast inputs incorporated REACH authorization timelines, CDSCO ICH Q7 implementation phases, and semiconductor node advancement roadmaps from Korean and Japanese wafer fabricators.
Forecasts assume regulatory continuity in EMA pharmacopeial standards, REACH chemical safety registrations, and FDA cGMP expectations; material policy shifts would require re-modeling of supplier qualification timelines and import substitution dynamics. Specific risks that could revise projections include carbon border adjustment implementation in European jurisdictions, amorphous alumina substitute penetration in catalyst applications, and ICP-MS analytical talent scarcity blocking certification timelines for secondary market refiners. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Global High Heat Foam Market
High-Value Chemicals
High-K Dielectric Material Market
High-Value Chemicals
Global High Dispersible Silica Market
High-Value Chemicals
Potassium Hydroxide Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
High-Purity Boehmite Market
High-Value Chemicals
P-Hydroxybenzoates (PHB) Market
High-Value Chemicals
Hydroquinone Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
High-Silica Zeolite Market
High-Value Chemicals
High Friction Films Market
High-Value Chemicals
Sodium Hexametaphosphate Market
High-Value Chemicals
Asia-Pacific Hydrogen Bromide Market
High-Value Chemicals
High-Purity Acetic Acid Market
High-Value Chemicals
High-Temperature Epoxy Market
High-Value Chemicals
Global High Purity Oxygen Market