
 Global Boric Acid Market | 2026-2036
Global Boric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Boric Acid Market Foresight
Pharmaceutical-grade specifications is redrawing competitive boundaries across the boric acid value chain. U.S. Borax Inc. leverages its captive California deposit to sustain supply security for high-purity applications. Eti Maden anchors Turkey's export position through integrated refining from domestic colemanite reserves. 5E Advanced Materials, Inc. competes in North American specialty distribution with vertically controlled logistics.
Boric acid (H₃BO₃) is a weak Lewis acid derived from borate mineral processing, typically refined to purities spanning 99.0–99.9 percent for industrial and pharmaceutical deployment. It functions primarily as a flame retardant synergist, glass fluxing agent, and antimicrobial intermediate across manufacturing chains. Technical grade currently occupies the largest volume share, though pharmaceutical grade commands superior margin pools due to compendial testing burdens and CDSCO and FDA validation requirements. Flame retardants and glass manufacturing represent mature demand basins, while cosmetics applications are gaining traction as formulators seek boron-based alternatives to halogenated additives.
EPA registration requirements for pesticide-grade boric acid and REACH substance evaluation in Europe are elevating compliance costs and compressing spot-market supplier participation. FDA cGMP enforcement for pharmaceutical-grade material and India's BIS certification mandate for imported technical product are tightening market access corridors. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate qualification timeline shifts and lock in multi-region supply agreements.
Market Dynamics
Pharmaceutical-grade purity requirements are compressing supplier margins while concentrating procurement among vertically integrated borate miners with captive refining capabilities. REACH substance evaluation and FDA cGMP enforcement are accelerating qualification timelines, forcing mid-scale traders to exit compendial segments.
Growth Catalysts
- Flame retardant synergist demand:Construction codes in Germany and California mandate boron-based additives for cellulose insulation, pulling technical-grade volumes into building materials.
- REACH authorization timelines:ECHA's evaluation of boric acid reproductive toxicity is channeling R&D spend into exposure-mitigation formulations rather than substitution, preserving incumbent market positions.
- Ophthalmic solution compounding:Hospital pharmacies in India and Brazil are expanding buffered eyewash production, tightening pharmaceutical-grade spot availability.
Market Restraints
- Colemanite concentrate volatility:Turkish mining royalties and natural gas input costs for refining create margin squeeze for non-integrated distributors.
- Substitution by zinc borate:Polymer compounders in wire and cable applications are reformulating with zinc borate to bypass boric acid's reproductive toxicity classification.
- Supply concentration in Anatolia:Eti Maden and private Turkish miners control roughly two-thirds of exportable colemanite reserves, creating single-source vulnerability for European glassmakers.
Strategic Opportunities
- Indonesia ceramics cluster:Surabaya-area tile manufacturers lack domestic boron refining, creating import substitution potential for integrated suppliers.
- Nuclear grade purification:Boron-10 isotope enrichment for control rod applications commands 40-60x technical-grade pricing, rewarding capital deployment into isotope separation.
- EU Green Deal construction incentives:Renovation wave subsidies for energy-efficient insulation are expanding boric acid-treated cellulose demand in France and Poland.
Industry Challenges
- Pharmacopeial testing bottlenecks:USP and EP heavy metals validation queues at contract laboratories extend pharmaceutical-grade release timelines by 8-14 weeks.
- Legacy ERP integration:Mid-scale distributors struggle to serialize batch records for FDA DSCSA compliance without wholesale system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Boric Acid Market |
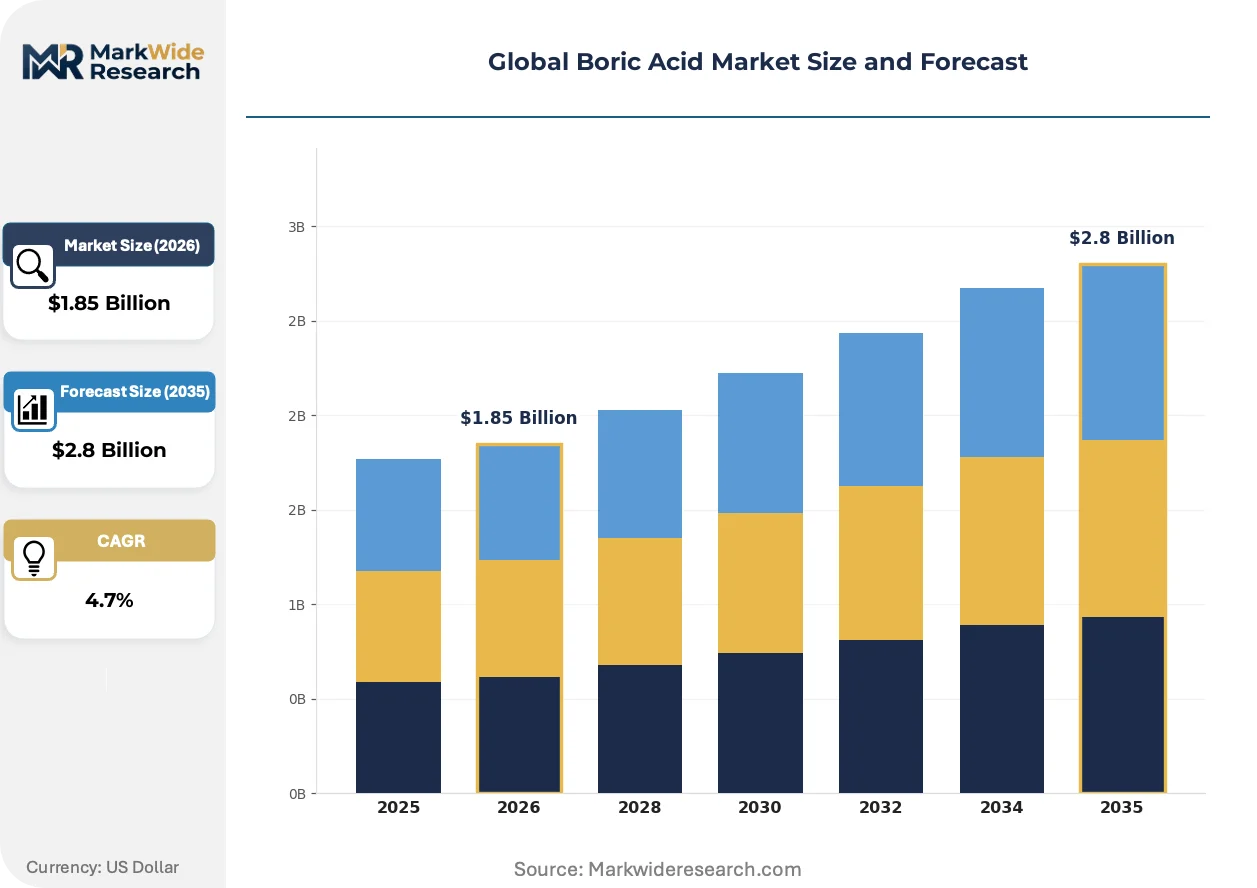
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Technical Grade, Agricultural Grade, Pharmaceutical Grade Application: Flame Retardants, Wood Preservatives, Glass Manufacturing, Cosmetics, Insecticides End User Industry: Ceramics Producers, Pesticide Manufacturers, Pharmaceutical Companies, Chemical Suppliers Packaging Type: Bulk Bags, Paper Bags, Plastic Drums, Loose Packaging |
| Companies Covered | Quiborax SA, Rio Tinto Ltd., 3M Company, Organic Industries Pvt. Ltd., Gujarat Boron Derivatives Pvt. Ltd., U.S. Borax Inc., Avantor Inc., 5E Advanced Materials, Inc., Eti Maden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Boric Acid Market Shifts & Advancements
Process intensification in borate refining and compendial testing automation are compressing cost structures while elevating purity thresholds. Formulation science is diverging between industrial applications tolerating technical variance and pharmaceutical segments demanding single-digit ppm impurity ceilings.
Membrane electrodialysis is supplanting traditional evaporative crystallization for high-purity boric acid production. Pharmaceutical contract manufacturers in Switzerland and Singapore are adopting this technology to reduce energy intensity and heavy metals carryover. The shift is enabling just-in-time purification for ophthalmic and parenteral applications previously constrained by batch-scale economics.
REACH restriction proposals under SVHC review are forcing downstream users to document safe-use scenarios across the supply chain. Glass fiber producers in Italy and the Netherlands are consolidating supplier bases to reduce exposure assessment burdens. The regulatory pressure is accelerating long-term offtake agreements with miners willing to share toxicological data ownership.
Direct procurement from refiners is displacing layered distribution for technical-grade material in ceramics and agriculture. Large tile manufacturers in Spain and fertilizer blenders in the US Midwest are establishing annual contracts with Turkish and Argentine miners, bypassing regional traders. The channel compression is most visible in Brazil, where domestic boron derivative producers have captured import substitution volumes through backward integration into colemanite sourcing.
Global Boric Acid Market Segmentation
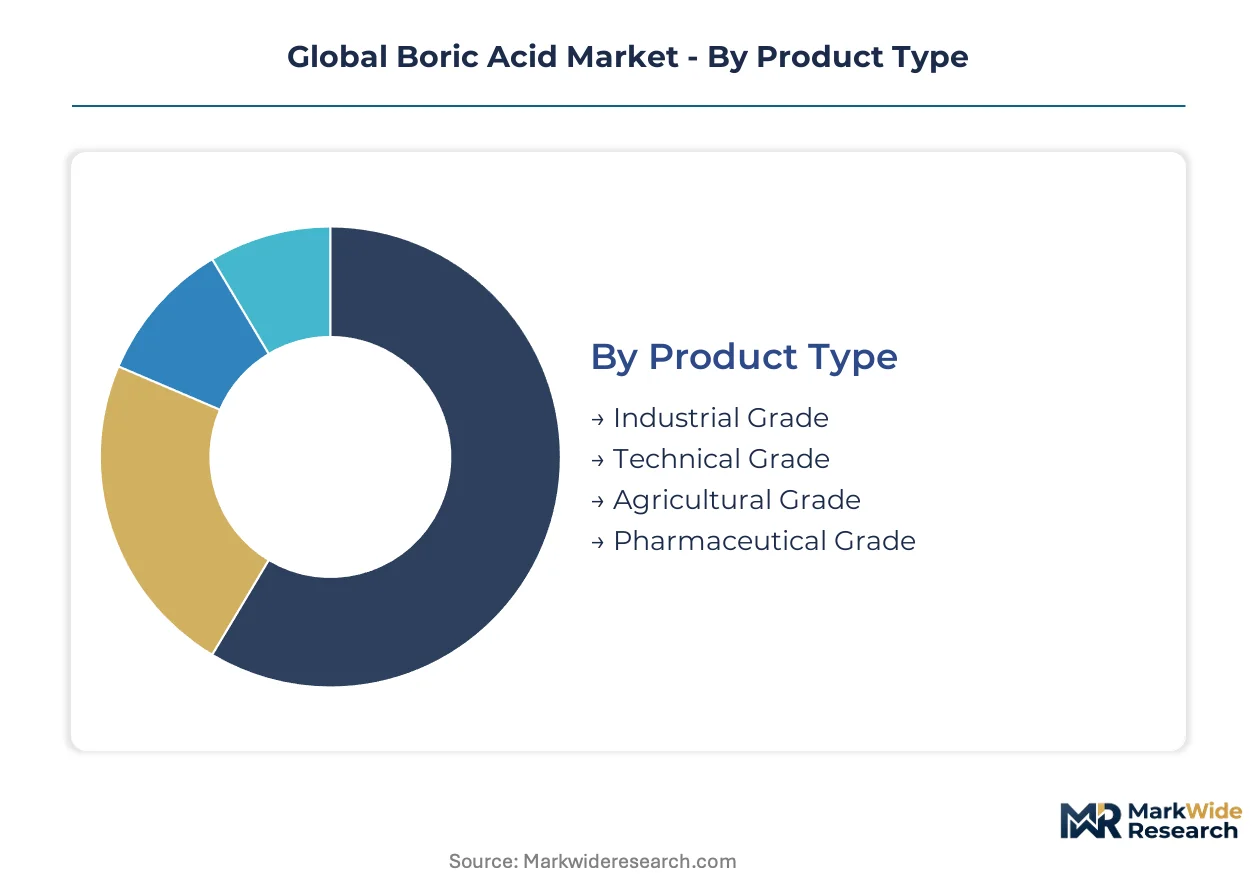
Segmentation in boric acid markets tracks divergent purity thresholds and regulatory burdens that separate commodity trading from compendial supply. Each category reflects distinct qualification timelines, customer consolidation patterns, and margin structures that reward specialized positioning.
Product Type:
REACH substance evaluation and FDA cGMP enforcement create tiered compliance costs that stratify supplier participation across purity grades.
- Pharmaceutical Grade:Compendial material meeting USP and EP heavy metals specifications below 10 ppm. Hospital pharmacies in India and Brazil are expanding ophthalmic solution compounding, tightening spot availability for validated batches.
- Technical Grade:Refined to 99.0–99.5 percent purity for industrial deployment. German and Californian construction codes mandate boron-based additives for cellulose insulation, pulling volumes into building materials.
- Industrial Grade:Standard purity for bulk chemical processing and intermediate manufacturing. Pricing tracks Turkish mining royalties and natural gas input costs for refining.
- Agricultural Grade:Formulated for fertilizer blending and soil amendment applications. US Midwest fertilizer blenders are establishing annual contracts with Argentine miners to bypass regional traders.
Technical grade handles the majority of throughput; pharmaceutical grade is climbing the fastest on share.
Application:
End-use concentration varies sharply by regional industrial structure and substitution vulnerability.
- Flame Retardants:Synergist function in polymer systems and cellulose insulation. EU Green Deal renovation subsidies for energy-efficient insulation are expanding treated cellulose demand in France and Poland.
- Glass Manufacturing:Fluxing agent in borosilicate and fiberglass production. Eti Maden and private Turkish miners control roughly two-thirds of exportable colemanite reserves, creating single-source vulnerability for European glassmakers.
- Cosmetics:Antimicrobial intermediate in personal care formulations. Formulators seek boron-based alternatives to halogenated additives.
- Wood Preservatives:EPA registration requirements elevate compliance costs for pesticide-grade material.
- Insecticides:Active ingredient in bait formulations and agricultural pest control.
Glass manufacturing absorbs the largest volume base; flame retardants are gaining share fastest.
End User Industry:
Customer consolidation patterns favor direct procurement from refiners over layered distribution.
- Ceramics Producers:Tile manufacturers in Spain and Indonesia's Surabaya cluster lack domestic boron refining, creating import substitution potential.
- Pharmaceutical Companies:CDSCO and FDA validation requirements compress supplier margins while concentrating procurement among vertically integrated miners.
- Pesticide Manufacturers:EPA registration timelines and exposure assessment burdens drive supplier base consolidation.
- Chemical Suppliers:Mid-scale distributors struggle to serialize batch records for FDA DSCSA compliance without wholesale system replacement.
Ceramics producers handle the majority of throughput; pharmaceutical companies are expanding most quickly on share.
Packaging Type:
Logistics configuration tracks customer scale and handling infrastructure at destination.
- Bulk Bags:Containerized shipment for large-volume ceramics and glass customers with pneumatic unloading systems.
- Paper Bags:Standard multi-wall packaging for agricultural and technical grade distribution.
- Plastic Drums:Sealed containment for pharmaceutical and high-purity industrial grades requiring moisture protection.
- Loose Packaging:Bulk vessel shipment for integrated downstream processors with captive refining capability.
Bulk bags handle the majority of throughput; plastic drums are expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkish colemanite exports flow predominantly to German glassmakers and Chinese ceramics processors, anchoring Eurasian trade corridors. Argentine boron derivatives reach US Midwest fertilizer blenders through dedicated bulk shipping lanes. Indian domestic production scales to capture regional agriculture and ceramics demand.
United States
California's Mojave Desert hosts captive colemanite mining and refining operations serving domestic glass and flame retardant manufacturers. EPA registration requirements for pesticide-grade material compress spot-market participation. Hospital pharmacies in Texas and Florida expand ophthalmic solution compounding, tightening pharmaceutical-grade availability.
Germany
Construction codes in Bavaria and North Rhine-Westphalia mandate boron-based additives for cellulose insulation in energy-efficient buildings. ECHA's REACH substance evaluation channels R&D investment into exposure-mitigation formulations. Glass fiber producers in the Rhineland consolidate supplier bases to reduce toxicological assessment burdens.
China
Qinghai and Liaoning provinces host domestic borate refining capacity serving ceramics clusters in Guangdong and Shandong. GB standards for industrial chemicals elevate purity benchmarks for export-oriented production. Yangtze River Delta glassmakers secure long-term offtake agreements to bypass Turkish supply concentration.
India
Gujarat and Maharashtra-based boron derivative producers scale technical-grade output for domestic tile manufacturers and fertilizer blenders. CDSCO validation requirements for pharmaceutical-grade imports compress procurement timelines. Surat-area ceramics processors establish direct contracts with Argentine miners to reduce landed costs.
Brazil
São Paulo-state pesticide manufacturers reformulate boric acid bait products under ANVISA exposure assessment protocols. Domestic boron derivative producers capture import substitution volumes through backward integration into colemanite sourcing. Rio Grande do Sul tile clusters lack domestic refining, creating import dependency for technical-grade supply.
Global Boric Acid Market Competitive Landscape
Listed leaders compete with private specialists across refining scale and regulatory qualification depth. The vendor base stratifies into three tiers: integrated miners with captive deposits, regional refiners serving technical-grade bulk markets, and pharmaceutical specialists maintaining compendial certifications. Dominant competitive moves include capacity expansion in high-purity segments and strategic partnerships with downstream formulators seeking supply security.
Within the integrated mining tier, Rio Tinto Ltd. and U.S. Borax Inc. exemplify deposit-controlled supply architectures. Eti Maden anchors Turkish export positioning through state-linked colemanite reserves. Among specialty distributors, 5E Advanced Materials, Inc. occupies a position emphasizing vertically controlled logistics for North American pharmaceutical and industrial accounts.
| Leading Market Players |
|---|
| Quiborax SA |
| Rio Tinto Ltd. |
| 3M Company |
| Organic Industries Pvt. Ltd. |
| Gujarat Boron Derivatives Pvt. Ltd. |
| U.S. Borax Inc. |
| Avantor Inc. |
| 5E Advanced Materials, Inc. |
| Eti Maden |
| Others |
Supply & Pricing Matrix
REACH substance evaluation and FDA cGMP enforcement gate both supplier qualification and price differentiation simultaneously, compressing spot-market participation while rewarding vertically integrated miners with captive refining capabilities. Pharmaceutical-grade material commands substantial premia over technical-grade boric acid due to compendial testing burdens and heavy metals validation queues.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with pharmaceutical-grade material separated from technical-grade by certification intensity and impurity ceilings. Price differentiation rests on USP/EP compliance tier and volume scale, with large glassmakers securing annual contract discounts unavailable to spot purchasers. Cost compression in technical-grade segments is intensifying because Turkish mining royalties and natural gas refining costs are squeezing non-integrated distributors. Agricultural blenders in the US Midwest exhibit highest price sensitivity, while ophthalmic compounders in hospital pharmacies show lowest sensitivity due to patient-safety imperatives.
Supply Chain Analysis
Container availability on the Izmir-Rotterdam trade lane and port congestion at Mersin anchor inbound logistics costs for European glassmakers dependent on Turkish colemanite. Supply concentrates in Turkey, Argentina, and the United States, with Eti Maden and private Anatolian miners controlling roughly two-thirds of exportable reserves. Raw material dependencies draw from colemanite concentrate, natural gas for refining energy, and sulfuric acid for processing chemistry. Single-source vulnerability for European glassmakers represents the dominant structural risk. Distribution runs through direct annual contracts between miners and large downstream processors, displacing layered regional traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified refining capacity for pharmaceutical-grade boric acid is scarce relative to compounding demand growth, creating durable positioning for incumbent miners willing to absorb CDSCO and FDA validation timelines. This capability gap rewards backward integration and punishes traders lacking batch serialization infrastructure.
For Market Incumbents: Consolidate supplier relationships with European glass fiber producers seeking toxicological data ownership for REACH exposure assessments. Add pharmaceutical-grade capacity in Switzerland or Singapore where membrane electrodialysis adoption is compressing energy intensity. Lock in long-term offtake agreements with Indian hospital pharmacy chains expanding ophthalmic compounding to preempt spot-market tightness.
For New Entrants and Emerging Players: Differentiate on nuclear-grade Boron-10 isotope enrichment, where technical-grade pricing multipliers of 40-60x reward capital deployment into isotope separation. Target Indonesia's Surabaya ceramics cluster, where domestic tile manufacturers lack boron refining and import substitution potential remains underexploited. Pursue direct procurement contracts with Argentine miners to bypass Turkish supply concentration and establish independent logistics lanes.
For Investors and Strategic Acquirers: ECHA's SVHC review conclusion reshapes the acquisition landscape by determining whether downstream users must document safe-use scenarios or accelerate substitution R&D. Five-to-ten year viability favors vertically integrated miners with captive colemanite deposits and existing pharmaceutical-grade certifications over pure-play distributors. Watch for REACH authorization timeline announcements as the critical inflection signal distinguishing incumbent preservation from displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Colemanite Mining | Captive ore supply insulates margin from Turkish royalty volatility and natural gas cost swings. |
| Membrane Electrodialysis Capacity Installation | Swiss and Singaporean pharmaceutical contract manufacturers adopt this technology for energy-efficient heavy metals reduction. |
| Long-term Supply Agreement with Hospital Pharmacy Chains | Indian and Brazilian ophthalmic compounders seek validated batch security amid spot-market tightness. |
| REACH Toxicological Data Partnership | Italian and Dutch glass fiber producers consolidate supplier bases to reduce exposure assessment burdens. |
| Boron-10 Isotope Separation Facility | Nuclear control rod applications command pricing multiples that justify capital-intensive enrichment infrastructure. |
Research Methodology
The analysis maps pharmaceutical-grade, technical-grade, industrial-grade, and agricultural-grade boric acid segments, each validated through procurement leads at downstream OEMs, plant managers at ceramics and glass manufacturers, distribution channel partners, and regulatory affairs directors at pharmaceutical compounders. Primary interview findings triangulate against customs and trade data, ECHA REACH dossiers, SEC 10-K filings from listed miners, and CDSCO import registration records. Bottom-up volume modeling from end-use consumption patterns cross-checks against top-down production capacity assessments from Turkish, Argentine, and US refining operations.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window, with segmentation dimensions spanning purity grade tier, end-use industry application, packaging format, and regional production hub. CAGRs derive from regression analysis of historical consumption trends adjusted for regulatory inflection points and substitution elasticity. Forecast inputs incorporate ECHA authorization timeline scenarios, German and Californian construction code adoption rates for cellulose insulation, and Indian domestic production scaling curves.
The analysis sits within stated boundaries; outcomes outside sustained REACH regulatory continuity, Turkish mining royalty stability, and pharmaceutical-grade validation queue durations would require recalibration. Forecasts reflect assumptions regarding colemanite reserve depletion rates, natural gas refining cost trajectories, and ophthalmic solution compounding growth in emerging hospital pharmacy markets. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Asia-Pacific Choline Chloride Market
Bulk Chemicals
Dimethyl Terephthalate (DMT) Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Furfuryl Alcohol Market
Bulk Chemicals
Calcium Carbonate Market
Bulk Chemicals
Europe Caustic Soda Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Benzyl Acetate Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Global Benzaldehyde Market
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Di-Isobutylene Market
Bulk Chemicals
Valeric Acid Market