
 Diketene Market | 2026-2036
Diketene Market Size, Share, and Industry Trends Forecast 2026-2036
Diketene Market Analysis
Specialized organic synthesis expertise is unwinding capacity bottlenecks across diketene derivative production. Lonza Group AG leverages its Swiss-based pharmaceutical intermediate infrastructure to sustain high-purity acetoacetic ester output for API manufacturers. Eastman Chemical Company anchors North American supply through backward integration into acetic anhydride feedstock. Daicel Corporation differentiates via Japan-focused pharmaceutical-grade diketene derivatives with stringent impurity controls.
Diketene is a highly reactive dimer of ketene, typically stabilized with additives and handled below 0 degrees Celsius to prevent polymerization, serving primarily as a building block for acetoacetic acid derivatives, pyrazoles, and pigments. Pharmaceutical applications lead value capture due to stringent purity premiums on diketene-derived intermediates for beta-lactam antibiotics and antiretroviral synthesis. Agrochemical applications represent the fastest-expanding segment as pyrazole herbicide and fungicide formulations gain acreage in Brazil and India. Chemical manufacturers as end users concentrate procurement through direct sales channels to secure batch consistency and technical service support.
EPA oversight of ketene emissions shapes US plant design and abatement capital allocation, while REACH registration requirements in Europe constrain non-compliant importers from accessing derivative markets. China's SAMR enforces GB standards on diketene storage and transport that elevate domestic logistics costs versus integrated producers. Stakeholders must monitor regulatory divergence on ketene exposure limits as jurisdictions tighten occupational safety thresholds independently.
Market Dynamics
Pharmaceutical purity specifications and acetic acid feedstock integration are compressing margins for non-integrated diketene producers while concentrating derivative supply in coastal China clusters.
Growth Catalysts
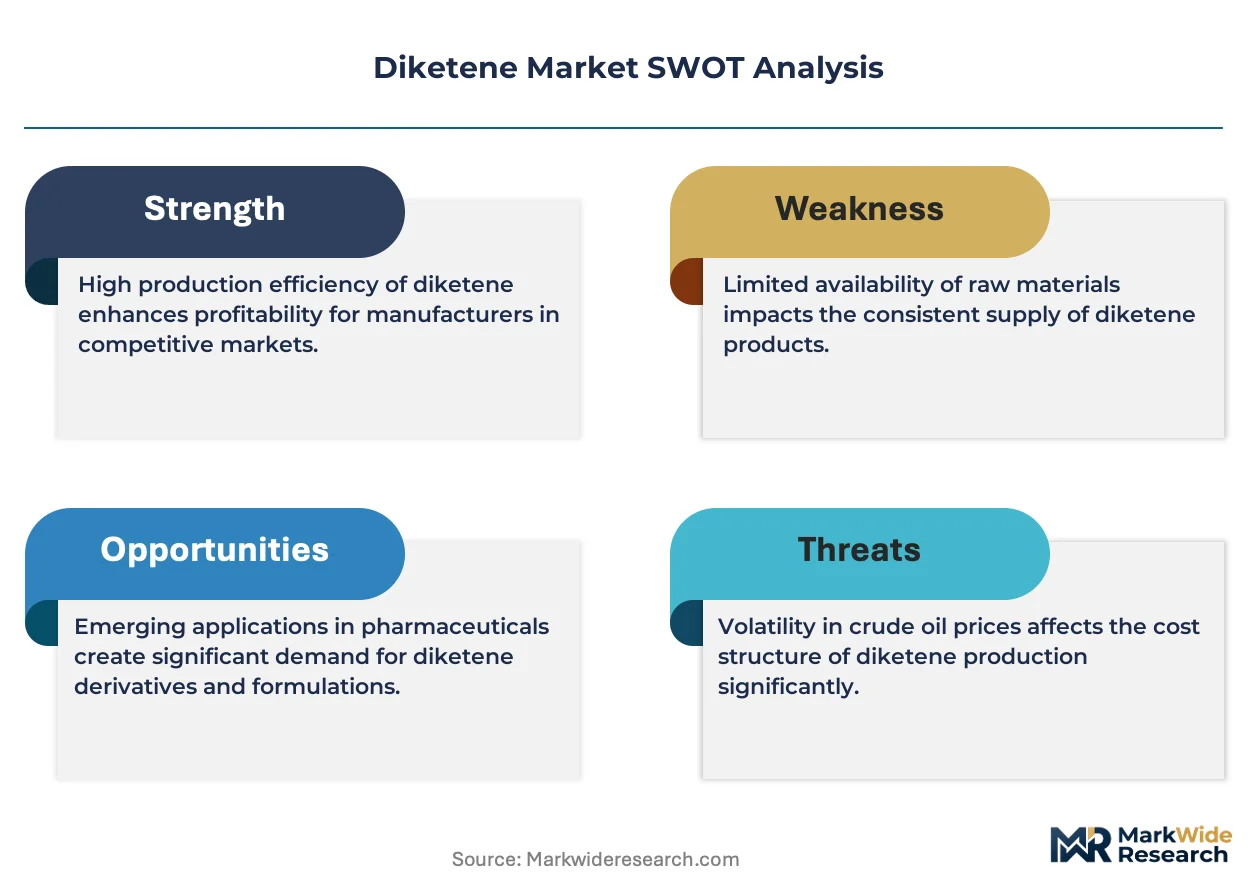
- REACH Registration Tiering:ECHA's updated registration requirements for acetoacetic esters are filtering out low-volume European importers, tightening supply discipline for compliant manufacturers.
- Pyrazole Agrochemical Formulations:Brazil's expanding soybean acreage and India's cotton belt are accelerating pyrazole herbicide consumption that requires diketene-derived intermediates.
- Acetic Acid Integration:Chinese producers with captive acetic anhydride supply are capturing cost advantages that standalone European converters cannot match.
Market Restraints
- Acetic Anhydride Volatility:Feedstock price swings tied to methanol-carbonylation economics compress diketene derivative margins during energy market disruptions.
- Sub-Zero Cold Chain Requirements:Diketene polymerization risk below 0°C necessitates specialized refrigerated transport that elevates logistics costs for non-integrated distributors.
- Ketene Emission Abatement:EPA-mandated thermal oxidizer installations at US production sites require capital allocations that strain mid-scale producers.
Strategic Opportunities
- Antiretroviral API Expansion:Indian pharmaceutical manufacturers are expanding diketene-derived intermediate consumption for efavirenz and related non-nucleoside reverse transcriptase inhibitors.
- EU Green Deal Compliance Services:Carbon footprint verification and renewable feedstock certification present service-revenue streams for derivative exporters to European formulators.
- Continuous Flow Synthesis Adoption:Microreactor technology convergence with diketene handling protocols is enabling safer on-site generation that reduces polymerization losses.
Industry Challenges
- Specialized Cryogenic Handling Expertise:Qualified technicians for sub-zero diketene transfer and storage operations are scarce in emerging production regions.
- Batch-to-Batch Purity Certification:Pharmaceutical-grade acetoacetic ester production requires extended analytical validation timelines that delay customer qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diketene Market |
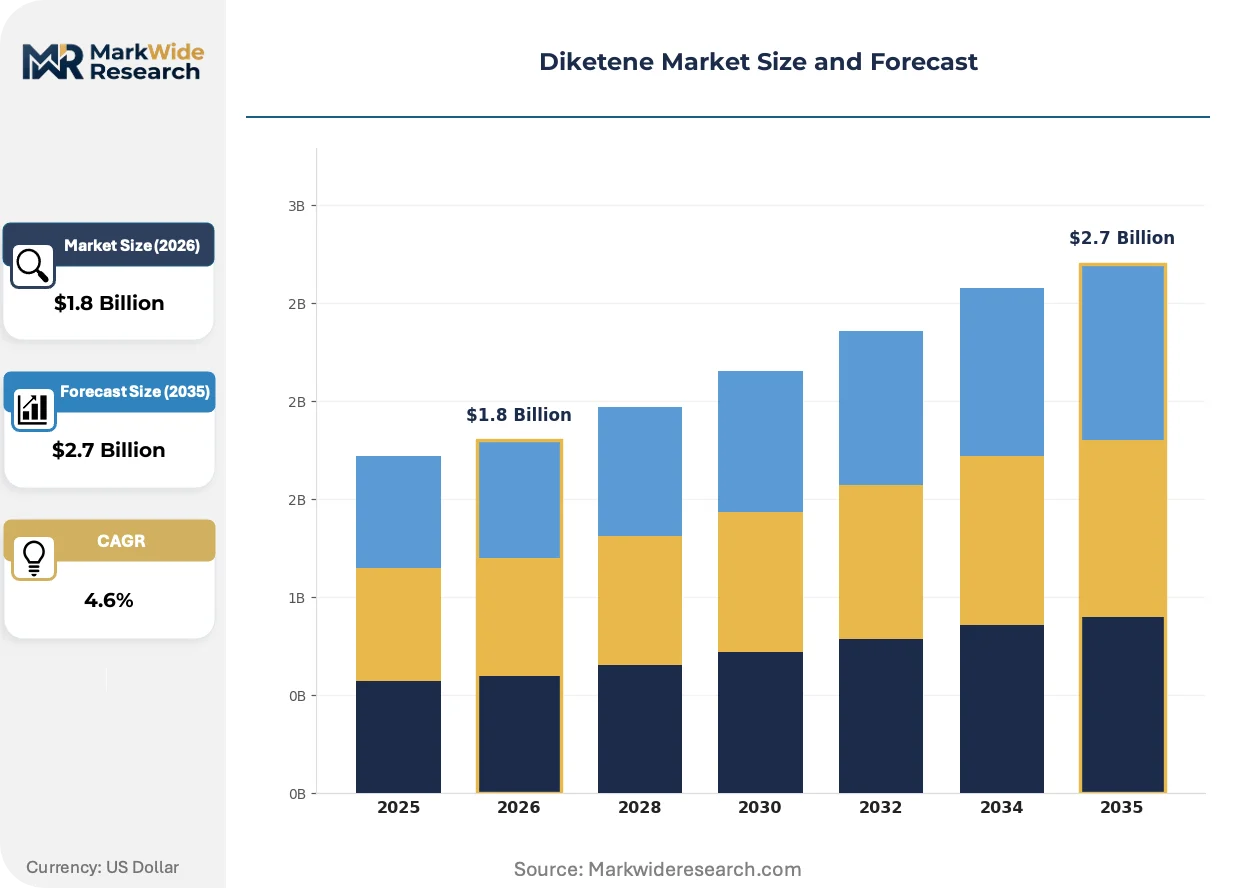
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetic Anhydride, Acetic Acid, Ethyl Acetate, Others Application: Pharmaceuticals, Agrochemicals, Dyes, Plastics End User: Chemical Manufacturers, Coatings Industry, Textile Industry, Food Industry Distribution Channel: Direct Sales, Distributors, Online Retail, Exporters |
| Companies Covered | Lonza Group AG, Eastman Chemical Company, Daicel Corporation, Laxmi Organics Industries Limited, Teijin Shoji Co. Ltd., Celanese Corporation, FMC Corporation, Mitsubishi Chemical Co., Ltd., Nantong Acetic Acid Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diketene Market Emerging Trajectories
Continuous processing technologies and regulatory carbon-accounting mandates are restructuring how diketene derivatives are manufactured, certified, and procured across pharmaceutical and agrochemical value chains.
Microreactor-based diketene generation is displacing traditional batch-wise ketene dimerization in pharmaceutical intermediate plants. Lonza and specialized CDMOs are adopting flow-chemistry platforms that reduce polymerization losses from 8-12% to under 3%. This technology is displacing conventional stirred-tank assets in high-purity acetoacetic ester production.
ECHA's REACH authorization timeline extensions for acetoacetic derivatives are compressing registration windows for non-EU exporters. The industrial consequence is accelerated dossier preparation costs and third-party testing expenditures. Specialty chemical distributors serving European agrochemical formulators are most affected, with many consolidating supplier bases to reduce compliance fragmentation.
Direct technical-service contracting is replacing spot-market purchasing among pharmaceutical API manufacturers. Buyers now require batch-specific impurity profiling and stability data packages that commodity traders cannot supply. This pattern is most visible in Swiss and German pharmaceutical clusters where Lonza and DSM operate integrated qualification programs.
Diketene Market Segmentation
Diketene derivative procurement channels vary sharply by purity grade and end-use criticality. Pharmaceutical API manufacturers demand direct technical partnerships, while agrochemical formulators tolerate distributor intermediation for commodity acetoacetic esters.
Product Type:
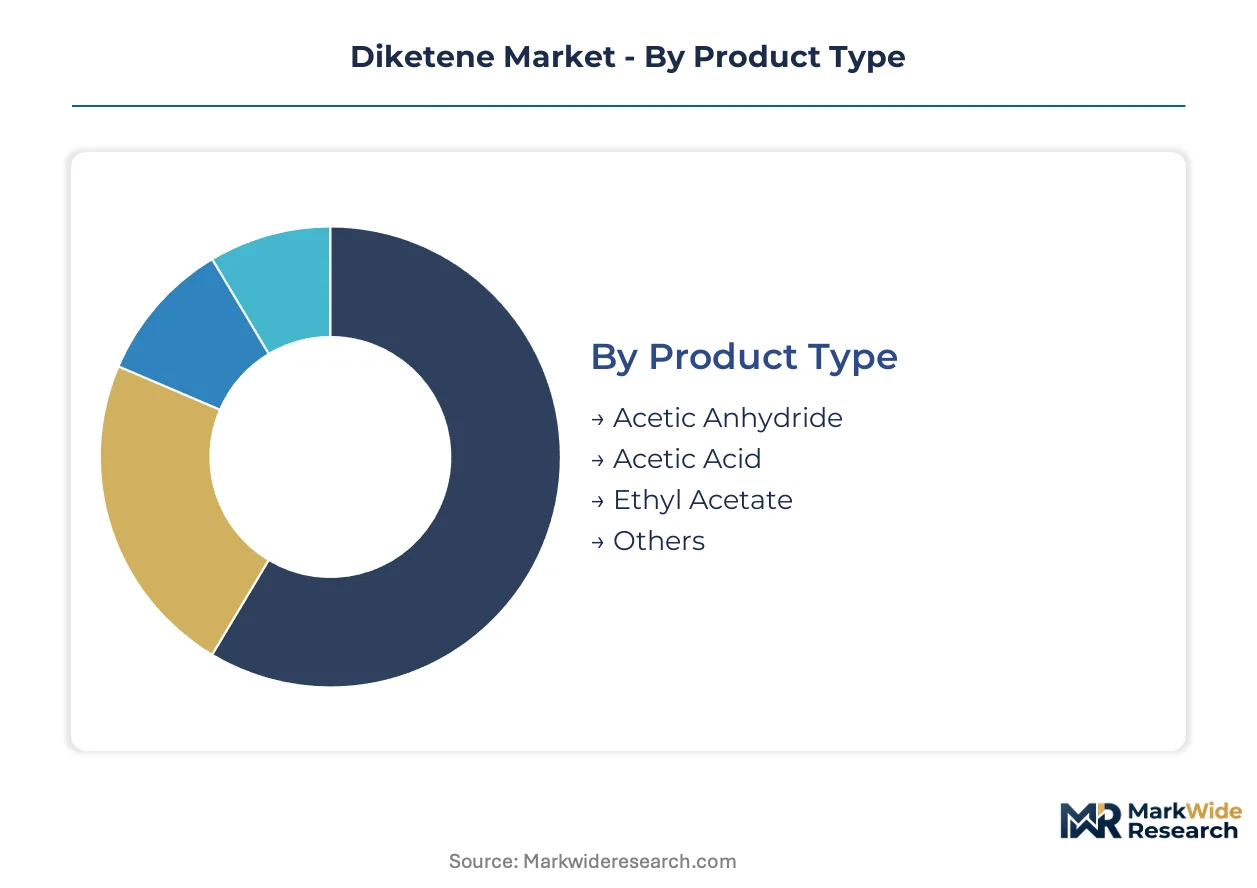
Channel-mix patterns split sharply: acetic anhydride and acetic acid flow predominantly through direct sales to integrated derivative producers, while ethyl acetate and specialty solvents move through distributor networks serving fragmented coatings and textile formulators.
- Acetic Anhydride:Primary feedstock for ketene generation via thermal cracking, requiring 99%+ purity and moisture specifications below 0.1%. Demand concentrates at Chinese coastal clusters with captive acetic acid supply, where SAMR-enforced GB storage standards elevate handling costs for non-integrated buyers.
- Acetic Acid:Serves as both diketene precursor and pH stabilizer in downstream esterification. Pharmaceutical-grade consumption in Basel and Mumbai API corridors is tightening impurity specifications for heavy metals and halogenated residuals.
- Ethyl Acetate:Common solvent carrier for stabilized diketene solutions in pigment and coating applications. Distributor channels dominate procurement for mid-scale Brazilian and Indian paint manufacturers.
- Others:Includes methyl acetate and specialty stabilizer blends for cryogenic transport formulations. Niche volumes flow through exporter networks serving Japanese pharmaceutical CDMOs.
Acetic anhydride dominates installed base. Ethyl acetate is where expansion concentrates.
Application:
Margin structures diverge by application maturity: pharmaceutical intermediates command three-tier pricing stratification across premium, standard, and economy certification grades, while agrochemical pyrazole derivatives compete on volume throughput.
- Pharmaceuticals:Beta-lactam antibiotic and antiretroviral intermediate synthesis requires sub-50ppm impurity thresholds. Swissmedic and CDSCO oversight in Basel and Hyderabad corridors is extending batch validation timelines.
- Agrochemicals:Pyrazole herbicide and fungicide formulations for Brazilian soybean and Indian cotton acreage. ECHA REACH authorization tiering is filtering non-compliant importers from European formulator supply bases.
- Dyes:Pigment intermediate production for textile coloration, primarily serving polyester and nylon fiber processors. Chinese Zhejiang and Jiangsu province clusters absorb volumes through direct mill procurement.
- Plastics:Acetoacetate plasticizers and polymer stabilizers for flexible PVC and engineering resin compounding. Automotive sector demand from Stuttgart and Detroit tier suppliers is stabilizing after prior volatility.
Pharmaceuticals capture value concentration. Agrochemicals is climbing the fastest.
End User:
Customer scale determines service intensity: chemical manufacturers with in-house derivative capability require technical co-development, while food industry buyers prioritize documentation packages for FDA and FSSAI compliance.
- Chemical Manufacturers:Integrated producers of acetoacetic esters and pyrazole intermediates with captive diketene handling infrastructure. Lonza and Eastman anchor procurement through multi-year direct contracts.
- Coatings Industry:Industrial and automotive paint formulators sourcing stabilized diketene for pigment dispersion. Brazilian and Mexican architectural coating producers are consolidating supplier bases.
- Textile Industry:Dye intermediate consumers in Surat and Shaoxing clusters, procuring through regional distributor networks with 30-day inventory terms.
- Food Industry:Limited direct diketene contact; primarily downstream acetoacetate derivative users for flavor and fragrance synthesis. Documentation burdens for FDA GRAS and FSSAI safety assessments dominate procurement criteria.
Chemical manufacturers dominate installed base. Coatings industry is where expansion concentrates.
Distribution Channel:
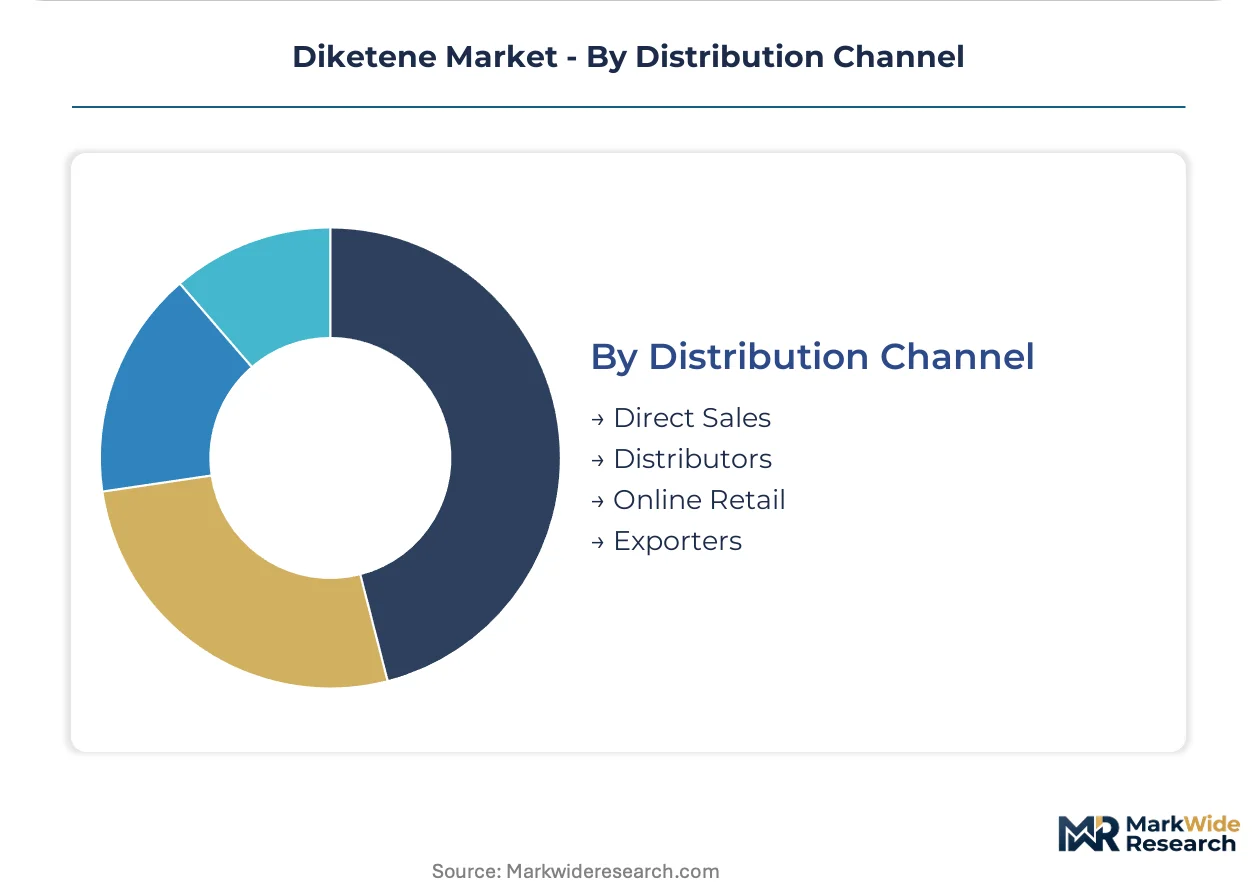
Channel selection tracks purity grade and geographic concentration: direct sales correlate with pharmaceutical certification requirements, while online retail penetration remains negligible due to cryogenic handling constraints.
- Direct Sales:Technical service contracts with batch-specific impurity profiling and stability data packages. Swiss and German pharmaceutical clusters require integrated qualification programs.
- Distributors:Regional chemical distributors serving fragmented agrochemical and coatings formulators with standard-grade acetoacetic esters. REACH registration tiering is compressing compliant supplier counts.
- Online Retail:Minimal penetration due to sub-zero cold chain requirements and hazardous material shipping restrictions. Limited to small-volume laboratory reagent sales.
- Exporters:Cross-border specialists navigating ECHA dossier preparation and third-party testing expenditures for non-EU producers. Indian and Chinese derivative manufacturers are consolidating export channels.
Direct sales dominates installed base. Distributors is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes diketene primarily for agrochemical pyrazole synthesis, while Switzerland and Germany channel derivatives into pharmaceutical-grade acetoacetic esters for API manufacturing. This consumption-mix differential shapes regulatory investment priorities and cold-chain infrastructure development across producing regions.
China
Jiangsu and Zhejiang provinces host integrated acetic acid-to-diketene complexes serving domestic pyrazole herbicide formulators. SAMR-enforced GB standards on sub-zero storage and transport elevate logistics costs for non-integrated distributors versus coastal cluster producers with captive cold-chain assets. Nantong and Taizhou chemical parks concentrate derivative output for Brazilian and Indian agrochemical export markets.
United States
Texas and Louisiana Gulf Coast acetic anhydride capacity feeds ketene generation for pharmaceutical intermediate producers. EPA-mandated thermal oxidizer installations at production sites strain mid-scale operators with capital allocation burdens for ketene emission abatement. Houston-area chemical manufacturers anchor North American supply through backward integration into methanol-carbonylation feedstock economics.
Germany
REACH registration tiering for acetoacetic esters filters low-volume importers from European derivative markets, tightening supply discipline for compliant manufacturers. ECHA dossier preparation costs and third-party testing expenditures compress margins for non-EU exporters serving German agrochemical formulators. Ludwigshafen and Leverkusen industrial corridors concentrate pharmaceutical-grade consumption with extended batch validation timelines.
India
Hyderabad and Mumbai API corridors expand diketene-derived intermediate consumption for efavirenz and non-nucleoside reverse transcriptase inhibitor synthesis. CDSCO oversight extends pharmaceutical-grade certification timelines, delaying customer qualification for new derivative suppliers. Gujarat chemical clusters integrate acetic anhydride procurement with pyrazole fungicide production for domestic cotton belt applications.
Switzerland
Swissmedic oversight in the Basel pharmaceutical corridor sustains premium pricing for sub-50ppm impurity threshold acetoacetic esters. Direct technical-service contracting replaces spot-market purchasing among API manufacturers requiring batch-specific impurity profiling. Lonza anchors high-purity derivative output through integrated qualification programs serving German and Swiss pharmaceutical clusters.
Diketene Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the diketene derivative market. Three strategic archetypes dominate: acetic acid-integrated Chinese producers with captive ketene generation, Swiss-Japanese pharmaceutical-grade specialists with stringent impurity controls, and North American chemical conglomerates with backward integration into acetic anhydride feedstock. Competitive moves concentrate on capacity expansion in coastal China clusters and strategic partnerships for REACH-compliant European market access.
Within the pharmaceutical-grade specialist tier, Lonza Group AG and Daicel Corporation exemplify the premium-tier positioning anchored by Swiss and Japanese regulatory infrastructure. Eastman Chemical Company occupies a position among North American acetic anhydride-integrated producers with Gulf Coast feedstock advantages. Laxmi Organics Industries Limited represents the Indian specialist archetype serving domestic API corridors with regional logistics optimization.
| Leading Market Players |
|---|
| Lonza Group AG |
| Eastman Chemical Company |
| Daicel Corporation |
| Laxmi Organics Industries Limited |
| Teijin Shoji Co. Ltd. |
| Celanese Corporation |
| FMC Corporation |
| Mitsubishi Chemical Co., Ltd. |
| Nantong Acetic Acid Chemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Ninety-day customer qualification timelines for pharmaceutical-grade acetoacetic esters concentrate pricing power among Swiss and German incumbent producers with established batch validation protocols, while non-integrated distributors absorb margin compression from SAMR-enforced GB cold-chain compliance costs in China.
Pricing Analysis
Multi-year direct contracts dominate pharmaceutical API procurement, replacing spot-market purchasing as Swissmedic and CDSCO oversight extends validation requirements. Pricing stratifies across premium, standard, and economy tiers based on impurity thresholds and certification grade, with sub-50ppm pharmaceutical specifications commanding substantial premiums over agrochemical-grade alternatives. Cost compression in standard-grade pyrazole intermediates is intensifying because Chinese acetic acid-integrated producers capture feedstock advantages that European converters cannot match. Agrochemical formulators in Brazil and India exhibit highest price sensitivity, while Basel and Hyderabad API manufacturers prioritize batch consistency over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites acetic anhydride feedstock flows to Nantong and Taizhou chemical parks, where integrated diketene generation clusters serve Brazilian agrochemical export markets. Supply concentrates in China, Switzerland, and the United States, with Jiangsu province hosting captive ketene generation assets and Basel anchoring pharmaceutical-grade purification. Raw material dependencies rest on methanol-carbonylation economics for acetic anhydride, specialized stabilizer additives for polymerization prevention, and cryogenic refrigerants for sub-zero transport. Single-source vulnerability around Swiss-Japanese pharmaceutical-grade specialists exposes European formulators to extended lead times during batch requalification. Distribution runs through direct technical-service contracts for pharmaceutical grades and regional distributor networks for commodity agrochemical intermediates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microreactor-based continuous flow synthesis is disrupting traditional batch-wise ketene dimerization, compressing polymerization losses and reshaping capital allocation priorities across pharmaceutical intermediate production.
For Market Incumbents: Fortify qualification program stickiness by embedding batch-specific impurity profiling into multi-year API supply contracts, and extend captive acetic acid integration into Jiangsu coastal clusters to match Chinese feedstock economics. Lonza and Eastman anchor positions through backward integration advantages that standalone European converters cannot replicate.
For New Entrants and Emerging Players: REACH registration fast-track services for Indian and Chinese derivative exporters present immediate white-space opportunity, targeting ECHA-compliant dossier preparation as German agrochemical formulators consolidate supplier bases. Brazilian pyrazole herbicide demand offers the most penetrable volume segment, with technical co-development partnerships replacing commodity spot sales as the viable go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because REACH authorization tiering and EPA emission abatement mandates are structurally filtering non-compliant competitors from premium derivative markets. Acquisition targets should concentrate on Swiss-Japanese pharmaceutical-grade specialists with established Swissmedic validation protocols. The signal to watch is CDSCO timeline extensions for Indian API corridor qualification, which would accelerate consolidation pressure on regional logistics-optimized producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Anhydride | Captive methanol-carbonylation assets in Texas and Louisiana anchor North American ketene generation economics against Chinese coastal clusters. |
| Continuous Flow Synthesis Adoption | Microreactor platforms at Lonza and specialized CDMOs reduce polymerization losses from conventional stirred-tank assets. |
| REACH Compliance Service Expansion | Third-party dossier preparation for non-EU exporters captures margin as ECHA authorization windows compress for acetoacetic derivatives. |
| Cryogenic Cold-Chain Infrastructure | Sub-zero transport asset deployment in Jiangsu and Zhejiang elevates handling costs for non-integrated distributors versus integrated producers. |
| Antiretroviral API Partnership Programs | Direct technical-service contracting with Hyderabad and Mumbai manufacturers displaces spot-market purchasing for efavirenz intermediates. |
Methodological Framework
Initial hypotheses were tested against primary input from pharmaceutical plant managers, agrochemical procurement leads, acetic anhydride distribution channel partners, and technical R&D directors at CDMOs, and refined through secondary validation against customs/trade data, Cefic sector reports, SEC 10-K filings, and ECHA registration databases. Bottom-up capacity modeling across Chinese coastal clusters triangulated with top-down demand estimation from Brazilian and Indian agrochemical formulation data.
Variance decomposition across product grade, end-use industry, regional production hub, and certification tier shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by purity-premium realization rates, with ketene emission abatement capital requirements and REACH registration cost burdens incorporated as supply-side constraints.
Decision-makers should treat outputs as directional under stable acetic anhydride feedstock economics and unchanged ECHA authorization timelines; material deviation in methanol-carbonylation costs or regulatory tiering would warrant model refresh. Practitioners should keep alternative scenarios live as EPA ketene exposure limit revisions and SAMR cold-chain enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Bulk Ingredients Market
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
Bio Based Paraxylene Market
Bulk Chemicals
Refined Naphthalene Market
Bulk Chemicals
Sodium Hypophosphite Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
Europe Lipids Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
Linear Alkylbenzene (LAB) Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
Global Pitch Coke Market
Bulk Chemicals
Crude Tall Oil Derivative Market
Bulk Chemicals
Sodium Nitrate Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Propionic Acid Market