
 Cosmetic Grade Preservative Market | 2026-2036
Cosmetic Grade Preservative Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Grade Preservative Market Insights
Multi-source procurement for active preservative ingredients is recalibrating how personal care brands manage supply security and cost exposure. BASF SE leverages its integrated petrochemical feedstock position to sustain phenoxyethanol cost advantages across European manufacturing. Lonza Group anchors its competitive stance through biotechnology-derived preservation platforms that reduce petrochemical dependency. Symrise differentiates via botanical extract synergies that extend shelf-life claims for clean-label skin care formulations.
Cosmetic grade preservatives comprise biocidal and biostatic compounds formulated to inhibit microbial proliferation in water-based personal care products, typically active at concentrations between 0.1% and 1.0% by weight. These substances function through membrane disruption, metabolic interference, or proton gradient collapse to ensure product safety across shelf and in-use periods. Organic acids and phenoxyethanol segments command expanding share as paraben alternatives gain traction among personal care brands responding to consumer ingredient scrutiny. Formaldehyde donor systems occupy a contracting position in skin care applications while maintaining residual demand in hair care where cost sensitivity remains acute. Isothiazolinone usage concentrates in rinse-off formats as leave-on restrictions tighten across dermatology clinic procurement standards.
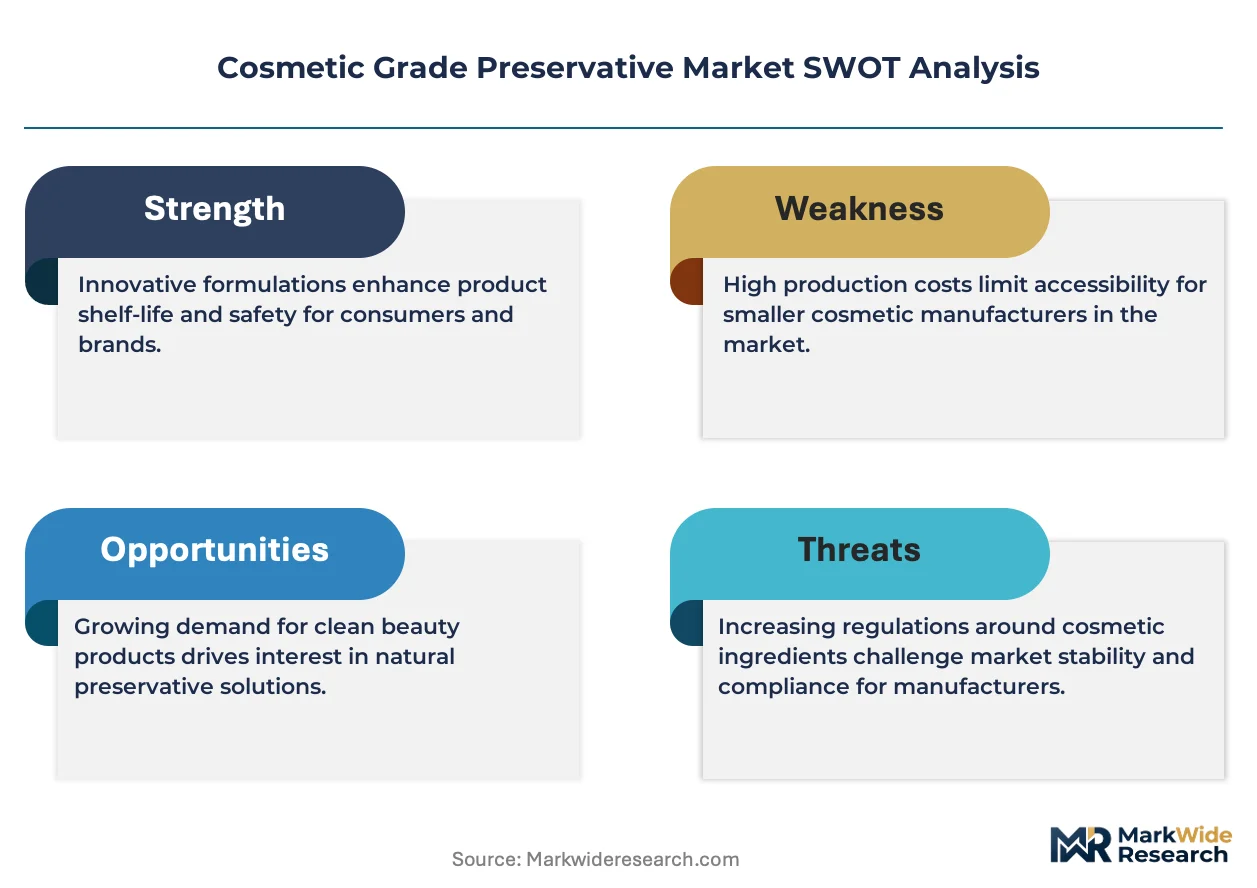
REACH registration requirements and the EU Green Deal chemical sustainability framework are elevating compliance costs for conventional preservative chemistries while creating preferential pathways for biodegradable alternatives. ECHA substance evaluation protocols directly determine market access timelines for new active ingredients entering European personal care supply chains. FDA cosmetic ingredient oversight and emerging state-level disclosure mandates in California and New York are layering additional compliance complexity for brands operating across transatlantic markets. Stakeholders must monitor regulatory divergence between European hazard-based restrictions and American risk assessment frameworks when prioritizing preservation platform investments.
Market Dynamics
REACH substance evaluation protocols and the EU Green Deal chemical sustainability framework are systematically elevating compliance costs for conventional biocidal chemistries while redirecting formulation investment toward biodegradable preservation platforms. This regulatory pivot is compressing market access timelines and forcing active ingredient portfolios toward organic acid blends and phenoxyethanol alternatives.
Growth Catalysts
- Clean beauty procurement mandates:Personal care brands across Germany and France are reformulating water-based skin care lines to exclude formaldehyde donors ahead of tightening dermatology clinic standards.
- REACH registration pathways:Biodegradable active ingredients now receive preferential market access timelines under ECHA evaluation protocols compared to legacy biocidal chemistries.
- Rinse-off format concentration:Isothiazolinone usage is concentrating in hair care applications where leave-on restrictions do not apply, sustaining residual demand for cost-sensitive preservation systems.
Market Restraints
- Petrochemical feedstock volatility:Phenoxyethanol production costs fluctuate with ethylene oxide pricing, compressing margin stability for European manufacturers dependent on integrated petrochemical supply.
- Biotechnology scale-up bottlenecks:Fermentation-derived preservation platforms face yield constraints that limit batch consistency compared to synthetic biocide manufacturing.
- Paraben substitution complexity:Clean-label alternatives often require higher active concentrations or synergistic blends, elevating raw material costs per finished formulation.
Strategic Opportunities
- Botanical extract synergies:Antimicrobial plant-derived compounds combined with mild organic acids enable shelf-life extension claims for premium skin care lines targeting ingredient-conscious consumers.
- State-level disclosure mandates:California and New York cosmetic ingredient reporting requirements are creating first-mover advantages for brands with pre-positioned transparent preservation platforms.
- Biotechnology platform licensing:Contract manufacturing arrangements for fermentation-derived actives offer asset-light entry for mid-size personal care brands seeking petrochemical independence.
Industry Challenges
- Formulation compatibility testing:Preservative efficacy validation across diverse emulsion chemistries extends product development timelines and elevates R&D headcount requirements.
- Regulatory divergence management:Brands operating across European hazard-based restrictions and American risk assessment frameworks must maintain dual compliance documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Grade Preservative Market |
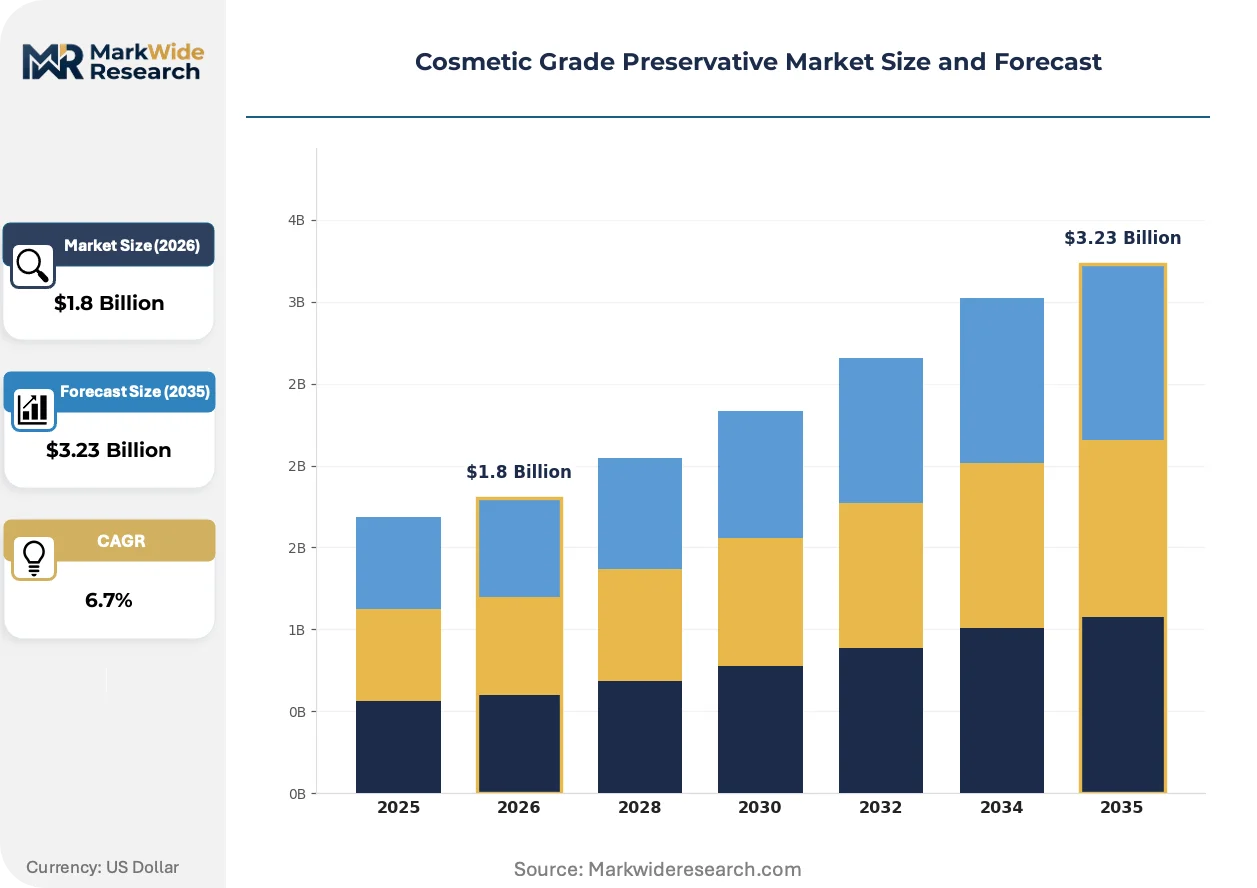
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parabens, Phenoxyethanol, Organic Acids, Formaldehyde Donors, Isothiazolinones Form: Liquid, Powder, Emulsion, Gel, Solid Application: Skin Care, Hair Care, Color Cosmetics, Oral Care, Sun Care End User: Personal Care Brands, Contract Manufacturers, Dermatology Clinics, Beauty Salons |
| Companies Covered | BASF SE, Ashland, Lonza Group, Clariant, Symrise, Dow, Evonik Industries, Brenntag SE, Akema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Grade Preservative Market Trends and Innovations
Preservation technology is bifurcating between synthetic biocide optimization and biotechnology-derived alternatives, with regulatory pressure accelerating the shift toward biodegradable active platforms. Formulation science is converging with systems biology to engineer microbial inhibition through metabolic interference rather than membrane toxicity.
Multi-functional preservation systems combining organic acids with chelating agents are expanding into premium skin care and sensitive skin product lines. European dermatology brands are adopting these platforms at accelerated pace to preempt REACH restrictions on conventional biocides. The technology is expanding into previously paraben-dependent segments by enabling comparable shelf-life claims with improved consumer ingredient perception.
ECHA substance evaluation protocols under REACH are compressing market access for new synthetic biocides while expediting pathways for biodegradable alternatives. Cosmetic ingredient manufacturers are redirecting registration investment toward organic acid blends and fermentation-derived actives. Skin care applications face the most acute compliance pressure, with hair care maintaining residual tolerance for conventional chemistries due to rinse-off format classification.
Ingredient transparency mandates are reshaping procurement criteria for personal care brands, with preservation system selection now preceding formulation architecture in product development workflows. Clean-label certification programs are displacing traditional efficacy-only supplier evaluation in premium segment sourcing. This behavioral shift is most visible in German and French brand procurement, where reformulation timelines now align with regulatory deadline clustering rather than traditional product refresh cycles.
Cosmetic Grade Preservative Market Segmentation
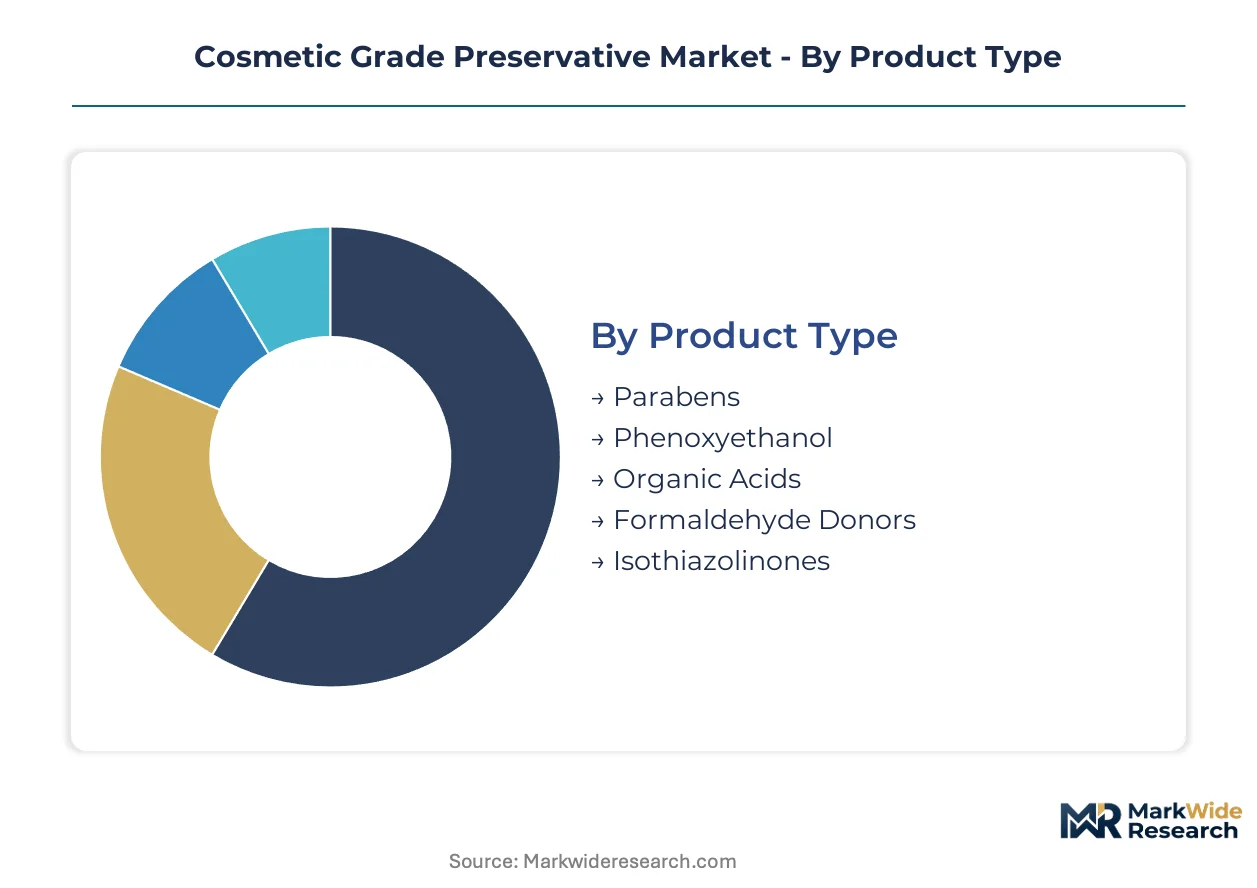
Preservative selection in cosmetic formulations follows distinct technical and commercial logics across product chemistry, physical state, application category, and buyer type. Each segmentation dimension carries specific regulatory weight and supply chain implications that determine procurement priorities for personal care brands.
Product Type:
Supply concentration for active preservative ingredients varies sharply by chemistry family, with petrochemical-derived phenoxyethanol and fermentation-based organic acids commanding divergent manufacturing footprints.
- Parabens:Ester-based antimicrobial compounds including methylparaben and propylparaben deliver broad-spectrum efficacy at low concentrations. German and French personal care brands are systematically excluding these chemistries ahead of REACH substance evaluation deadlines, compressing demand toward alternative preservation platforms.
- Phenoxyethanol:A glycol ether synthesized from ethylene oxide, this chemistry dominates water-based skin care preservation due to cost efficiency and regulatory acceptance across FDA and ECHA frameworks. BASF SE maintains supply advantages through integrated petrochemical feedstock positions at Ludwigshafen and Antwerp manufacturing complexes.
- Organic Acids:Sorbic acid, benzoic acid, and their salt derivatives function through pH-dependent metabolic interference in acidic formulations. Biotechnology fermentation routes are displacing synthetic production for clean-label claims.
- Formaldehyde Donors:Slow-release compounds including DMDM hydantoin preserve hair care and industrial formulations where cost sensitivity outweighs ingredient perception concerns. Dermatology clinic procurement standards are accelerating phase-out in leave-on skin applications.
- Isothiazolinones:Methylisothiazolinone and methylchloroisothiazolinone deliver potent biocidal activity at parts-per-million concentrations. ECHA restrictions confine usage to rinse-off formats, sustaining residual demand in hair care while eliminating leave-on applications.
Phenoxyethanol absorbs the bulk of installed capacity; organic acids are expanding most quickly.
Form:
Physical presentation determines compatibility with formulation equipment, dissolution kinetics, and stability during storage and transport.
- Liquid:Pre-dissolved aqueous or solvent-based solutions enable direct incorporation into emulsion manufacturing without heating cycles. Concentrated liquid phenoxyethanol dominates high-volume skin care production at contract manufacturing facilities.
- Powder:Spray-dried or crystalline actives offer extended shelf stability and reduced shipping costs for distant supply chains. Powdered organic acids require controlled humidity handling to prevent caking and potency degradation.
- Emulsion:Pre-dispersed preservative systems in oil-in-water carriers simplify incorporation into cold-process formulations. These specialty forms command premium pricing for sensitive skin and natural-positioned product lines.
- Gel:Thickened aqueous matrices prevent separation and enable precise dosing in laboratory and pilot-scale manufacturing. Gel formats find preference among dermatology clinic compounding pharmacies.
- Solid:Compressed tablets or pellets support specific oral care and solid cleanser applications where liquid preservation is impractical. Limited demand constrains dedicated manufacturing investment.
Liquid forms dominate manufacturing throughput; emulsion formats are climbing the fastest on clean-process demand.
Application:
Product category determines regulatory scrutiny intensity, exposure duration, and consumer ingredient sensitivity thresholds.
- Skin Care:Facial moisturizers, serums, and cleansers face the most stringent preservation requirements due to extended skin contact and damaged-barrier user populations. ECHA evaluation protocols and dermatology clinic procurement standards are driving reformulation toward organic acid and phenoxyethanol systems.
- Hair Care:Shampoos, conditioners, and styling products tolerate broader preservation chemistries due to rinse-off classification and lower dermal absorption risk. Isothiazolinone and formaldehyde donor systems maintain residual demand in this cost-sensitive segment.
- Color Cosmetics:Anhydrous formulations reduce water activity and preservation burden, though liquid foundations and mascaras require robust microbial control. Powder formats leverage packaging design over chemical preservation.
- Oral Care:Toothpastes and mouthwashes incorporate preservatives alongside flavor systems, with regulatory limits stricter than skin applications due to mucosal exposure and accidental ingestion risk.
- Sun Care:UV filter compatibility testing extends development timelines, with photostability requirements adding complexity to preservation system selection. Organic acid blends are displacing parabens in premium beach and daily wear segments.
Skin care commands the largest formulation investment; sun care is gaining share fastest on SPF-moisturizer hybrid proliferation.
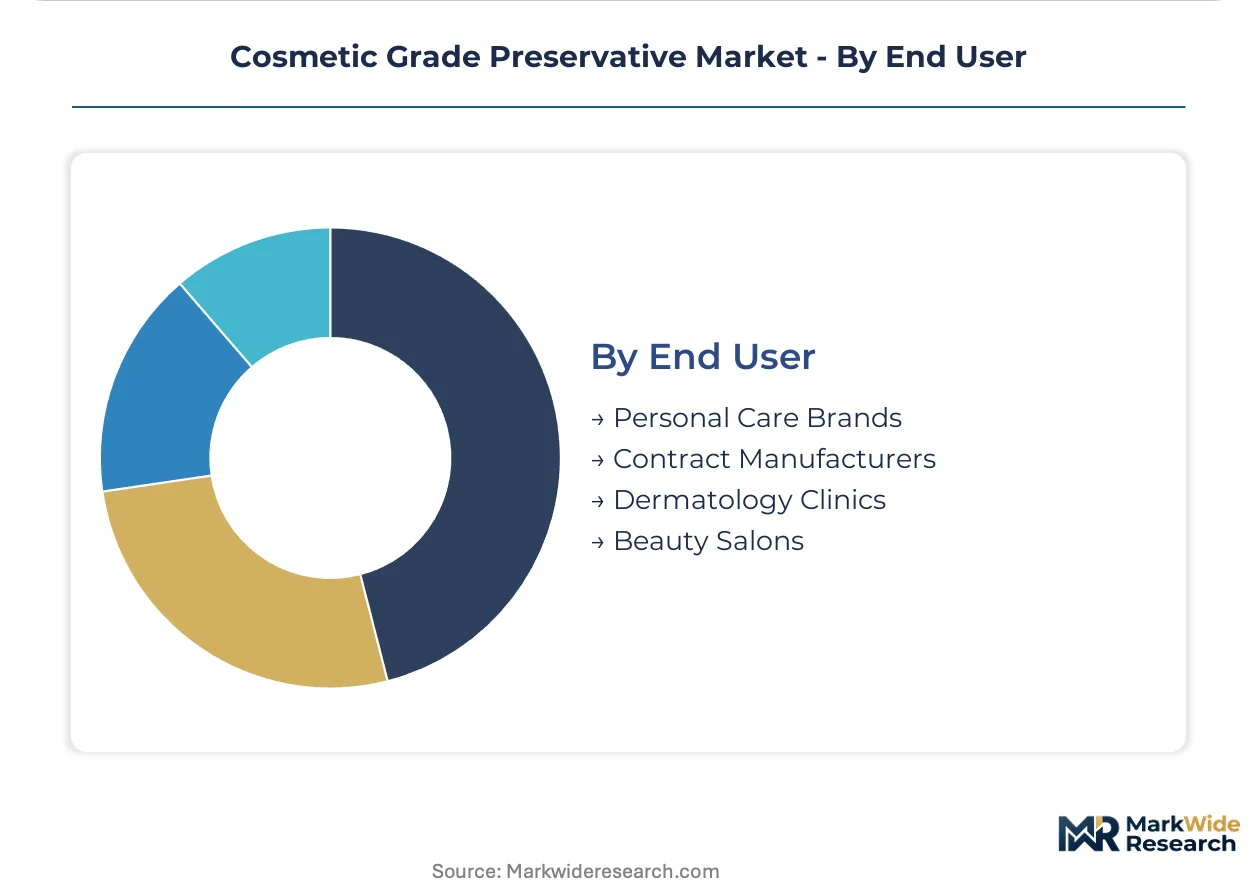
End User:
Buyer sophistication and compliance obligations create distinct procurement behaviors across the value chain.
- Personal Care Brands:L'Oréal, Unilever, and Beiersdorf-scale entities maintain internal toxicology and regulatory affairs functions that evaluate preservation platforms against multi-jurisdiction requirements. Clean beauty positioning is accelerating direct investment in biotechnology-derived alternatives.
- Contract Manufacturers:Toll production facilities serving mid-size brands prioritize preservative flexibility to accommodate diverse client specifications. Multi-source active procurement has become standard to mitigate supply disruption exposure.
- Dermatology Clinics:Medical-channel skin care lines face elevated scrutiny from prescribing physicians and institutional procurement committees. ECHA substance restrictions are codifying into clinic-level ingredient exclusion policies.
- Beauty Salons:Professional-use hair color and treatment products prioritize cost efficiency and salon-worker safety over consumer-facing ingredient transparency. Bulk concentrate formats dominate this channel.
Personal care brands direct the steepest preservation R&D spending; dermatology clinics are tightening specifications fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene oxide feedstock availability in the Antwerp-Rotterdam corridor anchors European phenoxyethanol manufacturing. German chemical parks concentrate fermentation capacity for organic acid production. Asian fermentation platforms in China and South Korea supply cost-competitive benzoic acid derivatives.
Germany
L'Oréal and Beiersdorf procurement mandates drive reformulation toward REACH-compliant preservation systems. ECHA substance evaluation protocols under the EU Green Deal compress market access timelines for conventional biocides. The Ludwigshafen chemical complex maintains integrated phenoxyethanol production serving personal care brands across Western Europe.
France
Dermatology clinic procurement standards exclude formaldehyde donors from leave-on skin care formulations. ANSM cosmetic ingredient oversight aligns with ECHA restrictions on isothiazolinone concentrations. Paris-based clean beauty brands accelerate organic acid adoption ahead of regulatory deadline clustering.
United States
FDA cosmetic ingredient oversight and emerging state-level disclosure mandates in California and New York layer compliance complexity for transatlantic brands. The New Jersey chemical corridor distributes preservative actives to contract manufacturing facilities serving mid-size personal care companies. Multi-source procurement has become standard practice among domestic toll producers.
United Kingdom
Post-Brexit regulatory divergence from REACH creates dual compliance documentation requirements for brands operating across European markets. The Midlands manufacturing belt hosts contract manufacturing facilities reformulating water-based skin care lines. Clean-label certification programs displace traditional efficacy-only supplier evaluation in premium segment sourcing.
China
SAMR cosmetic safety regulations and GB standards govern preservative concentration limits in domestic and export formulations. The Yangtze River Delta fermentation industry supplies sorbic acid and benzoic acid derivatives at scale-competitive pricing. Zhejiang and Jiangsu provinces concentrate spray-dried organic acid manufacturing for distant supply chains.
Cosmetic Grade Preservative Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation-derived preservation platforms scale to meet clean beauty procurement mandates. The vendor base stratifies across three tiers: integrated petrochemical producers, biotechnology specialists, and botanical extract formulators. Strategic archetypes include feedstock-integrated manufacturers, fermentation platform operators, and clean-label ingredient blenders. M&A activity concentrates on biotechnology licensing arrangements and regional distribution network consolidation.
Within the integrated petrochemical tier, BASF SE exemplifies feedstock-integrated manufacturing anchored in European chemical park infrastructure. Lonza Group occupies a position among biotechnology platform operators leveraging fermentation-derived preservation systems. Symrise sits within the botanical extract segment, representing clean-label formulation approaches that combine antimicrobial plant-derived compounds with mild organic acids.
| Leading Market Players |
|---|
| BASF SE |
| Ashland |
| Lonza Group |
| Clariant |
| Symrise |
| Dow |
| Evonik Industries |
| Brenntag SE |
| Akema |
| Others |
Pricing and Supply Chain Analysis
Fermentation-derived preservation platforms are displacing synthetic biocide manufacturing, simultaneously elevating batch production costs and fragmenting supply concentration across European biotechnology clusters and Asian fermentation hubs. This technology transition compresses margin stability for brands dependent on petrochemical-derived phenoxyethanol while creating premium pricing tiers for clean-label organic acid alternatives.
Pricing Analysis
Technical service bundling separates contract manufacturing arrangements from pure ingredient supply, with formulation compatibility testing and regulatory documentation unbundled at the standard tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from petrochemical feedstock volatility compressing phenoxyethanol margins, while contract manufacturers exhibit acute price sensitivity compared to integrated personal care brands with captive R&D functions.
Supply Chain Analysis
Regional distribution centers in the Antwerp-Rotterdam corridor and Yangtze River Delta maintain hub-and-spoke patterns serving contract manufacturing facilities across Western Europe and East Asia. Supply concentrates in Germany, China, and South Korea, with fermentation capacity anchored in the Ludwigshafen chemical complex and Zhejiang province manufacturing zones. Raw material dependencies center on ethylene oxide, corn-derived fermentation feedstock, and benzoic acid derivatives. Single-source vulnerability persists for biotechnology-derived actives with limited qualified suppliers. Distribution runs through toll manufacturing networks serving mid-size personal care brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation scale-up bottlenecks constrain biotechnology-derived preservation capacity, propping pricing premiums for clean-label alternatives and sustaining margin pools for incumbent synthetic producers.
For Market Incumbents: Deepen backward integration into ethylene oxide supply chains at Ludwigshafen and Antwerp chemical parks to defend phenoxyethanol cost positions against biotechnology substitution. Expand fermentation capacity in Germany ahead of REACH deadline clustering to capture organic acid demand from reformulating French and German personal care brands. For New Entrants and Emerging Players: Enter via contract manufacturing partnerships for fermentation-derived actives, targeting mid-size personal care brands seeking petrochemical independence without captive biotechnology investment. Focus initial penetration on dermatology clinic procurement channels where ECHA restriction timelines are codifying into institutional exclusion policies. For Investors and Strategic Acquirers: Exit pathways concentrate in biotechnology platform licensing arrangements and regional distribution network consolidation. Five-to-ten year viability favors fermentation specialists with proven scale-up yields over synthetic biocide assets facing REACH compression. Monitor ECHA substance evaluation protocol announcements as the critical inflection signal for portfolio rebalancing timing.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Biotechnology scale-up in German chemical parks captures clean beauty procurement mandates from L'Oréal and Beiersdorf. |
| Backward Integration into Ethylene Oxide | Captive petrochemical feedstock at BASF Ludwigshafen sustains phenoxyethanol cost advantages against Asian imports. |
| Regulatory Registration Investment | ECHA REACH compliance for organic acid blends accelerates market access timelines relative to legacy biocides. |
| Botanical Extract Licensing | Symrise antimicrobial plant compound patents enable shelf-life claims for premium sensitive skin formulations. |
| Contract Manufacturing Partnership | Toll production arrangements offer asset-light entry for mid-size brands seeking biotechnology-derived preservation systems. |
Research Methodology
Multi-period observation of ECHA substance evaluation timelines, fermentation capacity buildouts, and personal care brand reformulation announcements anchored the trend analysis, supplemented by interviews with technical R&D directors at ingredient manufacturers, procurement leads at contract manufacturing facilities, regulatory affairs specialists, and dermatology clinic purchasing committees. Secondary validation drew from REACH registration databases, ECHA evaluation protocols, SEC 10-K filings of listed chemical companies, and customs trade data for preservative active imports. Bottom-up triangulation across product-type demand curves and top-down validation against regional production capacity estimates structured the market sizing.
Input-output matrices modeled preservative active consumption against finished personal care product volumes across chemistry family, physical form, application category, and end-user procurement sophistication. Segmentation dimensions included grade tier, end-use industry, packaging format, and regional production hub. CAGRs were derived from regression analysis of historical consumption patterns projected across the analysis window. Industry-specific forecast inputs incorporated REACH compliance deadline clustering and clean beauty certification adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA restriction timelines or biotechnology yield breakthroughs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Sodium Bisulphite Market
Disinfectants and Preservatives
IV Disinfecting Caps Market
Disinfectants and Preservatives
Global Potassium Sorbate Market
Disinfectants and Preservatives
Air Treatment Products Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
UVC Disinfection Products Market
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
Disinfectant Wipes Market
Disinfectants and Preservatives
Color Preservatives Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market
Disinfectants and Preservatives
Antimicrobial Chemicals Market
Disinfectants and Preservatives
North America Hydrogen Peroxide Market
Disinfectants and Preservatives
Global Mold Inhibitors Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
Sterilants Market