
 Asia-Pacific Non-Phthalate Plasticizers Market | 2026-2036
Asia-Pacific Non-Phthalate Plasticizers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Non-Phthalate Plasticizers Market Outlook
Price-performance divergence between premium bio-based formulations and commodity petrochemical alternatives is recalibrating procurement strategies across Asia-Pacific vinyl compounders. BASF SE leverages its integrated adipic acid chain to sustain cost leadership in sebacate and adipate grades. LG Chem anchors high-volume supply to Korean automotive OEMs, while Eastman Chemical Company differentiates through trimellitate specialization for high-temperature wire and cable applications.
Non-phthalate plasticizers are synthetic or bio-derived compounds, typically esters of adipic, citric, sebacic, or trimellitic acids, that impart flexibility and workability to polyvinyl chloride without incorporating ortho-phthalate structures; they function by inserting between polymer chains to reduce glass transition temperature and enhance elongation at break. The product type landscape shows adipate and trimellitate formulations dominating volume due to their cost-performance balance in flooring and wire insulation, while citrate esters capture premium positioning in food-contact films and medical-grade PVC where regulatory thresholds are tightest. Application demand clusters in flooring and plastic films, with coatings and adhesives representing faster-growing niches as waterborne formulation standards tighten across Japanese and South Korean industrial sectors.
China's SAMR enforces GB standards restricting phthalate content in toys and childcare articles, while Japan's METI maintains JIS standards for electrical cable sheathing that increasingly reference non-phthalate alternatives; South Korea's MFDS and KOSHA jointly shape occupational exposure limits that push processors toward lower-toxicity plasticizer systems. India's BIS has initiated alignment with EU REACH restricted substance lists, creating compliance complexity for exporters serving European automotive and consumer goods supply chains. Stakeholders must monitor divergence between national GB standards, JIS certification requirements, and emerging ASEAN harmonization frameworks to anticipate where formulation switching mandates will tighten next.
Market Dynamics
REACH-aligned regulatory pressure from the EU Green Deal is forcing Asian chemical producers to reconfigure formulation portfolios for export compliance, while automotive OEMs in China and Southeast Asia accelerate specification switches for interior vinyl components.
Growth Catalysts
- EU Green Deal export alignment:Asian compounders serving European automotive supply chains must certify non-phthalate content under REACH restricted substance lists, creating formulation switching mandates across China's eastern manufacturing corridor.
- Automotive interior specifications:Korean and Japanese OEMs now require adipate and sebacate grades for dashboard skins and door panels, pulling volume from ortho-phthalate legacy systems.
- GB standards enforcement:China's SAMR restricts phthalate content in toys and childcare articles, compelling domestic PVC processors to source citrate esters for compliant export production.
Market Restraints
- Castor oil supply volatility:Sebacate production depends on Indian and Brazilian castor bean harvests, exposing bio-based grades to agricultural commodity swings that petrochemical alternatives avoid.
- Adipic acid concentration:BASF SE and LG Chem control integrated adipic acid chains, limiting cost-competitive entry for mid-scale compounders seeking adipate grade supply security.
- Performance gaps in low-temperature flexibility:Trimellitate formulations struggle to match ortho-phthalate efficiency below minus 20 degrees Celsius, constraining adoption in cold-climate automotive applications.
Strategic Opportunities
- Indian BIS-REACH convergence:India's alignment with EU restricted substance lists creates compliance complexity that domestic non-phthalate producers can exploit to capture export-oriented compounders.
- Waterborne coatings transition:Japanese and South Korean industrial sectors are tightening VOC standards, opening volume for citrate and adipate esters in adhesive and sealant formulations.
- Medical-grade PVC specialization:Tightest regulatory thresholds in food-contact films and blood bag applications position premium citrate esters for margin expansion.
Industry Challenges
- Formulation requalification timelines:Automotive OEMs demand 18-24 month validation cycles for new plasticizer systems, compressing supplier switching windows and locking in incumbent relationships.
- Legacy equipment incompatibility:Southeast Asian PVC processors running 1990s-era calendering lines face retrofit costs to handle higher-viscosity non-phthalate grades without throughput loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Non-Phthalate Plasticizers Market |
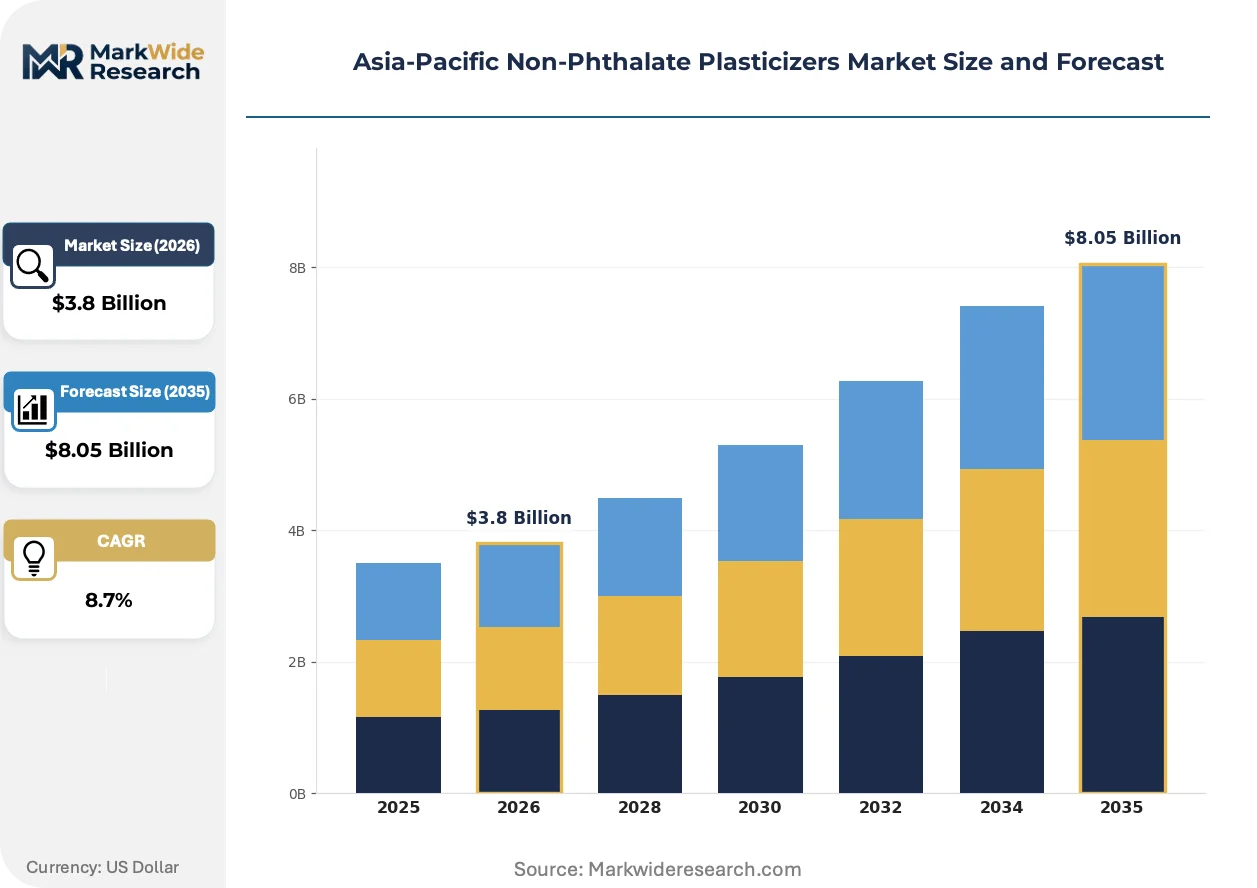
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adipate, Citrate, Sebacate, Trimellitate Application: Flooring, Coatings, Adhesives, Plastic Films End User: Automotive, Construction, Consumer Goods, Electronics Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | UPC Technology Corporation, NAN YA PLASTICS CORPORATION, LG Chem, BASF SE, Eastman Chemical Company, Evonik Industries AG, DIC Corporation, Kao Corporation, Aekyung Chemical, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Non-Phthalate Plasticizers Market Strategic Shifts
Formulation science and regulatory compliance are converging to reshape how vinyl compounders specify, source, and certify plasticizer systems across the Asia-Pacific supply base.
Bio-based sebacate production from castor oil derivatives is modularizing supply chain architecture for automotive and flooring segments. Korean tier-one suppliers are piloting dedicated sebacate blending facilities co-located with OEM assembly plants. This distributed production model is modularizing the traditional centralized petrochemical supply structure, reducing freight exposure and enabling just-in-time inventory.
Japan's METI has revised JIS standards for electrical cable sheathing to explicitly reference non-phthalate alternatives in high-temperature applications. Japanese wire and cable manufacturers now face mandatory requalification of legacy formulations for domestic infrastructure projects. The industrial cable segment is responding fastest, with trimellitate grades capturing specification share in power transmission sheathing.
Compounders in China's Shandong and Jiangsu provinces are consolidating procurement through direct long-term contracts with adipic acid producers, bypassing traditional distributor networks. This disintermediation concentrates buying power among the largest vinyl processors while marginalizing mid-scale compounders dependent on spot market supply. The pattern is most visible in flooring applications, where cost pressure from real estate developers drives aggressive input cost management.
Asia-Pacific Non-Phthalate Plasticizers Market Segmentation
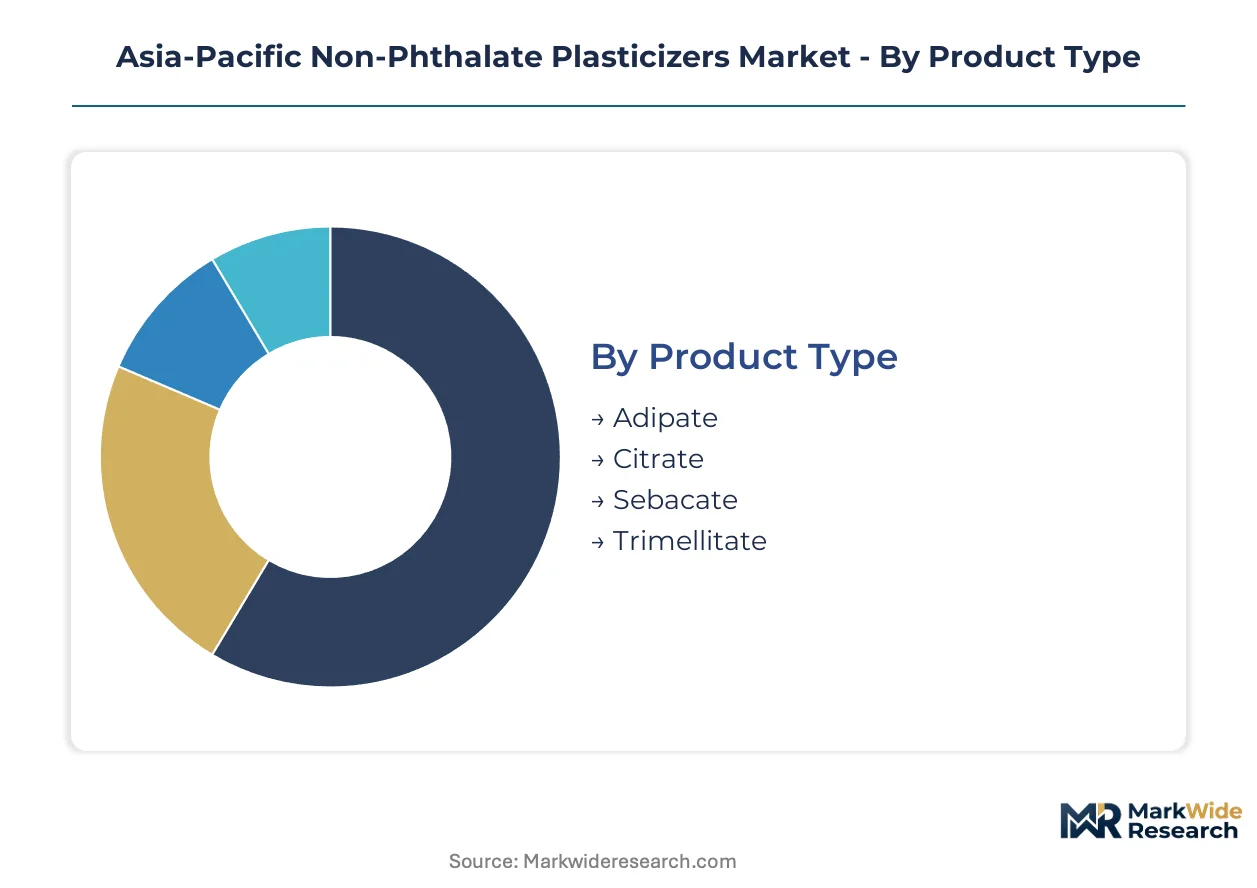
Non-phthalate plasticizer procurement in Asia-Pacific fragments across performance requirements, regulatory exposure, and supply chain proximity. Compounders select grades based on specific end-use temperature demands, migration limits, and OEM certification status rather than commodity pricing alone.
Product Type:
Supply concentration in adipic acid chains shapes competitive access across this category, with integrated producers capturing volume in high-throughput applications while specialty esters command premium positioning.
- Adipate:Diesters of adipic acid with C8-C10 alcohols deliver balanced cost-performance for general-purpose flexible PVC. Demand concentrates in China's Shandong flooring clusters where real estate developers pressure input costs. The grade dominates wire insulation and calendered sheet production across eastern manufacturing corridors.
- Trimellitate:Triesters of trimellitic anhydride provide exceptional volatility resistance and high-temperature stability. Japanese wire and cable manufacturers specify these grades for power transmission sheathing under revised METI JIS standards. The chemistry addresses migration concerns in automotive interior applications exposed to cabin heat cycling.
- Citrate:Esters of citric acid with C8-C10 alcohols serve food-contact films and medical-grade PVC where regulatory thresholds are tightest. SAMR GB standards enforcement drives specification in toys and childcare articles.
- Sebacate:Diesters derived from castor oil deliver superior low-temperature flexibility. Korean automotive OEMs specify these grades for cold-climate dashboard skins despite agricultural supply volatility from Indian and Brazilian harvests.
Today's leader: Adipate. Tomorrow's challenger: Sebacate.
Application:
Cost tier differentiation separates commodity volume applications from formulation-switching niches where regulatory pressure enables margin capture.
- Flooring:Vinyl sheet and tile production consumes the largest adipate volumes across China, India, and Southeast Asia. Jiangsu province compounders consolidate procurement through direct adipic acid contracts, bypassing distributor networks to defend margin position against real estate developer pricing pressure.
- Plastic Films:Food packaging and agricultural greenhouse films drive citrate ester demand where migration limits into consumables apply. Japanese processors lead specification switching for export-compliant production.
- Coatings:Waterborne formulation standards in South Korean and Japanese industrial sectors open volume for citrate and adipate esters in adhesive and sealant applications.
- Adhesives:VOC tightening across Japanese construction and electronics assembly creates specification opportunities for lower-toxicity plasticizer systems in pressure-sensitive formulations.
Volume concentrates in Flooring. Steepest expansion trajectory appears in Coatings.
End User:
Customer type segmentation reveals divergent procurement power, with automotive OEMs dictating qualification timelines while construction buyers prioritize spot-market flexibility.
- Automotive:Korean and Japanese OEMs enforce 18-24 month validation cycles for new plasticizer systems, locking in incumbent adipate and sebacate suppliers for dashboard skins, door panels, and interior trim. REACH-aligned export requirements compound specification rigidity.
- Construction:Real estate developers in China's eastern corridor drive aggressive cost management in flooring and waterproofing membranes. Spot market dependence exposes mid-scale compounders to adipic acid supply concentration.
- Consumer Goods:Toys and childcare articles face SAMR GB phthalate restrictions, compelling citrate ester adoption for compliant export production to European supply chains.
- Electronics:Wire and cable sheathing under METI JIS standards mandates trimellitate grades for high-temperature power transmission infrastructure.
Procurement power leader: Automotive. Fastest qualification pressure: Electronics.
Distribution Channel:
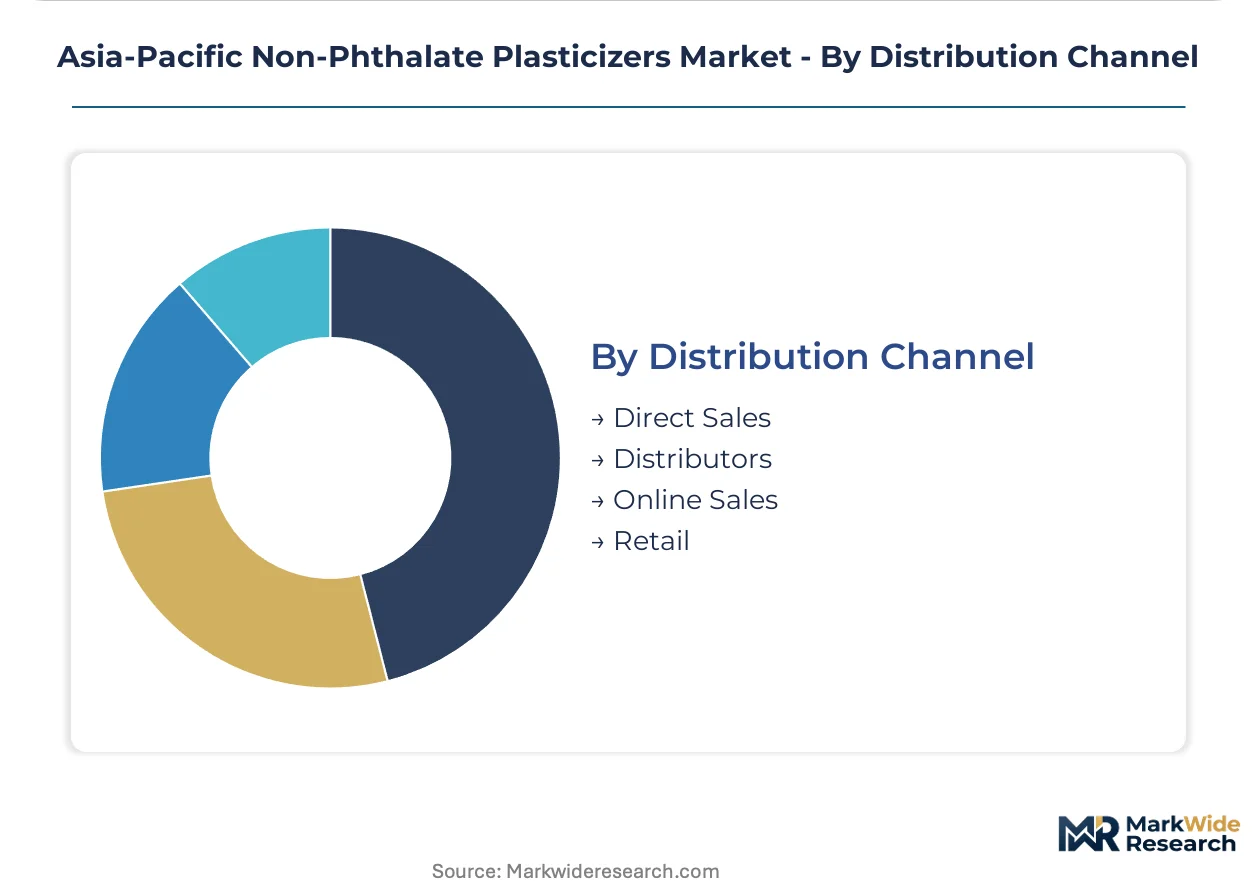
Geography of demand relative to production assets determines channel selection, with proximity to adipic acid sources enabling direct procurement while remote compounders rely on distributor inventory buffers.
- Direct Sales:Large vinyl processors in Shandong and Jiangsu provinces negotiate long-term adipic acid supply contracts, securing volume commitments and price stability unavailable through intermediaries.
- Distributors:Mid-scale compounders across India and Southeast Asia depend on distributor networks for sebacate and citrate specialty grades where minimum order quantities exceed their consumption.
- Online Sales:Technical data sheet access and sample ordering for formulation trials, particularly for trimellitate grades requiring specification documentation for OEM submission.
- Retail:Limited to small-volume maintenance, repair, and operations procurement for industrial processors with intermittent flexible PVC requirements.
Channel concentration: Direct Sales. Emerging flexibility: Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical engineering talent clusters in eastern China and South Korea anchor formulation development for non-phthalate plasticizers across the region. Regulatory divergence between national standards and EU REACH alignment creates compliance complexity that reshapes production geography.
China
Shandong and Jiangsu provinces concentrate flexible PVC compounding for flooring and construction membranes. SAMR enforces GB standards restricting phthalate content in toys and childcare articles, forcing domestic processors toward citrate ester formulations. The eastern manufacturing corridor dominates adipate consumption through direct long-term contracts with adipic acid producers.
South Korea
Automotive OEMs in the Seoul Capital Area specify adipate and sebacate grades for interior vinyl components exposed to cabin heat cycling. MFDS and KOSHA jointly shape occupational exposure limits that push processors toward lower-toxicity plasticizer systems. Korean tier-one suppliers pilot dedicated sebacate blending facilities co-located with OEM assembly plants.
Japan
Wire and cable manufacturers in the Kansai region face mandatory requalification of legacy formulations under revised METI JIS standards. The industrial cable segment responds fastest, with trimellitate grades capturing specification share in power transmission sheathing. Japanese processors lead specification switching for export-compliant food packaging films.
India
BIS alignment with EU REACH restricted substance lists creates compliance complexity for exporters serving European automotive supply chains. Maharashtra and Gujarat host growing vinyl compounding capacity targeting medical-grade PVC and food-contact applications. Castor oil supply dependence exposes sebacate producers to agricultural commodity swings from domestic and Brazilian harvests.
Thailand
Southeast Asian processors running legacy calendering equipment face retrofit costs to handle higher-viscosity non-phthalate grades without throughput loss. Automotive component suppliers in the Eastern Economic Corridor adapt to Korean and Japanese OEM specification switches for dashboard skins and door panels. Waterborne coating formulation standards tighten across industrial sectors, opening volume for citrate and adipate esters.
Asia-Pacific Non-Phthalate Plasticizers Market Competitive Environment
Top-tier vendors anchor integrated adipic acid production, while mid-scale compounders depend on distributor networks for specialty ester supply security. The market structures around three strategic archetypes: petrochemical majors with backward integration into acid chains, regional specialists in high-temperature or bio-based grades, and automotive-focused compounders with OEM qualification lock-in. Dominant competitive moves include direct long-term supply contracts bypassing traditional distribution, and co-location of blending facilities with OEM assembly plants to reduce freight exposure.
Within the integrated petrochemical tier, BASF SE and LG Chem exemplify producers controlling captive adipic acid supply. Eastman Chemical Company occupies a position among trimellitate specialists serving high-temperature wire and cable applications. UPC Technology Corporation represents the regional compounder archetype with proximity to Taiwanese electronics manufacturing clusters.
| Leading Market Players |
|---|
| UPC Technology Corporation |
| NAN YA PLASTICS CORPORATION |
| LG Chem |
| BASF SE |
| Eastman Chemical Company |
| Evonik Industries AG |
| DIC Corporation |
| Kao Corporation |
| Aekyung Chemical |
| Others |
Value Chain & Pricing Dynamics
Specialized chemical engineering talent clusters in eastern China and South Korea anchor formulation development cost structures, with labor-cost differentials between these hubs and Southeast Asian compounding centers widening pricing-tier spreads across adipate, trimellitate, and citrate ester grades. This workforce geography concentrates premium pricing power among integrated producers while compressing margins for distributors serving price-sensitive construction buyers.
Pricing Analysis
Bundled long-term supply contracts dominate pricing for large vinyl processors, while unbundled spot-market transactions serve mid-scale compounders lacking volume scale. Three-tier pricing structure across premium bio-based sebacates, standard adipates, and economy-grade citrates reflects certification intensity and automotive OEM qualification status. Cost compression in flooring-grade adipates is intensifying because real estate developers in China's eastern corridor demand aggressive input cost management. Construction buyers exhibit highest price sensitivity, while medical-grade PVC compounders accept premium positioning for regulatory compliance.
Supply Chain Analysis
Reverse-logistics flows for castor oil derivatives remain underdeveloped, exposing sebacate producers to harvest volatility without buffer stock recovery mechanisms. Supply concentrates in China, South Korea, and India, with adipic acid chains anchored in Shandong province and Korean petrochemical complexes. Raw material dependencies rest on castor bean harvests from India and Brazil, adipic acid from cyclohexane oxidation, and trimellitic anhydride from xylene oxidation. Single-source vulnerability in integrated adipic acid production creates supply security risks for non-integrated compounders. Distribution runs through direct long-term contracts for large processors and regional distributor networks for specialty ester grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through premium-tier shifts toward medical-grade citrate formulations, justified by tightening SAMR GB standards and EU REACH alignment that compounders can monetize through certification-driven pricing power.
For Market Incumbents: Deploy backward integration into adipic acid production to secure cost leadership against Korean and Chinese petrochemical majors threatening volume share. Incumbents should consolidate procurement relationships with Shandong and Jiangsu flooring compounders through multi-year offtake agreements, locking in volume against emerging sebacate alternatives while investing in trimellitate capacity for Japanese wire and cable requalification cycles. For New Entrants and Emerging Players: Mid-scale Indian exporters to European automotive supply chains represent an underserved buyer archetype struggling with BIS-REACH compliance complexity. New entrants should establish sebacate blending facilities in Maharashtra or Gujarat to capture castor oil proximity, offering bundled regulatory documentation services that incumbent petrochemical majors underinvest in. Waterborne coatings transition in Thailand and Vietnam presents additional white-space for citrate and adipate ester formulations. For Investors and Strategic Acquirers: Specialty chemical divisions of diversified industrial conglomerates are the most active acquirers in this space, seeking trimellitate and citrate capabilities to complete non-phthalate portfolios. Long-term viability hinges on regulatory divergence persisting between national standards and EU REACH alignment, creating sustained formulation-switching demand. Investors should monitor BIS notification timelines and ASEAN harmonization framework developments as inflection indicators for Indian export-oriented capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adipic Acid | BASF SE and LG Chem demonstrate how captive acid supply secures cost leadership in high-volume flooring grades. |
| Co-located Sebacate Blending Facilities | Korean tier-one suppliers reduce freight exposure by positioning production adjacent to Seoul Capital Area OEM assembly plants. |
| Medical-Grade Citrate Specialization | SAMR GB enforcement and EU REACH alignment position premium esters for blood bag and food-contact film applications. |
| Direct Long-Term Supply Contracts | Shandong and Jiangsu compounders bypass distributor networks to defend margin position against real estate developer pricing pressure. |
| Waterborne Coatings Formulation Transition | Japanese and South Korean VOC tightening opens volume for citrate and adipate esters in adhesive and sealant applications. |
Study Parameters
Coverage spans China, South Korea, Japan, India, and Thailand, with primary inputs from each market's vinyl compounding clusters. The study combines interviews with plant managers at adipic acid producers, procurement leads at Korean automotive OEMs, distribution channel partners serving Southeast Asian processors, and technical R&D directors at citrate ester specialists. Secondary validation draws from customs and trade data, SAMR GB standard filings, METI JIS revision notices, and SEC 10-K disclosures from listed chemical producers. Bottom-up volume modeling and top-down value triangulation cross-validate segment-level outputs.
Granularity-level modeling disaggregates the market by product type (adipate, trimellitate, citrate, sebacate), application (flooring, plastic films, coatings, adhesives), end user (automotive, construction, consumer goods, electronics), and distribution channel (direct sales, distributors, online sales). CAGRs across the analysis window derive from regression-based demand forecasting anchored to automotive production schedules, construction activity indices, and regulatory implementation timelines. Industry-specific inputs include castor oil harvest forecasts from Indian and Brazilian agricultural sources, adipic acid capacity utilization rates from major producers, and OEM plasticizer requalification cycle durations.
Underlying measurement precision varies by segment; automotive and electronics applications carry tighter precision than construction and consumer goods due to more transparent OEM specification data. Forecasts reflect assumptions about regulatory implementation pace, raw material supply stability, and substitution elasticity between phthalate and non-phthalate systems. Practitioners should monitor BIS notification progress, ASEAN harmonization framework negotiations, and castor oil harvest reports for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
North America Construction Chemicals Market
Chemicals
South America Construction Chemicals Market
Chemicals
Caustic Soda Market
Chemicals
Fluoroantimonic Acid Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
South Korea Methanol Market
Chemicals
Hydrogen Chloride Market
Chemicals
Global Thiophene Market
Chemicals
Gas Sweetening Chemicals Market
Chemicals
North America Oxo-Alcohol Market
Chemicals
Hexamine Market
Chemicals
Periodic Acid Market
Chemicals
Malic Acid Market
Chemicals
Global Glycine Market
Chemicals
Fluorochemicals Market
Chemicals
Methoprene Market