
 4-Dichlorodiphenyl Sulfone (DCDPS) Market | 2026-2036
4-Dichlorodiphenyl Sulfone (DCDPS) Market Size, Share, and Industry Trends Forecast 2026-2036
4-Dichlorodiphenyl Sulfone (DCDPS) Market Outlook
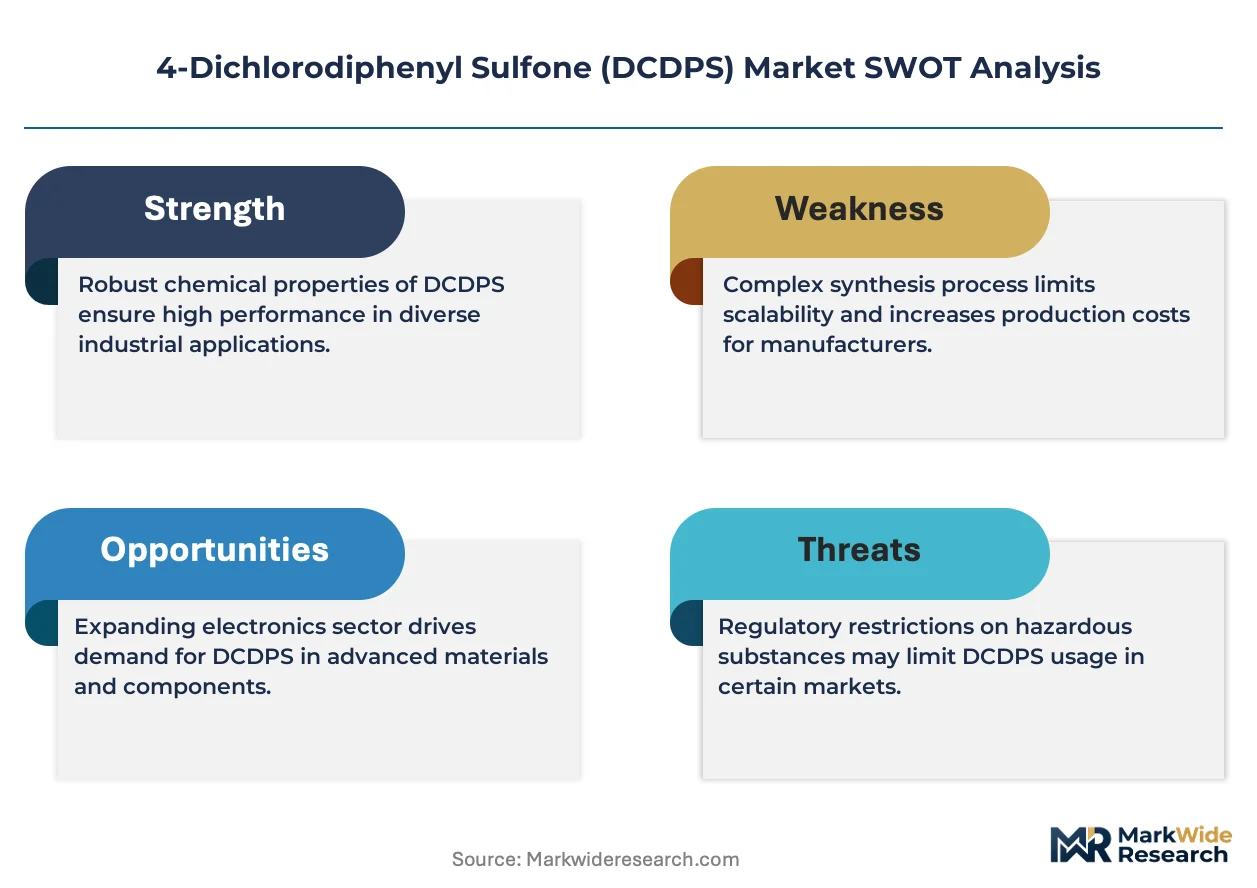
The capital-intensity divergence between integrated producers and merchant manufacturers is unwinding competitive stability in DCDPS supply. Solvay S.A. leverages its backward integration into phenol and sulfur chemistry to sustain margin resilience across European polymer value chains. Atul Ltd. anchors its position through dedicated chlorination infrastructure on India's west coast. Vertellus Holdings LLC differentiates via specialized sulfone derivative portfolios serving North American electronics and coatings customers.
4-Dichlorodiphenyl Sulfone (DCDPS) is a chlorinated aromatic sulfone compound with the molecular formula C12H8Cl2O2S, manufactured through electrophilic substitution of diphenyl sulfone with chlorine gas under Lewis acid catalysis, serving primarily as a monomeric building block for polyarylether sulfone thermoplastics and as an intermediate for agrochemical and pharmaceutical synthesis. Industrial grade material dominates volume throughput due to standardized purity thresholds sufficient for bulk polymerization, while pharmaceutical grade commands premium positioning through stringent residual impurity controls demanded by FDA and EMA drug master file protocols. Polymer production applications absorb the majority of DCDPS offtake, with electronics-grade sulfone resins representing the fastest-expanding demand pool as miniaturization trends intensify dielectric performance requirements.
EPA oversight under TSCA Section 5 governs new chemical introductions in the United States, while REACH registration mandates under ECHA impose comprehensive toxicological dossier requirements for DCDPS importation and manufacture within the European Economic Area. China's MEE enforces GB standard compliance for chlorinated aromatic emissions from sulfone production facilities, elevating capital requirements for regional capacity additions. Stakeholders must monitor evolving per- and polyfluoroalkyl substance substitution dynamics, as sulfone-based polymers gain preference in applications previously served by fluorinated materials facing regulatory restriction.
Market Dynamics
REACH registration mandates under ECHA are tightening purity specifications for imported chemical intermediates, forcing specialty polymer manufacturers to requalify supplier bases and consolidate procurement relationships around certified integrated producers with demonstrated dossier compliance.
Growth Catalysts
- Electronics-grade sulfone resin demand:Miniaturization trends in semiconductor packaging are intensifying dielectric performance requirements for polyarylether sulfone thermoplastics.
- Per- and polyfluoroalkyl substance substitution:Regulatory restrictions on fluorinated materials under EPA TSCA Section 5 are redirecting coating and membrane applications toward sulfone-based alternatives.
- Yangtze River Delta concentration:China's chemical manufacturing corridor is absorbing capacity expansion for chlorinated aromatic intermediates serving regional polymer value chains.
Market Restraints
- Phenol and sulfur input volatility:Backward-integrated producers maintain cost advantages during feedstock price swings that strain merchant manufacturers without captive chlorination infrastructure.
- Capital intensity divergence:Electrolytic chlorination and Lewis acid catalysis systems require substantial fixed investment, creating barriers for new entrants against established European and Indian producers.
- Fluoropolymer residual preference:High-performance applications in aerospace and medical devices retain incumbent fluorinated materials where sulfone alternatives have not yet achieved full thermal stability parity.
Strategic Opportunities
- Pharmaceutical-grade certification:FDA and EMA drug master file protocols for residual impurity controls create premium positioning for producers with validated quality systems.
- Agrochemical intermediate diversification:Sulfone chemistry applications in crop protection synthesis remain underdeveloped relative to polymer markets, offering expansion vectors.
- GB standard compliance services:China's MEE emissions enforcement creates advisory and technology licensing revenue streams for producers with demonstrated environmental management capabilities.
Industry Challenges
- Electrophilic substitution process control:Maintaining consistent chlorination selectivity for diphenyl sulfone requires specialized chemical engineering expertise that concentrates among aging technical workforces in Western Europe and Japan.
- REACH dossier maintenance burden:ECHA toxicological data requirements demand ongoing investment in analytical capabilities and regulatory affairs staffing that diverts resources from commercial development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4-Dichlorodiphenyl Sulfone (DCDPS) Market |
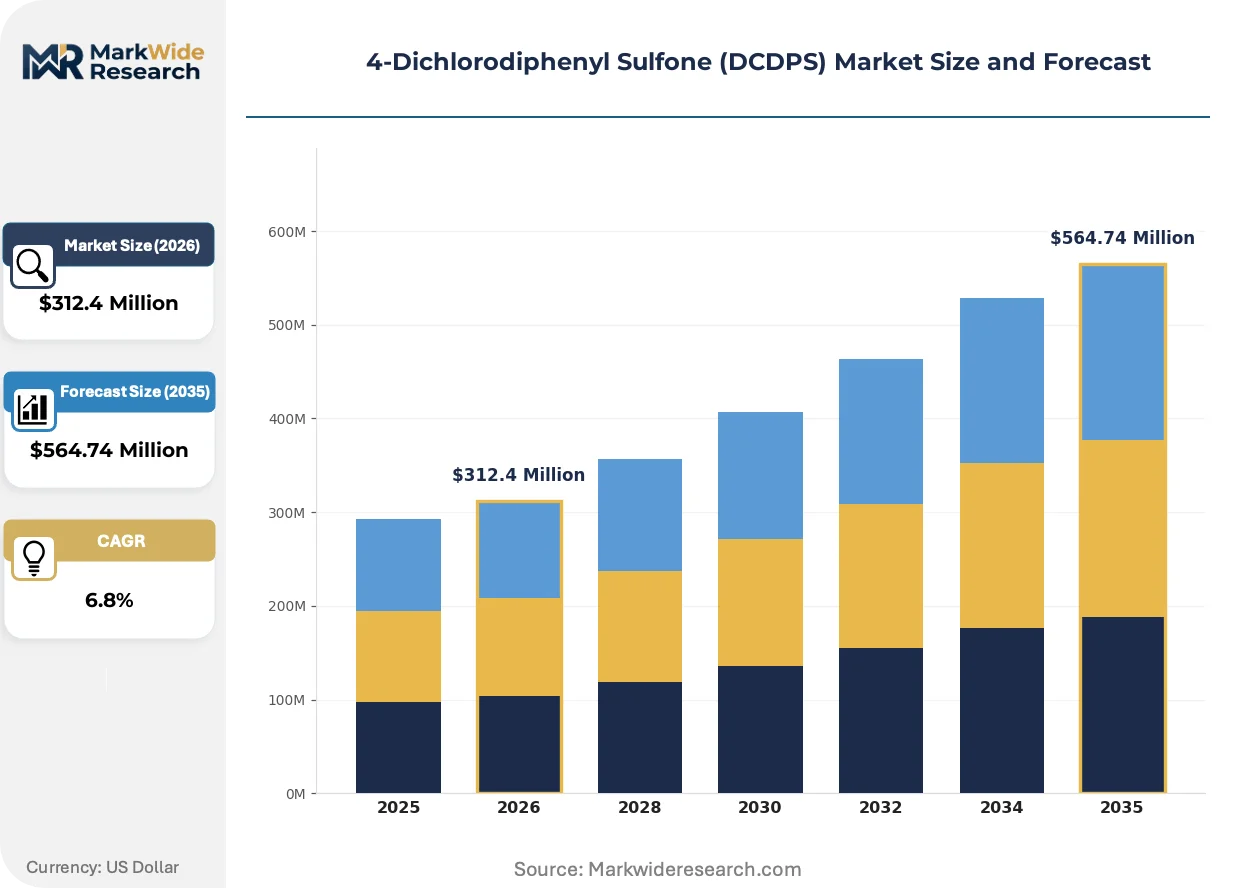
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Research Grade, Pharmaceutical Grade, Technical Grade Application: Polymer Production, Coatings, Agrochemicals, Electronics End User: Chemical Manufacturers, Pharmaceutical Companies, Material Science Researchers, Electronics Manufacturers Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail |
| Companies Covered | Solvay S.A., Atul Ltd., Aarti Industries Ltd., Vertellus Holdings LLC, Toray Industries, Inc., BASF SE, Banchem Intermediates, Nantong VolantChem Corp., Jiujiang Zhongxing Medicine Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4-Dichlorodiphenyl Sulfone (DCDPS) Market Strategic Shifts
Process intensification and regulatory substitution dynamics are actively reshaping competitive positioning in chlorinated aromatic sulfone manufacturing. Three developments warrant particular attention.
Continuous-flow chlorination reactors are replacing batch electrophilic substitution systems in newer production facilities. Specialty polymer manufacturers in Germany and Japan are adopting these intensified processes to reduce solvent inventory and improve heat transfer control. This equipment transition is miniaturizing plant footprints while enabling tighter purity specifications for electronics-grade material.
EU F-Gas Regulation phase-down schedules are accelerating material substitution timelines for membrane and coating applications previously dependent on fluorinated polymers. Industrial gas separation and water treatment equipment OEMs are requalifying sulfone-based alternatives to maintain product certification. German automotive suppliers and French aerospace subcontractors represent the most advanced adoption segments, with technical validation programs compressing from historical 36-month cycles toward 18-month windows.
Consolidated procurement desks at major polyarylether sulfone resin producers are reducing qualified supplier lists from historical 6-8 vendors toward 3-4 strategic partnerships. This concentration behavior favors integrated producers with demonstrated REACH compliance and multi-year volume commitments. The Yangtze River Delta and India's west coast chemical corridors are experiencing the most visible supplier base compression, with merchant manufacturers facing exclusion from approved vendor lists.
4-Dichlorodiphenyl Sulfone (DCDPS) Market Segmentation
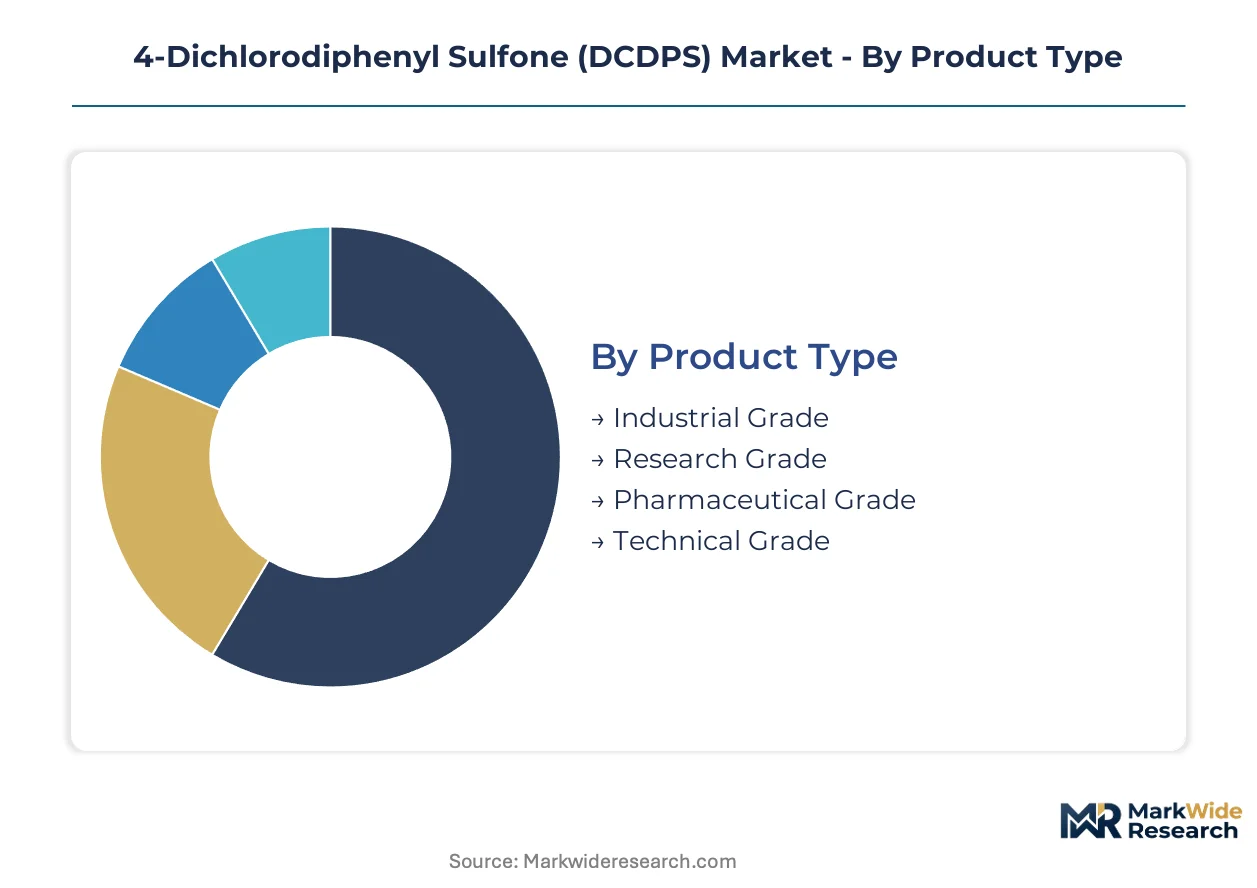
DCDPS procurement patterns diverge sharply across purity grades and application verticals, with electronics-grade specifications commanding substantial premiums over bulk polymer feedstock. Specialty polymer manufacturers in Germany and pharmaceutical formulators in Switzerland are driving qualification requirements that reshape supplier economics.
Product Type:
Margin pools concentrate in validated pharmaceutical-grade material where FDA and EMA drug master file protocols impose residual impurity controls that exclude commodity producers.
- Industrial Grade:Standardized purity thresholds sufficient for bulk polyarylether sulfone polymerization dominate volume throughput. Chinese chemical manufacturers in the Yangtze River Delta absorb the majority of this segment's offtake for regional polymer value chains.
- Pharmaceutical Grade:Stringent residual impurity controls demanded by FDA and EMA drug master file protocols create premium positioning. Specialty producers with validated quality systems capture disproportionate returns as agrochemical and drug synthesis applications expand.
- Research Grade:Small-batch specifications serve material science laboratories and pilot-scale polymer development.
- Technical Grade:Intermediate purity tier bridges industrial and specialized applications with flexible specification windows.
Industrial grade holds installed capacity. Pharmaceutical grade is rotating up the share rankings.
Application:
Cost tier stratification separates electronics-grade dielectric resins from commodity coating formulations, with capital requirements for cleanroom manufacturing concentrating supply among integrated sulfone producers.
- Polymer Production:Polyarylether sulfone thermoplastics absorb the majority of DCDPS offtake as monomeric building blocks. German automotive suppliers and French aerospace subcontractors are compressing technical validation cycles for sulfone-based alternatives to fluorinated materials.
- Electronics:Semiconductor packaging miniaturization intensifies dielectric performance requirements, with miniaturization trends accelerating qualification timelines. Electronics-grade sulfone resins are climbing the fastest as dielectric specifications tighten.
- Coatings:Industrial membrane and protective layer applications redirect from fluorinated polymers under regulatory restriction.
- Agrochemicals:Crop protection synthesis intermediates remain underdeveloped relative to polymer markets.
Polymer production anchors volume scale. Electronics is gaining share fastest.
End User:
Customer type determines procurement modality, with chemical manufacturers consolidating supplier lists while pharmaceutical companies demand dedicated batch documentation.
- Chemical Manufacturers:Integrated polyarylether sulfone resin producers operate consolidated procurement desks, reducing qualified vendor lists from historical 6-8 suppliers toward 3-4 strategic partnerships.
- Pharmaceutical Companies:Drug master file protocols require validated impurity profiling and multi-year stability data.
- Material Science Researchers:Academic and corporate R&D facilities purchase small quantities with flexible lead times.
- Electronics Manufacturers:Semiconductor packaging OEMs impose electronics-grade specifications with tight purity windows.
Chemical manufacturers hold contracted volume. Pharmaceutical companies are rotating up the share rankings.
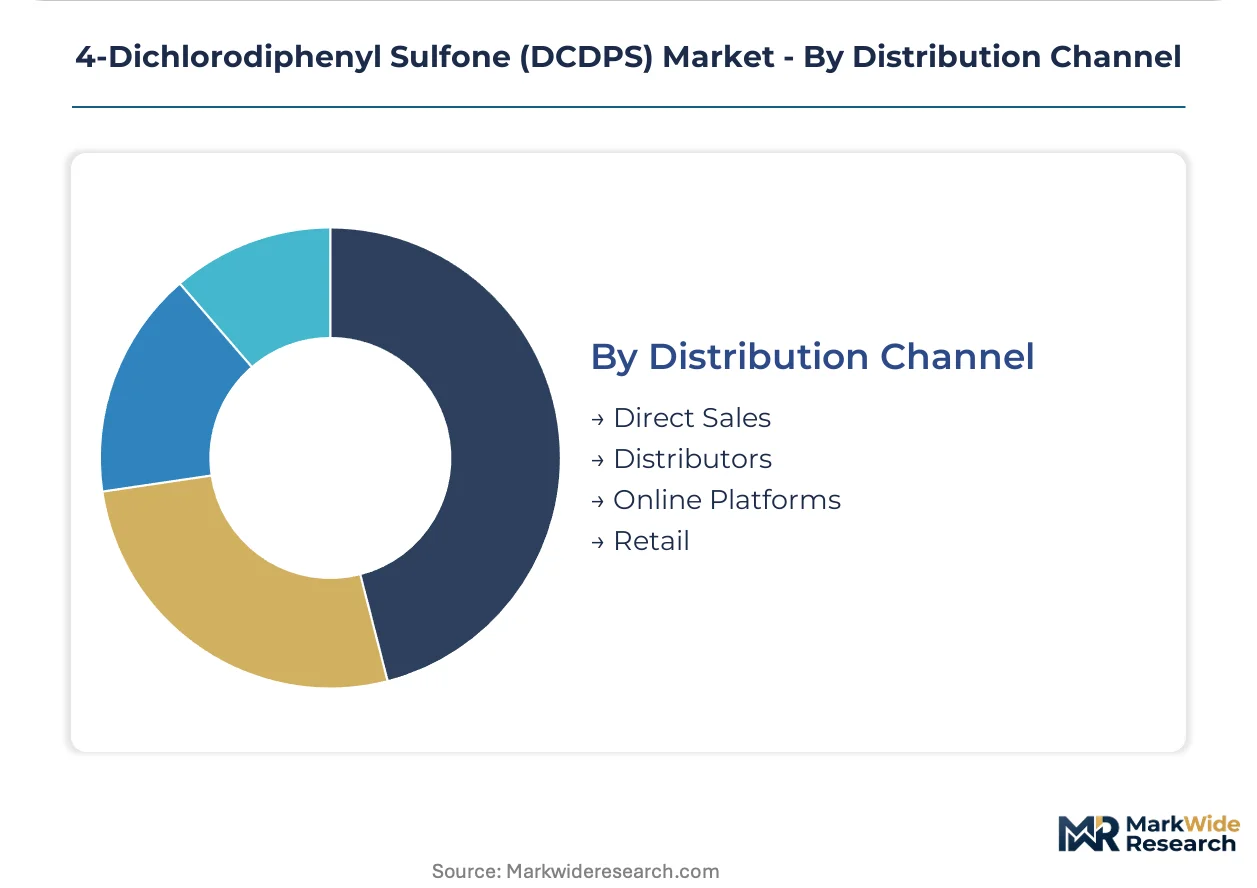
Distribution Channel:
Supply concentration favors direct relationships for bulk polymer feedstock, while fragmented research-grade demand sustains distributor networks.
- Direct Sales:Multi-year volume commitments between integrated DCDPS producers and specialty polymer manufacturers dominate industrial-grade procurement.
- Distributors:Regional chemical distributors serve mid-tier coating formulators and agrochemical synthesizers with smaller batch requirements.
- Online Platforms:Research-grade and technical-grade material moves through specialized chemical marketplaces serving laboratories.
- Retail:Minimal presence limited to small-quantity laboratory reagents.
Direct sales holds contracted volume. Distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry separates German specialty polymer manufacturers from Yangtze River Delta commodity producers, with REACH compliance costs embedding structural premiums into European material. This divergence concentrates procurement relationships around certified integrated suppliers with demonstrated dossier capabilities.
China
Electronics-grade sulfone resin demand from semiconductor packaging OEMs drives procurement intensity in the Yangtze River Delta chemical corridor. MEE enforcement of GB standards for chlorinated aromatic emissions elevates capital requirements for regional capacity additions. Nantong and Shanghai absorb the majority of industrial-grade DCDPS offtake for regional polyarylether sulfone value chains.
Germany
Automotive suppliers and aerospace subcontractors compress technical validation cycles for sulfone-based fluoropolymer alternatives. ECHA REACH registration mandates tighten purity specifications for imported chemical intermediates, forcing requalification of supplier bases. The North Rhine-Westphalia chemical cluster hosts specialty polymer manufacturers expanding DCDPS procurement for high-performance thermoplastics.
United States
Industrial gas separation and water treatment equipment OEMs requalify sulfone-based membranes under EPA TSCA Section 5 oversight of fluorinated material restrictions. FDA drug master file protocols for pharmaceutical-grade material create premium positioning for validated producers. The Gulf Coast petrochemical corridor sustains merchant manufacturer competition through access to phenol and sulfur feedstock networks.
India
Agrochemical intermediate diversification opportunities attract investment from crop protection synthesis formulators seeking sulfone chemistry applications. CDSCO alignment with international drug master file standards elevates documentation requirements for pharmaceutical-grade exports. Gujarat's west coast chemical corridor anchors dedicated chlorination infrastructure serving domestic and export polymer markets.
Japan
Miniaturization trends in semiconductor packaging intensify dielectric performance requirements for electronics-grade sulfone resins. METI industrial policy supports domestic specialty chemical production against import dependency. The Chubu region around Nagoya maintains concentrated technical expertise in electrophilic substitution process control for chlorinated aromatic manufacturing.
4-Dichlorodiphenyl Sulfone (DCDPS) Market Competitive Environment
Concentration sits with integrated producers possessing backward integration into phenol and sulfur chemistry, while merchant manufacturers face margin compression from feedstock volatility. Three archetypes dominate: European chemical conglomerates with captive chlorination infrastructure, Indian specialty chemical houses with dedicated sulfone derivative capabilities, and Chinese regional producers serving Yangtze River Delta polymer clusters. Competitive moves center on REACH dossier maintenance investments and continuous-flow reactor technology licensing.
Within the integrated producer tier, Solvay S.A. and BASF SE exemplify European archetypes leveraging upstream chemical control, while Atul Ltd. represents Indian positioning through geographic concentration on the west coast. Vertellus Holdings LLC occupies a specialized position in North American electronics and coatings derivative portfolios. These three names anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Solvay S.A. |
| Atul Ltd. |
| Aarti Industries Ltd. |
| Vertellus Holdings LLC |
| Toray Industries, Inc. |
| BASF SE |
| Banchem Intermediates |
| Nantong VolantChem Corp. |
| Jiujiang Zhongxing Medicine Chemical Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between integrated DCDPS producers and German specialty polymer manufacturers lock in multi-year volume commitments while anchoring price visibility against phenol and sulfur feedstock swings. These arrangements concentrate procurement power among REACH-certified suppliers with demonstrated dossier compliance, embedding structural premiums into European material relative to Yangtze River Delta commodity grades.
Pricing Analysis
The customization-premium spread between electronics-grade specifications and industrial-grade bulk material runs wide, with FDA and EMA drug master file protocols adding certification-driven tiers atop purity-based differentiation. Contract-based long-term offtake dominates volume procurement, while spot transactions serve research-grade and technical-tier buyers with flexible lead times. Price differentiation hinges on REACH dossier completeness and cleanroom manufacturing capability, with merchant manufacturers facing cost compression from phenol volatility that backward-integrated rivals absorb. Specialty polymer manufacturers in Germany and semiconductor packaging OEMs in Japan show least price sensitivity; coating formulators and agrochemical synthesizers concentrate bargaining power in volume negotiations.
Supply Chain Analysis
Inventory cycles and lead-time compression favor producers with continuous-flow chlorination reactors over legacy batch systems, tightening just-in-time delivery windows for electronics-grade material. Supply concentrates in China, Germany, and India, with the Yangtze River Delta and Gujarat's west coast anchoring chlorinated aromatic capacity. Feedstock dependencies rest on phenol, sulfur, and chlorine gas networks, with electrolytic chlorination infrastructure creating captive supply advantages. Single-source vulnerability runs through REACH-registered European suppliers for pharmaceutical-grade certification. Distribution runs through direct sales for industrial-grade polymer feedstock, while regional chemical distributors serve mid-tier coating and agrochemical customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as REACH compliance costs and electronics-grade qualification requirements split demand into certifiable and commodity tiers, creating defendable niches for specialists with validated quality systems.
For Market Incumbents: Fortify dossier maintenance investments and continuous-flow reactor licensing to defend against emerging Chinese producers with cost-advantaged commodity capacity. Backward integration into phenol chemistry remains essential for margin resilience during feedstock volatility. Prioritize multi-year partnerships with consolidating German automotive suppliers compressing technical validation cycles. For New Entrants and Emerging Players: Pharmaceutical-grade batch documentation services represent a service-layer gap where incumbents under-serve mid-tier agrochemical formulators seeking CDSCO-aligned export capabilities. Target India's crop protection synthesis corridor with toll-manufacturing partnerships leveraging existing chlorination infrastructure. Lead with regulatory advisory offerings rather than commodity volume plays. For Investors and Strategic Acquirers: Capital is best deployed toward integrated mid-cap specialists with captive sulfone derivative portfolios and demonstrated EMA/FDA master file capabilities. Long-term viability over a multi-year horizon favors producers with both polymer and pharmaceutical end-market optionality. Watch for EU F-Gas Regulation phase-down acceleration as inflection signal for sulfone-based fluoropolymer substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Chemistry | Solvay S.A. and BASF SE anchor margin resilience through captive feedstock control against merchant competitors. |
| Continuous-Flow Reactor Technology Licensing | Specialty polymer manufacturers in Germany and Japan adopt intensified processes to miniaturize plant footprints. |
| REACH Dossier Maintenance Investment | ECHA toxicological data requirements concentrate procurement relationships around certified integrated producers. |
| Pharmaceutical-Grade Certification Pathway | FDA and EMA drug master file protocols create premium positioning for validated quality systems. |
| Long-term Supply Agreement with Electronics OEMs | Semiconductor packaging manufacturers compress qualification timelines for dielectric-grade sulfone resins. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with specialty polymer procurement directors, chlorinated aromatic plant managers, pharmaceutical regulatory affairs leads, and agrochemical synthesis formulators. Secondary validation drew from ECHA REACH registration databases, FDA drug master file listings, customs trade data for diphenyl sulfone derivatives, and SEC filings from integrated chemical producers. Bottom-up volume estimates triangulated against top-down polymer consumption models.
Across the analysis window, the forecasting framework modeled grade-tier segmentation, end-use industry splits, and regional production hub dynamics. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Key inputs included semiconductor packaging miniaturization rates, EU F-Gas Regulation substitution timelines, and MEE GB standard compliance costs for Chinese capacity additions.
Forecasts assume regulatory continuity in REACH, EPA TSCA Section 5, and CDSCO alignment regimes; material policy shifts would require re-modeling. Phenol price volatility, fluoropolymer residual preference in aerospace applications, and REACH dossier maintenance burden concentration represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Dimethyl Phosphate Market
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Anhydrous Hydrogen Fluoride Market
Chemicals
Ethylenediaminetetraacetic Acid Market
Chemicals
1-Methylimidazole Market
Chemicals
Carbon Tetrachloride Market
Chemicals
Fireworks Market
Chemicals
Guanidine Carbonate Market
Chemicals
Nonaisoprenol Market
Chemicals
Chloroplatinic Acid Market
Chemicals
China Amines Market
Chemicals
Triisopropanolamine (TIPA) Market
Chemicals
Zinc Chemicals Market
Chemicals
Household Insecticides Market
Chemicals
Chemical Distribution Market
Chemicals
Paint Remover Market