
 3-Fluoro-5-Nitrotoluene Market | 2026-2036
3-Fluoro-5-Nitrotoluene Market Size, Share, and Industry Trends Forecast 2026-2036
3-Fluoro-5-Nitrotoluene Market Analysis
Chlorobenzene derivatives is rebalancing cost structures across fluorinated intermediate supply chains as manufacturers seek lower-halogen alternatives. Aarti Industries Limited leverages its integrated nitroaromatics platform to serve pharmaceutical and agrochemical offtake from South Asia. Zhejiang Yongtai Technology Co., Ltd. anchors fluorination capacity in East China, sustaining captive feedstock advantages for downstream toluidine derivatives. BASF SE competes through reagent-grade specialization, controlling distribution networks for European pharmaceutical research institutions.
3-Fluoro-5-nitrotoluene is a fluorinated nitroaromatic compound with the molecular formula C7H6FNO2, typically synthesized through selective nitration of 3-fluorotoluene under controlled temperature conditions to preserve regioselectivity. The compound functions primarily as a building block for pharmaceutical active ingredients, agrochemical intermediates, and specialty dye precursors requiring electron-deficient aromatic substitution patterns. Pharmaceutical applications dominate value capture due to stringent purity requirements and long-term supply agreements with drug substance manufacturers. Reagent-grade intermediates represent the fastest-expanding segment as contract research organizations escalate fluorinated scaffold procurement for candidate molecule libraries.
EPA standards govern nitroaromatic emissions and worker exposure limits at U.S. import and formulation facilities, while REACH registration requirements in Europe mandate comprehensive toxicity dossiers for fluorinated toluene derivatives above one-tonne annual thresholds. China's MEE enforces wastewater discharge standards that elevate capital requirements for nitration operations in Jiangsu and Zhejiang provinces, compressing marginal producer economics. Stakeholders must monitor regulatory divergence between OECD-aligned hazard classifications and emerging GB standard revisions to anticipate compliance cost reallocations across supply nodes.
Market Dynamics
Integrated fluoro-benzene production clusters in East China are compressing marginal producer economics elsewhere, as captive nitration and fluorination capabilities allow dominant suppliers to internalize cost advantages across the value chain.
Growth Catalysts
- Pharmaceutical API demand:Contract drug substance manufacturers in India and China are expanding fluorinated aromatic procurement for oncology and antiviral candidate synthesis.
- REACH registration thresholds:European importers above one-tonne annual volumes must file comprehensive toxicity dossiers, favoring established suppliers with existing compliance infrastructure.
- Agrochemical intermediate pipelines:Herbicide and fungicide innovators require electron-deficient aromatic scaffolds for next-generation active ingredient development.
Market Restraints
- Feedstock volatility:Toluene and hydrogen fluoride pricing swings directly compress nitration operation margins for non-integrated producers.
- Jiangsu-Zhejiang supply concentration:Over 60% of global fluorinated nitroaromatic capacity sits within 300 kilometers in East China, creating single-point vulnerability.
- Regulatory friction:Divergent hazard classifications between OECD-aligned frameworks and China's evolving GB standards force dual compliance investments.
Strategic Opportunities
- Reagent-grade specialization:European and North American contract research organizations are escalating fluorinated scaffold procurement for high-throughput screening libraries.
- India's PLI scheme:Production-linked incentives for active pharmaceutical ingredients are attracting backward integration investments into nitroaromatic intermediates.
- Continuous flow nitration:Microreactor technology convergence with automated process control is enabling smaller-batch, higher-purity production for specialty applications.
Industry Challenges
- Fluorination specialist scarcity:Selective electrophilic aromatic substitution expertise remains concentrated among aging technical workforces in legacy chemical manufacturing regions.
- MEE wastewater compliance:China's Ministry of Ecology and Environment discharge standards for nitration effluents require capital-intensive treatment infrastructure upgrades.
- IP fragmentation:Process patents covering regioselective nitration of fluorotoluene isomers create licensing complexity for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3-Fluoro-5-Nitrotoluene Market |
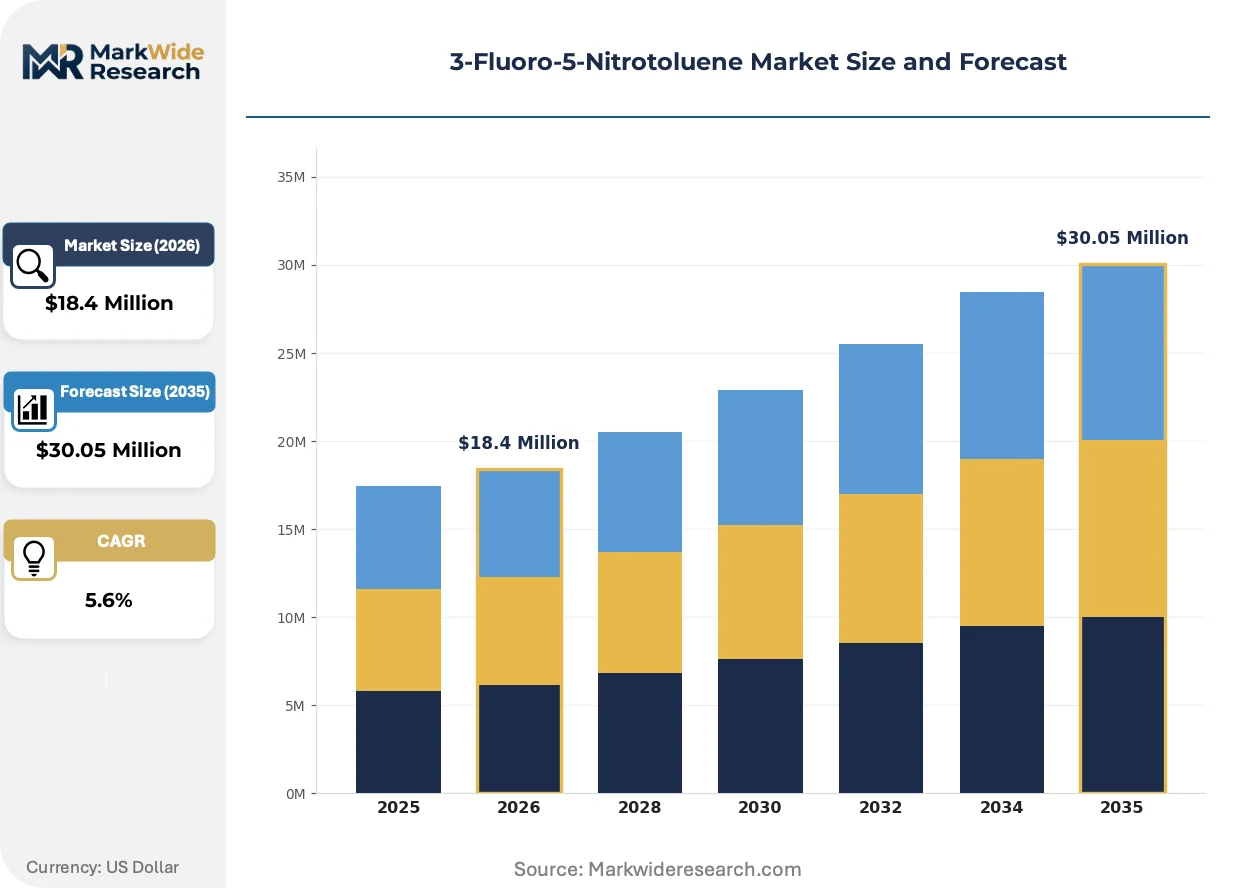
| Market Size in 2026 | $18.4 Million |
| Market Size in 2035 | $30.05 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Intermediates, Reactants, Additives Application: Dyes, Pharmaceuticals, Agrochemicals, Coatings End User: Chemical Industry, Pharmaceutical Manufacturers, Agricultural Sector, Research Institutions Grade: Industrial Grade, Reagent Grade, Analysis Grade, Cosmetic Grade |
| Companies Covered | Aarti Industries Limited, Zhejiang Yongtai Technology Co., Ltd., Ginte Material Industry, Bosche, Toronto Research Chemicals, Accela, Hanhong Scientific, Lanxess AG, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3-Fluoro-5-Nitrotoluene Market Emerging Trajectories
Fluorination chemistry and regulatory compliance frameworks are converging to reshape how nitroaromatic intermediates are manufactured, certified, and procured across pharmaceutical and agrochemical value chains.
Continuous flow microreactor technology is unifying temperature control and mixing precision for selective nitration of fluorotoluene feedstocks. Mid-scale pharmaceutical intermediate manufacturers in Germany and Switzerland are adopting these systems to reduce thermal runaway risks and improve batch-to-batch consistency. The technology is unifying quality assurance protocols across contract manufacturing organizations, compressing validation timelines for reagent-grade supply agreements.
REACH's updated requirements for Substances of Very High Concern are tightening documentation obligations for fluorinated toluene derivatives imported above threshold volumes. European formulators must now demonstrate supply chain transparency through SCIP database entries, elevating administrative burdens for distributors. Agrochemical blenders in Germany and France are responding by consolidating supplier relationships with REACH-registered producers possessing existing dossier infrastructure.
Long-term offtake contracting is displacing spot-market purchasing for high-purity fluorinated intermediates. Pharmaceutical API manufacturers are locking in three-to-five-year supply agreements with integrated producers to secure volume certainty against regulatory disruption. This pattern is most visible among oncology drug substance specialists in India and China, where backward integration into nitroaromatics remains incomplete.
3-Fluoro-5-Nitrotoluene Market Segmentation
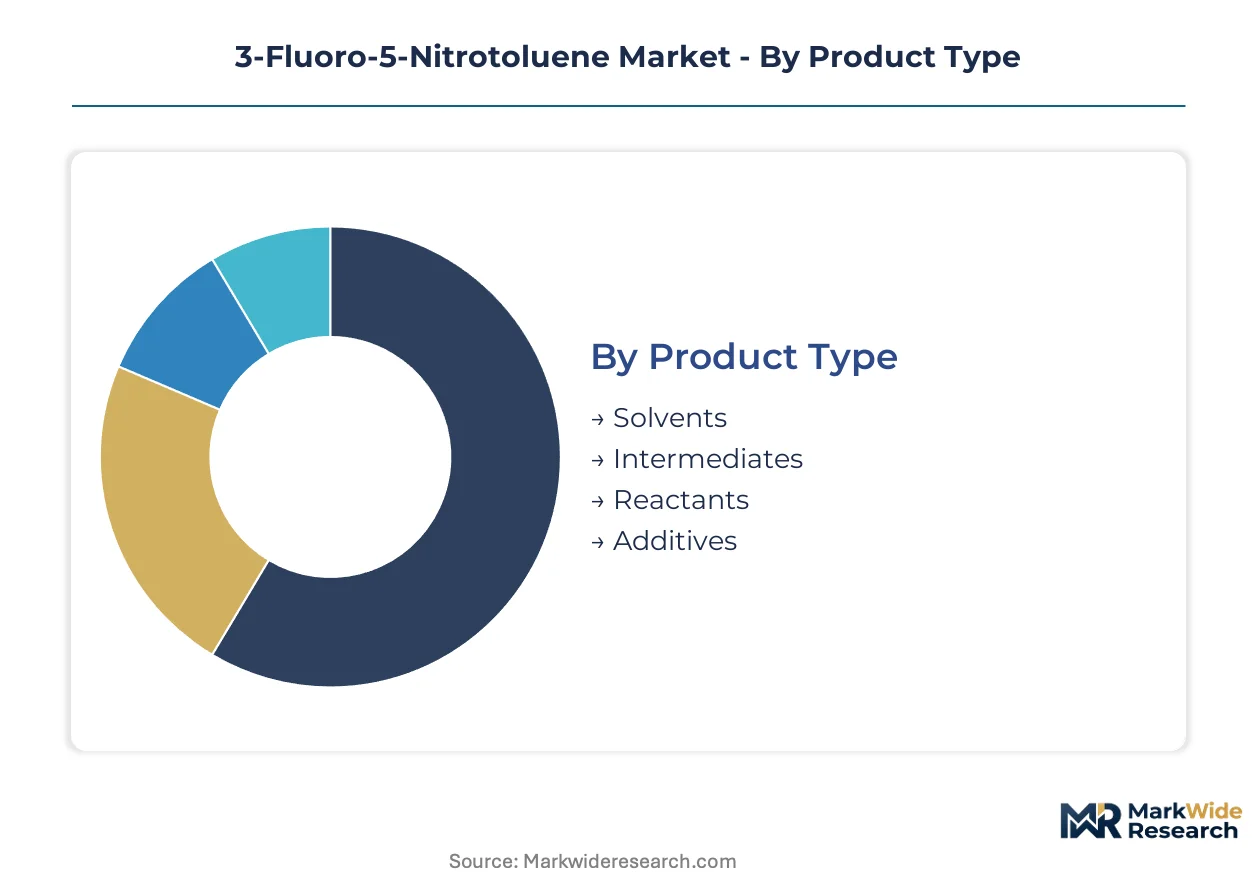
Segmentation of the 3-Fluoro-5-Nitrotoluene market reflects divergent purity specifications, regulatory thresholds, and synthesis scale requirements across pharmaceutical, agrochemical, and specialty chemical value chains. Each category captures distinct procurement patterns, from bulk industrial offtake to gram-scale reagent orders for contract research organizations.
Product Type:
Customization intensity spans from commodity solvents to precision-engineered reactants, with specification tolerance tightening as molecular complexity increases.
- Intermediates:These compounds serve as core building blocks for downstream active pharmaceutical ingredient synthesis, typically supplied at 98-99% purity with batch-specific certificate of analysis. Pharmaceutical manufacturers in India and China dominate procurement volumes, driven by oncology and antiviral pipeline expansion requiring fluorinated aromatic scaffolds.
- Reactants:Electrophilic aromatic substitution reagents with controlled moisture content and defined isomeric ratios enable regioselective transformations in multi-step syntheses. Contract research organizations in Germany and Switzerland are escalating procurement for high-throughput screening libraries, prioritizing lot-to-lot consistency over unit cost.
- Solvents:Process solvents for nitration and fluorination reactions, supplied in bulk drum and tanker quantities.
- Additives:Specialty formulation components for polymer and coating applications requiring nitroaromatic functionalization.
Most installed capacity flows through Intermediates. Expansion is steepest in Reactants.
Application:
Margin structure correlates inversely with production scale, as pharmaceutical applications command purity premiums while agrochemical volumes run on cost-optimized specifications.
- Pharmaceuticals:Active pharmaceutical ingredient precursors for oncology, antiviral, and central nervous system therapeutics, requiring sub-ppm metal content and chiral purity documentation. Drug substance manufacturers in Hyderabad and Shanghai are locking in long-term supply agreements to secure volume certainty against REACH and EPA regulatory disruption.
- Agrochemicals:Herbicide and fungicide intermediates leveraging electron-deficient aromatic substitution patterns for next-generation active ingredient development. Formulators in Jiangsu province concentrate demand, sourcing from integrated fluoro-benzene production clusters to minimize logistics exposure.
- Dyes:Specialty colorant precursors for high-performance pigment synthesis.
- Coatings:Functional additives for corrosion-resistant and UV-stable industrial finishes.
Pharmaceuticals capture the highest value per kilogram. Agrochemicals absorb the greatest absolute tonnage.
End User:
Customer sophistication determines specification stringency, with research institutions demanding maximum analytical documentation and agricultural blenders prioritizing bulk delivery reliability.
- Pharmaceutical Manufacturers:Integrated drug substance producers and contract development manufacturing organizations requiring GMP-aligned supply chains with full regulatory dossier support. CDSCO-registered facilities in India and NMPA-authorized sites in China are consolidating supplier relationships to reduce audit burden.
- Research Institutions:Universities and contract research organizations procuring gram-to-kilogram quantities for candidate molecule library construction. European academic consortia are driving demand for reagent-grade material with comprehensive characterization data packages.
- Chemical Industry:Diversified intermediate processors serving multiple downstream sectors.
- Agricultural Sector:Formulators and blenders integrating nitroaromatics into crop protection product lines.
Pharmaceutical Manufacturers account for the most rigorous qualification protocols. Research Institutions are gaining share fastest.
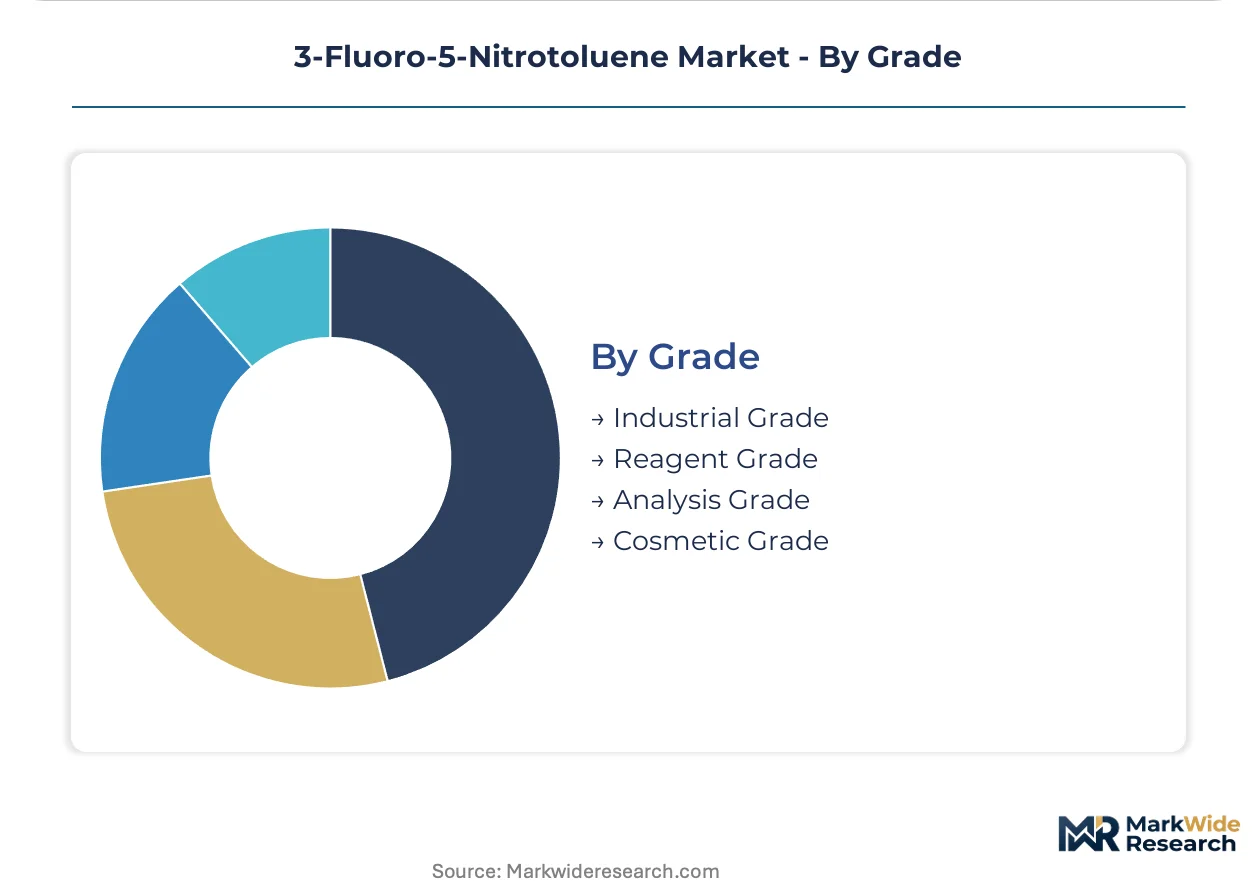
Grade:
Certification tiers separate commodity industrial supply from analytical-grade material, with pricing spreads reflecting documentation depth and impurity profiling investment.
- Reagent Grade:Material meeting ACS or comparable specifications for synthetic chemistry applications, with comprehensive COA including NMR, GC-MS, and HPLC purity verification. Contract research organizations in Basel and Boston are standardizing procurement on this tier to streamline regulatory submissions.
- Industrial Grade:Bulk quantities for agrochemical and dye intermediate production, with standardized purity thresholds and simplified documentation. Integrated producers in East China leverage captive nitration capacity to maintain cost position in this segment.
- Analysis Grade:Ultra-high purity material for analytical reference standard and quality control applications.
- Cosmetic Grade:Specialized material meeting residual solvent and heavy metal limits for personal care ingredient synthesis.
Industrial Grade absorbs the majority of production volume. Reagent Grade is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East China's chemical manufacturing corridor concentrates over sixty percent of global fluorinated nitroaromatic capacity within a three-hundred-kilometer radius, anchoring procurement patterns for pharmaceutical and agrochemical value chains worldwide.
China
Pharmaceutical API manufacturers in Shanghai and agrochemical formulators in Jiangsu province drive concentrated demand for high-purity fluorinated intermediates. MEE wastewater discharge standards for nitration effluents compel capital-intensive treatment infrastructure upgrades across Zhejiang and Jiangsu facilities. The Yangtze River Delta integrated fluoro-benzene production clusters sustain captive feedstock advantages that compress marginal producer economics elsewhere.
India
Contract drug substance manufacturers in Hyderabad and Mumbai escalate procurement of fluorinated aromatic scaffolds for oncology and antiviral candidate synthesis. CDSCO registration requirements and the PLI scheme for active pharmaceutical ingredients attract backward integration investments into nitroaromatic intermediates. Gujarat's specialty chemical corridor hosts expanding nitroaromatic capacity serving both domestic formulation and export markets.
Germany
European pharmaceutical research institutions and agrochemical blenders in the Rhine-Ruhr region sustain demand for reagent-grade fluorinated intermediates. REACH registration thresholds above one-tonne annual volumes mandate comprehensive toxicity dossiers, favoring established suppliers with existing compliance infrastructure. BASF SE's Ludwigshafen operations anchor distribution networks for reagent-grade specialization across European academic consortia.
United States
Contract research organizations in Boston and pharmaceutical manufacturers in New Jersey procure fluorinated scaffolds for high-throughput screening libraries and commercial API production. EPA standards govern nitroaromatic emissions and worker exposure limits at import and formulation facilities, elevating compliance costs for non-registered suppliers. The Gulf Coast petrochemical corridor provides toluene feedstock proximity for limited domestic nitration operations.
Switzerland
Precision chemical manufacturers in Basel and contract research organizations escalate procurement for candidate molecule library construction requiring gram-to-kilogram reagent-grade quantities. Swissmedic oversight and OECD-aligned hazard classification frameworks demand comprehensive analytical documentation packages. The country's pharmaceutical research ecosystem sustains premium pricing for ultra-high-purity fluorinated intermediates with full characterization data.
3-Fluoro-5-Nitrotoluene Market Vendor Landscape
Global majors compete with regional champions across integrated production capabilities and regulatory compliance infrastructure. The vendor base stratifies between scale-driven integrated producers in East China, specialized reagent-grade suppliers in Europe, and emerging contract manufacturers in South Asia. Three archetypes dominate: captive feedstock-integrated chemical conglomerates, reagent-grade specialists serving research institutions, and pharmaceutical-intermediate pure-plays. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing long-term offtake agreements to defend volume positions.
Among Indian specialty chemical producers, Aarti Industries Limited occupies a position exemplifying integrated nitroaromatics platform capabilities. Zhejiang Yongtai Technology Co., Ltd. anchors the East China fluoro-benzene production cluster archetype with apparent captive fluorination capacity. BASF SE represents the European reagent-grade specialization tier, controlling distribution networks for pharmaceutical research institutions. These three entities collectively illustrate the geographic and capability segmentation shaping procurement decisions across pharmaceutical and agrochemical value chains.
| Leading Market Players |
|---|
| Aarti Industries Limited |
| Zhejiang Yongtai Technology Co., Ltd. |
| Ginte Material Industry |
| Bosche |
| Toronto Research Chemicals |
| Accela |
| Hanhong Scientific |
| Lanxess AG |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Hydrogen fluoride feedstock costs cascade through fluorinated nitroaromatic pricing tiers, with captive fluorination capacity in East China compressing delivered prices for industrial-grade material while reagent-grade imports to European pharmaceutical laboratories sustain substantial premiums.
Pricing Analysis
Input-cost pass-through from toluene and hydrogen fluoride volatility structures contract-based long-term offtake as the dominant pricing model for pharmaceutical API manufacturers. Price differentiation hinges on certification grade—REACH-registered suppliers command premiums over industrial-grade exporters—and volume scale, with tonnage commitments securing favorable terms. Pricing pressure stems from Jiangsu-Zhejiang supply concentration compressing margins for non-integrated nitration operators. Agrochemical formulators exhibit highest price sensitivity, while Swiss contract research organizations prioritize lot-to-lot consistency over unit economics.
Supply Chain Analysis
Fluorination specialist scarcity in legacy chemical manufacturing regions constrains capacity expansion outside East China's integrated clusters. Geographic supply concentration centers on China, India, and Germany, with raw material dependencies drawing from toluene refining, hydrogen fluoride production, and nitration catalyst supply. Single-source vulnerability pervades the Jiangsu-Zhejiang corridor where over sixty percent of global capacity resides within three hundred kilometers. Distribution runs through direct long-term supply agreements with pharmaceutical API manufacturers and agrochemical formulators, bypassing spot-market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through continuous flow microreactor adoption reducing thermal runaway waste, and through reagent-grade specialization capturing premium pricing from European research institutions.
For Market Incumbents: To counter feedstock volatility eroding nitration margins, deepen captive fluorination capacity in East China and secure backward integration into hydrogen fluoride supply. Prioritize REACH dossier maintenance to defend European pharmaceutical offtake against emerging Indian competitors.
For New Entrants and Emerging Players: Contract research organizations in Basel and Boston represent underserved buyer archetypes demanding gram-scale reagent-grade material with comprehensive characterization data. Penetrate this segment through microreactor-enabled small-batch production and OECD-aligned hazard classification compliance, bypassing bulk industrial competition.
For Investors and Strategic Acquirers: Consolidation pressure builds where MEE wastewater compliance costs compress marginal producer economics in Jiangsu and Zhejiang provinces. Long-term viability favors integrated fluoro-benzene producers with captive nitration and existing regulatory dossier infrastructure. Watch for GB standard revision divergence from OECD frameworks as inflection indicator for compliance cost reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Fluoride | Captive feedstock supply insulates East China producers from raw material volatility. |
| Continuous Flow Nitration Deployment | Microreactor technology enables Swiss and German manufacturers to serve reagent-grade demand. |
| REACH Dossier Expansion | Comprehensive toxicity documentation secures European pharmaceutical procurement above one-tonne thresholds. |
| Long-term Supply Agreement Lock-in | Three-to-five-year offtake contracts with Indian API manufacturers reduce volume uncertainty. |
| MEE Wastewater Treatment Upgrade | Compliance infrastructure investment defends Jiangsu-Zhejiang operating licenses against enforcement escalation. |
Methodological Framework
Direct dialogue with plant managers at nitroaromatic facilities, procurement leads at pharmaceutical API manufacturers, distribution channel partners serving European research institutions, and technical R&D directors specializing in fluorination chemistry grounded qualitative insights. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from disclosed chemical producers, and REACH registration databases. Bottom-up capacity assessments across Jiangsu and Zhejiang provinces triangulated against top-down demand estimates from pharmaceutical and agrochemical end-use sectors.
Segment-level value and volume trajectories across the analysis window reflect modeled interactions between grade tier, end-use industry concentration, and regional production hub economics. CAGRs derived from regression analysis of historical fluorinated intermediate pricing and capacity utilization rates, incorporating nitration yield improvements and regulatory compliance cost escalations as industry-specific forecast inputs.
Underlying measurement precision varies by segment; reagent-grade material carries tighter precision than industrial-grade bulk quantities due to documented transaction transparency. Forecasts reflect assumptions regarding MEE enforcement consistency, REACH registration renewal timelines, and hydrogen fluoride supply stability. Material deviation in GB standard revision pace or sudden Jiangsu-Zhejiang environmental enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Muriatic Acid Market
Chemicals
Guaiazulene Market
Chemicals
Etching Chemicals Market
Chemicals
Global Phenoxyethanol Market
Chemicals
Maleic Acid Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Spirodiclofen Market
Chemicals
Malaysia Construction Chemicals Market
Chemicals
RO Membrane Chemicals Market
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Global Thiophene Market
Chemicals
Global Aluminum Hydroxide Market
Chemicals
Pinoxaden Market
Chemicals
Asia-Pacific Construction Chemicals Market
Chemicals
Global Syringaldehyde Market