
 Acrylic Acids and Esters Market | 2026-2036
Acrylic Acids and Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Acids and Esters Market Analysis
Multi-source procurement is consolidating as petrochemical buyers narrow supplier panels to secure propylene feedstock continuity. BASF SE anchors its acrylic acid position through backward integration into propylene oxide supply chains. Mitsubishi Chemical Corporation differentiates via high-purity ester grades for electronics-grade adhesives. Dow Inc. competes on manufacturing scale across Texas and Louisiana production corridors.
Acrylic acids and esters comprise unsaturated carboxylic acids and their alkyl esters synthesized via propylene oxidation, with acid values typically ranging from 99.0% to 99.5% purity for industrial grades. These compounds serve primarily as polymer building blocks for pressure-sensitive adhesives, waterborne coatings, and superabsorbent polymers. Butyl acrylate leads product type demand through its dominance in latex paint formulations and construction sealants. Paints and coatings end-use industry concentrates margin pools where low-VOC regulatory mandates shift formulation chemistry toward higher-ester content systems. Direct sales distribution channel controls bulk chemical logistics for integrated buyers, while distributor networks serve fragmented coatings compounders across South Asia and Latin America.
REACH in Europe and EPA VOC regulations in the United States constrain solvent-borne acrylic formulations, redirecting R&D spending toward emulsion polymerization technologies. China's MEE enforces stricter effluent standards on acrylic acid plants along the Yangtze River basin, raising compliance costs for regional producers. Stakeholders must monitor feedstock propylene pricing volatility and bio-based acrylic acid pilot scale-up timelines to anticipate sourcing model disruptions.
Market Dynamics
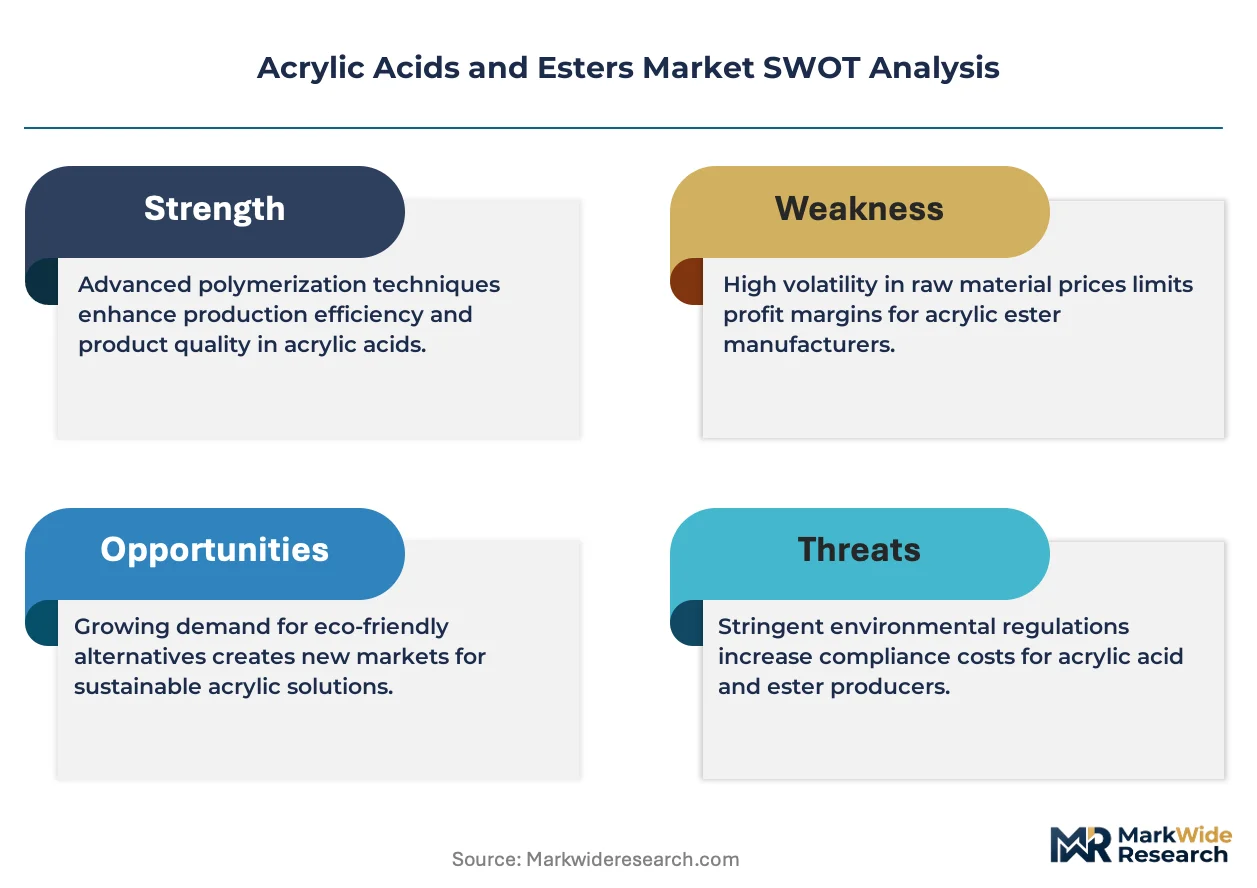
Propylene feedstock volatility and REACH-mandated VOC reductions are compressing formulation margins while accelerating emulsion polymerization R&D commitments across coatings and adhesives supply chains.
Growth Catalysts
- Water-based adhesive mandates:Automotive assembly plants in Germany and the United States are substituting solvent-borne systems with acrylic emulsion binders to meet EPA and ECHA emission thresholds.
- Construction-grade emulsion demand:China's infrastructure build-out absorbs butyl acrylate derivatives for exterior masonry coatings and sealant applications at accelerating volumes.
- Superabsorbent polymer expansion:Personal hygiene manufacturers in Japan and South Korea specify high-purity glacial acrylic acid for ultra-thin diaper core layers.
Market Restraints
- Propylene price volatility:Naphtha-cracker economics and refinery output swings in the US Gulf Coast directly transmit to acrylic acid production cost structures.
- Effluent compliance burdens:China's MEE enforcement along the Yangtze River basin forces capital-intensive wastewater treatment retrofits on regional producers.
- Bio-acid scale-up delays:Fermentation-derived acrylic acid from C3 sugar feedstocks remains trapped at pilot-plant scale, limiting near-term substitution pathways.
Strategic Opportunities
- India coatings penetration:Architectural paint formulators in Maharashtra and Gujarat are transitioning from alkyds to acrylic latex systems, opening ester demand corridors.
- Electronics-grade ester specialization:Semiconductor packaging adhesives require sub-ppm purity methyl acrylate grades that command technical premiums over commodity offerings.
- EU Green Deal chemistry incentives:Horizon Europe funding streams favor bio-based monomer development, creating R&D subsidy pools for sustainable acrylic acid pathways.
Industry Challenges
- Process control expertise scarcity:Two-stage propylene oxidation reactor optimization requires specialized catalytic engineering talent concentrated at legacy production sites.
- Multi-jurisdiction registration timelines:New monomer variants face 18-24 month REACH and EPA PMN review cycles before commercial clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Acids and Esters Market |
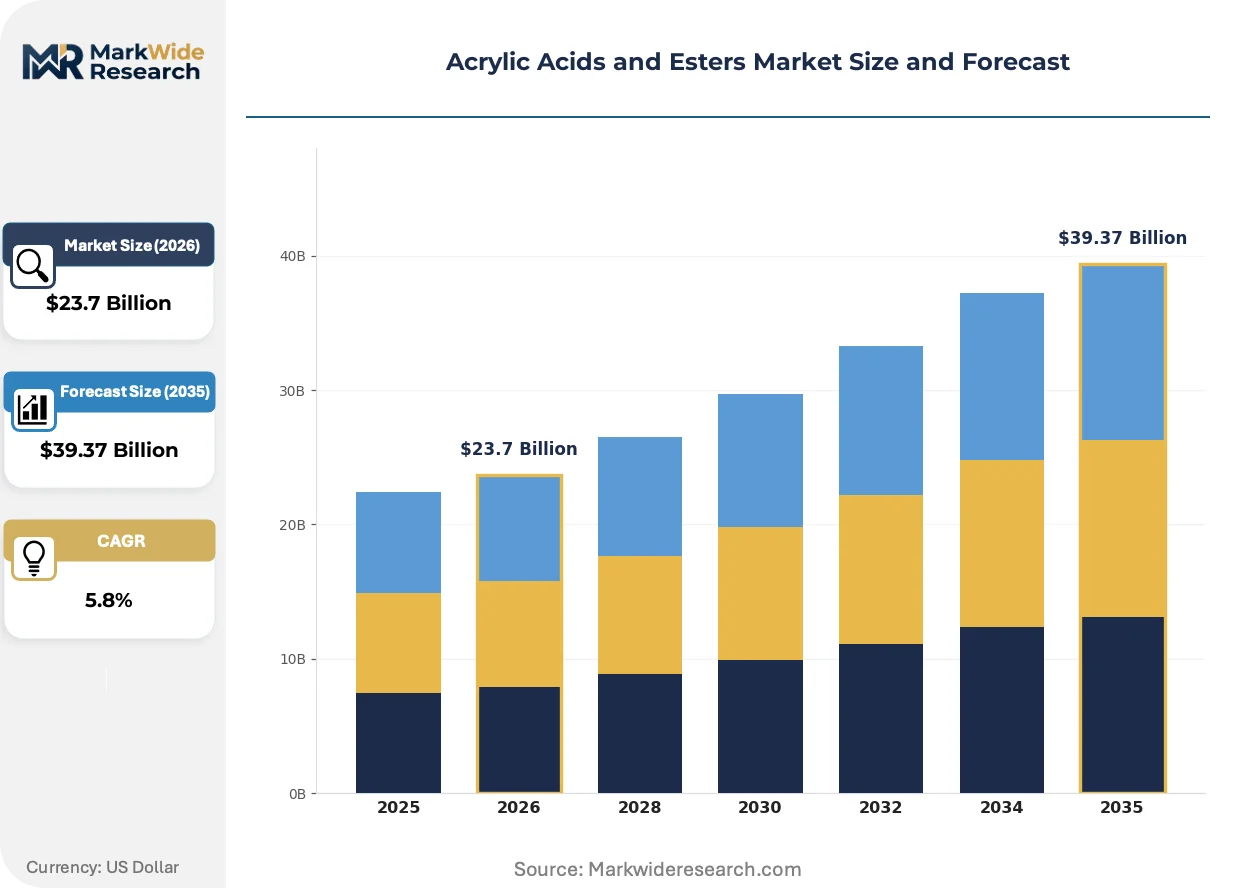
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic Acid, Butyl Acrylate, Ethyl Acrylate, Methyl Acrylate End Use Industry: Adhesives, Paints & Coatings, Plastics, Textiles Application: Sealants, Surface Coatings, Emulsions, Inks Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | BASF SE, Dow Inc., Arkema, Mitsubishi Chemical Corporation, LG Chem, Nippon Shokubai Co., Ltd., Evonik Industries, Formosa Plastics Corporation, SIBUR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Acids and Esters Market Emerging Trajectories
Emulsion polymerization advances and bio-based feedstock pilots are restructuring how acrylic monomers enter formulated products, with regulatory chemistry mandates acting as the primary technology selection filter.
Continuous-flow reactor designs for acrylic acid synthesis are electrifying process economics by compressing residence times and improving heat-transfer efficiency. Specialty chemical producers in the Netherlands and Belgium are piloting these systems for high-value ester grades. The technology is electrifying capital deployment patterns, with modular units displacing conventional multi-reactor trains in greenfield planning.
REACH Annex XVII restrictions on solvent-borne architectural coatings are forcing reformulation toward higher solids and waterborne acrylic systems across EU member states. Paint manufacturers in Italy and Spain are accelerating emulsion polymerization capacity additions. Decorative coatings segments in Eastern Europe face the steepest compliance cost curves as transitional periods expire.
Specification consolidation among multinational coatings compounders is compressing supplier panels for bulk ester procurement. Regional distributors in Brazil and Mexico are losing volume share to direct mill relationships as buyer concentration intensifies. Procurement teams at tier-one automotive OEMs now mandate supplier sustainability scorecards alongside technical compliance, with the strictest requirements emerging in German and Japanese supply chains.
Acrylic Acids and Esters Market Segmentation
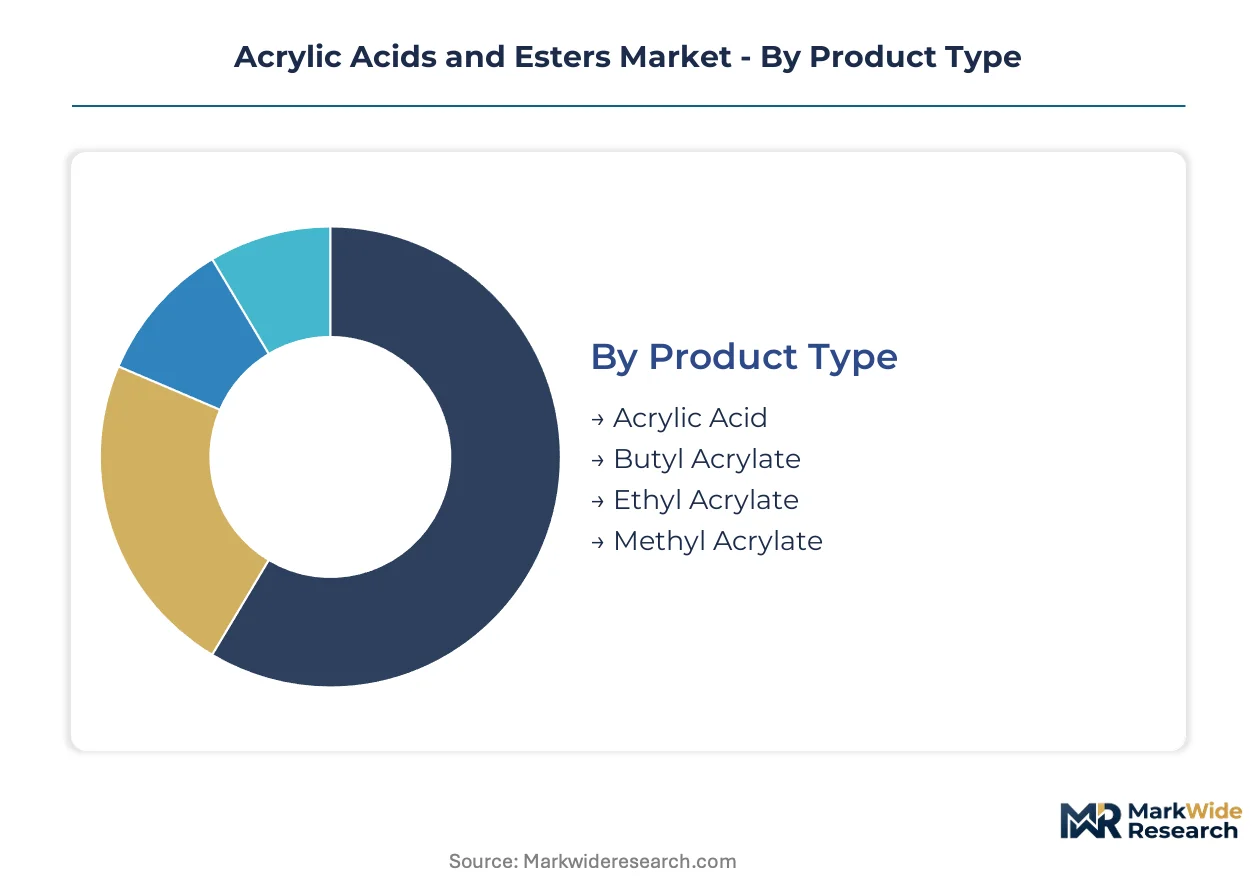
Acrylic acids and esters serve distinct functional roles across polymer chemistry, with product specifications varying sharply between commodity bulk grades and precision electronic formulations. Segmentation reveals where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Customization intensity spans from standardized commodity acids to specialty esters engineered for sub-ppm purity thresholds in semiconductor applications.
- Acrylic Acid:Unsaturated carboxylic acid synthesized via two-stage propylene oxidation, with glacial grades reaching 99.5% purity for superabsorbent polymer production. Personal hygiene manufacturers in Japan specify ultra-high purity for ultra-thin diaper core layers where fluid retention performance is critical.
- Butyl Acrylate:Alkyl ester dominating latex paint formulations and construction sealants through superior weathering resistance and flexibility retention. China's infrastructure build-out along the Yangtze River basin absorbs accelerating volumes for exterior masonry coatings and architectural sealants.
- Ethyl Acrylate:Ester intermediate for textile finishing agents and leather coatings, offering rapid polymerization kinetics for industrial coating lines.
- Methyl Acrylate:Low-viscosity monomer for pressure-sensitive adhesive tapes and optical film substrates, with electronics-grade specifications commanding technical premiums in South Korean display supply chains.
Leading the category by volume: Butyl Acrylate. Expanding most quickly: Acrylic Acid driven by superabsorbent polymer capacity additions.
End Use Industry:
Application maturity separates established coatings demand from emerging adhesive specifications in automotive lightweighting programs.
- Paints & Coatings:Dominant value pool where REACH Annex XVII and EPA VOC regulations are forcing reformulation toward waterborne acrylic emulsions. Italian and Spanish manufacturers are accelerating emulsion polymerization capacity to serve EU decorative coatings compliance deadlines.
- Adhesives:Fastest-growing specification set as automotive assembly plants in Germany and the United States substitute solvent-borne systems with acrylic emulsion binders to meet ECHA and EPA emission thresholds.
- Plastics:Impact modifier applications for PVC and engineering thermoplastics, with construction profiles driving steady demand in North American extrusion markets.
- Textiles:Fabric finishing and nonwoven binders, concentrated in South Asian garment manufacturing clusters seeking durable press and soil-release performance.
Highest margin capture: Paints & Coatings. Steepest specification upgrade curve: Adhesives.
Application:
Performance requirements stratify between bulk construction applications and precision surface engineering for electronics.
- Emulsions:Waterborne polymer dispersions for architectural coatings and pressure-sensitive adhesives, with particle size distribution controlling film formation and tack properties. India's Maharashtra and Gujarat formulators are transitioning from alkyds to acrylic latex systems, opening ester demand corridors in western states.
- Surface Coatings:Protective and decorative films where gloss retention and UV resistance specifications vary by substrate exposure severity.
- Sealants:Flexible gap-filling compounds for construction and transportation assembly, requiring balanced elasticity and adhesion.
- Inks:Pigment dispersion vehicles for packaging and publication printing, with viscosity and drying speed tuned to press configurations.
Widest formulation flexibility: Emulsions. Tightest specification windows: Surface Coatings for automotive OEM compliance.
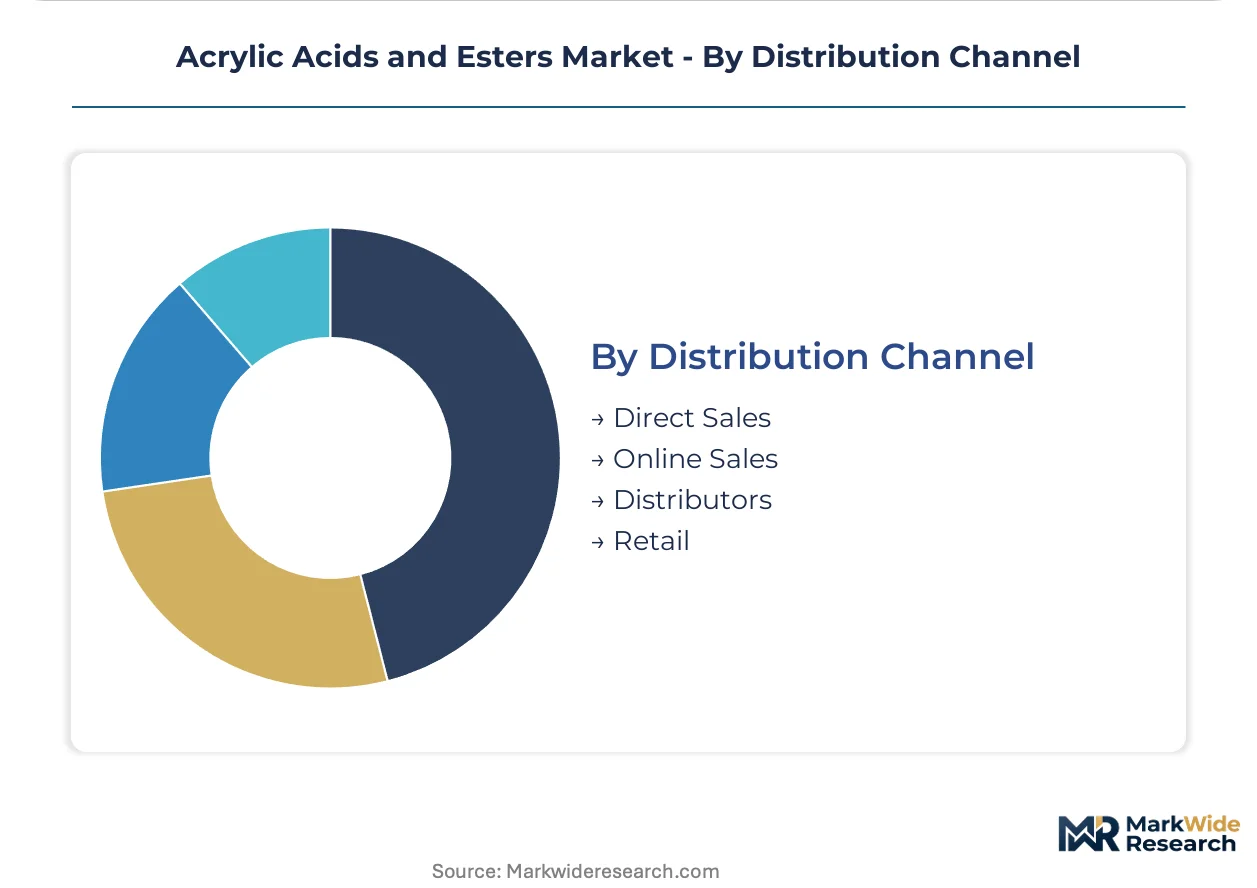
Distribution Channel:
Customer scale and technical service requirements determine whether bulk logistics or fragmented technical support dominates procurement patterns.
- Direct Sales:Controls bulk chemical logistics for integrated buyers with dedicated tankage and rail receipt infrastructure. BASF SE and Dow Inc. anchor relationships through captive propylene supply continuity and technical service engineering.
- Distributors:Serve fragmented coatings compounders across South Asia and Latin America with smaller lot sizes and local inventory positioning.
- Online Sales:Emerging for standardized ester grades and technical documentation access, though bulk hazardous material shipping constraints limit penetration.
- Retail:Niche presence for small-volume specialty esters in research and prototype development quantities.
Volume concentration: Direct Sales. Fastest channel evolution: Distributors consolidating technical service capabilities to defend against mill-direct procurement trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene availability from Gulf Coast crackers and naphtha-fed steam crackers anchors acrylic acid production economics across major manufacturing corridors. Feedstock proximity dictates regional cost competitiveness and shapes cross-border trade flows in ester derivatives.
United States
Shale-derived propylene supply from Texas and Louisiana petrochemical corridors supports acrylic acid capacity serving automotive adhesive mandates. EPA VOC regulations under the Clean Air Act push coating formulators toward waterborne emulsion systems. The Houston Ship Channel cluster concentrates ester production for pressure-sensitive adhesive exports to Latin American markets.
Germany
Automotive assembly plants in Stuttgart and Wolfsburg specify low-emission acrylic emulsion binders for interior component bonding. REACH Annex XVII restrictions on solvent-borne architectural coatings force decorative paint reformulation toward higher solids content. The Ludwigshafen chemical complex maintains backward integration into propylene oxide supply chains for captive acrylic acid production.
China
Infrastructure investment along the Yangtze River Delta absorbs butyl acrylate derivatives for exterior masonry coatings and construction sealants. MEE effluent standards enforce wastewater treatment retrofits on acrylic acid plants in Jiangsu and Zhejiang provinces. The Ningbo petrochemical zone anchors regional ester production capacity serving domestic coatings compounders.
Japan
Personal hygiene manufacturers in Hyogo and Osaka prefectures specify ultra-high purity glacial acrylic acid for superabsorbent polymer production in ultra-thin diaper applications. METI chemical safety guidelines establish purity thresholds for hygiene-grade monomer imports. The Kawasaki industrial corridor concentrates specialty ester refining for electronics-grade adhesive specifications.
India
Architectural paint formulators in Maharashtra and Gujarat transition from alkyd systems to acrylic latex formulations for interior and exterior applications. BIS certification requirements for emulsion paint quality create technical barriers for imported ester grades. The Mundra port cluster enables bulk butyl acrylate imports serving western state construction chemical manufacturers.
Acrylic Acids and Esters Market Vendor Landscape
Global majors compete with regional champions across feedstock integration and specialty ester purity tiers. The vendor base stratifies between propylene-backward integrated producers and merchant ester specialists dependent on spot acid purchases. Three archetypes dominate: integrated petrochemical majors with captive propylene supply, Asian conglomerates with regional distribution density, and European specialty houses focusing on electronics-grade purity segments. Competitive moves center on capacity expansion in low-cost feedstock corridors and strategic partnerships with coatings compounders for formulation co-development.
Among the integrated petrochemical majors, BASF SE and Dow Inc. occupy positions exemplifying backward integration into propylene supply chains. Mitsubishi Chemical Corporation represents the specialty purity tier, serving electronics-grade adhesive specifications. These three anchors illustrate how competitive positioning splits between feedstock-cost leadership and technical-premium capture across divergent end-use segments.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Arkema |
| Mitsubishi Chemical Corporation |
| LG Chem |
| Nippon Shokubai Co., Ltd. |
| Evonik Industries |
| Formosa Plastics Corporation |
| SIBUR |
| Others |
Supply Flow & Price Mechanics
Propylene feedstock costs from US Gulf Coast crackers and Asian naphtha-fed steam crackers cascade through acrylic acid production tiers into differentiated ester pricing bands. Contract offtake agreements for bulk butyl acrylate shipments to coatings compounders bundle technical service and tankage provision, while spot market transactions for specialty methyl acrylate grades trade unbundled from logistics support.
Pricing Analysis
Service-bundling separates contract-based long-term offtake arrangements from spot market transactions where technical support and tankage provision stand unpriced. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity grade and certification tier, with electronics-grade methyl acrylate commanding technical premiums over commodity butyl acrylate. Cost compression in standard-grade esters is intensifying because propylene price volatility transmits directly from naphtha-cracker economics. Small-batch coatings compounders in South Asia exhibit highest price sensitivity, while Japanese personal hygiene manufacturers demonstrate lowest sensitivity due to specification rigidity for superabsorbent polymer feedstock.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns for bulk ester movements into European, North American, and Asia-Pacific coating clusters. Acrylic acid production concentrates in the United States, China, and Germany where propylene availability from crackers and refineries supports cost-competitive oxidation capacity. The supply chain draws from propylene, sulfuric acid catalysts, and specialized reactor metallurgy as critical inputs. Single-source vulnerability around catalyst engineering talent concentrated at legacy production sites poses structural risk. Distribution runs through direct mill relationships for integrated buyers and distributor networks for fragmented compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Emulsion polymerization technology is displacing solvent-borne formulation systems across coatings and adhesives applications, compressing margins for legacy solvent-based supply chains while rewarding aqueous system capabilities.
For Market Incumbents: To counter bio-based acrylic acid pilot scale-up from C3 sugar fermentation pathways, BASF SE and Dow Inc. should deepen backward integration into propylene oxide supply chains and accelerate continuous-flow reactor electrification for process cost compression. Captive feedstock control and modular production units defend margin position against merchant acid competitors exposed to spot propylene volatility. For New Entrants and Emerging Players: Electronics-grade ester specialization with sub-ppm purity methyl acrylate production offers the most penetrable wedge into semiconductor packaging adhesive supply chains serving South Korean and Japanese display manufacturers. Target India's Maharashtra and Gujarat architectural paint transition from alkyds to acrylic latex systems through distributor technical service partnerships rather than direct mill competition. For Investors and Strategic Acquirers: Fermentation-derived acrylic acid achieving demonstration-scale throughput is the leading indicator that bio-based feedstock substitution will disrupt propylene-linked cost structures within the long-term viability window. Acquisition targets should profile European specialty houses with REACH registration assets and electronics-grade purity capabilities. The signal to monitor is EU Green Deal chemistry funding flows into Horizon Europe bio-monomer development streams.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive propylene supply from crackers insulates BASF and Dow from feedstock volatility. |
| Capacity Expansion | Modular continuous-flow reactor additions in Texas and Louisiana corridors compress unit economics. |
| Green Manufacturing Transition | Bio-based acrylic acid pilot scale-up aligns with EU Green Deal subsidy eligibility. |
| Long-term Supply Agreement | Direct mill relationships with German automotive OEMs lock in emulsion binder volumes. |
| Joint Venture | Regional distribution partnerships in India defend against distributor consolidation trends. |
Methodological Framework
SEC 10-K filings, Cefic industry reports, and customs trade data formed the secondary backbone for production capacity and trade flow validation. Primary interviews with acrylic acid plant managers, procurement leads at coatings OEMs, distribution channel partners, and technical R&D directors supplied operational perspective on specification trends and capacity utilization. Bottom-up volume modeling by product grade and end-use application triangulated against top-down macroeconomic demand drivers to ensure analytical consistency.
Historical trendline analysis across installed capacity additions, feedstock cost indices, and regulatory compliance expenditure patterns informed the projection framework. Segmentation dimensions modeled include product purity tier, end-use industry concentration, regional production hub configuration, and distribution channel structure. CAGRs were derived through regression analysis of volume trajectories against driver variables including construction activity indices and automotive production schedules. Forecast inputs incorporated REACH Annex XVII implementation timelines and China's MEE effluent enforcement intensity along the Yangtze River basin.
Several conditions sit outside the modeled scope, including unannounced capacity closures, breakthrough bio-acid fermentation scale-up, and geopolitical disruptions to propylene trade flows. Forecasts reflect stated assumptions around regulatory implementation schedules and feedstock cost transmission mechanisms. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Flatting Agents Market
Chemicals
Electroplating Chemicals Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Acid Anhydrides Market
Chemicals
Phenylethyl Market
Chemicals
Butylated Triphenyl Phosphate Market
Chemicals
Hexamine Market
Chemicals
Ferric Phosphate Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Trifluoroacetic Acid (TFA) Market
Chemicals
3-Dimethylacrylic Acid Methyl Ester Market
Chemicals
CHPTAC Market
Chemicals
Global Tetraacetylethylenediamine (TAED) Market
Chemicals
India Metal Treatment Chemical Market
Chemicals
North America Oxo-Alcohol Market
Chemicals
Global P-Phenylenediamine Market