
 Leather Tanning Chemicals Market | 2026-2036
Leather Tanning Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Leather Tanning Chemicals Market Foresight
Automotive manufacturers is collapsing the traditional footwear-first procurement hierarchy in leather tanning chemicals. BASF SE leverages its polymer chemistry portfolio to supply synthetic tanning agents for automotive interior specifications. Stahl Holdings B.V. sustains dominance in water-based finishing systems across European luxury upholstery channels. LANXESS AG anchors chrome tanning agent supply through backward integration into chromium chemical production.
Leather tanning chemicals comprise formulated substances that alter collagen protein structures in raw hides, typically operating at pH ranges of 2.5 to 4.0 during mineral tanning and achieving shrinkage temperatures above 85°C for chrome-tanned outputs to impart dimensional stability and rot resistance for downstream manufacturing. Chrome tanning agents retain the largest volume share due to cost efficiency and colorfastness performance, though organic tanning agents are gaining fastest as footwear manufacturers face brand-level restricted substance commitments. Vegetable tanning agents occupy specialized margin pools in saddlery and artisan leather goods where natural patina development commands premium positioning.
REACH regulates chromium VI limits in finished leather articles across Europe, while EPA oversight governs effluent discharge from tanneries in the United States, and BIS certification requirements in India standardize chemical inputs for export-oriented leather processing. These frameworks collectively elevate compliance costs for chrome-dependent formulations while creating preferential market access for suppliers with validated low-metal or metal-free portfolios. Stakeholders must monitor evolving restricted substance lists from automotive OEMs and fashion brands, as these private standards increasingly outpace regulatory baselines in determining chemical specification wins.
Market Dynamics
REACH chromium VI restrictions are forcing tanneries across Italy, Germany, and Spain to abandon chrome-dependent workflows. Automotive OEM procurement specifications now outpace regulatory baselines, compressing formulation cycles for chemical suppliers serving vehicle interior programs.
Growth Catalysts
- REACH Phase-out Mandates:European tanneries face binding chromium VI limits in finished articles, accelerating vegetable and synthetic tanning agent procurement for export-compliant output.
- Automotive Interior Specifications:OEMs including BMW and Mercedes-Benz enforce metal-free leather standards for seating and dashboard applications, redirecting chemical sourcing toward polymer-based tanning systems.
- Arzignano Cluster Concentration:Italy's Veneto tanning district generates intensified specialty chemical demand for luxury upholstery, consolidating supplier relationships around validated low-metal portfolios.
Market Restraints
- Chromium Chemical Price Volatility:Chrome tanning agent costs fluctuate with South African chromite ore supply disruptions and energy-intensive reduction processing economics.
- Effluent Treatment Capital Burden:Tanneries in Tamil Nadu and Uttar Pradesh face BIS-mandated zero-liquid-discharge upgrades requiring membrane bioreactor investments that compress operating margins.
- Synthetic Tanning Performance Gap:Polymer-based agents fail to achieve chrome-equivalent shrinkage temperatures in heavy leather applications, limiting substitution in industrial belting and sole leather.
Strategic Opportunities
- Indian Export-Oriented Processing:Kanpur and Ambur tannery clusters seek compliant chemical inputs for EU-bound finished leather, creating preferential access for REACH-validated suppliers.
- Biopolymer Tanning Convergence:Collagen-stabilizing enzymes combined with vegetable tannins enable reduced chrome dosing while maintaining performance thresholds for automotive upholstery.
- Direct Chemical Leasing Models:Stahl Holdings and specialty distributors pilot per-meter-finished-leather pricing structures, transferring effluent liability and dosing optimization risk to suppliers.
Industry Challenges
- Formulation Chemist Scarcity:European tanneries struggle to recruit specialists capable of bridging mineral, vegetable, and synthetic tanning system integration without chrome bridging agents.
- Multi-Certification Timeline Compression:Suppliers must simultaneously satisfy automotive IMDS registration, ZDHC MRSL conformance, and brand-specific restricted substance lists with divergent analytical protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leather Tanning Chemicals Market |
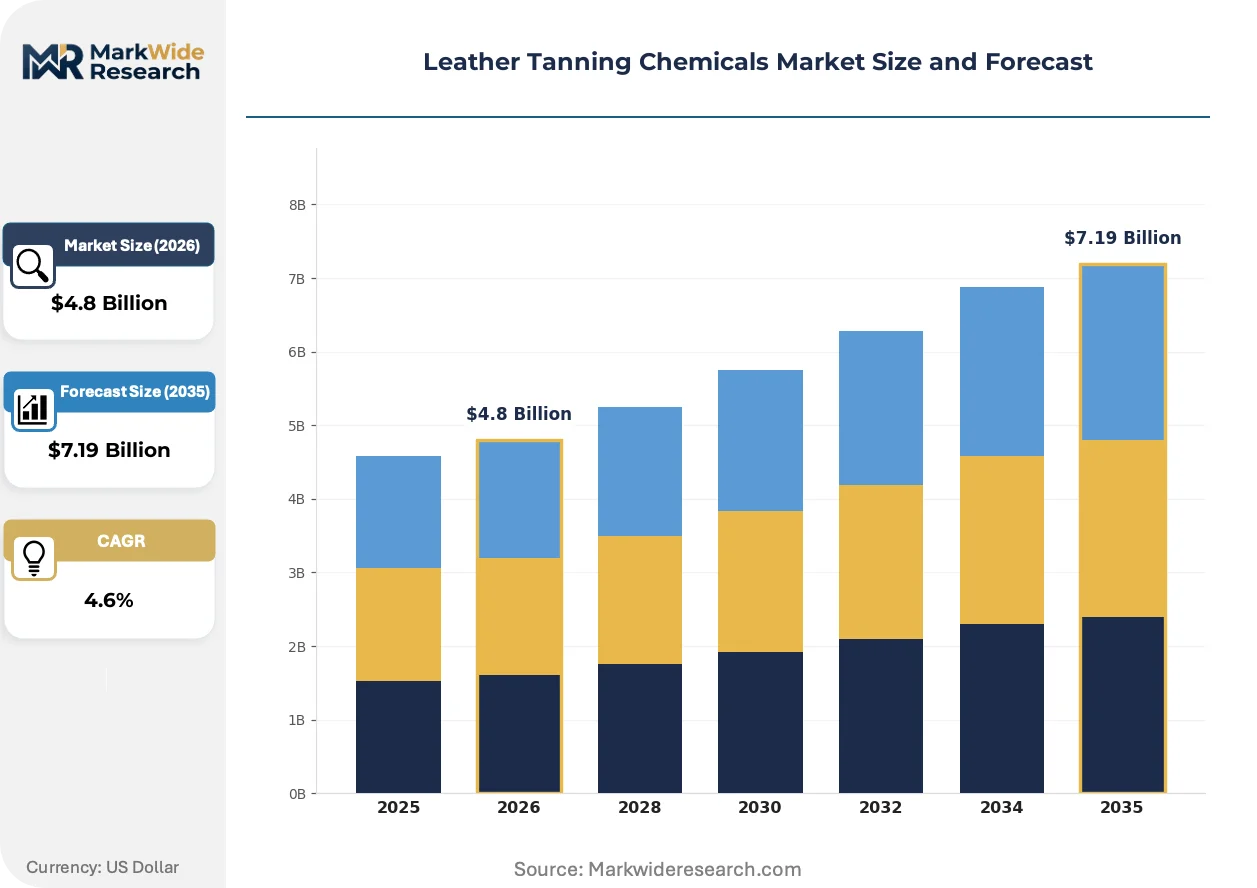
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chrome Tanning Agents, Vegetable Tanning Agents, Synthetic Tanning Agents, Organic Tanning Agents Application: Footwear, Apparel, Upholstery, Leather Goods End User: Footwear Manufacturers, Clothing Manufacturers, Furniture Manufacturers, Automotive Manufacturers Distribution Channel: Direct Sales, Online Sales, Retail Sales, Distributors |
| Companies Covered | LANXESS AG, Buckman Laboratories International, Inc., Stahl Holdings B.V., Chemtan Company, Inc., Balmer Lawrie & Co. Ltd., Clariant AG, BASF SE, Arkema SA, TFL Ledertechnik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leather Tanning Chemicals Market Shifts & Advancements
Enzymatic pre-tanning technologies are compressing process water consumption while enabling hybrid mineral-organic systems. Regulatory pressure on chromium discharge is accelerating patent filing around protein-stabilizing biopolymers. Procurement specifications from luxury fashion houses now embed chemical traceability requirements that reshape supplier qualification protocols.
Micro-encapsulated tanning agents are miniaturizing active ingredient delivery for precision collagen crosslinking. Automotive seating manufacturers in Stuttgart and Munich adopt these systems to achieve consistent dye uptake across batch variations. The technology is miniaturizing quality-control tolerances that previously required chrome-based process buffers, enabling synthetic tanning penetration into premium upholstery segments.
EPA effluent guidelines for leather tanning under the Clean Water Act are tightening chromium discharge limits for US tanneries in Pennsylvania and Tennessee. Facilities face biological treatment upgrades or process reconfiguration toward metal-free alternatives. Chrome-tanned heavy leather production for industrial belting concentrates in states with relaxed state-level implementation timelines.
Brand-level chemical traceability mandates are reshaping supplier qualification protocols. Kering and LVMH enforce ZDHC MRSL conformance through third-party verification of tanning agent inputs. Italian luxury goods manufacturers in Florence and Milan prioritize suppliers with blockchain-documented supply chains for vegetable tannin sourcing from French and Spanish chestnut extractors.
Leather Tanning Chemicals Market Segmentation
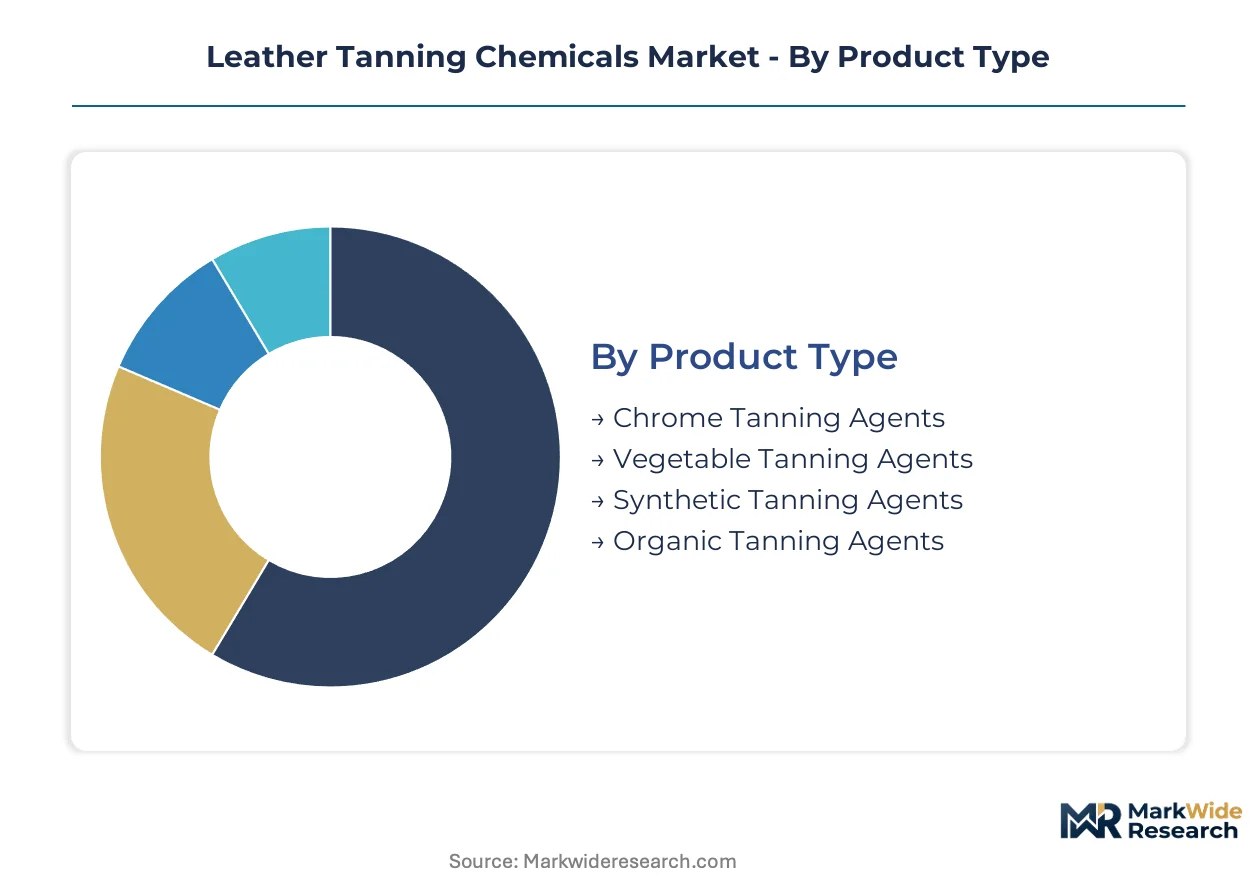
Leather tanning chemical suppliers configure product portfolios and channel strategies around distinct performance requirements across mineral, organic, and polymer-based systems. Segment boundaries increasingly blur as hybrid formulations penetrate automotive and luxury goods applications. Procurement specifications from end-users now dictate segmentation logic more than traditional chemical taxonomy.
Product Type:
Channel-mix patterns diverge sharply: bulk chrome tanning agents flow through distributor networks to high-volume tanneries, while specialty synthetic and organic agents move via direct technical sales to automotive OEM-certified suppliers.
- Chrome Tanning Agents:Chromium sulfate and basic chromium sulfate formulations deliver shrinkage temperatures exceeding 85°C for dimensional stability. Demand concentrates in industrial belting and heavy sole leather production across Tamil Nadu and Uttar Pradesh clusters, constrained by REACH chromium VI discharge limits and South African chromite supply volatility.
- Synthetic Tanning Agents:Phenolic and amino-based polymer systems enable metal-free leather for automotive seating specifications. BMW and Mercedes-Benz procurement programs in Stuttgart and Munich drive fastest expansion, though polymer agents fail to match chrome-equivalent thermal stability in thick hide applications.
- Vegetable Tanning Agents:Condensed tannins from chestnut and quebracho extracts serve saddlery and artisan leather goods in Italy's Veneto district.
- Organic Tanning Agents:Aldehyde and oil-based systems occupy niche pharmaceutical and food-contact leather segments with strict metal-content restrictions.
By volume, chrome tanning agents lead. By growth pace, synthetic tanning agents are climbing the fastest.
Application:
Margin structures stratify by finished leather complexity: upholstery commands premium chemical specifications, while footwear operates on volume-optimized formulation economics.
- Footwear:Athletic and fashion shoe leather requires rapid chromium penetration for consistent dye uptake across batch variations. Kanpur and Ambur tanneries in India source REACH-compliant agents for EU-bound export orders.
- Upholstery:Automotive and aviation seating specifications enforce ZDHC MRSL conformance with full chemical traceability. Kering and LVMH luxury furniture programs in Milan and Florence drive vegetable tannin demand for natural patina development.
- Apparel:Garment leather prioritizes softness and drape, favoring reduced chrome dosing with enzymatic pre-tanning aids.
- Leather Goods:Handbags and small accessories balance durability with lightweight construction, mixing synthetic retanning agents for handle stability.
Footwear generates the largest chemical offtake. Upholstery delivers the steepest value-per-kilogram expansion.
End User:
Customer scale determines service model: automotive OEMs demand co-development partnerships, while furniture manufacturers purchase through formulated systems houses.
- Automotive Manufacturers:Metal-free leather mandates for vehicle interiors in Germany and luxury EV programs redirect procurement toward polymer-based tanning systems with IMDS-registered chemical inputs.
- Footwear Manufacturers:Brand-level restricted substance commitments from athletic and fashion houses accelerate organic tanning agent validation for consumer-facing sustainability claims.
- Furniture Manufacturers:Residential and contract upholstery segments split between cost-optimized chrome retanning and premium vegetable-tanned inputs for heritage positioning.
- Clothing Manufacturers:Apparel leather processors in Italy's Arzignano cluster seek hybrid mineral-organic systems to balance softness with effluent compliance.
Automotive manufacturers exert the strongest specification leverage. Footwear manufacturers provide the broadest segment coverage across geographies.
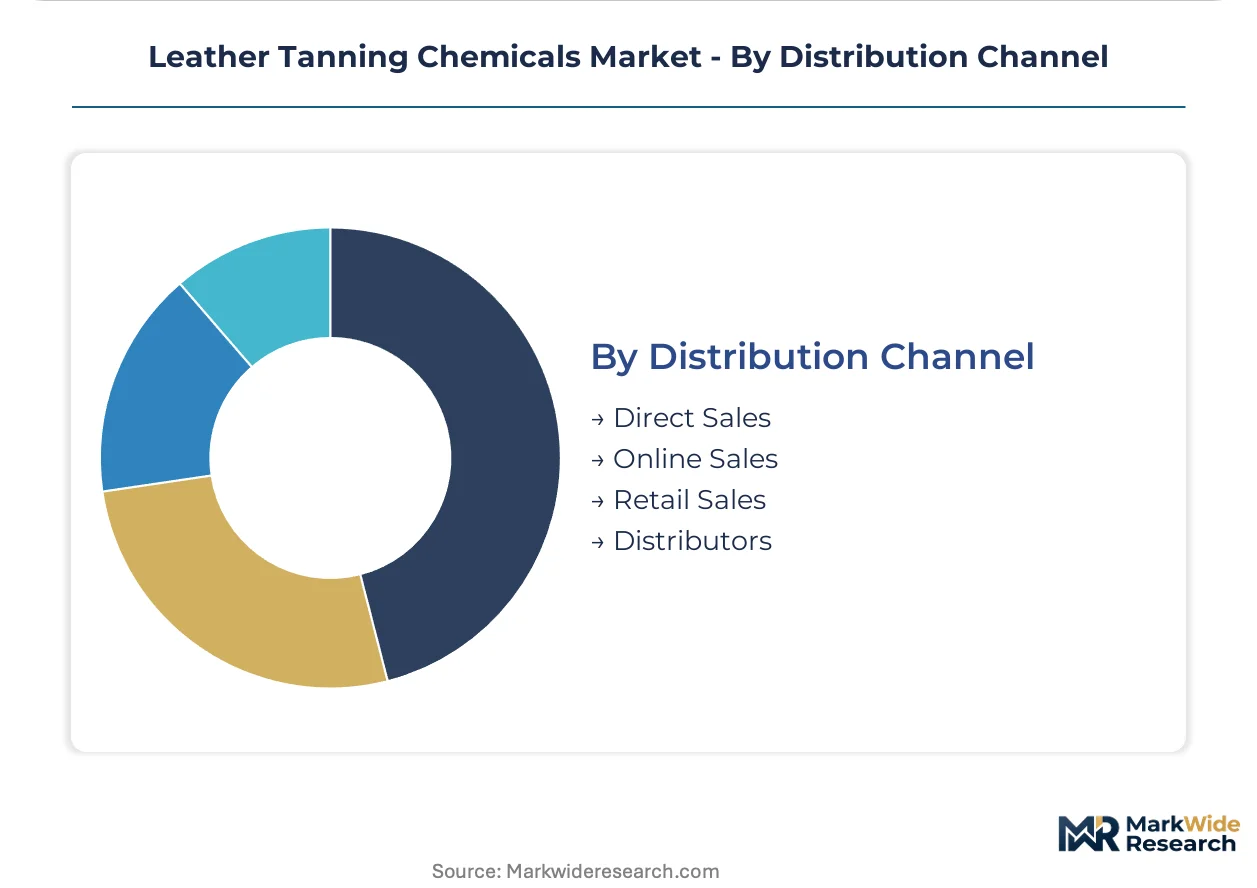
Distribution Channel:
Logistics complexity scales with technical service intensity: direct sales carry formulation liability, while distributors handle commodity chrome salt movements.
- Direct Sales:Stahl Holdings and LANXESS deploy technical field teams for automotive upholstery co-development, embedding per-meter-finished-leather pricing with effluent liability transfer.
- Distributors:Regional chemical distributors in India and Italy consolidate chrome tanning agent procurement for mid-tier tanneries lacking laboratory formulation capabilities.
- Online Sales:E-commerce platforms serve small artisan tanners and educational institutions with packaged vegetable tannin extracts and specialty dyes.
- Retail Sales:Limited to hobbyist and craft leatherworking supplies, negligible in industrial chemical volumes.
Direct sales capture the highest value per transaction. Distributors maintain the widest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's Arzignano tanning cluster exports finished leather to German automotive OEMs, creating a specialized chemical demand corridor that concentrates procurement specifications and supplier validation protocols across the Veneto-to-Baden-Württemberg trade axis.
Italy
Arzignano's Veneto district drives premium upholstery chemical demand for luxury furniture and automotive seating. ECHA REACH enforcement on chromium VI discharge limits accelerates vegetable tannin procurement from French chestnut extractors. Florence and Milan luxury goods manufacturers consolidate supplier relationships around ZDHC MRSL-validated inputs.
Germany
BMW and Mercedes-Benz procurement programs enforce metal-free leather standards for vehicle interiors. BfR consumer product safety guidance elevates compliance thresholds for chemical inputs in automotive upholstery. Stuttgart and Munich seating manufacturers source polymer-based tanning systems with IMDS-registered specifications.
India
Kanpur and Ambur tannery clusters seek REACH-compliant agents for EU-bound footwear and leather goods exports. BIS certification requirements standardize chemical inputs for export-oriented processing facilities. Tamil Nadu facilities face zero-liquid-discharge mandates requiring membrane bioreactor capital investments.
United States
Pennsylvania and Tennessee tanneries confront EPA Clean Water Act effluent guideline tightening on chromium discharge limits. Pennsylvania facilities evaluate biological treatment upgrades or process reconfiguration toward metal-free alternatives. Chrome-tanned heavy leather production for industrial belting concentrates in states with relaxed implementation timelines.
France
ANSM oversight of chemical substances in consumer goods reinforces brand-level traceability mandates from Paris-based luxury houses. Kering and LVMH enforce ZDHC MRSL conformance through third-party verification of tanning agent inputs. Chestnut extractors in southern France supply condensed tannins to Italian artisan leather goods manufacturers.
Leather Tanning Chemicals Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with backward integration into chromium production and specialty systems houses with formulation expertise. Market structure concentrates around three to five dominant suppliers capable of meeting automotive OEM co-development requirements alongside fragmented regional distributors serving commodity chrome salt demand. Strategic archetypes include mineral tanning specialists with captive chromium supply, polymer-based systems developers for metal-free specifications, and vegetable tannin extractors with certified traceability chains. Competitive moves center on direct chemical leasing models transferring effluent liability and per-meter-finished-leather pricing structures.
Among European-based diversified suppliers, LANXESS AG exemplifies the mineral tanning specialist archetype with chromium chemical production integration. Stahl Holdings B.V. occupies the polymer-based systems tier for automotive upholstery specifications. BASF SE represents the chemical conglomerate vector leveraging broad polymer chemistry portfolios across multiple industrial applications. These three anchors illustrate the competitive segmentation between mineral-dependent, metal-free transition, and diversified chemical supply strategies.
| Leading Market Players |
|---|
| LANXESS AG |
| Buckman Laboratories International, Inc. |
| Stahl Holdings B.V. |
| Chemtan Company, Inc. |
| Balmer Lawrie & Co. Ltd. |
| Clariant AG |
| BASF SE |
| Arkema SA |
| TFL Ledertechnik GmbH |
| Others |
Supply & Pricing Matrix
REACH chromium VI discharge limits gate both supplier qualification and price differentiation simultaneously, forcing tanneries to pay premiums for ZDHC MRSL-validated inputs while commodity chrome salts trade at compressed margins. Automotive OEM certification requirements concentrate purchasing power among validated chemical systems houses, creating tiered access economics that separate REACH-compliant premium formulations from standard industrial grades.
Pricing Analysis
Chrome tanning agent pricing reflects prior-generation commodity economics, synthetic polymer systems capture current-generation automotive premiums, and enzymatic pre-tanning aids command next-generation sustainability markups. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with ZDHC MRSL conformance adding substantial cost layers. Price erosion runs through commodity chrome sulfate channels due to South African chromite supply volatility. Footwear manufacturers in Kanpur and Ambur exhibit highest price sensitivity, while Stuttgart and Munich automotive seating programs absorb premium polymer tanning system costs without volume pushback.
Supply Chain Analysis
Just-in-time inventory strategies dominate specialty synthetic tanning agent procurement for automotive upholstery programs, while strategic stockpiling of South African chromite ore persists among chrome-dependent tanneries. Supply concentrates in Germany for polymer-based systems, South Africa for chromium chemical feedstock, and Italy for vegetable tannin extraction. Raw material dependencies include chromite ore, phenolic resin precursors, and chestnut extract supplies. Single-source vulnerability from South African chromite concentration threatens chrome tanning agent cost stability. Distribution runs through direct technical sales for automotive-certified suppliers and regional distributors for commodity chrome salt offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH and ZDHC conformance creates defensive moats for validated suppliers, as switching costs for tanneries span requalification timelines and formulation redevelopment cycles that lock in incumbent relationships.
For Market Incumbents: Secure backward integration into chromium chemical production to buffer chromite ore price volatility, while expanding polymer-based tanning agent capacity for automotive OEM programs. Synthetic tanning substitution threats from enzymatic pre-tanning technologies demand accelerated R&D investment in hybrid mineral-organic systems. Certification investment in ZDHC MRSL and IMDS registration reinforces channel control against emerging specialty chemical entrants. For New Entrants and Emerging Players: Technical service gaps in formulation chemist scarcity present white-space opportunities for boutique consulting-led chemical supply models. India's Kanpur and Ambur tannery clusters offer the most penetrable geography for REACH-compliant agent introduction, given BIS-mandated export orientation and limited local formulation expertise. A direct chemical leasing model transferring effluent liability to suppliers provides differentiated go-to-market positioning against established distributor networks. For Investors and Strategic Acquirers: REACH Phase-out mandates reshape the acquisition landscape toward metal-free tanning technology portfolios and validated supply chain traceability systems. Long-term viability centers on suppliers capable of bridging chrome-dependent industrial leather with automotive metal-free specifications across the projection horizon. Acquisition targets should demonstrate ZDHC MRSL conformance with blockchain-documented vegetable tannin sourcing. The signal to watch is automotive OEM procurement specification tightening beyond regulatory baselines, which accelerates synthetic tanning agent demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromium Chemical Production | LANXESS AG's captive chromite processing insulates margin exposure from South African ore supply disruptions. |
| Direct Chemical Leasing Models | Stahl Holdings pilots per-meter-finished-leather pricing that transfers effluent liability from tanneries to suppliers. |
| ZDHC MRSL Certification Investment | Third-party verification enables preferential access to Kering and LVMH luxury goods supply chains. |
| Enzymatic Pre-tanning Technology Development | Collagen-stabilizing enzymes reduce chrome dosing while maintaining automotive upholstery performance thresholds. |
| Geographic Expansion into Indian Export Clusters | Kanpur and Ambur tanneries seek REACH-compliant inputs for EU-bound footwear and leather goods exports. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, combining tannery plant managers, automotive OEM procurement leads, specialty chemical distribution channel partners, and technical R&D directors with secondary validation from customs and trade data, Cefic industry reports, SEC 10-K filings, and BIS certification registries. Bottom-up volume modeling from individual tannery cluster consumption patterns was triangulated against top-down chemical industry production disclosures to ensure convergence.
Across the analysis window, the forecasting framework segments by tanning agent chemistry type, end-use application, automotive OEM certification tier, and regional regulatory cluster to capture specification-driven demand divergence. CAGRs were derived from regression analysis of historical consumption patterns against REACH implementation timelines and automotive metal-free procurement adoption curves. Industry-specific inputs include chromite ore price volatility indices and ZDHC MRSL conformance penetration rates by leather goods brand.
Material uncertainties — South African chromite supply disruptions, EPA effluent guideline tightening timelines, and automotive OEM specification acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions around regulatory implementation pacing and substitution technology performance thresholds. Revision becomes warranted when automotive metal-free leather procurement specifications cross thresholds that displace chrome tanning agent demand faster than enzymatic hybrid systems can compensate.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Construction Chemical Market
Chemicals
Carbon Tetrachloride Market
Chemicals
Non PVC Plasticizers Market
Chemicals
Methylamines Market
Chemicals
Latin America Construction Chemicals Market
Chemicals
Monoisopropanolamine (MIPA) Market
Chemicals
Global Glycine Market
Chemicals
Anhydrous Hydrogen Fluoride Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Concrete Surface Treatment Chemicals Market
Chemicals
Calcium Borate Market
Chemicals
1-Methylimidazole Market
Chemicals
Negative Photoresist Chemicals Market
Chemicals
SLS and LABSA Market
Chemicals
Butylated Triphenyl Phosphate Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market