
 Acetate Salt Market | 2026-2036
Acetate Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Acetate Salt Market Analysis
Green chemistry process intensification is narrowing the cost gap between bio-based acetic acid feedstocks and conventional petrochemical routes for acetate salt production. Eastman Chemical Company leverages its integrated acetyl chain to sustain cost-advantaged positions across sodium and calcium acetate grades. Solvay anchors European pharmaceutical-grade supply through dedicated fermentation-derived product lines.
Acetate salts comprise metal or ammonium cations bonded to the acetate anion (CH3COO−), typically manufactured through neutralization of acetic acid with corresponding hydroxides or carbonates, and function as pH buffers, preservatives, and electrolyte replenacers across industrial and therapeutic applications. Sodium acetate dominates volume consumption in food preservation and concrete retardation, while calcium acetate commands premium positioning in renal dialysis and pharmaceutical buffering where USP-grade certification creates margin concentration. Ammonium acetate exhibits the fastest application expansion in HPLC mobile phase preparation and protein crystallization workflows.
FDA pharmaceutical cGMP standards, EPA Toxic Substances Control Act provisions, and REACH registration requirements collectively elevate barrier costs for new acetate salt entrants while mandating batch-level traceability for medical and food-contact grades. EFSA purity specifications for food additive E262 further segment the European market between technical and refined product tiers. Stakeholders must monitor feedstock volatility in acetic acid markets and pre-position compliance documentation ahead of anticipated revisions to pharmacopeial monographs.
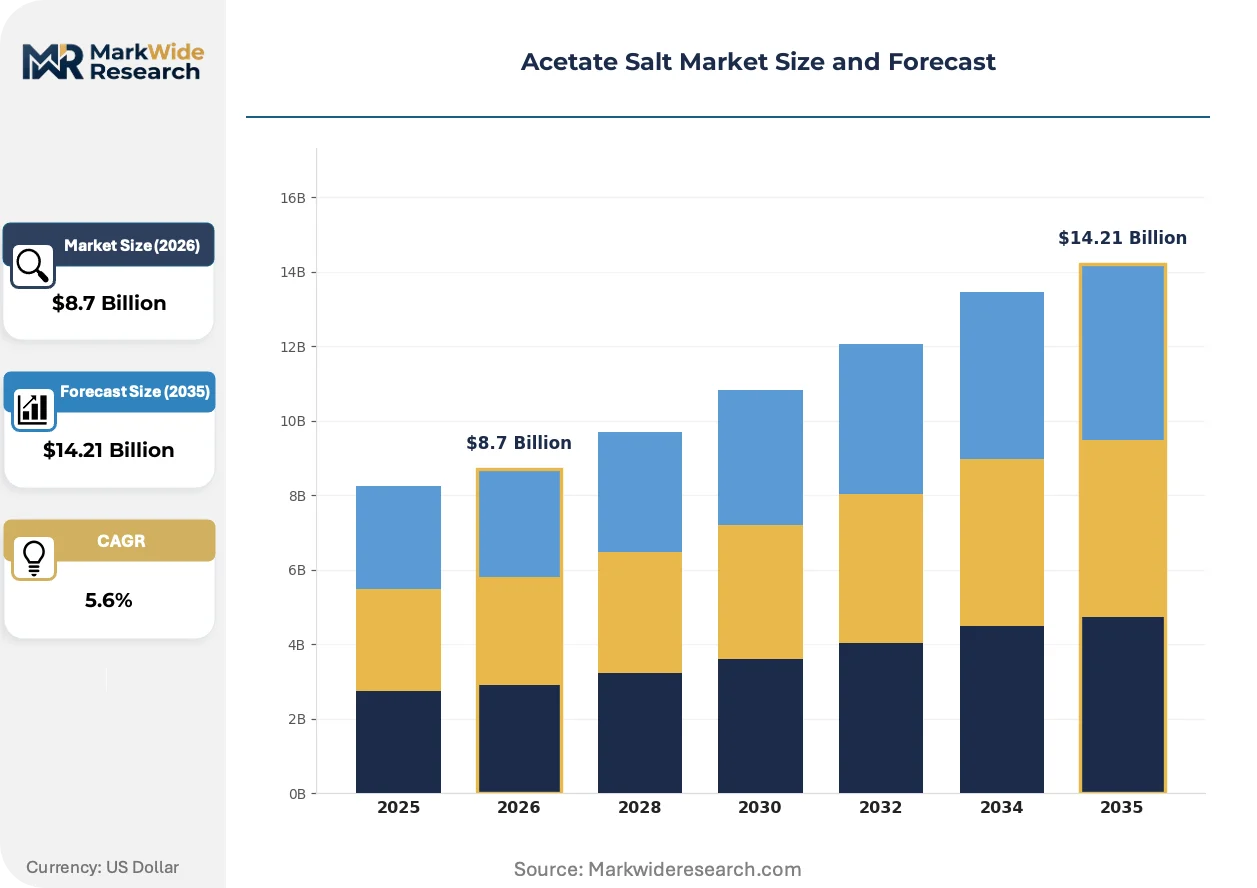
Market Dynamics
Pharmaceutical formulators in Germany and the United States are expanding acetate salt usage in intravenous electrolyte solutions and dialysis concentrates, tightening purity thresholds and reshaping supplier qualification requirements across the value chain.
Growth Catalysts
- REACH compliance tightening:European EFSA purity specifications for food additive E262 segment the market between technical and refined product tiers, elevating margin capture for certified producers.
- Renal dialysis demand:Calcium acetate commands premium positioning in renal dialysis applications where USP-grade certification creates concentrated margin pools for qualified suppliers.
- Asia-Pacific manufacturing corridor expansion:Expanding chemical processing capacity in China and India supports regional supply chain localization and reduces import dependency for acetate salt derivatives.
Market Restraints
- Acetic acid feedstock volatility:Price swings in petrochemical-derived acetic acid directly compress production margins for conventional acetate salt manufacturers.
- European supply concentration:Solvay anchors pharmaceutical-grade acetate supply through dedicated fermentation-derived product lines, creating single-source dependency risks for buyers.
- Substitution pressure from citrate salts:Sodium citrate and potassium citrate partially displace acetate salts in food preservation and buffering applications where milder taste profiles are preferred.
Strategic Opportunities
- Green chemistry process intensification:Bio-based acetic acid feedstocks are narrowing cost gaps with petrochemical routes, enabling margin expansion for early adopters of fermentation-derived inputs.
- HPLC mobile phase preparation:Ammonium acetate exhibits the fastest application expansion in protein crystallization workflows and analytical chemistry, opening specialized high-purity segments.
- Concrete retardation specification upgrades:Sodium acetate volume consumption in construction chemicals is rising as infrastructure durability standards tighten in India and Southeast Asia.
Industry Challenges
- Batch-level traceability mandates:FDA pharmaceutical cGMP standards and EPA Toxic Substances Control Act provisions require comprehensive documentation systems that strain mid-tier producers.
- Pharmacopeial monograph revision cycles:Anticipated updates to USP and EP monographs for acetate salts demand pre-positioned compliance investments before implementation deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetate Salt Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Acetate, Calcium Acetate, Ammonium Acetate, Lithio Acetate End Use Industry: Food & Beverage, Pharmaceuticals, Agriculture, Textiles Application: Preservative, pH Regulator, Flavors, Buffering Agent Form: Solid, Liquid, Powder, Granule |
| Companies Covered | BASF SE, Eastman Chemical Company, Merck KGaA, Solvay, Lanxess AG, CABB GmbH, Jost Chemicals, Shandong Kunda Biotechnology Co. Ltd., Niacet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetate Salt Market Emerging Trajectories
Green chemistry process intensification and regulatory purity escalation are compressing the competitive set while opening differentiated positioning for fermentation-derived and USP-certified product lines.
Continuous flow neutralization technology is virtualizing traditional batch reactor operations for acetate salt manufacturing. Pharmaceutical-grade producers in Switzerland and Germany are adopting these systems to reduce solvent waste and accelerate batch release timelines. This technology is virtualizing capital allocation patterns, favoring modular plant designs over large-scale centralized facilities.
REACH registration requirements and evolving EPA standards collectively elevate barrier costs for new acetate salt entrants while mandating expanded toxicological dossiers for existing substances. Industrial consequence includes forced consolidation among technical-grade producers unable to absorb compliance expenditures. Food-contact and medical-grade categories are responding through dedicated regulatory affairs teams and third-party certification pre-loading.
Specification-driven procurement is compressing supplier qualification cycles as pharmaceutical formulators consolidate vendor bases around dual-certified acetate salt sources. Large molecule drug manufacturers and dialysis concentrate blenders are displacing spot-market purchasing with multi-year supply agreements incorporating audit rights and dedicated capacity clauses. This pattern is most visible in the United States and Germany, where cGMP compliance costs have already eliminated marginal regional suppliers.
Acetate Salt Market Segmentation
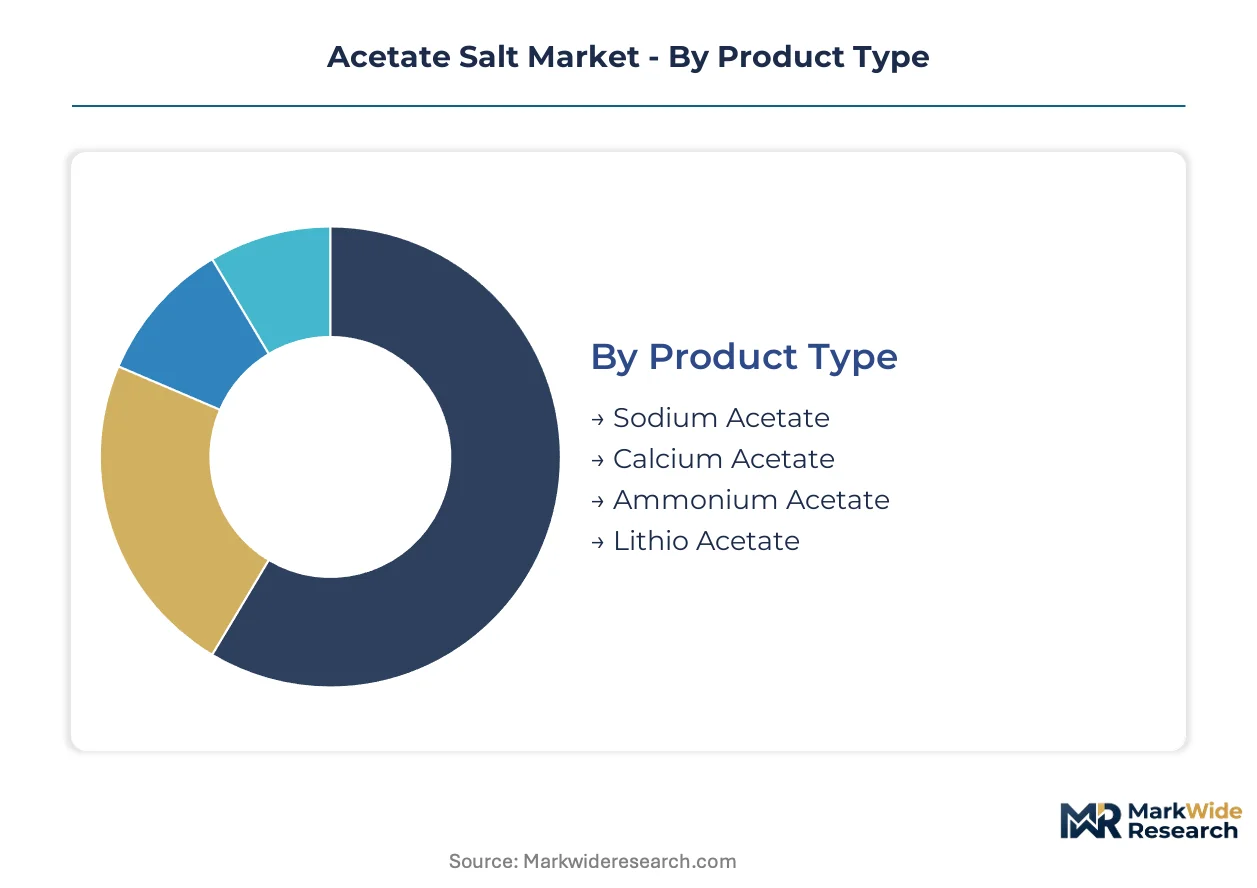
Acetate salt manufacturers navigate distinct specification tiers across pharmaceutical, food-grade, and industrial applications. Segmentation clarity enables suppliers to align purification investments with margin concentration points in dialysis concentrates, concrete retardation, and HPLC reagents.
Product Type:
The use-case spectrum spans from high-volume concrete additives to USP-certified dialysis inputs, with purity thresholds determining commercial positioning.
- Sodium Acetate:Manufactured through acetic acid neutralization with sodium hydroxide or carbonate, this salt functions primarily as a concrete retardation agent and food preservative. Demand concentrates in India's infrastructure build-out and Southeast Asian construction chemicals where durability specifications are tightening.
- Calcium Acetate:Produced to USP-grade monograph standards for renal dialysis concentrates and pharmaceutical buffering, this segment commands premium pricing through certification barriers. German and United States formulators are expanding intravenous electrolyte applications, tightening supplier qualification requirements.
- Ammonium Acetate:High-purity grades serve HPLC mobile phase preparation and protein crystallization workflows in analytical chemistry laboratories.
- Lithio Acetate:Specialized battery electrolyte and pharmaceutical intermediate applications drive small-volume, high-specification demand.
The dominant share belongs to Sodium Acetate, while Ammonium Acetate is closing the gap fastest.
End Use Industry:
Cost tier differentiation separates commodity chemical buyers from certified pharmaceutical and food-grade purchasers.
- Pharmaceuticals:USP-grade sodium and calcium acetates serve dialysis concentrate blending, intravenous electrolyte solutions, and active pharmaceutical ingredient buffering. FDA cGMP compliance and batch-level traceability mandates elevate supplier barriers.
- Food & Beverage:E262-designated sodium acetate functions as preservative and pH regulator in processed foods, with EFSA purity specifications segmenting technical from refined tiers.
- Agriculture:Technical-grade acetates serve as feed additives and soil amendment intermediates with lower certification burdens.
- Textiles:Dye bath pH control and mordant applications consume standard-grade sodium acetate in bulk volumes.
Pharmaceuticals capture the steepest margin expansion, while Food & Beverage maintains volume leadership.
Application:
Customer type segmentation distinguishes specification-driven procurement from spot-market purchasing.
- Buffering Agent:Pharmaceutical-grade acetates stabilize pH in biologic drug formulations and diagnostic reagents, with USP and EP monograph compliance mandatory for supplier qualification.
- Preservative:Food additive E262 applications in processed meats and baked goods require EFSA-certified purity tiers for European market access.
- pH Regulator:Industrial water treatment and textile processing utilize technical-grade specifications with minimal regulatory documentation.
- Flavors:Sodium diacetate derivatives provide vinegar flavoring in snack foods and condiments.
Buffering Agent applications command premium positioning, while Preservative volumes scale highest.
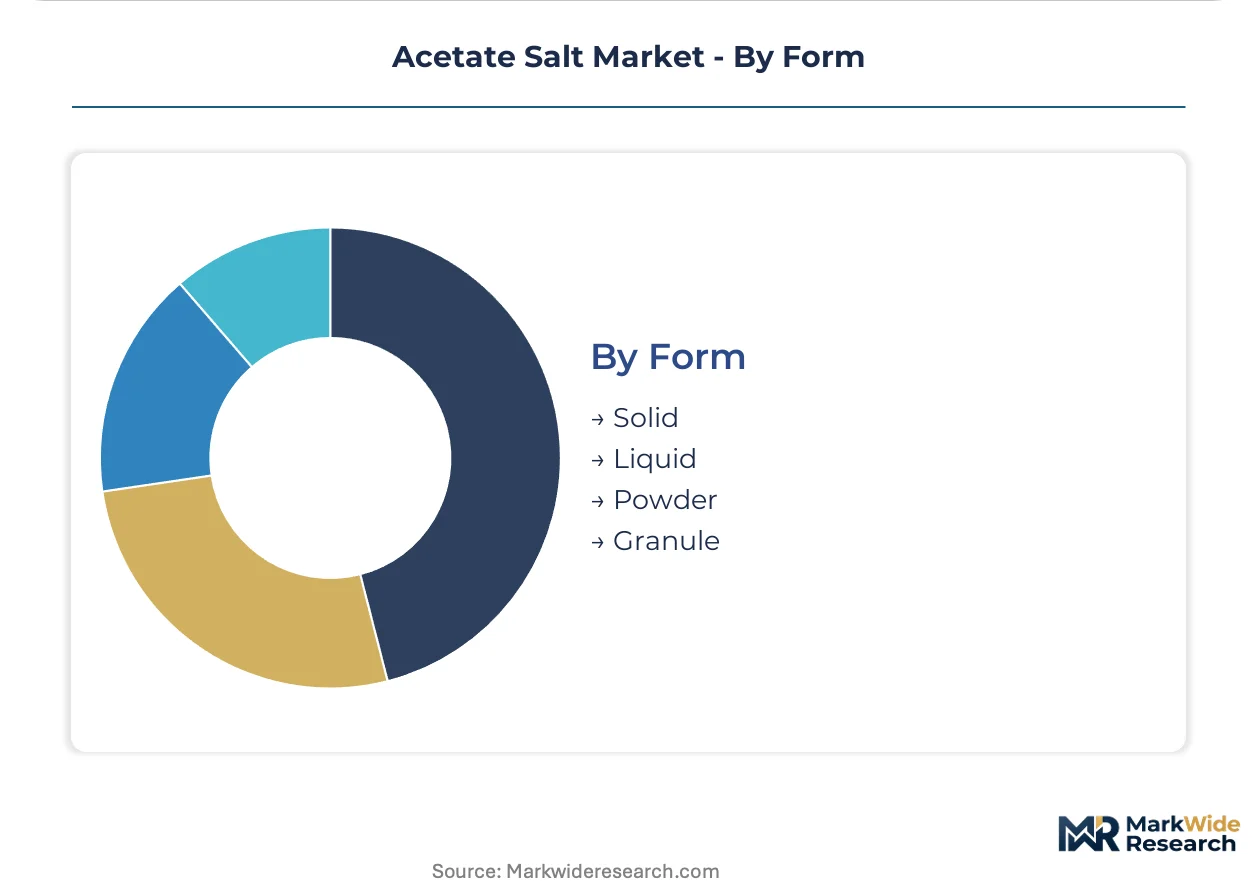
Form:
Supply concentration patterns favor solid and powder formats for transport efficiency and shelf stability.
- Solid:Crystalline sodium acetate trihydrate dominates concrete retardation and food preservation with established handling infrastructure.
- Powder:Anhydrous grades serve pharmaceutical compounding and rapid-dissolution applications where moisture content is critical.
- Granule:Low-dust formulations target automated feed and fertilizer blending operations.
- Liquid:Pre-dissolved solutions reduce handling steps in dialysis concentrate manufacturing and large-volume industrial processes.
Solid forms retain the largest installed base, though Liquid is gaining share fastest in pharmaceutical contract manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulators and construction chemical buyers concentrate demand across four distinct national markets, each shaped by divergent regulatory stringency and feedstock access conditions.
United States
FDA cGMP standards and EPA Toxic Substances Control Act provisions govern pharmaceutical-grade acetate salt procurement for dialysis concentrate blenders in Indianapolis and Boston. Batch-level traceability mandates eliminate marginal suppliers, consolidating vendor relationships around dual-certified sources. The Southeast chemical processing corridor, particularly Louisiana and Texas, hosts expanding fermentation-derived acetic acid capacity serving domestic acetate salt manufacturers.
Germany
REACH registration requirements and EFSA purity specifications for food additive E262 segment technical from refined product tiers, elevating margin capture for certified producers. Pharmaceutical formulators in Frankfurt and Munich expand intravenous electrolyte applications, tightening supplier qualification cycles. The Rhine-Ruhr industrial cluster anchors European pharmaceutical-grade supply through dedicated fermentation-derived product lines.
China
Expanding chemical processing capacity in Jiangsu and Shandong provinces supports regional supply chain localization for acetate salt derivatives. MIIT industrial standards and evolving GB purity specifications for food-contact grades create compliance differentiation between coastal exporters and inland technical-grade producers. The Yangtze River Delta concentration of acetic acid manufacturing enables backward integration into sodium and calcium acetate production.
India
BIS certification requirements and CDSCO pharmaceutical standards govern import substitution strategies for dialysis-grade calcium acetate. Infrastructure durability standards in Maharashtra and Gujarat drive sodium acetate consumption for concrete retardation applications. The Gujarat chemical belt, anchored by Dahej and Vadodara manufacturing zones, hosts expanding neutralization capacity serving domestic construction chemical formulators.
Acetate Salt Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers: integrated petrochemical conglomerates with captive acetic acid supply, dedicated acetate salt manufacturers with pharmacopeial certifications, and regional technical-grade producers serving construction and textile applications. Consolidation pressures favor scale-driven participants capable of absorbing REACH and FDA compliance expenditures. Dominant competitive moves include fermentation-derived feedstock transitions and multi-year supply agreements incorporating audit rights and dedicated capacity clauses.
Among integrated chemical conglomerates, BASF SE and Eastman Chemical Company exemplify archetypes with upstream acetic acid control and downstream acetate salt finishing capabilities. Solvay occupies a position within the European pharmaceutical-grade tier, anchoring fermentation-derived supply for dialysis and intravenous electrolyte applications. These three entities represent the concentration of regulatory-certified capacity serving USP-grade and EP-grade market segments.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Merck KGaA |
| Solvay |
| Lanxess AG |
| CABB GmbH |
| Jost Chemicals |
| Shandong Kunda Biotechnology Co. Ltd. |
| Niacet |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese acetic acid derivatives is compressing margins for technical-grade acetate salt producers while simultaneously strengthening pricing power for USP-certified suppliers in Germany and the United States. This utilization divergence is forcing mid-tier manufacturers to choose between certification investments and volume-driven commoditization strategies.
Pricing Analysis
Cost-plus contracts indexed to methanol and ethylene feedstock benchmarks dominate long-term supply agreements between pharmaceutical formulators and certified acetate salt producers. Price differentiation rests on USP-grade certification and fermentation-derived provenance, with premium tiers capturing margin pools in dialysis concentrates. Pricing pressure stems from bio-based acetic acid cost convergence eroding petrochemical route advantages. Spot-market buyers in construction chemicals exhibit highest price sensitivity, while dialysis concentrate blenders prioritize supply security over unit economics.
Supply Chain Analysis
Upstream acetic acid supply concentrates in the United States Gulf Coast, China's Yangtze River Delta, and Germany's Rhine-Ruhr corridor, with each hub feeding distinct acetate salt specification tiers. Production draws from methanol carbonylation and fermentation-derived feedstocks, with purity requirements determining facility qualification. Single-source vulnerability risks concentrate in European pharmaceutical-grade supply anchored by Solvay's fermentation lines. Distribution runs through regional chemical distributors for technical grades and direct manufacturer relationships for certified pharmaceutical tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where FDA cGMP and REACH compliance costs create defensive moats that marginalize uncertified competitors and consolidate vendor relationships around dual-qualified incumbents.
For Market Incumbents: Harden certification barriers by pre-positioning compliance documentation ahead of anticipated USP and EP monograph revisions. Anchor capacity expansion in the Southeast United States chemical corridor to exploit fermentation-derived acetic acid feedstock localization. Citrate salt substitution in food preservation represents the primary demand-side threat requiring proactive customer retention investments.
For New Entrants and Emerging Players: Mid-tier pharmaceutical-grade acetate salts in India and Southeast Asia represent the most penetrable entry point where CDSCO and BIS certification burdens remain below FDA-EU parity. Target contract manufacturing organizations serving generic drug formulators with lower qualification cycle intensity. A fermentation-derived feedstock positioning offers the strongest go-to-market differentiation against petrochemical incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward regional champions with existing pharmacopeial certifications and underutilized neutralization capacity in high-growth manufacturing corridors. Long-term viability hinges on regulatory compliance scalability rather than feedstock cost optimization alone. Watch for REACH registration deadline clustering as an inflection signal for forced consolidation among technical-grade producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation-Derived Acetic Acid | Captures margin expansion as bio-based feedstock costs converge with petrochemical routes. |
| USP-Grade Certification Pre-Loading | Positions suppliers ahead of FDA cGMP batch-traceability mandate expansions in dialysis applications. |
| Multi-Year Supply Agreement Structuring | Locks in pharmaceutical formulator relationships through audit rights and dedicated capacity clauses. |
| Continuous Flow Neutralization Technology Adoption | Reduces solvent waste and accelerates batch release timelines for Swiss and German producers. |
| Regional Supply Chain Localization in India | Addresses CDSCO import substitution strategies for dialysis-grade calcium acetate demand growth. |
Methodological Framework
Desk research of customs trade databases, SEC 10-K filings, and ECHA REACH registration records preceded structured interviews with pharmaceutical procurement managers, dialysis concentrate blenders, chemical plant operations directors, and construction chemical formulators. Primary fieldwork combined with secondary validation across ACC and Cefic industry reports enabled bottom-up capacity modeling and top-down demand triangulation for acetate salt derivatives.
Fixed assumptions across the analysis window include sustained REACH compliance stringency and continued acetic acid feedstock cost convergence between bio-based and petrochemical routes. Modeled segmentation spans pharmaceutical grade tier, food-grade certification status, end-use industry concentration, and regional production hub clustering. CAGRs were derived from production capacity expansion schedules cross-referenced against end-use demand elasticity coefficients in dialysis and construction chemical applications.
Practitioners should monitor acetic acid feedstock volatility spikes and pharmacopeial monograph revision announcements for early signals requiring forecast adjustment. Cross-checking against ECHA registration database updates and FDA warning letter trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
Butachlor Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Potassium Hydrogen Sulfite Market
Bulk Chemicals
North America Acrylamide Monomer Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
Benzyl Chloride Market
Bulk Chemicals
Copper Sulphate Market
Bulk Chemicals
Nickel Nitrate Hexahydrate Market
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
Diketene Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
Calcium Carbonate Market
Bulk Chemicals
Isobutene Market
Bulk Chemicals
Calcium Nitrate Market