
 Ammonium Sulfate Food Grade Market | 2026-2036
Ammonium Sulfate Food Grade Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Sulfate Food Grade Market Analysis
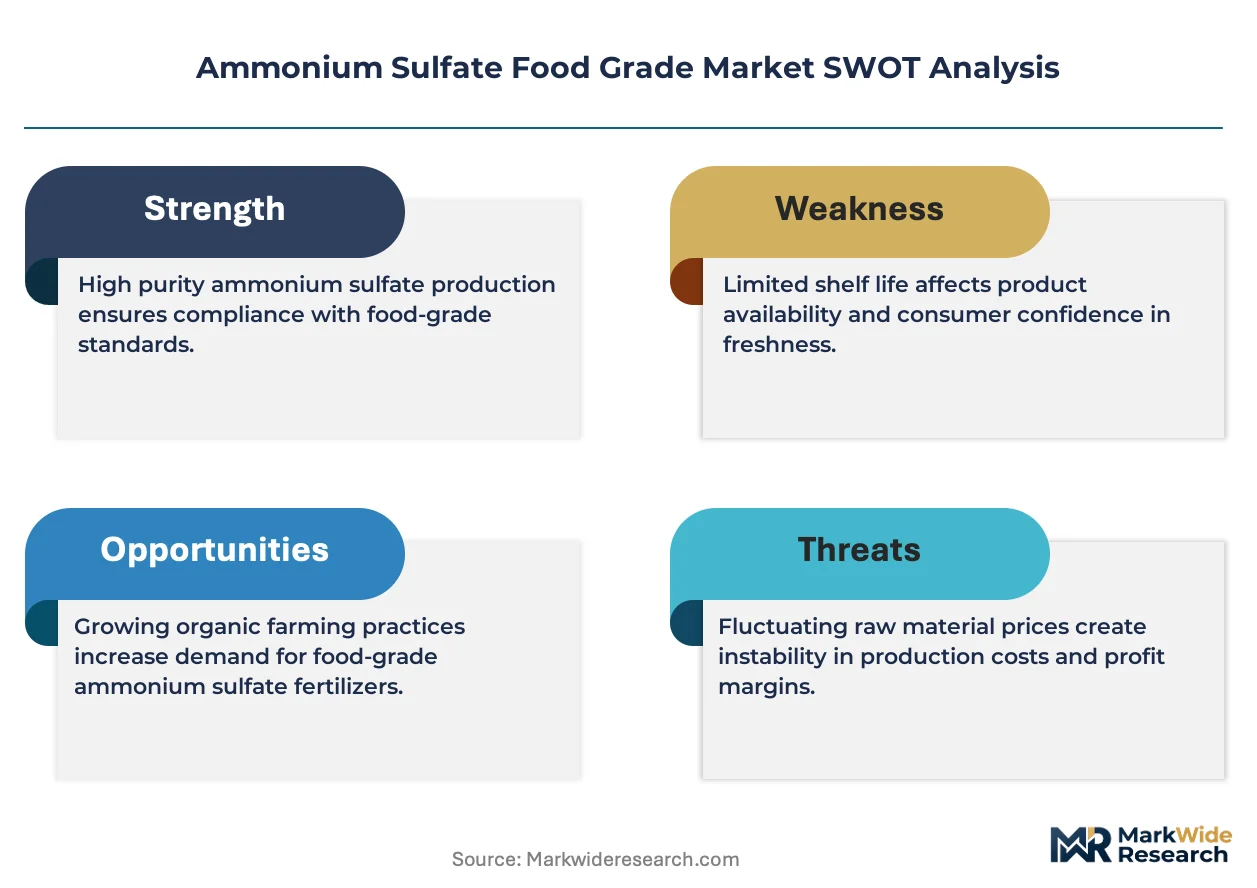
REACH is recalibrating the cost-of-entry calculus for ammonium sulfate food grade suppliers seeking European market access. BASF SE leverages its integrated Ludwigshafen complex to sustain cost advantages across multiple purity grades. Evonik Industries AG anchors its position through specialized crystallization technology that meets pharmaceutical-adjacent food standards. Tata Chemicals Ltd. competes on bulk volume from its Indian manufacturing base while navigating divergent national purity protocols.
Ammonium sulfate food grade is a purified inorganic salt with minimum purity specifications typically exceeding 99 percent, produced through controlled neutralization of sulfuric acid with ammonia and subsequent crystallization or granulation for use as a regulated food additive, dough conditioner, and processing aid. The granular product type dominates volume flows into agriculture and food processing channels where flowability and dust control matter. Powder grades command premium positioning in nutraceutical applications where dissolution rate and particle uniformity determine formulation performance. Crystal forms occupy specialized niches in high-purity laboratory and pharmaceutical-food crossover segments where visual inspection and batch traceability requirements intensify.
The European Food Safety Authority sets maximum residue and contaminant thresholds that directly determine which production batches qualify for food-grade designation. China's National Medical Products Administration and the US Food and Drug Administration maintain parallel but non-harmonized purity standards that fragment certification requirements for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of manufacturing location decisions and inventory segmentation strategies.
Market Dynamics
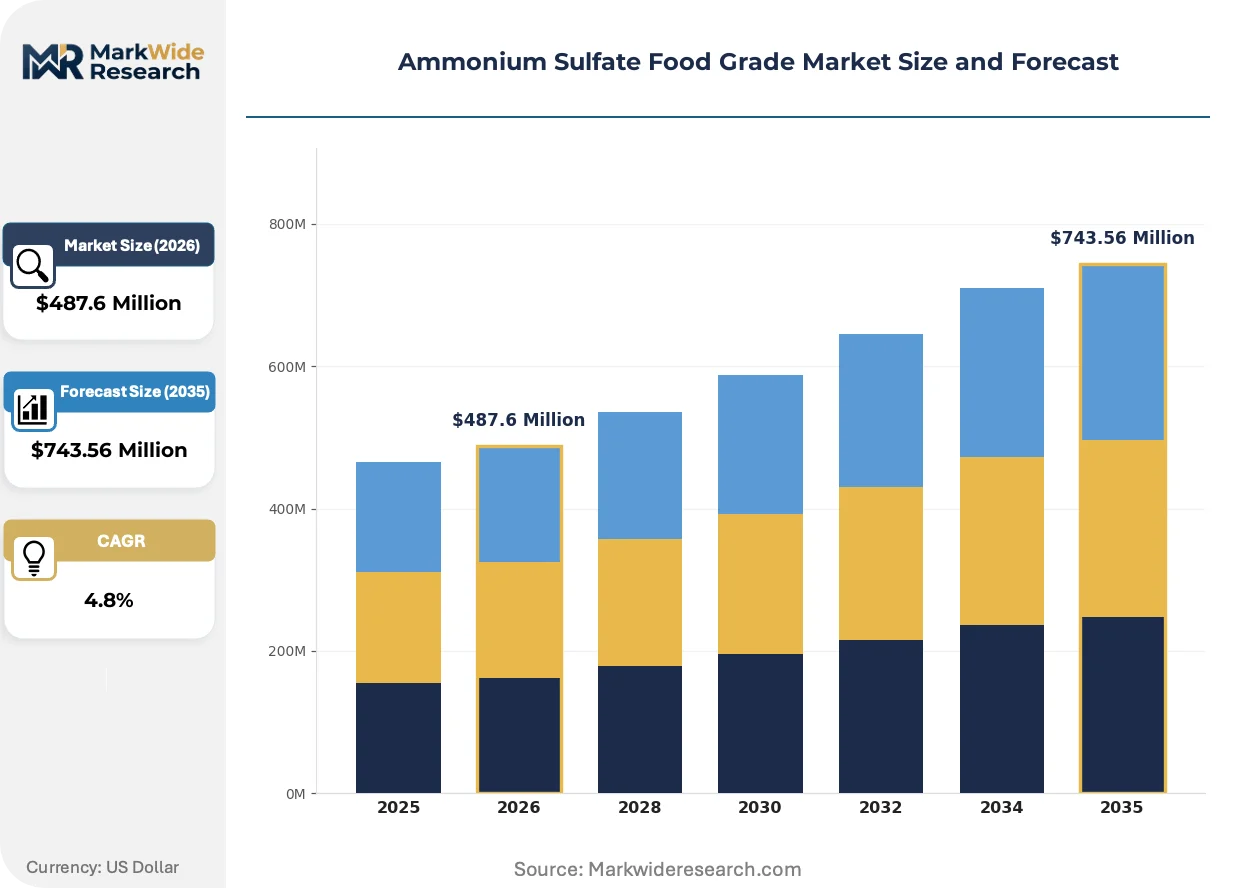
REACH compliance is recalibrating the cost-of-entry calculus for ammonium sulfate food grade suppliers seeking European market access. The regulation's documentation burdens and purity threshold adjustments are forcing capital reallocation toward certification infrastructure.
Growth Catalysts
- Clean-label ingredient protocols:Food processors in Germany's industrial chemical corridor are reformulating with ammonium sulfate to replace synthetic preservatives. EFSA maximum residue thresholds validate this substitution pathway.
- Dual carbon goals:China's eastern processing hubs are integrating ammonium sulfate into carbon-neutral fertilizer-food crossover supply chains. NMPA standards accommodate this dual-use positioning.
- Crystallization technology advancement:Pharmaceutical-adjacent food standards are pulling higher-purity grades into nutraceutical applications. Specialized crystallization methods enable particle uniformity specifications previously unattainable.
Market Restraints
- Ammonia feedstock volatility:Natural gas price swings directly compress margins for neutralization-process manufacturers. Ludwigshafen-style integrated complexes partially insulate against this exposure.
- Supply concentration risk:Bulk volume production concentrates in Indian and Chinese manufacturing bases. Divergent national purity protocols fragment inventory segmentation strategies.
- Substitution threat from ammonium phosphate:Dough conditioning applications face displacement where phosphate functionality suffices. FDA GRAS status for alternatives accelerates this erosion.
Strategic Opportunities
- Underpenetrated laboratory-grade segment:Crystal forms for high-purity laboratory and pharmaceutical-food crossover niches carry visual inspection and batch traceability premiums. Visual clarity standards exclude commodity suppliers.
- EU Green Deal alignment:Carbon footprint documentation requirements favor producers with renewable ammonia sourcing. REACH-compliant producers can capture this regulatory tailwind.
- Direct-to-formulator distribution:Nutraceutical compounders are bypassing traditional chemical distributors for specification-controlled supply. Powder grades with dissolution-rate certification enable this channel shift.
Industry Challenges
- Analytical chemistry skill scarcity:Contaminant detection at parts-per-billion levels requires specialized chromatography expertise. Smaller manufacturers face recruitment bottlenecks for EFSA-compliant batch testing.
- Crystallizer capex intensity:Pharmaceutical-adjacent food standards demand stainless-steel crystallization trains with clean-in-place validation. Brownfield sites face write-off decisions against greenfield investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Sulfate Food Grade Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Solution, Crystals Application: Fertilizers, Food Additives, Animal Feed, Soil Amendments Packaging Type: Bulk Bags, 50 kg Bags, Drums, Totes End User: Agriculture, Food Processing, Nutraceuticals, Horticulture |
| Companies Covered | BASF SE, Evonik Industries AG, Lanxess AG, Tata Chemicals Ltd., Honeywell International Inc., Yara International, Sumitomo Chemical Co., Ltd., Nutrien Ltd., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Sulfate Food Grade Market Emerging Trajectories
Continuous crystallization systems are displacing batch processing as the dominant production paradigm. This shift compresses cycle times while tightening particle size distribution control.
Membrane filtration pretreatment is electrifying impurity removal before crystallization stages. European nutraceutical formulators are adopting this technology rapidly to meet EFSA contaminant thresholds. The process is electrifying competitive positioning for suppliers with installed membrane capacity against conventional neutralization-only producers.
REACH substance evaluation workflows are extending documentation timelines for food-grade designation renewals. Industrial consequence includes inventory pre-positioning ahead of evaluation deadlines. Powder-grade suppliers with existing dossier depth are capturing volume from competitors facing evaluation gaps.
Specification-driven procurement is compressing supplier qualification cycles. Nutraceutical compounders in Germany are unbundling technical service from material supply, paying premiums for certificates of analysis with full traceability chains. This pattern is most visible in the Rhine-Main corridor where pharmaceutical-grade sourcing discipline transfers to food-grade inputs.
Ammonium Sulfate Food Grade Market Segmentation
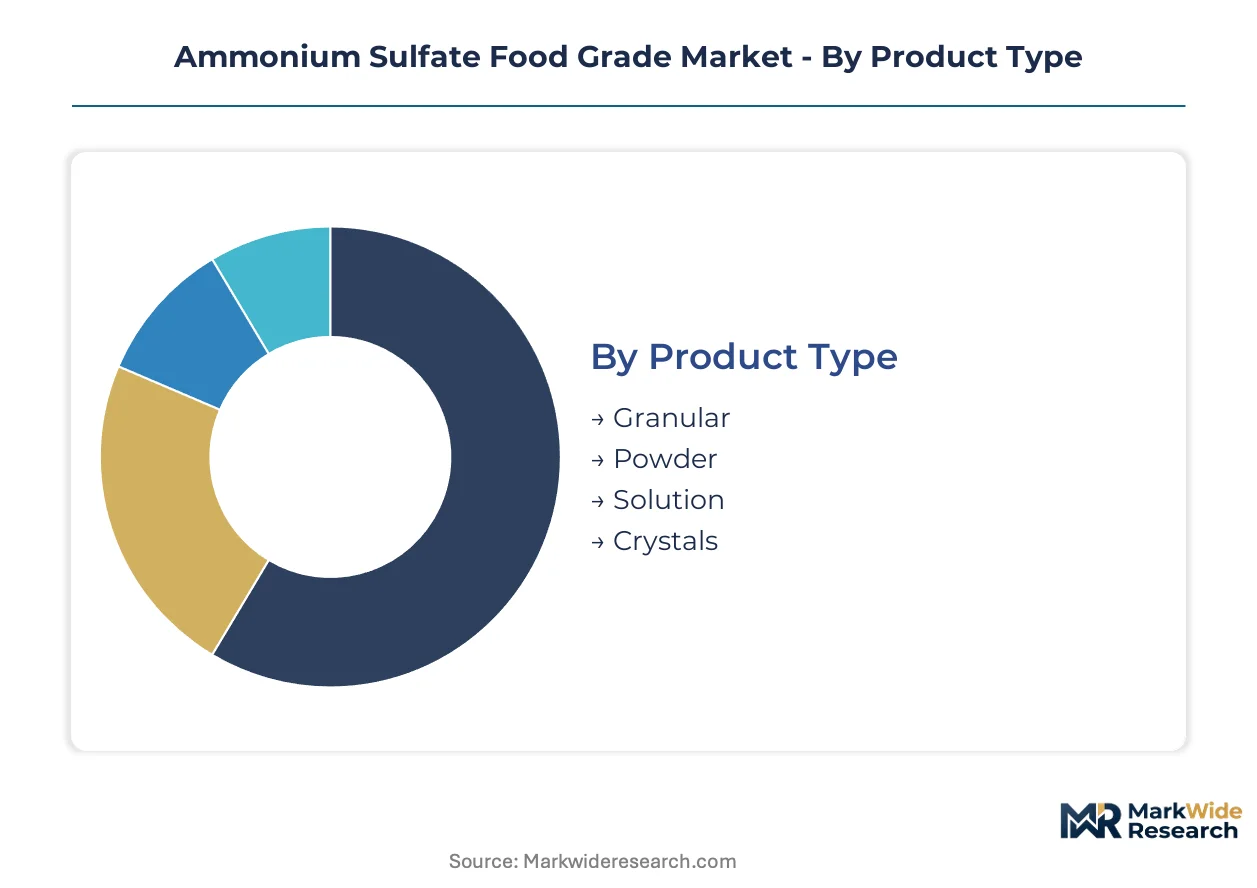
Product form and packaging configuration directly determine which regulatory pathways ammonium sulfate food grade must navigate. Specification requirements vary sharply between bulk agricultural flows and precision nutraceutical dosing, forcing manufacturers to segment production lines and certification dossiers.
Product Type:
Upgrade cycles favor higher-purity crystalline forms as food processors replace legacy granular stocks with specification-controlled alternatives.
- Granular:Dense, free-flowing particles engineered for mechanical handling and minimal dust generation. Demand concentrates in Germany's industrial chemical corridor where automated dosing systems in large-scale bakeries require consistent flow characteristics.
- Powder:Fine-milled particles with rapid dissolution profiles meeting pharmaceutical-adjacent food standards. Nutraceutical compounders in the Rhine-Main corridor pay premiums for dissolution-rate certification and particle uniformity documentation.
- Solution:Pre-dissolved liquid form eliminating hydration variables in continuous processing lines.
- Crystals:Visual clarity and geometric regularity enabling batch traceability through visual inspection protocols.
Volume placements concentrate in Granular; the faster expansion belongs to Powder.
Application:
Cost tier separation drives procurement patterns, with food-grade certification commanding substantial premiums over agricultural grades.
- Fertilizers:Dual-use positioning leverages ammonium sulfate's nitrogen-sulfur content for crop nutrition. China's eastern processing hubs are integrating carbon-neutral certification into fertilizer-food crossover supply chains under NMPA dual-use standards.
- Food Additives:Regulated dough conditioning and pH buffering functions replacing synthetic preservatives. EFSA maximum residue thresholds validate clean-label substitution pathways in German bakery reformulations.
- Animal Feed:Ruminant nutrition applications requiring contaminant thresholds below agricultural fertilizer grades.
- Soil Amendments:Sulfur-deficiency correction in high-value horticultural substrates.
Revenue margins peak in Food Additives; volume scale dominates in Fertilizers.
Packaging Type:
Customer type determines packaging configuration, with direct-to-formulator channels bypassing traditional distributor repackaging.
- Bulk Bags:One-ton flexible intermediate bulk containers minimizing handling costs for high-volume agricultural offtake.
- 50 kg Bags:Standard woven polypropylene units serving mid-scale food processors and regional distributors.
- Drums:Sealed steel or fiber containers protecting hygroscopic powder grades from moisture ingress during extended storage.
- Totes:Intermediate rigid intermediate bulk containers with discharge valves enabling semi-bulk handling in nutraceutical clean rooms.
Unit economics favor Bulk Bags at scale; specification-controlled supply is shifting toward Totes and Drums.
End User:
Geographic supply concentration shapes service models, with proximity to manufacturing clusters determining technical support intensity.
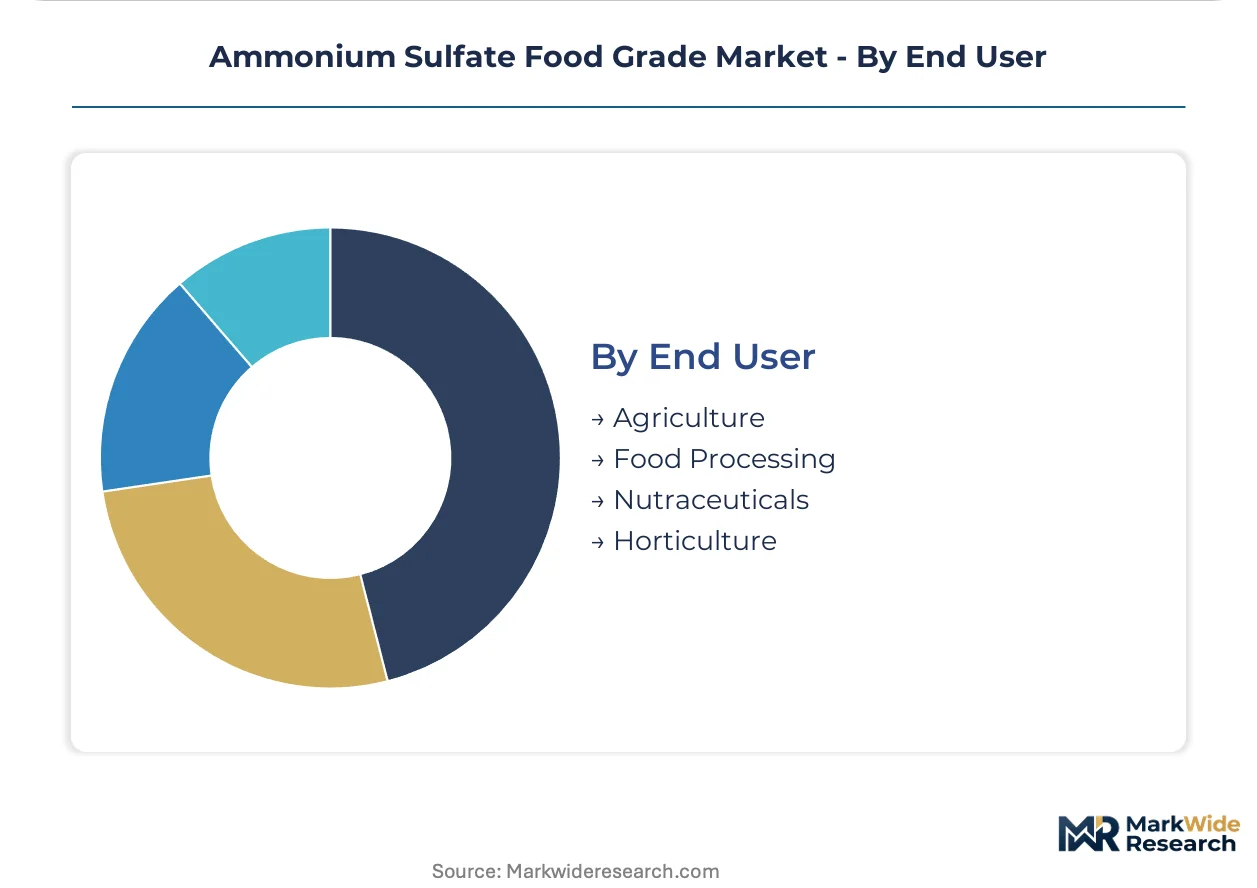
- Agriculture:Broadacre and specialty crop applications consuming volume production from Indian and Chinese manufacturing bases. Divergent national purity protocols fragment inventory segmentation strategies between fertilizer and food-grade channels.
- Food Processing:Industrial bakeries and prepared food manufacturers requiring EFSA-compliant batch documentation. REACH substance evaluation workflows are extending qualification timelines, forcing inventory pre-positioning ahead of deadline clusters.
- Nutraceuticals:Dietary supplement and functional food compounders demanding certificates of analysis with full traceability chains.
- Horticulture:Greenhouse and controlled-environment agriculture requiring sulfur supplementation in precision irrigation systems.
Procurement concentration sits with Food Processing; Nutraceuticals is climbing the fastest as specification premiums expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern processing hubs concentrate capacity within coastal special economic zones offering preferential tax treatment for food-grade chemical exports. Germany's industrial chemical corridor anchors European supply through integrated Ludwigshafen-style complexes. India's bulk manufacturing bases compete on volume while navigating divergent national purity protocols.
China
Dual carbon goals are accelerating carbon-neutral certification integration into fertilizer-food crossover supply chains. NMPA standards accommodate this dual-use positioning with adjusted purity thresholds. Shanghai and Jiangsu province processing hubs are expanding crystallization capacity to serve nutraceutical export demand.
Germany
Clean-label bakery reformulations are substituting ammonium sulfate for synthetic preservatives across industrial-scale production. REACH substance evaluation workflows extend documentation timelines for food-grade designation renewals. The Rhine-Main corridor hosts specification-driven procurement from pharmaceutical-grade sourcing disciplines.
United States
FDA GRAS status for dough conditioning applications maintains steady food additive demand despite phosphate substitution threats. The FDA maintains parallel but non-harmonized purity standards that fragment certification requirements. Midwest agricultural processing clusters consume volume flows for fertilizer-food dual-use positioning.
India
Bulk volume production from Gujarat and Maharashtra manufacturing bases competes on cost while navigating FSSAI purity protocols. The country's national food regulator maintains contaminant thresholds below agricultural fertilizer grades for food-grade designation. Mumbai-Pune chemical corridor facilities are upgrading analytical chemistry capabilities for export certification.
Japan
Pharmaceutical-adjacent food standards are pulling higher-purity grades into nutraceutical applications through specialized crystallization methods. METI industrial policy supports precision chemical manufacturing upgrades. Osaka-Kobe industrial zone producers are investing in membrane filtration pretreatment for EFSA-aligned export batches.
Ammonium Sulfate Food Grade Market Vendor Landscape
German producers anchor one tier; Indian and Chinese specialists hold volume-driven positions. The vendor base organizes around three strategic archetypes: integrated chemical conglomerates with captive ammonia supply, mid-scale crystallization specialists, and bulk commodity processors. Capacity expansion and REACH compliance certification represent the dominant competitive moves as qualification timelines extend.
Within the integrated conglomerate tier, BASF SE and Evonik Industries AG exemplify archetypes leveraging Ludwigshafen-style complex integration for cost insulation against ammonia feedstock volatility. Tata Chemicals Ltd. occupies a position representing volume-scale competition from Indian manufacturing bases navigating divergent national purity protocols. These three anchors illustrate how geographic origin and corporate structure map to strategic positioning: SE and AG suffixes signal European public company governance, while Ltd. denotes Indian corporate form.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Lanxess AG |
| Tata Chemicals Ltd. |
| Honeywell International Inc. |
| Yara International |
| Sumitomo Chemical Co., Ltd. |
| Nutrien Ltd. |
| Merck KGaA |
| Others |
Supply Flow & Price Mechanics
Ammonia feedstock volatility propagates through three distinct pricing tiers as Ludwigshafen-style integrated complexes capture margin insulation unavailable to standalone neutralization processors. Natural gas price swings compress returns at commodity-grade producers while crystallization specialists command specification premiums downstream.
Pricing Analysis
Lead-time compression commands measurable premiums in the Rhine-Main corridor where nutraceutical compounders bypass distributor inventories. Three-tier pricing structure across pharmaceutical-adjacent, standard food-grade, and agricultural-crossover levels separates certificate-of-analysis depth from basic contaminant screening. Pricing pressure stems from ammonium phosphate substitution in dough conditioning applications where FDA GRAS status accelerates displacement. Agricultural buyers exhibit highest price sensitivity; nutraceutical formulators absorb premiums for batch traceability documentation.
Supply Chain Analysis
Specialty ammonia supply rests on German and Chinese petrochemical complexes with captive production, while Indian manufacturers draw from merchant ammonia markets. Sulfuric acid, natural gas, and crystallization equipment constitute critical input dependencies. Single-source vulnerability concentrates in membrane filtration pretreatment systems where European nutraceutical demand outpaces installed capacity. Distribution runs through chemical distributor networks for bulk agricultural flows; direct-to-formulator channels are displacing intermediaries in specification-controlled segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH substance evaluation workflows erect documentation barriers that favor incumbents with existing dossier depth. EFSA maximum residue thresholds function as a moat against commodity-grade entrants lacking analytical chemistry infrastructure.
For Market Incumbents: Deploy crystallization capacity additions in China's eastern processing hubs to capture nutraceutical export demand growth. Ammonium phosphate substitution threatens dough conditioning volumes; backward integration into renewable ammonia sourcing aligns with EU Green Deal procurement preferences and insulates against feedstock volatility. Channel control through direct-to-formulator relationships in Germany's industrial chemical corridor protects specification premiums from distributor margin compression. For New Entrants and Emerging Players: E-commerce-enabled direct sampling to mid-scale nutraceutical compounders bypasses entrenched distributor relationships. Laboratory-grade crystal forms remain underpenetrated relative to commodity granular volumes, with visual clarity standards excluding established suppliers lacking pharmaceutical-adjacent certification. Target carbon-neutral fertilizer-food crossover positioning under NMPA dual-use standards as the most penetrable entry vector. For Investors and Strategic Acquirers: REACH evaluation deadline clustering is the leading indicator that inventory pre-positioning demand will concentrate among compliant producers. Mid-scale crystallization specialists with installed membrane capacity represent the optimal acquisition archetype over bulk commodity processors facing margin compression. Watch for ammonia feedstock contract renegotiations as the signal for margin inflection across integrated versus non-integrated producer tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Ammonia | EU Green Deal alignment secures preferential procurement positioning from carbon-conscious formulators. |
| Membrane Filtration Pretreatment Installation | EFSA contaminant threshold compliance electrifies competitive positioning against neutralization-only rivals. |
| Direct-to-Formulator Channel Development | Rhine-Main nutraceutical compounders pay premiums for certificates of analysis with full traceability chains. |
| Crystallization Capacity Expansion | Shanghai and Jiangsu province hubs capture pharmaceutical-adjacent food standard demand from export markets. |
| REACH Dossier Depth Investment | Substance evaluation workflow preparation captures volume from competitors facing documentation gaps. |
Methodological Framework
Multi-period observation of REACH evaluation timelines, ammonia feedstock contract structures, and crystallization technology adoption anchored the trend analysis, supplemented by interviews with plant managers at integrated chemical complexes, procurement leads at German bakery reformulation programs, technical R&D directors at membrane filtration equipment suppliers, and distribution channel partners in China's eastern processing hubs. Secondary validation drew from EFSA contaminant threshold documentation, customs and trade data for ammonium sulfate flows, SEC 10-K filings from diversified chemical producers, and Cefic industry reports. Bottom-up volume modeling triangulated against top-down market sizing across purity grade tiers.
Input-output matrices mapped ammonia-sulfuric acid neutralization capacity through crystallization stage outputs across granular, powder, and crystal product forms, with end-use industry demand elasticity and regional production hub cost differentials as segmentation dimensions. CAGRs were derived from regression analysis of historical purity-grade pricing spreads projected across the analysis window. Forecast inputs incorporated natural gas price scenario modeling and EFSA maximum residue threshold revision probabilities.
The model holds under stable REACH evaluation schedules and ammonia feedstock contract renewal patterns; deviation in dual carbon policy acceleration or phosphate substitution adoption rates would shift volume projections. Forecasts reflect documented assumptions about crystallization technology diffusion and regulatory harmonization timelines. Ammonia price volatility, REACH deadline clustering, and nutraceutical formulation substitution patterns warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Potassium Cryolite Market
Bulk Chemicals
Asia-Pacific Formic Acid Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
Chloroacetophenone Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Cyclohexylamine Market
Bulk Chemicals
Barium Nitrate Market