
 India Iodine Market | 2026-2036
India Iodine Market Size, Share, and Industry Trends Forecast 2026-2036
India Iodine Market Foresight
Pharmaceutical buyers are unwinding historical reliance on feed-grade offtake as contrast-agent and API formulators capture larger volume shares. Salvi Chemical Industries Ltd. leverages its coastal brine access to anchor iodine extraction capacity on the west coast. Calibre Chemicals Pvt. Ltd. sustains downstream integration into potassium iodide and iodate salts for domestic pharma customers. Eskay Iodine Pvt. Ltd. competes through specialized refining that meets IP-grade specifications for injectable applications.
Iodine is a halogen element extracted primarily from caliche deposits and brine solutions, with commercial grades ranging from technical to pharmaceutical and reagent purities exceeding 99.8 percent; it functions as an essential precursor in X-ray contrast media, disinfectants, and thyroid hormone synthesis. Inorganic iodine salts dominate current volume flows due to entrenched demand from sanitation and pharmaceutical compounding, while iodine derivatives represent the fastest-expanding structural pocket as contrast-agent manufacturers seek higher-value molecular intermediates. Organic iodine compounds command premium positioning in radiology applications where purity thresholds and regulatory certification create defensible margin pools.
BIS certification requirements and CDSCO pharmaceutical-grade standards constrain import quality and shape domestic manufacturing investments across the value chain. The PLI scheme for bulk drugs and the FSSAI's iodization mandates for edible salt create dual regulatory tailwinds that reinforce local production economics. Stakeholders must monitor how BIS's evolving purity specifications and CDSCO's active-ingredient traceability rules alter sourcing strategies for imported versus captive iodine refining.
Market Dynamics
Pharmaceutical formulators in Gujarat and Maharashtra are displacing historical feed-grade offtake as contrast-agent and API applications capture larger volume shares, reshaping domestic sourcing economics through CDSCO certification requirements and PLI scheme incentives.
Growth Catalysts
- PLI Scheme for Bulk Drugs:Production-linked incentives for active pharmaceutical ingredients reduce import dependency and anchor captive refining investments in coastal manufacturing clusters.
- FSSAI Salt Iodization Mandates:Universal edible salt fortification requirements sustain baseline demand for potassium iodate and create predictable offtake volumes for domestic producers.
- Brine Extraction Economics:Coastal access to subterranean brine reservoirs in Gujarat enables integrated extraction-to-derivatives operations with lower logistics costs than caliche-dependent imports.
Market Restraints
- Caliche Import Concentration:Primary raw material dependence on Chilean and Japanese caliche deposits exposes processors to currency volatility and shipping cost fluctuations.
- BIS Purity Certification Bottlenecks:Bureau of Indian Standards testing timelines for pharmaceutical-grade iodine create 4-6 month qualification delays that freeze spot purchasing.
- Fluorinated Contrast Media Substitution:Gadolinium-based MRI agents and emerging iron oxide nanoparticles are displacing iodinated compounds in specific radiology protocols.
Strategic Opportunities
- Underpenetrated Northeast States:Assam and Manipur lack localized iodine derivative production facilities, creating distribution advantages for Gujarat-based refiners with cold-chain logistics partnerships.
- Veterinary Pharmaceutical Expansion:Iodine-based teat dips and wound antiseptics for dairy cooperatives represent an emerging application segment with lower certification barriers than human injectables.
- CDSCO Traceability Requirements:Mandatory active-ingredient documentation for export-oriented API manufacturers favors domestic refiners with integrated batch-record systems over import-reliant compounders.
Industry Challenges
- IP-Grade Refining Talent Scarcity:Specialized operators capable of maintaining parts-per-billion impurity controls for injectable specifications command premium wages that strain mid-scale facilities.
- Legacy Salt Iodization Equipment:Pre-2015 spraying and mixing infrastructure at state-owned salt works requires capital-intensive retrofitting to meet current FSSAI homogeneity standards.
- CDSCO Inspection Backlogs:Central Drugs Standard Control Organization facility audits for pharmaceutical-grade certification face 18-month queues that delay market entry for new refining capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Iodine Market |
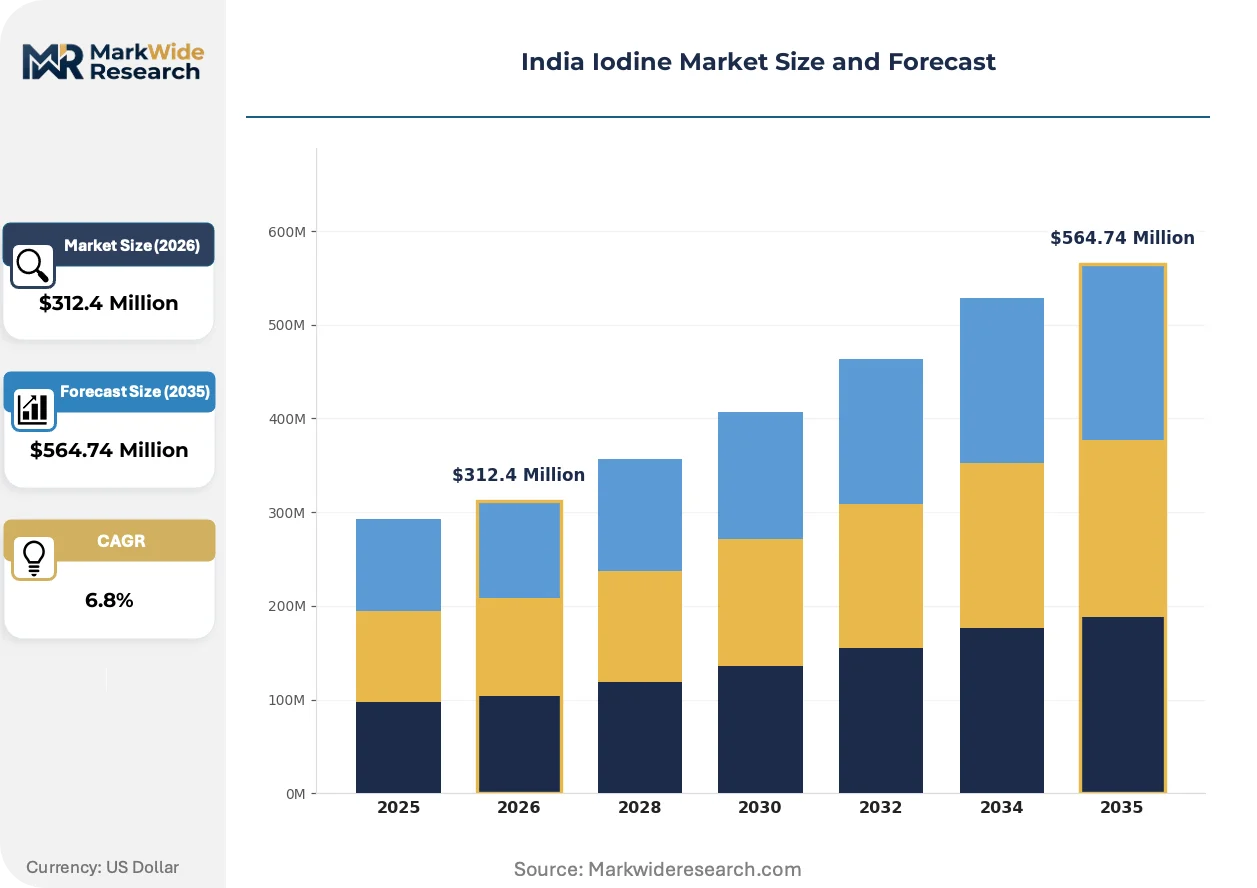
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Iodine, Inorganic Iodine, Iodine Derivatives, Iodine Salts End Use Industry: Pharmaceuticals, Food Additives, Water Purification, Feed Supplements Application: Contrast Agents, Dietary Supplements, Industrial Applications, Photography Distribution Channel: Online Retail, Distributors, Pharmaceutical Stores, Direct Sales |
| Companies Covered | Salvi Chemical Industries Ltd., Deep Water Chemicals, Samrat Pharmachem Limited, Glide Chem Private Limited, Eskay Iodine Pvt. Ltd., Calibre Chemicals Pvt. Ltd., Iochem Corporation, Akron Healthcare Pvt. Ltd., Infinium Pharmachem Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Iodine Market Shifts & Advancements
Refining technology and regulatory traceability requirements are restructuring competitive advantage around purity certification capabilities rather than raw material access alone.
Membrane-based brine concentration is bifurcating the extraction technology landscape. Gujarat-based operators deploy electrodialysis and reverse osmosis systems to achieve pharmaceutical-grade purity without energy-intensive thermal evaporation. Contrast-agent manufacturers now specify membrane-refined feedstocks for injectable applications, compressing margins for conventional thermal processors serving technical-grade markets.
CDSCO's active-ingredient traceability rules are tightening documentation requirements across the pharmaceutical value chain. Batch-level origin records must now span from brine source to final salt or derivative form. API exporters in Maharashtra and Telangana are responding by qualifying single-source domestic refiners rather than multi-origin import portfolios.
Contract manufacturing arrangements are displacing spot purchasing for potassium iodide and iodate salts. Large pharmaceutical formulators in Hyderabad and Ahmedabad are consolidating supplier relationships around three-year offtake agreements with embedded price adjustment clauses. This concentration is most visible among injectable contrast media producers seeking supply security for iodinated aromatic intermediates.
India Iodine Market Segmentation
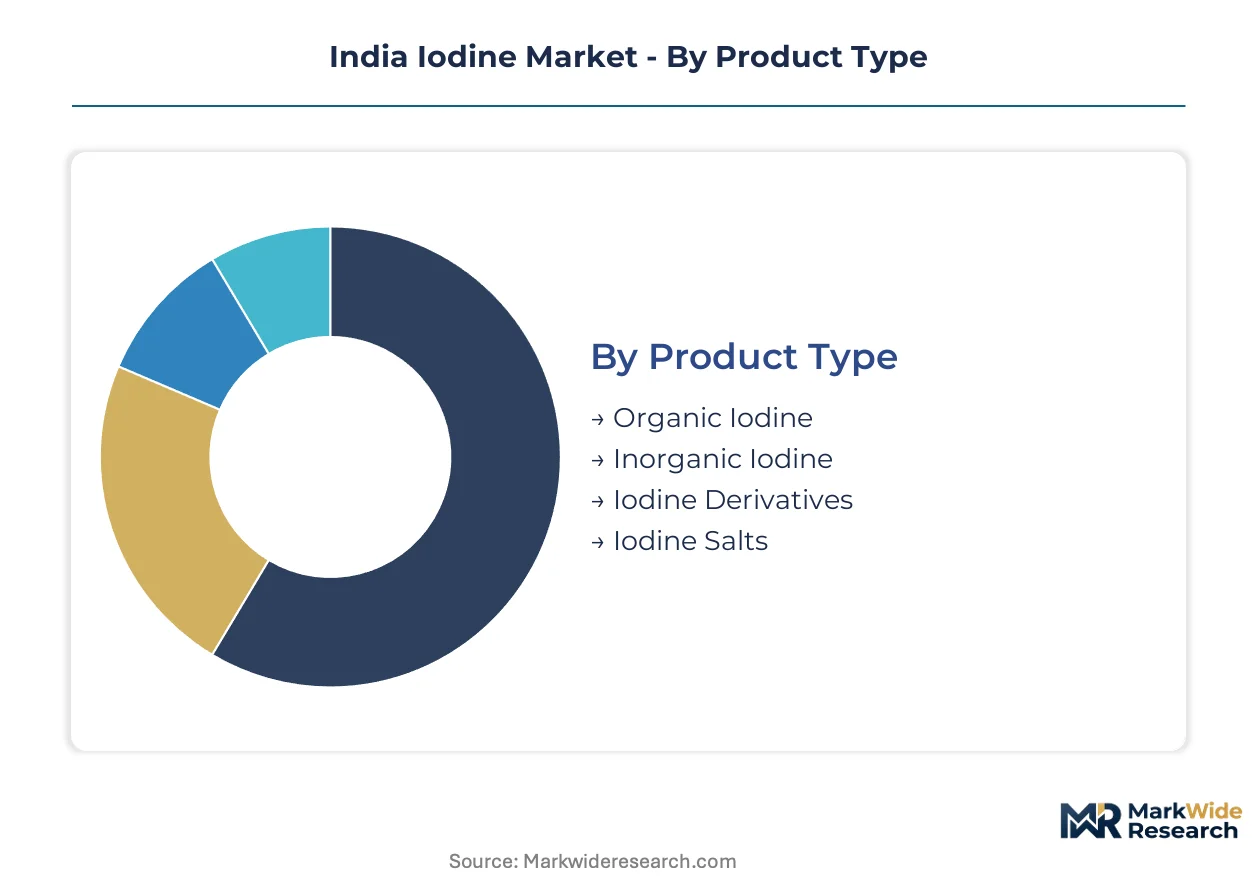
Iodine demand in India fragments across molecular forms and purity grades that command divergent margin structures. Pharmaceutical formulators and salt processors source from distinct supply tiers with incompatible certification requirements.
Product Type:
Gadolinium-based MRI contrast agents and fluorinated radiology compounds are exerting substitution pressure most acutely on organic iodine formulations, while inorganic salts maintain defensive positions in non-discretionary applications.
- Inorganic Iodine:Elemental iodine and simple salts extracted from brine or caliche sources serve as feedstock for potassium iodate production under FSSAI salt fortification mandates. Gujarat-based refiners supply state iodization programs through predictable annual contracts with limited price volatility.
- Iodine Derivatives:Functionalized intermediates for X-ray contrast media synthesis command premium positioning through CDSCO injectable-grade certification. Maharashtra pharmaceutical clusters absorb expanding volumes as domestic API manufacturing scales under PLI scheme incentives.
- Organic Iodine:Iodinated aromatic compounds face displacement risk from non-iodinated MRI agents in diagnostic imaging protocols.
- Iodine Salts:Potassium iodide and sodium iodide for thyroid hormone synthesis and nutritional fortification.
Inorganic iodine retains volume leadership; iodine derivatives hold the steepest expansion curve.
End Use Industry:
Cost-tier stratification separates pharmaceutical-grade demand from commodity offtake, with certification premiums creating order-of-magnitude price spreads between segments.
- Pharmaceuticals:Contrast media manufacturers and API formulators in Hyderabad and Ahmedabad drive specification-grade demand requiring IP purity and batch traceability. CDSCO active-ingredient documentation rules favor domestic refiners with integrated quality systems over import-dependent compounders.
- Food Additives:Potassium iodate for edible salt fortification operates under FSSAI homogeneity standards that mandate micron-level distribution consistency.
- Water Purification:Municipal and industrial disinfection applications.
- Feed Supplements:Animal nutrition formulations with lower purity thresholds than human pharmaceutical grades.
Food additives anchor baseline volume; pharmaceuticals deliver the highest value-per-kilogram realization.
Application:
Volume concentration in mature applications contrasts with emerging demand pockets that reshape refining investment priorities.
- Contrast Agents:Iodinated compounds for CT imaging face competitive pressure from gadolinium and iron oxide nanoparticle alternatives in specific diagnostic protocols. Domestic manufacturers are qualifying membrane-refined feedstocks to meet injectable purity specifications previously satisfied only by imported material.
- Dietary Supplements:Potassium iodide tablets for thyroid health support stable, predictable demand through pharmacy and direct-to-consumer channels.
- Industrial Applications:Catalysts, dyes, and chemical synthesis intermediates.
- Photography:Silver halide emulsion chemistry with declining demand trajectory.
Dietary supplements sustain volume stability; contrast agents navigate the most intense substitution dynamics.
Distribution Channel:
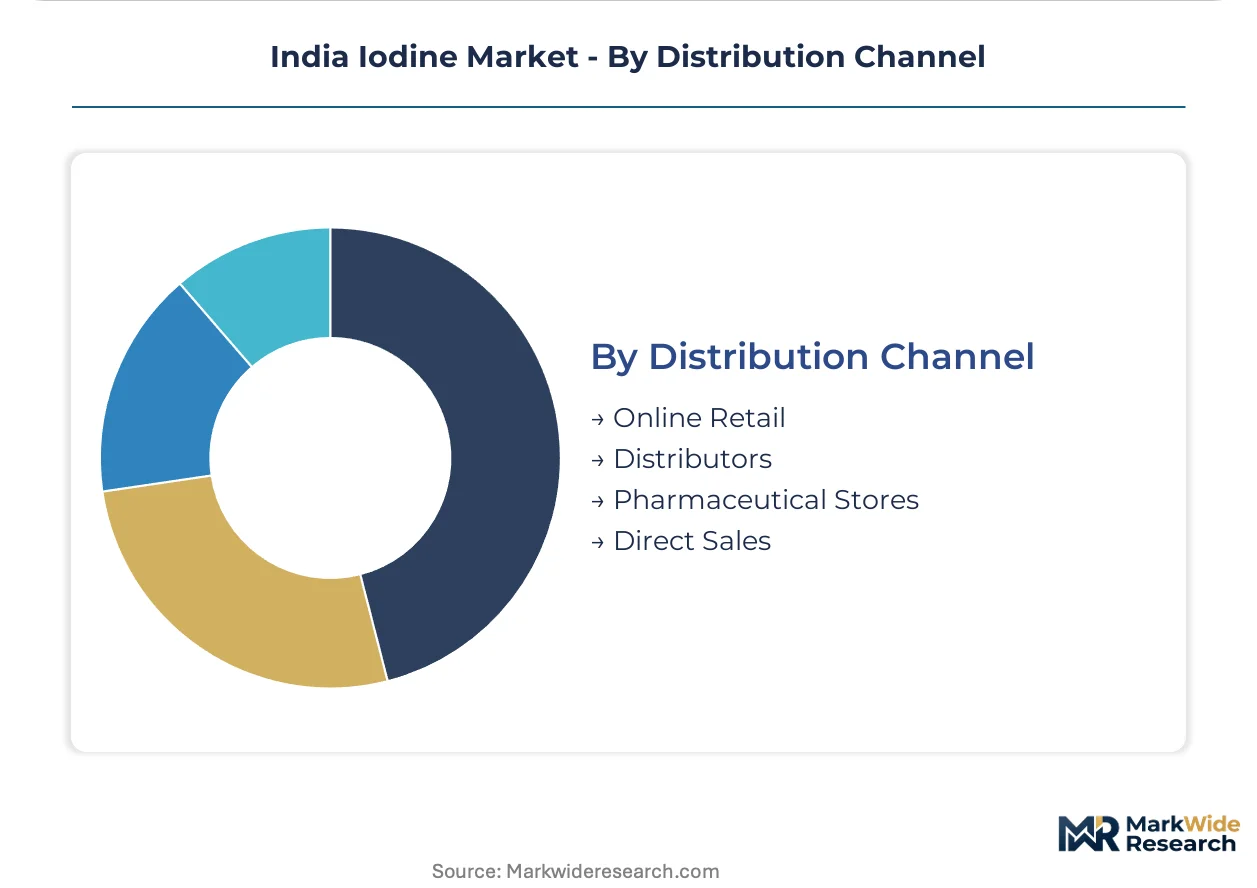
Customer-type stratification separates institutional procurement with multi-year agreements from fragmented spot purchasing.
- Distributors:Regional chemical distributors aggregate demand from mid-scale pharmaceutical compounders and salt processors across Gujarat and Maharashtra. These intermediaries manage inventory risk for refiners while extending credit terms that captive direct sales teams avoid.
- Direct Sales:Large pharmaceutical formulators in Ahmedabad and Hyderabad negotiate three-year offtake agreements with embedded price adjustment clauses for potassium iodide and iodate salts.
- Pharmaceutical Stores:Retail pharmacy chains for dietary supplement and antiseptic product distribution.
- Online Retail:Emerging channel for laboratory reagents and small-volume specialty grades.
Distributors retain broadest geographic coverage; direct sales capture the largest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean and Japanese caliche exports feed India's coastal refining clusters, where Gujarat and Maharashtra processors convert imported raw iodine into pharmaceutical-grade derivatives for domestic API manufacturers.
Gujarat
Pharmaceutical formulators in Ahmedabad and Vadodara drive specification-grade iodine demand for contrast media synthesis. The state's PLI scheme for bulk drugs anchors captive refining investments along the Gulf of Khambhat. Coastal brine access near Mithapur enables Salvi Chemical Industries to operate integrated extraction-to-derivatives facilities with lower logistics costs than caliche-dependent competitors.
Maharashtra
API manufacturers in Mumbai and Pune absorb expanding volumes of potassium iodide and iodate salts under CDSCO traceability requirements. The FSSAI's salt iodization mandates sustain predictable offtake for state iodization programs. Mumbai-based pharmaceutical clusters qualify domestic refiners with integrated batch-record systems over import-reliant compounders.
Telangana
Hyderabad's contract research organizations drive demand for IP-grade iodine derivatives in early-stage drug development. CDSCO facility audits create 18-month certification queues that delay market entry for new refining capacity. The city's pharmaceutical parks favor single-source domestic suppliers with documented brine-to-salt origin records.
Tamil Nadu
Salt processors along the Coromandel Coast face retrofitting requirements for pre-2015 iodization equipment to meet current FSSAI homogeneity standards. Chennai-based distributors aggregate demand from mid-scale pharmaceutical compounders across South India. Regional chemical distributors manage inventory risk while extending credit terms that captive direct sales teams avoid.
West Bengal
Kolkata's trading houses historically managed iodine import flows from Japanese caliche suppliers. The state's salt works require capital-intensive upgrading to achieve micron-level potassium iodate distribution consistency. Eastern India lacks localized iodine derivative production, creating distribution advantages for Gujarat-based refiners with cold-chain logistics partnerships.
India Iodine Market Competitive Landscape
Player mix skews toward mid-scale chemical specialists with coastal brine access or downstream pharmaceutical integration. The market structure concentrates around Gujarat-based refiners with extraction assets and Maharashtra compounders with CDSCO-certified finishing capacity. Two strategic archetypes dominate: brine-integrated extractors with thermal or membrane refining capabilities, and formulation-focused derivative producers serving API customers. Competitive moves center on three-year offtake agreements with embedded price adjustment clauses and backward integration into captive iodine refining.
Among Gujarat-based operators with coastal asset positions, Salvi Chemical Industries Ltd. and Calibre Chemicals Pvt. Ltd. exemplify the brine-integrated archetype. Eskay Iodine Pvt. Ltd. occupies a specialist position within the pharmaceutical-grade refining tier. These three entities represent the competitive core around which contract manufacturing arrangements and direct sales relationships consolidate.
| Leading Market Players |
|---|
| Salvi Chemical Industries Ltd. |
| Deep Water Chemicals |
| Samrat Pharmachem Limited |
| Glide Chem Private Limited |
| Eskay Iodine Pvt. Ltd. |
| Calibre Chemicals Pvt. Ltd. |
| Iochem Corporation |
| Akron Healthcare Pvt. Ltd. |
| Infinium Pharmachem Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Membrane-based brine concentration displacing thermal evaporation in Gujarat simultaneously redraws supply geography toward coastal extraction assets and compresses pricing premiums for pharmaceutical-grade feedstocks. This technology substitution bifurcates the market into membrane-refined injectable tiers and legacy thermal grades, with CDSCO certification requirements amplifying price spreads between qualified and unqualified supply tiers.
Pricing Analysis
Membrane-generation refining commands pricing premiums over thermal-evaporation legacy grades, while next-generation electrodialysis systems threaten further cost compression. Contract-based long-term offtake agreements with embedded price adjustment clauses dominate pharmaceutical procurement, with CDSCO IP-grade certification and batch traceability documentation as the primary price differentiation drivers. Cost compression in technical-grade iodine salts is intensifying because membrane processors are expanding capacity into historically thermal-served segments. Salt iodization programs under FSSAI mandates exhibit the highest price sensitivity due to government tender mechanisms, while contrast-agent manufacturers show the least sensitivity given injectable purity requirements.
Supply Chain Analysis
Port congestion at Mundra and Hazira elevates inbound logistics costs for Chilean and Japanese caliche shipments, compressing margins for processors without coastal brine access. Geographic supply concentration centers on Chilean caliche deposits, Japanese refined iodine exports, and Gujarat coastal brine extraction. Raw material dependencies encompass caliche ore, subterranean brine reservoirs, and sulfuric acid for extraction chemistry. Single-source vulnerability to Chilean caliche supply disruptions represents the dominant structural risk. Distribution runs through regional chemical distributors aggregating mid-scale pharmaceutical demand, with direct sales channels capturing large formulator contracts in Ahmedabad and Hyderabad.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India iodine market sits in an early-cycle expansion phase as PLI scheme incentives for bulk drug manufacturing accelerate domestic API capacity buildout and captive refining investments. Penetration of membrane-based extraction technology remains below saturation thresholds across Gujarat's coastal manufacturing corridor.
For Market Incumbents: Consolidate membrane-refining capabilities through equipment upgrades at existing coastal facilities to defend against thermal-grade margin erosion. Anchor three-year offtake agreements with Maharashtra and Telangana pharmaceutical clusters before CDSCO traceability requirements harden supplier qualification barriers. Prioritize backward integration into brine extraction assets over import-dependent caliche processing to mitigate currency volatility exposure.
For New Entrants and Emerging Players: Differentiate on veterinary pharmaceutical applications including teat dips and wound antiseptics for dairy cooperatives, where certification barriers sit below human injectable standards. Target Assam and Manipur distribution networks through cold-chain logistics partnerships with Gujarat-based refiners, exploiting the absence of localized derivative production in Northeast states. Pursue contract manufacturing arrangements with mid-scale API formulators seeking single-source domestic suppliers with integrated batch-record systems.
For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors brine-integrated processors with CDSCO-certified finishing capabilities over import-reliant compounders. Long-term viability over the next decade hinges on regulatory tailwinds from PLI scheme extensions and FSSAI salt iodization mandate enforcement. Target acquisition archetypes include coastal refiners with membrane technology deployments and established pharmaceutical customer relationships. Monitor CDSCO facility audit queue lengths as the critical inflection signal for domestic capacity shortage conditions.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Refining Capacity Expansion | Electrodialysis and reverse osmosis deployments enable pharmaceutical-grade purity without thermal energy intensity. |
| Backward Integration into Brine Extraction | Coastal asset control reduces logistics costs and caliche import dependency for Gujarat-based processors. |
| Long-term Supply Agreement Structuring | Three-year offtake contracts with embedded price adjustments secure volume commitments from Hyderabad API manufacturers. |
| CDSCO Certification Investment | IP-grade refining capabilities and batch-record systems qualify domestic suppliers for export-oriented pharmaceutical demand. |
| Veterinary Pharmaceutical Market Entry | Teat dip and wound antiseptic formulations exploit lower certification barriers than human injectable applications. |
Research Methodology
Desk research of BIS certification databases, CDSCO pharmaceutical-grade standards, and FSSAI salt iodization compliance records preceded structured interviews with iodine refinery plant managers, pharmaceutical procurement leads at API manufacturers, distribution channel partners, and technical R&D directors at derivative producers. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of listed chemical processors, and industry association reports. Bottom-up volume estimates by product grade and end-use application were triangulated against top-down market sizing from production capacity assessments.
Variance decomposition across product type, purity grade, end-use industry, and regional production hub dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-kilogram realizations across pharmaceutical, food additive, and industrial application tiers. Forecast inputs incorporated PLI scheme disbursement schedules, CDSCO facility certification queue projections, and membrane technology adoption curves at coastal refining assets.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme funding, stable Chilean caliche export flows, and FSSAI enforcement continuity would require recalibration. Forecasts reflect documented assumptions regarding regulatory incentive durability and technology substitution rates. Specific risk factors include BIS purity certification timeline extensions, gadolinium-based MRI agent substitution acceleration, and CDSCO inspection backlog deterioration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
Commodity Plastics Market
Bulk Chemicals
Global Concentrated Nitric Acid Market
Bulk Chemicals
Malathion Market
Bulk Chemicals
Global Internal Olefins Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
Encapsulated Sodium Bicarbonate Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
Global Nitrite Market
Bulk Chemicals
Global Sodium Percarbonate Market
Bulk Chemicals
Sodium Ferrocyanide Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
Ammonium Sulfate Market