
 Sodium Cyanide Market | 2026-2036
Sodium Cyanide Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Cyanide Market Analysis
Modular solid-to-liquid conversion systems is repositioning procurement patterns among remote mining operators seeking reduced transport hazards. Draslovka leverages its European manufacturing base to supply briquette formulations optimized for hot-climate leaching. Taekwang Industrial Co Ltd anchors Asian supply through integrated petrochemical feedstock access. Orica Limited competes on logistics networks that bypass conventional distributor channels entirely.
Sodium cyanide is an inorganic salt with the formula NaCN, typically manufactured through the Andrussow process combining hydrogen cyanide with sodium hydroxide; it serves primarily as a lixiviant in precious metal recovery and as a chemical intermediate in organic synthesis. Solid briquette and powder grades retain dominance in bulk mining contracts where storage stability and controlled dissolution rates command premium positioning. Liquid formulations represent the fastest-growing configuration, particularly for on-site leach operations that eliminate reconstitution steps and reduce worker exposure incidents.
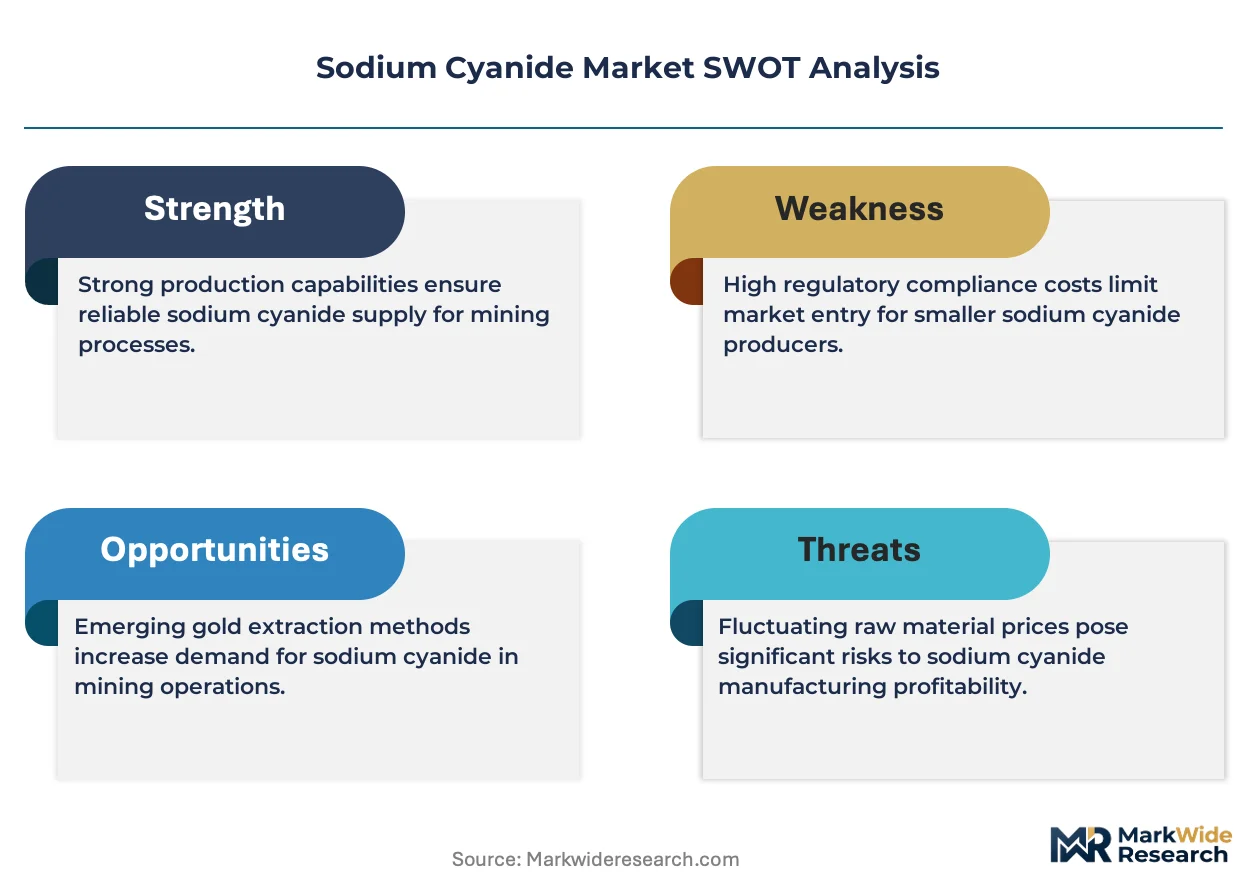
EPA enforcement under the Clean Air Act and Emergency Planning and Community Right-to-Know Act constrains domestic production capacity and elevates compliance expenditures for US-based manufacturers. EMA and ECHA oversight through REACH registration and CLP hazard classification restrict import pathways and mandate downstream user communication protocols. Stakeholders must monitor evolving cyanide management codes from the International Cyanide Management Institute and assess whether regional certification requirements will fragment procurement standards across operating jurisdictions.
Market Dynamics
Modular solid-to-liquid conversion systems are redrawing procurement patterns among remote mining operators seeking reduced transport hazards and simplified on-site handling. This technology shift compresses distributor margins while elevating logistics specialists with chemical engineering capabilities.
Growth Catalysts
- Gold extraction intensity:Australian and South African mining operations sustain bulk procurement volumes through deep-vein deposits requiring intensive lixiviant application.
- REACH compliance maturation:ECHA registration completion by established European suppliers creates regulatory moats against unregistered import competition.
- Captive production expansion:Shandong province chemical manufacturers integrate backward into cyanide synthesis to secure precious metal processing feedstock.
Market Restraints
- Hydrogen cyanide feedstock volatility:Natural gas price swings directly transmit to sodium cyanide production economics through the Andrussow process input chain.
- EPA enforcement compression:Clean Air Act permitting delays and Emergency Planning compliance costs constrain domestic US manufacturing capacity expansion.
- Thiosulfate substitution threat:Alternative lixiviants gain pilot traction in environmentally sensitive jurisdictions with strict cyanide discharge prohibitions.
Strategic Opportunities
- Latin American mining corridors:Peruvian and Chilean gold-silver operations present underpenetrated demand for briquette formulations optimized for high-altitude leaching conditions.
- ICMI certification leverage:International Cyanide Management Institute code adoption creates premium positioning for suppliers with verified transport and storage protocols.
- Digital inventory integration:Real-time consumption monitoring systems enable vendor-managed inventory contracts that lock out competitor access.
Industry Challenges
- Specialized transport certification:ADR and DOT hazardous materials licensing requirements create driver shortages and route constraints.
- Legacy leach pad retrofit complexity:Existing heap-leach infrastructure requires costly reengineering to accommodate modified cyanide delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Cyanide Market |
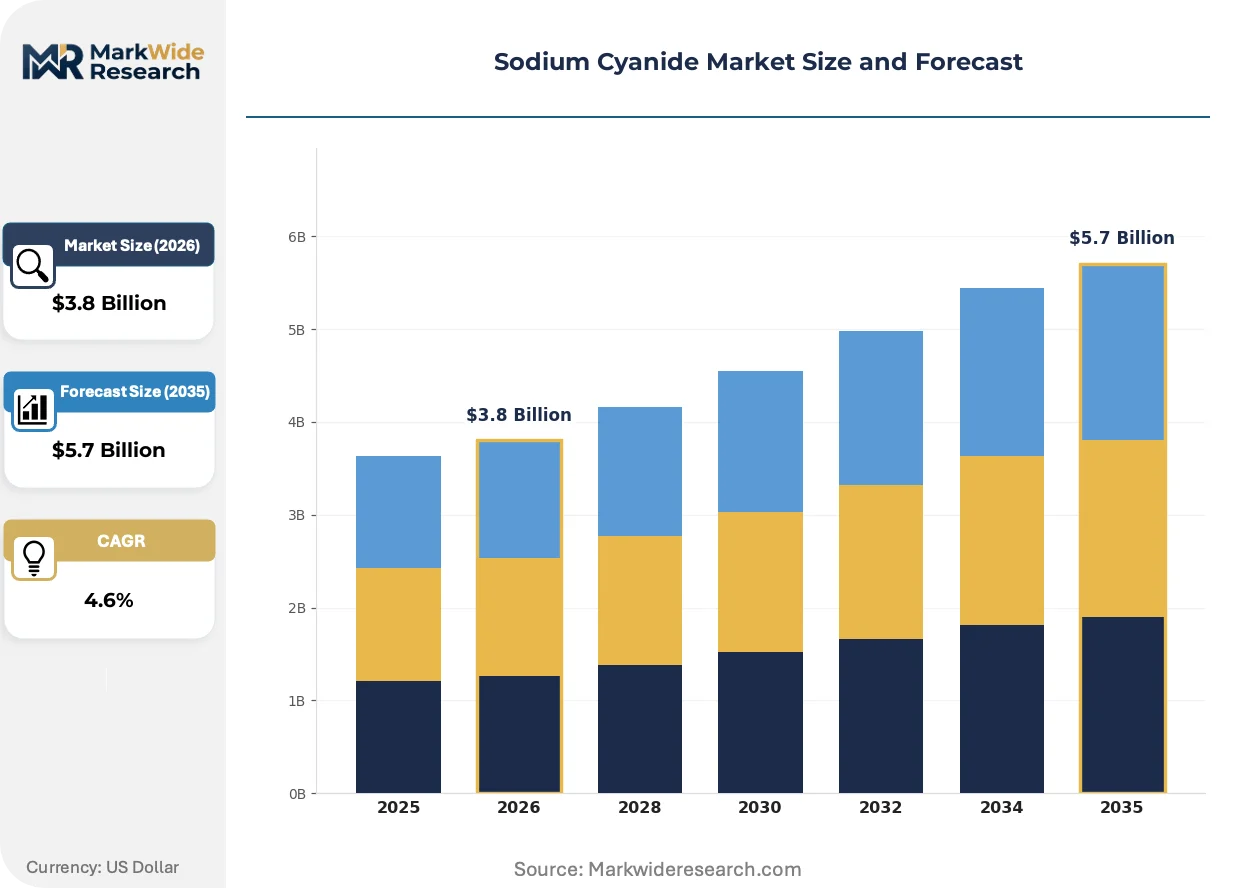
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Solution, Powder End User: Mining, Chemical Manufacturing, Agriculture, Pharmaceuticals Distribution Channel: Direct Sales, Online, Distributors, Wholesalers Application: Gold Extraction, Electroplating, Herbicide, Intermediate |
| Companies Covered | Australian Gold Reagents Pty Ltd, Taekwang Industrial Co Ltd, Draslovka, The Chemours Company, Anhui Shuguang Chemical Group, Orica Limited, Evonik Industries AG, Tongsuh Petrochemical Corp Ltd, Cyanco International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Cyanide Market Emerging Trajectories
Active transformation across three vectors—process technology, regulatory architecture, and procurement behavior—is compressing traditional supply chain hierarchies while elevating integrated service providers with chemical engineering and logistics capabilities combined.
Membrane-based cyanide recovery circuits are unifying effluent treatment with reagent regeneration in closed-loop configurations. Mid-tier gold operators in Nevada and Western Australia pilot these systems to eliminate tailings pond discharge liabilities. The technology is unifying environmental compliance and operating cost reduction into single capital decisions that favor integrated technology vendors over commodity chemical suppliers.
REACH authorization requirements for sodium cyanide downstream users tighten substance tracking obligations across European precious metal refiners. ECHA's expanded CLP hazard classification mandates revised safety data sheet distribution and worker training protocols. German and Finnish electroplating facilities absorb compliance costs through supplier consolidation toward vertically integrated chemical service providers.
Direct manufacturer contracting supplants traditional distributor networks among volume mining accounts seeking technical service integration. Large Australian and South African operators negotiate formula-based pricing tied to gold recovery rates rather than chemical volume. This pattern concentrates procurement influence with Orica and Draslovka technical sales teams while marginalizing regional chemical distributors without on-site engineering support.
Sodium Cyanide Market Segmentation
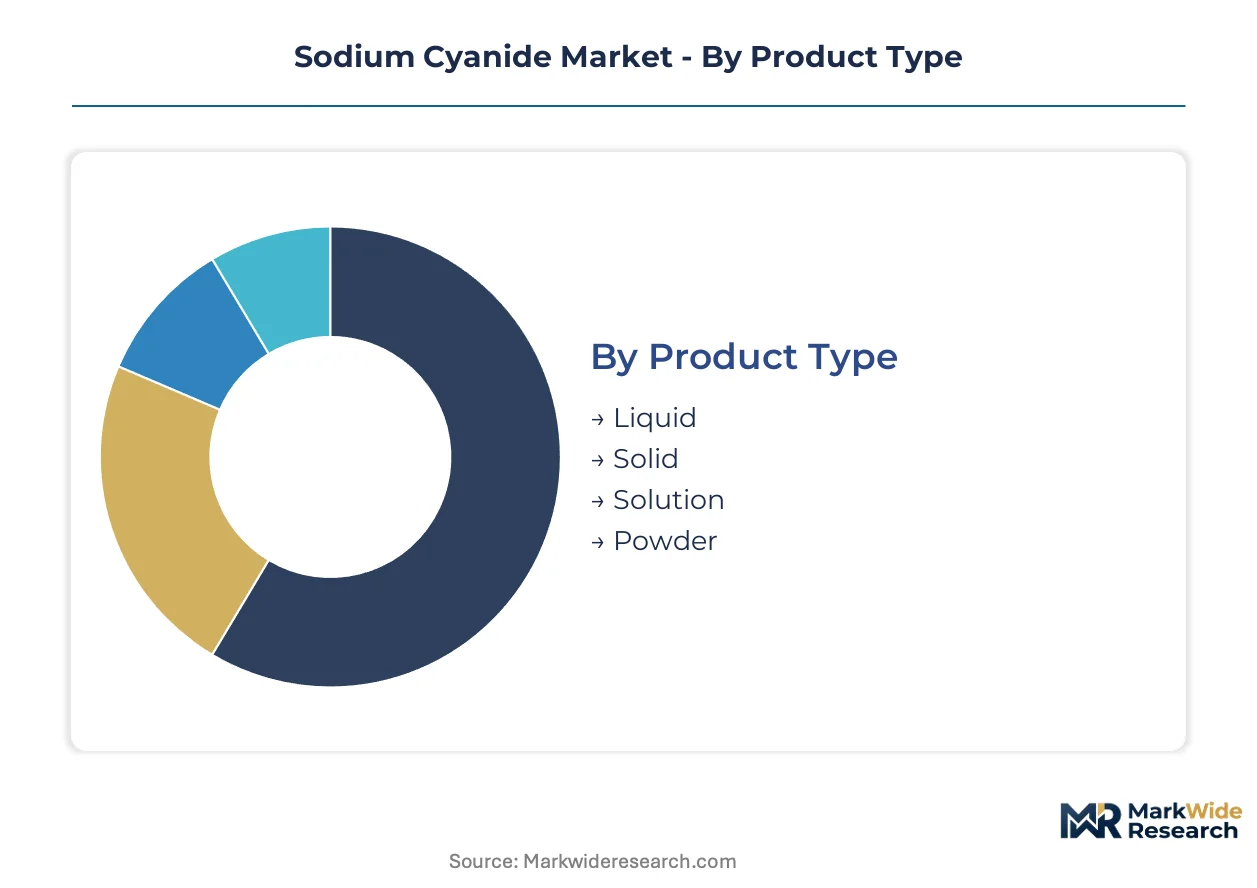
Sodium cyanide procurement patterns diverge sharply across physical form, end-use chemistry, and regulatory exposure. Each segment carries distinct handling protocols, transport certification requirements, and margin structures that reshape supplier positioning.
Product Type:
ICMI certification mandates and ADR transport licensing create tiered compliance burdens across physical formulations, with liquid grades triggering the most stringent downstream user protocols.
- Liquid:Pre-dissolved NaCN eliminates on-site reconstitution hazards. Gold extraction operators in Western Australia and Nevada prefer this grade for continuous leach circuits where worker exposure minimization drives procurement decisions. EPA Emergency Planning compliance costs elevate pricing premiums against solid alternatives.
- Solid:Briquette and tablet configurations dominate bulk mining contracts requiring storage stability across variable climates. South African deep-vein operations specify this grade for controlled dissolution rates in heap-leach infrastructure.
- Solution:Dilute concentrations serve electroplating facilities with precision dosing requirements. German automotive component suppliers specify solution grades to meet REACH downstream user communication mandates.
- Powder:Fine particulate form retains niche demand in chemical synthesis intermediates. Chinese pharmaceutical manufacturers in Jiangsu province procure powder grades for organic cyanation reactions.
Solid formulations sit at the top of the volume ranking, with liquid grades climbing the fastest.
End User:
Customer scale and process integration depth separate segments by contract structure and technical service intensity.
- Mining:Precious metal extraction consumes the majority of global sodium cyanide volume. Australian and South African gold operators negotiate multi-year supply agreements with embedded technical support for leach optimization.
- Chemical Manufacturing:Organic synthesis applications require high-purity grades with tight specification windows. Specialty chemical producers in Gujarat, India source cyanide for pharmaceutical intermediate production under CDSCO oversight.
- Agriculture:Fumigation and pest control applications face tightening regulatory restrictions. California agricultural operators confront EPA re-registration delays that compress accessible supply channels.
- Pharmaceuticals:GMP-compliant synthesis demands certificate-of-analysis documentation for every batch. Swiss and German API manufacturers specify pharmaceutical-grade material with full supply chain traceability.
Mining commands the dominant revenue share, though pharmaceutical applications show the steepest margin expansion trajectory.
Distribution Channel:
Route-to-market selection reflects customer technical sophistication and volume scale, with direct engagement displacing traditional intermediaries among sophisticated buyers.
- Direct Sales:Manufacturer-to-operator contracting eliminates distributor margins for volume accounts. Large Australian mining houses negotiate formula-based pricing tied to gold recovery performance rather than chemical tonnage.
- Distributors:Regional chemical distributors retain relevance for mid-tier miners lacking on-site engineering capabilities. Peruvian and Chilean operations rely on distributor networks for localized storage and emergency response support.
- Wholesalers:Bulk aggregation serves smaller electroplating facilities with intermittent demand patterns. Italian jewelry manufacturing clusters access cyanide through consolidated wholesale purchasing cooperatives.
- Online:Digital procurement platforms emerge for standardized reagent grades with documented specifications. Japanese research institutions utilize B2B marketplaces for small-quantity pharmaceutical-grade orders.
Direct sales channels capture the largest contract value, with online platforms gaining share fastest among institutional research buyers.
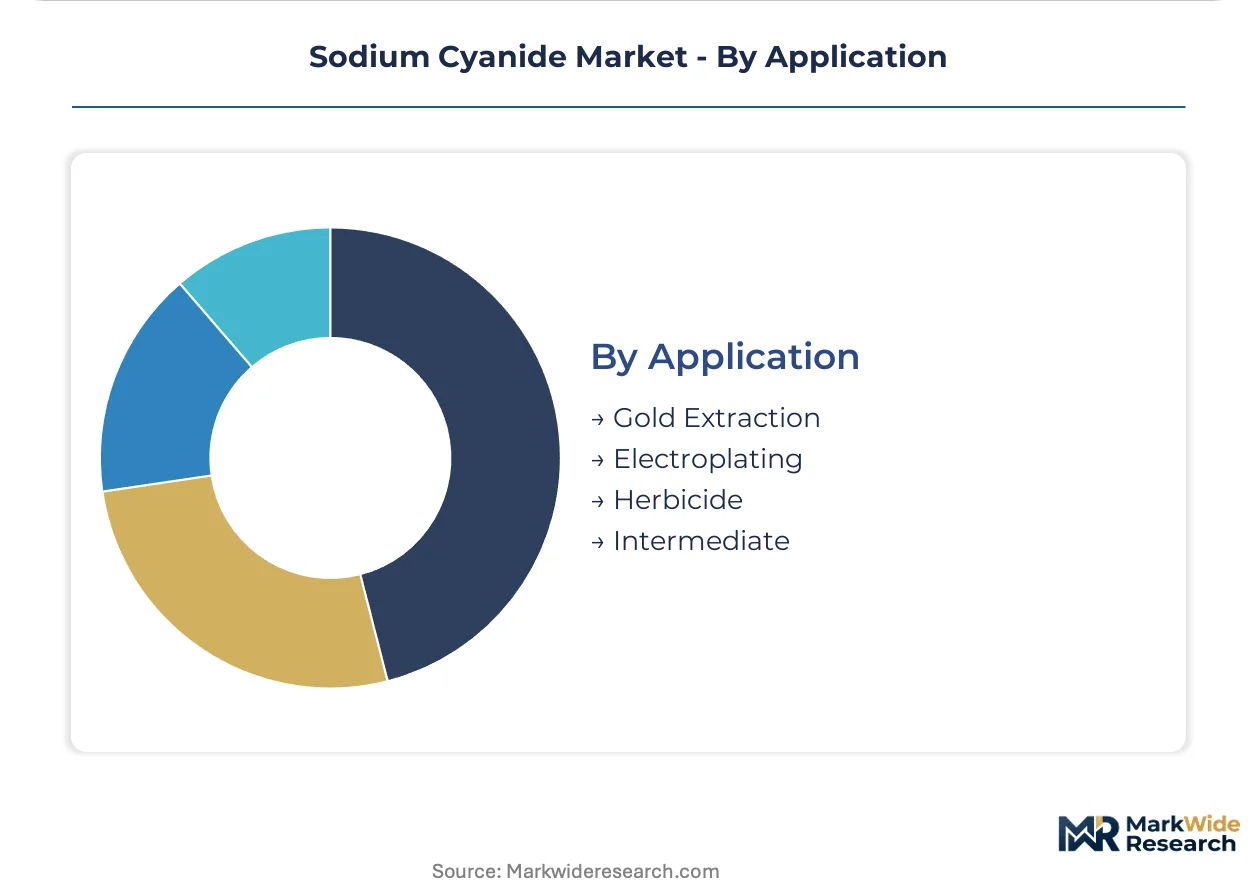
Application:
Process chemistry and environmental discharge profiles segment demand by regulatory jurisdiction and effluent treatment burden.
- Gold Extraction:Hydrometallurgical lixiviant application dominates volume consumption. Nevada heap-leach operations pilot membrane-based cyanide recovery circuits to eliminate tailings pond liabilities.
- Electroplating:Surface finishing for electronics and automotive components requires controlled bath chemistry. Finnish and German facilities absorb REACH compliance costs through supplier consolidation toward integrated service providers.
- Herbicide:Agricultural chemistry applications face substitution pressure from bio-based alternatives. Brazilian sugarcane operators confront ANVISA re-evaluation timelines that constrain formulation access.
- Intermediate:Organic synthesis feedstock for pharmaceuticals and fine chemicals demands high-purity certification. Shandong province chemical manufacturers integrate backward into captive cyanide production to secure processing economics.
Gold extraction sits at the top of the volume ranking, with electroplating applications expanding most quickly in Asian electronics manufacturing corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The sodium cyanide industry traces its modern scale to German chemical engineering advances in the early twentieth century, when the Andrussow process enabled mass production. Today's procurement geography reflects both this European technical heritage and the subsequent shift toward gold-rich mining jurisdictions.
Australia
Western Australian goldfields sustain the country's position as a top-tier sodium cyanide consumer. The TGA oversees chemical handling standards while state-level environmental regulators enforce tailings management protocols. Kalgoorlie's Super Pit operations anchor demand through continuous leach circuits requiring steady lixiviant supply.
South Africa
Deep-vein gold deposits in the Witwatersrand Basin drive intensive cyanide application rates. The country's national chemical regulator mandates strict transport certification under hazardous materials frameworks. Johannesburg-Pretoria industrial corridors concentrate both mining headquarters and chemical distribution infrastructure.
China
Shandong province chemical manufacturers have integrated backward into captive cyanide production for precious metal processing. NMPA-aligned standards govern pharmaceutical-grade material while MEE oversight tightens effluent discharge limits. Jiangsu province pharmaceutical clusters source powder grades for organic synthesis intermediates.
United States
Nevada heap-leach operations pilot membrane-based cyanide recovery circuits to eliminate tailings pond liabilities. EPA enforcement under the Clean Air Act and Emergency Planning and Community Right-to-Know Act constrains domestic production capacity. Elko County mining logistics hubs coordinate just-in-time chemical delivery to remote sites.
Germany
Finnish and German electroplating facilities absorb REACH compliance costs through supplier consolidation toward integrated service providers. ECHA registration completion by established European suppliers creates regulatory moats against unregistered import competition. North Rhine-Westphalia chemical clusters maintain formulation expertise for high-purity industrial grades.
Sodium Cyanide Market Vendor Landscape
The competitive structure tilts toward integrated petrochemical-chemical conglomerates with captive hydrogen cyanide feedstock access. Three to five multinational suppliers command bulk mining contracts through embedded technical service capabilities. Specialist logistics operators and regional distributors occupy mid-tier positions serving smaller electroplating and chemical synthesis accounts. Capacity expansion and direct manufacturer contracting represent the dominant competitive moves reshaping procurement relationships.
Among Asian chemical conglomerates, Taekwang Industrial Co Ltd and Tongsuh Petrochemical Corp Ltd exemplify the feedstock-integrated archetype, leveraging petrochemical chain economics to anchor regional supply. Draslovka represents the European manufacturing base optimized for hot-climate leaching formulations. Orica Limited occupies a position defined by logistics networks that bypass conventional distribution channels entirely.
| Leading Market Players |
|---|
| Australian Gold Reagents Pty Ltd |
| Taekwang Industrial Co Ltd |
| Draslovka |
| The Chemours Company |
| Anhui Shuguang Chemical Group |
| Orica Limited |
| Evonik Industries AG |
| Tongsuh Petrochemical Corp Ltd |
| Cyanco International |
| Others |
Supply Flow & Price Mechanics
Large Australian and South African gold operators anchor sodium cyanide procurement through formula-based contracts tied to gold recovery performance, compressing distributor margins while elevating technical service premiums. This buyer concentration enables manufacturers to bypass conventional chemical distribution entirely and capture value through embedded engineering support.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ICMI-certified supply from conventional industrial grades and unregistered import alternatives. Price differentiation rests on certification grade and volume scale, with mining houses absorbing technical service premiums while mid-tier operators face cost compression from hydrogen cyanide feedstock volatility. Margins are tightening due to REACH compliance maturation elevating supplier qualification costs. Small electroplating facilities exhibit highest price sensitivity, whereas integrated mining corporations prioritize recovery-rate guarantees over unit chemistry costs.
Supply Chain Analysis
Domestic-content mandates in China's Shandong province and captive production requirements across Indian pharmaceutical corridors are reshaping sourcing patterns toward localized synthesis. Supply concentrates in Australia, South Africa, and Germany, with production drawing from hydrogen cyanide feedstock anchored in petrochemical complexes. Single-source vulnerability runs through Andrussow process technology licensors and specialized ADR-certified transport fleets. Distribution runs through direct manufacturer contracting for volume mining accounts, while regional distributors serve fragmented electroplating and chemical synthesis demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium cyanide functions as a stable compounder anchored by irreplaceable lixiviant demand in deep-vein gold extraction, where deposit geology sustains intensive chemical application regardless of price cycles.
For Market Incumbents: Deploy ICMI certification leverage to lock out unregistered competitors as ECHA authorization timelines tighten. Deepen captive hydrogen cyanide supply through backward integration into petrochemical feedstock access, defending against thiosulfate substitution threats in environmentally sensitive jurisdictions. Prioritize technical sales team expansion in Latin American mining corridors where distributor relationships remain penetrable. For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical-grade powder formulations offers entry traction for GMP-compliant specialists. Target Jiangsu province organic synthesis intermediates and Japanese research institution procurement through digital inventory platforms. Pursue membrane-based cyanide recovery circuit partnerships with Nevada mid-tier operators seeking tailings pond liability elimination. For Investors and Strategic Acquirers: Petrochemical conglomerates with hydrogen cyanide positions represent the most active acquirer category in this space, consolidating backward into captive cyanide synthesis. Long-term viability frames around 5-10 year precious metal extraction intensity in Australian and South African deposits. Watch thiosulfate pilot scale-up in Western Australian jurisdictions as the inflection signal for substitution timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Cyanide | Secures feedstock economics against natural gas price swings through Andrussow process control. |
| ICMI Certification Program | Creates regulatory moats against unregistered imports under ECHA REACH authorization timelines. |
| Membrane-Based Cyanide Recovery | Unifies environmental compliance with operating cost reduction for Nevada heap-leach operators. |
| Direct Manufacturer Contracting | Eliminates distributor margins through formula-based pricing tied to gold recovery performance. |
| Latin American Distribution Expansion | Captures underpenetrated Peruvian and Chilean demand for high-altitude leaching formulations. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at sodium cyanide manufacturing facilities, procurement leads at Australian and South African mining houses, distribution channel partners specializing in hazardous materials logistics, and technical R&D directors overseeing leach optimization. Secondary validation drew from customs and trade data, International Cyanide Management Institute certification registries, SEC 10-K filings of listed chemical conglomerates, and ECHA REACH registration databases. Bottom-up volume modeling and top-down value estimation were triangulated to ensure consistency.
Historical reference periods spanning the pre-pandemic baseline through recent supply chain disruptions anchored the forecast window. The analytical framework segmented demand across physical form, end-use chemistry, and regulatory exposure tiers, with additional modeling of captive production versus merchant supply dynamics. CAGRs were derived from regression analysis against gold extraction intensity indicators and hydrogen cyanide feedstock cost trajectories. Key forecast inputs included leach pad expansion pipelines in Nevada and Western Australia, plus REACH authorization completion timelines for European downstream users.
Caveats apply where hydrogen cyanide feedstock volatility, EPA enforcement compression, or thiosulfate substitution traction could materially shift the outlook. Forecasts reflect assumptions around regulatory stability in major mining jurisdictions and continued precious metal price support for deep-vein extraction economics. A small set of named triggers—substitute lixiviant pilot results, ECHA substance evaluation outcomes, and ADR transport certification capacity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
North America Construction Chemicals Market
Chemicals
Phenothiazine Market
Chemicals
Heptaldehyde Market
Chemicals
Methanol to Gasoline Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
Superplasticizer Market
Chemicals
Global Syringaldehyde Market
Chemicals
Flame Retardants Chemicals Market
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Bakers Ammonia Market
Chemicals
Global Cysteine Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Europe Textile Chemicals Market
Chemicals
Germany Methanol Market
Chemicals
Nonanoic Acid Market
Chemicals
Europe Calcium Peroxide Market