
 Chloroacetophenone Market | 2026-2036
Chloroacetophenone Market Size, Share, and Industry Trends Forecast 2026-2036
Chloroacetophenone Market Intelligence
Chinese fine-chemical producers is expanding chloroacetophenone capacity to serve rising pharmaceutical intermediate orders from South Asia. TCI (Shanghai) Development Co., Ltd. leverages its integrated Shanghai R&D hub to sustain high-purity crystal output for research institutions globally. Lianyungang Guangda Chemical Co. Ltd. anchors eastern China's supply base with dedicated phenylacetone derivative lines. Capot Chemical Co. Ltd. differentiates through custom synthesis services targeting European pharmaceutical compliance standards.
Chloroacetophenone, or phenacyl chloride, is an organic compound with the formula C8H7ClO, typically appearing as white crystalline solid with a pungent odor and melting point near 59°C; manufacturers synthesize it via Friedel-Crafts acylation of benzene with chloroacetyl chloride, yielding a versatile aryl ketone intermediate for pharmaceutical and agrochemical synthesis. The chemical intermediates application dominates volume offtake, as the compound serves as a building block for hypnotic and anesthetic APIs, while the pharmaceuticals end-user segment captures the deepest margin pools due to stringent purity certifications and long-term supply contracts with generic drug makers. Solid form products lead shipment volumes for stable shelf-life requirements, though solution formulations are gaining traction in automated chemical processing lines.
India's Central Drugs Standard Control Organization and the US Food and Drug Administration both scrutinize chloroacetophenone traceability in scheduled substance precursors, tightening documentation burdens on exporters. The European Chemicals Agency classifies the compound under REACH as a skin sensitizer and aquatic toxin, forcing reformulation investments among agrochemical blenders. China's Ministry of Ecology and Environment enforces dual carbon goals that elevate energy costs for chlorination-stage production. Stakeholders must monitor regulatory divergence between OECD chemical control frameworks and emerging economy enforcement gaps to anticipate supply relocation.
Market Dynamics
Pharmaceutical API manufacturers in India and China are consolidating chloroacetophenone procurement under long-term contracts, compressing spot market liquidity and forcing intermediaries to absorb inventory risk. This structural shift toward captive supply chains is reshaping margin distribution between derivative producers and bulk chemical traders.
Growth Catalysts
- PLI scheme for specialty chemicals:India's production-linked incentive program subsidizes chloroacetophenone derivative manufacturing, drawing capacity expansion to Maharashtra's pharmaceutical clusters.
- Ketamine API demand:Generic anesthetic manufacturers in South Asia are scaling phenacyl chloride offtake for hypnotic drug synthesis under tightened narcotic precursor traceability rules.
- Friedel-Crafts process optimization:Continuous flow chlorination technology is reducing benzene waste in acylation-stage production, lowering unit costs for high-purity crystal output.
Market Restraints
- Chloracetyl chloride cost volatility:Feedstock prices fluctuate with chlorine gas and acetic acid spot markets, squeezing contract manufacturer margins on fixed-price pharmaceutical orders.
- Eastern China supply concentration:Lianyungang and Shanghai producers control bulk export volumes, creating single-source vulnerability for European agrochemical blenders.
- REACH skin sensitizer classification:ECHA's hazard designation forces reformulation investments among European downstream users, delaying product re-registration timelines.
Strategic Opportunities
- Flavoring agent export gap:ASEAN food additive regulations are opening certification pathways for phenacyl chloride derivatives in synthetic vanilla and almond flavor production.
- Automated processing solutions:Solution-formulation chloroacetophenone is penetrating chemical handling systems that require liquid feedstock compatibility, displacing manual solid-dosing operations.
- Dual carbon compliance services:China's MEE enforcement creates advisory revenue streams for auditors certifying chlorination-stage carbon intensity reductions.
Industry Challenges
- Cross-border documentation complexity:Exporters must reconcile CDSCO precursor tracking with FDA narcotic substance protocols, extending customs clearance cycles.
- High-purity certification bottlenecks:Pharmaceutical-grade crystal production requires GMP-aligned facility investments that smaller Indian manufacturers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chloroacetophenone Market |
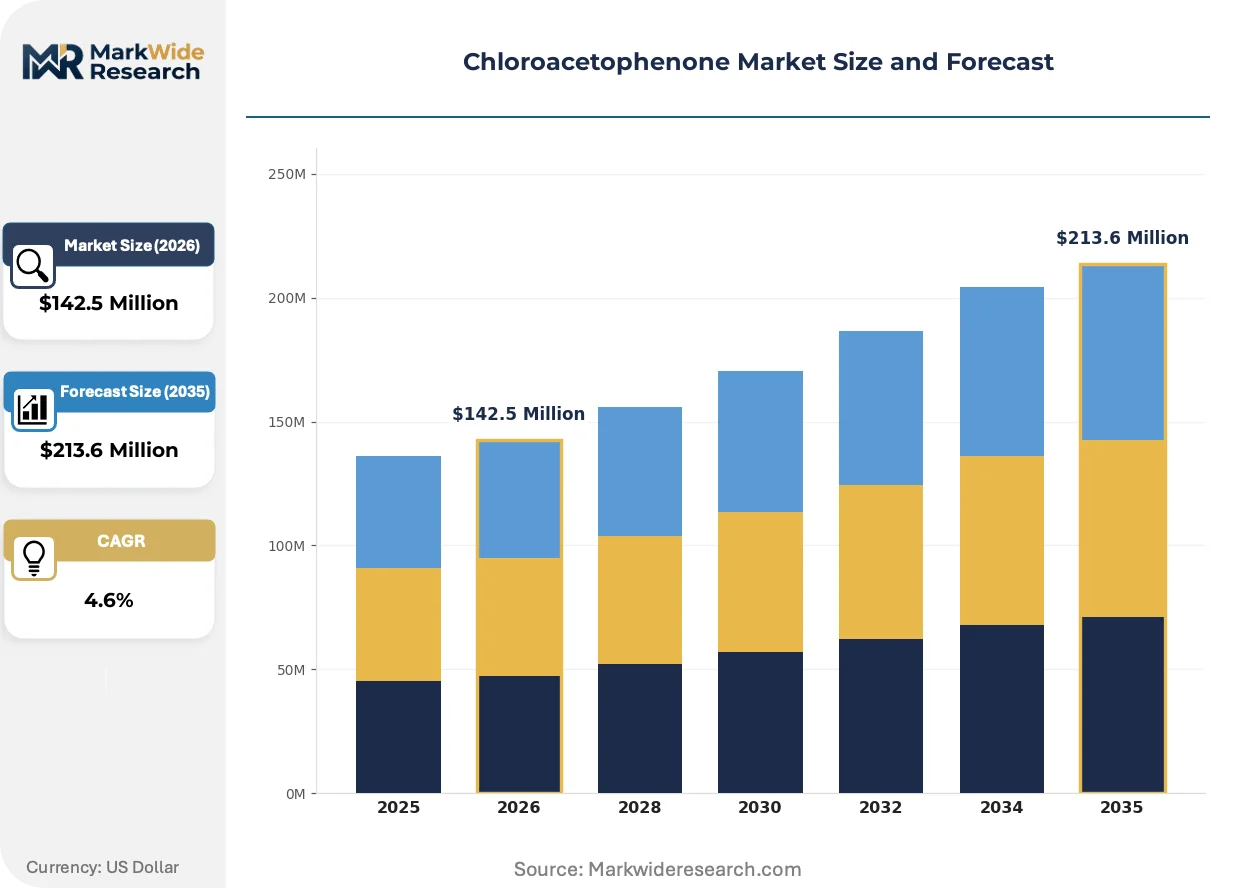
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $213.6 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid, Liquid, Diluents, Solvents Application: Chemical Intermediates, Pharmaceuticals, Agrochemicals, Flavoring Agents End User: Chemical Manufacturers, Pharmaceutical Companies, Agricultural Firms, Research Institutions Form: Crystals, Powders, Solutions, Emulsions |
| Companies Covered | TCI (Shanghai) Development Co., Ltd., Santa Cruz Biotechnology, Inc., Fisher Scientific, SynZeal, Lianyungang Guangda Chemical Co. Ltd., Taj Pharmaceuticals Ltd., Val Organics Pvt. Ltd., Capot Chemical Co. Ltd., Neuchatel Chemie Specialities, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chloroacetophenone Market Strategic Shifts & Innovations
Process intensification and regulatory digitization are converging to transform how chloroacetophenone moves from bulk chemical to qualified pharmaceutical intermediate. These shifts favor integrated producers with captive analytical capabilities over trading intermediaries.
Continuous flow reactor technology is integrating chlorination and acylation stages into single-unit operations, eliminating batch-to-batch variability in phenacyl chloride purity. Pharmaceutical API manufacturers in India are adopting these systems fastest, driven by CDSCO pressure for reproducible impurity profiles. The technology is integrating quality assurance directly into production, compressing the role of third-party testing laboratories.
REACH Article 33 supply chain communication obligations are forcing downstream users to document chloroacetophenone concentration in every mixture exported to EU member states. Agrochemical formulators are responding by substituting phenacyl chloride derivatives in seed treatment coatings. German and French blenders now require full substance volume tracking from Indian exporters, extending contract negotiation cycles.
Long-term offtake agreements are displacing spot purchasing among Maharashtra's ketamine API producers, who seek price certainty amid chloracetyl chloride volatility. These contracts bundle technical support and regulatory documentation, transferring compliance burden upstream to chemical manufacturers. The shift is most visible in Mumbai-Pune pharmaceutical corridor procurement patterns, where three-year supply locks now dominate tender structures.
Chloroacetophenone Market Segmentation
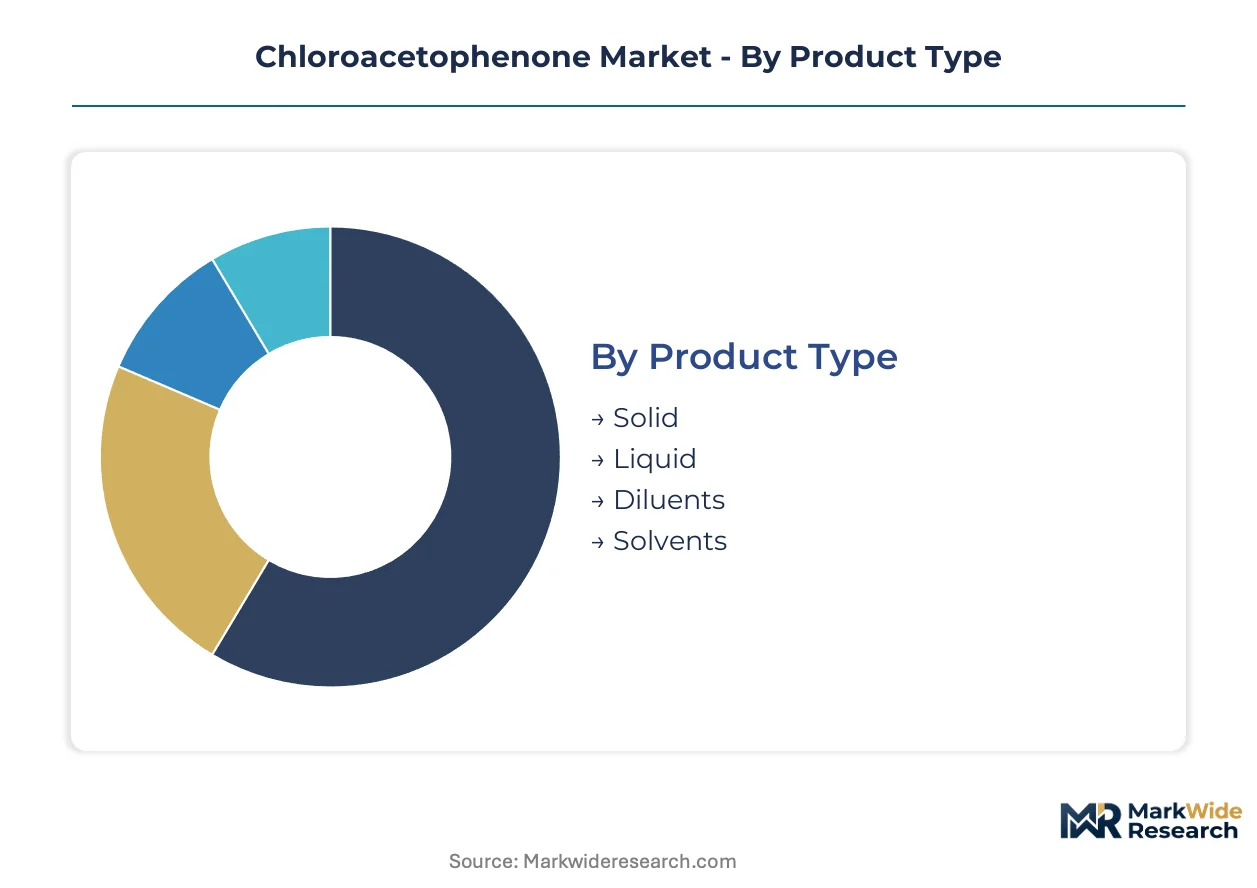
Chloroacetophenone's segmentation reflects divergent capital requirements across product forms and end-use specifications. Pharmaceutical-grade purity thresholds demand fundamentally different facility investments than industrial chemical intermediate production.
Product Type:
Solid and liquid formulations absorb the heaviest upfront capital, with crystallization infrastructure and solvent-handling systems driving facility costs into the tens of millions.
- Solid:White crystalline phenacyl chloride with melting point near 59°C requires controlled-temperature crystallization lines and inert atmosphere packaging. Maharashtra's pharmaceutical API clusters source solid grades for ketamine synthesis under CDSCO narcotic precursor protocols. Most installed capacity flows through Solid. Expansion is steepest in Liquid.
- Liquid:Solution formulations enable automated chemical processing line integration, displacing manual solid-dosing operations in high-throughput environments. Automated processing demand in eastern China's chemical parks is accelerating liquid-form adoption for continuous flow reactor compatibility.
- Diluents:Pre-blended concentration grades reduce on-site handling complexity for agrochemical formulators managing REACH skin sensitizer compliance.
- Solvents:Carrier-based delivery systems serve research institutions requiring precise volumetric dosing in analytical applications.
Capital allocation favors solid-form infrastructure in established production corridors, while liquid capacity expands fastest in greenfield automated facilities.
Application:
Margin structures vary sharply across applications, with pharmaceutical intermediates commanding certification premiums that chemical intermediate volumes cannot support.
- Chemical Intermediates:Bulk aryl ketone building blocks for downstream synthesis dominate volume offtake but operate on thin spreads. Friedel-Crafts acylation output from Lianyungang and Shanghai producers flows primarily into this tier, serving agrochemical and general industrial derivative markets.
- Pharmaceuticals:Hypnotic and anesthetic API manufacturing requires GMP-aligned facilities and long-term supply contracts with generic drug makers. India's PLI scheme for specialty chemicals is consolidating procurement under three-year supply locks in the Mumbai-Pune corridor.
- Agrochemicals:Seed treatment and crop protection formulations face ECHA-driven reformulation investments as phenacyl chloride derivatives encounter substitution pressure from skin sensitizer classification.
- Flavoring Agents:Synthetic vanilla and almond flavor precursors are penetrating ASEAN food additive markets as certification pathways open for phenacyl chloride derivatives.
Pharmaceutical-grade volumes generate the deepest margin pools. Flavoring agent applications are climbing the fastest as regulatory harmonization proceeds across Southeast Asian markets.
End User:
Procurement sophistication separates end-user tiers, with research institutions demanding batch-level documentation that agricultural firms rarely require.
- Chemical Manufacturers:Integrated phenylacetone derivative producers in eastern China anchor regional supply bases with dedicated production lines and captive analytical capabilities.
- Pharmaceutical Companies:Generic anesthetic manufacturers in South Asia are scaling phenacyl chloride offtake under tightened narcotic precursor traceability rules enforced by CDSCO and FDA.
- Agricultural Firms:European agrochemical blenders in Germany and France now require full substance volume tracking from Indian exporters, extending contract negotiation cycles.
- Research Institutions:High-purity crystal demand from TCI Shanghai's integrated R&D hub sustains specialized output for global research markets with reproducible impurity profile requirements.
Pharmaceutical companies command the most stringent supply terms. Research institutions are expanding most quickly as continuous flow reactor technology integrates quality assurance directly into production workflows.
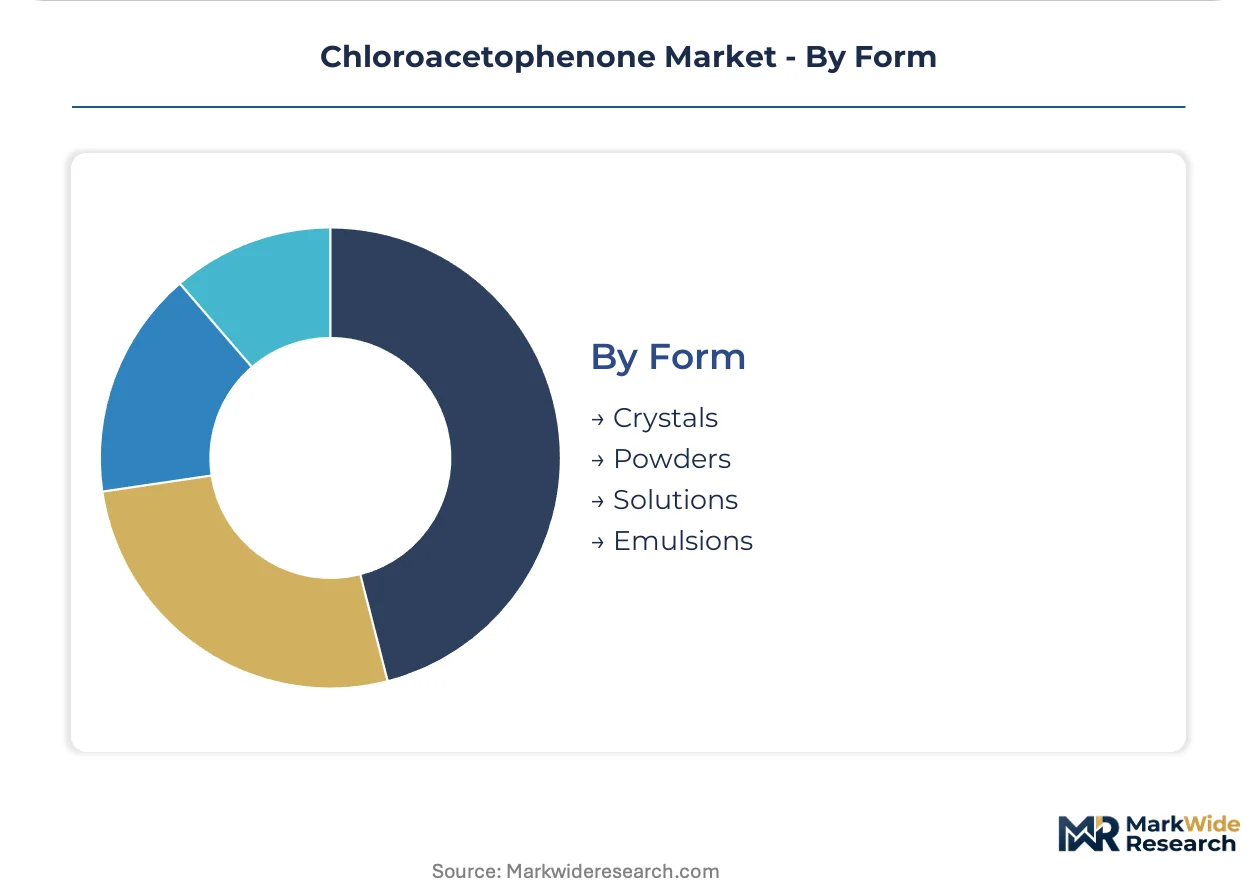
Form:
Physical form selection determines logistics economics, with crystalline stability enabling longer supply chains than solution formulations permit.
- Crystals:Stable shelf-life characteristics support intercontinental shipment to European and North American pharmaceutical manufacturers. Solid-form products lead shipment volumes for inventory-holding efficiency.
- Powders:Milled particle size grades accelerate dissolution rates in batch chemical processing, serving agrochemical blenders with rapid formulation turnaround requirements.
- Solutions:Liquid feedstock compatibility penetrates automated chemical handling systems, displacing manual operations in high-throughput Indian and Chinese processing lines.
- Emulsions:Stabilized colloidal dispersions serve specialized agrochemical delivery systems requiring extended field persistence.
Crystalline forms dominate existing inventory infrastructure. Solution formulations are gaining share fastest as continuous processing adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting chloroacetophenone production toward jurisdictions where compliance costs remain manageable relative to enforcement rigor. India's PLI subsidies and China's dual carbon enforcement create divergent cost structures that reshape supplier selection.
China
Fine-chemical manufacturers in Lianyungang and Shanghai are expanding phenacyl chloride capacity to capture pharmaceutical intermediate orders from South Asia. MEE's dual carbon goals elevate energy costs for chlorination-stage production, favoring integrated producers with captive power. The Yangtze River Delta corridor anchors eastern China's supply concentration with dedicated phenylacetone derivative lines.
India
Maharashtra's pharmaceutical API clusters are consolidating chloroacetophenone procurement under three-year supply locks for ketamine synthesis. CDSCO's tightened narcotic precursor traceability rules extend customs clearance cycles for exporters. The Mumbai-Pune corridor is drawing capacity expansion under the PLI scheme for specialty chemicals.
Germany
Agrochemical blenders in Germany now require full substance volume tracking from Indian exporters under REACH Article 33 obligations. ECHA's skin sensitizer classification forces reformulation investments in seed treatment coatings. The Rhine-Ruhr industrial region is experiencing delayed product re-registration timelines as downstream users substitute phenacyl chloride derivatives.
United States
Generic anesthetic manufacturers are scaling phenacyl chloride offtake under FDA narcotic substance protocols that scrutinize cross-border documentation. The FDA's precursor tracking requirements extend contract negotiation cycles with Asian suppliers. Research institutions along the Boston-Cambridge corridor source high-purity crystals for analytical applications.
Japan
Pharmaceutical intermediate demand from METI-regulated manufacturers is sustaining specialized output for reproducible impurity profile requirements. PMDA's alignment with international GMP standards creates certification premiums for qualified suppliers. The Kansai region's chemical processing lines are adopting solution-formulation compatibility for automated handling systems.
Chloroacetophenone Market Key Industry Players
Chinese producers anchor the scale-driven tier; Indian specialists hold the contract-manufacturing position. The vendor base splits between integrated phenylacetone derivative manufacturers and trading intermediaries absorbing inventory risk. Two strategic archetypes dominate: vertically integrated chemical parks with captive analytical capabilities, and compliance-focused custom synthesis houses serving pharmaceutical certification requirements. Capacity expansion and long-term offtake bundling constitute the prevailing competitive moves.
Among China-based fabricators, Lianyungang Guangda Chemical Co. Ltd. and TCI (Shanghai) Development Co., Ltd. occupy positions within the integrated production tier, representing the scale-driven archetype with eastern China supply base concentration. Capot Chemical Co. Ltd. exemplifies the custom synthesis specialist archetype, sitting within the compliance-focused segment targeting European pharmaceutical standards. These three entities collectively illustrate the geographic and strategic bifurcation shaping supplier selection.
| Leading Market Players |
|---|
| TCI (Shanghai) Development Co., Ltd. |
| Santa Cruz Biotechnology, Inc. |
| Fisher Scientific |
| SynZeal |
| Lianyungang Guangda Chemical Co. Ltd. |
| Taj Pharmaceuticals Ltd. |
| Val Organics Pvt. Ltd. |
| Capot Chemical Co. Ltd. |
| Neuchatel Chemie Specialities |
| Others |
Cost & Logistics Intelligence
Chloracetyl chloride cost volatility transmits directly through phenacyl chloride pricing tiers, compressing margins for fixed-price pharmaceutical contract manufacturers while rewarding integrated producers with captive chlorination capacity in eastern China's chemical parks.
Pricing Analysis
Distributor markups widen sharply between pharmaceutical-grade crystal and industrial chemical intermediate tiers, with GMP certification and CDSCO precursor documentation commanding substantial premiums over bulk aryl ketone building blocks. Three-tier pricing structure across pharmaceutical-grade, agrochemical-grade, and general industrial grades reflects purity thresholds and regulatory burden rather than manufacturing cost alone. Pricing pressure stems from chloracetyl chloride feedstock volatility in spot chlorine and acetic acid markets, squeezing contract manufacturers locked into long-term fixed-price pharmaceutical orders. Generic anesthetic API producers in Maharashtra exhibit lowest price sensitivity due to narcotic precursor traceability requirements, while agrochemical blenders facing ECHA-driven reformulation investments show highest sensitivity to input cost fluctuations.
Supply Chain Analysis
Freight cost differentials between solid crystalline shipments and liquid solution formulations are reshaping procurement patterns, with automated processing lines in Indian and Chinese chemical parks favoring liquid-form compatibility despite higher per-unit logistics expenditure. Supply concentrates in China and India, with Lianyungang and Shanghai producers anchoring bulk export volumes while Maharashtra's Mumbai-Pune corridor consolidates ketamine API procurement. Raw material dependencies center on benzene feedstock, chlorine gas, and chloracetyl chloride intermediates, with acylation-stage production drawing from regional petrochemical complexes. Single-source vulnerability runs through eastern China's phenylacetone derivative concentration, exposing European agrochemical blenders to disruption risk. Distribution runs through long-term offtake agreements bundling technical support and regulatory documentation, displacing spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chloroacetophenone quality specifications are hardening as pharmaceutical API manufacturers prioritize reproducible impurity profiles and CDSCO-aligned traceability over volume discounts, elevating late-cycle positioning for GMP-certified producers.
For Market Incumbents: Extend captive analytical capabilities and backward integration into chloracetyl chloride production to defend margin position against feedstock volatility and emerging continuous flow reactor specialists. Secure three-year supply locks with Maharashtra's ketamine API producers before PLI scheme subsidies attract additional capacity entrants. Prioritize REACH Article 33 documentation infrastructure to maintain European agrochemical blender relationships amid substitution pressure from skin sensitizer classification. For New Entrants and Emerging Players: Contract research organizations and custom synthesis houses represent the most penetrable channel partner type for building initial revenue traction without GMP facility capital requirements. Target ASEAN flavoring agent certification pathways where phenacyl chloride derivative regulations remain less harmonized than pharmaceutical precursor controls. Lead with automated processing solution compatibility and liquid-formulation technical support to differentiate from established solid-form commodity suppliers. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale custom synthesis specialists because CDSCO and FDA documentation burdens are consolidating procurement under integrated producers with captive regulatory affairs capabilities. Five-to-ten year viability favors GMP-aligned facilities with long-term pharmaceutical contracts over trading intermediaries absorbing inventory risk. Monitor chloracetyl chloride spot market volatility as inflection indicator for contract manufacturer margin stress and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chloracetyl Chloride | Captive feedstock supply insulates phenacyl chloride margins from chlorine gas spot volatility. |
| Continuous Flow Reactor Adoption | CDSCO pressure for reproducible impurity profiles accelerates batch-to-batch consistency investments. |
| Long-term Supply Agreement Bundling | Three-year offtake locks with Maharashtra API producers transfer compliance burden upstream. |
| REACH Article 33 Documentation Infrastructure | Full substance volume tracking secures German and French agrochemical blender relationships. |
| ASEAN Flavoring Agent Certification | Synthetic vanilla and almond flavor pathways open regulatory arbitrage ahead of harmonization. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Lianyungang and Shanghai chemical parks, procurement leads at Maharashtra pharmaceutical API clusters, distribution channel partners serving European agrochemical blenders, and technical R&D directors at custom synthesis houses. Secondary validation drew from customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed specialty chemical producers, and CDSCO narcotic precursor regulatory filings. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting approaches applied differential growth assumptions by product form, application tier, and regional regulatory cluster. The analytical framework modeled pharmaceutical-grade versus industrial-grade purity thresholds, solid versus liquid formulation adoption rates, and captive versus merchant supply chain configurations throughout the forecast period. CAGRs derived from historical volume trajectories adjusted for PLI scheme subsidy impacts, ECHA reformulation timelines, and continuous flow reactor penetration curves. Industry-specific inputs included chloracetyl chloride feedstock cost indices and CDSCO precursor enforcement intensity metrics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to dual carbon enforcement intensity in China, REACH regulatory expansion, and ketamine API demand shifts under international narcotic control protocols. Forecasts reflect assumptions about regulatory harmonization trajectories and feedstock cost stabilization. A model refresh is warranted upon material change in CDSCO precursor tracking requirements or chloracetyl chloride supply disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America Acrylamide Monomer Market
Bulk Chemicals
FT Wax Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
Foundry Coke Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Alkali Metal Hydroxides Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
Fine Hydrate Market
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
North America Calcium Carbonate Market
Bulk Chemicals
Green Petroleum Coke and Calcined Petroleum Coke Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
North America Starch Derivatives Market
Bulk Chemicals
Lysine Market