
 Global Electrophoresis Reagents Market | 2026-2036
Global Electrophoresis Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrophoresis Reagents Market Foresight
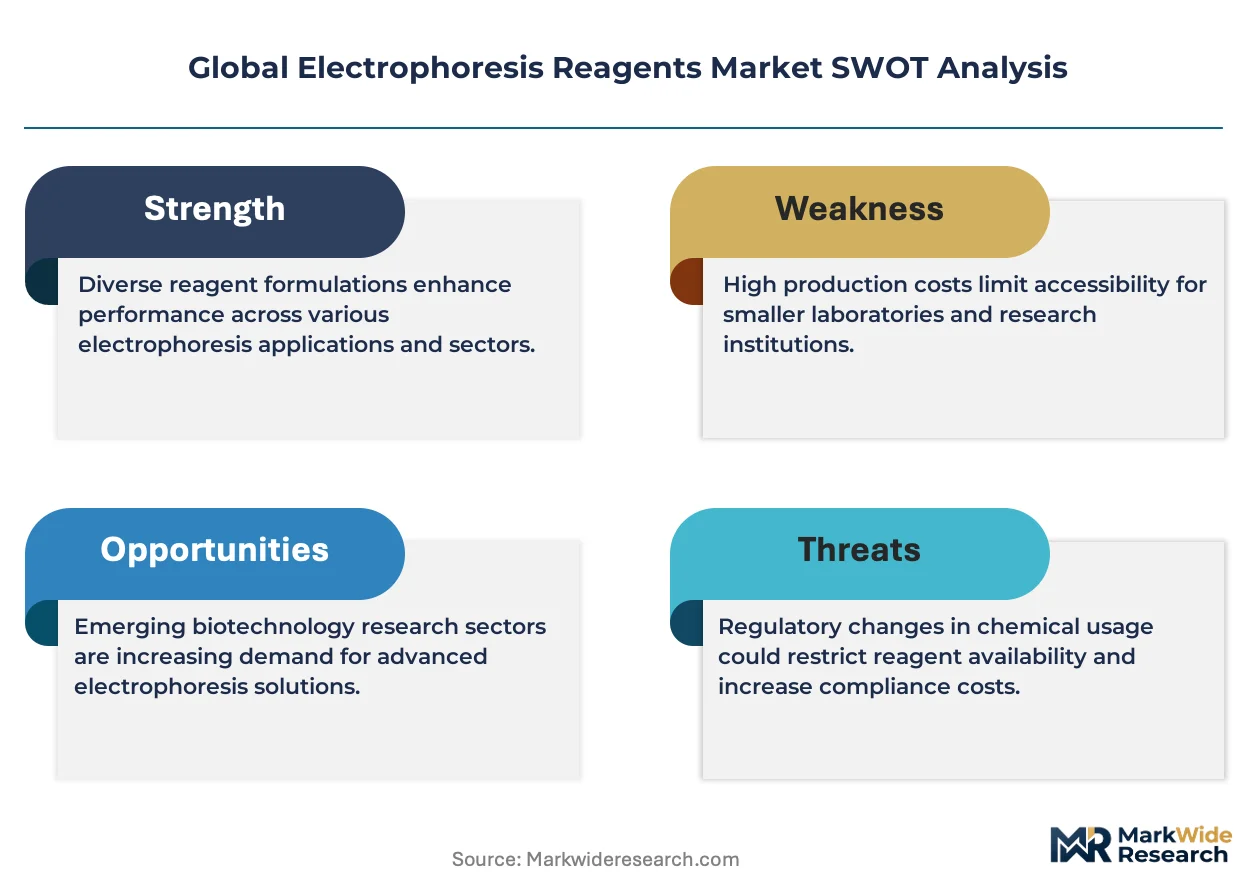
ISO 13485 certification for in vitro diagnostic reagents is reorganizing supplier eligibility across the electrophoresis value chain, forcing smaller chemical providers to upgrade quality management systems or exit clinical-grade segments. Thermo Fisher Scientific leverages its captive chromatography resin production to secure buffer supply continuity for high-throughput capillary electrophoresis platforms. Bio-Rad Laboratories anchors its position through proprietary staining dye formulations that serve both research and regulated diagnostic workflows. Merck KGaA competes on pharmaceutical-grade raw material traceability, extending its historical solvent expertise into gel concentrate manufacturing.
Electrophoresis reagents comprise buffer solutions, staining dyes, gel concentrates, molecular weight markers, and loading buffers formulated to precise ionic strength and pH specifications for biomolecule separation. These reagents enable nucleic acid sizing, protein purity verification, and forensic fragment analysis by establishing controlled electric-field migration environments. Capillary electrophoresis technology commands premium pricing due to its integration with automated sequencing instruments in pharmaceutical quality control laboratories. Staining dyes represent a mature margin pool where product differentiation hinges on sensitivity thresholds and environmental safety profiles rather than fundamental chemistry innovation. DNA analysis applications sustain the largest volume pull, though protein separation reagents are gaining share as biologics development pipelines expand.
The FDA enforces current Good Manufacturing Practice standards for diagnostic-grade reagents, while the EMA's In Vitro Diagnostic Regulation requires enhanced performance documentation for CE-marked electrophoresis kits. China's NMPA implements GB standards for imported biological reagents, creating registration barriers that favor domestic buffer manufacturers with established compliance teams. Stakeholders must monitor evolving pharmacopeial monographs for electrophoresis buffers as regulatory bodies harmonize analytical method requirements across jurisdictions.
Market Dynamics
ISO 13485 certification requirements are reorganizing supplier eligibility across the electrophoresis value chain, forcing smaller chemical providers to upgrade quality management systems or exit clinical-grade segments entirely. Pharmaceutical-grade traceability mandates now filter procurement decisions at major sequencing facilities and contract research organizations.
Growth Catalysts
- Biologics quality control expansion:Pharmaceutical manufacturers are scaling electrophoresis workflows for monoclonal antibody purity verification, creating sustained demand for high-sensitivity staining dyes and molecular weight markers.
- FDA analytical method validation:Updated guidance on reagent qualification is tightening documentation requirements, favoring suppliers with established current Good Manufacturing Practice infrastructure.
- Capillary electrophoresis automation:Integration with high-throughput sequencing platforms in quality control laboratories commands premium pricing for buffer solutions with precise ionic specifications.
Market Restraints
- Acrylamide monomer price volatility:Gel concentrate manufacturers face margin compression from petrochemical feedstock fluctuations and specialized polymer purification costs.
- Supply concentration in chromatography resins:Captive production of buffer components by integrated platform vendors limits third-party reagent penetration in automated capillary systems.
- EMA In Vitro Diagnostic Regulation documentation:Enhanced performance validation requirements for CE-marked kits extend product registration timelines and increase regulatory compliance expenditure.
Strategic Opportunities
- China NMPA registration pathways:GB standards for imported biological reagents favor domestic buffer manufacturers with established compliance teams, creating partnership opportunities for foreign gel chemistry specialists.
- Protein separation reagent expansion:Biologics development pipelines are diversifying demand beyond DNA analysis into antibody fragment sizing and purity verification workflows.
- Environmental safety profile differentiation:Staining dye reformulation to eliminate hazardous waste classification opens procurement access to sustainability-mandated academic and government sequencing facilities.
Industry Challenges
- Analytical method harmonization:Divergent pharmacopeial monographs for electrophoresis buffers across FDA, EMA, and NMPA jurisdictions force multi-standard formulation development and inventory complexity.
- ISO 13485 quality management system implementation:Small and mid-size chemical suppliers struggle with documentation infrastructure upgrades required for clinical-grade reagent segments, creating talent acquisition bottlenecks in quality assurance functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrophoresis Reagents Market |
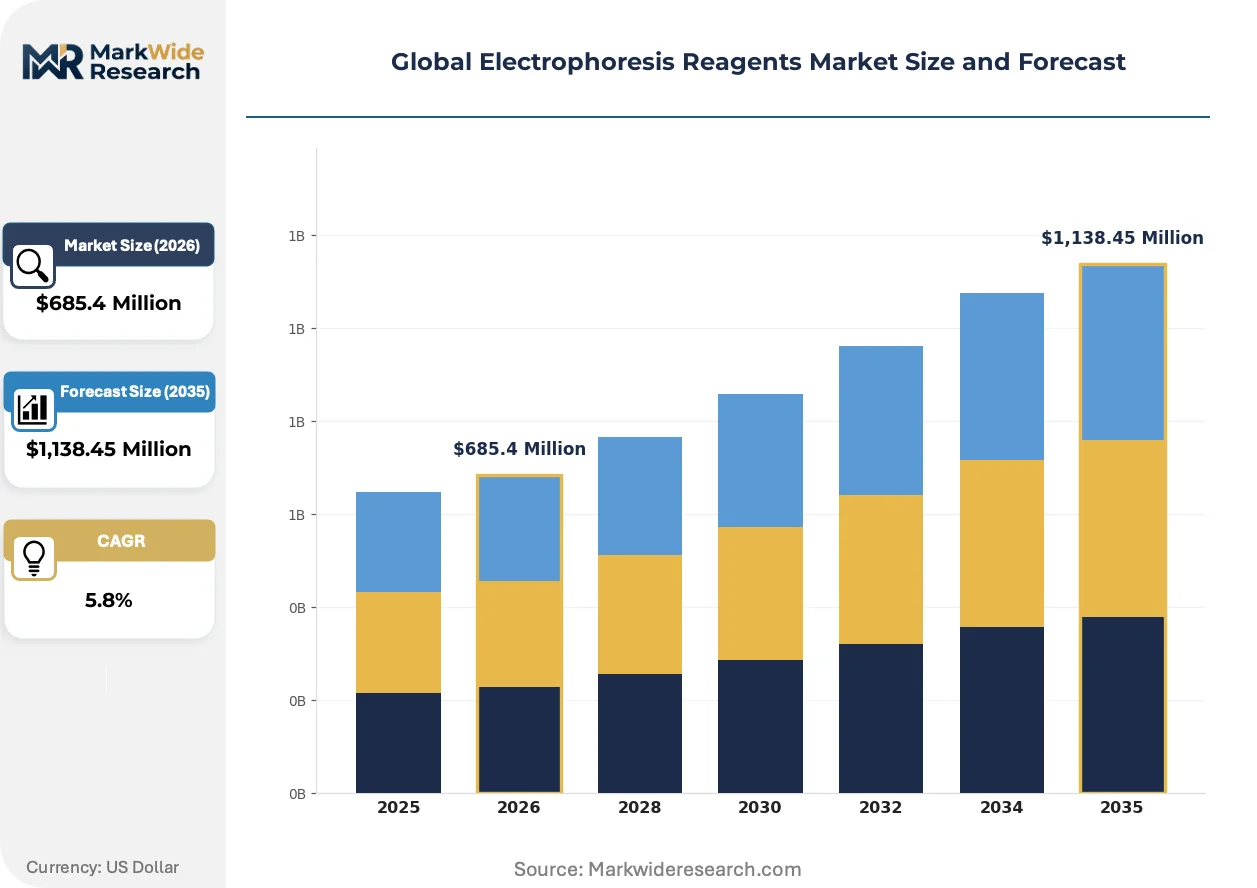
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Buffer Solutions, Staining Dyes, Gel Concentrates, Molecular Weight Markers, Loading Buffers Technology: Agarose Gel Electrophoresis, Polyacrylamide Gel Electrophoresis, Capillary Electrophoresis, Isoelectric Focusing, Two-Dimensional Gel Electrophoresis Application: DNA Analysis, Protein Separation, RNA Isolation, Forensic Studies, Clinical Diagnostics End User: Research Institutes, Diagnostic Laboratories, Pharmaceutical Companies, Biotechnology Firms, Academic Institutions |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Inc., Merck KGaA, Agilent Technologies Inc., QIAGEN N.V., Lonza Group AG, GE Healthcare, Sigma-Aldrich, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrophoresis Reagents Market Shifts & Advancements
Pre-formulated buffer systems and ready-to-use gel concentrates are displacing laboratory-prepared reagents, reshaping purchasing patterns toward certified, lot-traceable products with documented stability data.
Capillary electrophoresis technology is fragmenting the separation reagent landscape by embedding consumables into closed-platform ecosystems. Pharmaceutical quality control laboratories now prioritize vendor-locked buffer cartridges over open-system chemicals. This integration is compressing margins for independent reagent suppliers while concentrating volume with platform-integrated chemistry providers.
REACH substance restrictions on acrylamide and related polymerization catalysts are forcing reformulation of traditional gel matrices. European manufacturers face substitution timelines for cross-linking agents in PAGE systems. Diagnostic-grade gel producers are responding with alternative polymer chemistries that maintain resolution performance while meeting ECHA authorization requirements.
Consolidated procurement by multi-site sequencing networks is unbundling reagent purchasing from instrument service contracts. Large contract research organizations now negotiate direct buffer supply agreements separate from capillary electrophoresis platform vendors. This channel disintermediation is most visible in United States and Germany, where academic sequencing core facilities aggregate demand across institutional consortia.
Global Electrophoresis Reagents Market Segmentation
Electrophoresis reagents fragment across four critical dimensions that determine procurement patterns, margin structures, and regulatory exposure. Product chemistry dictates manufacturing complexity and certification requirements. Technology platforms create vendor lock-in effects that reshape competitive dynamics. Application focus channels R&D investment toward nucleic acid or protein workflows. End-user concentration in pharmaceutical quality control and academic sequencing cores concentrates volume with specific performance specifications.
Product Type:
Buffer solutions and staining dyes dominate export flows from Germany and the United States to sequencing facilities across Asia-Pacific, while gel concentrates and molecular weight markers retain stronger domestic manufacturing footprints due to polymer chemistry expertise.
- Buffer Solutions:Ionic strength and pH specifications are formulated precisely for capillary electrophoresis platforms. Pharmaceutical quality control laboratories in the United States and Germany command premium pricing for lot-traceable products with documented stability data.
- Staining Dyes:Sensitivity thresholds and environmental safety profiles differentiate mature margin pools. REACH substance restrictions are forcing European manufacturers toward alternative chemistries that eliminate hazardous waste classification.
- Gel Concentrates:Acrylamide monomer purification requirements concentrate production with petrochemical-integrated suppliers facing margin compression from feedstock volatility.
- Molecular Weight Markers:Calibrated reference standards for nucleic acid sizing and protein purity verification require ISO 13485-certified manufacturing infrastructure.
- Loading Buffers:Tracking dye formulations with density agents enable sample visualization during gel migration.
Buffer solutions hold the largest share; momentum sits with staining dyes as environmental safety mandates accelerate reformulation cycles.
Technology:
Platform selection determines reagent format—open-system chemicals versus vendor-locked consumables—with capillary electrophoresis commanding steepest pricing tiers due to automation integration.
- Agarose Gel Electrophoresis:Low-resolution nucleic acid separation for routine DNA sizing applications. Academic sequencing core facilities in the United States and Germany sustain volume through high-throughput screening workflows.
- Polyacrylamide Gel Electrophoresis:High-resolution protein and nucleic acid separation requiring acrylamide-bisacrylamide cross-linking chemistry. REACH authorization timelines are compressing European supplier margins.
- Capillary Electrophoresis:Automated separation integrated with sequencing instruments. Pharmaceutical quality control laboratories prioritize vendor-locked buffer cartridges over open-system chemicals.
- Isoelectric Focusing:Protein separation by isoelectric point using pH gradient gels.
- Two-Dimensional Gel Electrophoresis:Combined isoelectric focusing and SDS-PAGE for complex protein mixture resolution.
Capillary electrophoresis generates the highest revenue per unit; agarose gel electrophoresis maintains the broadest installed base across academic consortia.
Application:
DNA analysis workflows concentrate demand in forensic laboratories and sequencing facilities, while protein separation applications are climbing the fastest as biologics pipelines expand purity verification requirements.
- DNA Analysis:Nucleic acid sizing, genotyping, and fragment analysis for forensic and research applications. Contract research organization clusters in the United States and China aggregate the largest volume pull.
- Protein Separation:Purity verification, molecular weight determination, and antibody fragment sizing. Monoclonal antibody manufacturing quality control in Germany and Switzerland is diversifying demand beyond traditional nucleic acid workflows.
- RNA Isolation:Integrity assessment and size profiling for transcriptomics research.
- Forensic Studies:DNA fingerprinting and short tandem repeat analysis for criminal justice systems.
- Clinical Diagnostics:Hemoglobin variant detection and serum protein analysis for disease monitoring.
DNA analysis commands the greatest absolute volume; protein separation is gaining share fastest as biologics development accelerates.
End User:
Pharmaceutical companies and diagnostic laboratories concentrate procurement of clinical-grade reagents with ISO 13485 certification, while research institutes and academic institutions drive open-system chemical demand.
- Research Institutes:Basic science applications requiring flexible reagent formats and cost-sensitive procurement. Multi-site sequencing networks in Germany are consolidating purchasing across institutional consortia.
- Diagnostic Laboratories:Regulated workflows requiring CE-marked kits and FDA-compliant documentation. EMA In Vitro Diagnostic Regulation performance validation is extending registration timelines.
- Pharmaceutical Companies:Biologics quality control with current Good Manufacturing Practice infrastructure. Monoclonal antibody purity verification in the United States and Switzerland sustains premium buffer demand.
- Biotechnology Firms:Process development and analytical method validation for therapeutic candidates.
- Academic Institutions:Teaching laboratories and core sequencing facilities with sustainability-mandated procurement policies.
Pharmaceutical companies represent the highest-value segment; biotechnology firms are expanding most quickly as therapeutic pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's updated guidance on analytical method validation is tightening reagent qualification requirements across pharmaceutical quality control laboratories. The EMA's In Vitro Diagnostic Regulation imposes enhanced performance documentation mandates for CE-marked electrophoresis kits. China's NMPA implements GB standards that favor domestic buffer manufacturers with established compliance infrastructure.
United States
Monoclonal antibody purity verification workflows and forensic DNA analysis sustain demand for high-sensitivity staining dyes and molecular weight markers. FDA current Good Manufacturing Practice standards filter procurement decisions at major sequencing facilities and contract research organizations. Boston-Cambridge and San Diego biotech clusters concentrate pharmaceutical-grade reagent consumption for biologics development pipelines.
Germany
Academic sequencing core facilities and industrial proteomics laboratories drive premium buffer demand for capillary electrophoresis platforms. REACH substance restrictions on acrylamide monomer force reformulation timelines for PAGE gel concentrate manufacturers. Munich and Heidelberg host the largest contract research organization clusters for protein separation reagent qualification.
China
NMPA GB standards for imported biological reagents create registration barriers that accelerate domestic buffer manufacturer expansion. Government funding for precision medicine initiatives channels investment into nucleic acid sizing workflows. Shanghai and Beijing academic sequencing facilities aggregate volume across institutional consortia with sustainability-mandated procurement policies.
Switzerland
Swissmedic pharmaceutical-grade traceability mandates align with ISO 13485 certification requirements for diagnostic reagent suppliers. Basel's monoclonal antibody manufacturing hub sustains premium demand for protein purity verification reagents. The country's solvent expertise infrastructure extends into gel concentrate manufacturing for European export markets.
Japan
PMDA quality standards for in vitro diagnostic reagents enforce documentation rigor comparable to FDA and EMA frameworks. Tokyo-Osaka pharmaceutical corridors integrate capillary electrophoresis automation into biologics quality control workflows. Domestic buffer manufacturers leverage established compliance teams to serve regional sequencing network procurement consolidation.
Global Electrophoresis Reagents Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with captive chromatography resin production and specialized reagent formulators with proprietary dye chemistry. Market structure concentrates volume among three strategic archetypes: integrated platform vendors embedding consumables into closed-system ecosystems, independent chemical suppliers competing on pharmaceutical-grade traceability, and regional manufacturers exploiting NMPA registration advantages in China. Dominant competitive moves include backward integration into buffer component production and strategic partnerships to secure ISO 13485 certification infrastructure.
Among diversified conglomerates, Thermo Fisher Scientific and Bio-Rad Laboratories exemplify contrasting approaches to reagent market positioning. Thermo Fisher represents the integrated archetype with captive supply chain control over chromatography resin production. Bio-Rad occupies a position emphasizing proprietary formulation expertise in staining dye chemistry. Merck KGaA sits within the pharmaceutical-grade raw material traceability tier, extending historical solvent manufacturing capabilities into gel concentrate production. These three entities collectively illustrate how supplier eligibility reorganizes around quality management system certification and regulatory documentation infrastructure.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories, Inc. |
| Merck KGaA |
| Agilent Technologies Inc. |
| QIAGEN N.V. |
| Lonza Group AG |
| GE Healthcare |
| Sigma-Aldrich |
| Promega Corporation |
| Others |
Supply & Pricing Matrix
Acrylamide monomer purification capacity utilization rates in Germany and the United States determine gel concentrate cost floors while simultaneously concentrating supply leverage with petrochemical-integrated manufacturers. This scale asymmetry compresses margins for independent formulators and amplifies pricing power for buffer solution suppliers serving ISO 13485-certified clinical segments.
Pricing Analysis
Certification level creates the primary spread between premium FDA-grade buffers and economy research-grade alternatives. Three-tier pricing structure across pharmaceutical-grade, diagnostic-grade, and research-grade levels reflects documentation burden and traceability investment. Pricing pressure stems from REACH substance restrictions forcing acrylamide reformulation timelines in European manufacturing. Academic sequencing core facilities exhibit highest price sensitivity; pharmaceutical quality control laboratories absorb premium tiers for vendor-locked capillary electrophoresis cartridges.
Supply Chain Analysis
Acrylamide monomer feedstock transit through Rotterdam and Houston petrochemical hubs underwrites gel concentrate availability for PAGE system manufacturers. Germany, the United States, and China anchor buffer solution formulation capacity, while Switzerland hosts pharmaceutical-grade solvent purification infrastructure. Raw material dependencies center on acrylamide-bisacrylamide cross-linking agents, chromatography-grade solvents, and fluorescent dye precursors. Single-source vulnerability concentrates in chromatography resin production controlled by integrated platform vendors. Distribution runs through contract research organization procurement consortia and academic core facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reagent lot-traceability services and stability monitoring subscriptions are expanding faster than instrument hardware sales as pharmaceutical quality control laboratories outsource documentation compliance. This service-attach dynamic repositions chemistry suppliers toward recurring revenue models anchored in regulatory file maintenance.
For Market Incumbents: Secure backward integration into buffer component production to defend against captive chromatography resin supply by integrated platform vendors. Expand ISO 13485-certified manufacturing footprint in China to preempt NMPA registration barriers for imported clinical-grade reagents. Lock in multi-year buffer supply agreements with Boston-Cambridge biotech clusters before consolidated procurement by multi-site sequencing networks accelerates.
For New Entrants and Emerging Players: Differentiate on environmental safety profile reformulation to access sustainability-mandated academic procurement channels. Target protein separation reagent white space in antibody fragment sizing workflows where biologics pipelines outpace established supplier capacity. Enter through partnership with domestic Chinese buffer manufacturers lacking gel chemistry expertise but holding NMPA compliance infrastructure.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized formulators with proprietary dye chemistry over diversified conglomerates facing platform commoditization. Long-term viability hinges on regulatory documentation capabilities rather than fundamental chemistry innovation. Acquisition target archetype: ISO 13485-certified gel concentrate manufacturers with REACH-compliant alternative polymer portfolios. Watch for EMA In Vitro Diagnostic Regulation enforcement intensity as inflection indicator for CE-marked kit registration timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks clinical-grade reagent procurement eligibility at FDA-regulated diagnostic laboratories. |
| REACH-Compliant Gel Reformulation | Eliminates hazardous waste classification and sustains European manufacturing authorization. |
| Capillary Electrophoresis Buffer Cartridge Development | Captures vendor-locked premium pricing in pharmaceutical quality control automation. |
| NMPA Registration Partnership | Accelerates market access for foreign gel chemistry specialists in China. |
| Stability Data Documentation Service | Converts transactional reagent sales into recurring regulatory file maintenance contracts. |
Research Methodology
Cross-validation between primary interviews with electrophoresis platform engineers and secondary regulatory filing analysis anchors the qualitative findings on certification requirement evolution. Conversations with pharmaceutical quality control directors, academic sequencing core facility managers, diagnostic laboratory procurement leads, and gel chemistry R&D specialists generated demand-side insight. FDA guidance documents, EMA In Vitro Diagnostic Regulation technical files, NMPA GB standard registrations, and REACH authorization timelines supplied secondary validation. Bottom-up reagent consumption modeling triangulated against top-down pharmaceutical biologics pipeline forecasts.
Sensitivity analysis across acrylamide feedstock price scenarios and regulatory enforcement intensity variations stress-tested projection robustness. Segmentation dimensions span product chemistry tier, technology platform integration level, application workflow type, and end-user certification requirements. CAGRs were derived from fitted growth curves calibrated to documented biologics quality control expansion rates and academic sequencing facility capital investment cycles. Forecast inputs incorporate pharmacopeial monograph harmonization timelines and capillary electrophoresis platform installation base trajectories.
Material uncertainties — REACH authorization delays, NMPA registration pathway modifications, and acrylamide monomer supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory enforcement continuity and petrochemical feedstock price stability. Practitioners should keep alternative scenarios live as EMA In Vitro Diagnostic Regulation implementation intensity and China precision medicine funding allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Potassium Benzoate Market
Chemical Intermediates
Dye Intermediates Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Global Aniline Derivative Market
Chemical Intermediates
Leather Chemicals Market
Chemical Intermediates
Carboxylic Acid Chlorides Market
Chemical Intermediates
2-Acetylthiophene Market
Chemical Intermediates
Methoxypropylamine (MOPA) Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Acetoacetanilide Market
Chemical Intermediates
Acid Chlorides Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Diketene Derivatives Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Refinery Process Chemicals Market