
 Heptanoic Acid Market | 2026-2036
Heptanoic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Heptanoic Acid Market Outlook
REACH is rebalancing the cost-of-entry calculus for European suppliers, forcing upstream investment in purity certification and traceability systems. OQ Chemicals GmbH leverages its integrated C4 chemistry platform to sustain margin capture across industrial-grade heptanoic acid. Arkema anchors its position through specialty ester derivatives for high-performance lubricants. Jinan Chenghui Shuangda Chemical Co., Ltd. competes on pharmaceutical-grade volume from Shandong Province.
Heptanoic acid is a seven-carbon saturated fatty acid (C7H14O2) synthesized via oxo-chemistry or fermentation routes, serving as a critical building block for esters, salts, and synthetic lubricant base stocks. Food-grade and pharmaceutical-grade segments command premium positioning due to stringent purity thresholds and batch-certification requirements, while industrial-grade volumes dominate tonnage through lubricant and plasticizer applications. Chemical intermediates and flavoring agents represent the fastest-growing application clusters as downstream formulators seek bio-based feedstock alternatives.
EMA pharmaceutical guidelines, REACH substance registration, and FDA food-contact regulations collectively shape product specifications and market access corridors for heptanoic acid producers. EMA's evolving impurity profiling standards for excipient-grade materials directly filter which suppliers qualify for European pharmaceutical contracts. Stakeholders must monitor regulatory divergence between FDA and EMA purity benchmarks to avoid dual-certification cost traps.
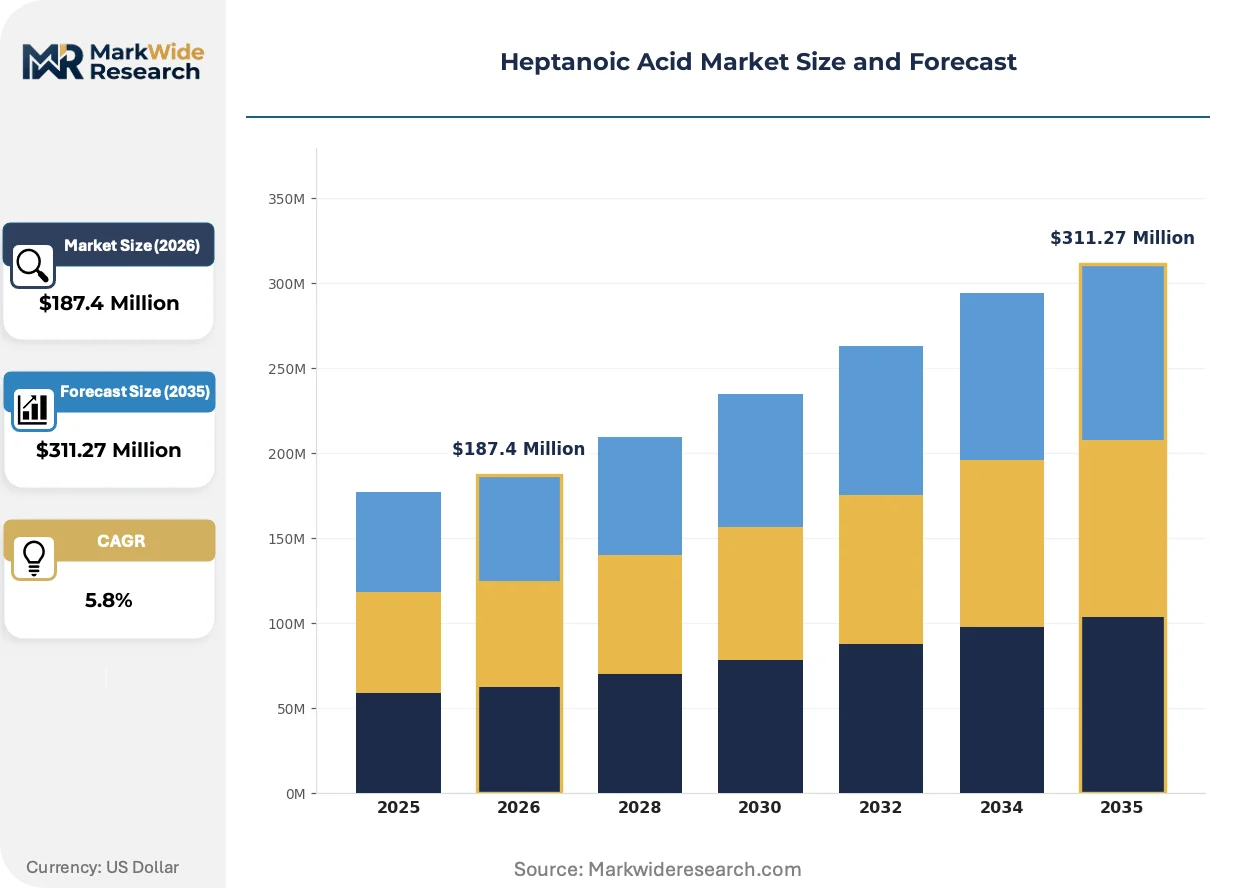
Market Dynamics
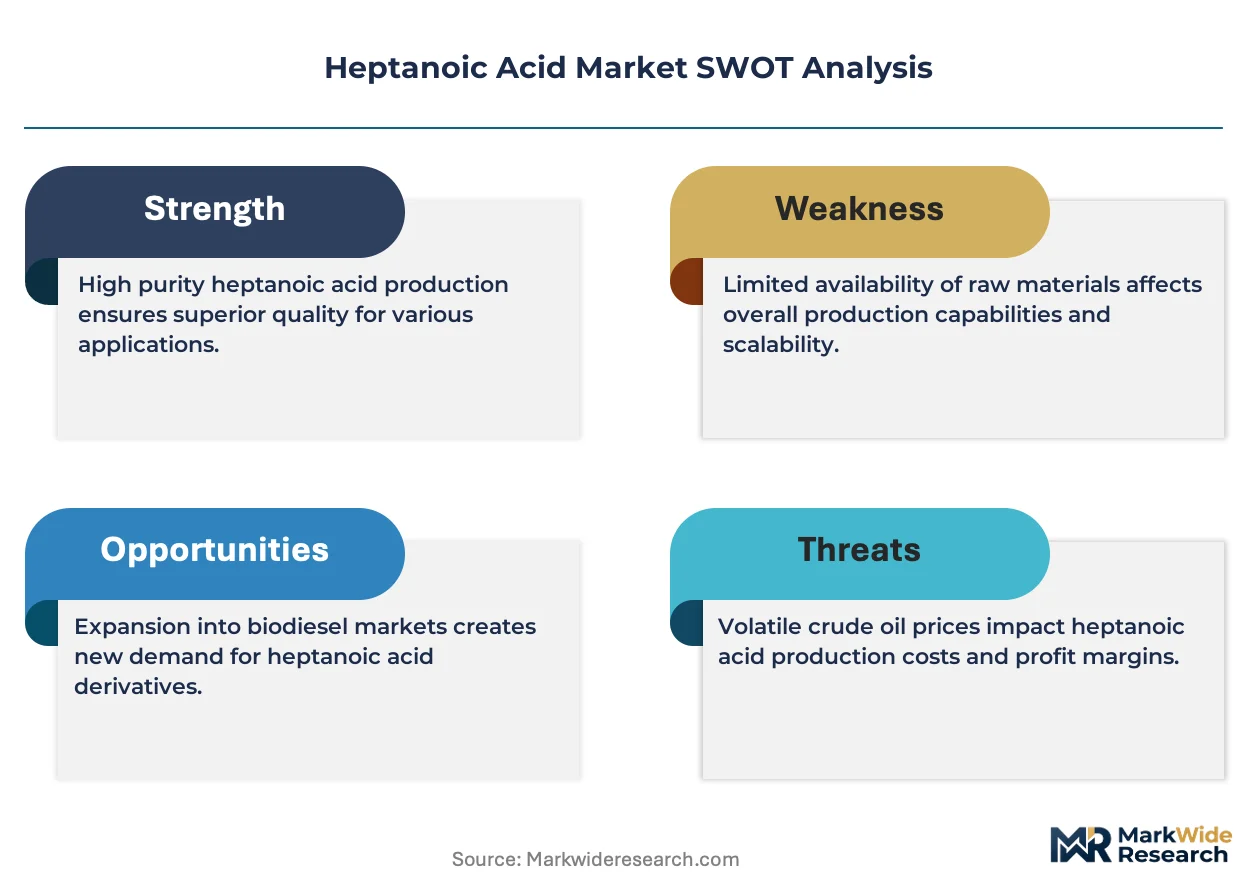
REACH substance registration deadlines are compressing supplier qualification timelines across European pharmaceutical corridors, forcing upstream investment in purity certification infrastructure before 2026 renewal cycles.
Growth Catalysts
- EMA pharmaceutical guidelines:Impurity profiling standards for excipient-grade materials are filtering supplier pools and concentrating contract volumes among certified producers.
- Bio-based feedstock alternatives:Chemical intermediate formulators are pivoting toward fermentation-derived heptanoic acid to meet sustainability procurement mandates.
- Germany's specialty chemical corridor:Demand concentration in Rhineland-Palatinate and North Rhine-Westphalia is anchoring high-purity production investment.
Market Restraints
- Crude oil price volatility:Oxo-chemistry feedstock costs fluctuate with C4 olefin pricing, compressing margin stability for industrial-grade producers.
- REACH compliance costs:European registration fees and toxicity testing requirements create disproportionate barriers for sub-scale suppliers.
- Caprylic acid substitution:Eight-carbon fatty acids compete in lubricant ester applications where viscosity specifications allow chain-length flexibility.
Strategic Opportunities
- India's pharmaceutical manufacturing:CDSCO excipient-grade certification pathways remain underpenetrated relative to formulation volume growth.
- EU Green Deal bio-mandates:Renewable carbon quotas for chemical intermediates are creating preferential offtake terms for fermentation-route producers.
- Direct-to-formulator digital platforms:Specialty ester distributors are bypassing traditional chemical merchant networks in high-performance lubricant segments.
Industry Challenges
- Dual-certification complexity:Divergent FDA and EMA purity benchmarks force redundant analytical method validation for suppliers serving both markets.
- Specialized synthesis talent:Fermentation process engineering expertise for C7 fatty acid production remains concentrated among legacy oxo-chemistry workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heptanoic Acid Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Application: Flavoring Agent, Fragrance, Chemical Intermediates, Lubricants End User: Food & Beverage, Pharmaceuticals, Personal Care, Agriculture Packaging Type: Drum, Bag, Container, Bulk |
| Companies Covered | International Flavors & Fragrances Inc., OQ Chemicals GmbH, Arkema, Jinan Chenghui Shuangda Chemical Co., Ltd., Thermo Fisher Scientific Inc., Merck KGaA, Lanxess AG, Acme Synthetic Chemicals, INEOS Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heptanoic Acid Market Strategic Shifts
Biotechnology process engineering is displacing conventional petrochemical synthesis as the dominant innovation vector, with regulatory carbon accounting accelerating adoption curves across pharmaceutical and food-grade segments.
Precision fermentation using engineered yeast strains is rewriting the cost structure for pharmaceutical-grade heptanoic acid. Specialty chemical divisions at established oxo-chemistry houses are piloting these routes to secure renewable carbon certificates. The technology is compressing the premium gap between bio-based and synthetic feedstocks in European contract negotiations.
REACH authorization requirements for Substances of Very High Concern are tightening impurity disclosure thresholds for chemical intermediates. ECHA dossier updates now mandate analytical detection limits below 100 ppm for specified contaminants. Pharmaceutical excipient suppliers are responding by investing in dedicated batch-traceability systems to preempt audit failures.
Formulator procurement teams are consolidating supplier panels around certified-grade single sources to reduce qualification overhead. Lubricant compounders in the US and Germany are eliminating secondary suppliers for pharmaceutical-grade ester inputs. This concentration is most visible in synthetic base stock procurement for aerospace and medical device applications.
Heptanoic Acid Market Segmentation
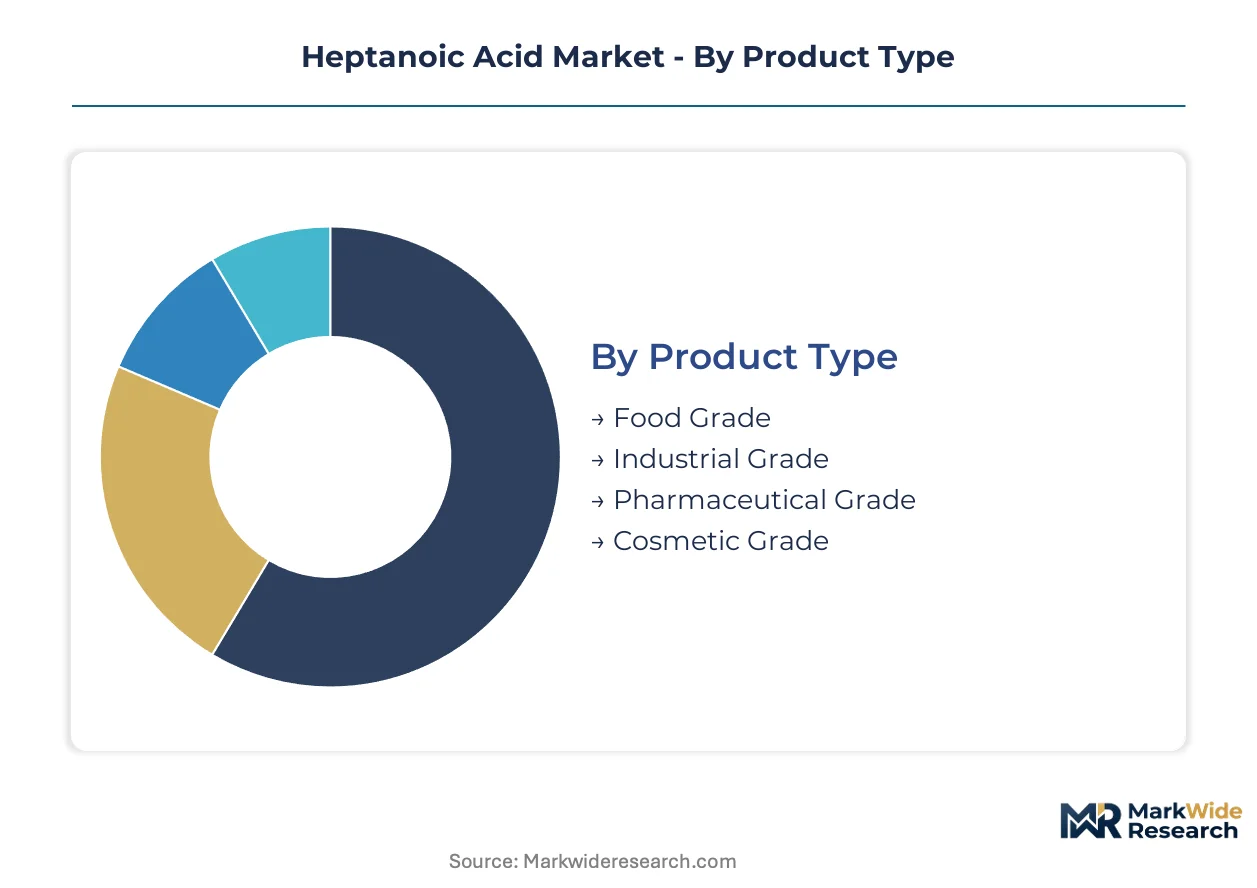
Heptanoic acid segmentation maps directly to certification intensity and end-use liability exposure. Grade differentiation determines regulatory burden, while application clusters reveal where fermentation-derived supply is displacing conventional oxo-chemistry routes.
Product Type:
Specification thresholds separate segments by impurity tolerance, analytical validation requirements, and batch documentation depth.
- Pharmaceutical Grade:Purity exceeds 99.5% with full impurity profiling per EMA and FDA excipient monographs. German and Swiss contract manufacturers dominate procurement, driven by injectable formulation demand and audit-ready traceability mandates.
- Food Grade:Meets FCC and EFSA food-contact specifications with organoleptic neutrality certification. Flavor houses in France and Italy concentrate volume for savory and dairy flavor precursors, constrained by dual-labeling complexity for export markets.
- Industrial Grade:Standard oxo-chemistry output serves synthetic lubricant base stocks and plasticizer applications where color stability and acid value specifications suffice.
- Cosmetic Grade:Intermediate purity tier for ester emollients and fragrance fixatives, governed by EU Cosmetics Regulation microplastic restrictions and preservative compatibility testing.
Mature deployment sits with Industrial Grade. Newer deployment is concentrated in Pharmaceutical Grade.
Application:
End-use functionality dictates molecular modification requirements and downstream formulation integration complexity.
- Chemical Intermediates:Largest volume cluster encompassing heptanoate esters, metal salts, and acyl chloride derivatives. Rhineland-Palatinate specialty chemical producers anchor demand for polymerization catalysts and agrochemical precursors.
- Lubricants:Synthetic ester base stocks for aviation and refrigeration compressors require low pour-point heptanoic acid fractions. German automotive suppliers specify renewable carbon content for EU Green Deal compliance.
- Flavoring Agent:Ethyl and methyl heptanoate production for fruit and dairy flavor profiles, concentrated in Grasse fragrance corridors and New Jersey flavor compounds manufacturing.
- Fragrance:Heptanoic acid derivatives serve as fixative extenders in fine fragrance formulations, facing substitution pressure from bio-identical synthetic molecules.
Volume leadership rests with Chemical Intermediates. Steepest expansion trajectory belongs to Lubricants.
End User:
Customer procurement sophistication ranges from commodity spot purchasing to multi-year excipient qualification programs.
- Pharmaceuticals:Parenteral and topical formulation houses in Germany, Switzerland, and India drive pharmaceutical-grade contract structures. CDSCO certification pathways are opening for Shandong Province suppliers.
- Food & Beverage:Flavor compounders and savory seasoning manufacturers specify food-grade material with kosher and halal certification overlays.
- Personal Care:Cosmetic formulators in France and South Korea demand cosmetic-grade heptanoic acid for emollient esters, navigating EU microplastic and preservative regulatory evolution.
- Agriculture:Agrochemical intermediate producers utilize industrial-grade material for herbicide and fungicide synthesis, exposed to C4 olefin feedstock cost volatility.
Contract discipline is tightest in Pharmaceuticals. Spot market fluidity concentrates in Agriculture.
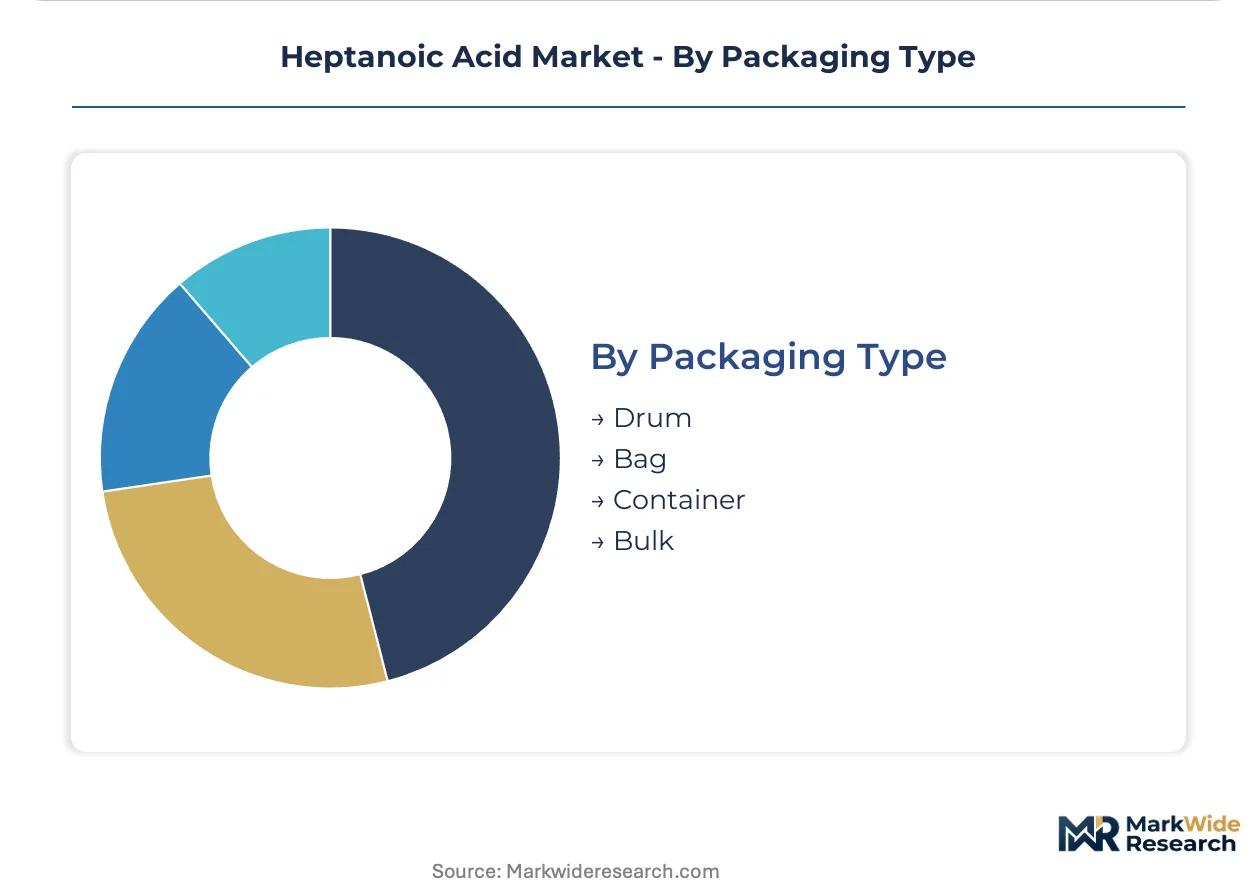
Packaging Type:
Logistics configuration reflects shipment scale, contamination risk, and customer handling infrastructure.
- Drum:Standard 200-liter steel drums dominate pharmaceutical and food-grade shipments requiring sealed, nitrogen-blanketed containment for oxidation-sensitive material.
- Bulk:Tank truck and ISO tank container deliveries serve industrial lubricant compounders with dedicated unloading infrastructure and rapid inventory turnover.
- Container:Intermediate bulk containers and totes support mid-volume chemical intermediate processors with flexible discharge systems.
- Bag:Multi-layer laminate bags for solid heptanoic acid salts and derivatives, limited to stable salt forms with low hygroscopicity.
High-certification segments default to Drum. Cost-optimized industrial flows favor Bulk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhineland-Palatinate chemical corridor anchors European heptanoic acid production through tax-advantaged special economic zones and REACH-aligned purity infrastructure. Shandong Province in China concentrates pharmaceutical-grade fermentation capacity. India's CDSCO certification pathways are opening for excipient-grade suppliers.
Germany
Specialty lubricant compounders in North Rhine-Westphalia and Rhineland-Palatinate drive pharmaceutical-grade demand for synthetic ester base stocks. REACH substance registration deadlines through ECHA compress supplier qualification timelines before 2026 renewal cycles. Ludwigshafen and Leverkusen chemical clusters anchor high-purity production investment for EU Green Deal compliance.
China
Shandong Province fermentation facilities supply pharmaceutical-grade volume for CDSCO-certified export pathways into India. NMPA excipient monographs and dual carbon goals reshape domestic procurement toward bio-based routes. Jinan and Qingdao chemical parks concentrate C7 fatty acid capacity for flavor and fragrance derivative exports.
United States
New Jersey flavor compounders and Texas lubricant blenders split demand between food-grade esters and industrial synthetic base stocks. FDA food-contact regulations and EPA toxicity testing requirements filter supplier pools for pharmaceutical and agricultural chemical applications. Houston's petrochemical corridor maintains oxo-chemistry output for plasticizer and agrochemical intermediate segments.
India
Hyderabad and Mumbai pharmaceutical formulation houses drive excipient-grade procurement as CDSCO certification pathways mature for parenteral drug applications. BIS purity standards and PLI scheme incentives for active pharmaceutical ingredients extend to critical starting materials. Gujarat's specialty chemical zones attract fermentation-route investment for renewable carbon quotas.
Switzerland
Basel-based contract manufacturers anchor European pharmaceutical-grade demand through Swissmedic-certified excipient supply chains. EMA impurity profiling standards filter supplier qualification for injectable formulation applications. Swiss pharmaceutical clusters concentrate procurement around single-source certified suppliers to reduce audit overhead.
Heptanoic Acid Market Competitive Environment
German producers anchor the high-purity tier; Chinese specialists hold volume positions in pharmaceutical-grade fermentation. The vendor base stratifies across integrated oxo-chemistry houses, precision fermentation entrants, and regional ester derivative specialists. Three archetypes dominate: REACH-certified European incumbents, Shandong-based fermentation scale players, and India-focused certification specialists. Competitive moves concentrate on backward integration into C4 feedstock control and fermentation technology licensing.
Within the integrated chemistry tier, OQ Chemicals GmbH and Arkema occupy positions shaped by C4 platform economics and specialty ester derivative focus. Jinan Chenghui Shuangda Chemical Co., Ltd. exemplifies the Shandong fermentation archetype serving pharmaceutical-grade export markets. These three represent the geographic and technological split defining competitive positioning: European REACH compliance, Chinese fermentation scale, and cross-border certification agility.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| OQ Chemicals GmbH |
| Arkema |
| Jinan Chenghui Shuangda Chemical Co., Ltd. |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Lanxess AG |
| Acme Synthetic Chemicals |
| INEOS Group Limited |
| Others |
Value Chain & Pricing Dynamics
C4 olefin feedstock costs cascade through oxo-chemistry production economics, compressing margins for industrial-grade producers while fermentation-route suppliers in Shandong Province capture renewable carbon premiums in European contract negotiations.
Pricing Analysis
Short lead-time premiums for pharmaceutical-grade heptanoic acid widen contract spreads against spot industrial volumes, with German specialty chemical buyers paying certification-linked uplifts for REACH-compliant batch documentation. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects purity thresholds and analytical validation depth. Cost compression in industrial-grade esters stems from caprylic acid substitution in lubricant applications where viscosity specifications permit chain-length flexibility. Agriculture sector buyers exhibit highest price sensitivity, while Swiss pharmaceutical formulators accept premium positioning for single-source qualified supply.
Supply Chain Analysis
Dual-sourcing mandates from German lubricant compounders and Swiss pharmaceutical manufacturers force fermentation-scale players to maintain redundant qualification pathways across Shandong and Rhineland-Palatinate production nodes. Supply concentrates in China, Germany, and India, with C4 olefins, engineered yeast strains, and analytical reagents feeding production networks. Single-source vulnerability intensifies around pharmaceutical-grade fermentation capacity as formulators consolidate supplier panels. Distribution runs through specialty chemical distributors for drum-quantified pharmaceutical shipments and direct tank-truck delivery for industrial lubricant compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology is displacing conventional oxo-chemistry synthesis, with regulatory carbon accounting accelerating adoption curves across certification-intensive segments.
For Market Incumbents: To counter fermentation-route margin compression in pharmaceutical-grade segments, OQ Chemicals GmbH and Arkema should deepen backward integration into C4 feedstock control while licensing precision fermentation technology through specialty chemical divisions. REACH renewal cycles before 2026 create defensive moats for European incumbents with established purity certification infrastructure. For New Entrants and Emerging Players: CDSCO excipient-grade certification pathways in India open a window for Shandong-based fermentation specialists to bypass saturated European supplier pools. White-space concentration sits with parenteral formulation houses in Hyderabad and Mumbai seeking qualified alternative sources. Direct-to-formulator digital platforms bypass traditional chemical merchant networks in high-performance lubricant segments. For Investors and Strategic Acquirers: ECHA dossier updates mandating 100 ppm contaminant detection limits are the leading indicator that batch-traceability system investments will separate viable acquisition targets from stranded capacity. Five-to-ten year viability favors fermentation-scale specialists with CDSCO certification progress and EU Green Deal renewable carbon positioning. Watch for CDSCO approval announcements for Shandong suppliers as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Technology Licensing | Enables oxo-chemistry incumbents to secure renewable carbon certificates for EU Green Deal compliance. |
| Backward Integration into C4 Feedstocks | Stabilizes margin capture for industrial-grade producers exposed to olefin price volatility. |
| CDSCO Certification Investment | Unlocks excipient-grade supply contracts with Indian pharmaceutical formulation houses. |
| Batch-Traceability System Deployment | Preempts REACH audit failures as ECHA tightens impurity disclosure thresholds. |
| Direct-to-Formulator Platform Launch | Bypasses traditional chemical distributors in synthetic lubricant base stock procurement. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at oxo-chemistry facilities, procurement leads at German lubricant compounders, distribution channel partners, and technical R&D directors at fermentation specialists. Bottom-up volume modeling triangulated against top-down value estimates from Cefic sector reports, ECHA registration databases, and SEC filings from specialty chemical divisions.
Data-stream reconciliation across production capacity surveys, import-export statistics, and end-use procurement patterns generated consistent growth trajectories across the projection horizon. Segmentation modeling incorporated grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs derived from weighted average of historical trajectory and technology adoption curve analysis, with fermentation cost reduction curves and REACH compliance cost inflation as specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation scale-up would alter the outlook if bioreactor capital costs fail to decline as projected. Deviation in C4 olefin feedstock pricing or EMA impurity profiling standard evolution would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Citrate Market
Functional Chemicals
US Potassium Methylate Market
Functional Chemicals
Citrulline Malate Market
Functional Chemicals
Global Potassium Citrate Market
Functional Chemicals
Adipamide Market
Functional Chemicals
Urea Formaldehyde Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Carbomer Market
Functional Chemicals
Lauric Arginate Market
Functional Chemicals
Global Sodium Lignosulfonate Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Acrylamide Monomer Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
2-Propylheptanol Market
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Europe Fumaric Acid Market