
 Glutaraldehyde Market | 2026-2036
Glutaraldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Glutaraldehyde Market Outlook
ISO 14160 certification for sterilization of single-use medical devices incorporating animal tissues is redrawing competitive boundaries in glutaraldehyde supply. ACURO ORGANICS LIMITED leverages its Indian manufacturing base to serve pharmaceutical sterilization contracts across South Asia. BASF SE anchors European demand through controlled-release sterilant formulations that meet ECHA biocidal product regulation timelines. LANXESS competes on corrosion inhibitor grades for oilfield water treatment, a segment where technical service capabilities differentiate suppliers.
Glutaraldehyde is a dialdehyde with two aldehyde groups separated by a three-carbon chain, typically supplied as acidic aqueous solutions at concentrations from 25% to 50% that require alkaline activation before biocidal use; it functions by crosslinking proteins and nucleic acids, making it effective for cold sterilization of medical instruments and fixation of biological specimens. The sterilant product type dominates value capture due to hospital infection control mandates, while the water treatment application expands fastest as industrial biocide formulations replace legacy chemistries in cooling towers and oilfield injection systems. Distribution through specialized chemical distributors controls the majority of volume, with direct sales capturing premium sterilant contracts that require technical validation support.
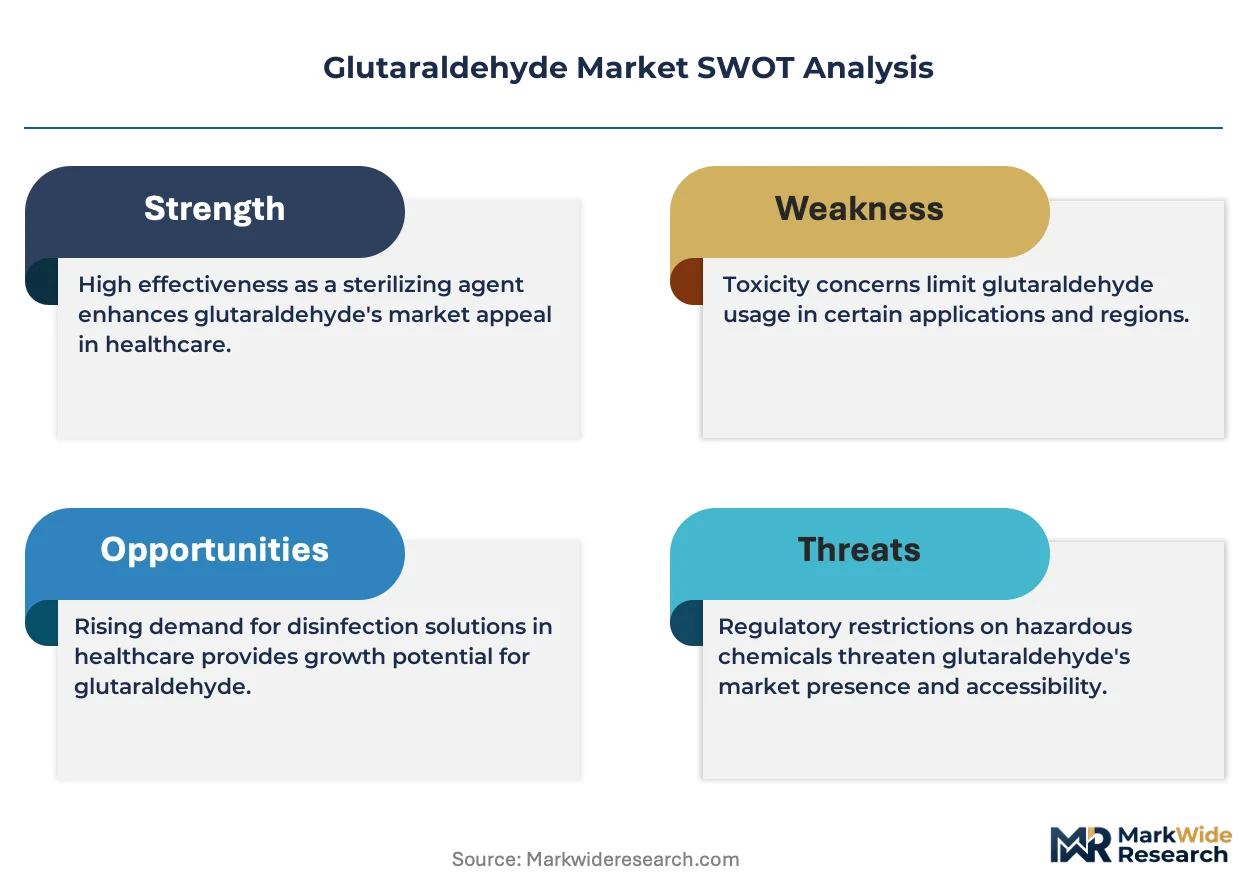
US EPA re-registration review under the Federal Insecticide, Fungicide, and Rodenticide Act shapes product formulation requirements, while ECHA's Biocidal Products Regulation drives active substance approval timelines in Europe. India's Central Insecticides Board registration process for disinfectants creates compliance complexity for imported formulations. Stakeholders must monitor regulatory divergence between jurisdictions where data requirements for biocidal efficacy and environmental fate are tightening without harmonization.
Market Dynamics
Hospital infection control mandates are compressing sterilization cycle times while EPA re-registration review is forcing reformulation investments across biocide portfolios. This dual pressure is restructuring competitive positioning between legacy glutaraldehyde suppliers and alternative chemistry providers.
Growth Catalysts
- Cold sterilization protocols:Healthcare facilities are expanding alkaline-activated glutaraldehyde use for heat-sensitive endoscopes and laparoscopic instruments. This shift protects instrument integrity while meeting Joint Commission sterilization standards.
- India's pharmaceutical manufacturing expansion:Bulk drug production growth is accelerating glutaraldehyde procurement for both equipment sterilization and tissue fixation in vaccine manufacturing facilities.
- ECHA Biocidal Products Regulation timelines:Controlled-release sterilant formulations are gaining preference as manufacturers pre-position for active substance approval deadlines in European healthcare markets.
Market Restraints
- Acrolein contamination risk:Thermal degradation of glutaraldehyde solutions during storage and transport elevates toxic byproduct formation, requiring cold chain logistics that inflate delivered costs.
- Peracetic acid substitution:Sporicidal alternatives with faster contact times are capturing outpatient surgical center contracts where instrument turnover speed dominates purchasing criteria.
- US EPA re-registration data requirements:Efficacy study mandates for antimicrobial pesticides are extending product approval timelines and elevating regulatory compliance expenditures for existing formulations.
Strategic Opportunities
- Oilfield water treatment biocides:Corrosion inhibitor grades are penetrating North American shale formations where produced water recycling mandates are displacing legacy chlorine treatments.
- ISO 14160 certification pathways:Single-use medical devices incorporating animal tissues are creating qualification demand for sterilization validation services that lock in supplier relationships.
- Specialized chemical distributor networks:Technical validation support capabilities are enabling premium pricing capture for direct sterilant contracts outside traditional bulk chemical channels.
Industry Challenges
- Alkaline activation training deficits:Healthcare facility staff require competency certification in pH adjustment protocols to ensure biocidal efficacy without instrument corrosion.
- Cross-jurisdictional registration complexity:India's Central Insecticides Board disinfectant approval process diverges from US EPA and ECHA data requirements, fragmenting formulation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glutaraldehyde Market |
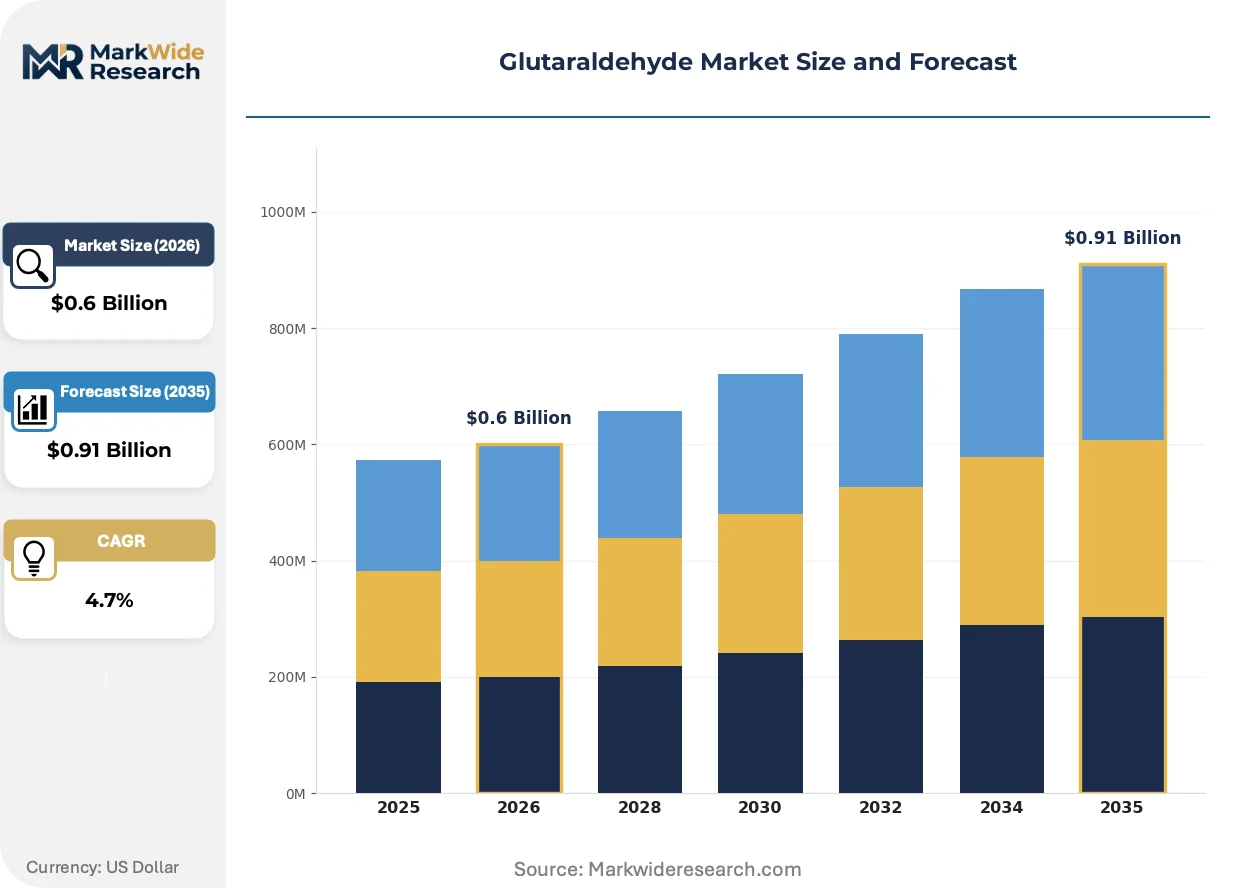
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $0.91 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Disinfectant, Sterilant, Corrosion Inhibitor End User: Healthcare, Pharmaceuticals, Laboratories, Veterinary Application: Medical Equipment, Water Treatment, Biocides, Tissue Preservation Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | ACURO ORGANICS LIMITED, Fengchen Group Co., Ltd, BASF SE, UPICHEM, Neogen Corporation, LANXESS, Becta Laboratories, Hebei Guanlang Biotechnology Co., Ltd., ASP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glutaraldehyde Market Strategic Shifts
Glutaraldehyde chemistry is decomposing into application-specific formulations as end-users demand performance-optimized solutions over commodity biocide supply. This specialization is compressing margins for undifferentiated producers while rewarding technical service capabilities.
Stabilized acidic aqueous solutions with extended shelf life are decomposing traditional supply chain economics for glutaraldehyde distribution. Hospital procurement teams are adopting these formulations to reduce inventory waste and eliminate on-site activation errors. The technology is decomposing price-based competition into total-cost-of-ownership models where technical support and validation documentation determine supplier selection.
REACH authorization procedures for biocidal active substances are forcing reformulation investments across European glutaraldehyde portfolios. Manufacturers are pre-submission testing controlled-release variants to secure Article 95 listing before 2025 renewal deadlines. Healthcare sterilization contracts in Germany and France are increasingly specifying ECHA-compliant formulations, displacing imported products lacking BPR dossier support.
Consolidated purchasing by hospital systems is compressing distributor margins and favoring direct manufacturer relationships for high-volume sterilant contracts. IDN procurement teams are unbundling technical validation services from chemical supply, creating separate RFP streams for biocide and compliance documentation. This bifurcation is most visible in US metropolitan markets where health system mergers have concentrated buying power among three to five regional entities.
Glutaraldehyde Market Segmentation
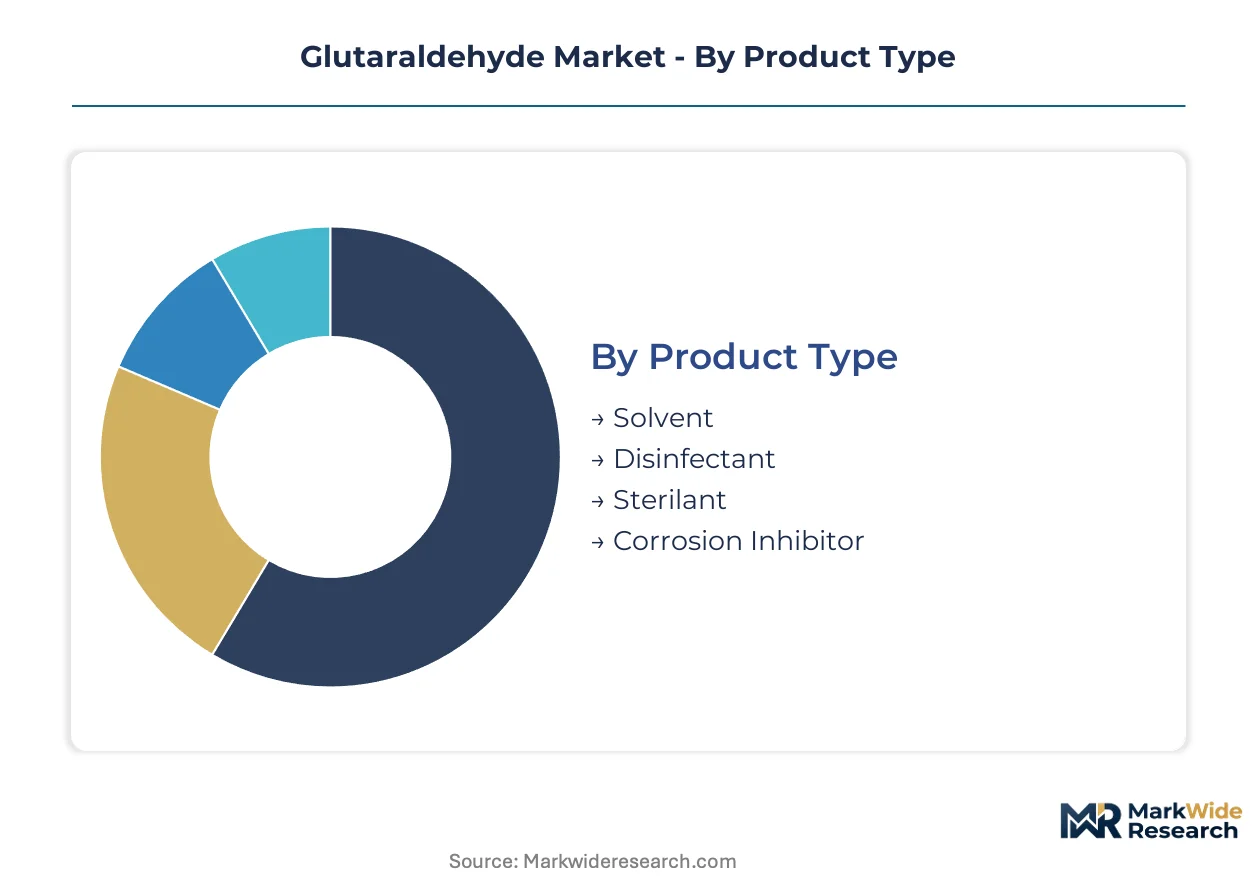
Glutaraldehyde's dual role as biocide and crosslinking agent fragments demand across incompatible performance specifications. Segmentation reveals how formulation chemistry and regulatory jurisdiction determine supplier positioning and margin capture.
Product Type:
Sterilant grades dominate hospital procurement in North America and Western Europe, while disinfectant volumes concentrate in India's expanding healthcare infrastructure.
- Sterilant:Alkaline-activated aqueous solutions at 2.0-3.5% concentration deliver sporicidal efficacy for heat-sensitive endoscopes. Demand clusters in US hospital systems where Joint Commission accreditation mandates documentation of sterilization cycles. EPA re-registration timelines are compressing supplier qualification windows.
- Disinfectant:Lower-concentration acidic formulations target surface decontamination in pharmaceutical cleanrooms. India's bulk drug manufacturing zones in Hyderabad and Ahmedabad are accelerating procurement as CDSCO inspection frequency intensifies.
- Solvent:Industrial-grade solutions serve chemical synthesis and leather tanning applications with reduced purity requirements.
- Corrosion Inhibitor:Oilfield water treatment grades incorporate amine additives for downhole injection systems in North American shale plays.
Sterilant holds the largest share; momentum sits with corrosion inhibitor grades as produced water recycling mandates expand.
End User:
Customer sophistication varies sharply: healthcare facilities demand validation documentation while pharmaceutical manufacturers prioritize batch consistency.
- Healthcare:Hospital infection control departments specify glutaraldehyde for flexible endoscope reprocessing. US metropolitan health systems are consolidating sterilant procurement through IDN-level contracts that unbundle chemical supply from technical support services.
- Pharmaceuticals:Vaccine manufacturers deploy tissue fixation protocols during viral cultivation. India's Bharat Biotech and Serum Institute of India facilities are expanding glutaraldehyde storage capacity as pandemic preparedness funding flows.
- Laboratories:Research institutions require electron microscopy-grade fixation for cellular structure preservation.
- Veterinary:Equine tissue preservation and small animal surgical instrument sterilization drive smaller-volume demand.
Healthcare captures the dominant value pool; pharmaceutical procurement is climbing the fastest as biologics manufacturing scales.
Application:
Performance requirements diverge between human-contact medical applications and industrial biocide deployment.
- Medical Equipment:Cold sterilization of laparoscopic instruments and bronchoscopes demands neutralization verification and rinse-water quality monitoring. German hospital procurement teams increasingly specify ECHA-compliant formulations with Article 95 listing.
- Water Treatment:Cooling tower biocide formulations and oilfield produced water treatment are displacing chlorine-based chemistries. US shale operators in the Permian Basin are adopting glutaraldehyde-amino acid blends for corrosion control.
- Biocides:General industrial disinfection spans food processing equipment and agricultural facility sanitation.
- Tissue Preservation:Histological fixation for pathology diagnostics requires buffered solutions with minimal autofluorescence.
Medical equipment commands premium pricing; water treatment is expanding most quickly as industrial biocide regulations tighten.
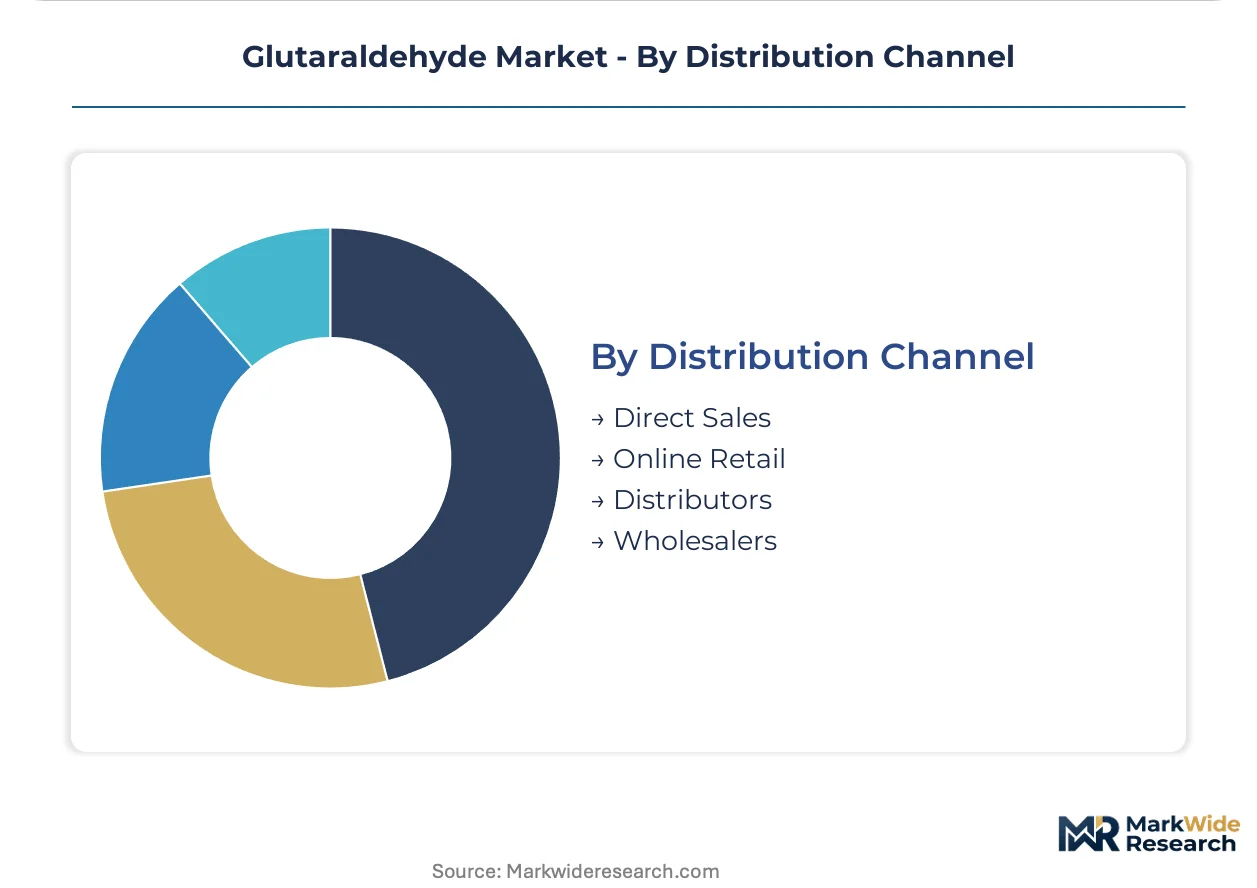
Distribution Channel:
Channel selection reflects purchase scale and technical validation requirements rather than pure cost optimization.
- Direct Sales:High-volume hospital system contracts require manufacturer-provided sterilization validation documentation and staff training certification. US EPA registration data packages travel through this channel exclusively.
- Distributors:Specialized chemical distributors control bulk volumes for mid-tier pharmaceutical manufacturers and regional laboratory networks.
- Wholesalers:Veterinary and agricultural biocide volumes flow through regional chemical wholesalers with limited technical support capability.
- Online Retail:Small-volume laboratory reagent sales and educational institution procurement utilize B2B platforms with standardized SDS documentation.
Direct sales secures the highest margins; distributor networks retain volume leadership across fragmented customer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA re-registration timelines and ECHA Biocidal Products Regulation deadlines are redrawing procurement patterns across healthcare and industrial biocide markets. Hospital infection control mandates in developed economies intersect with pharmaceutical manufacturing expansion in emerging markets to create divergent growth trajectories.
United States
Hospital systems in Texas and Florida are consolidating sterilant procurement through IDN-level contracts that unbundle chemical supply from validation services. EPA re-registration review under FIFRA is compressing supplier qualification windows for antimicrobial pesticide formulations. The Permian Basin shale formation in West Texas is accelerating glutaraldehyde-amino acid blend adoption for produced water recycling mandates.
Germany
Healthcare procurement teams in Bavaria and North Rhine-Westphalia increasingly specify ECHA-compliant formulations with Article 95 listing for flexible endoscope reprocessing. REACH authorization procedures for biocidal active substances are forcing reformulation investments ahead of 2025 renewal deadlines. The Frankfurt-Rhine-Main pharmaceutical cluster is expanding cold sterilization capacity for biologics manufacturing.
India
Bulk drug production growth in Hyderabad and Ahmedabad is accelerating glutaraldehyde procurement for equipment sterilization and tissue fixation in vaccine manufacturing facilities. CDSCO inspection frequency intensification is driving disinfectant registration through the Central Insecticides Board. Serum Institute of India and Bharat Biotech facilities in Pune are expanding storage capacity as pandemic preparedness funding flows.
China
Pharmaceutical manufacturing zones in Jiangsu and Zhejiang provinces are scaling glutaraldehyde consumption for single-use medical device sterilization incorporating animal tissues. NMPA registration requirements for disinfectant formulations are creating compliance complexity for imported biocide products. The Yangtze River Delta chemical industry corridor is integrating domestic glutaraldehyde production with downstream sterilant formulation.
Saudi Arabia
Healthcare infrastructure expansion in Riyadh and Jeddah is driving procurement of alkaline-activated sterilant solutions for heat-sensitive surgical instruments. SFDA medical device registration pathways are mandating ISO 14160 certification for sterilization validation documentation. The King Abdullah Economic City pharmaceutical manufacturing zone is attracting biocide suppliers through localization incentives.
Glutaraldehyde Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with biocide portfolios alongside specialized sterilization service providers. Market structure exhibits moderate consolidation with tiered differentiation between premium formulation suppliers and commodity biocide traders. Two strategic archetypes dominate: integrated chemical manufacturers leveraging regulatory compliance capabilities, and regional distributors capturing technical validation service premiums. Competitive moves center on ECHA dossier pre-positioning for BPR renewal deadlines and direct hospital system contracting to bypass distributor margins.
Within the integrated chemical manufacturer tier, BASF SE and LANXESS exemplify European players anchoring controlled-release formulation development. ACURO ORGANICS LIMITED occupies a position representing Indian manufacturing base advantages for South Asian pharmaceutical sterilization contracts. Among specialty biocide suppliers, Neogen Corporation and ASP sit within the technical service differentiation segment where validation documentation capabilities determine contract capture. Hebei Guanlang Biotechnology Co., Ltd. and Fengchen Group Co., Ltd represent Chinese manufacturing scale positions serving domestic pharmaceutical zone demand.
| Leading Market Players |
|---|
| ACURO ORGANICS LIMITED |
| Fengchen Group Co., Ltd |
| BASF SE |
| UPICHEM |
| Neogen Corporation |
| LANXESS |
| Becta Laboratories |
| Hebei Guanlang Biotechnology Co., Ltd. |
| ASP |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day inventory cycles for alkaline-activated sterilant solutions concentrate pricing power with manufacturers possessing cold chain logistics networks, while acrolein degradation risks during extended storage compress margins for distributors lacking temperature-controlled infrastructure.
Pricing Analysis
Certification level creates the primary spread between ECHA Article 95-listed formulations and unregistered commodity grades. Three-tier pricing structure across premium, standard, and economy levels reflects validation documentation depth, with hospital IDN contracts commanding premium-mid-economy pricing differentiation based on technical service bundling. Cost compression in standard grades intensifies because peracetic acid alternatives capture outpatient surgical center volume. Pharmaceutical manufacturers show least price sensitivity due to batch consistency requirements, while regional laboratories exhibit highest sensitivity to per-liter delivered costs.
Supply Chain Analysis
India and China anchor glutaraldehyde base production, with Germany and the United States specializing in controlled-release formulation finishing. Manufacturing draws from acrolein-free feedstock specifications, amine additive packages for corrosion inhibitor grades, and pharmaceutical-grade purity certifications. Single-source vulnerability concentrates in acrolein-contaminated batch recalls requiring cold chain replacement shipments. Distribution runs through specialized chemical distributors for mid-tier pharmaceutical accounts, while direct manufacturer relationships capture hospital system sterilant contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peracetic acid substitution in outpatient surgical centers forces incumbents into defensive positioning around validation documentation and technical service capabilities that commodity biocide suppliers cannot replicate.
For Market Incumbents: Compound regulatory compliance capabilities through ECHA dossier pre-positioning and EPA re-registration data package investments. Deepen backward integration into acrolein-free feedstock supply to neutralize contamination risk exposure. Anchor hospital IDN contracts with unbundled technical validation services that peracetic acid alternatives cannot match. For New Entrants and Emerging Players: Differentiate on ISO 14160 certification pathways for single-use medical devices incorporating animal tissues, where sterilization validation services lock in supplier relationships. Target India's Central Insecticides Board registration complexity as a white-space opportunity where foreign competitors lack local compliance infrastructure. Pursue direct sales to vaccine manufacturers in Pune and Hyderabad with tissue fixation application expertise. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory moat play because ECHA Biocidal Products Regulation deadlines and EPA re-registration timelines continuously filter out undercapitalized competitors. Acquisition candidates include regional distributors with hospital system validation service contracts and Indian manufacturers with CDSCO registration track records. Monitor peracetic acid contact-time improvements as the signal to watch for substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ECHA Dossier Pre-Positioning | Article 95 listing secures European healthcare procurement specifications before BPR renewal deadlines. |
| Backward Integration into Feedstock | Acrolein-free raw material control neutralizes thermal degradation risks during storage and transport. |
| Hospital IDN Direct Contracting | Unbundled technical validation services capture premium pricing outside traditional distributor channels. |
| ISO 14160 Certification Investment | Single-use medical device sterilization validation locks in supplier relationships with tissue-incorporating manufacturers. |
| India CDSCO Registration Expansion | Central Insecticides Board disinfectant approvals create compliance barriers for imported formulations. |
Study Parameters
Cross-validation between primary interviews with hospital infection control officers, pharmaceutical manufacturing quality directors, and oilfield water treatment procurement leads anchors the qualitative findings against secondary validation from EPA re-registration filings, ECHA biocidal product dossiers, and CDSCO disinfectant registration databases. Technical R&D directors at sterilant formulation companies and specialized chemical distributor account managers provided downstream channel perspective. Bottom-up demand modeling across healthcare, pharmaceutical, and industrial end-uses triangulates with top-down chemical industry production capacity assessments.
Sensitivity analysis around EPA re-registration timeline scenarios and ECHA Article 95 renewal outcomes tests forecast robustness across the projection horizon. Segmentation dimensions include product grade tier, end-use industry application, distribution channel structure, and regional regulatory cluster. CAGRs derive from installed base expansion in hospital cold sterilization protocols, pharmaceutical manufacturing capacity additions, and produced water recycling mandate adoption. Industry-specific inputs incorporate Joint Commission accreditation frequency, CDSCO inspection intensity, and shale formation water treatment regulation evolution.
The analysis sits within stated boundaries; outcomes outside continued EPA antimicrobial pesticide re-registration activity or sustained ECHA biocidal product enforcement would require recalibration. Forecasts reflect assumptions regarding peracetic acid substitution velocity, acrolein contamination incident frequency, and hospital system consolidation trajectories. Recalibration cycles align with material shifts in EPA re-registration timelines, ECHA renewal deadlines, and Indian pharmaceutical manufacturing investment flows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Soy-Based Chemical Market
Functional Chemicals
Potassium Methylate Market
Functional Chemicals
Ortho Phthalic Aldehyde Market
Functional Chemicals
2-Propylheptanol Market
Functional Chemicals
Asparagine Market
Functional Chemicals
Serine Market
Functional Chemicals
Europe Fumaric Acid Market
Functional Chemicals
Functional Polymer Market
Functional Chemicals
Para-Aminophenol Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
Isophthaloyl Chloride Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Tartrazine Market
Functional Chemicals
Sodium Methylate Market