
 Chlorobutanol Market | 2026-2036
Chlorobutanol Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorobutanol Market Analysis
Maintenance contracts for excipient qualification and stability testing are expanding what suppliers actually sell beyond bulk material. Toronto Research Chemicals leverages its analytical services to anchor long-term relationships with formulation labs. Spectrum Chemical Mfg. Corp. sustains geographic dominance through North American distribution infrastructure. JSN Chemicals competes on cost-advantaged hemihydrate production serving Asian generic injectable manufacturers.
Chlorobutanol is a chlorinated organic compound with the formula C4H7Cl3O, typically supplied as hemihydrate or anhydrate crystal forms with melting points near 78-80°C, functioning primarily as an antimicrobial preservative and mild sedative in parenteral and ophthalmic preparations. The compound inhibits microbial growth through membrane disruption, making it indispensable for multi-dose vial stability in sterile pharmaceutical applications. Pharmaceutical-grade hemihydrate commands the deepest margin pools due to compendial compliance burdens, while chlorobutanol powder is gaining traction in cosmetic preservative blends as formulators seek alternatives to paraben systems. Laboratory reagent demand remains structurally smaller but sticky, anchored by chromatography and synthesis protocols that resist substitution.
FDA excipient guidance and USP monograph revisions govern chlorobutanol purity specifications for drug applications, while REACH registration in Europe imposes toxicological data obligations that filter out non-compliant suppliers. India's CDSCO aligns with ICH Q3C residual solvent guidelines, creating a three-jurisdiction compliance threshold that shapes supplier viability. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP standards, as divergence in chlorobutanol impurity limits could fragment procurement strategies across manufacturing regions.
Market Dynamics
Pharmaceutical preservative procurement is consolidating around certified hemihydrate grades as FDA and REACH antimicrobial excipient guidelines tighten purity thresholds, redirecting volume toward qualified suppliers capable of supporting stability protocol reformulation.
Growth Catalysts
- REACH compliance mandates:ECHA antimicrobial excipient guidelines are filtering out non-certified suppliers, concentrating procurement among registrants with complete toxicological dossiers.
- India's API manufacturing expansion:Domestic sterile injectable production and CDMO buildout are accelerating chlorobutanol consumption across parenteral formulation lines.
- Paraben substitution:Cosmetic formulators are reformulating preservative systems, creating incremental demand for chlorobutanol powder in personal care applications.
Market Restraints
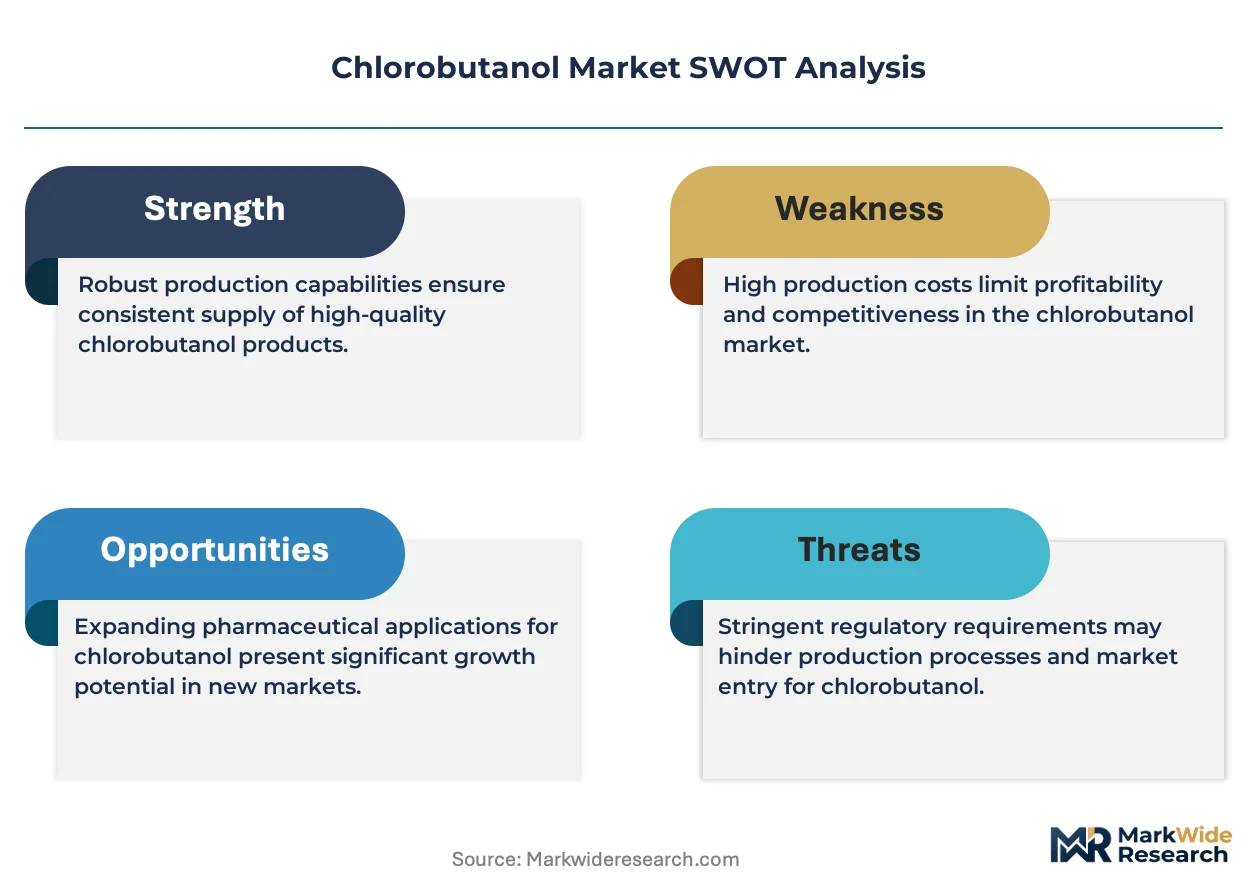
- Acetone feedstock volatility:Chlorobutanol synthesis depends on acetone chlorination, exposing margins to petrochemical input cost swings.
- Chinese supply concentration:Bulk hemihydrate production clusters in Shandong and Jiangsu provinces, creating geographic risk for Western pharmaceutical buyers.
- Phenoxyethanol substitution:Alternative preservatives are capturing share in ophthalmic applications where lower irritation profiles are prioritized.
Strategic Opportunities
- Brazilian generic injectable growth:ANVISA-aligned manufacturers are localizing parenteral production, opening demand for import-qualified chlorobutanol grades.
- Maintenance contract bundling:Suppliers can anchor relationships by packaging excipient qualification and stability testing services with material supply.
- PLI scheme alignment:India's production-linked incentive framework for pharmaceuticals rewards backward integration into critical excipient manufacturing.
Industry Challenges
- Pharmacopeial harmonization gaps:Diverging USP, EP, and IP impurity limits are fragmenting procurement strategies across multi-jurisdictional manufacturing networks.
- Analytical method transfer:Chromatography protocol validation for chlorobutanol assay and related substances consumes 12-18 months in regulatory filing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorobutanol Market |
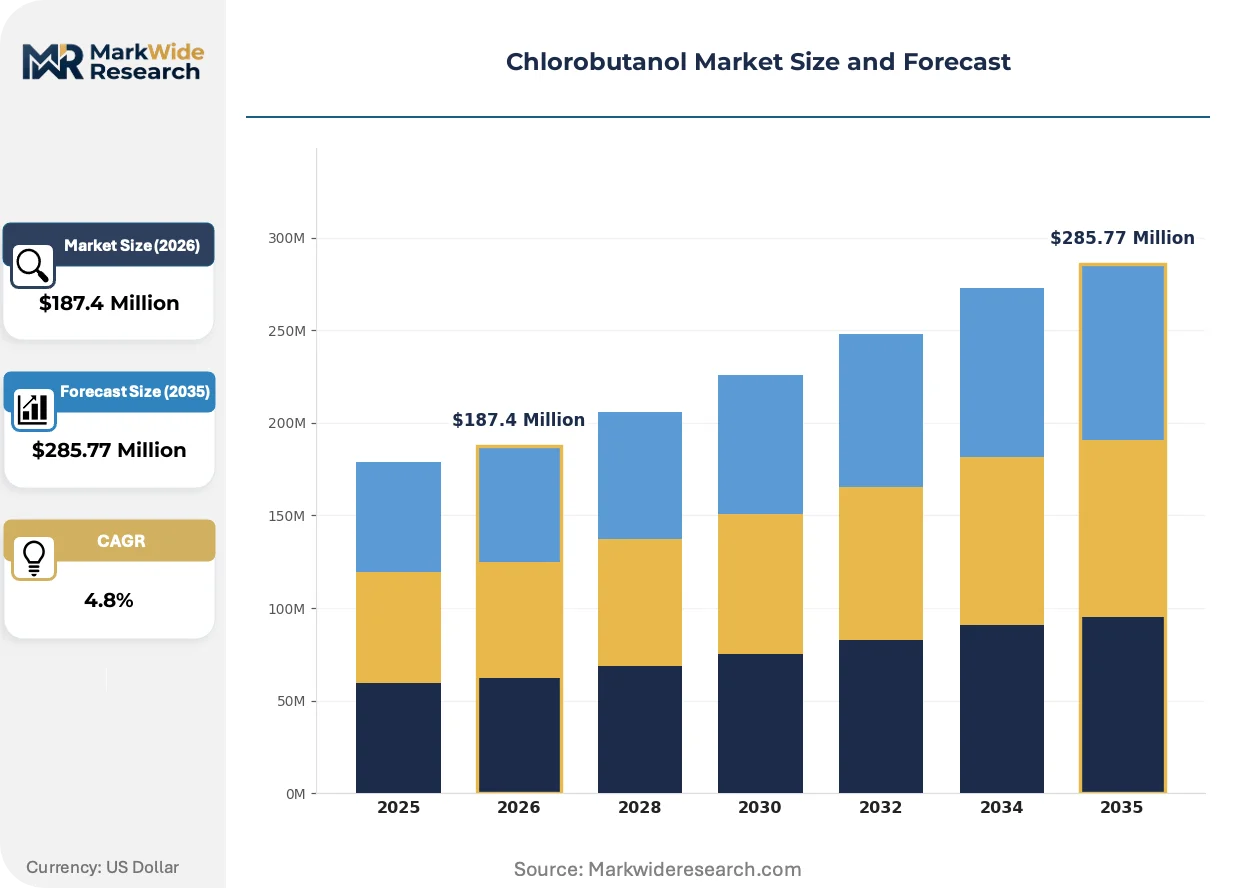
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorobutanol Hemihydrate, Chlorobutanol Anhydrate, Chlorobutanol Solution, Chlorobutanol Powder Application: Pharmaceuticals, Cosmetics, Food Preservation, Laboratory Reagent End User: Pharmaceutical Companies, Cosmetic Manufacturers, Research Institutions, Food Processing Form: Liquid, Solid, Gel, Powder |
| Companies Covered | Toronto Research Chemicals, Bruchem, Inc., Spectrum Chemical Mfg. Corp., JSN Chemicals, Capot Chemical Co. Ltd., Athenstaedt, Penta Manufacturing Company, Otto Chemie Pvt. Ltd., Laxachem Organics Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorobutanol Market Emerging Trajectories
Continuous manufacturing adoption in sterile injectable production is reshaping how preservative excipients are specified, dosed, and validated, with implications for supplier technical service capabilities and quality agreement structures.
Process analytical technology (PAT) implementation in chlorobutanol crystallization is consolidating quality control into real-time release testing protocols. Pharmaceutical manufacturers adopting continuous direct compression for parenteral powders are demanding excipients with tighter particle size distributions and validated PAT-compatible specifications. This consolidation is compressing the traditional batch-release testing cycle and favoring suppliers with embedded analytical development teams.
REACH registration deadlines for existing antimicrobial substances are forcing toxicological data generation that smaller chlorobutanol manufacturers cannot fund. ECHA's 2024 substance evaluation work program prioritizes chlorinated organics, accelerating dossier submission requirements. European generic injectable formulators are responding by dual-sourcing from REACH-registered suppliers and auditing Indian manufacturers for Article 95 compliance.
Multi-year excipient supply agreements with embedded price collars are displacing spot procurement in North American parenteral manufacturing. Large pharmaceutical buyers are consolidating vendor bases to three qualified suppliers per excipient category, with technical service integration as the selection criterion. This pattern is most visible in New Jersey and Massachusetts formulation clusters, where stability protocol reformulation costs dominate total cost of ownership calculations.
Chlorobutanol Market Segmentation
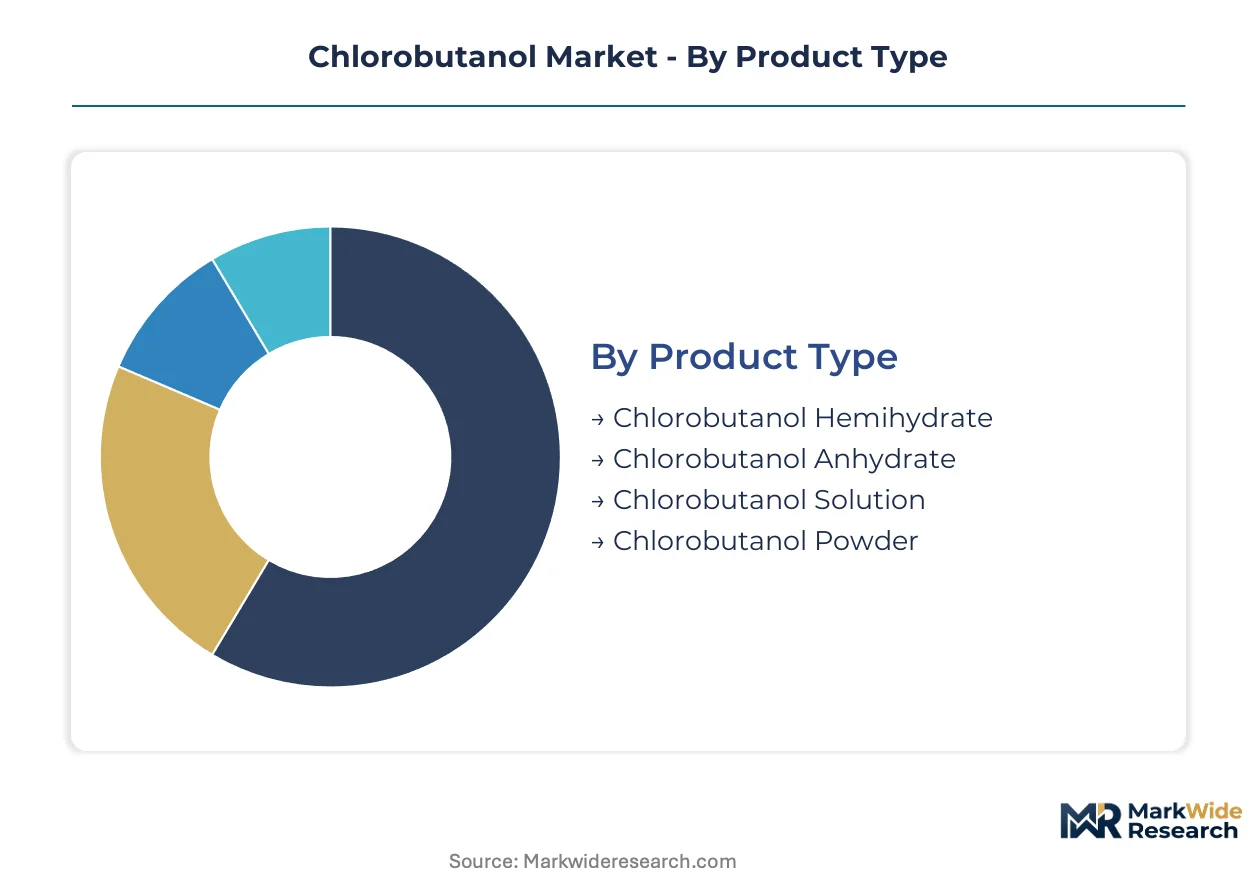
Chlorobutanol procurement splits across purity grades, physical forms, and regulatory compliance tiers that determine supplier qualification requirements. Pharmaceutical formulators prioritize hemihydrate certification while cosmetic buyers trade purity for cost, creating parallel demand tracks with diverging margin structures.
Product Type:
Certification burden and stability protocol requirements drive buyer selection across crystal forms and solution concentrations.
- Chlorobutanol Hemihydrate:The hemihydrate crystal form carries USP and EP monograph compliance, commanding premium positioning for parenteral and ophthalmic applications where microbial preservation must meet stability protocol validation. Demand concentrates among sterile injectable manufacturers in India and the United States as FDA and CDSCO tighten antimicrobial excipient purity thresholds.
- Chlorobutanol Anhydrate:Water-free anhydrate offers extended shelf stability for hygroscopic formulation environments, finding preference in continuous manufacturing lines where moisture control affects process analytical technology calibration. European generic injectable producers favor anhydrate for multi-year supply agreements with embedded technical service requirements.
- Chlorobutanol Solution:Pre-dissolved aqueous formulations reduce handling complexity for smaller cosmetic and laboratory buyers lacking crystallization expertise.
- Chlorobutanol Powder:Bulk powder serves cost-sensitive cosmetic preservative blending where compendial compliance is not mandated.
Volume sits with hemihydrate grades; growth tilts toward anhydrate as continuous manufacturing adoption accelerates.
Application:
End-use specifications fragment procurement around microbial challenge testing requirements and regulatory filing burdens.
- Pharmaceuticals:Parenteral and ophthalmic preservation demands compendial-grade hemihydrate with validated assay methods and related substances documentation. FDA excipient guidance and REACH registration requirements filter supplier pools to qualified registrants with complete toxicological dossiers, concentrating procurement among certified manufacturers.
- Cosmetics:Personal care formulators seek chlorobutanol powder as a paraben alternative in preservative systems, with lower purity thresholds and reduced documentation requirements enabling cost-advantaged sourcing from non-pharmaceutical grade suppliers.
- Food Preservation:Regulatory restrictions limit food-grade applications to specific jurisdictions with approved additive status.
- Laboratory Reagent:Chromatography and synthesis protocols sustain steady demand for analytical-grade material with batch-specific certificates of analysis.
Pharmaceuticals anchor revenue concentration; cosmetics expand most quickly amid paraben substitution trends.
End User:
Scale and technical capability determine whether buyers qualify for direct supply relationships or distributor intermediation.
- Pharmaceutical Companies:Large sterile injectable manufacturers consolidate vendor bases to three qualified suppliers per excipient category, embedding multi-year agreements with stability testing and analytical method transfer services. New Jersey and Massachusetts formulation clusters drive North American demand concentration.
- Cosmetic Manufacturers:Mid-sized personal care formulators prioritize spot procurement flexibility and lower minimum order quantities, accessing chlorobutanol powder through regional chemical distributors rather than direct manufacturer relationships.
- Research Institutions:Academic and contract research organizations sustain fragmented, small-volume demand with stringent documentation requirements for grant-funded synthesis projects.
- Food Processing:Limited approved applications constrain this segment to specialized preservative niches in select regulatory jurisdictions.
Procurement scale peaks with pharmaceutical companies; research institutions gain share fastest through expanding contract research activity.
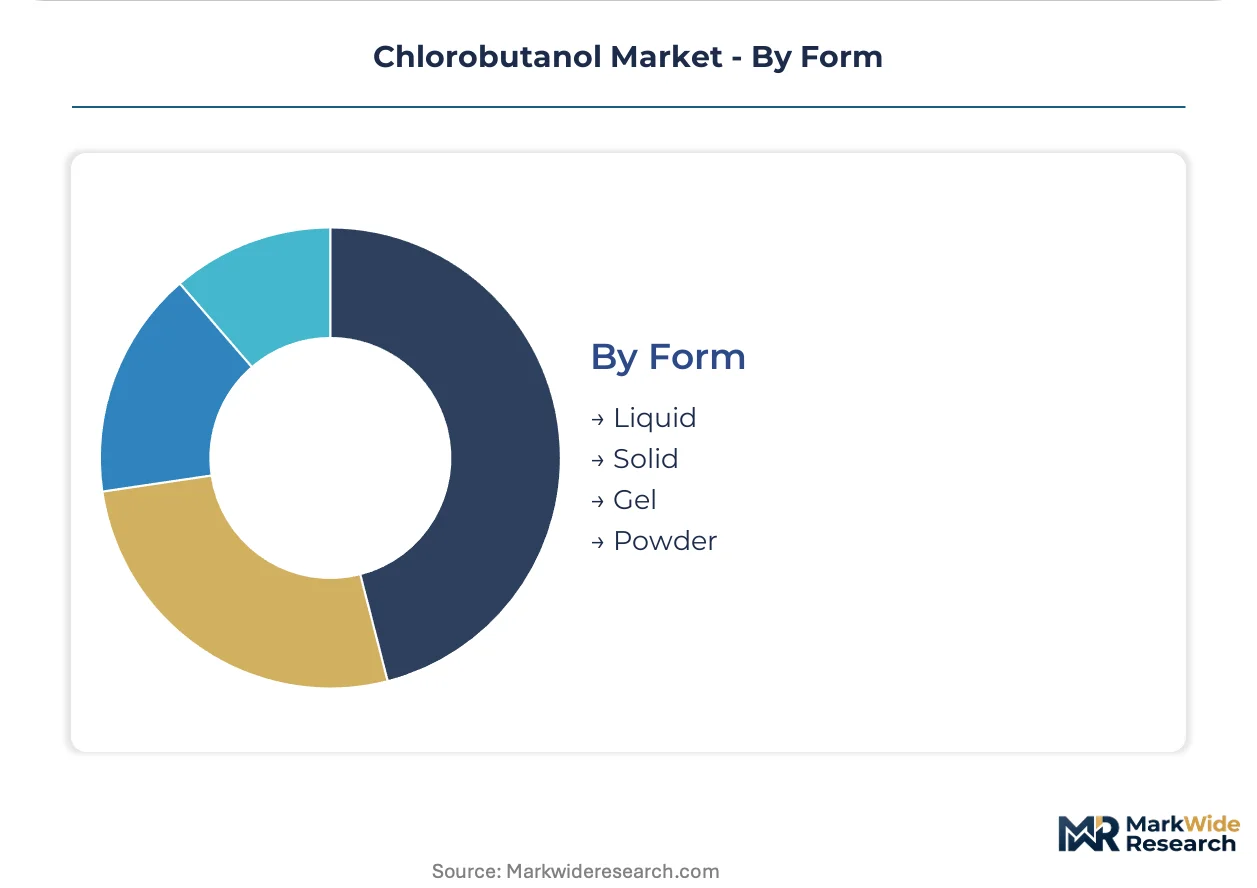
Form:
Physical state selection hinges on formulation process integration and handling infrastructure investment.
- Liquid:Aqueous solutions enable direct incorporation into ophthalmic and parenteral formulations without dissolution steps, preferred by continuous manufacturing adopters seeking reduced processing variability.
- Solid:Crystalline hemihydrate and anhydrate offer extended stability and flexible reconstitution, dominating bulk pharmaceutical procurement.
- Gel:Semi-solid preparations serve topical and mucosal delivery systems with sustained-release preservation requirements.
- Powder:Fine particle grades facilitate uniform dispersion in cosmetic emulsions and dry blend applications.
Solid forms capture the largest volume position; liquid preparations climb fastest as direct compression manufacturing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chlorobutanol production concentrates in Chinese chemical manufacturing zones while consumption tilts toward pharmaceutical formulation centers in India and the United States. This geographic mismatch shapes procurement strategies, freight costs, and regulatory compliance investments across supplier networks.
United States
Sterile injectable manufacturers in New Jersey and Massachusetts drive hemihydrate demand as FDA antimicrobial excipient guidance tightens purity thresholds. The FDA's 2023 excipient quality initiative pressures formulators to validate stability protocols with certified suppliers. Boston-area biotech clusters anchor technical service-intensive procurement relationships.
India
Domestic API production and CDMO expansion accelerate chlorobutanol consumption across parenteral lines in Maharashtra and Gujarat. CDSCO alignment with ICH Q3C residual solvent guidelines creates compliance thresholds that filter supplier pools. Hyderabad's formulation corridor attracts multi-year excipient supply agreements with embedded analytical services.
China
Bulk hemihydrate manufacturing clusters in Shandong and Jiangsu provinces supply global pharmaceutical buyers despite geographic concentration risks. NMPA oversight of chemical excipient exports intensifies documentation requirements for international shipments. Qingdao's chemical processing zone hosts acetone chlorination capacity that feeds downstream preservative synthesis.
Germany
REACH-registered suppliers serve European generic injectable producers from industrial chemical hubs in North Rhine-Westphalia. ECHA's 2024 substance evaluation work program prioritizes chlorinated organics, accelerating toxicological dossier submissions. Leverkusen's pharmaceutical manufacturing corridor demands compendial-grade material with validated assay methods.
Brazil
ANVISA-aligned manufacturers localize parenteral production in São Paulo state, opening demand for import-qualified chlorobutanol grades. Brazil's pharmaceutical production-linked incentive framework rewards backward integration into critical excipient supply chains. Campinas' emerging sterile injectable cluster sources hemihydrate through audited Indian and European suppliers.
Chlorobutanol Market Vendor Landscape
Capital-heavy producers compete with asset-light distributors for relationship control in chlorobutanol procurement. The supplier base stratifies across three tiers: integrated chemical manufacturers with acetone chlorination assets, specialized excipient distributors with analytical service capabilities, and regional traders serving cost-sensitive cosmetic buyers. Consolidation pressures favor multi-product chemical houses that can amortize regulatory compliance costs across excipient portfolios. Dominant competitive moves include bundling stability testing services with material supply and securing REACH registration ahead of evaluation deadlines.
Among North American distributors, Toronto Research Chemicals and Spectrum Chemical Mfg. Corp. exemplify the service-anchored archetype that dominates qualified pharmaceutical procurement. JSN Chemicals represents cost-advantaged hemihydrate production serving Asian generic injectable manufacturers. These three entities illustrate the geographic and capability segmentation that structures competitive positioning across certification tiers.
| Leading Market Players |
|---|
| Toronto Research Chemicals |
| Bruchem, Inc. |
| Spectrum Chemical Mfg. Corp. |
| JSN Chemicals |
| Capot Chemical Co. Ltd. |
| Athenstaedt |
| Penta Manufacturing Company |
| Otto Chemie Pvt. Ltd. |
| Laxachem Organics Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Acetone price indices cascade through chlorobutanol manufacturing cost structures, compressing margins at the commodity hemihydrate tier while compendial-grade suppliers defend premiums through REACH registration and stability testing bundling. Chinese acetone chlorination capacity anchors base-material economics, yet FDA and ECHA purity mandates fragment procurement into certification-driven pricing tiers that reward qualified registrants with multi-year contract pricing power.
Pricing Analysis
Margin tightening in pharmaceutical-grade hemihydrate reflects REACH dossier completion costs and embedded analytical service requirements that smaller manufacturers cannot absorb. Three-tier pricing structure across compendial-certified, technical-grade, and cosmetic powder levels separates buyers by validation burden and volume scale. Cost-down pressure on technical-grade material accelerates because Indian generic injectable manufacturers consolidate vendor bases to three qualified suppliers per excipient category. Cosmetic formulators exhibit highest price sensitivity, sourcing powder through spot procurement and regional distributors, while sterile injectable manufacturers prioritize total cost of ownership over unit price.
Supply Chain Analysis
Dual-sourcing mandates from European and North American pharmaceutical buyers are fragmenting procurement across REACH-registered European suppliers, CDSCO-aligned Indian manufacturers, and NMPA-certified Chinese producers. Bulk hemihydrate synthesis draws from acetone feedstocks concentrated in Shandong and Jiangsu provinces, with chlorination capacity tethered to Qingdao's chemical processing zone. Single-source vulnerability persists at the acetone chlorination stage, where geographic concentration in eastern China exposes Western buyers to freight cost volatility and documentation delays. Distribution runs through specialized excipient distributors with analytical capabilities in North America and direct manufacturer relationships in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chlorobutanol supplier consolidation is accelerating as REACH registration deadlines and FDA excipient quality initiatives force non-compliant manufacturers from the market, concentrating viable supply among registrants with complete toxicological dossiers.
For Market Incumbents: Anchor market position by securing Article 95 REACH compliance ahead of ECHA substance evaluation deadlines and embedding stability protocol reformulation services within multi-year supply agreements. Phenoxyethanol substitution in ophthalmic applications threatens volume retention; defend against erosion by certifying anhydrate grades for continuous manufacturing lines with PAT-compatible specifications. Backward integration into acetone chlorination assets in India aligns with PLI scheme incentives and insulates margin from petrochemical input volatility. For New Entrants and Emerging Players: Enter via cosmetic preservative blending as paraben substitution creates white-space demand for technical-grade chlorobutanol powder with lower certification barriers. Brazil's ANVISA-aligned generic injectable localization offers the most penetrable geographic entry point, with Campinas sterile injectable clusters sourcing through audited Indian suppliers. Pursue distributor partnerships rather than direct manufacturer qualification to bypass 12-18 month analytical method transfer timelines. For Investors and Strategic Acquirers: The window for entry favors REACH-registered mid-cap specialists with embedded analytical development teams and existing relationships with New Jersey or Massachusetts formulation clusters. Long-term viability hinges on excipient qualification service revenue streams displacing commoditized material margins. Monitor ECHA substance evaluation progress as the inflection signal; accelerated chlorinated organics prioritization would trigger distressed acquisition opportunities among non-compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Completion | ECHA Article 95 compliance filters supplier pools to viable registrants with complete toxicological dossiers. |
| Stability Testing Service Bundling | Toronto Research Chemicals anchors relationships by embedding analytical method transfer within material supply agreements. |
| Backward Integration into Acetone Chlorination | Indian PLI scheme rewards captive feedstock production for critical excipient manufacturing. |
| Continuous Manufacturing Grade Certification | Anhydrate specifications with validated PAT-compatible particle size distributions capture formulation line conversions. |
| Brazilian Import Qualification | ANVISA-aligned parenteral localization in São Paulo state opens demand for audited hemihydrate supply. |
Methodological Framework
Multi-period observation of FDA excipient guidance revisions, REACH registration progress, and CDSCO alignment with ICH Q3C standards anchored the trend analysis, supplemented by interviews with sterile injectable formulators, excipient procurement leads at CDMOs, regulatory affairs directors, and analytical development managers. Secondary validation drew from ECHA substance evaluation work programs, USP monograph revision notices, Indian PLI scheme filings, and customs trade data tracking acetone derivative flows. Bottom-up volume estimates across hemihydrate, anhydrate, and powder grades triangulated against top-down pharmaceutical preservative market sizing.
Segment-weighting approaches modeled grade tier, end-use application, and regional regulatory cluster as primary dimensions, with CAGRs derived from elasticity-adjusted demand projections across the projection horizon. Forecast inputs incorporated continuous manufacturing adoption curves in sterile injectable production and paraben substitution rates in cosmetic preservative systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pharmacopeial harmonization failures or acetone supply disruptions. Deviation in ECHA substance evaluation timelines or FDA excipient quality initiative enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
US Potassium Methylate Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Urea Formaldehyde Market
Functional Chemicals
Lauric Arginate Market
Functional Chemicals
Citrulline Malate Market
Functional Chemicals
Imidazole Market
Functional Chemicals
Adipamide Market
Functional Chemicals
Trimer Acid Market
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
Acrylamide Monomer Market
Functional Chemicals
Lauric Acid Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Europe Fumaric Acid Market
Functional Chemicals
Calcium Citrate Malate Market
Functional Chemicals
Carbomer Market