
 Citrulline Malate Market | 2026-2036
Citrulline Malate Market Size, Share, and Industry Trends Forecast 2026-2036
Citrulline Malate Market Outlook
Pharmaceutical-grade citrulline malate is rotating toward the center of premium sports nutrition procurement. Kyowa Hakko Bio Co., Ltd. leverages its fermentation-derived amino acid platform to supply ingredient-grade material to branded finished-product manufacturers. NOW Foods sustains broad retail distribution across mass-market and natural channels in North America. NutraBio Labs Inc. differentiates through transparent labeling and in-house testing protocols that appeal to performance-oriented consumers.
Citrulline malate is a compound formed from the amino acid L-citrulline and malic acid, typically standardized at ratios of 2:1, and manufactured through enzymatic synthesis or fermentation processes to achieve purity levels exceeding 98% for supplement applications. It functions primarily as a nitric oxide precursor and Krebs cycle intermediate, supporting vasodilation and ATP regeneration during high-intensity exercise. Powder formulations dominate bulk manufacturing and private-label supply due to lower unit costs and flexible dosing, while capsule and tablet formats capture convenience-driven segments among traveling athletes and regimented supplement users. Online retail channels are expanding fastest as direct-to-consumer brands bypass traditional wholesale markups, though specialty stores retain margin pools through personalized consultation and immediate fulfillment.
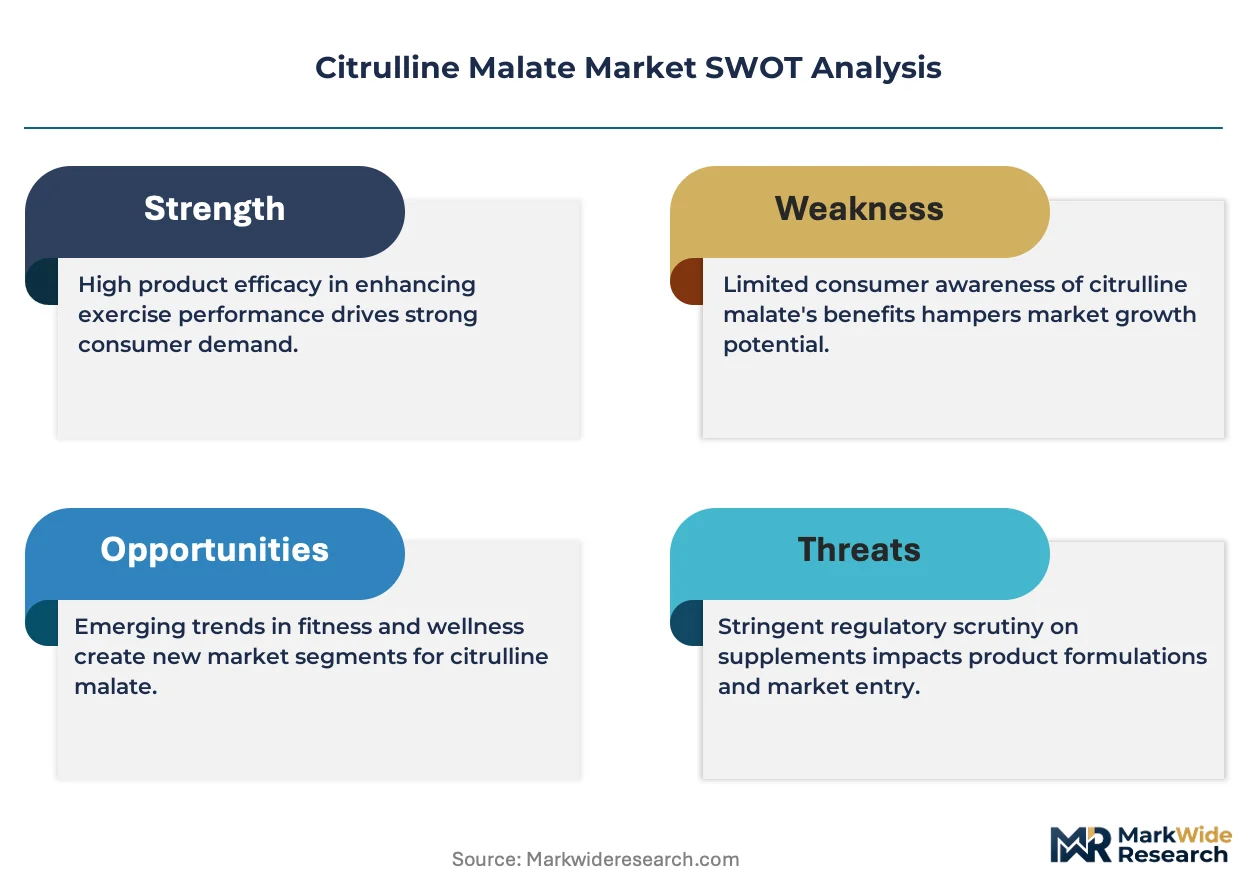
FDA cGMP enforcement and NSF International certification requirements shape product liability exposure and retail access for citrulline malate suppliers. The Dietary Supplement Health and Education Act framework, combined with FTC substantiation standards for performance claims, constrains marketing language and demands clinical evidence for endurance and recovery positioning. Stakeholders must monitor evolving FDA enforcement priorities around New Dietary Ingredient notifications and state-level pre-workout ingredient restrictions that could alter formulation strategies.
Market Dynamics
FDA cGMP enforcement and third-party certification mandates are compressing supplier margins while elevating pharmaceutical-grade material premiums, forcing procurement teams to requalify ingredient sources against evolving purity benchmarks.
Growth Catalysts
- NSF Certified for Sport penetration:Athletic programs and collegiate sports departments now require third-party-tested citrulline malate, expanding addressable demand beyond recreational fitness into institutional procurement channels.
- CrossFit-affiliated retail density:The functional fitness ecosystem drives pre-workout supplement turnover through coach-recommended protocols and box-specific retail partnerships.
- Fermentation platform maturation:Biocatalytic production methods achieve pharmaceutical-grade purity thresholds at scale, reducing reliance on chemical synthesis and opening pharmaceutical contract manufacturing opportunities.
Market Restraints
- Arginine and beetroot nitrate substitution:Competing nitric oxide precursors capture price-sensitive segments through lower per-serving costs and established clinical marketing.
- Japanese and Korean supply concentration:Fermentation-derived L-citrulline feedstock depends on concentrated East Asian amino acid manufacturing clusters, exposing buyers to logistics disruption and currency fluctuation.
- FTC substantiation enforcement:Performance claims for endurance and recovery require clinical trial investment that mid-tier brands cannot fund, constraining marketing differentiation.
Strategic Opportunities
- Clinical nutrition expansion:Hospital formulary adoption for sarcopenia and cardiovascular support creates institutional volume beyond sports nutrition, with reimbursement pathways under exploration in Germany and Japan.
- Direct-to-consumer subscription models:Personalized dosing protocols and auto-replenishment platforms capture lifetime value while bypassing retail margin extraction.
- EU Novel Food authorization pathway:Successful regulatory navigation would unlock fortified food and beverage applications across the European single market, displacing powder-only positioning.
Industry Challenges
- Analytical chemistry talent scarcity:In-house HPLC and mass spectrometry validation requires specialized personnel that contract manufacturers struggle to recruit and retain at competitive compensation.
- Dual certification timeline compression:Simultaneous pursuit of NSF Certified for Sport and Informed Sport accreditation extends product launch windows by 8-14 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrulline Malate Market |
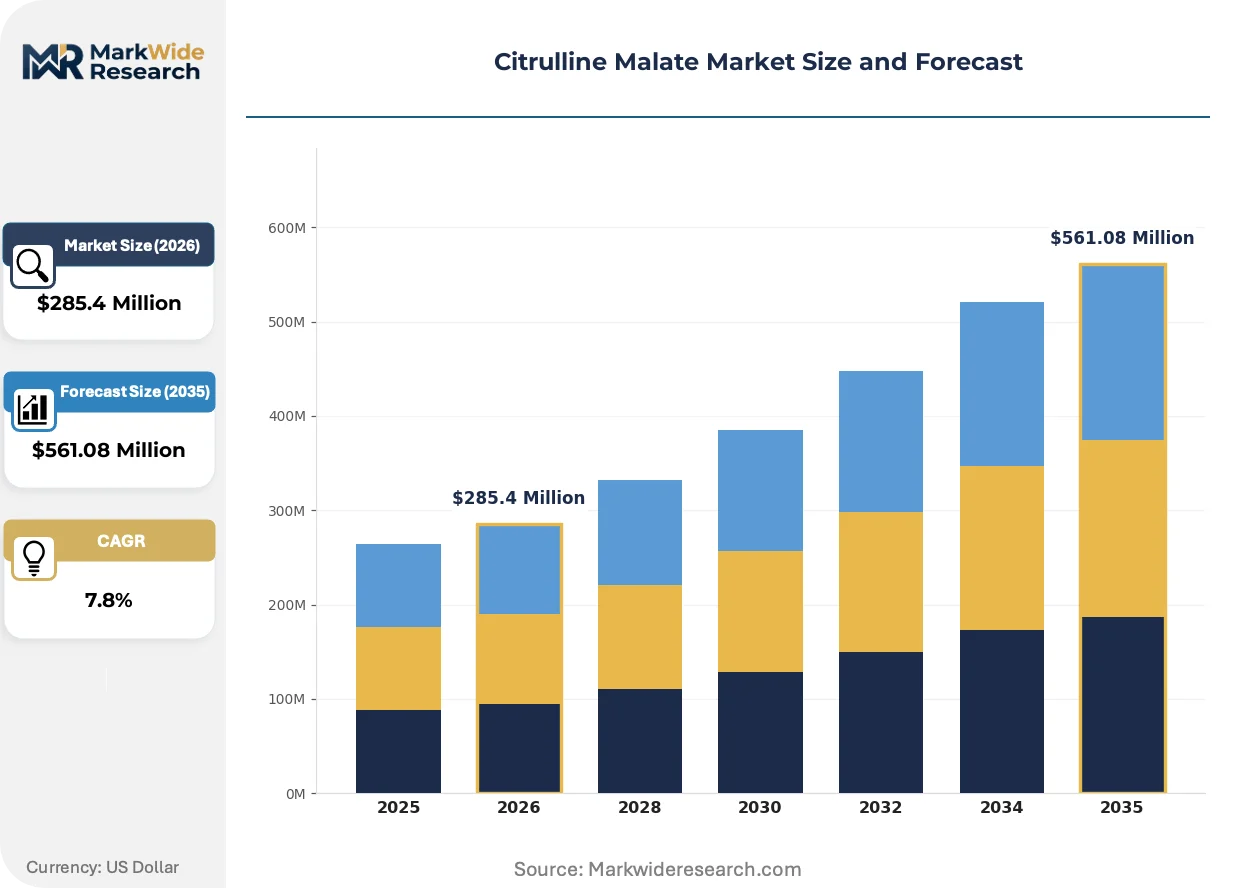
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $561.08 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Tablet, Liquid End User: Athletes, Bodybuilders, Fitness Enthusiasts, Health Supplements Distribution Channel: Online Retail, Specialty Stores, Health Food Stores, Wholesale Application: Energy Boosting, Muscle Recovery, Performance Enhancement, Endurance |
| Companies Covered | Kyowa Hakko Bio Co., Ltd., NutraBio Labs Inc., NOW Foods, Prinova Group LLC, Swanson Health Products, BulkSupplements.com, PureBulk, Inc., AIDP, Inc., Shanghai Freemen LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrulline Malate Market Strategic Shifts
Ingredient-grade sourcing standards are splitting the supplier base into pharmaceutical-compliant and commodity-grade tiers, with testing transparency becoming the primary competitive signal rather than formulation complexity.
Microencapsulation technology is bifurcating the powder segment into standard bulk material and taste-masked, cold-water-dispersible formats. Premium pre-workout brands adopt the latter to eliminate bitterness complaints and enable ready-to-drink co-development. This technology is compressing flavor system R&D cycles while raising minimum viable batch sizes for contract manufacturers.
FTC substantiation standards are tightening claim language around nitric oxide production and muscular endurance. Marketing teams must now reference peer-reviewed trials rather than mechanistic hypotheses, elevating brands with clinical research budgets and exposing those dependent on borrowed science. The United States bears the strictest enforcement, with warning letters targeting social media influencer partnerships.
Subscription-based replenishment is displacing retail repurchase cycles among regimented supplement users. Direct-to-consumer brands capture purchase data to optimize dosing reminders and cross-sell complementary amino acids, while specialty retailers respond with personalized consultation services that justify immediate fulfillment premiums. This channel tension is most visible in metropolitan United States markets with dense CrossFit and functional fitness participation.
Citrulline Malate Market Segmentation
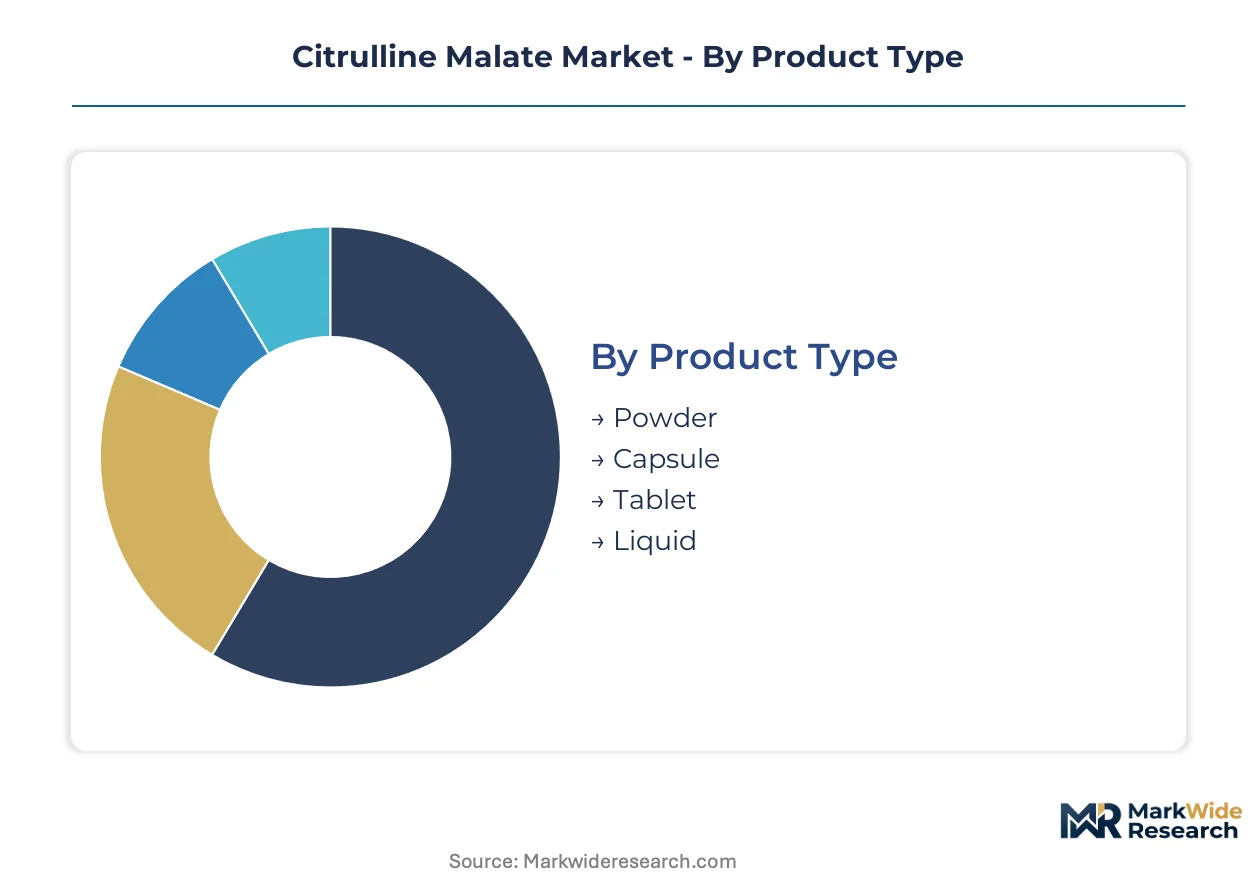
Citrulline malate procurement splits across four distinct category axes, each commanding different margin structures and certification requirements. Sports nutrition brands optimize formulation choices against channel access rules and end-user dosing preferences, creating tiered pricing bands that pharmaceutical-grade suppliers exploit.
Product Type:
Premium margin pools concentrate in taste-masked and rapid-dispersing formats that enable ready-to-drink co-development, while bulk powder retains volume leadership through private-label supply contracts.
- Powder:Standard 2:1 citrulline malate ratio delivered in bulk containers or single-serve sachets, serving private-label manufacturers and direct-to-consumer brands with flexible dosing protocols. Demand concentrates in United States CrossFit-affiliated retail channels where coach-recommended pre-workout protocols drive repurchase frequency. NSF Certified for Sport compliance requirements compress supplier margins while elevating pharmaceutical-grade material premiums.
- Capsule:Pre-measured gelatin or vegetable cellulose shells containing 750-1500mg citrulline malate per unit, targeting traveling athletes and regimented supplement users who prioritize convenience over per-serving cost. United States metropolitan markets with dense functional fitness participation show strongest adoption, though capsule shell supply constraints periodically extend lead times.
- Tablet:Compressed formulations with binding agents and disintegrants for shelf-stable retail distribution, capturing pharmacy and mass-market channels where pill-form familiarity reduces education costs.
- Liquid:Ready-to-drink suspensions or concentrated shots requiring flavor system masking and preservative stabilization, enabling immediate consumption without mixing infrastructure.
Powder holds installed capacity. Liquid is rotating up the share rankings.
End User:
Volume concentration follows institutional procurement channels where third-party certification mandates gate access, while direct-to-consumer subscription models capture lifetime value in enthusiast segments.
- Athletes:Collegiate, professional, and competitive amateur competitors subject to anti-doping protocols and institutional supplement policies. Demand clusters in United States athletic departments requiring NSF Certified for Sport or Informed Sport accreditation, with procurement teams requalifying ingredient sources against evolving purity benchmarks.
- Bodybuilders:Physique-focused consumers prioritizing nitric oxide-mediated vasodilation and training volume capacity, typically purchasing through specialty retailers or direct-to-consumer brands with transparent labeling protocols. This segment shows highest price elasticity for pharmaceutical-grade material and lowest tolerance for proprietary blend opacity.
- Fitness Enthusiasts:Recreational exercisers incorporating citrulline malate into broader supplement stacks, often initiating purchase through influencer recommendations or subscription auto-replenishment platforms.
- Health Supplements:General wellness positioning targeting cardiovascular support and circulatory function beyond exercise contexts, with reimbursement pathway exploration underway in Germany and Japan for sarcopenia applications.
Athletes anchor institutional volume. Health Supplements is climbing the fastest.
Distribution Channel:
Channel economics bifurcate between margin-extractive retail intermediaries and data-rich direct relationships, with certification requirements filtering supplier access differently across each pathway.
- Online Retail:Direct-to-consumer platforms and marketplace listings bypassing wholesale markups, capturing purchase data for dosing optimization and cross-sell sequencing. United States direct-to-consumer brands lead channel expansion, though FTC substantiation enforcement constrains performance claim language in social media influencer partnerships.
- Specialty Stores:Fitness-focused retailers and supplement boutiques offering personalized consultation and immediate fulfillment, justifying price premiums through staff expertise and protocol customization.
- Health Food Stores:Natural products channels emphasizing clean label positioning and non-GMO verification, with shelf placement contingent on third-party certification completion.
- Wholesale:Bulk supply to contract manufacturers, private-label brands, and institutional procurement teams, with minimum order quantities and pharmaceutical-grade documentation requirements filtering supplier participation.
Wholesale holds installed capacity. Online Retail is gaining share fastest.
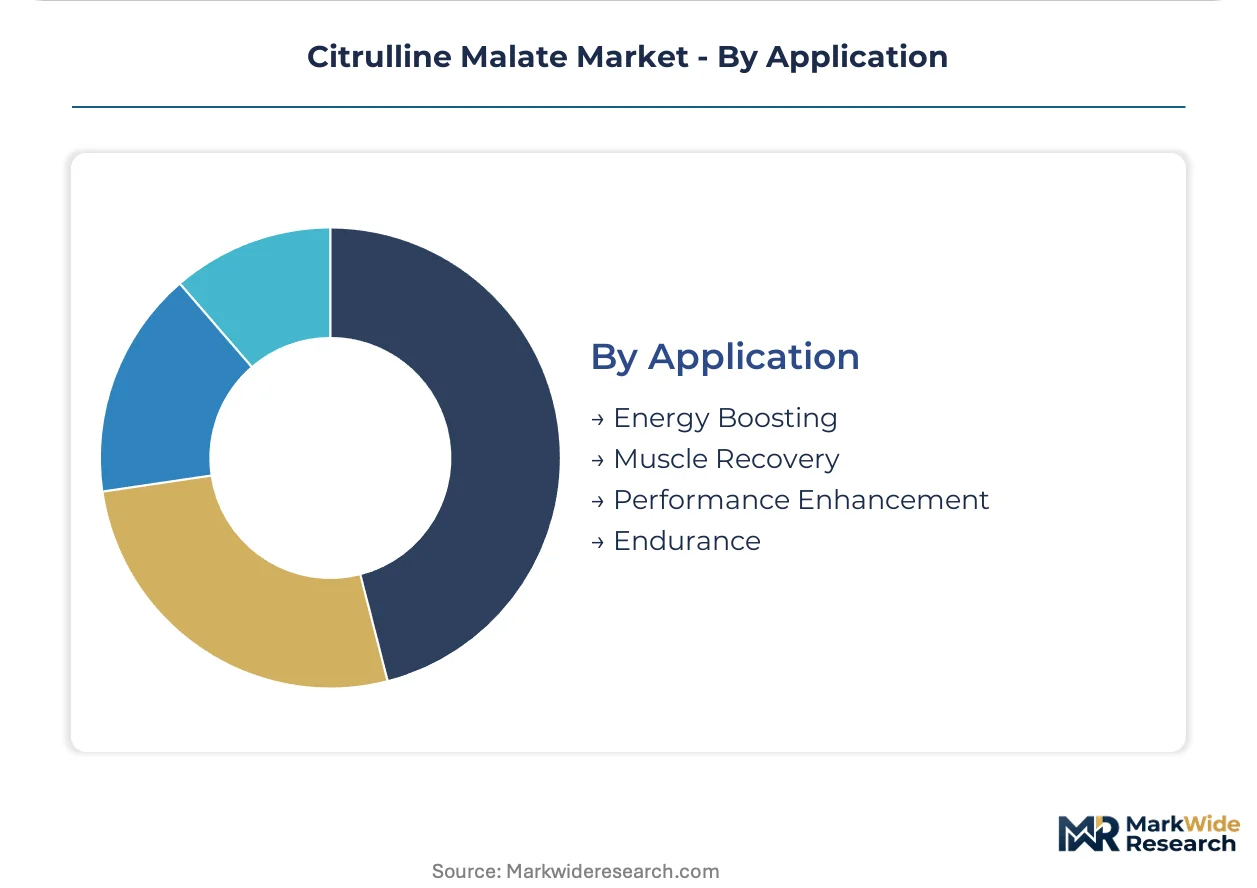
Application:
Claim substantiation requirements from FTC and FDA partition marketing positioning between clinically defensible endurance messaging and mechanistic hypothesis language that enforcement actions increasingly target.
- Energy Boosting:Positioning around ATP regeneration and Krebs cycle intermediate function, requiring careful claim language to avoid FDA scrutiny of disease implications.
- Muscle Recovery:Post-exercise ammonia clearance and lactate buffering narratives, with peer-reviewed trial references now mandatory for United States marketing compliance.
- Performance Enhancement:Nitric oxide precursor claims supporting power output and training volume, the most contested positioning category given FTC enforcement priority around influencer partnerships and social media substantiation.
- Endurance:Time-to-exhaustion and cardiovascular efficiency positioning with strongest clinical trial support, enabling premium pricing in marathon, cycling, and triathlon segments.
Performance Enhancement holds installed capacity. Endurance is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence on East Asian fermentation feedstock shapes procurement strategies across major consuming markets, with finished-product manufacturers diversifying supplier qualification programs to mitigate logistics disruption exposure.
United States
CrossFit-affiliated retail channels and direct-to-consumer subscription platforms drive pharmaceutical-grade citrulline malate absorption. FDA cGMP enforcement and FTC substantiation standards constrain marketing claims around nitric oxide production. Greater metropolitan areas in Texas and California concentrate specialty store distribution networks serving functional fitness participants.
Germany
Hospital formulary exploration for sarcopenia applications creates institutional procurement pathways beyond sports nutrition. EU Novel Food authorization efforts target fortified food and beverage integration. The Rhine-Ruhr industrial corridor hosts contract manufacturers supplying private-label brands across the European single market.
Japan
Fermentation-derived amino acid production clusters concentrate L-citrulline feedstock supply under METI industrial guidance. Reimbursement pathway development for cardiovascular and muscle-wasting indications proceeds through PMDA consultation. The Kanto region around Tokyo anchors pharmaceutical-grade manufacturing capacity serving domestic and export demand.
China
Enzymatic synthesis and biocatalytic production platforms achieve scale efficiencies for ingredient-grade material. NMPA dietary supplement regulations and SAMR quality supervision reshape export documentation requirements. The Yangtze River Delta manufacturing belt supplies bulk powder to North American and European contract manufacturers.
United Kingdom
Specialist sports nutrition retailers and online direct-to-consumer platforms capture enthusiast demand with transparent labeling protocols. MHRA border inspection post-Brexit extends import clearance timelines for third-party-certified material. The Southeast England logistics corridor handles inbound pharmaceutical-grade shipments for redistribution across domestic and Irish markets.
Citrulline Malate Market Competitive Environment
Listed leaders compete with private specialists across certification tier and channel access dimensions, creating a bifurcated structure where pharmaceutical-grade documentation separates premium suppliers from commodity-grade competitors. The supplier base concentrates around fermentation-platform originators and finished-product brands with in-house testing protocols. Three archetypes dominate: East Asian fermentation specialists, North American direct-to-consumer brands with transparent supply chains, and private-label contract manufacturers serving mass-market retail. Capacity expansion and third-party certification pursuit constitute the primary competitive moves, with NSF Certified for Sport and Informed Sport accreditation timelines extending product launch windows.
Within the fermentation-specialist tier, Kyowa Hakko Bio Co., Ltd. exemplifies platform-based amino acid supply to branded finished-product manufacturers. Among North American direct-to-consumer operators, NutraBio Labs Inc. and NOW Foods occupy positions defined by testing transparency and broad retail distribution respectively. These three entities represent the spectrum from upstream ingredient supply through multi-channel finished-product presence.
| Leading Market Players |
|---|
| Kyowa Hakko Bio Co., Ltd. |
| NutraBio Labs Inc. |
| NOW Foods |
| Prinova Group LLC |
| Swanson Health Products |
| BulkSupplements.com |
| PureBulk, Inc. |
| AIDP, Inc. |
| Shanghai Freemen LLC |
| Others |
Value Chain & Pricing Dynamics
Fermentation-platform scale economies in East Asian amino acid manufacturing anchor supply concentration and establish pharmaceutical-grade price floors that commodity-grade suppliers cannot undercut. Capacity utilization at Japanese and Korean L-citrulline feedstock facilities directly determines ingredient-grade margin pools available to North American and European finished-product manufacturers.
Pricing Analysis
Industrial OEM buyers anchor pharmaceutical-grade premiums through NSF Certified for Sport and Informed Sport procurement mandates. Pricing stratifies across pharmaceutical-compliant, third-party-certified, and commodity-grade tiers based on purity thresholds and documentation depth. Cost compression in the commodity-grade segment is intensifying because enzymatic synthesis capacity expansion in China adds supply volume without quality-equivalent certification. Direct-to-consumer subscription brands show lowest price sensitivity, while private-label contract manufacturers serving mass-market retail exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for pharmaceutical-grade material extend 8-14 months due to dual-certification sequencing requirements. Fermentation-derived L-citrulline feedstock concentrates in Japan, South Korea, and China, with biocatalytic production platforms resting on corn-derived glucose and specialized enzyme cultures. Single-source vulnerability runs through the Kanto region's pharmaceutical-grade amino acid cluster, where METI-industrial guidance shapes export allocation. Distribution runs through contract manufacturers, private-label brands, and direct-to-consumer platforms with divergent documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among institutional procurement teams at collegiate athletic departments and hospital formulary committees, fragmenting volume across fewer decision-makers with stricter certification requirements.
For Market Incumbents: Secure NSF Certified for Sport and Informed Sport accreditation simultaneously to compress launch windows and preempt competitor access to institutional channels. Backward integration into fermentation-platform partnerships with East Asian suppliers reduces currency exposure and feedstock allocation risk from Japanese and Korean manufacturing clusters.
For New Entrants and Emerging Players: Certification fast-track through EU Novel Food authorization unlocks fortified food and beverage applications with lower competitive density than saturated pre-workout powder segments. White-space concentration sits in clinical nutrition positioning for sarcopenia and cardiovascular support in Germany and Japan, where reimbursement pathway exploration proceeds without established ingredient-grade suppliers. Direct-to-consumer subscription platforms enable bypass of retail margin extraction while capturing lifetime value data.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer brands with transparent supply chains and auto-replenishment platforms. Long-term viability over a multi-year horizon favors acquisition targets with in-house HPLC and mass spectrometry validation capabilities, as analytical chemistry talent scarcity constrains contract manufacturer quality assurance. Watch FDA enforcement priority shifts around New Dietary Ingredient notifications as an inflection indicator for formulation strategy disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Pursuit | Simultaneous NSF Certified for Sport and Informed Sport accreditation accelerates institutional channel access for pharmaceutical-grade suppliers. |
| Fermentation Platform Partnership | Upstream alliances with Japanese and Korean amino acid manufacturers secure feedstock allocation amid logistics disruption exposure. |
| EU Novel Food Authorization | Successful regulatory navigation unlocks fortified food and beverage positioning across the European single market. |
| Direct-to-Consumer Subscription Launch | Auto-replenishment platforms capture purchase data for dosing optimization while bypassing wholesale margin extraction. |
| In-House Analytical Capability Buildout | Proprietary HPLC and mass spectrometry protocols reduce reliance on scarce contract manufacturer quality assurance talent. |
Study Parameters
A spread of perspectives from fermentation platform engineers, sports nutrition brand formulators, institutional procurement managers, and third-party certification auditors converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from FDA warning letter databases, NSF International certification registries, customs trade data, and SEC filings from listed ingredient suppliers. Bottom-up volume estimates from production capacity and top-down demand triangulation from end-use consumption patterns were reconciled.
Product type, end user archetype, distribution channel, and application claim category structured the segmentation dimensions modeled across the projection horizon. CAGRs were derived from regression analysis against historical volume trajectories and forward-looking capacity expansion announcements. Forecast inputs incorporated FDA cGMP enforcement intensity indices and CrossFit-affiliated retail channel density metrics.
Decision-makers should treat outputs as directional under assumptions of stable East Asian fermentation capacity and unchanged FTC substantiation enforcement posture; material deviation would warrant model refresh. Specific risk factors include tariff exposure on amino acid imports, state-level pre-workout ingredient restrictions, and PMDA reimbursement pathway decisions in Japan. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Global Methylal Market
Functional Chemicals
Calcium Citrate Malate Market
Functional Chemicals
Urea Formaldehyde Market
Functional Chemicals
Ortho Phthalic Aldehyde Market
Functional Chemicals
Isophthaloyl Chloride Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Sodium Methylate Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Heptanoic Acid Market
Functional Chemicals
Paraformaldehyde Market
Functional Chemicals
Succinimide Market
Functional Chemicals
Global Peptide Synthesis Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Serine Amino Acid Market