
 Asparagine Market | 2026-2036
Asparagine Market Size, Share, and Industry Trends Forecast 2026-2036
Asparagine Market Outlook
Pharmaceutical companies is bifurcating demand away from conventional food manufacturers as peptide drug synthesis and cell culture media formulations expand. Ajinomoto Co., Inc. leverages decades of amino acid fermentation expertise to dominate high-purity pharmaceutical-grade supply chains. Merck KGaA anchors European demand through its life science reagent portfolio serving biopharma R&D laboratories. Shanghai Meihua Biological Technology Co., Ltd. competes aggressively on fermentation scale and backward integration into corn-derived glucose feedstock.
Asparagine is a non-essential amino acid with the chemical formula C4H8N2O3, produced industrially via microbial fermentation of carbohydrate substrates or enzymatic conversion from aspartic acid, and serves primarily as a building block for protein synthesis, flavor enhancement, and pharmaceutical excipient applications. Food Grade asparagine retains mature volume leadership through sustained bakery and savory flavoring demand, though Pharmaceutical Grade generates superior margin pools from injectable and biologic formulation requirements. Nutraceutical Firms represent the fastest-growing end user channel as sports nutrition and clinical nutrition brands incorporate conditionally essential amino acid positioning into premium product lines.
FDA purity standards for pharmaceutical excipients and EMA's ICH Q3D elemental impurity guidelines constrain market access for unqualified fermentation batches, while China's NMPA strengthens amino acid API registration requirements under revised drug master file protocols. The EU Green Deal's fermentation carbon intensity benchmarks and REACH chemical safety obligations add compliance layers for European production facilities. Stakeholders must monitor regulatory divergence between pharmaceutical-grade certification regimes and emerging clean-label food additive standards to align capacity investments with the stricter of overlapping compliance thresholds.
Market Dynamics
Pharmaceutical-grade fermentation capacity is bifurcating supply chains as peptide drug manufacturers demand impurity profiles below 0.1%, forcing food-grade producers to abandon dual-use facilities or invest in segregated production lines.
Growth Catalysts
- ICH Q3D Compliance:EMA's elemental impurity guidelines for pharmaceutical excipients are accelerating facility upgrades across European contract manufacturers, expanding addressable market for qualified suppliers.
- Cell Culture Media Expansion:Monoclonal antibody production lines in China and Germany are absorbing pharmaceutical-grade asparagine at volumes exceeding traditional excipient demand.
- Enzymatic Conversion Efficiency:Aspartic acid precursor technologies are reducing fermentation cycle times, compressing unit economics for synthetic production routes.
Market Restraints
- Corn Feedstock Volatility:Drought conditions in North American grain belts are spiking glucose substrate costs, squeezing margin structures for fermentation-dependent producers.
- Pharmaceutical Certification Barriers:FDA drug master file requirements and NMPA's revised amino acid API protocols are extending qualification timelines to 18-24 months for new entrants.
- Glutamine Substitution:Conditionally essential amino acid alternatives are displacing asparagine in select sports nutrition formulations where nitrogen metabolism enhancement is the primary objective.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for active pharmaceutical ingredients are attracting fermentation capacity investments targeting export markets.
- Clean-Label Food Additive Positioning:EU Green Deal carbon intensity benchmarks are creating preference for fermentation-derived over chemically synthesized food-grade supply.
- Clinical Nutrition Channel:Hospital formulary and enteral nutrition brands are incorporating conditionally essential amino acid positioning into premium parenteral nutrition lines.
Industry Challenges
- Fermentation Scale-Up Expertise:Qualified bioprocess engineers capable of maintaining pharmaceutical-grade contamination controls command salary premiums exceeding 40% above food-grade facility managers.
- Dual-Use Facility Reconfiguration:Existing plants serving both food and pharmaceutical customers face 12-18 month downtime for segregated HVAC and piping system installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asparagine Market |
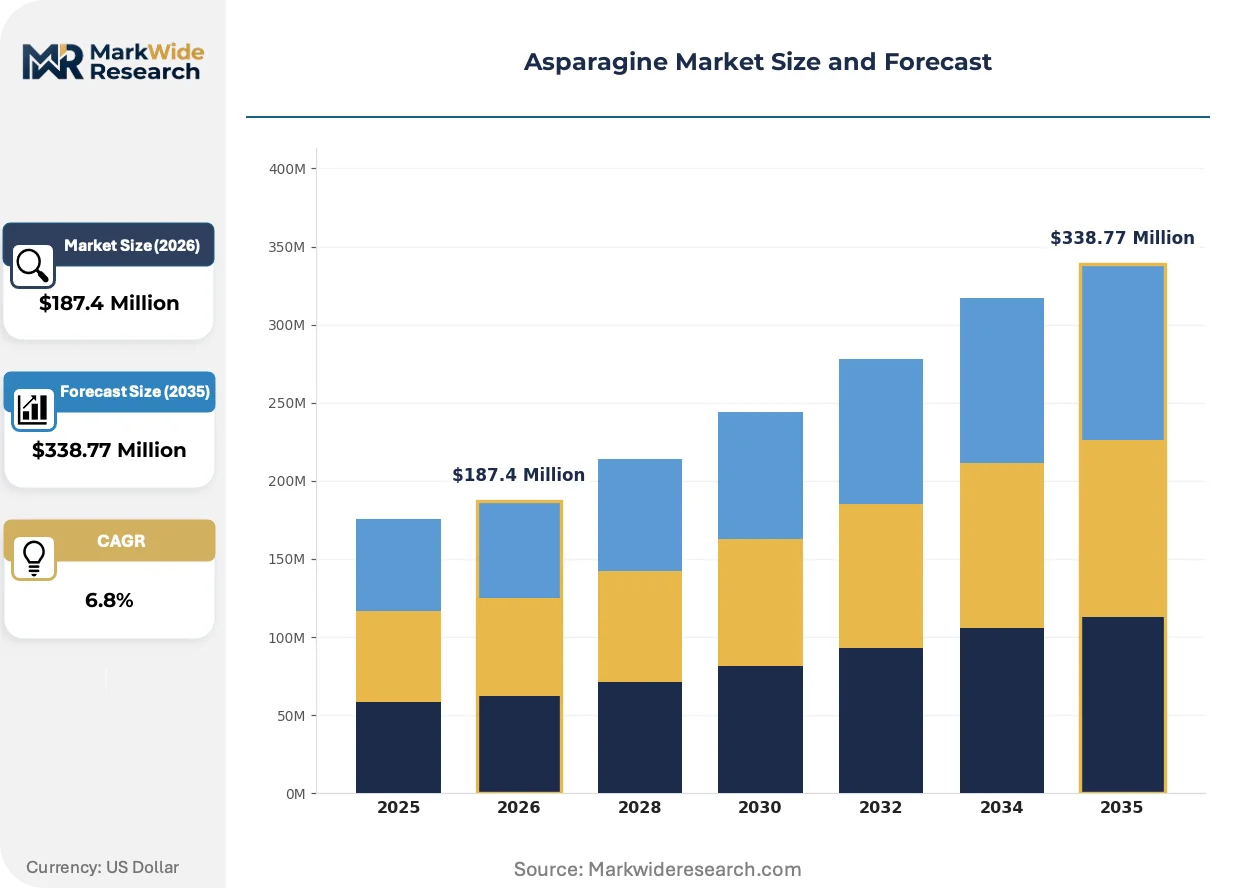
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Food Additives, Nutritional Supplements, Pharmaceutical Formulations, Cosmetics End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Suppliers, Nutraceutical Firms Distribution Channel: Online Retailers, Distributors, Wholesalers, Direct Sales |
| Companies Covered | Royal DSM N.V., Merck KGaA, Ajinomoto Co., Inc., Shanghai Meihua Biological Technology Co., Ltd., CJ CheilJedang Corporation, Archer Daniels Midland Company, Evonik Industries AG, Zhejiang NHU Co., Ltd., Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asparagine Market Strategic Shifts
Continuous fermentation monitoring systems are compressing batch-to-batch variability, while regulatory divergence between pharmaceutical and food additive regimes is fragmenting certification pathways.
Single-use bioreactor technology is bifurcating capital deployment strategies in asparagine fermentation. Contract manufacturers serving biopharma customers are adopting disposable vessel systems to eliminate cross-contamination risks between peptide drug campaigns. This shift is compressing facility validation timelines from months to weeks, though it is bifurcating the supplier base into pharmaceutical-dedicated versus multi-product operators.
REACH chemical safety obligations and the EU Green Deal's fermentation carbon intensity benchmarks are tightening operational parameters for European production facilities. Manufacturers must now document Scope 3 emissions from corn feedstock cultivation through final purification. German and Dutch plants are responding by securing renewable energy contracts and negotiating regenerative agriculture partnerships with grain suppliers.
Long-term offtake agreements are displacing spot market transactions among peptide drug manufacturers. Large-scale biopharma customers are locking in three-to-five-year supply contracts with fermentation specialists to secure capacity ahead of clinical trial milestones. This pattern is most visible in China's Yangtze River Delta cluster, where CMOs are signing exclusive pacts with domestic amino acid producers.
Asparagine Market Segmentation

Grade purity thresholds and end-use certification requirements fragment the asparagine market into non-interchangeable supply tiers. Channel economics vary sharply between bulk food ingredient procurement and pharmaceutical excipient qualification pathways.
Product Type:
Food-grade volumes flow through distributor networks to bakery and savory flavoring manufacturers, while pharmaceutical-grade supply chains require direct technical partnerships with peptide drug producers.
- Food Grade:Standard purity specifications (98-99%) serve bakery leavening systems and Maillard reaction flavor precursors. Demand concentrates in Germany and China where industrial baking and processed food manufacturing scale fastest, constrained by EFSA additive safety reviews and China's evolving GB standards for fermented food ingredients.
- Pharmaceutical Grade:Ultra-high purity (≥99.5%) with impurity profiles below 0.1% meets USP-NF and EP monograph requirements for injectable formulations. Peptide drug manufacturers in India and Germany absorb volumes at premium pricing, driven by FDA drug master file compliance deadlines and EMA's ICH Q3D elemental impurity enforcement.
- Industrial Grade:Technical-grade material supports chemical synthesis and agricultural applications where purity thresholds are less stringent.
- Cosmetic Grade:Intermediate purity band serves skin conditioning and humectant formulations in personal care products.
Food Grade dominates installed base. Pharmaceutical Grade is where expansion concentrates.
Application:
Cost-to-performance ratios stratify demand across functional categories, with clinical nutrition commanding the steepest premium tiers.
- Food Additives:Maillard reaction substrates in baked goods and savory flavor systems represent mature volume anchors. Bakery manufacturers in China and Germany source through regional distributors, facing margin pressure from clean-label reformulation trends and EU Green Deal carbon accounting requirements.
- Pharmaceutical Formulations:Excipient and active pharmaceutical ingredient applications in parenteral nutrition and peptide synthesis generate the highest margin pools. Biopharma R&D laboratories in India and Germany lock in long-term offtake agreements, constrained by 18-24 month FDA and NMPA qualification timelines.
- Nutritional Supplements:Sports nutrition and clinical nutrition brands incorporate conditionally essential amino acid positioning.
- Cosmetics:Moisturizing and skin-conditioning applications in premium personal care lines.
Food Additives commands volume leadership. Pharmaceutical Formulations is climbing the fastest.
End User:
Procurement sophistication varies from spot-market commodity purchasing to integrated supply chain partnerships with fermentation specialists.
- Pharmaceutical Companies:Peptide drug manufacturers and biopharma CMOs demand segregated production lines with pharmaceutical-grade contamination controls. India's PLI scheme for APIs is attracting fermentation capacity investments targeting export markets, while German facilities face REACH chemical safety and EU Green Deal carbon intensity compliance layers.
- Nutraceutical Firms:Sports nutrition and clinical nutrition brands are gaining share fastest as conditionally essential amino acid positioning penetrates premium product lines. Formulators in China and India source through specialized distributors, navigating FSSAI and SAMR registration requirements.
- Food Manufacturers:Industrial baking and processed food producers represent mature demand anchors.
- Cosmetic Suppliers:Personal care formulators with intermediate purity requirements.
Food Manufacturers retain volume dominance. Nutraceutical Firms is where share gains concentrate.
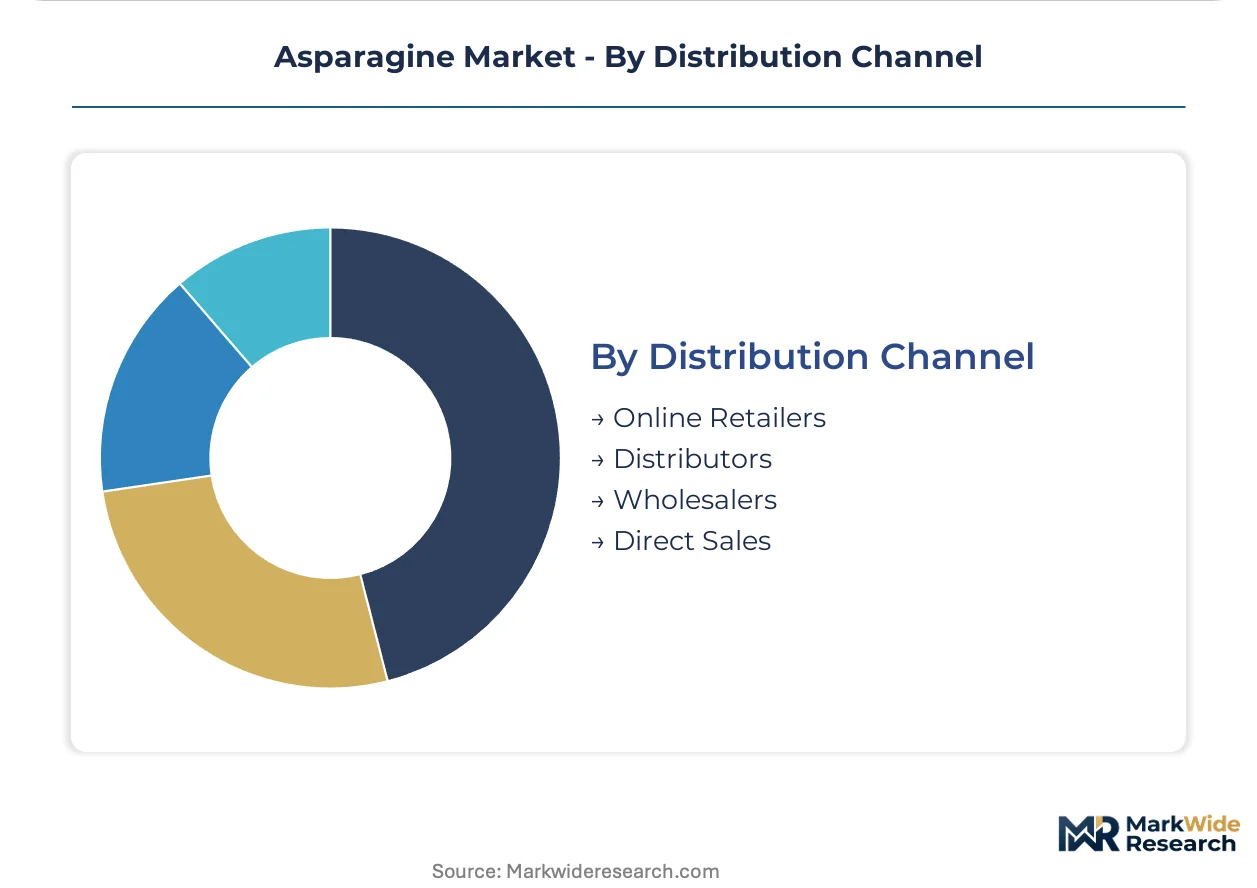
Distribution Channel:
Channel selection correlates directly with grade certification requirements and lot-size economics.
- Distributors:Regional chemical distributors dominate food-grade and industrial-grade flows, aggregating fragmented bakery and processed food demand across China, India, and Germany. Inventory carrying costs and working capital requirements create barriers for unqualified entrants.
- Direct Sales:Pharmaceutical-grade supply requires technical service relationships and long-term offtake agreements. Biopharma customers in China's Yangtze River Delta cluster sign exclusive pacts with fermentation specialists, eliminating spot-market exposure.
- Online Retailers:Small-lot nutraceutical and cosmetic ingredient sourcing.
- Wholesalers:Bulk commodity-grade material for industrial applications.
Distributors dominate food-grade throughput. Direct Sales is where pharmaceutical-grade expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports pharmaceutical-grade asparagine to biopharma clusters in Germany and India, while Japanese fermentation specialists supply high-purity grades to peptide drug manufacturers across East Asia. This trade corridor reflects the geographic concentration of amino acid API manufacturing and the regulatory divergence between Asian production hubs and Western qualification requirements.
China
Peptide drug synthesis and cell culture media expansion drive demand in the Yangtze River Delta, where CMOs sign exclusive offtake agreements with domestic producers. NMPA's revised drug master file protocols for amino acid APIs extend qualification timelines to 18-24 months. Shanghai Meihua Biological Technology anchors fermentation capacity in Shanghai, leveraging backward integration into corn-derived glucose feedstock.
Germany
Biopharma R&D laboratories and monoclonal antibody production lines absorb pharmaceutical-grade volumes at premium pricing. EMA's ICH Q3D elemental impurity guidelines and REACH chemical safety obligations force facility upgrades. Merck KGaA anchors European supply chains through its life science reagent portfolio serving laboratories in Darmstadt and surrounding industrial clusters.
India
Active pharmaceutical ingredient manufacturing and peptide synthesis operations expand under the PLI scheme's production-linked incentives. CDSCO registration requirements and FSSAI food additive standards create dual compliance layers. Hyderabad and Mumbai host fermentation capacity investments targeting export markets, with contract manufacturers qualifying for FDA drug master file protocols.
Japan
High-purity pharmaceutical-grade supply chains serve domestic biopharma and regional export demand. PMDA's stringent excipient standards and METI's industrial policy support fermentation technology leadership. Ajinomoto Co., Inc. leverages decades of amino acid expertise from its Kawasaki facilities, dominating technical partnerships with peptide drug developers.
United States
Injectable formulation and parenteral nutrition applications sustain demand despite domestic fermentation capacity constraints. FDA purity standards for pharmaceutical excipients and EPA environmental compliance add regulatory layers. Boston and San Diego biotech clusters rely on imported pharmaceutical-grade supply, with distributors managing inventory for regional food manufacturers.
Asparagine Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with fermentation expertise, creating a tiered structure where pharmaceutical-grade qualification separates premium suppliers from commodity operators. Three archetypes dominate: Japanese amino acid specialists with decades of bioprocess heritage, European life science conglomerates with integrated reagent portfolios, and Chinese fermentation scale players with feedstock integration. Competitive moves concentrate on segregated production line investments and long-term offtake agreements with biopharma customers.
Within the heritage-specialist tier, Ajinomoto Co., Inc. and Merck KGaA exemplify divergent geographic anchoring—Tokyo-based fermentation expertise versus Darmstadt-centered life science distribution. Shanghai Meihua Biological Technology Co., Ltd. occupies a position among Chinese scale-driven producers, representing the archetype of corn-belt feedstock integration and aggressive capacity expansion. These three entities illustrate how qualification depth, geographic proximity to demand clusters, and upstream supply control define competitive positioning.
| Leading Market Players |
|---|
| Royal DSM N.V. |
| Merck KGaA |
| Ajinomoto Co., Inc. |
| Shanghai Meihua Biological Technology Co., Ltd. |
| CJ CheilJedang Corporation |
| Archer Daniels Midland Company |
| Evonik Industries AG |
| Zhejiang NHU Co., Ltd. |
| Cargill |
| Others |
Value Chain & Pricing Dynamics
Fermentation scale economies at Chinese and Japanese producers compress unit costs below synthetic routes, concentrating supply-side pricing power among corn-belt integrated operators and fragmenting buyer leverage across pharmaceutical-grade and food-grade tiers.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates peptide drug manufacturers from bakery formulators and chemical synthesis buyers. Price differentiation hinges on USP-NF certification depth and impurity profile stringency, with pharmaceutical-grade commanding multiples over standard purity tiers. Cost compression in food-grade supply is intensifying because EU Green Deal carbon accounting requirements force facility upgrades. Nutraceutical firms demonstrate highest price sensitivity, while biopharma CMOs absorb premiums for segregated production line guarantees.
Supply Chain Analysis
Strategic stockpile preferences dominate pharmaceutical-grade procurement, with peptide drug manufacturers locking in three-to-five-year offtake agreements to secure capacity ahead of clinical milestones. Supply concentrates in China, Japan, and Germany, with fermentation capacity anchored in corn-belt provinces and coastal industrial clusters. Raw material dependencies center on corn-derived glucose substrates, purified water systems, and specialized enzyme preparations. Single-source vulnerability runs through Yangtze River Delta CMOs dependent on domestic amino acid producers. Distribution runs through direct technical partnerships for pharmaceutical grades and regional chemical distributors for food-grade volumes.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glutamine substitution in sports nutrition formulations threatens asparagine's conditionally essential positioning, forcing incumbents to defend clinical nutrition and peptide synthesis applications where amino acid specificity is irreplaceable.
For Market Incumbents: Fortify pharmaceutical-grade certification moats by investing in segregated HVAC and piping systems that eliminate cross-contamination risks, while securing renewable energy contracts to meet EU Green Deal carbon intensity benchmarks. Backward integration into regenerative agriculture partnerships with grain suppliers stabilizes corn feedstock exposure.
For New Entrants and Emerging Players: Contract manufacturing service gaps in India's PLI scheme corridors offer white-space entry points, with Hyderabad and Mumbai fermentation capacity serving export markets under FDA drug master file protocols. Target clinical nutrition channel partnerships where hospital formulary positioning commands premium pricing and long-term supply agreements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation specialists with demonstrated pharmaceutical-grade contamination controls and established NMPA registration pathways. Five-to-ten-year viability hinges on clean-label food additive demand convergence with pharmaceutical-grade supply chain rigor. Watch for ICH Q3D enforcement intensity in European contract manufacturing as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Segregated Production Line Investment | Eliminates cross-contamination risks for peptide drug manufacturers under FDA drug master file protocols. |
| Backward Integration into Feedstock | Corn-belt glucose supply control insulates margin structures from North American grain belt volatility. |
| Long-term Offtake Agreement | Three-to-five-year contracts with Yangtze River Delta CMOs secure capacity ahead of clinical trial milestones. |
| Pharmaceutical-Grade Certification | USP-NF and EP monograph compliance unlocks injectable formulation demand at premium pricing tiers. |
| Renewable Energy Transition | EU Green Deal carbon intensity benchmarks force German and Dutch plants into clean power contracts. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation plant managers, peptide drug development executives, biopharma procurement leads, and clinical nutrition formulators. Secondary validation drew from NMPA drug master file protocols, EMA ICH Q3D guidance documents, FDA excipient monographs, and customs trade data for amino acid API flows. Bottom-up capacity modeling triangulated against top-down demand aggregation across pharmaceutical, food additive, and nutraceutical end-uses.
Across the analysis window, volume and value projections segmented by grade tier, end-use industry, and regional production hub. CAGRs derived from historical fermentation capacity expansion rates, peptide drug pipeline progression, and clean-label food additive penetration curves. Modeled inputs incorporated corn feedstock price volatility bands, regulatory qualification timeline distributions, and single-use bioreactor adoption rates in contract manufacturing.
Underlying assumptions cover sustained pharmaceutical-grade contamination control standards, with deviation risk concentrated in NMPA registration timeline extensions and EU Green Deal carbon accounting enforcement intensity. Revision becomes warranted when glutamine substitution rates in sports nutrition cross threshold levels that erode asparagine's conditionally essential positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Serine Market
Functional Chemicals
Calcium Citrate Malate Market
Functional Chemicals
Adipamide Market
Functional Chemicals
Citrulline Malate Market
Functional Chemicals
Heptanoic Acid Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Transfluthrin Market
Functional Chemicals
Amino Acids Market
Functional Chemicals
Glutaraldehyde Market
Functional Chemicals
Succinimide Market
Functional Chemicals
Carbomer Market
Functional Chemicals
Imidazole Market
Functional Chemicals
Isophthaloyl Chloride Market
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
Acrylamide Monomer Market