
 Asia-Pacific Amino Acids Market | 2026-2036
Asia-Pacific Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Amino Acids Market Outlook
Premium pharmaceutical-grade amino acids and commodity feed-grade volumes is shifting along divergent margin curves in the Asia-Pacific landscape. Ajinomoto Co., Inc. leverages its fermentation technology leadership to dominate high-purity L-glutamate supply for intravenous nutrition across Japan and China. Fufeng Group anchors massive lysine capacity in Shandong Province, competing aggressively on feed-grade pricing through backward integration into corn processing. CJ CheilJedang Corporation differentiates its portfolio with specialty amino acids for functional foods, sustaining premium positioning against commodity competitors.
Asia-Pacific amino acids comprise organic compounds containing amine and carboxyl functional groups, typically produced via microbial fermentation of carbohydrate feedstocks or enzymatic conversion, with purity grades ranging from feed-grade to injection-grade meeting pharmacopeial specifications. These molecules serve as essential building blocks for protein synthesis, flavor enhancement, and metabolic modulation across industrial applications. L-Glutamate occupies the largest volume share as the dominant flavor enhancer in processed foods throughout East Asia, while L-Lysine generates the fastest growth trajectory driven by intensive poultry and swine operations across Vietnam and Indonesia. The powder form commands the widest distribution footprint due to stability advantages in tropical storage conditions, though liquid lysine gains traction in automated feed mills seeking dosing precision.
China's NMPA enforces pharmacopeial standards for injectable amino acid formulations, while Japan's PMDA maintains stringent GMP certification requirements that filter out lower-tier suppliers. India's CDSCO alignment with ICH quality guidelines is reshaping import requirements for fermentation-derived active pharmaceutical ingredients. Stakeholders must monitor how China's dual carbon goals and India's PLI scheme for biotechnology alter the cost structure of fermentation-based production relative to synthetic routes.
Market Dynamics
Fermentation capacity clustering in Shandong and Jiangsu provinces is compressing logistics costs while amplifying feedstock competition, forcing formulators to secure multi-year corn supply contracts or face margin erosion.
Growth Catalysts
- PLI scheme for biotechnology:India's production-linked incentive scheme redirects domestic capital toward fermentation-based amino acid manufacturing, reducing import dependency for pharmaceutical-grade products.
- Intensive livestock operations:Vietnam and Indonesia's expanding poultry and swine sectors drive lysine and methionine consumption as commercial feed penetration displaces traditional farming practices.
- Dual carbon goals:China's national emissions targets accelerate facility upgrades toward energy-efficient fermentation, creating competitive advantage for operators with captive renewable power.
Market Restraints
- Corn price volatility:Feedstock cost fluctuations in North China Plain directly compress fermentation margins, with limited hedging instruments available to mid-scale producers.
- Single-region supply concentration:Over 60% of regional lysine capacity sits within 200 kilometers of Jinan, creating systemic disruption risk from localized environmental enforcement or logistics bottlenecks.
- Synthetic route competition:Chemical synthesis of select amino acids maintains cost parity for non-chiral applications, capping fermentation price premiums in industrial segments.
Strategic Opportunities
- Underpenetrated Indian pharmaceutical market:Domestic injectable nutrition formulation capacity remains below regional demand, creating white space for fermentation-derived L-glutamate and L-arginine suppliers.
- Functional foods convergence:Sports nutrition and elderly care products in Japan and South Korea absorb specialty amino acids at pharmacopeial purity grades, commanding sustained premium pricing.
- Automated feed mill adoption:Liquid lysine dosing systems in Thailand and Malaysia reduce labor costs and improve ration precision, favoring suppliers with integrated liquid formulation capabilities.
Industry Challenges
- Pharmacopeial certification timelines:CDSCO and NMPA alignment with ICH quality guidelines extends approval cycles for new fermentation facilities, delaying capacity monetization.
- Skilled fermentation technologist scarcity:Industrial microbiology and downstream processing expertise concentrates with incumbent operators, constraining new entrant scale-up velocity.
- Legacy equipment integration:Retrofitting existing facilities for continuous fermentation requires substantial capital outlay with uncertain yield recovery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Amino Acids Market |
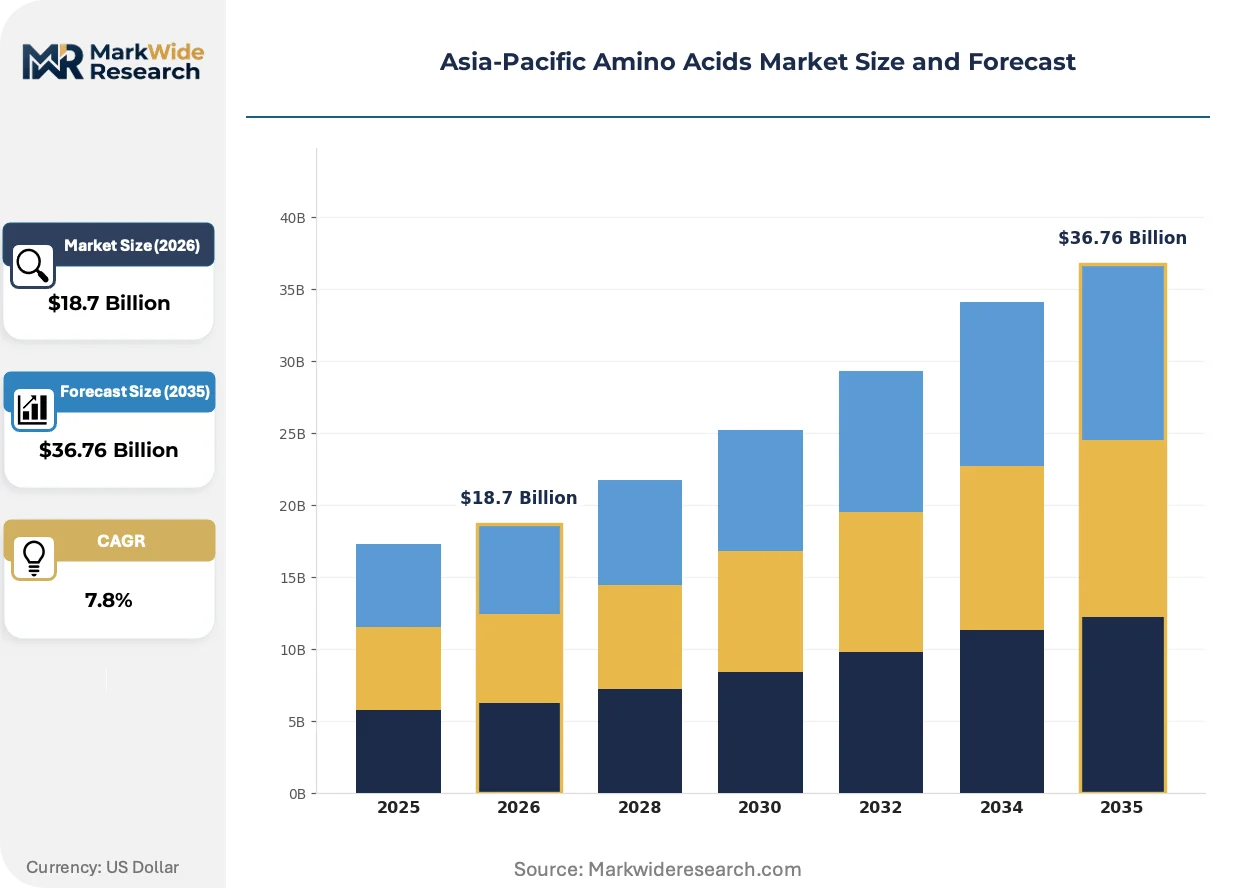
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Glutamate, L-Arginine, L-Lysine, L-Tryptophan End Use Industry: Pharmaceuticals, Food & Beverage, Animal Feed, Nutrition Form: Powder, Liquid, Granules, Tablets Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Ajinomoto Co., Inc., Evonik Industries AG, Archer Daniels Midland Company, CJ CheilJedang Corporation, Kyowa Hakko Bio Co., Ltd., Adisseo, Royal DSM N.V., Fufeng Group, Merck KGaA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Amino Acids Market Strategic Shifts
Bioprocess intensification and digital fermentation control are compressing batch cycles while regulatory harmonization across Asia-Pacific jurisdictions reshapes competitive entry barriers.
Continuous fermentation technology with real-time metabolite monitoring is decentralizing production economics away from mega-scale batch facilities. Mid-cap operators in Jiangsu and Guangdong provinces adopt modular skid-mounted systems to capture regional feedstock arbitrage. This technology is decentralizing the historical advantage of 100,000-tonne single-site plants by enabling distributed 10,000-tonne facilities with comparable unit costs.
China's NMPA implementation of pharmacopeial standards for injectable amino acid formulations is tightening purity verification protocols. The regulation forces fermentation operators to deploy multi-stage chromatographic purification or risk exclusion from hospital procurement tenders. Japanese and Korean pharmaceutical formulators are responding by qualifying secondary suppliers to reduce single-source dependency.
Direct procurement contracts between amino acid producers and integrated livestock conglomerates are displacing traditional distributor networks in Vietnam and Indonesia. Large poultry integrators in Mekong Delta provinces negotiate annual lysine supply agreements with price collars tied to corn futures. This pattern concentrates purchasing power among ten to fifteen feed groups, compressing distributor margins and forcing intermediaries toward specialty amino acid niches.
Asia-Pacific Amino Acids Market Segmentation
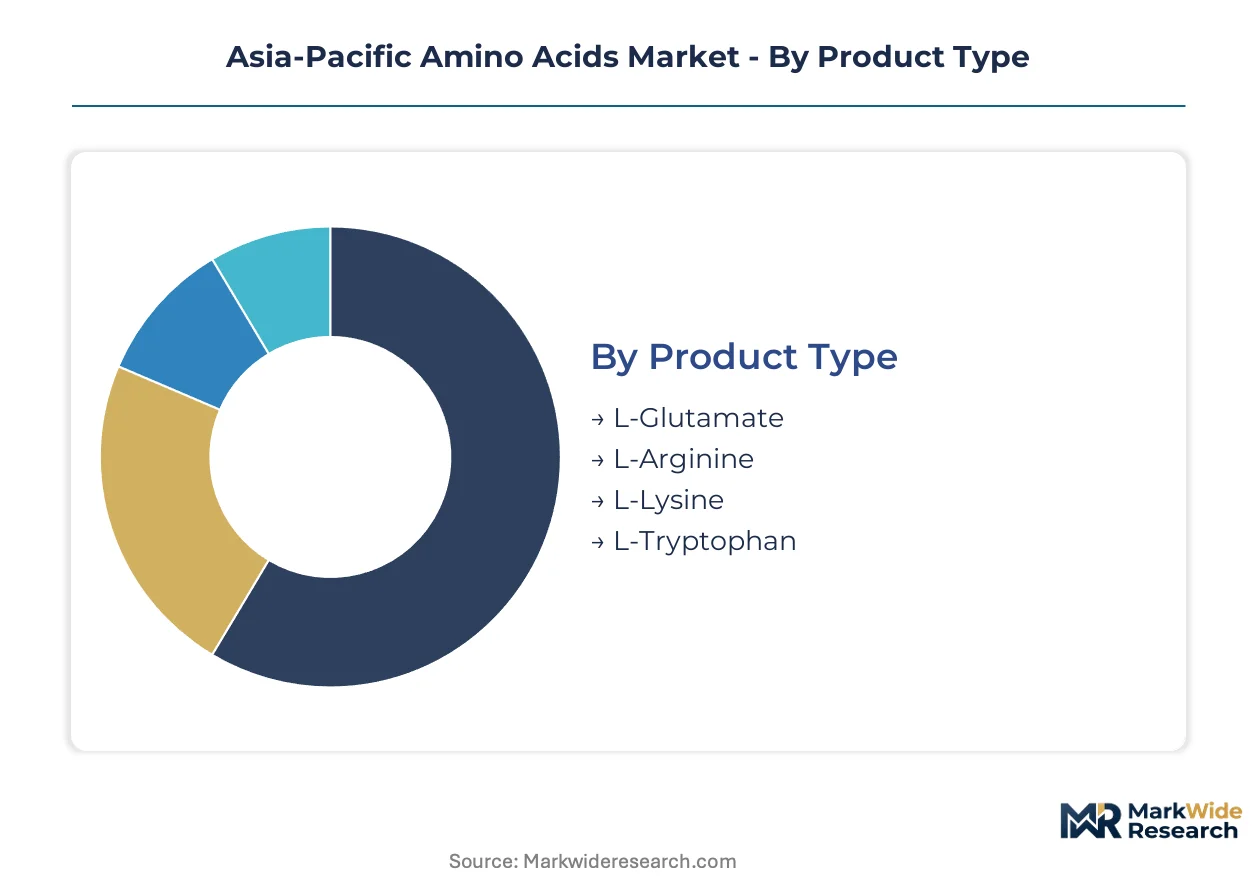
Segmentation in the Asia-Pacific amino acids market reveals how purity grades, formulation requirements, and procurement channels split manufacturing economics. Buyers in animal feed, pharmaceuticals, and food processing each impose distinct technical specifications that reshape supplier margins.
Product Type:
Buyers differentiate primarily by fermentation scale and downstream purification intensity required for their target application.
- L-Glutamate:Monosodium salt dominates flavor enhancement applications across East Asian processed food manufacturing. Demand concentrates in Japan and China's coastal provinces where umami-intensive cuisines sustain bulk purchasing from fermentation facilities with captive corn processing.
- L-Lysine:Essential for poultry and swine ration formulation, this segment absorbs the largest fermentation capacity expansion across Shandong and Jiangsu provinces. Vietnam's industrializing livestock sector drives fastest volume growth as commercial feed displaces traditional farming practices.
- L-Arginine:Pharmaceutical-grade material for intravenous nutrition and wound healing applications commands premium purification costs. Indian hospital procurement under CDSCO guidelines is expanding import substitution opportunities for domestic fermentation operators.
- L-Tryptophan:Limited commercial fermentation scale restricts supply to specialty feed and nutraceutical applications. Japanese functional food manufacturers absorb most regional output for sleep and mood support formulations.
Volume sits with L-Glutamate; growth tilts toward L-Lysine.
End Use Industry:
Application economics diverge sharply between commodity feed volumes and pharmacopeial-grade premiums.
- Animal Feed:Lysine and methionine integration into commercial poultry and swine rations drives bulk purchasing across Vietnam, Indonesia, and Thailand. Automated feed mills in Mekong Delta provinces negotiate direct annual contracts with fermentation producers, bypassing traditional distributor networks.
- Pharmaceuticals:Injectable amino acid formulations for parenteral nutrition require NMPA and PMDA pharmacopeial certification. Multi-stage chromatographic purification separates qualified suppliers from commodity producers, sustaining margin premiums for Japanese and Korean hospital suppliers.
- Food & Beverage:L-Glutamate flavor enhancement in processed foods and seasonings absorbs stable demand across China's urban consumer base. Powder stability in tropical storage conditions favors regional distribution from Shandong fermentation clusters.
- Nutrition:Sports nutrition and elderly care products in South Korea and Japan absorb specialty amino acids at intermediate purity grades. Direct-to-consumer channels are expanding for branched-chain amino acid formulations targeting fitness demographics.
Feed-grade tonnage dominates absolute volume; pharmaceutical certification sustains highest unit margins.
Form:
Physical state determines logistics economics and dosing precision for distinct buyer workflows.
- Powder:Dominates amino acid distribution due to thermal stability and extended shelf life in tropical climates. Chinese feed compounders and Southeast Asian distributors prefer bulk powder for manual blending operations.
- Liquid:Automated dosing systems in Thai and Malaysian integrated feed mills absorb expanding lysine volumes. Precision ration formulation reduces labor costs and improves feed conversion ratios for commercial poultry operations.
- Granules:Intermediate flow properties suit pharmaceutical tableting and controlled-release formulations. Japanese excipient manufacturers specify granule size distributions for direct compression processes.
- Tablets:Finished dosage forms for sports nutrition and clinical nutrition bypass compounding steps. South Korean direct-to-consumer brands package branched-chain amino acids in unit-dose formats for gym distribution.
Powder commands widest geographic reach; liquid formulations gain fastest adoption in automated processing environments.
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and price sensitivity segmentation.
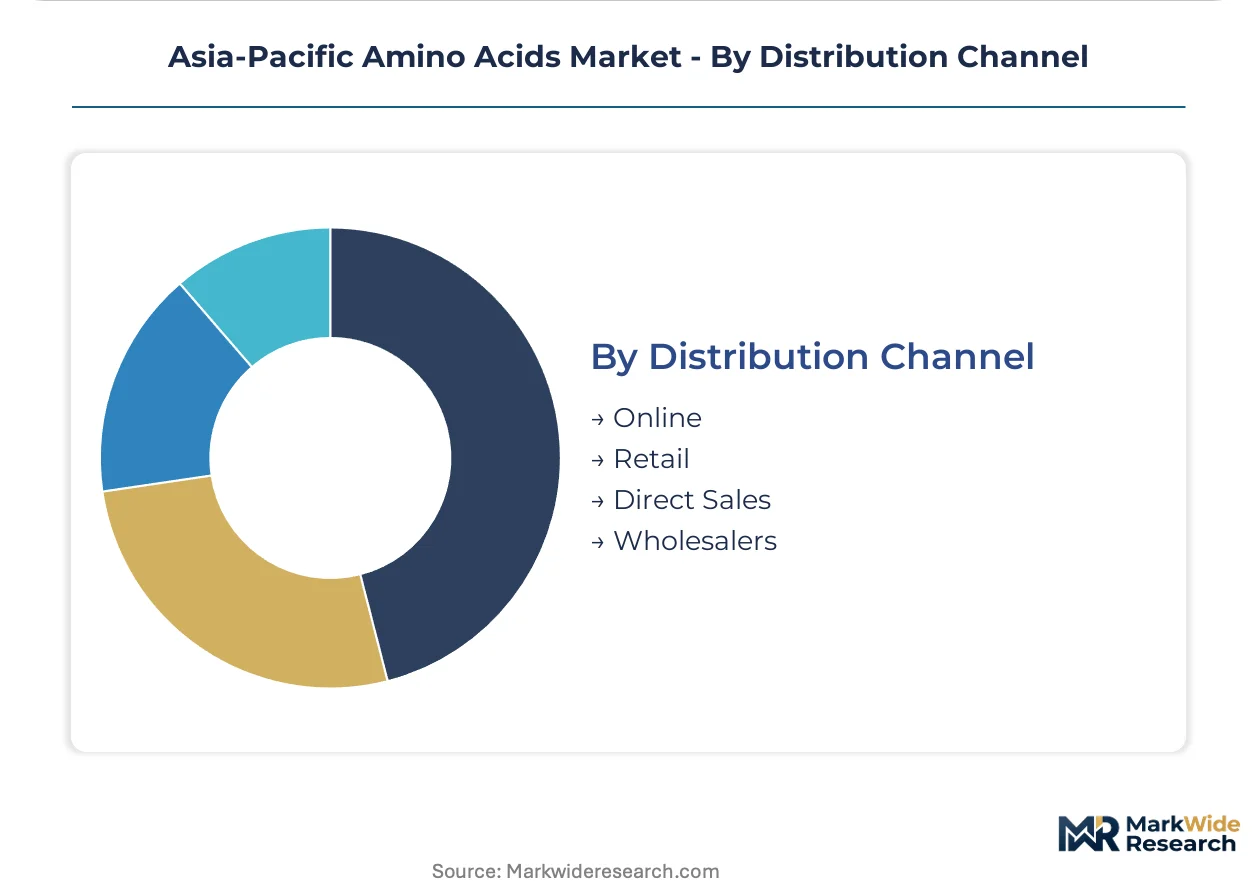
- Direct Sales:Large feed integrators in Vietnam and Indonesia negotiate annual lysine supply agreements with price collars tied to corn futures. This pattern concentrates purchasing power among fifteen major livestock groups across Mekong Delta provinces.
- Wholesalers:Traditional intermediaries serve mid-scale feed compounders and regional food manufacturers with fragmented demand. Margin compression from direct procurement is forcing wholesalers toward specialty amino acid niches.
- Online:Sports nutrition and clinical nutrition products reach consumers through South Korean and Japanese e-commerce platforms. Unit-dose amino acid supplements bypass pharmacy distribution for fitness and wellness demographics.
- Retail:Pharmacy and health food store channels dominate finished nutritional products in urban Japan. PMDA labeling requirements filter product assortment toward certified manufacturers with domestic quality systems.
Direct sales capture feed-grade volume; online channels expand fastest for finished consumer nutrition products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jinan anchors Asia-Pacific amino acid fermentation capacity, with clustered facilities in Shandong and Jiangsu provinces compressing logistics costs while amplifying feedstock competition among corn-dependent operators.
China
Livestock operations in Shandong and Jiangsu provinces drive lysine and methionine consumption as commercial feed penetration accelerates. NMPA pharmacopeial standards for injectable amino acid formulations tighten purity verification protocols, forcing multi-stage chromatographic upgrades. Corn-based feedstock availability in the North China Plain supports fermentation facility clustering near Jinan and Weifang.
India
Domestic injectable nutrition formulation capacity trails regional demand, creating white space for fermentation-derived L-glutamate and L-arginine suppliers. CDSCO alignment with ICH quality guidelines extends approval cycles for new fermentation facilities, delaying capacity monetization. The PLI scheme for biotechnology redirects capital toward domestic amino acid manufacturing in Maharashtra and Gujarat.
Japan
Functional foods and elderly care products in Kanto and Kansai regions absorb specialty amino acids at pharmacopeial purity grades. PMDA maintains stringent GMP certification requirements that filter out lower-tier suppliers from hospital procurement. Sports nutrition manufacturers in Osaka and Tokyo metropolitan areas command sustained premium pricing for branched-chain amino acid formulations.
Vietnam
Industrializing poultry and swine sectors in Mekong Delta provinces drive fastest regional lysine volume growth as commercial feed displaces traditional farming. Large poultry integrators negotiate annual lysine supply agreements with price collars tied to corn futures. Direct procurement contracts between producers and integrated livestock conglomerates are displacing traditional distributor networks.
Indonesia
Expanding commercial feed operations across Java and Sumatra absorb expanding methionine volumes for intensive broiler and layer operations. Automated feed mill adoption in Surabaya and Medan reduces labor costs and improves ration precision. Procurement is shifting toward direct annual contracts with fermentation producers as purchasing power concentrates among major feed groups.
Asia-Pacific Amino Acids Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification grade and application purity, with pharmacopeial-grade suppliers capturing sustained pricing power against feed-grade competitors. The vendor base stratifies into three tiers: integrated fermentation giants with captive corn processing, mid-scale specialists with modular continuous technology, and synthetic route operators competing on non-chiral industrial applications. Dominant competitive moves include backward integration into agricultural feedstock supply and technology licensing partnerships for bioprocess intensification.
Among Japanese and Korean pharmaceutical-grade specialists, Ajinomoto Co., Inc. and Kyowa Hakko Bio Co., Ltd. exemplify premium-tier positioning through fermentation technology leadership for intravenous nutrition. CJ CheilJedang Corporation occupies a position within the specialty amino acid tier for functional food applications. Fufeng Group represents scale-driven commodity feed-grade supply with Shandong-based capacity concentration.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Evonik Industries AG |
| Archer Daniels Midland Company |
| CJ CheilJedang Corporation |
| Kyowa Hakko Bio Co., Ltd. |
| Adisseo |
| Royal DSM N.V. |
| Fufeng Group |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Industrial microbiology talent concentration in Jiangsu and Shandong provinces widens labor-cost differentials between pharmacopeial-grade and feed-grade operations, compressing pricing-tier spreads as fermentation technologist scarcity inflates purification facility wages.
Pricing Analysis
Yield-guaranteed contract structures anchor amino acid pricing to livestock feed conversion ratios and pharmaceutical formulation throughput. Three-tier pricing structure across pharmacopeial, food-grade, and feed-grade levels separates NMPA-certified suppliers from commodity fermenters facing CDSCO compliance costs. Pricing pressure stems from corn futures volatility squeezing Shandong-based operators with single-region feedstock exposure. Automated feed mills in Vietnam demonstrate lowest price sensitivity; hospital procurement committees in Japan exhibit highest premium tolerance for GMP-certified supply.
Supply Chain Analysis
India's PLI scheme for biotechnology is redirecting capital toward domestic fermentation capacity, reducing import dependency for pharmaceutical-grade amino acids. Manufacturing gravity centers on China, India, and South Korea, with corn processing and downstream purification capabilities concentrated in Shandong and Jiangsu provinces. Raw material flows draw from North China Plain corn harvests, Indonesian palm-derived carbohydrate feedstocks, and Indian molasses sources. Single-region supply concentration within 200 kilometers of Jinan creates systemic disruption risk from localized environmental enforcement. Distribution runs through direct procurement contracts between fermentation producers and integrated Vietnamese livestock conglomerates, displacing traditional wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. NMPA pharmacopeial standards for injectable amino acid formulations create a barrier-to-entry moat that filters out lower-tier suppliers from hospital procurement tenders.
For Market Incumbents: Extend certification advantage by securing multi-year corn supply contracts in Shandong before feedstock competition intensifies. Deploy modular continuous fermentation systems in secondary Jiangsu facilities to capture regional labor arbitrage against mega-scale batch competitors. Synthetic route operators from non-chiral industrial segments threaten margin compression in commodity lysine tiers. For New Entrants and Emerging Players: Capture underpenetrated Indian pharmaceutical formulation capacity by qualifying L-arginine and L-glutamate supply under CDSCO ICH-aligned guidelines. Target Maharashtra and Gujarat for fermentation facility siting given PLI scheme capital availability. Automated feed mill partnerships in Thailand offer liquid lysine dosing precision as differentiated entry angle. For Investors and Strategic Acquirers: Re-rating potential sits with pharmacopeial-grade specialists given NMPA and PMDA certification scarcity constraining qualified supplier pools. Five-to-ten-year viability favors operators with backward integration into captive corn processing and renewable power assets. Watch for CDSCO approval timeline compression as inflection signal for domestic Indian capacity monetization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | Captive feedstock supply insulates Shandong fermenters from North China Plain price volatility. |
| Pharmacopeial Certification Investment | NMPA multi-stage chromatographic upgrades qualify suppliers for hospital procurement tenders. |
| Modular Continuous Fermentation Deployment | Skid-mounted systems in Jiangsu enable distributed 10,000-tonne facilities with mega-scale unit costs. |
| Direct Procurement Contract Negotiation | Annual lysine agreements with Vietnamese poultry integrators displace traditional distributor margins. |
| Liquid Lysine Formulation Capability | Precision dosing systems in Thai automated feed mills reduce labor costs and improve ration conversion. |
Study Parameters
Multi-period observation of fermentation capacity utilization rates, corn futures spreads, and pharmacopeial approval timelines anchored the trend analysis, supplemented by interviews with plant managers at Shandong and Jiangsu facilities, regulatory affairs leads navigating NMPA and CDSCO pathways, procurement directors at Vietnamese integrated livestock groups, and technical R&D directors developing continuous fermentation platforms. Secondary validation drew from customs and trade data tracking lysine and glutamate flows, China National Grain and Oils Information Center corn market reports, SEC 10-K filings of listed fermentation operators, and PMDA GMP certification registries. Bottom-up facility capacity aggregation and top-down end-use demand estimation were triangulated against reported production volumes.
Segment-weighting approaches modeled amino acid markets across product type, end-use industry, physical form, and distribution channel dimensions. Purity grade stratification and regional regulatory cluster differentiation shaped volume and value allocation throughout the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical capacity expansion patterns and livestock operation intensification trajectories. Forecast inputs incorporated PLI scheme capital deployment schedules in India and dual carbon goals facility upgrade timelines in China.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to corn price volatility, CDSCO approval cycle extensions, and environmental enforcement intensity in the North China Plain. Forecasts reflect documented assumptions regarding feedstock availability, regulatory harmonization velocity, and livestock feed commercialization penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Potassium Methylate Market
Functional Chemicals
Global Tert-Amylbenzene Market
Functional Chemicals
Succinimide Market
Functional Chemicals
Global Peptide Synthesis Market
Functional Chemicals
Glutaraldehyde Market
Functional Chemicals
Thymolphthalein Market
Functional Chemicals
Amino Acid Chelates Market
Functional Chemicals
Phthalimide Market
Functional Chemicals
US Potassium Methylate Market
Functional Chemicals
Sodium Lauroyl Glutamate Market
Functional Chemicals
L-Cysteine Market
Functional Chemicals
Global Sodium Lignosulfonate Market
Functional Chemicals
Global Functional Fluids Market
Functional Chemicals
Jellyfish-Derived Peptide Ingredient Concepts Market
Functional Chemicals
Adipamide Market