
 Sodium Hypophosphite Market | 2026-2036
Sodium Hypophosphite Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Hypophosphite Market Outlook
Electronics buyers are unwinding reliance on traditional metal-finishing suppliers in favor of specialty chemical vendors with electroless plating expertise. Hubei Xingfa Chemicals Group Co., Ltd. leverages captive phosphorus rock access to anchor feedstock costs. Solvay differentiates through pharmaceutical-grade certification and European regulatory alignment. Nippon Chemical Industrial Co., Ltd. sustains position in high-purity crystal production for semiconductor applications.
Sodium hypophosphite is an inorganic salt with the formula NaPO₂H₂, typically produced via neutralization of hypophosphorous acid with sodium carbonate or hydroxide, and functions primarily as a reducing agent in electroless nickel plating and as an intermediate in organophosphorus synthesis. The powder form dominates volume shipments due to stability in bulk storage and compatibility with standard dissolution systems, while liquid formulations are gaining traction in automated plating lines where dosing precision reduces waste. Electroless plating applications command the largest value share, though pharmaceutical-grade material carries the widest margin pool due to stringent impurity limits.
EPA oversight of nickel plating effluents in the United States and REACH chemical registration requirements in Europe constrain formulation choices and push suppliers toward higher-purity grades. China's MEE enforces wastewater discharge standards that directly affect hypophosphite consumption rates in plating baths. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments in one geography may not transfer to another, reshaping sourcing decisions without warning.
Market Dynamics
Electronics-grade purity requirements are compressing supplier margins while concentrating procurement among electroless plating specialists with captive acid neutralization capabilities and integrated phosphorus sourcing.
Growth Catalysts
- Electroless nickel plating in semiconductor packaging:Advanced substrate manufacturing demands phosphorus-rich reducing agents for uniform metal deposition on complex geometries. Taiwan and South Korea fabs are expanding plating line capacity.
- REACH compliance deadlines:European chemical registration requirements are filtering out low-purity imports, creating procurement windows for certified suppliers with ECHA-registered dossiers and analytical traceability.
- Phosphorus chemical clustering:Integrated production hubs in Hubei and Guizhou provinces combine phosphate rock mining, acid production, and salt crystallization under single-site control, compressing logistics costs for export-grade material.
Market Restraints
- Phosphate rock cost volatility:Feedstock prices swing with Moroccan and Chinese export quotas, squeezing margin predictability for non-integrated producers lacking captive mine access.
- Substitution by dimethylamine borane:This alternative reducing agent offers lower phosphorus effluent loads in some plating applications, threatening volume retention in environmental compliance-sensitive installations.
- EPA effluent concentration limits:United States wastewater discharge rules for total phosphorus are forcing plating shops to reduce bath concentrations or install recovery systems, directly depressing per-site hypophosphite consumption rates.
Strategic Opportunities
- Pharmaceutical intermediate synthesis:Organophosphorus drug manufacturing requires GMP-certified material with heavy metal specifications below electroless grades, opening margin expansion for certified producers.
- Indian electronics manufacturing incentives:PLI scheme subsidies for semiconductor and component production are attracting plating line investments in Gujarat and Tamil Nadu, creating new demand nodes outside established East Asian supply chains.
- Closed-loop plating bath regeneration:On-site hypophosphite recovery systems align with China's MEE circular economy mandates while locking in chemical service contracts for equipment-integrated suppliers.
Industry Challenges
- Analytical chemist scarcity:ICP-MS trace metal analysis and crystallization kinetics expertise are concentrated among retiring specialists, constraining quality control scaling for emerging producers.
- Multi-jurisdiction registration timelines:Separate REACH, EPA TSCA, and NMPA new chemical notifications require 18-36 month parallel track submissions, delaying market entry for reformulated grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Hypophosphite Market |
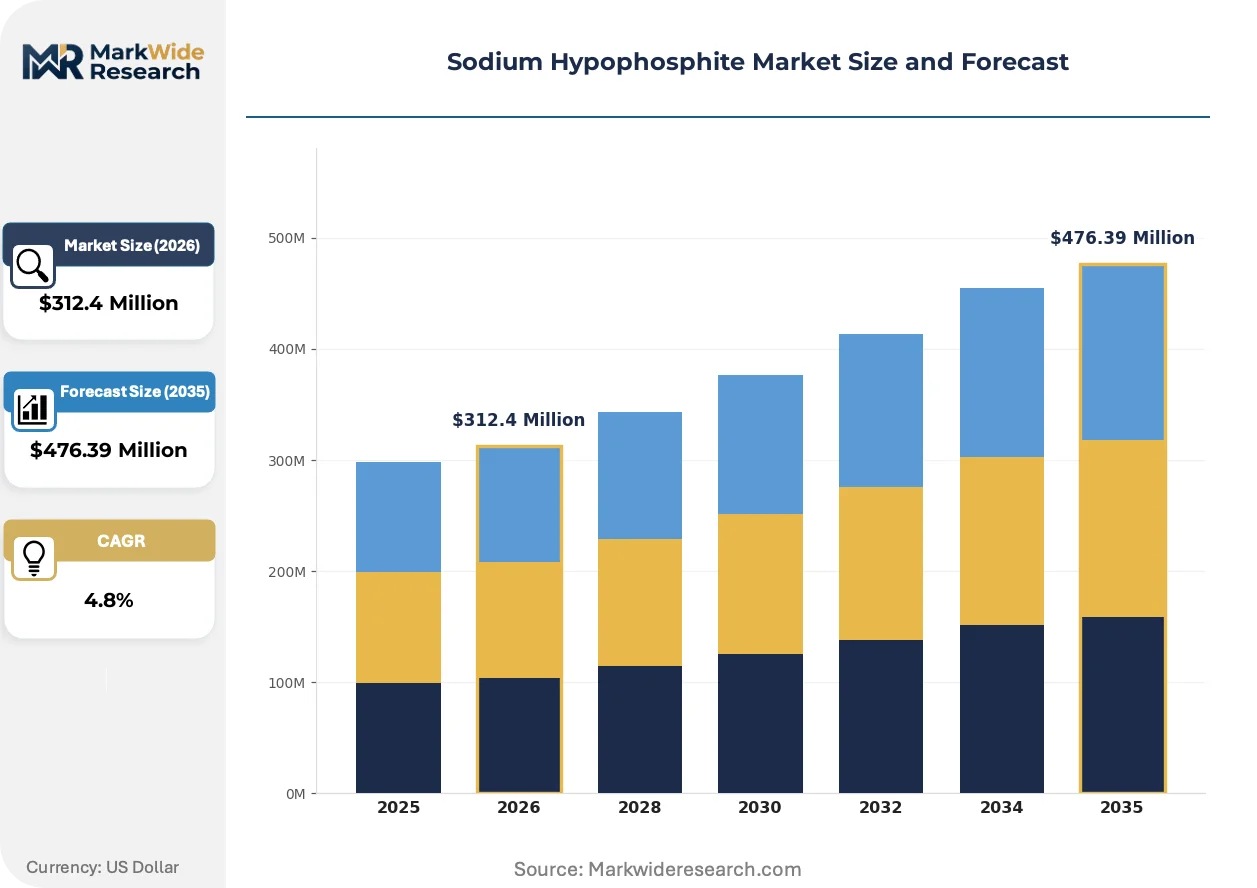
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Crystals Application: Electroless Plating, Water Treatment, Pharmaceuticals, Agriculture End User: Chemicals Industry, Electronics, Textile, Food Processing Packaging Type: Drums, Bags, Bulk Containers, Bottles |
| Companies Covered | Hubei Xingfa Chemicals Group Co., Ltd., Solvay, Changshu New-Tech Chemicals Co., Ltd., Arkema, Nippon Chemical Industrial Co., Ltd., Jiangxi Fuerxin Pharmaceutical & Chemical Co., Ltd., Jiangsu Kangxiang Industrial Group Co., Ltd., Sigma-Aldrich, Hubei Sky Lake Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Hypophosphite Market Strategic Shifts
Process intensification and regulatory digitization are compressing batch cycle times while fragmenting procurement authority between centralized chemical management and site-level plating engineers.
Continuous crystallization technology is miniaturizing production footprints for high-purity sodium hypophosphite. European specialty chemical firms are piloting modular units that slash solvent use and temperature cycling. This equipment shift is enabling distributed production closer to electroless plating clusters, reducing cross-border bulk shipment volumes.
China's GB standards for electronic chemicals are tightening impurity specifications for sodium, calcium, and sulfate ions. MIIT certification requirements now mandate third-party testing at designated laboratories in Beijing or Shanghai. Semiconductor-grade material faces the steepest compliance burden, with suppliers maintaining dual analytical protocols for domestic and export qualification.
Consolidated chemical management contracts are displacing spot purchasing at multi-site plating operations. Large EMS providers in Mexico and Eastern Europe are centralizing reducing agent procurement through single-source agreements with inventory guarantees. This purchasing concentration favors suppliers with regional warehousing networks and VMI capabilities over commodity traders.
Sodium Hypophosphite Market Segmentation
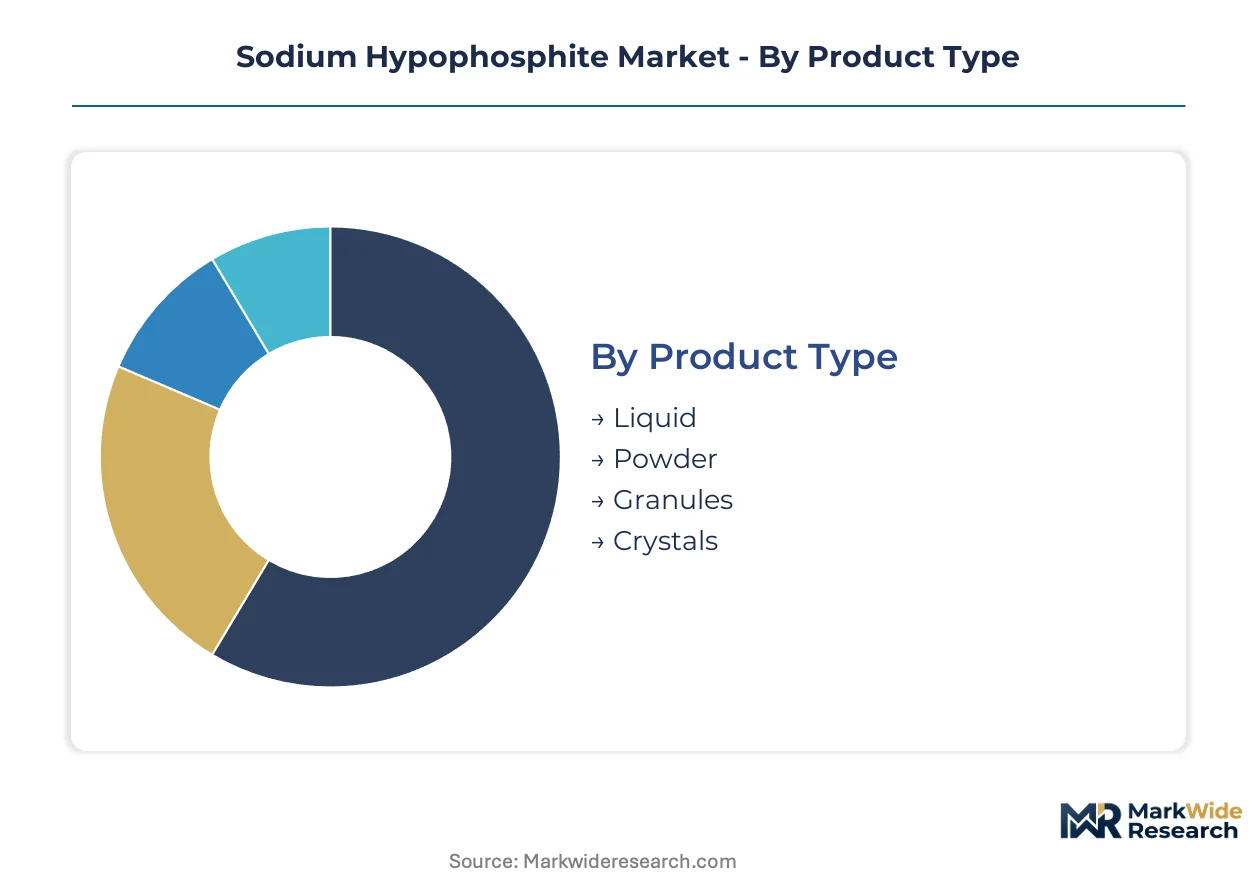
Sodium hypophosphite procurement splits across channel archetypes: bulk powder moves through integrated phosphorus chemical distributors, liquid formulations flow via plating chemical service contracts, and pharmaceutical-grade material channels through GMP-certified intermediaries with batch traceability. Understanding these pathways exposes margin concentration and sourcing leverage points.
Product Type:
Channel mix varies sharply by physical form: powder dominates spot-market commodity flows through chemical traders, liquid concentrates ship direct-to-fab under toll-manufacturing agreements, while crystals and granules move through specialty distributors serving quality-sensitive end-uses.
- Powder:Spray-dried crystalline solid with 99%+ purity specifications dominates bulk storage economics. Demand concentrates in China's Yangtze River Delta plating clusters where Hubei-origin material feeds electroless nickel lines. EPA effluent limits in the United States are compressing bath concentrations, indirectly reducing per-site powder offtake volumes.
- Liquid:Aqueous solutions at 30-50% concentration enable automated dosing systems in semiconductor packaging facilities. Taiwan and South Korea fabs are expanding procurement of pre-mixed formulations to reduce on-site dissolution labor and contamination risk. By volume, powder leads. By growth pace, liquid is expanding most quickly.
- Granules:Free-flowing agglomerated form reduces dust exposure in manual handling operations. Food processing applications in the European Union favor this format for controlled dissolution in antioxidant formulations.
- Crystals:Large-format monoclinic structures serve analytical reagent and laboratory synthesis markets. Japanese pharmaceutical intermediaries specify this grade for organophosphorus drug precursor manufacturing.
By volume, powder leads. By growth pace, liquid is expanding most quickly.
Application:
Cost tier stratification separates commodity plating chemicals from certified pharmaceutical intermediates, with water treatment applications occupying a mid-tier price band constrained by municipal procurement rules.
- Electroless Plating:Reducing agent for nickel-phosphorus deposition on printed circuit boards and semiconductor substrates. Taiwan Semiconductor Manufacturing Company expansion in Kaohsiung and Samsung's Pyeongtaek complex are driving specification tightening for phosphorus-rich baths. REACH registration requirements filter out uncertified suppliers from European automotive electronics supply chains.
- Pharmaceuticals:Intermediate for organophosphorus active pharmaceutical ingredients requiring heavy metal limits below 10 ppm. Solvay and Nippon Chemical Industrial Co. maintain GMP-certified production lines with dedicated analytical protocols. India's PLI scheme for bulk drug manufacturing is attracting investment in hypophosphite-to-intermediate conversion capacity.
- Water Treatment:Corrosion inhibitor and scale control agent in industrial cooling systems. China's MEE wastewater discharge standards limit phosphorus loading, constraining application growth in coastal manufacturing zones.
- Agriculture:Fungicide component and plant nutrient supplement in specialty crop protection. Brazilian ANVISA registration timelines delay market entry for new formulated products.
Electroless plating commands the largest revenue pool. Pharmaceuticals deliver the steepest margin expansion trajectory.
End User:
Customer type determines contract structure: electronics manufacturers demand VMI inventory guarantees, chemical processors negotiate formula pricing tied to phosphorus rock indices, and food processors require audit-ready documentation chains.
- Chemicals Industry:Organophosphorus synthesis and specialty reducing agent applications. German fine chemical houses source through Rotterdam bulk terminals with REACH-compliant documentation.
- Electronics:Semiconductor packaging and PCB manufacturing. Foxconn and Jabil facilities in Mexico centralize procurement through single-source chemical management contracts.
- Textile:Flame retardant finishing and dye reduction processes. Gujarat dyeing clusters in India represent emerging demand nodes outside established East Asian supply chains.
- Food Processing:Antioxidant additive with EFSA-approved usage limits. Japanese food chemical distributors maintain dedicated warehousing for additive-grade material.
Electronics buyers are consolidating supplier relationships fastest. Chemical industry procurement retains the most price sensitivity.
Packaging Type:
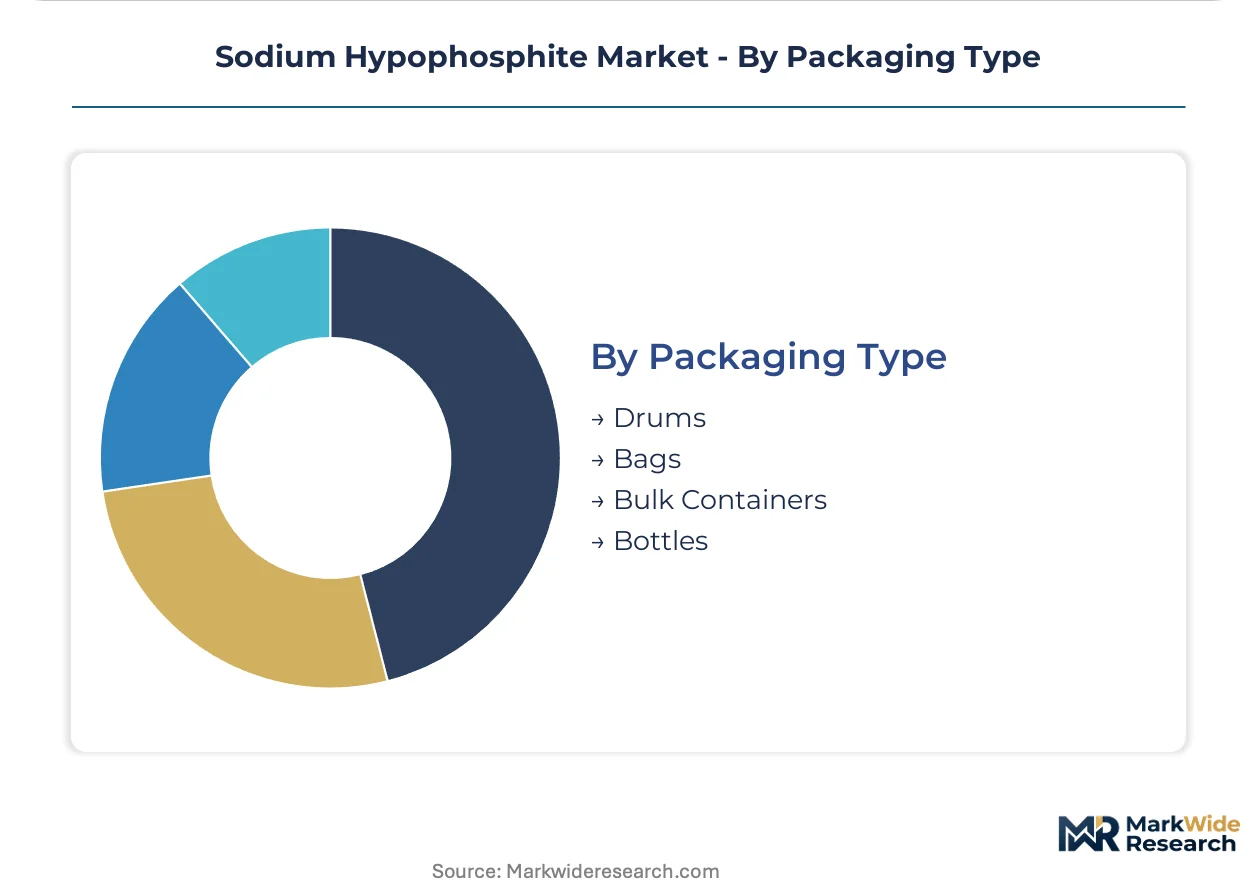
Volume scale and handling automation dictate packaging selection: bulk containers serve continuous-process plating lines, drums accommodate mid-scale chemical synthesis, and bottles reach laboratory and food-grade applications.
- Drums:200-liter steel or plastic containers for electroless plating bath preparation. Mexican EMS providers favor this format for line-side storage flexibility.
- Bags:25-50 kg multi-wall paper or woven polypropylene for powder shipments. Hubei Xingfa Chemicals Group Co. exports primarily in bag format through Shanghai port consolidation.
- Bulk Containers:Flexible intermediate bulk containers and ISO tanks for large-volume chemical processors. European specialty chemical firms are piloting returnable bulk systems to reduce packaging waste under EU Green Deal circular economy mandates.
- Bottles:Laboratory and reagent-grade packaging with tamper-evident seals. Pharmaceutical intermediate manufacturers specify amber glass for light-sensitive material.
Bulk containers move the highest tonnage. Bottle-format revenue per kilogram exceeds all other packaging categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China-to-Taiwan trade corridors dominate sodium hypophosphite flows, with Hubei-origin material feeding semiconductor plating clusters across the Taiwan Strait. European automotive electronics demand pulls certified grades through Rotterdam bulk terminals. Indian electronics manufacturing incentives are redirecting procurement patterns toward Gujarat and Tamil Nadu.
China
Yangtze River Delta plating facilities consume electroless-grade powder from Hubei phosphorus chemical clusters. MEE wastewater discharge standards enforce phosphorus loading limits that compress bath concentrations. Guizhou and Hubei provinces integrate phosphate rock mining with acid neutralization under single-site control.
Taiwan
TSMC expansion in Kaohsiung drives specification tightening for phosphorus-rich reducing agents in advanced substrate manufacturing. The island's semiconductor fabs source primarily through cross-strait chemical distributors with MIIT-certified documentation. Tainan Science Park plating lines are expanding capacity for chip packaging applications.
South Korea
Samsung's Pyeongtaek complex and SK Hynix facilities anchor electroless nickel demand for memory chip packaging. MFDS chemical registration requirements filter imported material through designated analytical protocols. Gyeonggi Province electronics clusters concentrate procurement among electroless plating specialists with VMI capabilities.
Germany
Automotive electronics supply chains in Bavaria and Baden-Württemberg demand REACH-registered material with ECHA dossier traceability. German fine chemical houses source through Rotterdam bulk terminals for organophosphorus synthesis. BASF Ludwigshafen and surrounding chemical parks maintain dedicated reducing agent inventories.
United States
EPA effluent concentration limits for total phosphorus force plating shops to reduce bath concentrations or install recovery systems. Foxconn and Jabil facilities in Mexico centralize procurement through single-source chemical management contracts. Texas and Arizona semiconductor investments are attracting plating line co-location.
Sodium Hypophosphite Market Competitive Environment
Player mix skews toward integrated phosphorus chemical producers with captive feedstock access and specialty distributors serving certified-grade segments. Market structure concentrates around three archetypes: upstream-integrated miners with acid neutralization capabilities, European regulatory-aligned specialists with pharmaceutical-grade certification, and regional electroless plating chemical service providers with VMI contracts. Dominant competitive moves include backward integration into phosphate rock mining and geographic expansion toward emerging electronics manufacturing clusters.
Within the integrated-producer tier, Hubei Xingfa Chemicals Group Co., Ltd. exemplifies upstream control over phosphorus rock access. Solvay occupies a position representing European regulatory alignment and pharmaceutical-grade certification. Nippon Chemical Industrial Co., Ltd. anchors the high-purity crystal production archetype for semiconductor applications. These three entities collectively illustrate how feedstock security, regulatory certification, and purity specialization define competitive positioning.
| Leading Market Players |
|---|
| Hubei Xingfa Chemicals Group Co., Ltd. |
| Solvay |
| Changshu New-Tech Chemicals Co., Ltd. |
| Arkema |
| Nippon Chemical Industrial Co., Ltd. |
| Jiangxi Fuerxin Pharmaceutical & Chemical Co., Ltd. |
| Jiangsu Kangxiang Industrial Group Co., Ltd. |
| Sigma-Aldrich |
| Hubei Sky Lake Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Hubei phosphorus chemical clusters anchors cost floors for electroless-grade material, compressing margin headroom for non-integrated producers while amplifying pricing power among mine-anchored suppliers. This scale concentration forces spot-market buyers toward long-term offtake contracts or toll-manufacturing arrangements that lock in volume commitments against feedstock volatility.
Pricing Analysis
Current-generation semiconductor-grade specifications command substantial premiums over prior-generation plating-grade material, while next-generation pharmaceutical-intermediate purity thresholds are widening the certification-price gap further. Three-tier pricing structure across premium, standard, and economy levels stratifies by heavy metal limits and analytical traceability, with GMP-certified material carrying the widest margin pool. Cost compression in standard electroless grades is intensifying because EPA effluent limits force bath concentration reductions, eroding per-site consumption rates. Chemical processors show the highest price sensitivity due to formula pricing tied to phosphate rock indices, while semiconductor fabs accept premium tiers for supply security.
Supply Chain Analysis
Strategic stockpiling dominates procurement behavior among Taiwan and South Korea semiconductor fabs, contrasting with just-in-timed powder shipments to China's Yangtze River Delta plating clusters. Supply concentrates in China, Taiwan, and Germany, with Hubei-origin material feeding cross-strait chemical distributors and Rotterdam bulk terminals serving European automotive electronics chains. Raw material flows draw from Moroccan and Chinese phosphate rock deposits, hypophosphorous acid neutralization capacity, and crystallization-grade sodium carbonate. Single-source vulnerability runs through integrated phosphorus chemical clusters in Hubei and Guizhou provinces. Distribution runs through specialty chemical distributors with REACH dossier capabilities and electroless plating service contracts with VMI guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronics manufacturer procurement consolidation through single-source chemical management contracts has shifted bargaining power toward large EMS providers, fragmenting supplier relationships and compressing margin pools for undifferentiated grades.
For Market Incumbents: Fortify captive phosphorus rock access through backward integration or long-term mining concessions, as Moroccan export quota volatility threatens feedstock security for non-integrated producers. Deepen certification investments in pharmaceutical-grade production lines to escape commodity pricing pressure from dimethylamine borane substitution in environmental compliance-sensitive installations. Prioritize VMI contract expansion in Mexico and Eastern Europe where Foxconn and Jabil facilities are centralizing reducing agent procurement. For New Entrants and Emerging Players: Analytical chemist scarcity among retiring specialists creates white-space opportunity for quality-control-as-a-service offerings targeting emerging producers in India's Gujarat plating clusters. Target pharmaceutical intermediate synthesis for organophosphorus drug manufacturing, where GMP certification barriers filter out commodity suppliers and margin expansion potential exceeds electroless plating tiers. Enter through toll-manufacturing partnerships with established distributors lacking crystallization expertise. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors upstream-integrated specialists with captive acid neutralization capabilities and ECHA-registered dossiers. Long-term viability hinges on phosphorus chemical clustering economics and regulatory alignment across REACH, EPA TSCA, and China's MIIT frameworks. Acquisition targets should demonstrate dual analytical protocols for domestic and export qualification. The signal to watch is TSMC and Samsung plating line expansion announcements, which precede specification tightening and certified-grade demand inflections.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | Hubei Xingfa Chemicals Group Co. anchors feedstock costs against Moroccan export quota volatility. |
| Pharmaceutical-Grade Certification Investment | Solvay maintains GMP-certified production lines with heavy metal specifications below 10 ppm for organophosphorus APIs. |
| Closed-Loop Plating Bath Regeneration Systems | Equipment-integrated suppliers lock in chemical service contracts under China's MEE circular economy mandates. |
| Regional Warehousing Network Expansion | Specialty distributors with VMI capabilities displace commodity traders in Mexico and Eastern Europe EMS procurement. |
| Continuous Crystallization Technology Piloting | European specialty chemical firms slash solvent use while enabling distributed production near electroless plating clusters. |
Study Parameters
Initial hypotheses were tested against primary input from electroless plating line engineers, phosphorus chemical procurement leads, pharmaceutical intermediate manufacturers, and specialty chemical distribution channel partners and refined through secondary validation. Primary fieldwork combined structured interviews with plant managers at Yangtze River Delta facilities, regulatory affairs specialists navigating REACH and EPA TSCA frameworks, and technical R&D directors at integrated phosphorus chemical producers. Secondary sources included customs and trade flow databases, SEC 10-K filings from listed chemical producers, ECHA registration dossiers, and MIIT certification records. Bottom-up volume estimates from plating line capacity expansions were triangulated against top-down phosphorus chemical consumption models.
Variance decomposition across grade tier, end-use industry, packaging format, and regional production hub dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate aggregation weighted by revenue contribution. Forecast inputs incorporated semiconductor fab expansion timelines from TSMC and Samsung, EPA effluent limit enforcement trajectories, and PLI scheme subsidy disbursement patterns for Indian electronics manufacturing.
Forecasts assume regulatory continuity in REACH, EPA, and China's MEE frameworks; material policy shifts would require re-modeling phosphorus loading limits or chemical registration timelines. Forecasts reflect assumptions about phosphate rock export quota stability, electroless nickel substitution rates, and analytical chemist labor market tightness. Revision becomes warranted when dimethylamine borane penetration in plating applications crosses thresholds that structurally depress hypophosphite consumption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
Diisopropylbenzene Market
Bulk Chemicals
Clomiphene Citrate Market
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market
Bulk Chemicals
Lithium Nitrate Market
Bulk Chemicals
Magnesium Chloride Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
Mangiferin Market
Bulk Chemicals
Global Crude Sulfate Turpentine Market
Bulk Chemicals
Global Basic Chemicals Market
Bulk Chemicals
Acetate Salt Market
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
Precipitated Calcium Carbonate Market