
 Bemotrizinol Market | 2026-2036
Bemotrizinol Market Size, Share, and Industry Trends Forecast 2026-2036
Bemotrizinol Market Analytics
Chinese specialty chemical producers is realigning capacity toward pharmaceutical-grade UV filter output. BASF SE leverages integrated aromatics chains to sustain European supply continuity for high-specification bemotrizinol. Xingrui Industry anchors export volumes through cost-optimized intermediates synthesis. Shiva Pharmachem competes on custom manufacturing flexibility for mid-tier personal care brands.
Bemotrizinol is a benzotriazole-derived organic UV-A and UV-B filter with peak absorption near 310 nm, synthesized through diazotization and cyclization of substituted anilines, primarily incorporated into topical photoprotection formulations. Sunscreen applications dominate volume absorption due to regulatory pressure on broad-spectrum protection claims across North America and Europe. Liquid formulations capture expanding share in mass-market spray products, while cream and lotion segments retain margin concentration in dermatologist-recommended premium lines. The distribution channel structure tilts toward pharmacies in regulated markets where SPF certification drives professional recommendation, whereas online retail accelerates in Asia-Pacific consumer markets.
FDA sunscreen monograph enforcement and REACH chemical registration in Europe jointly elevate analytical testing burdens on importers. China's NMPA and GB standards for cosmetics raw materials impose parallel toxicity documentation requirements that filter out non-compliant traders. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
REACH chemical registration in Europe and FDA sunscreen monograph updates in the United States are tightening purity benchmarks and reshaping supplier qualification requirements for UV filter manufacturers.
Growth Catalysts
- Broad-spectrum protection mandates:FDA and ECHA regulatory pressure on SPF certification drives formulators toward benzotriazole-derived filters with dual UV-A and UV-B absorption profiles.
- Spray sunscreen proliferation:Liquid bemotrizinol formulations capture expanding share in mass-market aerosol products, displacing powder-based alternatives in convenience-oriented segments.
- Southeast Asian cosmetics manufacturing:Chinese chemical producers scale export volumes to Thailand, Indonesia, and Vietnam, where domestic personal care brands accelerate UV filter procurement.
Market Restraints
- Substituted aniline feedstock volatility:Diazotization precursor costs fluctuate with aromatic petrochemical pricing, compressing margin predictability for cyclization-dependent synthesis routes.
- Regulatory documentation burdens:REACH compliance and China's GB standards impose parallel toxicity dossier requirements that filter out non-compliant traders and elevate analytical testing overhead.
- Photostability limitations:Benzotriazole derivatives require stabilization co-formulants in high-SPF products, adding complexity to minimalist formulation trends.
Strategic Opportunities
- Pharmaceutical-grade certification:Chinese specialty chemical producers realign capacity toward higher-purity output, capturing premium positioning in dermatologist-recommended lines.
- Online retail channel expansion:Direct-to-consumer sunscreen sales accelerate in Asia-Pacific consumer markets, bypassing traditional pharmacy distribution bottlenecks.
- Green chemistry incentives:EU Green Deal funding streams favor bio-based synthesis pathway development, creating first-mover advantage for enzymatic cyclization research.
Industry Challenges
- Analytical chemistry talent scarcity:Regulatory divergence between FDA, ECHA, and NMPA documentation requirements demands specialized toxicology expertise that mid-tier suppliers struggle to retain.
- Reformulation timeline compression:Accelerated monograph update cycles force personal care brands to requalify supplier bases within shortened windows, disrupting procurement continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bemotrizinol Market |
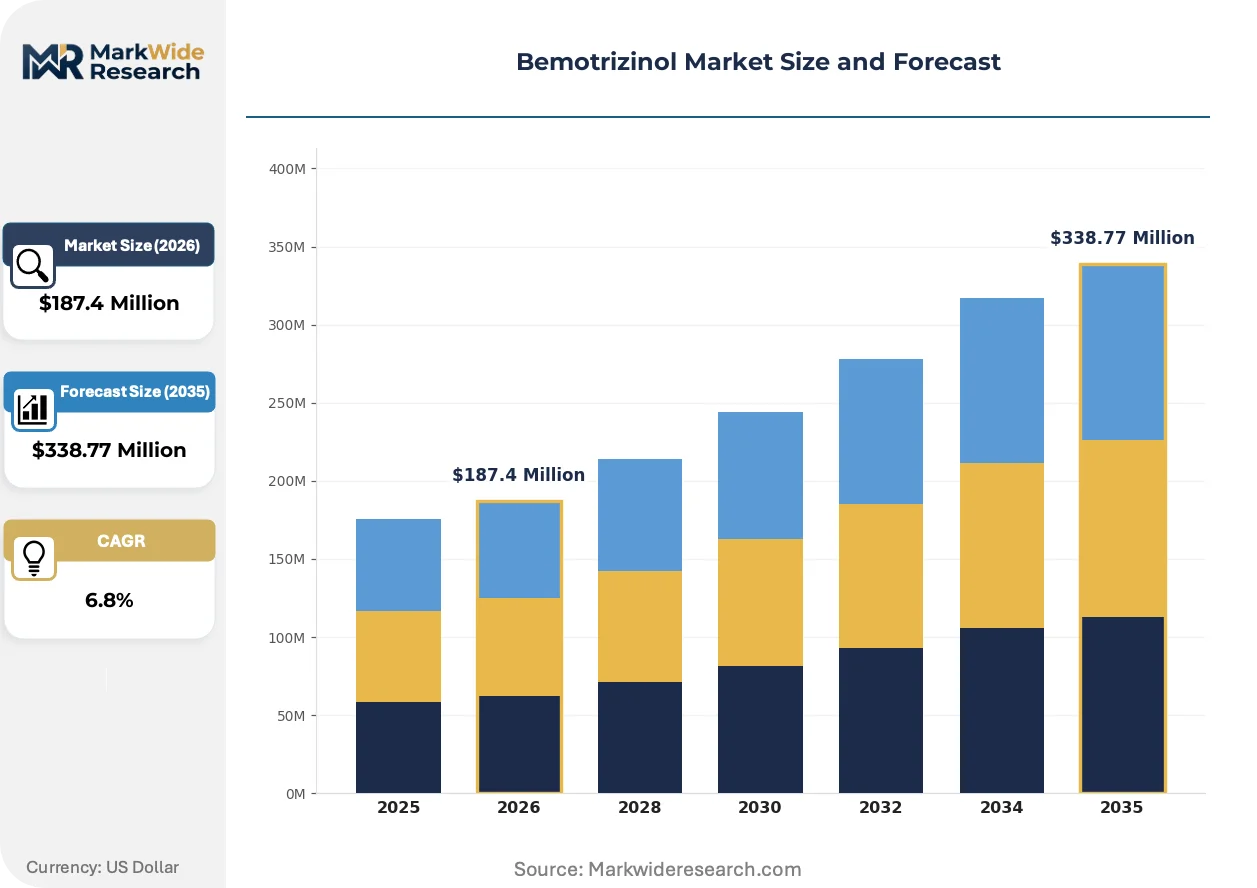
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Personal Care, Pharmaceutical, Cosmetics, Sunscreen Form: Liquid, Cream, Gel, Lotion End User: Consumers, Dermatologists, Estheticians, Manufacturers Distribution Channel: Online Retail, Pharmacies, Beauty Stores, Supermarkets |
| Companies Covered | Ciba Specialty Chemicals, Xingrui Industry, Coskin Specialities, Anhui Keynovo Biotech, Hainan Zhongxin Chemical, MFCI, Shiva Pharmachem, BASF SE, Biosynth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bemotrizinol Market Evolving Landscape
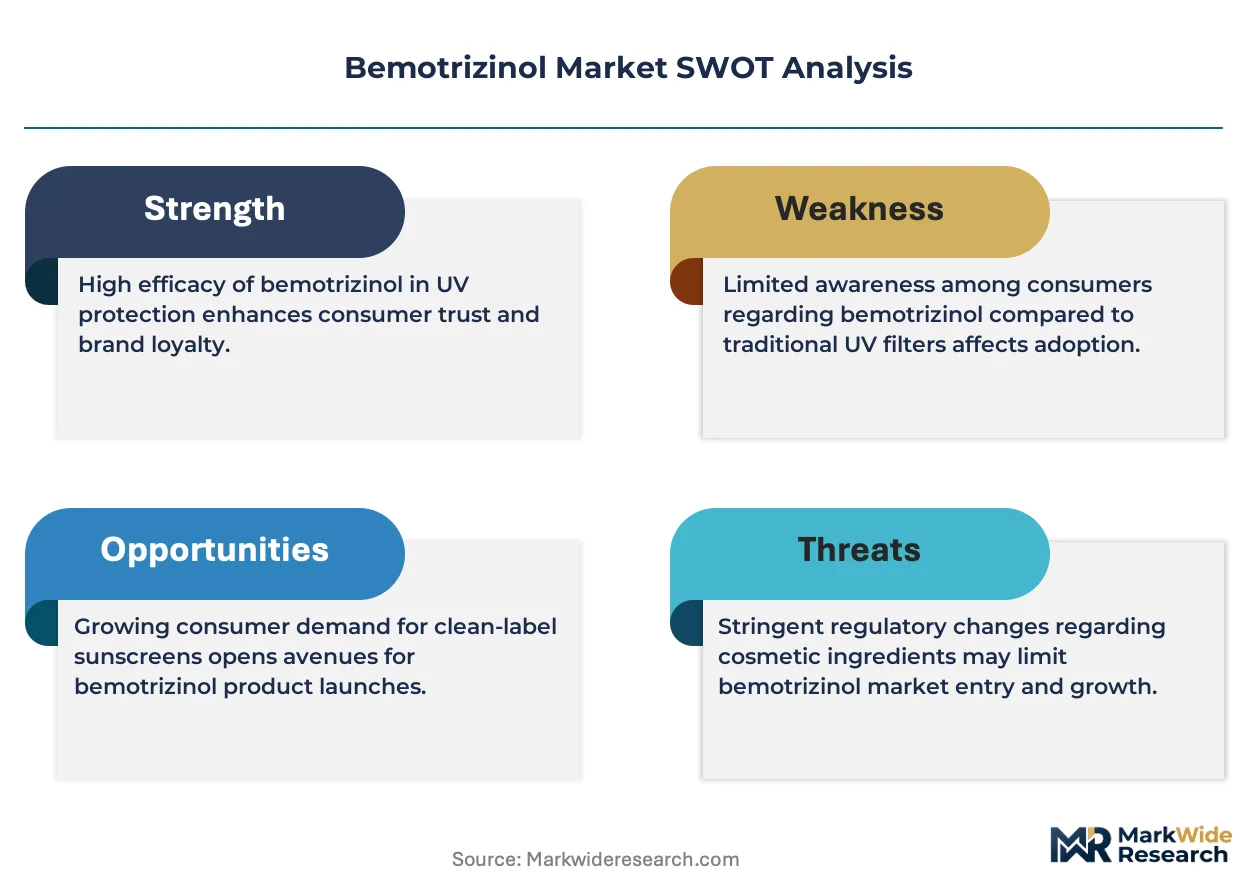
Formulation science and regulatory compliance frameworks are actively reshaping competitive positioning in UV filter supply, with technology convergence and channel evolution creating new value capture mechanisms.
Encapsulated bemotrizinol delivery systems are expanding into premium sunscreen lines, enabling photostability enhancement without heavy stabilizer loads. Dermatologist-recommended brands in Germany and France adopt these microsphere technologies fastest, compressing the performance gap between mass-market and clinical-positioned products. The technology is expanding into color cosmetics with SPF claims, where filter migration and aesthetic finish constraints previously limited benzotriazole adoption.
REACH authorization list expansion and candidate substance screening are elevating substitution pressure on legacy UV filters with higher hazard profiles. ECHA's systematic review of endocrine-disrupting properties in organic sunscreens redirects formulator R&D budgets toward benzotriazole alternatives with cleaner toxicological dossiers. European personal care manufacturers respond by accelerating supplier audits and dual-sourcing strategies for compliant bemotrizinol grades.
Direct ingredient sourcing by mid-tier personal care brands is compressing traditional distributor margins in Asia-Pacific markets. Chinese domestic cosmetics producers now procure bemotrizinol directly from specialty chemical manufacturers via digital procurement platforms, bypassing regional trading houses that previously controlled price discovery. This pattern concentrates most visibly in Shanghai and Guangzhou, where formulation houses build captive supplier relationships to secure volume commitments amid raw material allocation volatility.
Bemotrizinol Market Segmentation
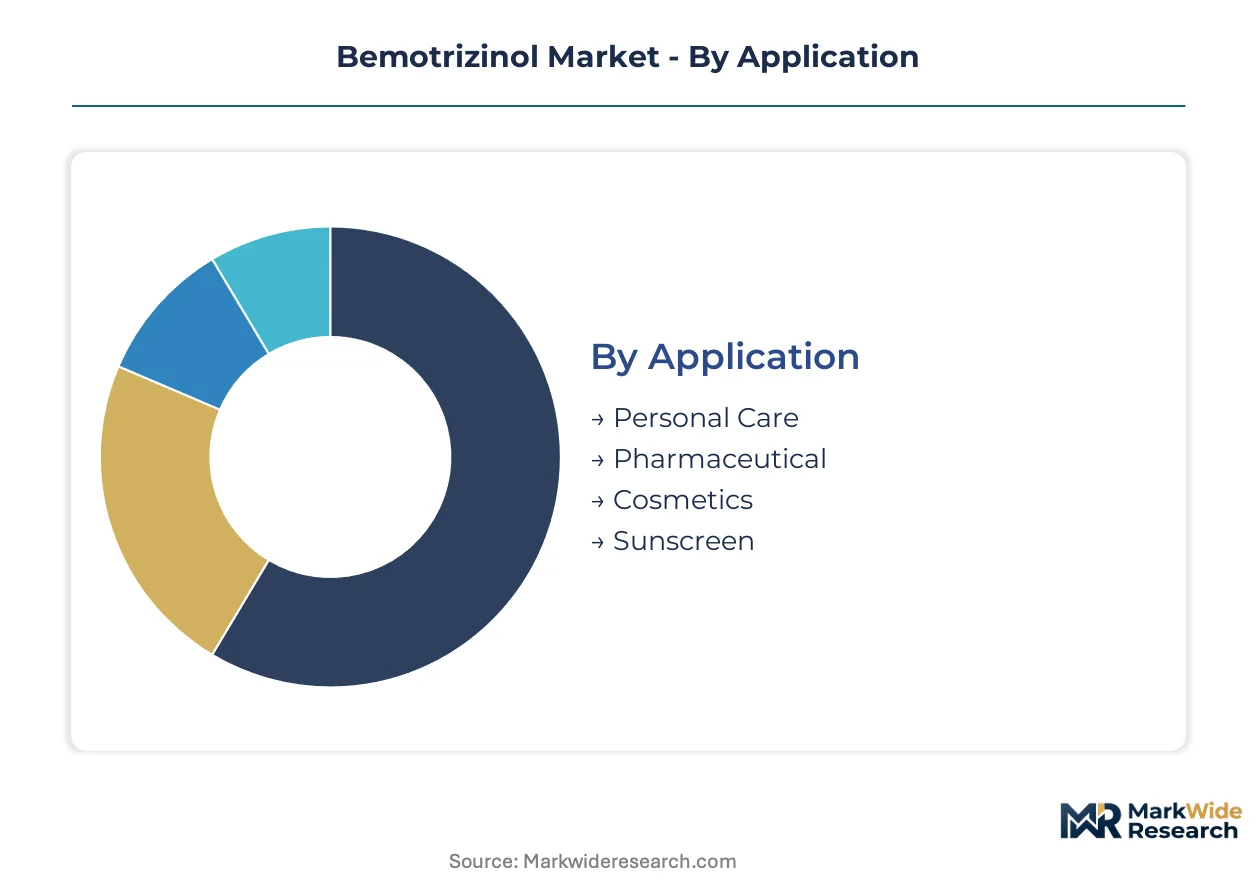
Segmentation in the bemotrizinol market reveals distinct procurement patterns across formulation types and professional versus consumer channels. Each dimension carries regulatory and margin implications that reshape supplier engagement models.
Application:
Integration depth varies sharply across these segments, with pharmaceutical and dermatological applications demanding standalone purity certification while mass-market formulations embed bemotrizinol as a commodity input.
- Sunscreen:Peak absorption at 310 nm enables broad-spectrum SPF claims that FDA and ECHA mandates now require. Volume concentrates in spray formulations for North American mass-market brands, where photostability co-formulants add formulation complexity.
- Personal Care:Daily moisturizers and anti-aging serums incorporate lower bemotrizinol loadings for incidental UV exposure protection. Demand clusters in Southeast Asian markets where humid climates accelerate photodamage awareness among urban consumers.
- Cosmetics:Color cosmetics with SPF claims utilize encapsulated delivery systems to prevent filter migration and maintain aesthetic finish. Korean and Japanese beauty brands lead adoption of microsphere technologies for BB creams and foundations.
- Pharmaceutical:Post-procedure and photosensitivity disorder treatments require pharmaceutical-grade certification with enhanced purity documentation. European dermatology clinics drive procurement through pharmacy-exclusive distribution channels.
Volume placements concentrate in Sunscreen; the faster expansion belongs to Cosmetics.
Form:
Cost tier differentiation separates premium dermatologist-recommended formats from economy mass-market vehicles, with manufacturing complexity and stabilizer requirements driving margin stratification.
- Liquid:Aerosol-compatible solutions capture expanding share in convenience-oriented spray sunscreens. Chinese chemical producers scale liquid output for export to Thai and Indonesian contract manufacturers serving private-label brands.
- Lotion:Emulsion-based vehicles retain margin concentration in premium lines recommended by German and French dermatologists. REACH-compliant stabilizer packages elevate production costs above mass-market alternatives.
- Cream:Occlusive bases suit dry-skin and winter formulations with higher bemotrizinol loading capacity. Pharmacy channels in regulated European markets favor cream presentations for professional recommendation authority.
- Gel:Water-based vehicles address oily-skin segments and tropical climate preferences where cosmetic elegance drives repeat purchase. Southeast Asian domestic brands accelerate gel formulation R&D to reduce import dependence.
Production runs heaviest for Liquid; the steepest expansion trajectory belongs to Gel.
End User:
Customer type determines specification intensity, with professional channels demanding certificate-of-analysis documentation that consumer-direct sales bypass entirely.
- Manufacturers:Personal care formulators represent the core procurement volume, with Chinese domestic producers scaling captive bemotrizinol synthesis to secure raw material allocation. NMPA and GB standards compliance filters supplier qualification to specialty chemical producers with in-house analytical capabilities.
- Consumers:Direct purchasing concentrates in Asia-Pacific online retail where ingredient transparency claims influence brand selection. Digital procurement platforms enable mid-tier brands to bypass traditional distributor markups.
- Dermatologists:Clinical recommendation drives pharmacy-channel volume for high-SPF therapeutic products. European markets require ECHA-compliant toxicological dossiers that elevate supplier documentation burdens.
- Estheticians:Professional treatment rooms incorporate bemotrizinol in post-procedure protocols and daily maintenance regimens. Training and certification requirements limit product selection to established pharmaceutical-grade suppliers.
Order volumes concentrate with Manufacturers; the fastest share gain belongs to Consumers.
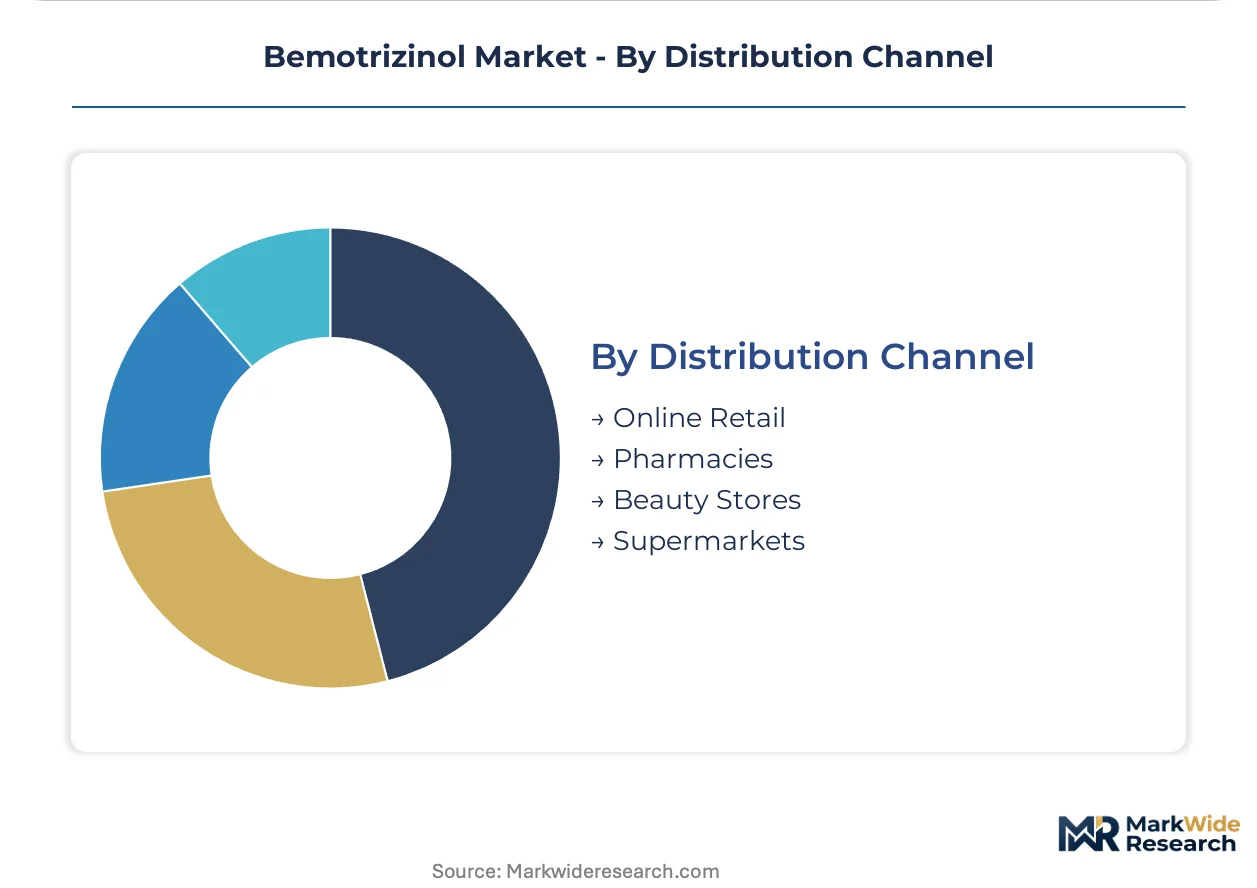
Distribution Channel:
Supply concentration patterns favor direct manufacturer relationships in digital channels while traditional retail maintains gatekeeper functions in regulated markets.
- Pharmacies:SPF certification requirements and professional recommendation authority sustain pharmacy dominance in European and North American regulated markets. FDA sunscreen monograph enforcement elevates analytical testing burdens that pharmacy chains pass to qualified suppliers.
- Online Retail:Direct-to-consumer platforms accelerate in China, South Korea, and Southeast Asia where mobile commerce penetration outpaces brick-and-mortar expansion. Domestic cosmetics producers in Shanghai and Guangzhou build captive supplier relationships through digital procurement.
- Beauty Stores:Specialty retailers curate premium and clean-beauty positioned sunscreens with enhanced ingredient storytelling. Encapsulated bemotrizinol technologies gain visibility through in-store education and sampling programs.
- Supermarkets:Mass-market volume placement for economy spray and lotion formats with price-competitive positioning. Private-label procurement concentrates through centralized buying offices with simplified specification requirements.
Transaction volume concentrates in Pharmacies; the channel expanding most quickly is Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Substituted aniline feedstock availability in the Yangtze River Delta anchors Chinese production scale for benzotriazole-derived UV filters. This concentration shapes procurement patterns across three continents as regional regulations diverge on purity certification.
China
Domestic chemical manufacturers in Shanghai and Guangzhou scale pharmaceutical-grade output for captive use and Southeast Asian export. NMPA and GB standards for cosmetics raw materials impose toxicity documentation requirements that filter non-compliant traders. Zhejiang and Jiangsu provinces concentrate diazotization capacity serving Thai and Indonesian contract manufacturers.
Germany
REACH authorization list expansion redirects formulator R&D budgets toward benzotriazole alternatives with cleaner toxicological dossiers. ECHA's systematic review of endocrine-disrupting properties elevates supplier audit intensity. The Rhine-Ruhr industrial corridor hosts integrated aromatics chains sustaining European supply continuity for high-specification grades.
United States
FDA sunscreen monograph enforcement drives broad-spectrum SPF certification requirements that favor dual UV-A and UV-B absorption profiles. Spray sunscreen proliferation accelerates liquid formulation procurement from domestic compounding facilities. New Jersey and Texas chemical corridors concentrate photostability co-formulant blending for mass-market aerosol products.
Japan
PMDA cosmetic safety standards and humid climate conditions accelerate gel formulation R&D for oily-skin segments. Korean and Japanese beauty brands lead microsphere technology adoption for color cosmetics with SPF claims. The Kansai region around Osaka anchors encapsulation technology development for premium sunscreen lines.
India
CDSCO import registration requirements and domestic personal care brand expansion drive UV filter procurement growth. Maharashtra and Gujarat specialty chemical producers develop cost-optimized synthesis routes for mid-tier formulators. Mumbai-based formulation houses build direct supplier relationships to bypass regional distributor markups.
Bemotrizinol Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and feedstock integration depth. The vendor base stratifies into three tiers: integrated petrochemical conglomerates with aromatics chain control, mid-scale specialty chemical producers with regional certification expertise, and trading houses consolidating fragmented import volumes. Strategic moves concentrate on pharmaceutical-grade capacity realignment and digital procurement platform development.
Within the integrated petrochemical tier, BASF SE anchors European supply continuity through backward integration into aromatics feedstocks. Xingrui Industry occupies a position among cost-optimized Chinese producers scaling export volumes to Southeast Asian cosmetics manufacturers. Shiva Pharmachem exemplifies the custom manufacturing flexibility archetype serving mid-tier personal care brands with shortened qualification timelines.
| Leading Market Players |
|---|
| Ciba Specialty Chemicals |
| Xingrui Industry |
| Coskin Specialities |
| Anhui Keynovo Biotech |
| Hainan Zhongxin Chemical |
| MFCI |
| Shiva Pharmachem |
| BASF SE |
| Biosynth |
| Others |
Value Network & Pricing Analysis
Encapsulated bemotrizinol delivery systems are compressing cost economics for premium formulations while simultaneously concentrating supply among microsphere technology licensors. This production-method transition rewards pharmaceutical-grade certification holders with pricing power while marginalizing commodity traders lacking stabilization co-formulant expertise.
Pricing Analysis
Certificate-of-analysis bundling separates qualified suppliers from unverified traders in procurement negotiations. Pricing stratifies across pharmaceutical-grade, technical-grade, and feedstock-intermediate tiers based on purity documentation and REACH compliance status. Cost compression in technical-grade segments is intensifying because Chinese producers scale diazotization capacity for Southeast Asian export. Mass-market spray formulators exhibit highest price sensitivity; dermatologist-recommended brands demonstrate lowest sensitivity due to professional recommendation authority.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang and Jiangsu province diazotization clusters serving global benzotriazole derivative output. Feedstock dependencies center on substituted aniline precursors, aromatic petrochemical streams, and cyclization catalysts. Tariff exposure on Chinese-origin UV filters entering US and European markets threatens procurement continuity for non-captive buyers. Distribution runs through direct manufacturer relationships in Asia-Pacific digital channels and pharmacy-exclusive networks in regulated European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encapsulation technology is displacing conventional bemotrizinol stabilization methods, creating transition-phase winners among microsphere R&D leaders and losers among legacy co-formulant suppliers.
For Market Incumbents: Acquire encapsulation technology IP and pilot-scale production assets to defend against Korean and Japanese beauty brands capturing premium SPF cosmetics share. Backward integration into substituted aniline feedstocks secures margin predictability amid aromatic petrochemical volatility. BASF SE's integrated aromatics chain in the Rhine-Ruhr corridor exemplifies this defensive positioning. For New Entrants and Emerging Players: Direct-to-consumer digital platforms in Southeast Asian markets offer the most penetrable route for pharmaceutical-grade bemotrizinol qualification. Target Thai and Indonesian contract manufacturers seeking dual-source security beyond Chinese supply concentration. Lead with custom synthesis flexibility and shortened documentation timelines versus established traders. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty chemical conglomerates seeking UV filter portfolio expansion. Long-term viability favors producers with simultaneous REACH, FDA, and NMPA registration capabilities across the projection horizon. Monitor ECHA candidate substance list additions as inflection indicators for substitution-driven demand surges.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Capacity Realignment | Captures premium positioning in dermatologist-recommended lines requiring enhanced purity documentation. |
| Encapsulation Technology Licensing | Enables photostability enhancement without heavy stabilizer loads in high-SPF formulations. |
| Direct Digital Procurement Platform | Bypasses traditional distributor markups for mid-tier personal care brands in Shanghai and Guangzhou. |
| Backward Integration into Aniline Feedstocks | Secures margin predictability against aromatic petrochemical price volatility in cyclization-dependent synthesis. |
| Multi-Jurisdiction Regulatory Registration | Qualifies suppliers for FDA, ECHA, and NMPA compliance across North American, European, and Chinese markets. |
Research Methodology
Trade databases, chemical industry association filings, and regulatory submission records formed the secondary backbone for this analysis. Primary interviews with specialty chemical plant managers, personal care formulator procurement leads, and pharmacy distribution channel partners validated demand-side assumptions. Bottom-up volume estimates triangulated against top-down market sizing across the analysis window.
Historical trendline analysis of UV filter procurement patterns informed projection frameworks without anchoring to specific year-over-year comparisons. Segmentation modeling incorporated application type, formulation grade tier, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves calibrated to capacity expansion announcements and import-export flow trajectories.
Inputs from customs records and producer capacity disclosures were available through the study window; gaps in private-label procurement data introduce uncertainty bands around mass-market volume estimates. Forecasts reflect assumptions about regulatory timeline adherence and feedstock price stability that ECHA candidate substance reviews or aromatic petrochemical shocks could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Security Ink Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Crystal Hard Wax Market
Specialty Chemicals
Betulinic Acid Market
Specialty Chemicals
Disodium Adenosine Triphosphate Market
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
North America Chromatography Resins Market
Specialty Chemicals
Bismaleimide Market
Specialty Chemicals
Global Molecular Weight Marker Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market
Specialty Chemicals
Fatty Acid Methyl Ester Market
Specialty Chemicals
Metominostrobin Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Tetrabromobisphenol a (TBBPA) Market