
 Toner Spray Market | 2026-2036
Toner Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Toner Spray Market Analysis
Specialty beauty retail is narrowing as e-commerce platforms and direct-to-consumer storefronts capture share from department store counters. L'Oréal leverages its multi-brand portfolio to control shelf space across mass and prestige channels. Estée Lauder anchors its premium positioning through dedicated flagship digital experiences. Shiseido competes by integrating sensorial R&D with regional formulation labs.
Toner spray denotes a liquid skincare preparation atomized into fine droplets, typically containing humectants, botanical extracts, and pH-balancing agents delivered via pressurized or mechanical pump systems for even facial coverage without manual application. The product serves to hydrate, prime, or set makeup while minimizing friction-induced barrier disruption. Hydrating formulations occupy the largest volume position, though exfoliating variants register the fastest structural expansion as acid-based at-home treatments gain professional credibility. Natural ingredient positioning commands premium pricing power, while synthetic segments defend accessibility tiers through manufacturing scale.
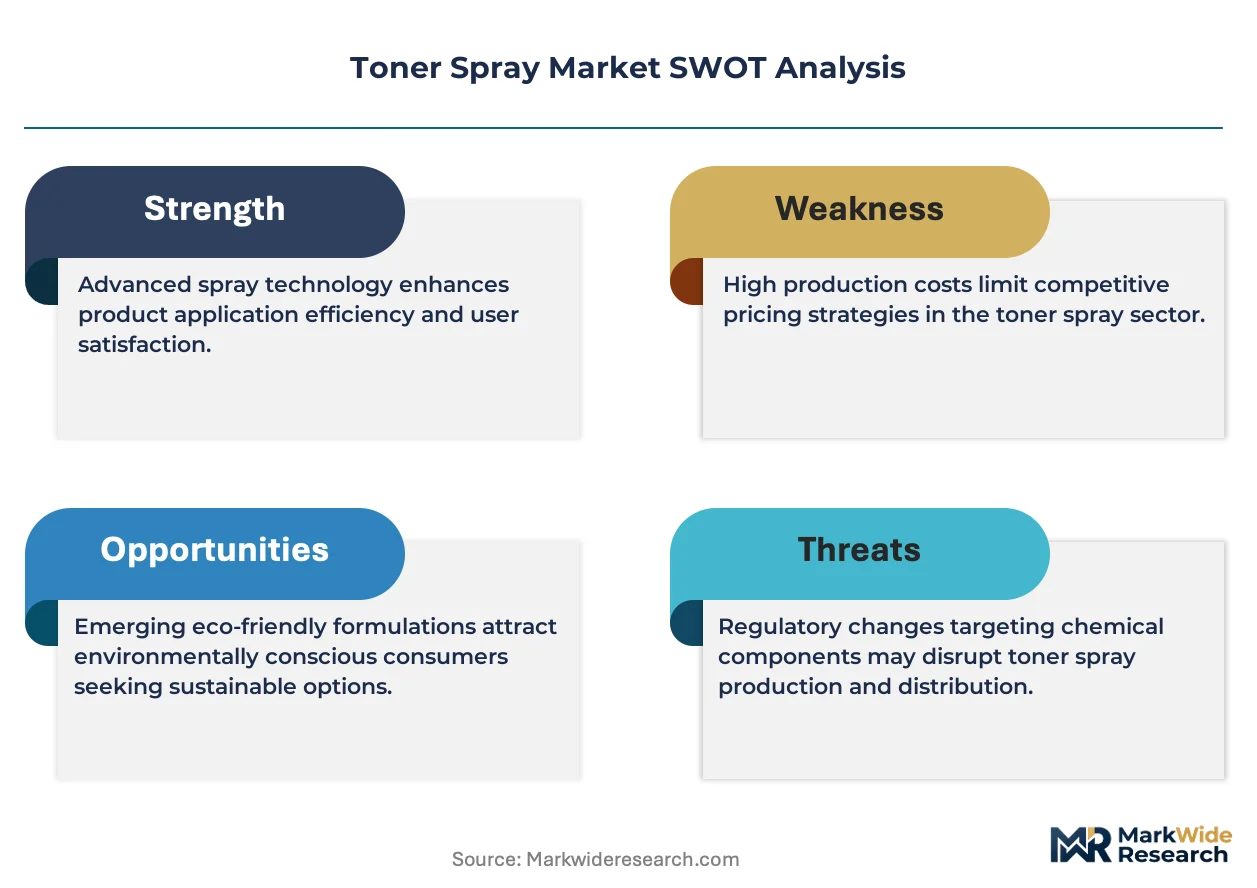
Regulatory oversight from the FDA governs cosmetic labeling and ingredient safety declarations in the United States, while REACH and the EU Cosmetics Regulation mandate exhaustive substance documentation and nanomaterial disclosure across European markets. Japan's Ministry of Health, Labour and Welfare enforces quasi-drug classifications that restrict functional claims for whitening or anti-aging toner sprays. Stakeholders must monitor evolving fragrance allergen labeling requirements and PFAS contamination thresholds that threaten reformulation timelines and sourcing contracts.
Market Dynamics
Clean beauty disclosure mandates across the European Union and Asia-Pacific jurisdictions are forcing compressed reformulation cycles, accelerating R&D spend and supplier qualification timelines for atomized skincare preparations.
Growth Catalysts
- K-Beauty Export Momentum:South Korean domestic skincare rituals sustain premium positioning for mist-format products across Southeast Asian and North American export corridors.
- Professional Channel Rebound:Post-pandemic service demand recovery in salon and makeup artist channels expands institutional procurement of professional-grade toner sprays.
- REACH Compliance:Exhaustive substance documentation requirements under EU Cosmetics Regulation elevate barriers for non-compliant competitors, consolidating shelf access for verified formulations.
Market Restraints
- Fragrance Allergen Labeling:Evolving EU fragrance allergen disclosure thresholds threaten sourcing contracts with established perfume houses and extend reformulation timelines.
- Quasi-Drug Classification:Japan's Ministry of Health, Labour and Welfare restricts functional whitening and anti-aging claims, limiting product positioning in the world's third-largest beauty market.
- PFAS Contamination Thresholds:Emerging detection limits for per- and polyfluoroalkyl substances in aerosol propellants and packaging materials disrupt established supply relationships.
Strategic Opportunities
- Direct-to-Consumer Flagships:Dedicated digital storefronts bypass narrowing specialty retail and department store counter channels, capturing margin and first-party data.
- Exfoliating Acid Formulations:Professional-credibility at-home treatments represent the fastest-expanding structural segment as acid-based mists displace manual toner application.
- Sensorial R&D Integration:Regional formulation labs in Asia-Pacific markets enable localized texture and scent profiles matched to humidity and skin-type preferences.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in atomized delivery systems and humectant stability under pressure constraints commands premium compensation and extended recruitment cycles.
- Multi-Jurisdiction Registration:Simultaneous compliance with FDA cosmetic labeling, REACH substance documentation, and Japan's quasi-drug classifications stretches regulatory affairs capacity.
- Mechanical Pump Validation:Transition from pressurized aerosol to mechanical atomization requires capital-intensive tooling validation and consumer education on dispensing technique.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toner Spray Market |
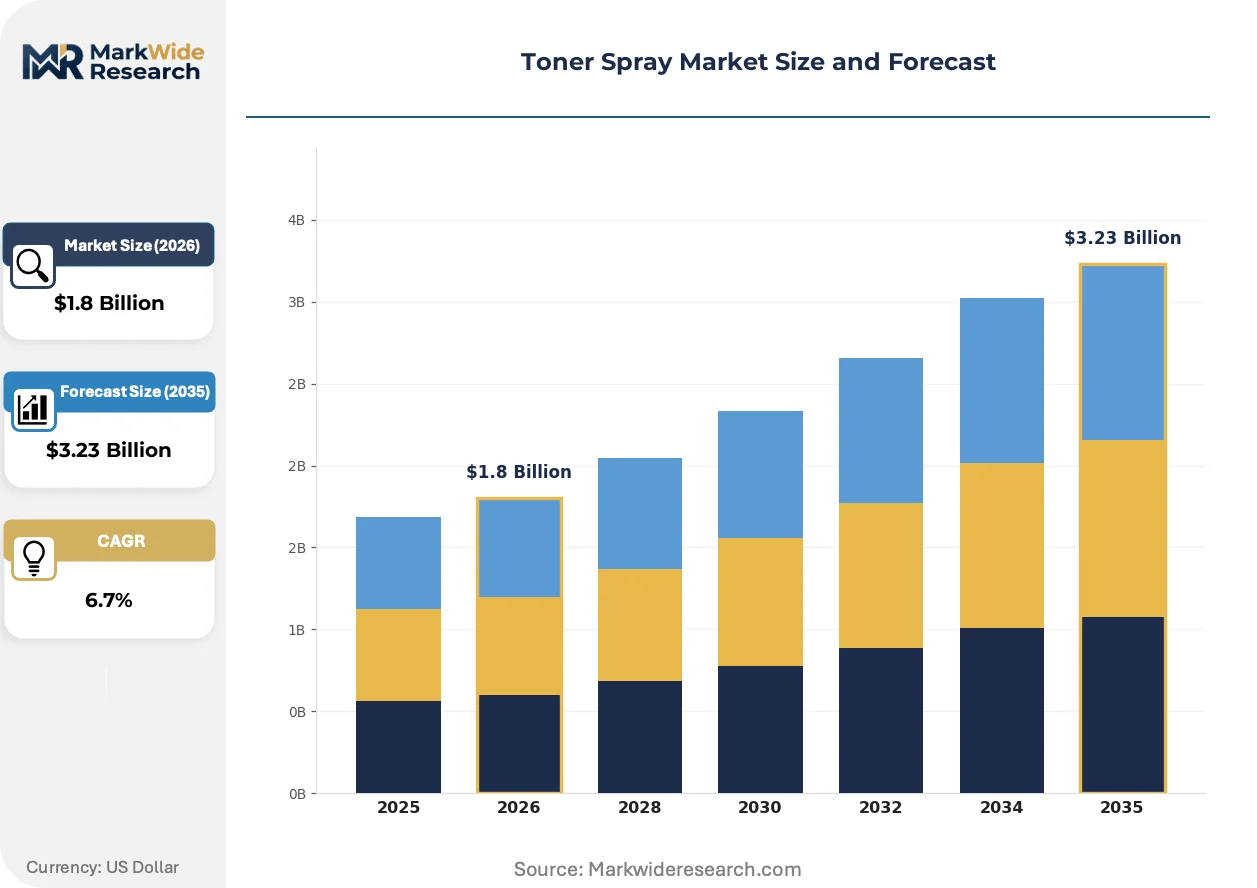
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrating, Mattifying, Exfoliating, Soothing Application: Skin Care, Makeup Setting, Prepping, Refreshing End User: Women, Men, Professionals, Teens Ingredient Type: Natural, Organic, Synthetic, Others |
| Companies Covered | L'Oréal, Estée Lauder, Procter & Gamble, Shiseido, Lancôme, Avène, Dr.Ci:Labo, Kao Corporation, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toner Spray Market Emerging Trajectories
Atomization technology and ingredient transparency protocols are actively compressing the gap between professional facial treatment outcomes and at-home skincare rituals, reshaping how consumers access clinical-grade hydration.
Micro-mist mechanical pumps are digitizing the delivery precision previously exclusive to professional airbrush systems. Prestige and masstige brands adopt these systems to reduce propellant dependency and enable finer droplet control. The technology is digitizing consumer expectations around even facial coverage without manual friction, compressing the performance gap between salon and home application.
REACH nanomaterial disclosure mandates are forcing granular supply chain visibility down to the sub-micron ingredient level. Cosmetic manufacturers must now document engineered particle characteristics for titanium dioxide and other functional additives used in toner sprays. European formulators are responding by reformulating with larger-particle alternatives or eliminating flagged nanomaterials entirely, shifting competitive advantage toward vertically integrated ingredient producers.
Subscription-based replenishment models are displacing traditional retail discovery for core skincare staples. Direct-to-consumer platforms capture recurring revenue from toner spray users who prioritize convenience over in-person consultation. South Korean and North American urban consumers demonstrate the highest adoption of automated replenishment, with preference clustering around multi-step regimen bundling rather than single-product subscriptions.
Toner Spray Market Segmentation
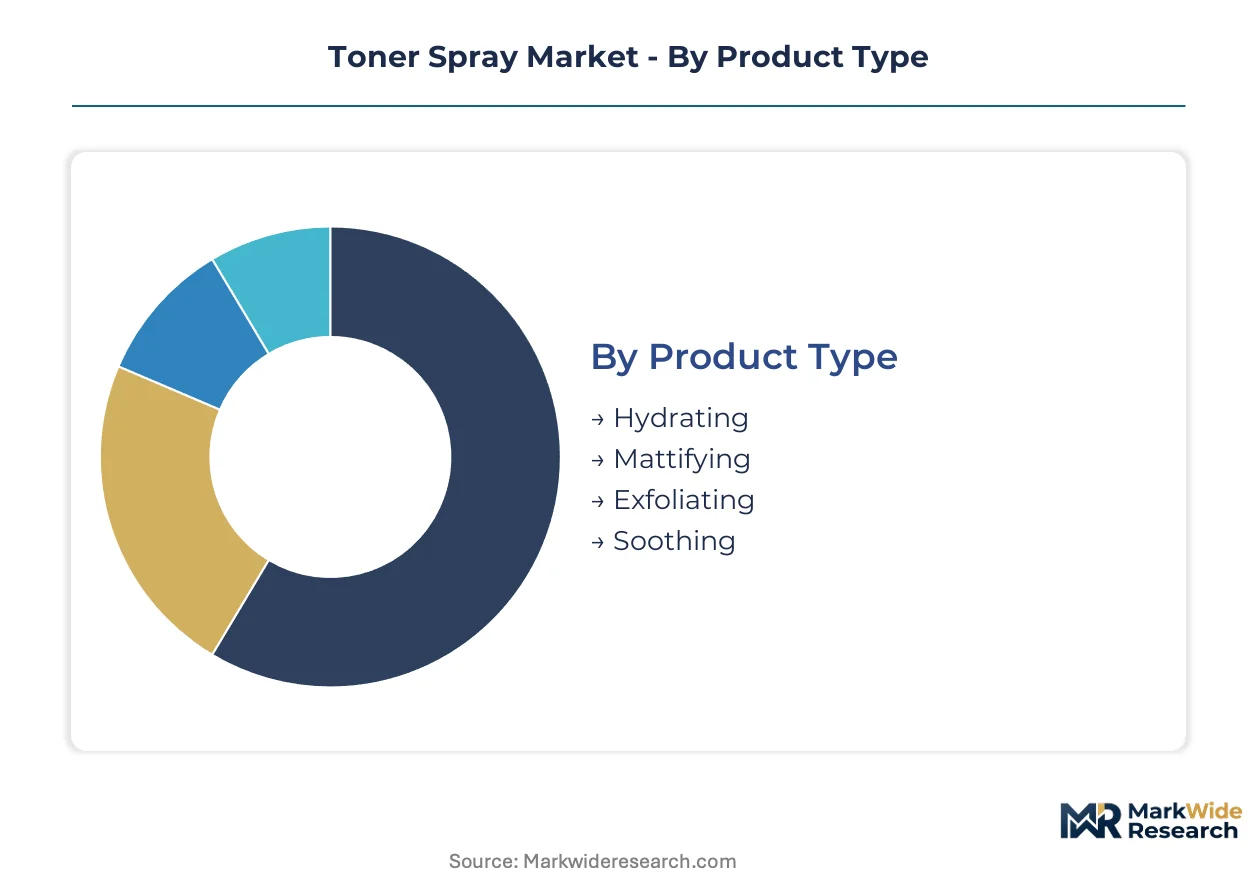
Segmentation in the Toner Spray Market reveals how atomized skincare formats fragment across functional claims, ritual contexts, and ingredient sourcing philosophies. Manufacturers calibrate droplet size, humectant load, and botanical positioning to match distinct usage occasions and buyer willingness-to-pay thresholds.
Product Type:
The maturity spectrum spans established hydration staples to emerging acid-based formats that borrow professional treatment credibility for home use.
- Hydrating:Glycerin and hyaluronic acid-based formulations dominate institutional procurement from makeup artists and salon channels. Demand concentrates in South Korea's domestic K-beauty ritual economy, where multi-layer misting sustains premium price positioning against Western competitors.
- Exfoliating:AHAs and BHAs delivered via micro-mist systems enable at-home chemical resurfacing without manual friction. Professional credibility transfers fastest through North American direct-to-consumer platforms, where acid-based regimens displace traditional cotton pad application.
- Mattifying:Silica and clay-infused variants target sebum control in humid climates, with formulation labs in Singapore and Bangkok driving regional adaptation.
- Soothing:Centella asiatica and thermal water compositions serve post-procedure recovery and sensitive skin protocols, anchoring pharmacy channel placement in France and Germany.
Hydrating toners handle the majority of throughput; Exfoliating variants are gaining share fastest as acid-based home treatments professionalize.
Application:
Cost tier separation runs from daily-use replenishment staples to occasion-specific performance formats commanding formulation premiums.
- Skin Care:Core hydration and barrier maintenance routines sustain the highest replenishment frequency and subscription-model adoption. South Korean and North American urban consumers cluster here, bundling mists into multi-step regimen purchases.
- Makeup Setting:Film-forming polymers and fine droplet control extend cosmetic wear time, with demand concentrating in professional makeup artist kits and prestige retail.
- Prepping:pH-balancing and primer-adjacent positioning captures value from consumers seeking to consolidate ritual steps, expanding fastest through masstige e-commerce channels.
- Refreshing:Mid-day revitalization and travel-format convenience drives impulse and airport retail placement, with smaller pack sizes defending accessible price points.
Skin Care absorbs the largest volume commitment; Makeup Setting climbs the fastest on professional channel recovery and social media tutorial amplification.
End User:
Customer type stratification reflects how gendered marketing, professional credential requirements, and age-specific skin concerns fragment demand signals.
- Women:The established core demographic across all price tiers, with purchasing decisions increasingly influenced by ingredient transparency and clean beauty positioning under EU disclosure mandates.
- Professionals:Makeup artists and aestheticians demand batch consistency, pump reliability, and backbar sizing, with institutional procurement recovering fastest in post-pandemic service economies.
- Men:Simplified ritual positioning and neutral scent profiles expand share through grooming-specialist retail and subscription platforms targeting routine consolidation.
- Teens:Acne-adjacent and social-media-discovered brands capture entry-level price points, with TikTok-driven discovery compressing traditional retail gatekeeper roles.
Women retain the deepest volume foundation; Professionals are expanding most quickly on salon channel reopening and kit replenishment cycles.
Ingredient Type:
Supply concentration for certified organic inputs and engineered synthetics creates divergent margin structures and regulatory exposure profiles.
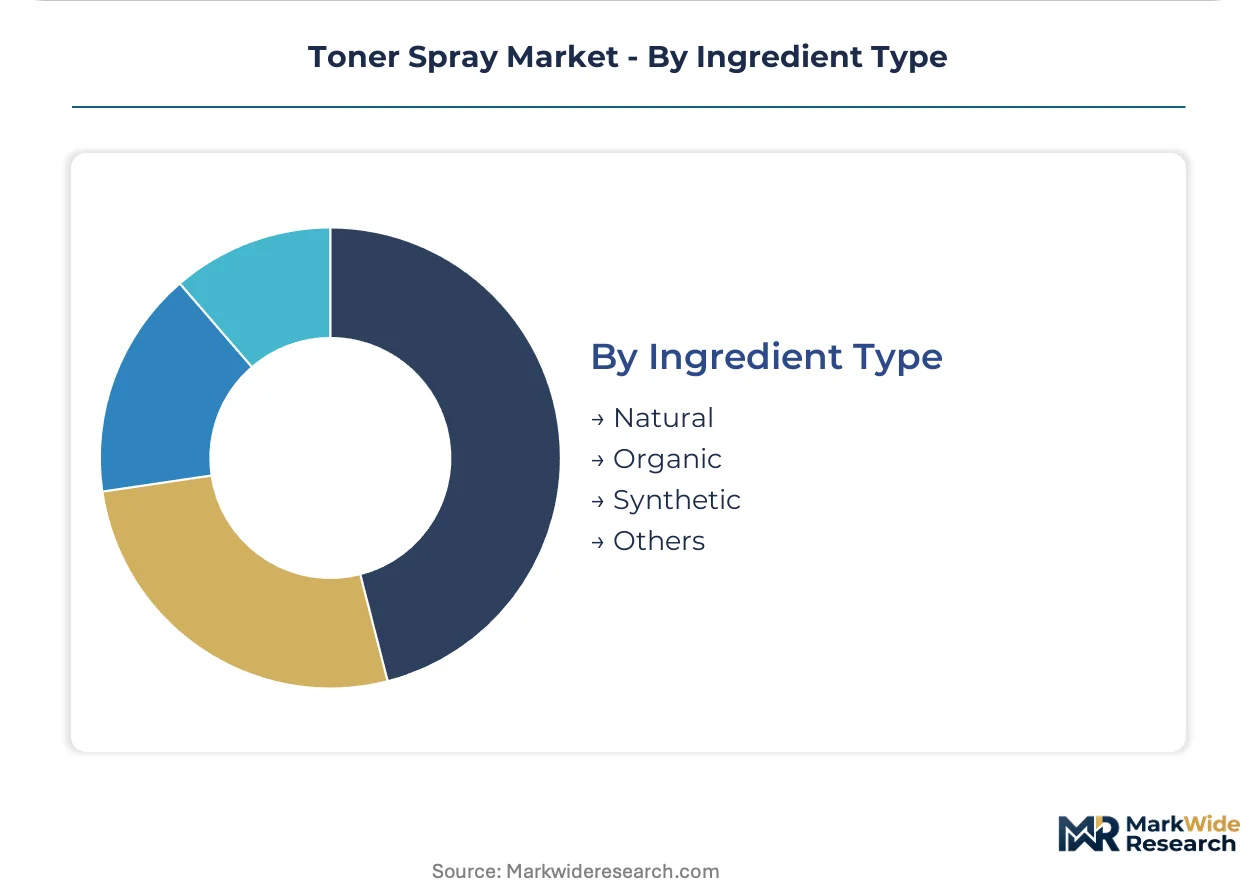
- Natural:Botanical extracts and fermentation-derived actives command premium pricing power, with sourcing transparency requirements intensifying under REACH nanomaterial disclosure and EU fragrance allergen rules.
- Synthetic:Manufactured humectants and stabilizers defend mass-market accessibility through scale economies, though PFAS contamination thresholds in propellants and packaging threaten established supplier relationships.
- Organic:Certified supply chains with restricted pesticide and solvent use carry the highest compliance burden but secure pharmacy and clean beauty specialist placement.
- Others:Hybrid and biotechnology-derived ingredients occupy emerging positioning, with fermentation platforms and lab-grown botanicals attracting R&D investment from Asia-Pacific formulation labs.
Natural ingredients anchor the largest revenue base; Organic certification is climbing fastest on clean beauty disclosure mandate expansion across European and Asia-Pacific jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan underwrites South Korea's export dominance in atomized skincare, channeling K-beauty production through maritime corridors reaching Southeast Asia and North America.
United States
Direct-to-consumer subscription platforms and professional makeup artist kit replenishment drive demand concentration. FDA cosmetic labeling requirements govern ingredient safety declarations, with fragrance allergen disclosure emerging as a compliance frontier. Los Angeles anchors West Coast formulation R&D clusters serving prestige and masstige brand incubators.
South Korea
Domestic multi-layer misting rituals and K-beauty export momentum sustain premium positioning for atomized formats. MFDS regulations align with quasi-drug classification standards that restrict functional whitening claims. Seoul Capital Area formulation labs integrate sensorial research with humidity-adapted texture development.
Japan
Pharmacy channel placement for sensitive skin protocols and post-procedure recovery formats anchors steady demand. The Ministry of Health, Labour and Welfare enforces quasi-drug classifications that constrain anti-aging claim positioning. Osaka-Kansai manufacturing clusters specialize in mechanical pump validation and fine droplet control systems.
Germany
Clean beauty disclosure mandates and REACH nanomaterial documentation requirements elevate compliance barriers for imported competitors. ECHA substance documentation protocols force granular supply chain visibility down to sub-micron ingredient levels. Frankfurt-Rhine-Main logistics hubs coordinate EU-wide distribution for verified formulation portfolios.
France
Thermal water-based soothing compositions and pharmacy channel heritage defend accessible premium positioning. ANSM and CNIL oversight intersect with EU Cosmetics Regulation fragrance allergen thresholds. Paris-Île-de-France headquarters clusters anchor multinational brand decision-making for European formulation strategies.
Toner Spray Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in atomization technology and certified ingredient supply. The vendor base stratifies across multi-brand conglomerates controlling shelf space, regional champions with localized formulation capabilities, and single-brand specialists defending clean beauty positioning. Three archetypes dominate: conglomerate platform operators, Asia-Pacific R&D-integrated houses, and dermatology-credentialed pharmacy brands. Competitive moves concentrate on direct-to-consumer flagship expansion and mechanical pump validation investments displacing legacy aerosol systems.
Among diversified beauty conglomerates, L'Oréal and Estée Lauder exemplify platform-scale operators with multi-brand portfolio control across mass and prestige channels. Shiseido occupies a position within the Asia-Pacific R&D-integrated tier, anchoring sensorial formulation capabilities through regional laboratory networks. These three entities represent distinct strategic postures: L'Oréal exemplifies shelf-space dominance, Estée Lauder anchors dedicated digital flagship experiences, and Shiseido sits within the technology-transfer bridge between professional salon systems and at-home atomization.
| Leading Market Players |
|---|
| L'Oréal |
| Estée Lauder |
| Procter & Gamble |
| Shiseido |
| Lancôme |
| Avène |
| Dr.Ci:Labo |
| Kao Corporation |
| Unilever |
| Others |
Supply Flow & Price Mechanics
Seoul Capital Area formulation clusters anchor atomized skincare production capacity, with their R&D-to-manufacturing density translating directly into pricing power for K-beauty exporters serving North American and Southeast Asian corridors. Concentrated mechanical pump validation expertise in this hub compresses tooling costs for compliant producers while elevating barriers for non-integrated competitors.
Pricing Analysis
Volume-discount tiering structures separate professional backbar sizing from retail single-unit purchases, with institutional procurement commanding 30-40% unit economics advantages. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—REACH-compliant formulations capture pharmacy channel premiums while mass-market synthetic variants compete on manufacturing scale. Pricing pressure stems from PFAS contamination threshold compliance costs in aerosol alternatives. Professional makeup artists exhibit lowest price sensitivity due to kit replenishment urgency; teen entry-level segments drive highest promotional intensity.
Supply Chain Analysis
Extended payment terms from South Korean pump system suppliers to Southeast Asian contract manufacturers are compressing working capital cycles across the tier. Geographic supply concentrates in South Korea, Japan, and Germany—each anchoring distinct specialization in sensorial R&D, mechanical validation, and clean beauty compliance documentation respectively. Raw material dependencies center on glycerin feedstocks, hyaluronic acid fermentation platforms, and titanium dioxide functional additives. Single-source vulnerability runs through certified organic botanical extract channels. Distribution runs through direct-to-consumer flagships bypassing narrowing department store counter access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned within a post-pandemic service economy cyclical recovery, with professional salon channel reopening velocity serving as the demand swing factor across institutional procurement segments.
For Market Incumbents: Insulate formulation portfolios from REACH nanomaterial disclosure disruption by accelerating backward integration into certified ingredient supply or securing exclusive fermentation platform partnerships. Prioritize mechanical pump validation capacity expansion in Osaka-Kansai manufacturing clusters to displace legacy aerosol dependencies before PFAS thresholds tighten. Channel control through dedicated digital flagships captures margin and first-party data away from narrowing specialty retail.
For New Entrants and Emerging Players: Pursue white-space positioning in men's grooming-specialist retail and subscription platforms targeting routine consolidation, where neutral scent profiles and simplified ritual positioning remain underdeveloped. Target teen acne-adjacent segments through TikTok-native discovery pathways that compress traditional retail gatekeeper roles. Go-to-market execution should anchor on acid-based exfoliating mists displacing manual cotton pad application in North American direct-to-consumer channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription platforms bundling multi-step regimen purchases, with South Korean and North American urban consumers demonstrating strongest automated replenishment adhesion. Long-term viability favors vertically integrated houses controlling regional formulation labs and sensorial R&D capabilities. Acquisition target archetype: Asia-Pacific R&D-integrated specialists with humidity-adapted texture development IP. Signal to watch: mechanical pump adoption rates displacing pressurized aerosol in prestige brand launches.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Flagship Expansion | Bypasses narrowing department store counters while capturing first-party subscription data and margin expansion. |
| Mechanical Pump Validation Investment | Displaces PFAS-vulnerable aerosol systems and enables finer droplet control matching professional airbrush precision. |
| Clean Beauty Certification Acceleration | Secures pharmacy channel placement under EU REACH and fragrance allergen disclosure mandates. |
| Regional Formulation Lab Integration | Enables localized sensorial profiles matched to humidity and skin-type preferences in Asia-Pacific markets. |
| Professional Channel Institutional Procurement | Captures post-pandemic salon reopening demand through backbar sizing and batch consistency guarantees. |
Methodological Framework
Operator-level perspectives from brand managers, category buyers at prestige retailers, formulation chemists, salon procurement directors, and regulatory affairs specialists anchored the qualitative base. Secondary validation drew from FDA cosmetic labeling filings, ECHA REACH substance documentation, MFDS quasi-drug registration databases, and K-beauty export trade statistics. Bottom-up demand modeling triangulated against top-down market sizing across atomized skincare consumption patterns.
Scenario-bracketing around regulatory acceleration and professional channel recovery velocity bounded the projection horizon. Segmentation dimensions spanned product type, application context, end-user archetype, and ingredient sourcing philosophy. CAGRs were derived from installed base replenishment cycles and format migration rates. Forecast inputs incorporated mechanical pump adoption curves and clean beauty disclosure mandate implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending elasticity or cross-border e-commerce logistics costs would shift the trajectory. Forecasts reflect documented assumptions around regulatory implementation pacing and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Myrcene Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
Taurine Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
UV/IR Blocker Market
Specialty Chemicals
Cellulose Derivatives Market
Specialty Chemicals
Silanes and Silicones Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
Isostearyl Alcohol Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
Niacin and Niacinamide Market
Specialty Chemicals
Magnesium Chelates Market
Specialty Chemicals
Eitelite Market