
 GLDA Market | 2026-2036
GLDA Market Size, Share, and Industry Trends Forecast 2026-2036
GLDA Market Insights
EDTA is hardening into a regulatory liability across industrial cleaning and water treatment sectors, pushing formulators toward GLDA as a biodegradable substitute. BASF SE leverages its integrated ethylene amine feedstock position to anchor European supply. Nouryon competes through specialized liquid grades for high-purity industrial applications. Evonik Industries AG differentiates via amino acid-derived manufacturing routes that reduce petrochemical dependency.
GLDA (tetrasodium glutamate diacetate) functions as a chelating agent with molecular formula C11H16NNa4O8, manufactured through glutamic acid neutralization followed by catalytic acetylation, primarily sequestering calcium and magnesium ions in hard water systems. The liquid product type dominates volume due to ease of handling in automated dosing systems, while powder and granule formats command margin premiums from fertilizer blenders seeking controlled-release compatibility. Food preservative applications represent the fastest-expanding end-use channel as clean-label formulations displace synthetic alternatives.
REACH registration requirements and the EU Green Deal's chemical sustainability criteria are elevating GLDA's market access relative to persistent chelators, while FDA food additive regulations and EPA safer choice labeling in the United States validate its toxicological profile for consumer-facing products. Stakeholders must monitor feedstock volatility in L-glutamic acid supply chains and evaluate backward integration into fermentation-based raw material production.
Market Dynamics
REACH restrictions on persistent chelators are compressing EDTA's industrial license, redirecting formulation demand toward biodegradable alternatives with verified environmental fate profiles.
Growth Catalysts
- REACH Annex XIV authorization:Persistent organic pollutant screening places EDTA under increasing substitution pressure across EU industrial cleaning applications, elevating GLDA's regulatory-access advantage.
- Water treatment infrastructure:Municipal hard-water conditioning facilities in Germany and the Netherlands are retrofitting dosing systems to accommodate liquid GLDA grades for calcium and magnesium sequestration.
- Fermentation feedstock advances:Microbial L-glutamic acid production is reducing petrochemical dependency in chelator synthesis, aligning with EU Green Deal bioeconomy targets.
Market Restraints
- L-glutamic acid price volatility:Corn and cassava feedstock swings in Southeast Asian fermentation supply chains transmit directly to GLDA manufacturing economics.
- Technical performance gaps:GLDA exhibits lower thermal stability than phosphonate alternatives above 80°C, constraining high-temperature boiler water treatment adoption.
- EDTA incumbency in legacy systems:Existing chelator dosing infrastructure across North American pulp and paper mills requires capital retrofit for GLDA compatibility.
Strategic Opportunities
- Clean-label food preservation:FSSAI and FDA food additive approvals for tetrasodium glutamate diacetate are opening bakery and beverage applications displacing synthetic preservatives.
- Personal care formulation:Shampoo and cosmetic manufacturers are reformulating around EU microplastic-free labeling requirements, favoring biodegradable chelators in rinse-off products.
- Agricultural micronutrient delivery:Controlled-release fertilizer blenders in Brazil and India are specifying powder-grade GLDA for iron and zinc complexation in foliar applications.
Industry Challenges
- Biodegradation certification timelines:OECD 301B ready biodegradability testing requires 28-day validation cycles that delay new product launches.
- Formulation technical service capacity:Chelation performance optimization across varying water hardness profiles demands specialized application engineering that mid-tier distributors struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GLDA Market |
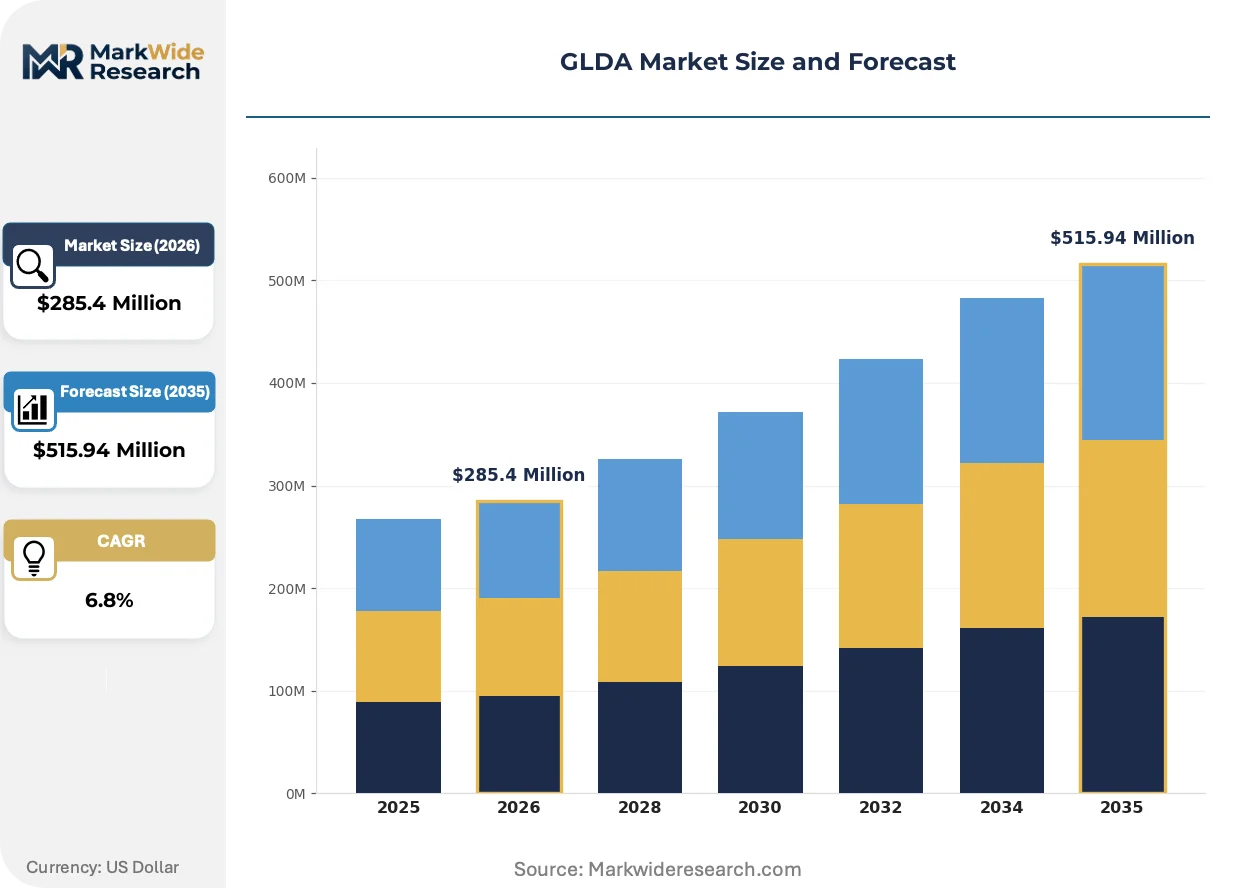
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Capsules End User: Food Industry, Pharmaceuticals, Cosmetics, Fertilizers Application: Food Preservative, Nutritional Supplement, Cosmetic Ingredient, Agricultural Additive Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesalers |
| Companies Covered | BASF SE, Nouryon, Evonik Industries AG, Dow Inc., Kemira Oyj, Jarchem, SHOWA DENKO, Jungbunzlauer Suisse AG, Lanxess AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GLDA Market Trends and Innovations
Formulation science is pivoting from single-chelator systems to synergistic blends that optimize performance-cost ratios while satisfying multi-jurisdictional environmental compliance requirements.
Continuous flow reactor technology for catalytic acetylation is integrating into European manufacturing assets, replacing batch processing with temperature-controlled microchannel systems that reduce solvent waste and improve yield consistency. Specialty chemical producers in Germany are adopting these systems to serve pharmaceutical-grade chelator demand. The capital efficiency of modular flow chemistry is compressing minimum viable scale thresholds for regional GLDA production.
REACH restriction proposals on tetrasodium EDTA are advancing through ECHA's SVHC identification process, with downstream users in metal finishing and textile processing facing substitution deadlines. Industrial laundries and hard-surface cleaners are reformulating ahead of regulatory enforcement. The compliance-driven specification shift is most visible in German automotive supplier parks where wastewater discharge permits now exclude persistent chelators.
Direct procurement relationships between chelator consumers and fermentation-based feedstock producers are consolidating supply chain control, bypassing traditional distributor intermediaries in agricultural and water treatment segments. Large-scale fertilizer blenders and municipal chemical buyers are negotiating multi-year L-glutamic acid supply agreements. This channel restructuring is pronounced in North American Great Lakes water treatment districts where volume buyers seek price predictability against agricultural commodity volatility.
GLDA Market Segmentation
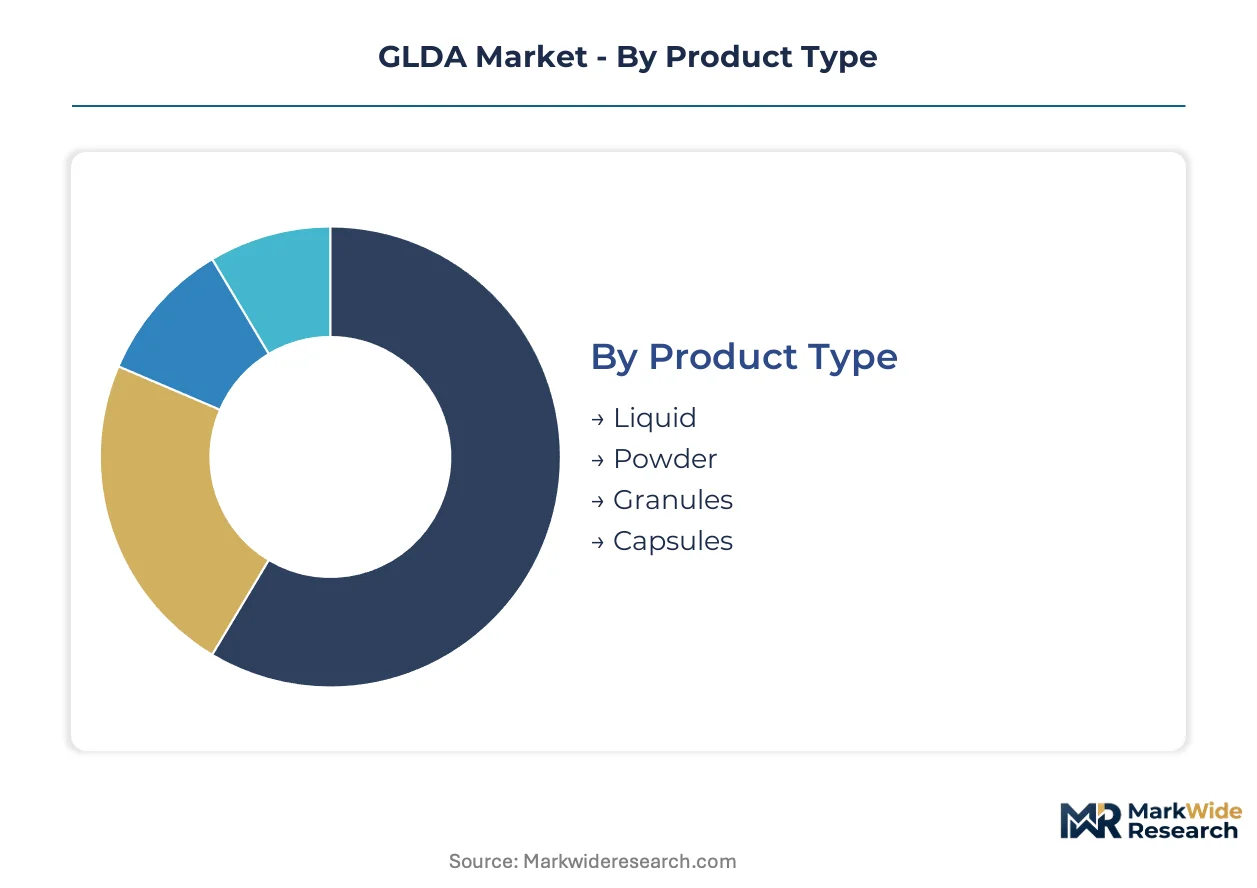
GLDA's molecular versatility across liquid, powder, and solid formats creates distinct value propositions for automated dosing systems versus controlled-release applications. End-use fragmentation across food preservation, pharmaceutical chelation, and agricultural micronutrient delivery demands format-specific technical specifications that reshape procurement criteria.
Product Type:
Buyers select formats based on handling infrastructure compatibility and dissolution kinetics for their specific application environment.
- Liquid:Aqueous tetrasodium glutamate diacetate solution with standardized active content enables precision metering through automated dosing skids in municipal water treatment facilities. Demand concentrates in German and Dutch hard-water conditioning plants retrofitting from EDTA-based systems to meet REACH discharge permit requirements.
- Powder:Spray-dried crystalline product with extended shelf stability supports controlled-release fertilizer blending where particle size distribution determines nutrient release kinetics. Brazilian and Indian agricultural compounders specify powder grades for iron and zinc complexation in foliar spray formulations.
- Granules:Agglomerated form reduces dust generation during bulk handling operations. Fertilizer manufacturers in the US Corn Belt favor granules for compatibility with existing blending equipment.
- Capsules:Pre-measured unit doses serve pharmaceutical and laboratory applications requiring batch traceability. Contract research organizations in Switzerland specify capsule formats for chelation therapy development protocols.
Volume sits with Liquid; growth tilts toward Powder.
End User:
Regulatory approval status and toxicological documentation requirements segment buyers by their tolerance for certification timelines and compliance investment.
- Food Industry:Clean-label bakery and beverage manufacturers leverage FDA and FSSAI food additive approvals for synthetic preservative displacement. Clean-label reformulation in European ready-to-eat meals drives specification.
- Pharmaceuticals:Chelating agent for active pharmaceutical ingredient stabilization and heavy metal detoxification therapies. Swiss and German drug manufacturers require pharmaceutical-grade documentation.
- Cosmetics:Rinse-off shampoo and personal care formulations seeking EU microplastic-free labeling compliance specify biodegradable chelators. French and Italian cosmetic houses lead formulation conversion.
- Fertilizers:Micronutrient complexation for controlled-release agricultural applications. Brazilian sugarcane and Indian rice cultivation operations drive agricultural-grade procurement.
Revenue concentrates in Food Industry; steepest expansion trajectory emerges in Cosmetics.
Application:
Performance specifications diverge based on thermal stability requirements, pH operating windows, and regulatory exposure of the final consumer product.
- Food Preservative:Calcium and magnesium sequestration extends shelf life in baked goods and beverages without synthetic additive labeling. Clean-label positioning in US and European retail chains accelerates adoption.
- Nutritional Supplement:Mineral bioavailability enhancement through chelated forms improves absorption in dietary formulations. Sports nutrition manufacturers in Germany and the Netherlands specify chelated mineral complexes.
- Cosmetic Ingredient:Hard-water ion sequestration prevents soap scum and improves surfactant efficacy in rinse-off products. EU microplastic-free labeling mandates reshape European personal care procurement.
- Agricultural Additive:Micronutrient stabilization in foliar feeds and soil amendments prevents precipitation in alkaline conditions. Brazilian soybean and Indian wheat operations specify agricultural-grade chelation.
Current procurement favors Food Preservative; forward momentum clusters on Agricultural Additive.
Distribution Channel:
Order scale predictability and technical service requirements determine channel selection between transactional efficiency and relationship-based support.
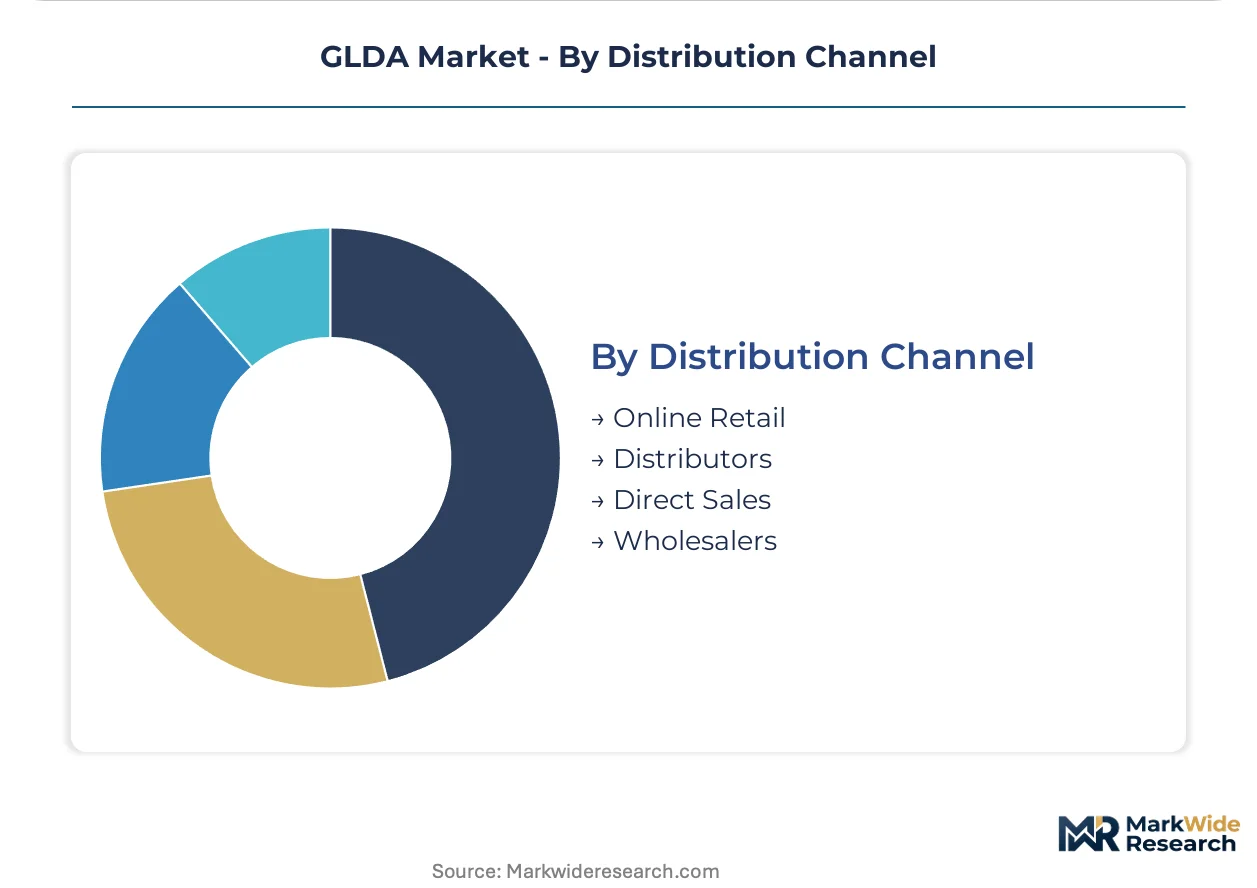
- Online Retail:E-commerce platforms serve small-volume laboratory and pilot-scale buyers requiring rapid fulfillment of standardized grades. Research institutions and startup formulators in the US and Germany utilize digital procurement.
- Distributors:Regional chemical distributors provide inventory buffering and local technical service for mid-tier water treatment and agricultural compounders. North American Great Lakes districts rely on distributor networks for just-in-time delivery.
- Direct Sales:Volume buyers negotiate multi-year supply agreements bypassing intermediaries to secure price predictability against L-glutamic acid feedstock volatility. Municipal water authorities and multinational fertilizer blenders favor direct relationships.
- Wholesalers:Bulk aggregators serve price-sensitive agricultural markets with commodity-grade product. Indian and Southeast Asian fertilizer markets utilize wholesale channels for seasonal procurement.
Transaction volume flows through Distributors; channel expansion is accelerating fastest in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water treatment infrastructure investments and food preservative reformulation are concentrating procurement in Germany, the United States, and select Asian manufacturing hubs. Regulatory pressure on persistent chelators is accelerating specification shifts toward biodegradable alternatives. Industrial clusters in the Rhine-Ruhr region, the American Midwest, and coastal China anchor production capacity and downstream formulation demand.
Germany
Municipal hard-water conditioning facilities in the Rhine-Ruhr region are retrofitting dosing systems for liquid GLDA grades. ECHA's SVHC screening of tetrasodium EDTA is compressing industrial license timelines for persistent chelators. BASF SE and Lanxess AG anchor production capacity in Ludwigshafen and Leverkusen, serving automotive supplier parks with wastewater discharge permits that now exclude EDTA.
United States
EPA Safer Choice labeling is validating GLDA's toxicological profile for consumer-facing cleaning products. Municipal water authorities in the Great Lakes districts are negotiating multi-year supply agreements for price predictability. Chicago and Milwaukee metropolitan treatment facilities are expanding biodegradable chelator adoption for calcium and magnesium sequestration.
China
Fermentation-based L-glutamic acid production is scaling to reduce petrochemical dependency in chelator synthesis. The country's dual carbon goals are elevating biodegradable alternatives in industrial procurement guidelines. Yangtze River Delta chemical parks are integrating continuous flow reactor technology for catalytic acetylation processes.
Brazil
Controlled-release fertilizer blenders are specifying powder-grade GLDA for iron and zinc complexation in sugarcane and soybean operations. ANVISA is tightening environmental fate requirements for agricultural chemical inputs. São Paulo state agricultural compounders are bypassing traditional distributors to secure direct procurement relationships with fermentation feedstock producers.
India
FSSAI food additive approvals are opening bakery and beverage applications for synthetic preservative displacement. Corn and cassava feedstock volatility in Southeast Asian supply chains is transmitting to GLDA manufacturing economics. Gujarat and Maharashtra pharmaceutical manufacturers are requiring pharmaceutical-grade documentation for chelating agent procurement.
GLDA Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation-based feedstock producers scale microbial L-glutamic acid output to meet chelator demand. The vendor base clusters around three strategic archetypes: integrated petrochemical majors with ethylene amine feedstock positions, fermentation specialists with amino acid-derived manufacturing routes, and regional distributors with technical service capabilities for water hardness optimization. Geographic expansion and backward integration into raw material production represent the dominant competitive moves as price predictability becomes a procurement priority.
Among European integrated producers, BASF SE and Lanxess AG exemplify the petrochemical-major archetype with captive feedstock positions, while Nouryon occupies a position within the specialty liquid grades segment for high-purity industrial applications. These three entities anchor the competitive structure through differentiated manufacturing routes and regulatory compliance positioning.
| Leading Market Players |
|---|
| BASF SE |
| Nouryon |
| Evonik Industries AG |
| Dow Inc. |
| Kemira Oyj |
| Jarchem |
| SHOWA DENKO |
| Jungbunzlauer Suisse AG |
| Lanxess AG |
| Others |
Pricing and Supply Chain Analysis
Corn futures and cassava spot markets in Southeast Asian trading hubs cascade directly into GLDA manufacturing economics, compressing margin structures for non-integrated producers while rewarding those with captive fermentation capacity. L-glutamic acid feedstock swings transmit through three distinct pricing tiers that separate pharmaceutical-grade documentation from agricultural commodity supply.
Pricing Analysis
Volume concentrates in liquid-grade municipal contracts with thin margins, while powder and capsule formats capture premium positioning through certification intensity. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and agricultural-grade levels reflects documentation burden and purity thresholds. Cost compression in commodity agricultural tiers is intensifying because Brazilian and Indian fertilizer blenders negotiate multi-year offtake agreements. Municipal water authorities in the Great Lakes districts exhibit lowest price sensitivity due to regulatory compliance mandates, whereas spot-market agricultural buyers face acute margin pressure.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical-grade GLDA involve batch-traceable returns and controlled-temperature refurbishment protocols that extend product lifecycle documentation. Manufacturing gravity centers on Germany, China, and the United States, with Ludwigshafen and Leverkusen anchoring European chelator output. Production draws from microbial fermentation of corn-derived glucose and cassava starch as primary carbohydrate feeds. Single-source vulnerability concentrates in Southeast Asian L-glutamic acid fermentation, where monsoon crop cycles and energy cost swings disrupt input predictability. Distribution runs through direct procurement relationships for volume buyers, with regional distributors buffering mid-tier agricultural and water treatment accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GLDA competitive dynamics have compressed into a vertical-integration race where control over L-glutamic acid fermentation capacity determines margin sustainability. Players are pursuing backward integration into microbial amino acid production to escape agricultural commodity volatility.
For Market Incumbents: Acquire fermentation-based feedstock assets in corn-belt geographies to anchor cost predictability against Southeast Asian supply swings. BASF SE and Lanxess AG should consolidate regional technical service capabilities for water hardness optimization before mid-tier distributors can staff equivalent expertise. ECHA's advancing SVHC screening of tetrasodium EDTA presents substitution demand that incumbents must capture through formulation support capacity. For New Entrants and Emerging Players: Capture agricultural micronutrient delivery in Brazil and India where ANVISA and FSSAI regulatory approvals remain penetrable for fermentation-derived chelators. Powder-grade GLDA for controlled-release fertilizer applications offers the most accessible volume ramp, with direct procurement relationships to large-scale blenders bypassing entrenched distributor networks. Position through pharmaceutical-grade documentation capabilities that command sustainable premium positioning. For Investors and Strategic Acquirers: The window for entry favors fermentation specialists with amino acid manufacturing routes and existing regulatory dossiers. Long-term viability rests on feedstock integration depth rather than formulation chemistry alone. Watch ECHA authorization timelines for tetrasodium EDTA as the inflection signal determining substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstock | Captive L-glutamic acid production insulates margin structures from Southeast Asian agricultural commodity volatility. |
| Continuous Flow Reactor Technology Deployment | Microchannel catalytic acetylation systems in German chemical parks reduce solvent waste and improve pharmaceutical-grade yield consistency. |
| Pharmaceutical-Grade Certification Investment | FDA and EMA drug master file documentation opens chelation therapy and API stabilization applications with premium pricing power. |
| Direct Procurement Relationship Development | Multi-year supply agreements with North American municipal water authorities secure volume predictability against spot-market turbulence. |
| Clean-Label Food Additive Positioning | FSSAI and FDA food additive approvals enable synthetic preservative displacement in European and US retail bakery chains. |
Research Methodology
Trade statistics from customs databases, Cefic sector reports, and SEC 10-K filings formed the secondary backbone for capacity and trade flow calibration. Primary interviews with plant managers at German and US chelator facilities, procurement leads at Brazilian fertilizer compounders, and technical R&D directors at personal care formulators validated demand assumptions and substitution timelines. Bottom-up and top-down triangulation reconciled fermentation capacity estimates against end-use consumption patterns.
Bottom-up modeling built product-grade volume and value outputs from individual facility capacities and regional pricing differentials, while top-down approaches cross-checked against chelator penetration rates in water treatment and agricultural applications. Segmentation dimensions spanned format type, end-use industry, certification grade, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating REACH enforcement trajectories and food preservative reformulation momentum. Forecast inputs included ECHA SVHC screening timelines and EPA Safer Choice labeling adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to L-glutamic acid feedstock volatility and fermentation technology cost curves. Practitioners should monitor ECHA authorization proposals for tetrasodium EDTA and ANVISA environmental fate requirements for agricultural chemical inputs as early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Fabric Softener Sheet Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
Global Bio Based Esters Market
Specialty Chemicals
Polyether Modified Silicone Market
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Sodium Ascorbyl Phosphate (SAP) Market
Specialty Chemicals
Global Foam Blowing Agents Market
Specialty Chemicals
Middle East and Africa Amino Acids Market
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market