
 Ursolic Acid Market | 2026-2036
Ursolic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Ursolic Acid Market Outlook
Chinese rosemary extract processors in Shaanxi province is hardening as a supply anchor for pharmaceutical-grade ursolic acid. Sabinsa Corporation leverages vertical integration from raw herb sourcing to standardized extract production. Changsha Staherb Natural Ingredients sustains R&D intensity in supercritical CO2 extraction methods. Geneham Pharmaceutical anchors its position through dominance in high-purity crystallization for API customers.
Ursolic acid is a pentacyclic triterpenoid compound (C30H48O3) extracted primarily from rosemary leaves and apple peels through solvent extraction or chromatographic refinement, valued for its anti-inflammatory, anti-cancer, and muscle-preserving bioactivity. Powder formulations occupy the largest volume share due to bulk ingredient demand from pharmaceutical compounders, while liquid extracts represent the fastest-growing format as cosmetics manufacturers seek water-soluble delivery systems. Rosemary-derived material leads source segmentation because of standardized triterpene content and established agricultural supply chains in Mediterranean and Chinese growing regions.
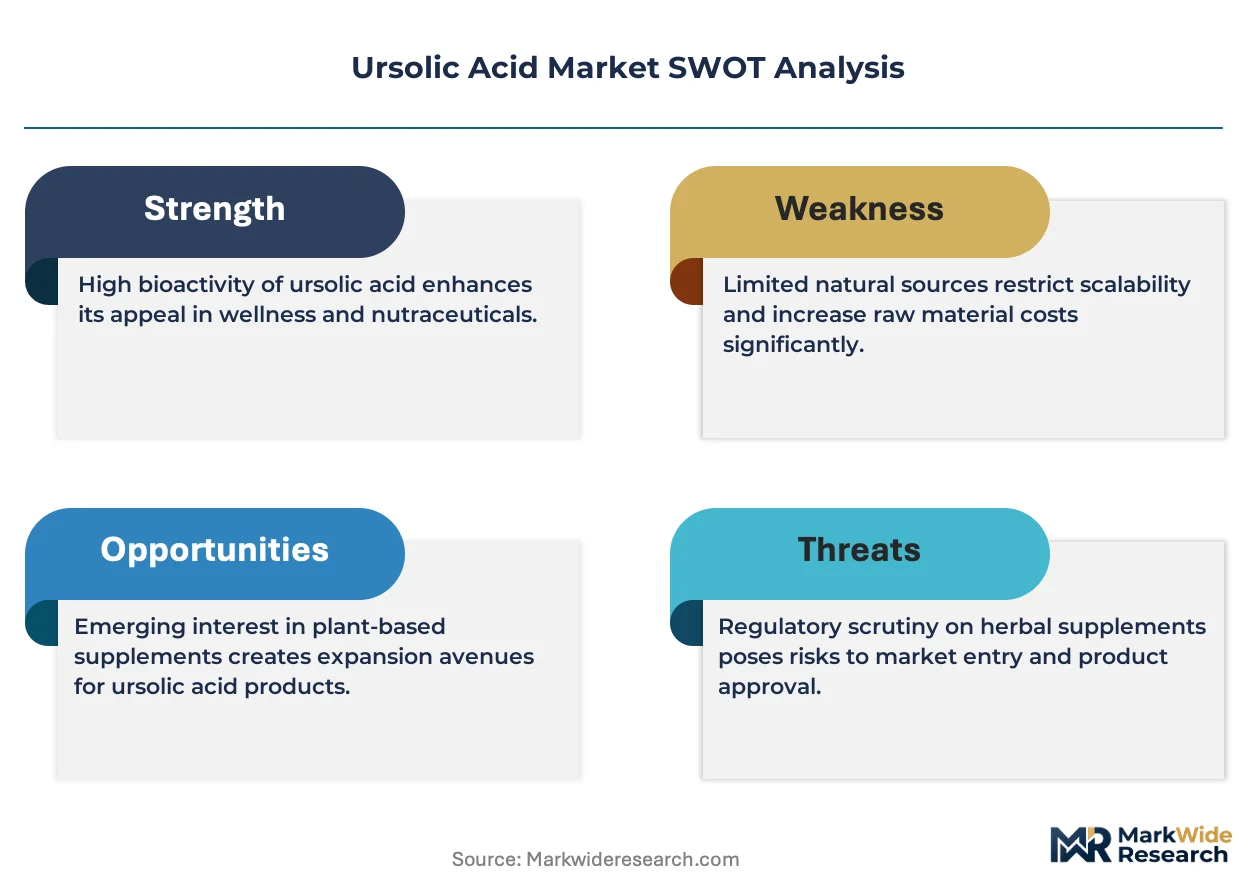
FDA dietary supplement cGMPs and EMA herbal medicine guidelines shape purity testing protocols and batch release requirements for ursolic acid entering regulated channels. China's NMPA botanical drug registration pathway creates additional compliance layers for domestic producers targeting hospital formulary inclusion. Stakeholders must monitor evolving pharmacopeial monograph revisions and botanical authentication standards as regulatory divergence between major markets intensifies qualification complexity.
Market Dynamics
Pharmaceutical formulators in Germany are expanding ursolic acid adoption for metabolic disorder therapies, while REACH compliance in Europe tightens purity thresholds for botanical extracts and China's Shaanxi province concentrates rosemary processing capacity.
Growth Catalysts
- Metabolic disorder therapy demand:Pharmaceutical compounders in Germany are incorporating ursolic acid into insulin-sensitizing formulations for type 2 diabetes management.
- REACH purity mandates:ECHA's tightening specifications for botanical triterpenoids are accelerating investments in chromatographic refinement capabilities among European extractors.
- Supercritical CO2 extraction advancement:Chinese processors in Shaanxi province are deploying supercritical fluid technology to achieve pharmaceutical-grade purity without residual solvent contamination.
Market Restraints
- Raw material concentration risk:Rosemary cultivation clusters in Mediterranean Spain and China's Shaanxi province create geographic vulnerability to climate-induced supply interruptions.
- High-purity crystallization cost structure:Multi-stage purification required for API-grade material consumes significant energy and solvent volumes, compressing margins for mid-scale producers.
- EMA herbal medicine guideline friction:Batch-to-batch triterpene variability in natural sources complicates compliance with EMA's fixed-marker-content requirements for botanical drug applications.
Strategic Opportunities
- Cosmetics water-soluble delivery systems:Korean and Japanese skincare manufacturers are requesting nano-emulsified ursolic acid formats for transparent serum formulations.
- NMPA botanical drug registration pathway:China's hospital formulary inclusion process creates a regulatory tailwind for domestic producers achieving documented anti-inflammatory efficacy in clinical settings.
- Apple peel waste valorization:Food processing byproduct streams in Poland and Washington State offer underutilized feedstock for triterpenoid extraction outside rosemary-dependent supply chains.
Industry Challenges
- Pharmacopeial monograph divergence:Discrepancies between USP, EP, and ChP purity specifications force manufacturers to maintain parallel quality systems for multi-market distribution.
- Supercritical extraction technician scarcity:Specialized CO2 plant operation and pressure-vessel maintenance skills are concentrated among a limited pool of trained personnel in extraction hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ursolic Acid Market |
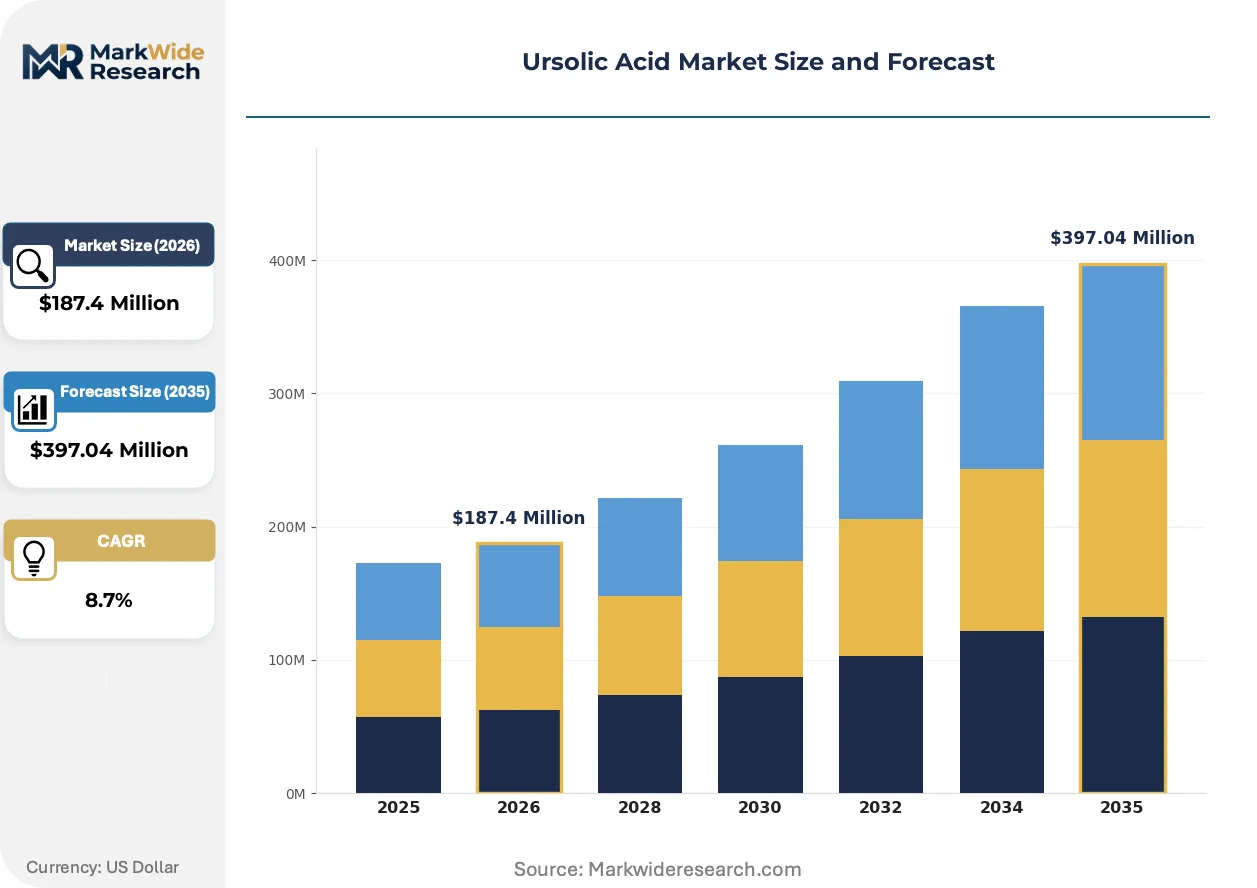
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid, Cream End User: Pharmaceuticals, Dietary Supplements, Cosmetics, Food & Beverage Source: Apple, Rosemary, Basil, Oregano Distribution Channel: Online, Retail Stores, Pharmacy, Direct Sales |
| Companies Covered | Sabinsa Corporation, Changsha Staherb Natural Ingredients, Geneham Pharmaceutical, Xuancheng Baicao Pharmaceutical, Yongzhou Huamao Biotechnology, Shaanxi Jintai Biological Engineering, Changsha E.K HERB, BASF SE, Hunan NutraMax Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ursolic Acid Market Strategic Shifts
Extraction technology advancement is compressing the purity gap between rosemary-derived and synthetic triterpenoid sources, while regulatory divergence between major markets intensifies qualification complexity for cross-border suppliers.
Supercritical CO2 extraction is expanding into pharmaceutical-grade ursolic acid production as Chinese and European processors replace solvent-based methods. API manufacturers in Germany and Japan are qualifying CO2-derived material for metabolic disorder formulations at accelerated pace. This technology is expanding into high-value triterpenoid segments previously reserved for chromatographic purification, compressing the cost premium between food-grade and pharmaceutical-grade supply tiers.
REACH authorization requirements for residual solvents in botanical extracts are forcing rosemary processors to document supply chain contamination controls. ECHA's 2023 updates to triterpenoid monograph specifications now mandate quantification of 12 specific polycyclic aromatic hydrocarbons. European extractors serving pharmaceutical customers are responding by installing in-house GC-MS testing capabilities rather than relying on third-party certificates.
Cosmetics manufacturers are consolidating supplier relationships around vertically integrated rosemary processors capable of certifying agricultural origin. Korean and Japanese skincare brands now require batch-specific phytochemical profiles with geographic traceability to specific Shaanxi cooperatives or Spanish Murcia farms. This consolidation is most visible in Seoul and Tokyo, where formulators are disqualifying traders lacking direct agricultural partnerships or in-house extraction assets.
Ursolic Acid Market Segmentation
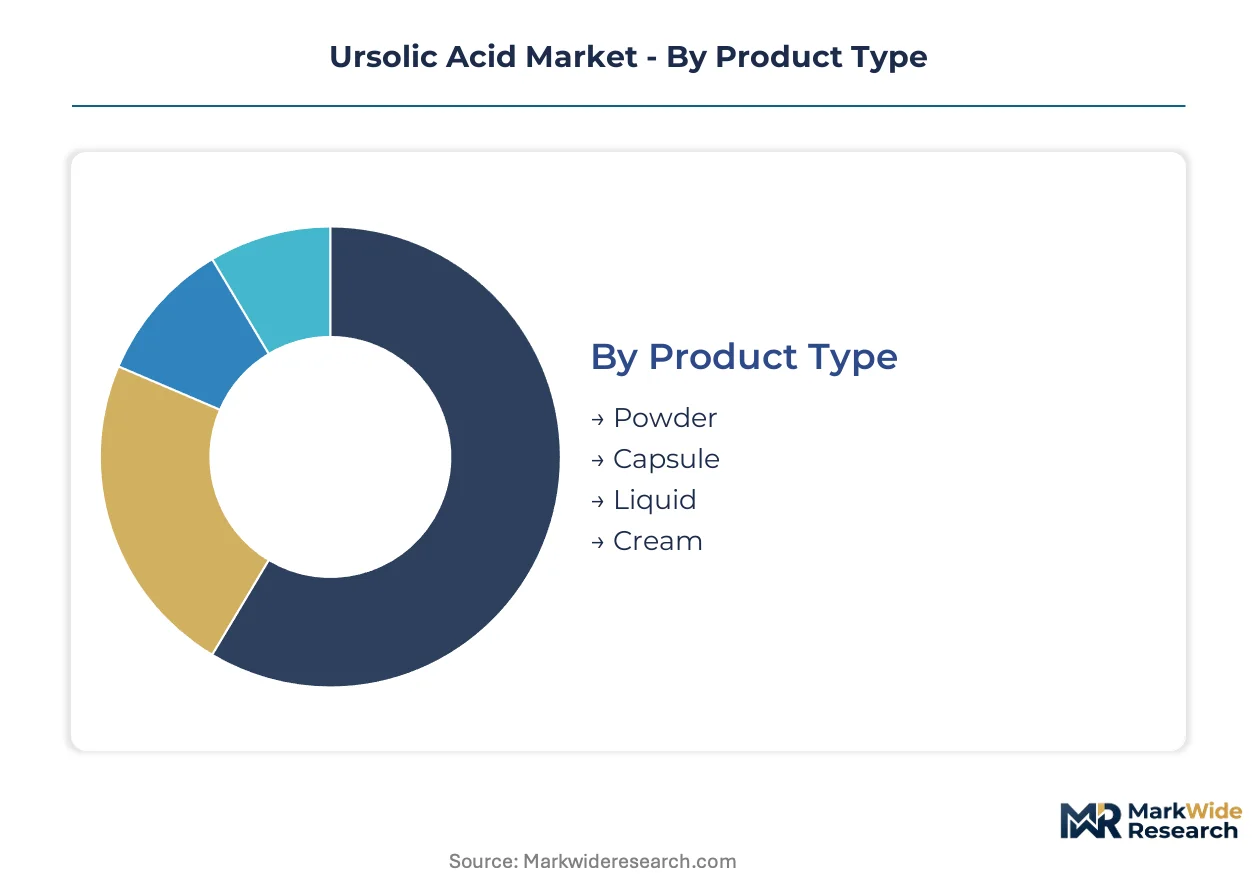
Product format decisions in ursolic acid procurement hinge on solubility requirements and downstream processing economics. Pharmaceutical compounders prioritize purity-certified inputs, while cosmetics formulators chase water-compatible delivery systems that bypass emulsification steps.
Product Type:
Upgrade cycles from solvent-extracted powders to supercritical CO2-derived alternatives are shortening as REACH compliance deadlines tighten residual solvent thresholds.
- Powder:Bulk crystalline material dominates pharmaceutical compounding due to standardized triterpene assays and extended shelf stability. German API manufacturers consume the largest volumes for metabolic disorder formulations, though powder processing energy costs are rising with multi-stage chromatographic refinement requirements.
- Liquid:Water-soluble and nano-emulsified formats command premium positioning in Korean and Japanese skincare manufacturing. Transparent serum compatibility drives procurement decisions in Seoul and Tokyo, where formulators reject particulate suspensions that compromise aesthetic clarity.
- Capsule:Pre-metered dosage units streamline dietary supplement manufacturing for contract packagers serving North American and European brands.
- Cream:Topical delivery vehicles incorporate ursolic acid for anti-inflammatory positioning in dermocosmetic lines targeting atopic dermatitis segments.
Powder sits at the top of the volume ranking, with Liquid climbing the fastest.
End User:
Application economics vary sharply across end-use sectors, with pharmaceutical qualification costs creating entry barriers that dietary supplement and cosmetics channels do not impose.
- Pharmaceuticals:API-grade material requires documented anti-inflammatory efficacy and batch-to-batch marker consistency under EMA herbal medicine guidelines. NMPA botanical drug registration in China creates additional clinical documentation burdens for hospital formulary inclusion.
- Dietary Supplements:cGMP compliance under FDA regulations permits broader triterpene variability, opening procurement to food-grade rosemary extracts. North American contract manufacturers source heavily from Shaanxi processors offering competitive bulk pricing.
- Cosmetics:Korean and Japanese skincare brands drive demand for origin-certified extracts with geographic traceability to specific agricultural cooperatives.
- Food & Beverage:Functional ingredient applications remain nascent, constrained by solubility limitations and taste masking requirements in beverage matrices.
Pharmaceuticals captures the highest purity premium, with Cosmetics expanding most quickly.
Source:
Feedstock selection determines extraction technology requirements and supply chain geographic exposure to climate and agricultural policy risks.
- Rosemary:Mediterranean Spain and China's Shaanxi province concentrate cultivation, with standardized triterpene content enabling pharmaceutical-grade production. Supercritical CO2 extraction deployment is most advanced among rosemary processors serving regulated markets.
- Apple:Peel waste streams from Polish and Washington State food processing operations offer underutilized triterpenoid reserves outside rosemary-dependent supply chains. Pectin extraction coprocessing economics currently limit commercial scale.
- Basil:Aromatic herb cultivation in India and Southeast Asia yields lower triterpene concentrations, restricting output to essential oil and fragrance applications.
- Oregano:Wild harvesting and small-scale cultivation in Turkey and Greece supply niche essential oil markets with limited standardization for pharmaceutical use.
Rosemary dominates current supply volumes, with Apple gaining share fastest as waste valorization technologies mature.
Distribution Channel:
Channel selection reflects customer scale, technical support requirements, and regulatory documentation needs that vary across end-use segments.
- Direct Sales:Long-term supply agreements anchor relationships between vertically integrated rosemary processors and multinational pharmaceutical compounders. Technical collaboration on extraction method qualification and pharmacopeial compliance justifies dedicated account management.
- Pharmacy:Hospital and retail pharmacy procurement in Germany and Japan concentrates demand for finished dosage forms containing ursolic acid, not bulk extract.
- Online:E-commerce platforms serve small-scale dietary supplement manufacturers and cosmetics startups with minimum order quantities below direct sales thresholds.
- Retail Stores:Consumer-facing finished products reach mass market through health food and beauty retail chains with limited bulk ingredient relevance.
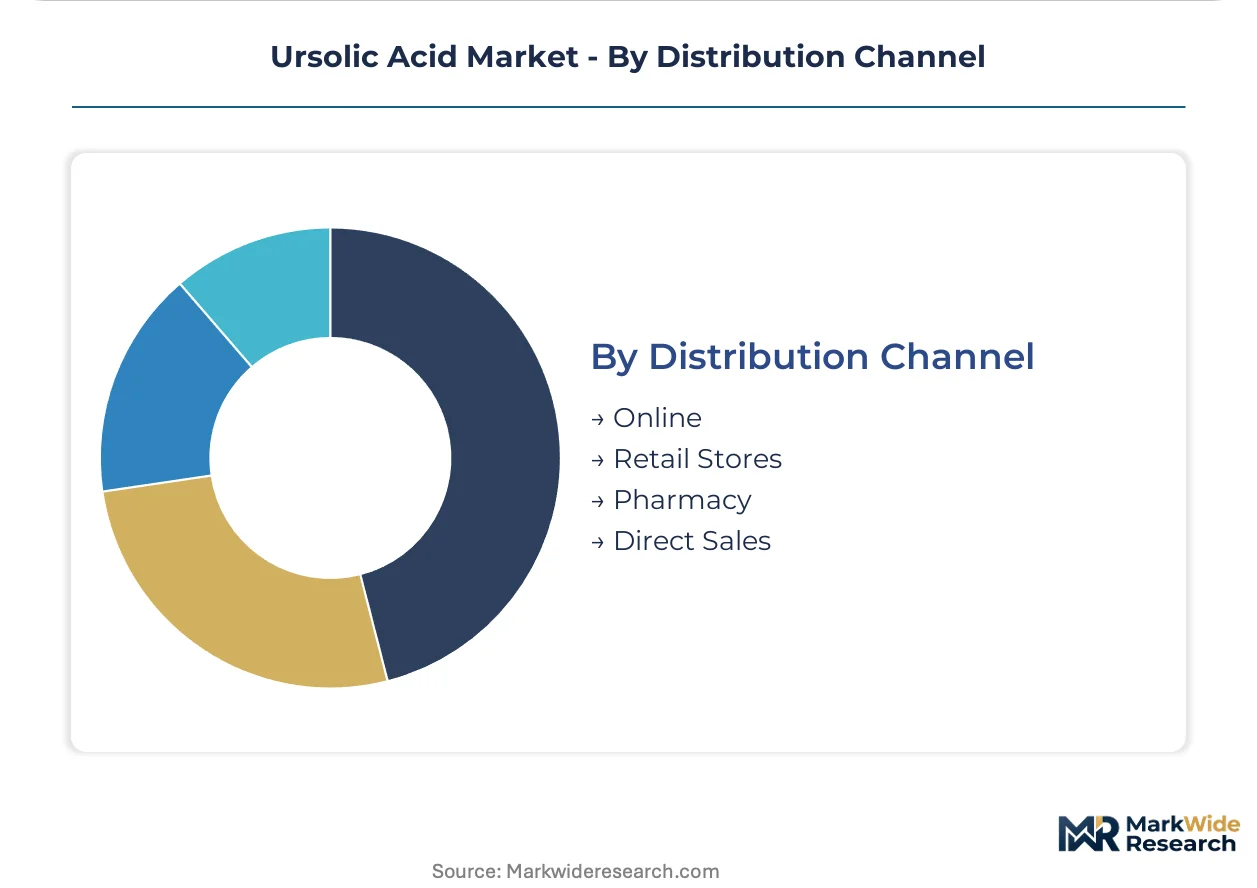
Direct Sales commands the highest transaction values, with Online showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling pharmaceutical-grade ursolic acid production toward jurisdictions with streamlined botanical extract compliance. Chinese processors exploit lower purity-certification costs, while European extractors absorb REACH-mandated investments to retain high-margin API contracts.
China
Shaanxi province hosts the densest concentration of rosemary processing capacity globally. NMPA botanical drug registration requirements are tightening clinical documentation standards for hospital formulary inclusion. Supercritical CO2 extraction clusters in Xi'an and Hanzhong are upgrading to serve API manufacturers in Germany and Japan.
Germany
Pharmaceutical compounders in Bavaria and North Rhine-Westphalia are expanding ursolic acid procurement for metabolic disorder therapies. EMA herbal medicine guidelines enforce batch-to-batch marker consistency that favors qualified European suppliers. REACH compliance investments in chromatographic refinement capabilities are concentrating among Baden-Württemberg extractors.
United States
Dietary supplement contract manufacturers in California and Utah source bulk powder from Shaanxi processors under FDA cGMP protocols. EPA residual solvent thresholds for botanical extracts remain less stringent than REACH mandates, preserving cost advantages for imported material. Pacific Northwest food processors are piloting apple peel waste valorization for domestic triterpenoid supply.
Japan
PMDA qualification requirements are accelerating adoption of supercritical CO2-derived ursolic acid for metabolic disorder formulations. Korean and Japanese cosmetics manufacturers in Osaka and Tokyo are consolidating supplier relationships around origin-certified extracts. METI standards for phytochemical traceability are disqualifying traders lacking direct agricultural partnerships.
Poland
Apple processing byproduct streams in Masovian and Greater Poland voivodeships offer underutilized feedstock for triterpenoid extraction. EFSA novel food regulations constrain rapid commercialization of apple-derived material for dietary supplements. Warsaw-based extractors are evaluating coprocessing economics with existing pectin production infrastructure.
Ursolic Acid Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue supercritical extraction specialization and cosmetics-grade water-soluble formats. The vendor base stratifies across three tiers: vertically integrated rosemary processors with agricultural partnerships, mid-scale extractors serving dietary supplement channels, and technology-focused specialists deploying advanced purification methods. Dominant competitive moves include backward integration into captive rosemary cultivation and strategic partnerships with Korean cosmetics formulators seeking origin-certified supply.
Among China-based extractors, Changsha Staherb Natural Ingredients and Geneham Pharmaceutical exemplify divergent archetypes within the Shaanxi processing cluster. Staherb occupies a position emphasizing extraction technology advancement, while Geneham anchors the high-purity crystallization segment for API customers. Sabinsa Corporation represents the vertically integrated model spanning raw herb sourcing through standardized extract production.
| Leading Market Players |
|---|
| Sabinsa Corporation |
| Changsha Staherb Natural Ingredients |
| Geneham Pharmaceutical |
| Xuancheng Baicao Pharmaceutical |
| Yongzhou Huamao Biotechnology |
| Shaanxi Jintai Biological Engineering |
| Changsha E.K HERB |
| BASF SE |
| Hunan NutraMax Inc. |
| Others |
Value Chain & Pricing Dynamics
Supercritical CO2 extraction deployment across Shaanxi province and European processing hubs is compressing cost differentials between food-grade and pharmaceutical-grade ursolic acid tiers while simultaneously concentrating supply relationships around technology-capable processors. This production-method transition rewards extractors with in-house chromatographic refinement capabilities, enabling them to capture margin premiums from German API manufacturers and Korean cosmetics formulators alike.
Pricing Analysis
Distributor margin layers in ursolic acid procurement vary sharply by purity certification and end-use channel. Three-tier pricing structure across premium, standard, and economy levels separates API-grade crystalline material from dietary supplement powders and cosmetic-grade liquid extracts. Price differentiation rests on REACH compliance documentation and supercritical CO2 extraction certification, with pharmaceutical compounders in Germany showing lowest price sensitivity due to formulary inclusion requirements. Cost compression in standard-tier powder supply is intensifying because Shaanxi processors are expanding capacity faster than quality-assured feedstock cultivation.
Supply Chain Analysis
Dual-sourcing requirements from EMA-compliant pharmaceutical compounders are forcing rosemary extract buyers to qualify processors in both China and Mediterranean Spain. Geographic supply concentration centers on Shaanxi province, Murcia region, and Polish apple processing districts. Raw material dependencies include rosemary leaf biomass, apple peel waste streams, and specialized CO2 extraction equipment. Single-source vulnerability runs through Shaanxi's supercritical CO2 technician pool. Distribution runs through direct sales agreements for pharmaceutical volumes and online platforms for dietary supplement contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ursolic acid margins are expanding through supercritical CO2 extraction adoption, which lowers residual solvent compliance costs while opening premium pharmaceutical and cosmetics tiers previously reserved for synthetic triterpenoid suppliers.
For Market Incumbents: Extend backward integration into captive rosemary cultivation in Shaanxi cooperatives or Spanish Murcia farms to secure origin-certification capabilities that Korean cosmetics brands now mandate. Deepen technical collaboration with German API manufacturers on batch-to-batch marker consistency documentation under EMA herbal medicine guidelines. This defends position against emerging Chinese processors deploying equivalent supercritical CO2 capacity.
For New Entrants and Emerging Players: REACH authorization requirements in Europe open a window for supercritical CO2 extraction specialists to displace solvent-dependent incumbents in pharmaceutical-grade supply. Target apple peel waste valorization in Poland and Washington State, where pectin extraction coprocessing economics remain underdeveloped. Lead with origin-traceable feedstock partnerships rather than commodity trading to bypass established distributor relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale rosemary extractors lacking pharmaceutical-grade certification but possessing installed supercritical CO2 capacity ready for upgrade. Long-term viability over the next decade hinges on NMPA botanical drug registration success in China and EMA herbal medicine guideline compliance in Europe. Watch Shaanxi processor consolidation velocity as the inflection signal—accelerating M&A activity indicates margin pressure on unintegrated traders.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | REACH residual solvent thresholds in Europe disqualify solvent-based extraction for pharmaceutical contracts. |
| Backward Integration into Rosemary Cultivation | Origin traceability to specific Shaanxi cooperatives satisfies Korean cosmetics brand procurement requirements. |
| Pharmaceutical-Grade Crystallization Investment | EMA batch-to-batch marker consistency mandates favor processors with in-house chromatographic refinement. |
| Apple Peel Waste Valorization Partnership | Polish food processing byproduct streams diversify feedstock beyond rosemary-dependent Mediterranean and Chinese supply chains. |
| NMPA Botanical Drug Registration Pathway | China's hospital formulary inclusion process creates regulatory tailwind for domestic producers with documented clinical efficacy. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extraction plant managers, pharmaceutical procurement leads at German API manufacturers, cosmetics formulators in Seoul and Tokyo, and regulatory affairs specialists at NMPA and EMA with secondary validation. Secondary sources included customs and trade data for rosemary extract flows, SEC filings from publicly traded ingredient suppliers, ECHA REACH authorization databases, and pharmacopeial monograph revision notices from USP, EP, and ChP. Bottom-up capacity estimates from Shaanxi and Murcia processing clusters were triangulated against top-down demand projections from pharmaceutical and cosmetics end-use segments.
Historical reference periods anchored the forecast window to observed supercritical CO2 extraction adoption curves and REACH compliance investment timelines across European botanical extract processors. Segmentation dimensions modeled include product format, purity grade tier, end-use industry, source material, and regional regulatory cluster. CAGRs were derived from slope analysis of installed extraction capacity expansion against qualified pharmaceutical customer adoption rates. Industry-specific forecast inputs incorporated NMPA botanical drug registration pipeline data and EMA herbal medicine guideline revision schedules.
Revisions become necessary when EMA pharmacopeial monograph specifications diverge further from USP or ChP standards, when climate events disrupt rosemary cultivation in Mediterranean Spain or Shaanxi province, or when supercritical CO2 technician scarcity constrains capacity expansion below demand growth. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Abierixin Market
Specialty Chemicals
Acesulfame Potassium Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
Copovidone Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
Glucono Delta Lactone Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Global Flash Chromatography Market
Specialty Chemicals
Solar Cell Front Side Silver Paste Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Natural Phytosphingosine Market
Specialty Chemicals
Croscarmellose Sodium Market