
 Snow Removal Equipment Market | 2026-2036
Snow Removal Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Snow Removal Equipment Market Insights
Equipment leasing and municipal fleet-as-a-service programs are reshaping competitive dynamics in snow removal equipment procurement. The Toro Company leverages its dealer network density to capture recurring municipal contracts across snow-belt states. Douglas Dynamics sustains market presence through specialized truck-mounted plow systems engineered for commercial-grade durability. Ariens Company anchors its position in residential segments with compact snow blower platforms optimized for suburban property footprints.
Snow removal equipment encompasses mechanized systems designed to displace, transport, or thermally eliminate accumulated snow and ice from surfaces, typically employing auger-fed impeller mechanisms, moldboard hydraulics, or radiant heat transfer with operational capacities spanning 20 inches to 16 feet of clearing width. Gas-powered technology dominates current municipal and commercial installations due to torque requirements and runtime demands in sub-zero conditions, though battery-operated platforms represent the fastest-expanding technology segment as lithium-ion energy density improves and total cost of ownership calculations shift. Snow plows command the largest product-type revenue pool given attachment versatility across vehicle classes, while snow melters capture premium margins in airport and healthcare campus applications where immediate surface restoration is critical.
EPA Tier 4 Final standards constrain diesel-driven equipment configurations, compelling manufacturers to certify alternative powertrains or absorb after-treatment costs that alter price positioning in municipal bids. OSHA winter hazard protocols and FAA airport surface condition reporting requirements create compliance-driven replacement schedules that insulate baseline demand from pure discretionary cycles. Stakeholders must monitor battery cold-weather performance warranties and charging infrastructure deployment rates as these factors determine the pace of technology transition in high-volume fleet segments.
Market Dynamics
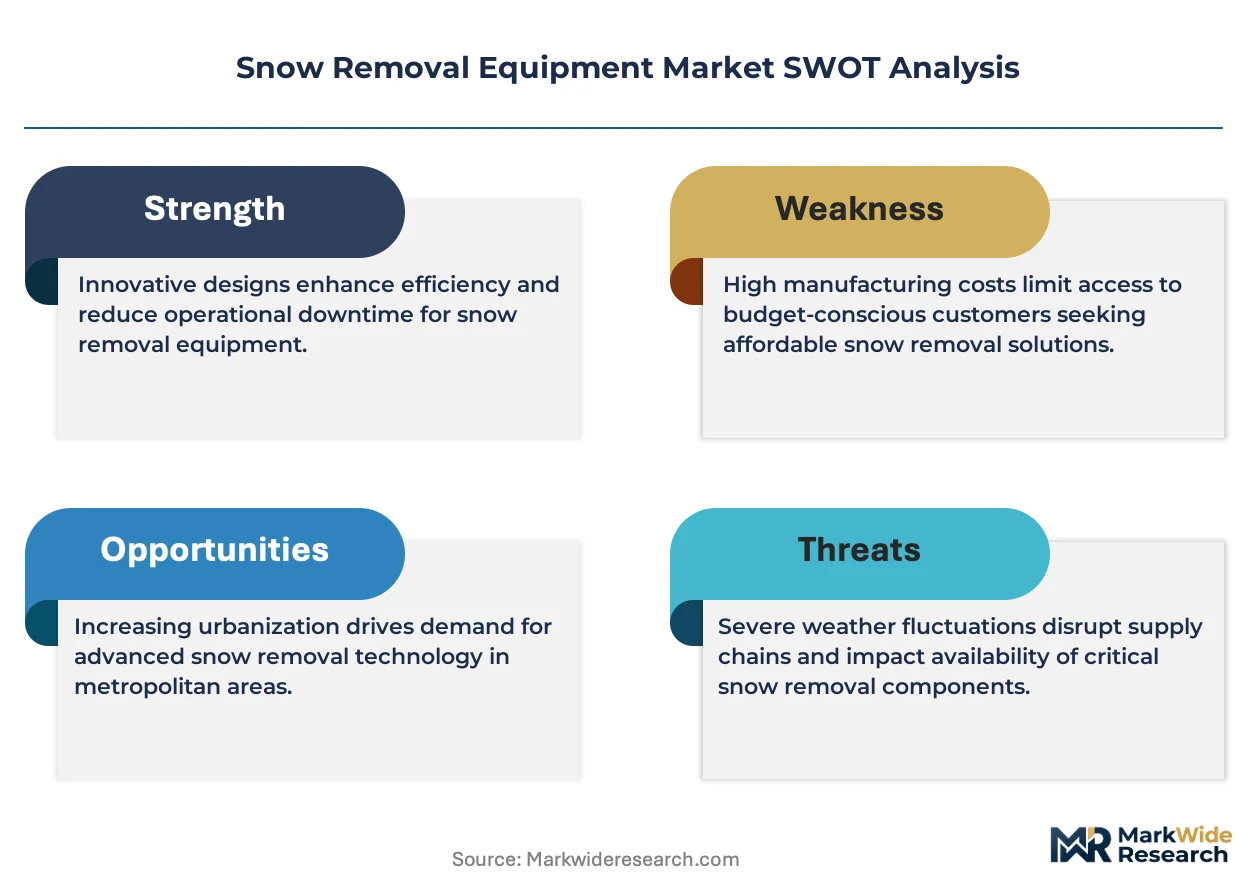
EPA Tier 4 Final emissions standards are forcing diesel equipment manufacturers toward electrification, compressing product development cycles and redrawing competitive boundaries between established combustion specialists and battery platform entrants.
Growth Catalysts
- OSHA Winter Hazard Protocols:Federal workplace safety mandates in the United States trigger compliance-driven replacement schedules for municipal fleets, insulating baseline demand from discretionary budget cycles.
- Airport Surface Condition Reporting:FAA requirements for immediate runway restoration sustain premium demand for high-capacity snow melters across North American aviation infrastructure.
- Lithium-Ion Energy Density Improvements:Advances in cold-weather battery chemistry are expanding operational viability of electric platforms into sub-zero municipal deployment scenarios previously reserved for combustion engines.
Market Restraints
- After-Treatment Cost Burden:EPA Tier 4 Final compliance adds diesel particulate filters and selective catalytic reduction systems that inflate municipal bid prices and compress manufacturer margins.
- Charging Infrastructure Gaps:Limited DC fast-charging networks across the Upper Midwest and rural Northeast corridors constrain electric fleet conversion timelines for dispersed municipal operations.
- Runtime Physics:Battery capacity degradation in sustained sub-zero conditions creates operational anxiety among fleet managers responsible for continuous storm response coverage.
Strategic Opportunities
- Telematics-Enabled Fleet-as-a-Service:Outcome-based municipal contracts linking uptime guarantees to payment terms are opening recurring revenue streams for equipment-as-a-service providers.
- Airport and Healthcare Campus Snow Melters:Immediate surface restoration requirements at critical infrastructure sites command premium pricing and shorter replacement cycles than general municipal equipment.
- Residential Battery Platform Expansion:Suburban property footprints in snow-belt states present conversion potential as homeowners seek quieter, lower-maintenance alternatives to gas-powered blowers.
Industry Challenges
- Electrification Skill Shortages:Municipal maintenance departments face gaps in high-voltage system diagnostics and battery thermal management training.
- Dual Certification Timelines:Manufacturers must simultaneously validate EPA Tier 4 Final compliance for remaining diesel SKUs and cold-weather performance warranties for emerging electric platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snow Removal Equipment Market |
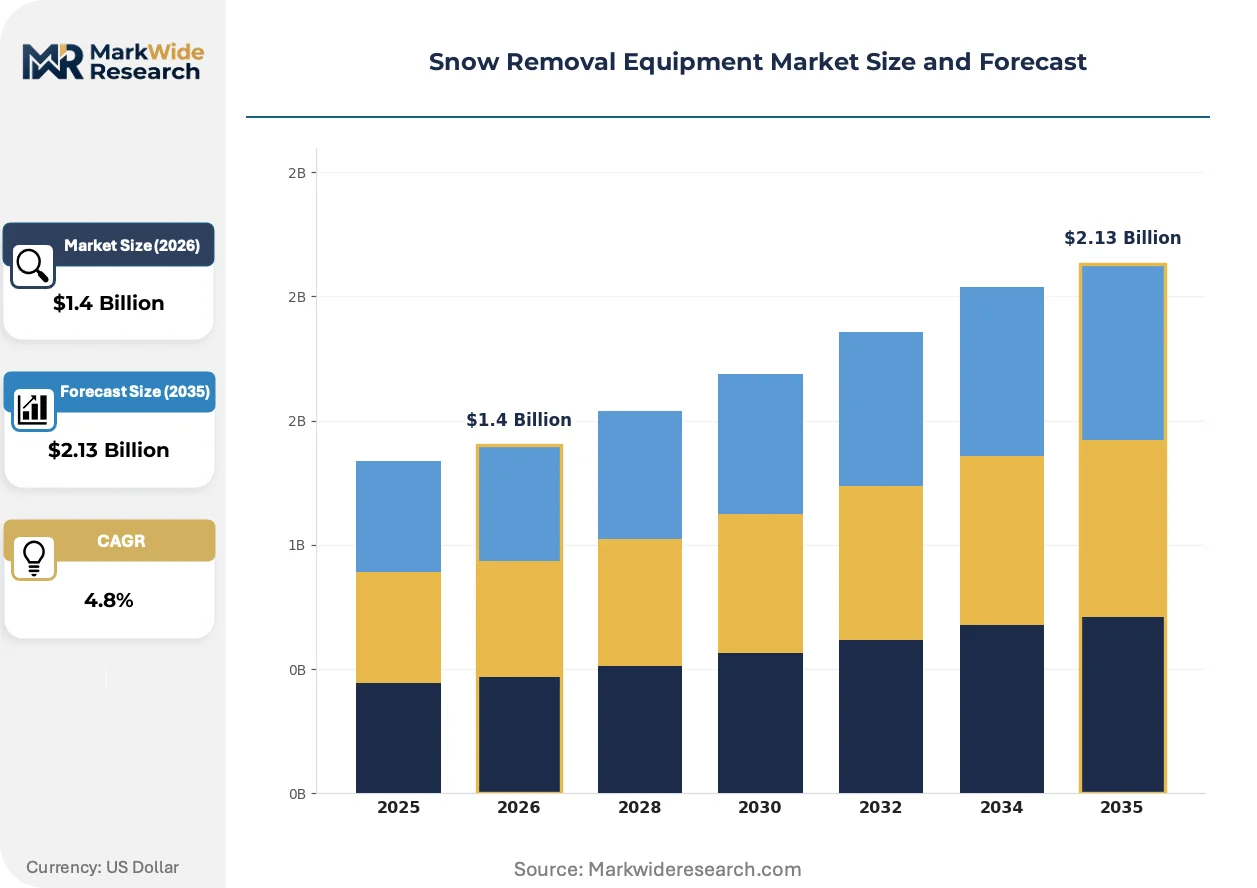
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
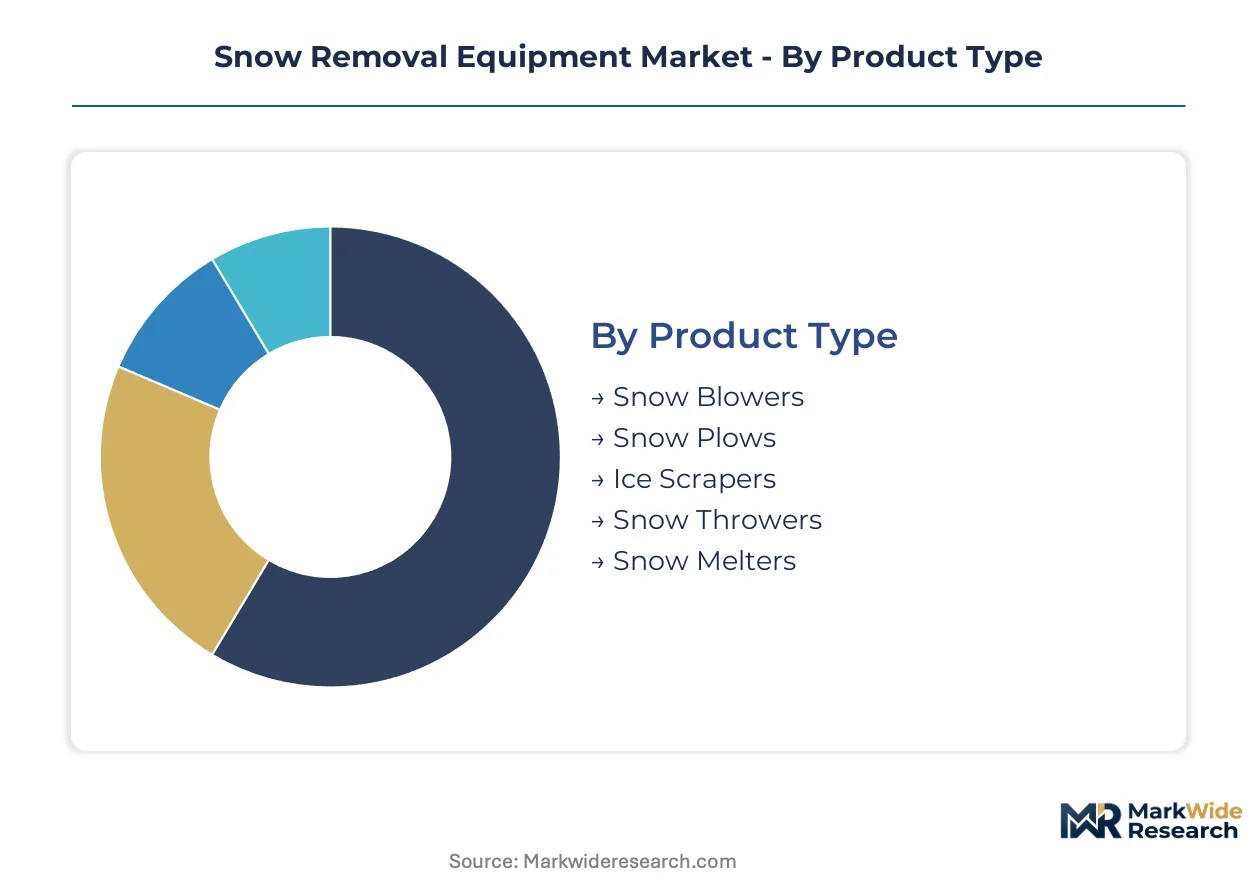
| Segmentation | Product Type: Snow Blowers, Snow Plows, Ice Scrapers, Snow Throwers, Snow Melters Technology: Gas-Powered, Electric-Powered, Battery-Operated, Hydraulic, Diesel-Driven Application: Residential Properties, Commercial Complexes, Municipalities, Construction Sites, Airports End User: Facility Management Firms, Road Maintenance Services, Rental Agencies, Property Managers |
| Companies Covered | The Toro Company, Ariens Company, Oshkosh Corporation, Douglas Dynamics, Husqvarna, Alamo Group, Team Eagle, M-B Companies, Boschung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snow Removal Equipment Market Trends and Innovations
Electrification, predictive maintenance integration, and procurement model restructuring are converging to compress equipment lifecycles and redistribute value capture across the supply chain.
Autonomous snow-clearing platforms equipped with LiDAR mapping and GPS-guided path optimization are rendering obsolete manual operator dependency for repetitive clearing routes. Airport authorities in Minnesota and Wisconsin are piloting these systems for overnight runway maintenance. The technology is compressing labor cost structures and enabling 24-hour operational coverage without shift rotation penalties.
EPA Tier 4 Final standards have eliminated off-road diesel engine configurations below 25 horsepower, forcing manufacturers to certify battery-electric alternatives or absorb after-treatment costs that alter municipal bid competitiveness. The regulation most acutely affects compact utility vehicle attachments where engine downsizing previously dominated cost engineering. Manufacturers are responding with modular battery packs swappable across equipment classes to amortize certification investments.
Municipal procurement departments are consolidating vendor relationships through multi-year fleet management agreements that bundle equipment, maintenance, and uptime insurance. Traditional equipment distributors in Michigan and New York are ceding margin to integrated service providers capable of guaranteeing storm-response availability. The shift is most visible in counties with aging internal maintenance capacity and constrained mechanic staffing.
Snow Removal Equipment Market Segmentation
Snow removal equipment procurement varies sharply across use cases, with airport and municipal fleets demanding uptime guarantees that reshape after-sales service economics. Residential and commercial segments prioritize acquisition cost over lifecycle support, fragmenting vendor engagement models across the market.
Product Type:
After-sales service intensity diverges dramatically across product categories, with snow melters requiring continuous thermal system calibration while blowers need seasonal blade replacement programs.
- Snow Blowers:Auger-fed impeller mechanisms with clearing widths from 20 inches to 36 inches dominate residential and light commercial duty cycles. Demand clusters in the Upper Midwest where suburban property footprints sustain replacement cycles every 7-10 years, though EPA small-engine emissions standards are compressing gas-powered model availability.
- Snow Plows:Moldboard hydraulic systems attach across vehicle classes from half-ton pickups to heavy municipal trucks, commanding the largest revenue pool given versatility. Minnesota and Wisconsin counties drive replacement demand through fleet modernization bonds, with hydraulic cylinder rebuild programs generating recurring service revenue.
- Ice Scrapers:Carbide-edged blades mounted on wheel loaders and graders for hard-packed removal. Municipal road maintenance departments in the Northeast specify cutting-edge replacement intervals.
- Snow Throwers:Single-stage electric and gas units for light accumulation under 8 inches. Home improvement retailers in snow-belt states stock seasonal inventory.
- Snow Melters:Thermal elimination systems processing 20-600 tons per hour for immediate surface restoration. Airports and healthcare campuses command premium pricing and 24-hour service contracts.
By volume, snow blowers lead. By growth pace, snow melters are ahead.
Technology:
Cost tier stratification separates premium battery platforms from economy gas configurations, with mid-tier diesel equipment absorbing after-treatment compliance burdens.
- Gas-Powered:Small-displacement engines under 25 horsepower dominate residential blower segments with established dealer service networks. EPA Tier 4 Final exemptions below 25hp preserve this tier's municipal compact utility attachment presence, though inventory is thinning.
- Battery-Operated:Lithium-ion packs with cold-weather chemistry warranties represent the fastest-expanding technology segment. Suburban homeowners in Michigan and New York seek quieter operation and reduced maintenance, though runtime anxiety persists in sub-zero conditions.
- Electric-Powered:Corded systems limited to residential walkways and small driveways by power tether constraints. Property managers with predictable clearing zones specify these for noise-sensitive environments.
- Hydraulic:Fluid-power systems for commercial-grade plow and blower attachments. Fleet-as-a-service providers specify these for uptime guarantees.
- Diesel-Driven:Compression-ignition engines above 25 horsepower for heavy municipal and airport equipment. After-treatment costs for Tier 4 Final compliance are compressing bid competitiveness against emerging battery alternatives.
By installed base, gas-powered systems dominate. By expansion trajectory, battery-operated platforms are climbing the fastest.
Application:
Customer type determines procurement model, with municipalities favoring multi-year fleet agreements and residential buyers transacting through seasonal retail channels.
- Municipalities:County and city fleets with 24-hour storm response mandates. Ohio and Pennsylvania local governments bundle equipment, maintenance, and uptime insurance through integrated service contracts.
- Airports:Runway condition reporting requirements under FAA regulations sustain premium demand for high-capacity melters and rapid-deployment plow trains. Minneapolis-St. Paul and Detroit Metro anchor this segment.
- Residential Properties:Single-family and multi-unit dwellings with clearing footprints under 2 acres. Big-box retailers in Illinois and Massachusetts drive seasonal sales peaks.
- Commercial Complexes:Retail parking lots, office parks, and industrial facilities with liability-driven clearing schedules. Facility management firms specify equipment with operator cab comfort for extended shifts.
- Construction Sites:Temporary winter access roads and laydown yards. Rental agencies supply this episodic demand.
By unit shipments, residential properties lead. By contract value, airports are expanding most quickly.
End User:
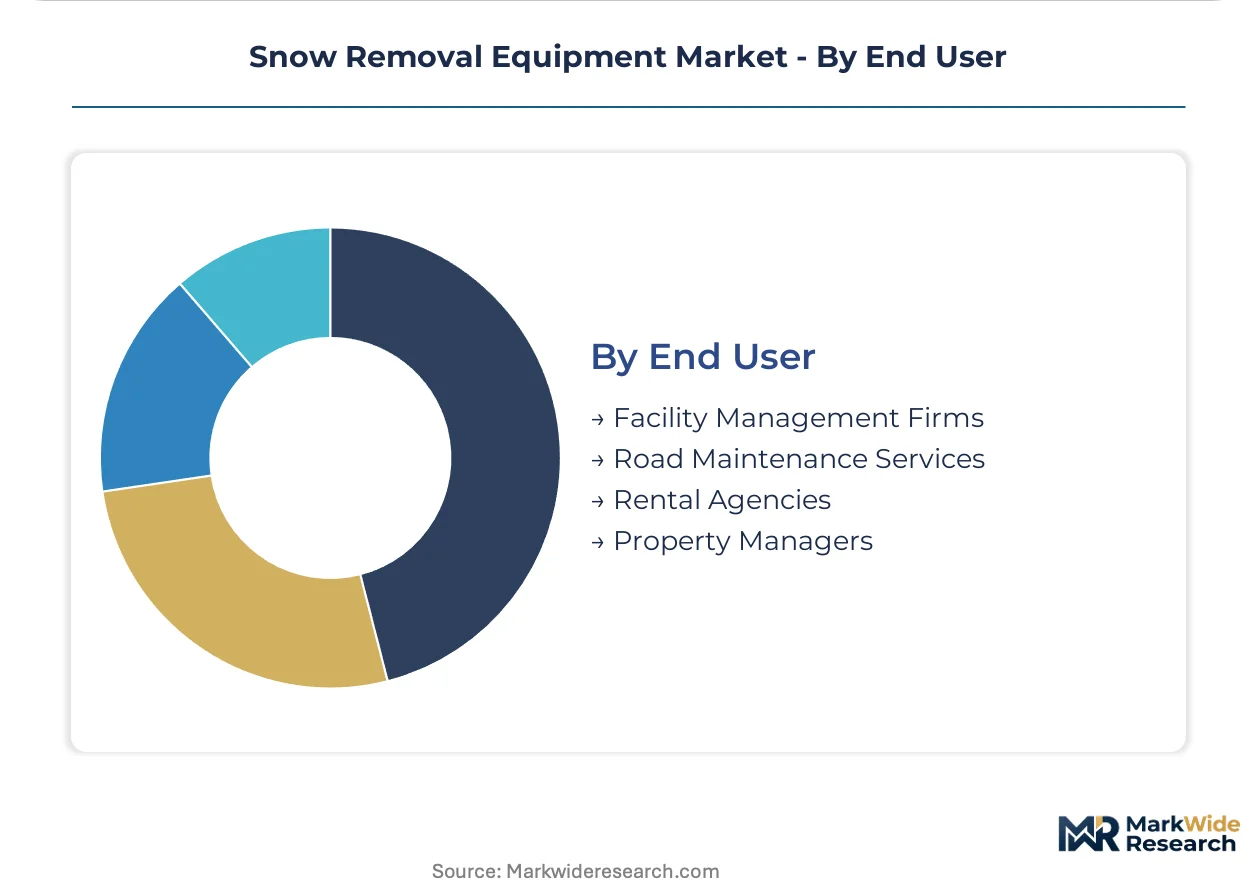
Supply concentration varies by end user sophistication, with road maintenance services demanding factory-authorized technicians and rental agencies accepting third-party rebuilds.
- Road Maintenance Services:State DOT contractors and county highway departments with certified mechanic staffing. Wisconsin and Michigan firms specify telematics-enabled equipment for remote diagnostics.
- Facility Management Firms:Multi-site property operators consolidating vendor relationships. These buyers prioritize parts availability over initial acquisition cost.
- Property Managers:Residential and commercial building operators with seasonal contractor relationships. Smaller portfolios transact through dealer financing programs.
- Rental Agencies:Short-term equipment lessors with high utilization targets and accelerated depreciation schedules. These users drive demand for simplified control interfaces.
By fleet scale, road maintenance services lead. By procurement flexibility, rental agencies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Snow removal equipment flows from manufacturing centers in the Upper Midwest toward import-dependent markets with limited winter infrastructure. Trade patterns concentrate in North America and Northern Europe where seasonal snowfall sustains equipment turnover cycles.
United States
Municipal fleet modernization bonds in Minnesota and Wisconsin drive replacement demand for truck-mounted plow systems. EPA Tier 4 Final standards compress diesel equipment availability below 25 horsepower, accelerating battery-electric trials in county highway departments. The Minneapolis-St. Paul metro anchors airport-grade snow melter procurement for runway condition compliance.
Canada
Provincial transportation ministries in Ontario and Quebec maintain multi-year equipment agreements with uptime guarantees for Trans-Canada Highway maintenance. Environment Canada winter severity indices trigger accelerated replacement schedules in Atlantic provinces. Toronto Pearson and Montreal-Trudeau airports sustain premium demand for rapid-deployment runway clearing systems.
Germany
Bavarian municipalities invest in compact electric utility vehicles for pedestrian zone clearing under stricter urban emissions zones. The KBA enforces cold-start emission protocols that disadvantage older diesel fleets. Stuttgart and Munich airport authorities pilot autonomous guidance systems for overnight apron maintenance.
Sweden
Arctic climate conditions in Norrbotten and Västerbotten counties sustain demand for extreme-duty hydraulic attachments. The Swedish Transport Administration mandates telematics integration for state road maintenance contractor equipment. Volvo Group's Gothenburg engineering cluster influences Nordic fleet specification standards.
Japan
Heavy snowfall corridors along the Sea of Japan coast in Niigata and Aomori prefectures sustain compact snow blower replacement cycles. METI subsidies for battery-powered agricultural and municipal equipment extend to snow removal platforms. Sapporo's municipal engineering department specifies low-noise equipment for dense urban clearing operations.
Snow Removal Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying hydraulic cylinders, moldboard assemblies, and auger mechanisms to final equipment assemblers. The vendor base concentrates among established combustion-era manufacturers and emerging battery-platform entrants, creating tiered competition across price-performance segments. Two strategic archetypes dominate: vertically integrated full-line producers and specialized attachment fabricators. Competitive moves center on fleet-as-a-service contract consolidation and cold-weather battery warranty certification programs.
Among North American equipment specialists, The Toro Company, Douglas Dynamics, and Ariens Company occupy distinct positioning archetypes. Toro leverages dealer network density across snow-belt states. Douglas Dynamics represents the specialized attachment fabricator model. Ariens Company anchors residential-tier positioning. These three exemplify how incumbent combustion-era players navigate electrification transitions while defending municipal contract relationships.
| Leading Market Players |
|---|
| The Toro Company |
| Ariens Company |
| Oshkosh Corporation |
| Douglas Dynamics |
| Husqvarna |
| Alamo Group |
| Team Eagle |
| M-B Companies |
| Boschung |
| Others |
Pricing and Supply Chain Analysis
Gothenburg's engineering cluster anchors Nordic hydraulic component production, concentrating moldboard cylinder and auger mechanism capacity among Tier 1 suppliers who command pricing leverage over downstream equipment assemblers seeking cold-weather certification guarantees.
Pricing Analysis
Industrial OEM buyers anchor municipal fleet procurement through multi-year fleet-as-a-service contracts that bundle equipment, maintenance, and uptime insurance. Three-tier pricing structure across premium, standard, and economy levels separates EPA Tier 4 Final-certified diesel platforms from emerging battery-electric alternatives and compact utility attachments. Pricing pressure stems from after-treatment cost absorption for remaining combustion SKUs as manufacturers dual-certify electric platforms. Road maintenance services exhibit highest price sensitivity due to constrained municipal budgets, while airport authorities prioritize performance guarantees over acquisition cost.
Supply Chain Analysis
Export control regimes on advanced lithium-ion cell technology and high-grade hydraulic steel limit component flows from select Asian manufacturing hubs to North American equipment assemblers. Supply concentrates in China for battery cell production, Germany for precision hydraulic systems, and the Upper Midwest for final assembly integration. Raw material dependencies include lithium carbonate, high-strength alloy steel, and specialized cold-weather lubricants. Single-source vulnerability persists in solid-state battery chemistry patents held by concentrated East Asian licensors. Distribution runs through authorized dealer networks with factory-trained technician certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated service providers as municipal procurement departments consolidate vendor relationships and cede traditional distributor margin to uptime-guarantee contractors.
For Market Incumbents: Insulate municipal contract retention through backward integration into battery thermal management systems and in-house production of swappable modular packs that amortize certification costs across equipment classes. Deepen channel control by acquiring regional service providers with EPA-certified technician staffing in Michigan and Wisconsin counties facing mechanic shortages. Battery-platform entrants threaten attachment-fabricator margins through direct municipal outreach. For New Entrants and Emerging Players: Establish a beachhead in residential battery-powered blower segments where suburban homeowners in snow-belt states seek quieter alternatives and dealer switching costs remain low. Target facility management firms with multi-site property portfolios that prioritize parts availability over brand loyalty and lack incumbent service entanglements. Deploy direct-to-municipal pilot programs in counties with aging internal maintenance capacity. For Investors and Strategic Acquirers: Long-term, this sits as a fleet-as-a-service consolidation play because outcome-based contracts are redistributing value capture from equipment manufacturers to integrated uptime providers with telematics capabilities. Acquisition targets should exhibit dense dealer network coverage in the Upper Midwest or proprietary cold-weather battery warranty programs. Monitor DC fast-charging infrastructure deployment rates across rural Northeast corridors as the inflection signal for electric fleet conversion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Weather Battery Certification Program | EPA Tier 4 Final compression creates first-mover advantage for validated electric platforms in municipal bids. |
| Telematics-Enabled Fleet-as-a-Service Launch | Outcome-based contracts with Ohio and Pennsylvania municipalities capture recurring revenue from aging highway departments. |
| Backward Integration into Hydraulic Cylinders | In-house production of moldboard actuators defends margin against specialized attachment fabricators in Wisconsin. |
| Airport Snow Melter Service Partnership | Minneapolis-St. Paul and Detroit Metro runway condition mandates sustain premium pricing and 24-hour service contracts. |
| Residential Battery Platform Expansion | Suburban property footprints in Michigan and New York present conversion potential as gas-powered inventory thins. |
Research Methodology
Initial hypotheses were tested against primary input from municipal fleet managers, aftermarket service directors, and battery platform engineering leads and refined through secondary validation against EPA certification databases, FAA airport surface condition reporting guidelines, and municipal bond prospectuses for fleet modernization programs. Bottom-up equipment shipment data triangulated with top-down municipal expenditure tracking across the analysis window.
Demand-supply balance modeling segmented the market by product type, technology platform, application intensity, and regional snowfall severity indices throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, regulatory compliance deadline clustering, and battery chemistry advancement trajectories. Cold-weather performance warranty terms and charging infrastructure deployment curves served as electric adoption scenario inputs.
Sensitivities concentrate around lithium-ion cell supply constraints, EPA enforcement variance on Tier 4 Final timelines, and municipal budget volatility tied to winter storm frequency. Forecasts reflect documented assumptions on battery energy density improvement curves and fleet-as-a-service contract penetration rates. Material shifts in federal infrastructure funding allocation or breakthrough solid-state battery commercialization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Tower Crane Market
Construction Equipment
Garage Equipment Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Cranes Rental Market
Construction Equipment
Thermal Spray Equipment Market
Construction Equipment
Welding Equipment and Consumables Market
Construction Equipment
Sandblast Nozzle Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
Casting Equipment Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Construction Helmet Market
Construction Equipment
Europe Construction Equipment Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Automatic Clay Brick Making Machine Market