
 Sandblast Nozzle Market | 2026-2036
Sandblast Nozzle Market Size, Share, and Industry Trends Forecast 2026-2036
Sandblast Nozzle Market Analytics
Preventive maintenance contracts for blast equipment fleets is restructuring how nozzle vendors monetize hardware relationships. Kennametal Inc. leverages captive carbide powder production to control tungsten supply costs across North American distribution. Clemco Industries Corporation anchors its position through factory-authorized service networks that lock in replacement part pull-through. Graco Inc. competes by bundling IoT-enabled flow monitors with premium nozzle lines.
A sandblast nozzle is a wear-resistant orifice component, typically machined from tungsten carbide, boron carbide, or ceramic composites, that accelerates abrasive media through a converging-diverging Venturi profile to strip surface contaminants or prepare substrates for coating adhesion. Venturi-type configurations dominate volume due to superior abrasive velocity efficiency in high-pressure systems, while ceramic segments command margin premiums in precision aerospace deburring applications where dimensional stability under thermal cycling matters. Surface preparation applications absorb the largest share of replacement demand, though coating removal workflows in maritime yards are gaining traction as environmental rules restrict open abrasive blasting.
OSHA silica exposure limits and EPA NESHAP standards for abrasive blasting operations compel end users to specify sealed-system nozzles with enhanced dust containment interfaces, directly elevating product certification requirements. The EU F-Gas Regulation and REACH substance restrictions further constrain material choices for European suppliers, pushing R&D toward boron carbide alternatives. Stakeholders must monitor how regional enforcement variance between EPA state implementation plans and EU member-level occupational rules reshapes procurement specifications before committing to capacity expansions.
Market Dynamics
Preventive maintenance contracts for blast equipment fleets are restructuring how nozzle vendors monetize hardware relationships, shifting revenue from transactional replacement sales toward recurring service pull-through. This contractual pivot concentrates purchasing authority within fleet operators and compresses vendor margins on standalone nozzle sales.
Growth Catalysts
- OSHA Silica Exposure Limits:The US Occupational Safety and Health Administration's tightened permissible exposure limits for respirable crystalline silica compel end users to specify sealed-system nozzles with enhanced dust containment interfaces, directly elevating product certification requirements across surface preparation workflows.
- Aerospace MRO Expansion:Maintenance, repair, and overhaul operations in Germany are expanding nozzle replacement schedules as commercial aviation fleet utilization rebounds, driving precision-grade boron carbide consumption for thermal cycling stability in deburring applications.
- Venturi Configuration Efficiency:Converging-diverging Venturi profiles dominate volume due to superior abrasive velocity efficiency in high-pressure systems, with petrochemical corridor operators along the United States Gulf Coast standardizing on these geometries for coating adhesion preparation.
Market Restraints
- Tungsten Carbide Supply Concentration:REACH compliance across Europe tightens material composition rules for tungsten carbide suppliers, constraining feedstock availability and elevating input costs for manufacturers dependent on EU-sourced powder.
- Ceramic Brittleness Limitation:Ceramic nozzle segments command margin premiums in precision aerospace applications but suffer from fracture susceptibility under impact loading, restricting their penetration into heavy-debris maritime and infrastructure blasting environments.
- Boron Carbide Substitution Pressure:Environmental rules restricting open abrasive blasting in maritime yards accelerate interest in alternative abrasive media that degrade nozzle geometries differently, compressing replacement intervals for traditional carbide configurations.
Strategic Opportunities
- IoT-Enabled Flow Monitoring:Integration of real-time abrasive flow sensors with nozzle assemblies creates predictive maintenance revenue streams, with industrial fleet operators in the US Gulf Coast corridor piloting subscription-based wear monitoring.
- EU F-Gas Regulation Tailwind:The European Union's fluorinated gas phase-down mandates accelerate investment in dry ice blasting alternatives, opening nozzle design requirements for CO2 pellet acceleration geometries that diverge from conventional abrasive specifications.
- Factory-Authorized Service Networks:Captive distribution through certified service channels locks in replacement part pull-through, with equipment OEMs expanding direct-to-operator maintenance contracts that bundle nozzle refresh cycles with compressor overhauls.
Industry Challenges
- Welder-Blaster Skill Convergence:Surface preparation contractors face acute shortages of technicians certified in both abrasive blasting and confined-space welding, complicating workforce deployment for integrated coating removal and reapplication projects.
- REACH Certification Timelines:European nozzle suppliers encounter extended substance notification periods for novel boron carbide composites, delaying product launches by twelve to eighteen months relative to North American regulatory pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandblast Nozzle Market |
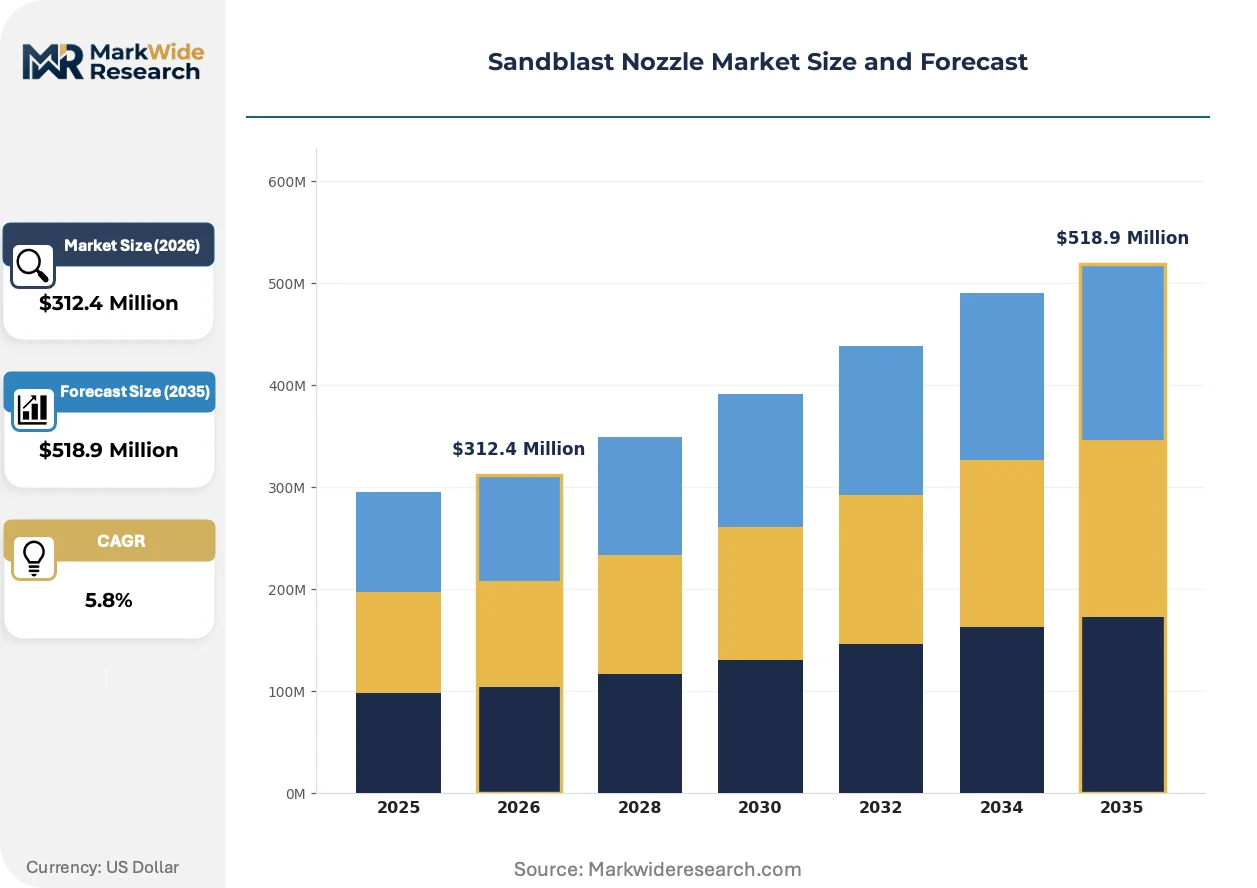
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Venturi, Abrasive, Flexible, Ceramic Application: Surface Preparation, Coating Removal, Deburring, Rust Removal Material: Steel, Aluminum, Tungsten Carbide, Plastic End User: Construction, Manufacturing, Automotive, Aerospace |
| Companies Covered | Kennametal Inc., Clemco Industries Corporation, Graco Inc., Airblast B.V., Marco International Group, Sponge-Jet Inc., Dover Corporation, AGSCO Corporation, BlastOne International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandblast Nozzle Market Evolving Landscape
Material science advances and embedded sensor integration are actively reshaping nozzle design priorities, with durability metrics giving way to predictive lifecycle management and regulatory compliance by design.
Boron carbide nozzle inserts are electrifying competitive positioning in precision aerospace deburring applications where dimensional stability under thermal cycling determines process yield. Tier-one MRO providers in Germany and France are standardizing on these configurations for turbine blade refurbishment, compressing tungsten carbide's historical dominance in high-value segments.
REACH substance restrictions are constraining material choices for European suppliers, pushing research and development toward boron carbide alternatives and novel ceramic matrix composites that satisfy ECHA notification requirements. German tungsten carbide processors face elevated compliance costs, while French and Italian nozzle assemblers accelerate qualification of non-carbide feedstocks for maritime coating removal workflows.
Equipment-as-a-service contracting is consolidating purchasing authority within fleet operators and compressing vendor margins on standalone nozzle sales. Maritime yards in the Netherlands and Belgium are unbundling after-sales service from hardware procurement, with operators negotiating all-inclusive blasting cost-per-square-meter agreements that internalize nozzle consumption risk.
Sandblast Nozzle Market Segmentation
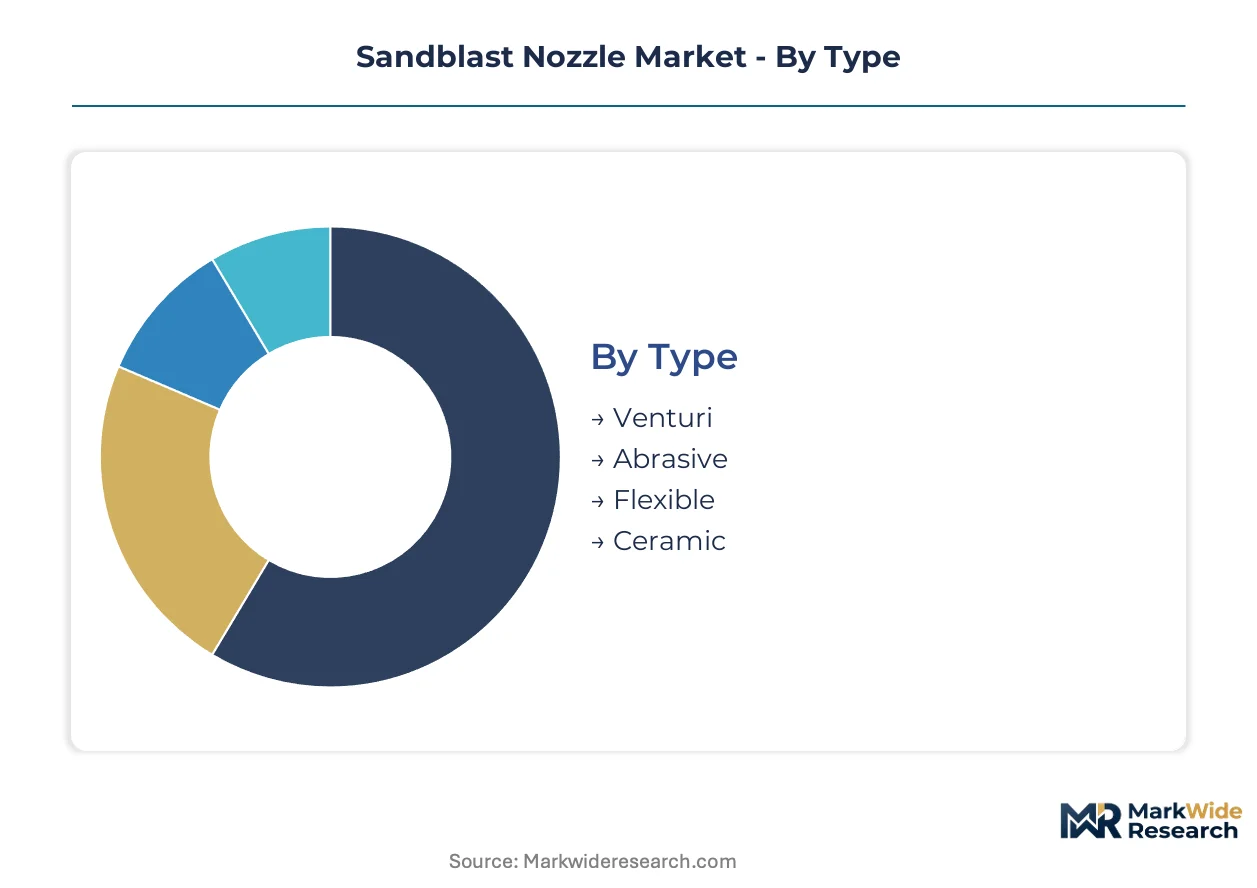
Sandblast nozzle procurement specifications diverge sharply across end-use environments, with OSHA silica compliance, REACH substance restrictions, and aerospace thermal cycling requirements fragmenting product standards. Vendors must maintain parallel certification portfolios to serve construction contractors, MRO facilities, and petrochemical operators under divergent regulatory frameworks.
Type:
OSHA and EPA NESHAP certifications dominate specification sheets for sealed-system configurations, while aerospace deburring applications require AS9100 traceability for dimensional stability claims.
- Venturi:Converging-diverging profiles machine tungsten carbide or boron carbide into geometries that accelerate abrasive media to supersonic velocities. Petrochemical corridor operators along the United States Gulf Coast standardize on these configurations for coating adhesion preparation, with OSHA silica exposure limits mandating enhanced dust containment interfaces.
- Ceramic:Precision-machined oxide or nitride ceramics deliver dimensional stability under thermal cycling for turbine blade refurbishment workflows. German aerospace MRO providers specify these for deburring applications where process yield depends on orifice consistency, though fracture susceptibility under impact loading restricts penetration into maritime environments.
- Abrasive:Straight-bore geometries suit low-pressure systems with expendable media.
- Flexible:Elastomer-jacketed configurations navigate confined-space geometries in infrastructure maintenance.
Leading the category by volume: Venturi. Growing fastest: Ceramic.
Application:
Cost tier stratification separates commodity surface preparation from precision coating removal, with per-nozzle pricing spreading across an order of magnitude based on certification burden and material grade.
- Surface Preparation:High-volume replacement demand concentrates in construction and maritime yards where abrasive consumption rates drive refresh cycles. EPA NESHAP standards for abrasive blasting operations compel sealed-system specifications with enhanced dust containment, elevating procurement costs for contractors in regulated jurisdictions.
- Coating Removal:Maritime yards in the Netherlands and Belgium are unbundling after-sales service from hardware procurement, negotiating all-inclusive blasting cost-per-square-meter agreements that internalize nozzle consumption risk under environmental rules restricting open abrasive blasting.
- Deburring:Precision aerospace applications command margin premiums.
- Rust Removal:Infrastructure maintenance drives seasonal demand spikes.
Surface Preparation absorbs the largest replacement volume. Coating Removal is expanding most quickly as environmental restrictions tighten.
Material:
Supply concentration in tungsten carbide powder processing creates cost tier differentiation, with REACH compliance timelines extending twelve to eighteen months for novel boron carbide composites.
- Tungsten Carbide:Cobalt-bonded cemented carbides dominate high-pressure applications through superior wear resistance against angular abrasive media. REACH compliance across Europe tightens material composition rules for suppliers, constraining feedstock availability and elevating input costs for manufacturers dependent on EU-sourced powder.
- Boron Carbide:Third-hardest known material delivers extended service life in precision deburring where thermal cycling stability determines process yield. German and French nozzle assemblers accelerate qualification of this feedstock for maritime coating removal workflows as ECHA notification requirements displace traditional carbide specifications.
- Steel:Entry-level configurations suit low-abrasion cleaning applications.
- Aluminum:Lightweight geometries serve portable equipment in construction.
- Plastic:Disposable inserts reduce cross-contamination in specialized finishing.
Tungsten Carbide retains volume leadership. Boron Carbide is gaining share fastest on regulatory tailwinds.
End User:
Customer type determines procurement authority concentration, with fleet operators consolidating purchasing through preventive maintenance contracts and compressing vendor margins on standalone sales.
- Aerospace:MRO operations in Germany are expanding nozzle replacement schedules as commercial aviation fleet utilization rebounds, driving precision-grade boron carbide consumption. Tier-one providers standardize on ceramic and boron carbide configurations for turbine blade refurbishment, compressing tungsten carbide's historical dominance in high-value segments.
- Manufacturing:Industrial fleet operators in the US Gulf Coast corridor pilot subscription-based wear monitoring, integrating IoT-enabled flow sensors with nozzle assemblies to create predictive maintenance revenue streams.
- Construction:Project-based procurement dominates with price-sensitive specifications.
- Automotive:OEM surface treatment lines drive standardized refresh cycles.
Manufacturing leads by installed base volume. Aerospace posts the steepest expansion trajectory on MRO recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Gulf Coast petrochemical corridor generates concentrated nozzle demand from coating adhesion preparation workflows, with OSHA silica exposure limits mandating sealed-system specifications across Texas and Louisiana refining clusters.
United States
Gulf Coast petrochemical operators standardize on Venturi configurations for high-pressure surface preparation, while EPA NESHAP standards for abrasive blasting operations compel enhanced dust containment interfaces. Houston-area fleet operators pilot IoT-enabled flow monitoring subscriptions, integrating predictive maintenance sensors with nozzle assemblies.
Germany
Aerospace MRO facilities in Hamburg and Frankfurt expand boron carbide nozzle replacement schedules as commercial aviation fleet utilization rebounds. REACH compliance tightens material composition rules for tungsten carbide suppliers, constraining feedstock availability from domestic powder processors.
Netherlands
Maritime yards in Rotterdam and Amsterdam unbundle after-sales service from hardware procurement, negotiating all-inclusive blasting cost-per-square-meter agreements. EU F-Gas Regulation phase-down mandates accelerate investment in dry ice blasting alternatives, opening nozzle design requirements for CO2 pellet acceleration geometries.
France
Turbine blade refurbishment operations in Toulouse and Paris standardize on ceramic and boron carbide configurations for precision deburring applications. ECHA notification requirements displace traditional carbide specifications, extending certification timelines for novel boron carbide composites.
Belgium
Antwerp port infrastructure maintenance drives seasonal demand spikes for coating removal workflows. Environmental rules restricting open abrasive blasting compress replacement intervals, with contractors internalizing nozzle consumption risk through outcome-based service contracts.
Sandblast Nozzle Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the sandblast nozzle supply base. Foundry-integrated carbide powder manufacturers maintain cost advantages through captive tungsten supply, while specialized nozzle assemblers rely on third-party feedstock procurement. Strategic archetypes separate into equipment OEMs with factory-authorized service networks, carbide specialists with backward-integrated powder operations, and technology bundlers integrating IoT sensors. Dominant competitive moves include preventive maintenance contract expansion and REACH-compliant material qualification programs.
Among North American industrial equipment providers, Kennametal Inc. and Graco Inc. exemplify divergent positioning archetypes. Kennametal represents the carbide-integrated model with in-house powder production capabilities. Graco occupies the technology-bundling tier, attaching digital monitoring solutions to premium hardware lines. Clemco Industries Corporation anchors the factory-authorized service network approach, locking replacement part pull-through through certified distribution channels.
| Leading Market Players |
|---|
| Kennametal Inc. |
| Clemco Industries Corporation |
| Graco Inc. |
| Airblast B.V. |
| Marco International Group |
| Sponge-Jet Inc. |
| Dover Corporation |
| AGSCO Corporation |
| BlastOne International |
| Others |
Value Network & Pricing Analysis
EU REACH substance restrictions gate both qualified boron carbide supply and premium-tier pricing access, compressing margins for vendors lacking ECHA-compliant feedstock while elevating certified nozzles to premium positioning. This environmental mandate fragments the supplier base into REACH-authorized processors commanding pricing power and non-compliant assemblers trapped in commodity tiers.
Pricing Analysis
Value-based pricing anchored to abrasive throughput uptime dominates the market, with petrochemical fleet operators paying premiums for nozzles certified to OSHA silica containment standards. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-registered boron carbide from REACH-constrained tungsten carbide and ungraded steel alternatives. Pricing pressure stems from maritime contractors internalizing nozzle consumption risk through outcome-based blasting contracts. Construction contractors exhibit highest price sensitivity, while aerospace MRO facilities prioritize thermal cycling yield over unit cost.
Supply Chain Analysis
Factory-authorized service networks handle fleet operator demand through captive distribution, locking replacement part pull-through. Powder processing concentrates in Germany, the United States, and China, with boron carbide sintering anchored in French and Italian ceramics corridors. Raw material flows draw from tungsten ore concentrates, cobalt bonding agents, and petroleum-derived carbon precursors. Single-source vulnerability runs through German tungsten carbide processors facing extended REACH notification timelines. Distribution runs through equipment OEM channels and specialized industrial distributors serving contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH-compliant material qualifications, forcing weaker players without ECHA-authorized feedstock access toward exit or acquisition. Regulatory compliance timelines function as the primary consolidation mechanism.
For Market Incumbents: Extend factory-authorized service networks into predictive maintenance subscriptions, bundling IoT-enabled wear monitoring with nozzle refresh cycles to lock in fleet operator relationships. Deepen backward integration into boron carbide powder processing to escape German tungsten supply constraints and capture REACH-driven margin expansion. Cement position against emerging technology bundlers by anchoring certified distribution channels. For New Entrants and Emerging Players: Direct-to-MRO digital platforms offer the lowest-friction entry path, bypassing entrenched distributor relationships serving established petrochemical corridors. Target dry ice blasting nozzle design for EU F-Gas Regulation tailwinds, where CO2 pellet acceleration geometries lack incumbent specialization. Pursue outcome-based contracting with Dutch and Belgian maritime yards unbundling hardware from service procurement. For Investors and Strategic Acquirers: REACH certification backlog clearance is the leading indicator that boron carbide-qualified assemblers will command sustained pricing power. Position for five-to-ten year holding periods around material science capabilities and regulatory authorization assets rather than volume scale. Monitor ECHA notification queue velocity as the inflection signal for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Carbide Powder | ECHA-authorized captive supply secures REACH-compliant feedstock independence from German processors. |
| IoT-Enabled Predictive Maintenance Launch | Real-time abrasive flow monitoring creates recurring revenue streams with US Gulf Coast fleet operators. |
| REACH Certification Acceleration Program | Novel composite qualification compresses twelve-to-eighteen month notification timelines for European market access. |
| Dry Ice Blasting Nozzle Development | CO2 pellet acceleration geometries capture EU F-Gas Regulation phase-down investment in Netherlands maritime yards. |
| Factory-Authorized Service Network Expansion | Certified distribution channels lock replacement part pull-through and compress standalone nozzle margins. |
Research Methodology
Multi-period observation of nozzle replacement cycle data, REACH certification timelines, and petrochemical fleet utilization rates anchored the trend analysis, supplemented by interviews with maintenance directors at Gulf Coast refineries, procurement leads at German aerospace MRO facilities, and aftermarket service heads at equipment OEMs. Secondary validation drew from EPA NESHAP enforcement records, ECHA substance notification databases, SEC filings of carbide powder processors, and customs trade data for tungsten concentrate flows. Bottom-up triangulation across end-use consumption patterns converged with top-down supply-side capacity assessments.
Input-output matrices mapped abrasive media throughput to nozzle wear rates across Venturi, ceramic, and boron carbide configurations over the projection horizon. Segmentation dimensions modeled include nozzle geometry type, material grade tier, end-use application, and regional regulatory cluster. CAGRs were derived from regression analysis of historical replacement intervals against fleet expansion trajectories. Forecast inputs incorporated OSHA silica enforcement variance across state implementation plans and EU member-level occupational rule adoption rates.
The model holds under stable REACH enforcement intensity and continued Gulf Coast petrochemical capacity expansion; deviation in ECHA notification processing speeds or F-Gas Regulation phase-down acceleration would shift boron carbide penetration trajectories. Forecasts reflect documented assumptions regarding abrasive media consumption patterns and fleet operator contract structuring preferences. Periodic stress-testing of base assumptions against regulatory enforcement variance and maritime environmental rule adoption is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Fixed Crane Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Hose End Sprayers Market
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
North America Construction Equipment Rental Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Robotic Total Stations (RTS) Market
Construction Equipment
Friction Stir Welding Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Baler Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
Tunnel Boring Machines Market