
 Middle East and Africa Rough Terrain Cranes Market | 2026-2036
Middle East and Africa Rough Terrain Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Rough Terrain Cranes Market Outlook
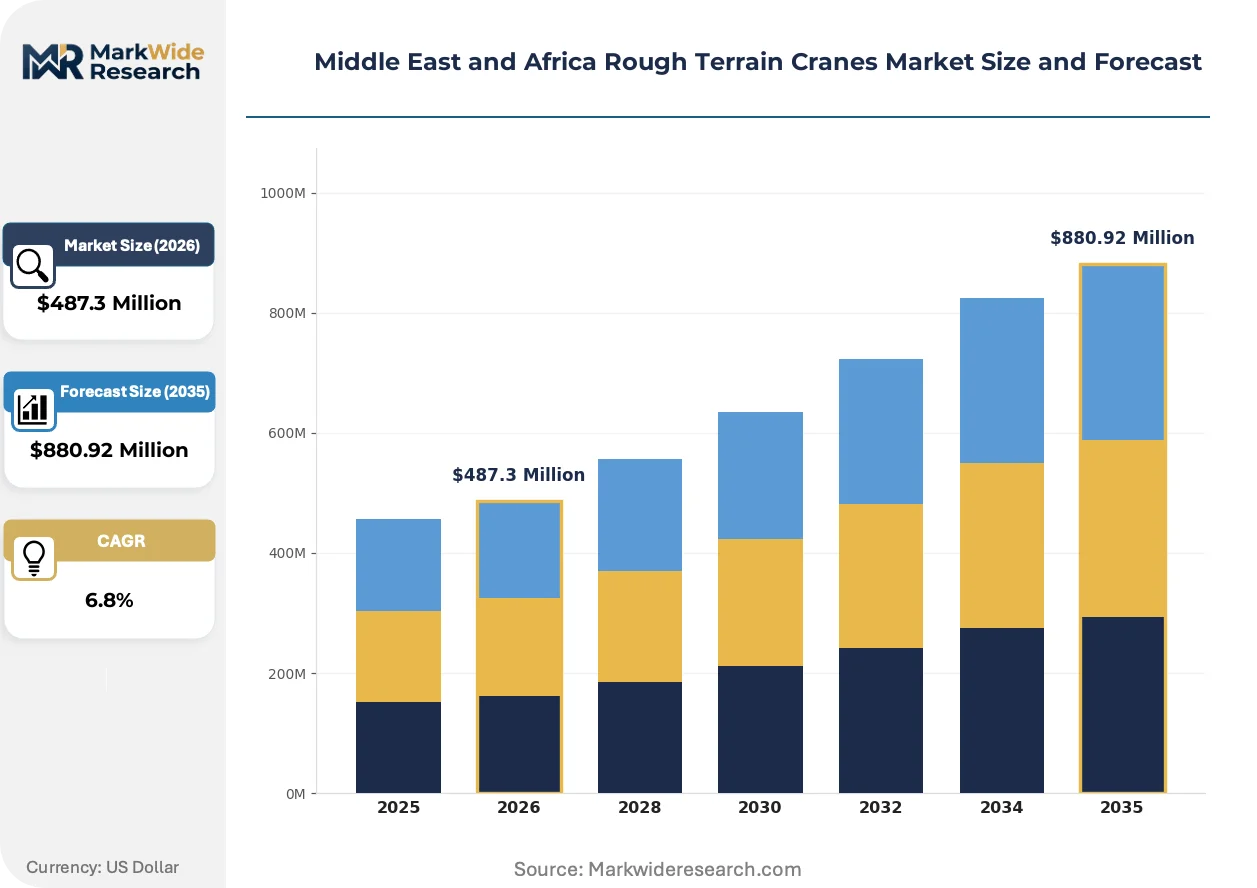
Saudi Arabia's giga-project pipeline is rewriting equipment deployment patterns across the Middle East and Africa Rough Terrain Cranes Market. Liebherr Group leverages its regional service footprint to sustain long-term rental contracts in Gulf infrastructure corridors. Tadano Ltd. anchors its position through all-terrain crane specialization suited to desert construction logistics. SANY Group competes on cost-adjusted lifting capacity for African mining and energy clients.
Rough terrain cranes are off-highway mobile lifting machines built on four-wheel-drive chassis with oscillating booms rated between 10 and 50 tons, engineered for unpaved jobsites where conventional truck cranes cannot operate. Their primary commercial purpose centers on erecting structures, maintaining oilfield equipment, and extracting minerals across remote or undeveloped ground conditions. Diesel cranes still dominate the installed base in African markets where grid access remains sparse, yet hybrid cranes capture expanding share in UAE urban construction zones governed by emission protocols. The 30-40 ton capacity band concentrates margin pools due to its versatility across both infrastructure and energy applications.
UAE's Ministry of Energy and Infrastructure enforces progressive emission benchmarks that restrict diesel-only crane registrations in Dubai and Abu Dhabi municipal zones. South Africa's Department of Mineral Resources and Energy ties mining equipment permits to occupational safety audits, elevating demand for certified lifting fleets. Saudi Standards, Metrology and Quality Organization aligns local crane testing with ISO 4309 wire rope standards for giga-project eligibility. Stakeholders must track how Gulf carbon compliance timelines and African mining permit cycles synchronize to shape fleet replacement schedules.
Market Dynamics
Saudi Arabia's giga-project pipeline is compressing crane procurement cycles, forcing rental fleets to pre-position capacity years ahead of construction milestones while UAE emission deadlines accelerate powertrain transitions.
Growth Catalysts
- NEOM Infrastructure Deadlines:Saudi Arabia's linear city construction mandates synchronized equipment deployment across multiple simultaneous sites, pulling forward rough terrain crane orders from regional rental operators.
- UAE Dual Carbon Goals:MOHAP emission benchmarks for Dubai municipal zones are disqualifying pure-diesel crane registrations, redirecting fleet investment toward hybrid powertrains.
- South African Mining Permit Renewals:The Department of Mineral Resources and Energy's occupational safety audit requirements are triggering certified lifting fleet replacements at platinum and gold extraction sites.
Market Restraints
- Diesel Engine Supply Concentration:European engine manufacturers control Tier 4 Final powertrain supply, exposing African fleet operators to euro-denominated input volatility and extended lead times.
- Wire Rope Certification Bottlenecks:Saudi Standards, Metrology and Quality Organization's ISO 4309 alignment requirements are creating testing queue backlogs that delay giga-project equipment eligibility.
- All-Terrain Crane Substitution:Tadano's all-terrain specialization is capturing desert logistics contracts that rough terrain cranes historically dominated, compressing the addressable site-access niche.
Strategic Opportunities
- Egyptian New Administrative Capital:The Cairo megaproject's phased construction timeline offers underpenetrated volume for 30-40 ton capacity bands ahead of peak Saudi and UAE saturation.
- Red Sea Tourism Infrastructure:Coastal resort development across Saudi Arabia's western seaboard is opening marine-adjacent applications where oscillating boom stability outperforms truck-mounted alternatives.
- Telematics-Hybrid Convergence:Integration of real-time load monitoring with battery-electric powertrains enables outcome-based rental pricing that captures fuel savings as margin.
Industry Challenges
- Certified Operator Scarcity:South Africa's mining safety audits and Saudi giga-project eligibility both demand rigger-certification density that regional training pipelines cannot match.
- Cross-Border Spare Parts Logistics:UAE-based service hubs face customs friction when supporting Egyptian or Nigerian fleet deployments, extending mean-time-to-repair.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Rough Terrain Cranes Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Cranes, Diesel Cranes, Electric Cranes, All-Terrain Cranes Capacity: 10-20 Tons, 20-30 Tons, 30-40 Tons, 40-50 Tons End User: Construction, Oil & Gas, Mining, Infrastructure Deployment Type: Onshore, Offshore, Urban, Rural |
| Companies Covered | Liebherr Group, Tadano Ltd., Manitowoc Company Inc., SANY Group, Zoomlion Heavy Industry Science and Technology Co Ltd, XCMG Group, Terex Corporation, Kobelco Construction Machinery Co Ltd, Konecranes Plc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Rough Terrain Cranes Market Strategic Shifts
Powertrain electrification and connected fleet management are rewriting equipment economics across Middle East and African jobsites, compressing the competitive window for conventional diesel-first strategies.
Hybrid-electric rough terrain cranes with onboard battery packs and regenerative boom lowering are rendering obsolete the fuel-cost advantage that sustained pure-diesel fleet dominance. Saudi rental operators at NEOM sites are specifying these systems for indoor construction phases where ventilation constraints apply. The technology is rendering obsolete the historical trade-off between site mobility and emission compliance.
MOHAP's progressive emission benchmarks for Dubai and Abu Dhabi municipal construction zones are disqualifying diesel-only crane registrations after specified phase-in deadlines. Equipment lessors must now hybridize or exit urban rental pools. The 30-40 ton capacity segment faces the steepest compliance cost concentration due to its density in UAE infrastructure applications.
Fleet telematics unbundling is separating hardware procurement from uptime-guarantee contracts. Saudi giga-project contractors now specify availability-based payment terms rather than day-rate structures, transferring utilization risk to rental providers. This shift is most visible in Riyadh and Jeddah corridor projects where synchronized multi-site deployment demands real-time redeployment flexibility.
Middle East and Africa Rough Terrain Cranes Market Segmentation
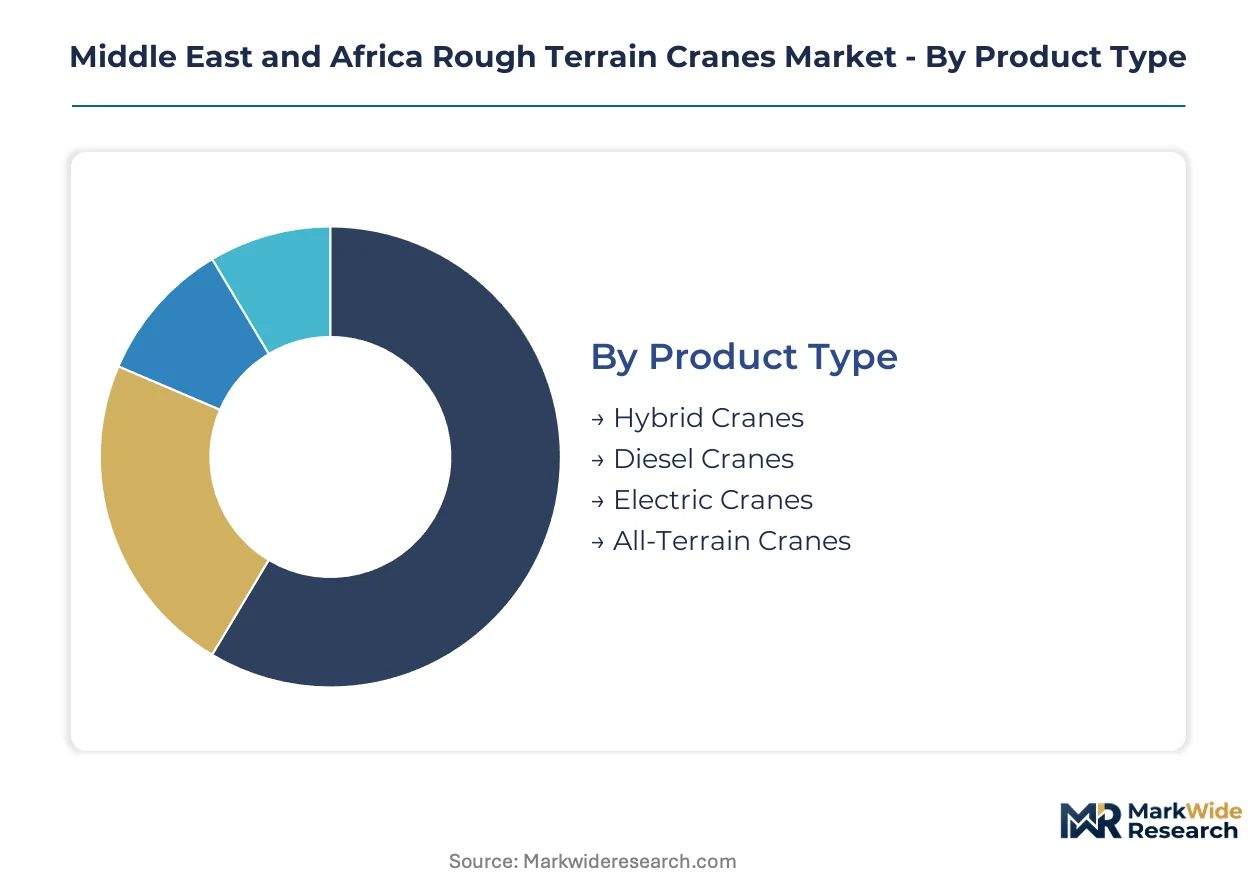
Rough terrain crane procurement patterns diverge sharply across powertrain technologies, lifting capacities, and site conditions in Middle East and Africa markets. After-sales service intensity varies dramatically by segment, with hybrid systems demanding specialized technician networks that reshape vendor selection criteria.
Product Type:
After-sales service intensity escalates with powertrain complexity, tilting procurement decisions toward manufacturers with proven regional technical infrastructure.
- Hybrid Cranes:Onboard battery packs paired with downsized diesel engines enable regenerative boom lowering and zero-emission indoor operation. MOHAP's Dubai municipal emission deadlines are disqualifying pure-diesel alternatives, concentrating rental fleet orders with UAE-based service providers capable of high-voltage system maintenance.
- Diesel Cranes:Tier 4 Final powertrains dominate African mining corridors where grid infrastructure remains sparse and technician familiarity with mechanical systems exceeds electrical competency. South African platinum and gold extraction sites specify these units for remote deployments beyond hybrid charging logistics.
- Electric Cranes:Battery-electric units with tethered or opportunity charging suit UAE urban construction zones with reliable grid access.
- All-Terrain Cranes:Highway-legal rough terrain hybrids capture desert logistics contracts requiring rapid site-to-site redeployment without low-loader transport.
Diesel cranes hold the largest share; momentum sits with hybrid cranes.
Capacity:
Margin concentration follows versatility across application types, with mid-range capacities capturing overlapping infrastructure and energy demand.
- 30-40 Tons:Oscillating booms in this band handle precast concrete erection, oilfield maintenance, and mineral processing equipment installation with minimal reconfiguration. NEOM's linear city construction mandates synchronized deployment across multiple simultaneous sites, pulling forward regional rental orders for this capacity tier.
- 20-30 Tons:Compact chassis dimensions navigate restricted urban jobsites while maintaining sufficient reach for mid-rise structural steel placement. Egyptian New Administrative Capital phased construction creates underpenetrated volume ahead of Saudi and UAE market saturation.
- 10-20 Tons:Lightweight units serve maintenance access in confined industrial facilities and telecommunications tower erection.
- 40-50 Tons:Heavy-lift configurations address offshore module assembly and large-scale mining equipment repositioning.
30-40 tons holds the largest share; 20-30 tons is climbing the fastest.
End User:
Customer procurement sophistication varies by sector, with infrastructure contractors demanding availability-based contracts that transfer utilization risk to rental providers.
- Construction:Giga-project contractors in Saudi Arabia now specify uptime-guarantee payment terms rather than day-rate structures, requiring real-time fleet telematics and multi-site redeployment flexibility.
- Oil & Gas:Field maintenance operations in remote hydrocarbon provinces prioritize diesel reliability over emission compliance.
- Mining:South Africa's Department of Mineral Resources and Energy occupational safety audits trigger certified lifting fleet replacements at platinum and gold extraction sites.
- Infrastructure:Red Sea coastal resort development opens marine-adjacent applications where oscillating boom stability outperforms truck-mounted alternatives.
Construction holds the largest share; mining is gaining share fastest.
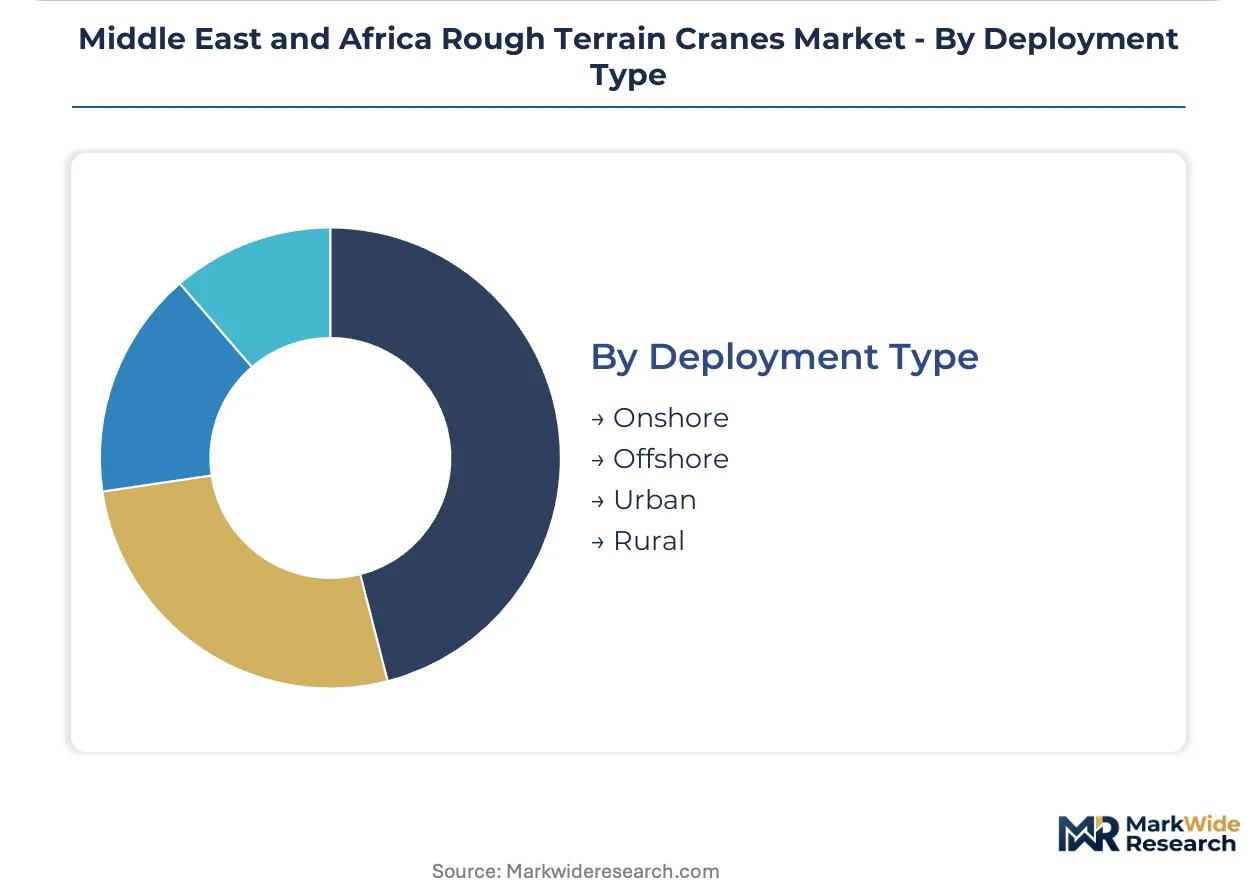
Deployment Type:
Site accessibility constraints determine chassis specification, with oscillating axle articulation and four-wheel-drive engagement requirements varying by terrain severity.
- Onshore:Unpaved desert construction corridors and undeveloped mineral extraction sites demand maximum ground clearance and differential lock capability.
- Offshore:Coastal and island projects require corrosion-resistant finishes and marine-grade wire rope specifications.
- Urban:Dubai and Abu Dhabi municipal zones governed by MOHAP emission benchmarks restrict diesel-only crane registrations, redirecting fleet investment toward hybrid powertrains.
- Rural:Grid-sparse African territories sustain diesel dominance where charging infrastructure and specialized technician networks remain undeveloped.
Onshore holds the largest share; urban is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOHAP's progressive emission benchmarks for Dubai and Abu Dhabi municipal zones are redirecting fleet investment toward hybrid powertrains across the Gulf, while African mining corridors sustain diesel dominance where grid infrastructure remains undeveloped.
Saudi Arabia
NEOM's linear city construction and Red Sea coastal resort development are compressing crane procurement cycles for synchronized multi-site deployment. Saudi Standards, Metrology and Quality Organization aligns local crane testing with ISO 4309 wire rope standards for giga-project eligibility. Riyadh and Jeddah corridor projects now specify uptime-guarantee payment terms rather than traditional day-rate structures.
United Arab Emirates
Dubai municipal emission deadlines are disqualifying pure-diesel crane registrations, concentrating rental fleet orders with UAE-based service providers capable of high-voltage system maintenance. MOHAP benchmarks govern construction zones in both Dubai and Abu Dhabi. Urban deployment types across these emirates are expanding most quickly as hybrid powertrains capture market share.
South Africa
Platinum and gold extraction sites are triggering certified lifting fleet replacements following Department of Mineral Resources and Energy occupational safety audit requirements. The country's mining permit renewal cycles synchronize with fleet replacement schedules. Johannesburg and the broader mining belt represent the continent's most sophisticated crane procurement environment.
Egypt
The New Administrative Capital megaproject's phased construction timeline offers underpenetrated volume for 20-30 ton capacity bands ahead of Saudi and UAE market saturation. National infrastructure investment programs prioritize domestic equipment certification standards. Cairo and the new capital zone are emerging as secondary demand centers for regional rental operators.
Nigeria
Oilfield maintenance operations in remote hydrocarbon provinces prioritize diesel reliability over emission compliance, sustaining conventional powertrain demand. The country's national petroleum regulator oversees equipment safety protocols for upstream operations. Lagos and the Niger Delta industrial corridor concentrate procurement activity for West African energy infrastructure.
Middle East and Africa Rough Terrain Cranes Market Competitive Environment
European-engineered specialists and Chinese scale manufacturers split the market across premium and cost-adjusted segments. The vendor base concentrates around manufacturers with proven regional service infrastructure capable of supporting high-voltage hybrid maintenance. Three archetypes dominate: full-lifecycle service integrators, capacity-focused volume suppliers, and desert logistics mobility specialists. Competitive moves center on telematics-hybrid convergence for outcome-based rental pricing and strategic partnerships with Gulf-based fleet operators.
Within the full-lifecycle service tier, Liebherr Group and Tadano Ltd. exemplify manufacturers anchoring long-term rental contracts through regional technical infrastructure. Liebherr leverages its established Gulf service footprint to sustain multi-year agreements across Saudi infrastructure corridors. Tadano occupies a position as the mobility specialist whose all-terrain configurations capture desert logistics contracts. SANY Group represents the scale-driven archetype competing on cost-adjusted lifting capacity for African mining and energy procurement.
| Leading Market Players |
|---|
| Liebherr Group |
| Tadano Ltd. |
| Manitowoc Company Inc. |
| SANY Group |
| Zoomlion Heavy Industry Science and Technology Co Ltd |
| XCMG Group |
| Terex Corporation |
| Kobelco Construction Machinery Co Ltd |
| Konecranes Plc |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in European Tier 4 Final engine production is compressing procurement leverage for African fleet operators while simultaneously elevating hybrid crane premiums in UAE municipal zones where MOHAP emission deadlines constrain supply alternatives.
Pricing Analysis
Geographic price spreads between Gulf hybrid deployments and African diesel corridors now exceed the freight cost differential itself. Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales bundling intensity. Pricing pressure stems from euro-denominated engine input volatility and extended lead times. Mining procurement teams in South Africa exhibit highest price sensitivity due to permit renewal cycle pressures, while NEOM infrastructure contractors prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from European engine manufacturers are straining working capital for regional rental operators navigating simultaneous fleet hybridization cycles. Manufacturing concentrates in Germany, Japan, and China for powertrain assemblies, wire rope systems, and structural components respectively. Supply chains rest on high-strength steel availability, battery cell chemistry, and hydraulic system integration. Single-source vulnerability concentrates in Tier 4 Final engine supply. Distribution runs through UAE-based service hubs with customs friction extending mean-time-to-repair for Egyptian and Nigerian deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection where telematics-hybrid convergence enables outcome-based rental pricing, unbundling hardware procurement from uptime-guarantee contracts across Saudi giga-project corridors.
For Market Incumbents: Entrench long-term rental contracts by expanding high-voltage technician networks ahead of MOHAP's progressive emission deadlines. Deepen backward integration into battery system maintenance capabilities to capture fuel savings as margin. Defend against Tadano's all-terrain substitution threat by emphasizing oscillating boom stability in marine-adjacent Red Sea applications.
For New Entrants and Emerging Players: Build out Egyptian New Administrative Capital presence ahead of Saudi and UAE saturation, targeting the underpenetrated 20-30 ton capacity band. Establish certified operator training partnerships to address rigger-certification scarcity that constrains giga-project eligibility. Lead with telematics-enabled availability pricing to differentiate from incumbent day-rate structures.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid powertrain development as battery-electric R&D demands escalate. Five-to-ten year viability favors manufacturers with proven regional service infrastructure capable of supporting high-voltage maintenance. Acquisition targets should demonstrate ISO 4309 wire rope certification alignment and established UAE service hub presence. Monitor MOHAP emission benchmark phase-in schedules as the critical inflection signal for fleet replacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Hybrid Integration | Enables outcome-based rental pricing that captures fuel savings as margin across NEOM sites. |
| High-Voltage Technician Network Expansion | Secures eligibility for Dubai municipal contracts under MOHAP emission benchmarks. |
| ISO 4309 Certification Alignment | Accelerates giga-project equipment eligibility by clearing Saudi Standards testing queue backlogs. |
| Egyptian Market Entry | Captures underpenetrated 20-30 ton volume ahead of Saudi and UAE capacity saturation. |
| Certified Operator Training Partnerships | Addresses rigger-certification scarcity constraining South African mining permit renewals. |
Study Parameters
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Conversations with rental fleet operators, maintenance directors at Saudi giga-project sites, procurement leads at South African mining houses, and aftermarket service heads across UAE hubs inform demand-side dynamics. Secondary sources include Saudi Standards, Metrology and Quality Organization testing protocols, South African Department of Mineral Resources and Energy permit documentation, MOHAP emission benchmark disclosures, and customs records for crane component trade flows. Bottom-up unit economics triangulate against top-down infrastructure investment pipelines.
Calibration against historical fleet replacement cycles and permit renewal patterns shapes the projection framework across the analysis window. Segmentation dimensions span powertrain technology, capacity tier, end-user sector, and deployment type. CAGRs derive from equipment procurement timing linked to named megaproject milestones and regulatory compliance deadlines. Industry-specific forecast inputs include NEOM construction phasing and MOHAP emission benchmark phase-in schedules.
Practitioners should monitor MOHAP deadline acceleration, euro-denominated engine cost volatility, and Saudi giga-project timeline adjustments for early signals of forecast revision. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Global Concrete Curing Equipment Market
Construction Equipment
Concrete Grinder Market
Construction Equipment
United States Crane Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
Smart Crane Market
Construction Equipment
Turkey Construction Equipment Market
Construction Equipment
Stud Welding Guns Market
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Concrete Spreader Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
US Aerial Work Platform Market